
 Grout Bags Market | 2026-2036
Grout Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Grout Bags Market Foresight
Modular packaging configurations are hardening as the dominant procurement format across municipal and industrial buyers. Kraft Tool Co. leverages its distribution network across North American hardware channels. Marshalltown anchors its position through specialized masonry tooling ecosystems. Bon Tool Co. competes on depth of SKU coverage for professional contractor segments.
Grout bags are flexible containers engineered from woven polypropylene or multi-layer laminates, typically rated for 25–50 kg fill capacity, designed to dispense cementitious, epoxy, or polymer-based grouts through a controlled spout or tear-seam aperture into tile joints, structural cracks, or precision anchoring voids. Cement-based material formulations occupy the largest volume share due to cost accessibility in residential tiling, while epoxy compositions command premium positioning in industrial infrastructure repair where chemical resistance and compressive strength above 80 MPa are specified. Pre-filled product configurations are gaining traction among time-sensitive commercial contractors, whereas bulk formats sustain margin pools for large-scale infrastructure tenders requiring site-mixed proportioning control.
The US EPA regulates leachable heavy metal content under Safe Drinking Water Act provisions, directly constraining latex additive formulations in potable water infrastructure applications. Germany's KBA and France's ANSM enforce construction product performance declarations through CE marking under the Construction Products Regulation, shaping cross-border material certification burdens. ISO 13007 tile adhesive and grout standards govern shear bond and shrinkage testing protocols that manufacturers must document for European public procurement eligibility. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions under REACH revisions, as fluorinated polymer coatings on high-performance grout bags face prospective phase-out timelines that would force material redesign investments.
Market Dynamics
Modular packaging configurations are hardening procurement patterns across municipal and industrial buyers, while EPA lead and copper rule revisions force material compliance upgrades in potable water applications. This structural tension between standardization pressure and regulatory fragmentation defines competitive positioning.
Growth Catalysts
- Rhine-Ruhr tunnel maintenance:Germany's industrial corridor drives specialized epoxy grout consumption through infrastructure rehabilitation programs targeting aging municipal assets.
- REACH fluorinated polymer phase-out:Anticipated restrictions on PFAS coatings are accelerating R&D investments in alternative high-performance barrier materials for critical applications.
- Pre-filled product configurations:Time-sensitive commercial contractors are consolidating purchasing around ready-to-deploy formats that compress on-site labor requirements.
Market Restraints
- Polypropylene feedstock volatility:Woven bag substrates face margin compression from petrochemical input cost swings that suppliers cannot fully pass through.
- CE marking documentation burdens:Germany's KBA and France's ANSM enforcement of Construction Products Regulation performance declarations creates cross-border certification friction for mid-tier manufacturers.
- Cement-based formulation ceiling:Residential tiling's cost-driven material preferences cap premium product penetration in volume segments.
Strategic Opportunities
- Site-mixed proportioning control:Bulk format tenders for large-scale infrastructure projects sustain margin pools that pre-filled configurations cannot capture.
- ISO 13007 compliance differentiation:Shear bond and shrinkage testing documentation creates procurement eligibility barriers that certified suppliers exploit.
- Hardware channel density:North American distribution networks anchored in professional contractor segments enable SKU breadth strategies against specialized competitors.
Industry Challenges
- Multi-layer laminate technical expertise:Barrier engineering talent scarcity constrains development of next-generation grout bags rated for extreme chemical exposure.
- Safe Drinking Water Act additive reformulation:Latex chemistry adjustments for potable water compliance extend product validation timelines without guaranteed approval outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grout Bags Market |
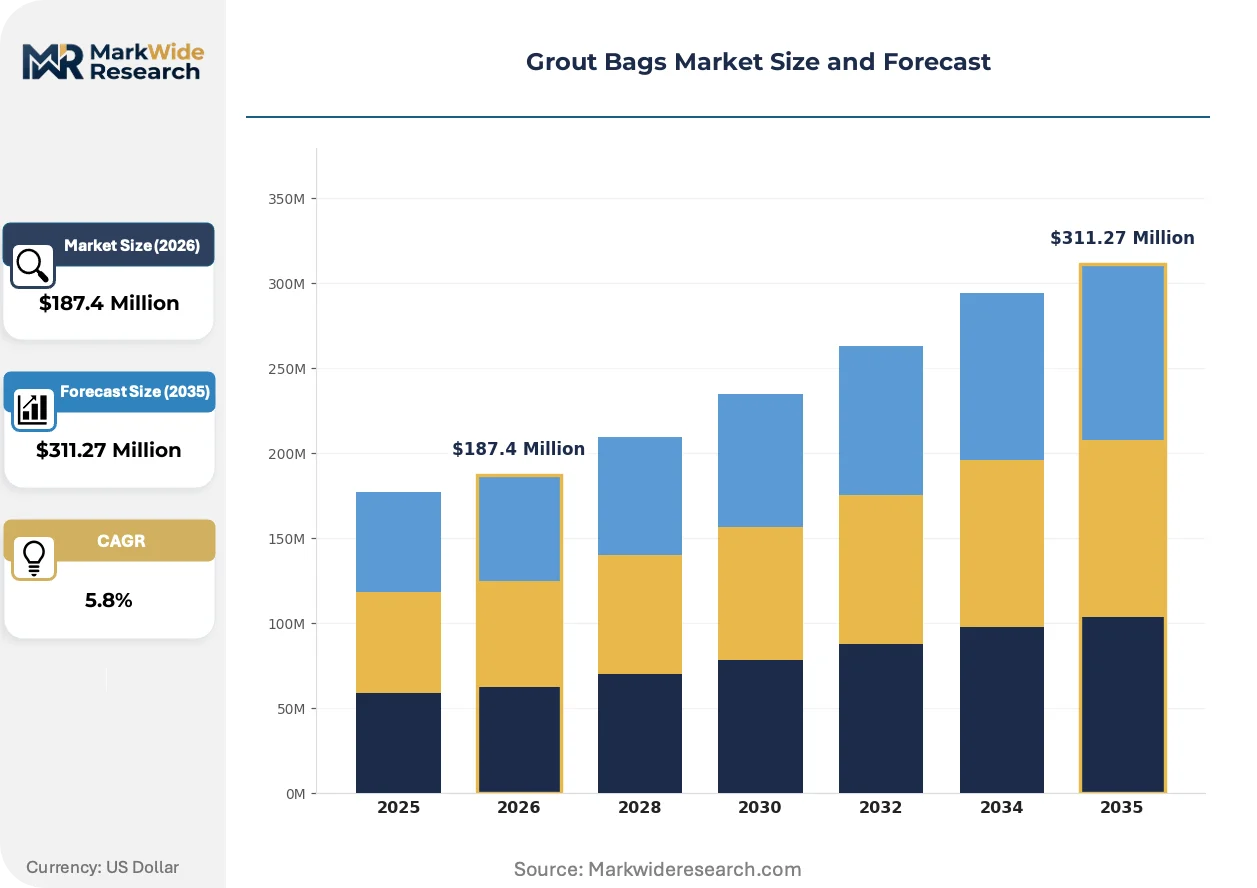
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Residential, Commercial, Industrial, Infrastructure Product Type: Pre-filled, Bulk, Custom, Specialty Material: Cement, Epoxy, Polymer, Latex Packaging Type: Bag, Pouch, Box, Others |
| Companies Covered | Bon Tool Co., Marshalltown, Kraft Tool Co., OX Tools, Q.E.P. Co. Inc., Westco Tools Inc., Bon Tool Company, Global Grout Bags, Private-label Manufacturers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grout Bags Market Shifts & Advancements
Material science advances and procurement model compression are restructuring how grout bag specifications propagate from regulatory laboratories to job sites. Three interconnected developments are redefining competitive advantage.
Multi-layer co-extruded laminates with oxygen and moisture barriers are unifying performance tiers previously served by separate product lines. Industrial infrastructure repair contractors in Germany's municipal water sector are specifying these materials for epoxy grout containment above 80 MPa compressive strength requirements. The technology is unifying premium and mid-market segments by delivering chemical resistance at scale-compatible price points.
EPA's lead and copper rule revisions are tightening leachable heavy metal thresholds for potable water infrastructure. Latex additive formulations face direct constraint as Safe Drinking Water Act provisions expand material documentation requirements. North American municipal procurement departments are responding by pre-qualifying suppliers with third-party certified compliance dossiers, compressing vendor pools.
Contractor purchasing departments are consolidating around specification bundles that combine grout bags with complementary masonry tooling. Professional segments in the US and Germany are displacing single-product procurement with integrated vendor relationships that reduce transaction overhead. This concentration pattern favors distributors with depth across hardware channels rather than specialized bag manufacturers.
Grout Bags Market Segmentation
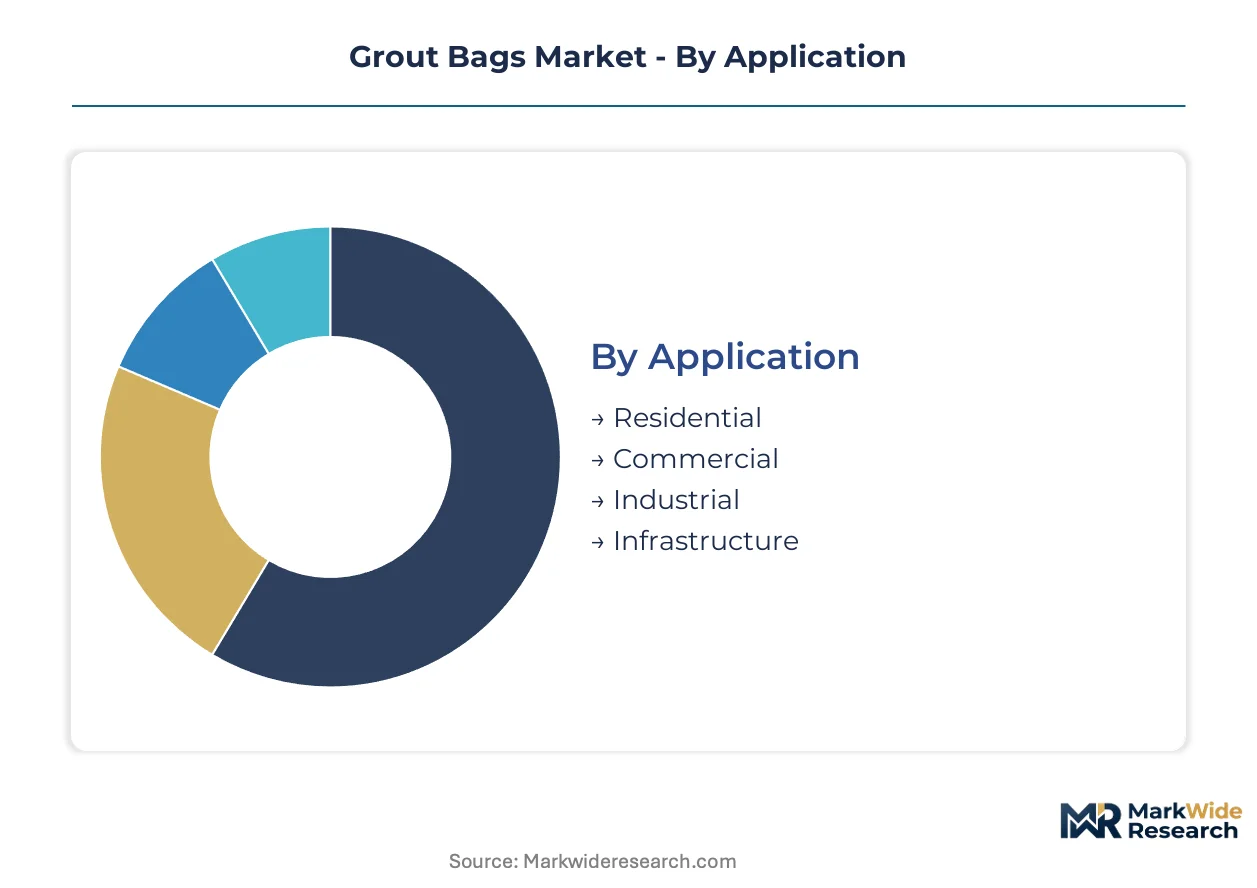
Grout bag specifications cascade from material chemistry through packaging geometry to end-use performance requirements. Procurement officers weight these axes differently across municipal tenders, commercial contracts, and residential retail channels.
Application:
Technical performance thresholds diverge sharply across installation environments, with compressive strength and chemical resistance specifications scaling with structural criticality.
- Residential:Cost-accessible cement-based formulations dominate volume, with 25–50 kg woven polypropylene bags serving tiling contractors through hardware retail channels. Preference for bulk formats sustains margin compression as price-sensitive homeowners prioritize material economy over performance premiums.
- Infrastructure:Municipal water system rehabilitation in Germany's Rhine-Ruhr corridor and US EPA-regulated potable water projects specify epoxy compositions above 80 MPa compressive strength with documented heavy metal leachate compliance. Pre-filled configurations face procurement friction against site-mixed proportioning requirements in large-scale tenders.
- Commercial:Time-sensitive contractors consolidate around ready-to-deploy formats that compress labor scheduling uncertainty in retail and hospitality fit-outs.
- Industrial:Chemical exposure environments in manufacturing facilities drive multi-layer laminate specifications with oxygen and moisture barriers.
Infrastructure leads on specification intensity; Commercial leads on format innovation velocity.
Product Type:
Format selection traces directly to project scale and mixing control requirements, with procurement patterns hardening around labor cost trade-offs.
- Bulk:Site-mixed proportioning control sustains margin pools for infrastructure tenders requiring batch-specific documentation. Rhine-Ruhr tunnel maintenance programs and US municipal water contracts specify bulk delivery to enable real-time formulation adjustments.
- Pre-filled:Ready-to-deploy configurations compress on-site labor requirements for commercial contractors facing scheduling penalties. North American professional segments consolidate purchasing around specification bundles that integrate grout bags with complementary masonry tooling.
- Custom:Project-specific aperture designs and fill capacity modifications serve specialized anchoring void geometries in industrial precision applications.
- Specialty:Fluorinated polymer-coated barriers for extreme chemical exposure face prospective phase-out pressure under REACH revisions, forcing R&D investment in alternative high-performance materials.
Bulk commands infrastructure procurement; Pre-filled climbs fastest in commercial adoption curves.
Material:
Chemistry selection governs compressive strength, chemical resistance, and regulatory compliance trajectories across end-use segments.
- Epoxy:Compositions above 80 MPa compressive strength command premium positioning in Germany's municipal water infrastructure and US EPA-regulated potable water applications. Multi-layer laminate containment systems are specified for oxygen-sensitive curing environments.
- Cement:Volume accessibility in residential tiling segments caps premium penetration, with woven polypropylene bags serving cost-driven hardware channel procurement.
- Polymer:Modified formulations bridge performance gaps between cement economy and epoxy specifications in commercial repair applications.
- Latex:Additive formulations face direct constraint under US EPA Safe Drinking Water Act provisions as lead and copper rule revisions tighten leachable heavy metal thresholds, extending product validation timelines without guaranteed approval outcomes.
Cement dominates unit volume; Epoxy captures value concentration.
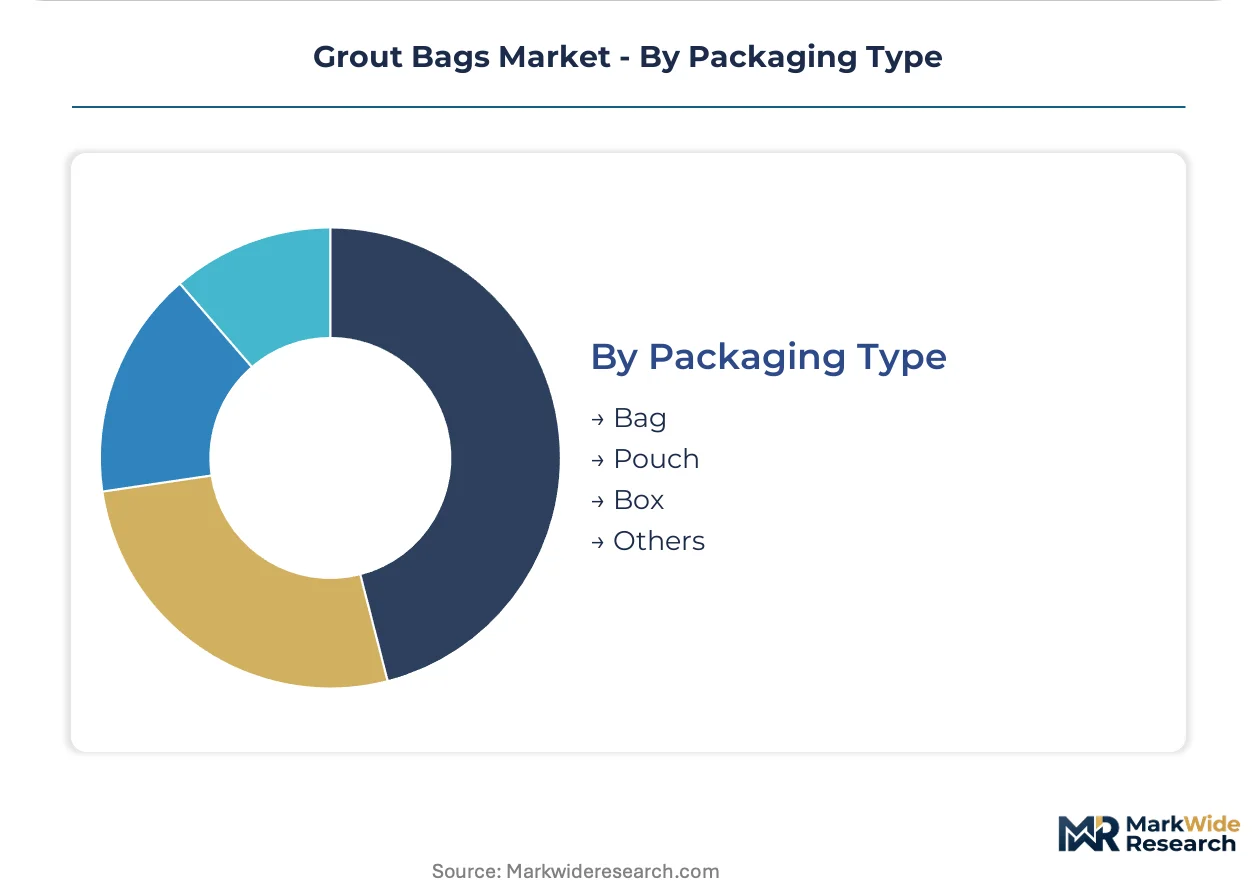
Packaging Type:
Containment geometry shapes dispensing control, storage efficiency, and transportation economics across distribution channels.
- Bag:Woven polypropylene and multi-layer laminate constructions rated for 25–50 kg fill capacity serve as the default format across residential, commercial, and infrastructure segments. Tear-seam apertures and controlled spout designs enable precision dispensing into tile joints and structural cracks.
- Pouch:Flexible single-use configurations gain traction in spot repair applications where material waste minimization outweighs unit cost premiums.
- Box:Rigid secondary containment supports pre-filled product configurations in commercial channels requiring palletized logistics efficiency.
- Others:Specialized drum and intermediate bulk container formats serve large-scale infrastructure tenders with automated mixing equipment compatibility.
Bag formats anchor procurement standardization; Pouch configurations expand in precision repair niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grout bag manufacturing originated in post-war European construction supply chains, with German industrial corridors pioneering woven polypropylene containment systems for tunnel rehabilitation. The technology migrated to North American hardware channels during the 1970s infrastructure boom.
United States
Municipal water system rehabilitation drives procurement volumes across aging infrastructure networks. EPA lead and copper rule revisions under Safe Drinking Water Act provisions constrain latex additive formulations in potable water applications. The Rust Belt corridor spanning Ohio, Michigan, and Pennsylvania concentrates demand from legacy industrial facility maintenance programs.
Germany
Rhine-Ruhr industrial corridor tunnel maintenance programs specify epoxy grout compositions above 80 MPa compressive strength. KBA enforcement of CE marking under Construction Products Regulation shapes cross-border material certification requirements. North Rhine-Westphalia's municipal water utilities anchor specialized multi-layer laminate procurement for oxygen-sensitive curing environments.
France
ANSM performance declaration requirements for construction products create documentation barriers for mid-tier suppliers. Infrastructure rehabilitation in Île-de-France's aging water distribution networks drives demand for documented heavy metal leachate compliance. Auvergne-Rhône-Alpes manufacturing clusters specify fluorinated polymer-coated barriers for chemical exposure applications facing prospective REACH phase-out timelines.
United Kingdom
Post-Brexit regulatory divergence from EU Construction Products Regulation creates parallel certification tracks for cross-channel suppliers. London's commercial construction sector consolidates purchasing around pre-filled configurations that compress on-site labor scheduling. Midlands industrial corridor maintenance programs sustain bulk format tenders requiring site-mixed proportioning control.
Canada
Health Canada and PMRA oversight of construction materials in potable water applications aligns with tightening North American compliance thresholds. Ontario's municipal infrastructure rehabilitation programs specify ISO 13007-compliant shear bond and shrinkage documentation. British Columbia's seismic retrofit initiatives drive specialized anchoring void applications requiring custom aperture designs.
Grout Bags Market Competitive Landscape
The competitive structure tilts toward distribution-anchored specialists with deep hardware channel penetration. Kraft Tool Co. leverages its North American network density against specialized masonry tooling competitors. Marshalltown anchors position through professional contractor segment relationships. Mid-tier manufacturers face margin compression from polypropylene feedstock volatility they cannot fully pass through.
Among North American hardware channel specialists, Kraft Tool Co., Marshalltown, and Bon Tool Co. occupy positions defined by SKU breadth strategies and professional contractor segment focus. These fabricators exemplify the archetype of distribution-anchored players competing on specification bundle integration rather than manufacturing scale. OX Tools and Q.E.P. Co. Inc. represent alternative positioning through complementary masonry tooling ecosystems that reduce transaction overhead for time-sensitive commercial contractors.
| Leading Market Players |
|---|
| Bon Tool Co. |
| Marshalltown |
| Kraft Tool Co. |
| OX Tools |
| Q.E.P. Co. Inc. |
| Westco Tools Inc. |
| Bon Tool Company |
| Global Grout Bags |
| Private-label Manufacturers |
| Others |
Supply & Pricing Matrix
EPA lead and copper rule revisions are forcing municipal procurement departments to pre-qualify suppliers with third-party certified compliance dossiers, compressing vendor pools and concentrating pricing power among ISO 13007-documented manufacturers while squeezing mid-tier competitors unable to absorb validation cost burdens.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the Grout Bags Market, with epoxy compositions above 80 MPa compressive strength commanding substantial premiums over cement-based alternatives. Price differentiation rests on ISO 13007 certification status and CE marking documentation completeness, particularly in German and French municipal tenders. Cost compression in residential-grade woven polypropylene formats is intensifying because polypropylene feedstock volatility constrains margin pass-through. Commercial contractors exhibit lowest price sensitivity due to labor scheduling penalties, while residential tilers remain most cost-responsive.
Supply Chain Analysis
Domestic-content requirements in US infrastructure tenders and German KBA enforcement of CE marking are reshaping sourcing patterns toward regional manufacturing footprints. Supply concentration centers on Germany, the United States, and China, with woven polypropylene substrates and multi-layer laminate films as critical inputs. Single-source vulnerability in fluorinated polymer coatings faces prospective disruption from REACH phase-out timelines. Distribution runs through North American hardware channel networks and European construction supply distributors serving professional contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Grout Bags Market represents a late-cycle quality story as infrastructure rehabilitation programs shift procurement specifications toward documented heavy metal leachate compliance and compressive strength thresholds above 80 MPa.
For Market Incumbents: Deepen ISO 13007 certification coverage across product lines to exploit procurement eligibility barriers that mid-tier competitors cannot surmount. Expand backward integration into multi-layer laminate film production to mitigate fluorinated polymer coating supply risks from REACH revisions. Anchor channel control through specification bundle integration with complementary masonry tooling ecosystems. For New Entrants and Emerging Players: Enter via custom aperture design services for industrial precision anchoring void applications in British Columbia's seismic retrofit programs and Ontario's municipal infrastructure tenders. Target spot repair pouch configurations where material waste minimization commands unit cost premiums unavailable in bulk format competition. Pursue go-to-market partnerships with regional construction supply distributors lacking technical barrier engineering capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with distributors possessing deep hardware channel density across North American professional contractor segments, as procurement consolidation favors specification bundle integration over manufacturing scale. Long-term viability hinges on regulatory compliance infrastructure capable of adapting to evolving PFAS restrictions and Safe Drinking Water Act additive reformulations. Monitor EPA enforcement patterns on lead and copper rule revisions as inflection indicator for vendor pool compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Multi-Layer Laminate Production | Mitigates REACH fluorinated polymer phase-out exposure for epoxy grout containment systems. |
| ISO 13007 Certification Investment | Creates procurement eligibility barriers in German KBA-regulated municipal water tenders. |
| Specification Bundle Integration | Reduces transaction overhead for time-sensitive commercial contractors consolidating vendor relationships. |
| Custom Aperture Design Capability | Captures premium positioning in industrial precision anchoring void applications requiring project-specific geometries. |
| Pre-Filled Product Configuration Expansion | Compresses on-site labor requirements for retail and hospitality fit-out contractors facing scheduling penalties. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific manufacturing hubs, with primary inputs from each region combined with secondary validation. Interviews with municipal procurement officers, construction supply distributors, plant managers at woven polypropylene manufacturers, technical R&D directors at multi-layer laminate suppliers, and maintenance directors at tunnel rehabilitation contractors informed demand-side and supply-side perspectives. Secondary sources included US EPA Safe Drinking Water Act documentation, ECHA REACH substance restriction timelines, ISO 13007 testing protocol standards, customs trade data on polypropylene substrate flows, and SEC filings from construction supply distributors. Bottom-up volume modeling and top-down value triangulation cross-validated segment-level estimates.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects in cement-based versus epoxy formulation segments. The analytical framework models application splits across residential, commercial, infrastructure, and industrial end-uses; product type segmentation across bulk, pre-filled, custom, and specialty formats; material chemistry tiers spanning cement, polymer, epoxy, and latex additive compositions; and packaging geometry distinctions between bags, pouches, boxes, and specialized containers. CAGRs were derived from regression-based trend extrapolation calibrated to infrastructure rehabilitation program announcements and regulatory compliance phase-in schedules.
Inputs from EPA rulemaking dockets and ECHA restriction proposals were available through the study window; gaps in real-time municipal tender award data introduce uncertainty bands around infrastructure segment projections. Forecasts reflect assumptions on REACH PFAS phase-out timelines and KBA CE marking enforcement intensity. Polypropylene feedstock price volatility and latex additive reformulation approval delays represent specific risk factors that could revise volume and value trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Americas Hydraulic Submersible Pumps Market
Construction Equipment
Industrial Nailers Market
Construction Equipment
Trailer Winch Market
Construction Equipment
China Construction Equipment Market
Construction Equipment
Asia Pacific Construction Equipment Market
Construction Equipment
Heavy Construction Equipment Market
Construction Equipment
Screw Compressor Rental Market
Construction Equipment
Cold Planers Market
Construction Equipment
Part Feeder Market
Construction Equipment
Demolition Equipment Market
Construction Equipment
Vertical Mill Market
Construction Equipment
Global Portable Sawmills Market
Construction Equipment
Industrial and Commercial Floor Scrubbers Market
Construction Equipment
Jib Crane Market
Construction Equipment
Road Marking Equipment Market
Construction Equipment
Rockbreakers Market