
 Dock Door Market | 2026-2036
Dock Door Market Size, Share, and Industry Trends Forecast 2026-2036
Dock Door Market Outlook
A capital-intensity divergence between in-house fabrication and outsourced assembly is reorganizing competitive tiers across the dock door industry. Rite-Hite leverages captive manufacturing of hydraulic dock levelers to sustain premium positioning in temperature-controlled logistics. ASSA ABLOY Group anchors its European footprint through automated entrance systems that compete on integration density with building management platforms.
Dock doors are engineered industrial barriers, typically constructed from galvanized steel or aluminum panels with R-value thermal ratings between 10 and 20, designed to seal loading bay openings against weather infiltration, pest intrusion, and energy loss while accommodating truck trailer dimensions. Sectional doors occupy the largest installed base in legacy warehouse retrofits where vertical tracks maximize clearance. Automatic installation types represent the fastest-expanding segment as distribution centers mandate touchless trailer docking cycles to match conveyor throughput.
The US Department of Energy enforces minimum thermal performance standards for commercial building envelopes, while OSHA mandates fall protection at elevated loading docks, and ISO 9001 certification shapes supplier qualification for multinational logistics operators. These frameworks elevate specification thresholds for insulated steel doors and integrated restraint systems. Stakeholders must weigh capital deployment toward smart dock ecosystems against modular upgrade paths that preserve existing door frames.
Market Dynamics
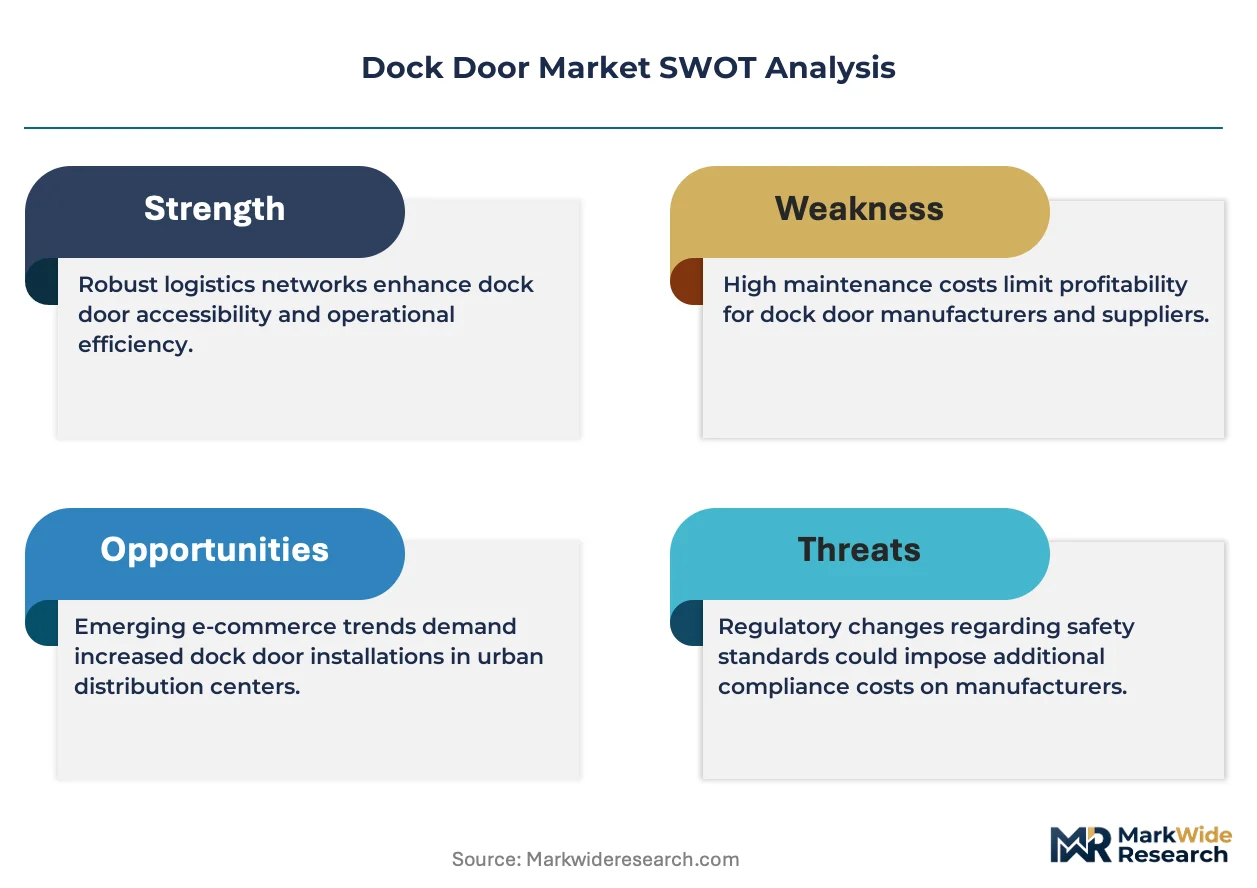
US Department of Energy efficiency mandates are compressing upgrade cycles for loading bay infrastructure, forcing facility operators to choose between full door replacement and retrofit sealing systems that preserve existing frames.
Growth Catalysts
- E-commerce fulfillment networks:Distribution centers in Dallas-Fort Worth and California's Inland Empire are expanding dock door density to match conveyor throughput demands.
- OSHA fall protection mandates:Elevated loading dock regulations are accelerating integrated restraint system installations across temperature-controlled logistics facilities.
- Automatic sealing technologies:Touchless trailer docking cycles are displacing manual operations in automated distribution corridors.
Market Restraints
- Galvanized steel input volatility:Raw material price swings compress margins for sectional door manufacturers serving legacy warehouse retrofits.
- Supplier concentration in hydraulic components:Captive production of dock levelers limits third-party component availability for mid-tier assemblers.
- ISO 9001 certification timelines:Multinational logistics operators impose 18-24 month supplier qualification windows that freeze out regional fabricators.
Strategic Opportunities
- Building management platform convergence:Integration density with automated entrance systems creates specification advantages for European facility operators.
- Modular upgrade paths:Retrofit sealing technologies that preserve existing door frames address capital-constrained warehouse operators in secondary distribution markets.
- Temperature-controlled logistics expansion:Cold chain infrastructure investments in automated distribution corridors drive premium insulated steel door demand.
Industry Challenges
- Automation integration complexity:Conveyor throughput matching requires synchronized dock door, leveler, and restraint system programming that strains in-house maintenance teams.
- Thermal performance certification:R-value testing protocols for insulated steel doors vary across jurisdictions, fragmenting product validation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dock Door Market |
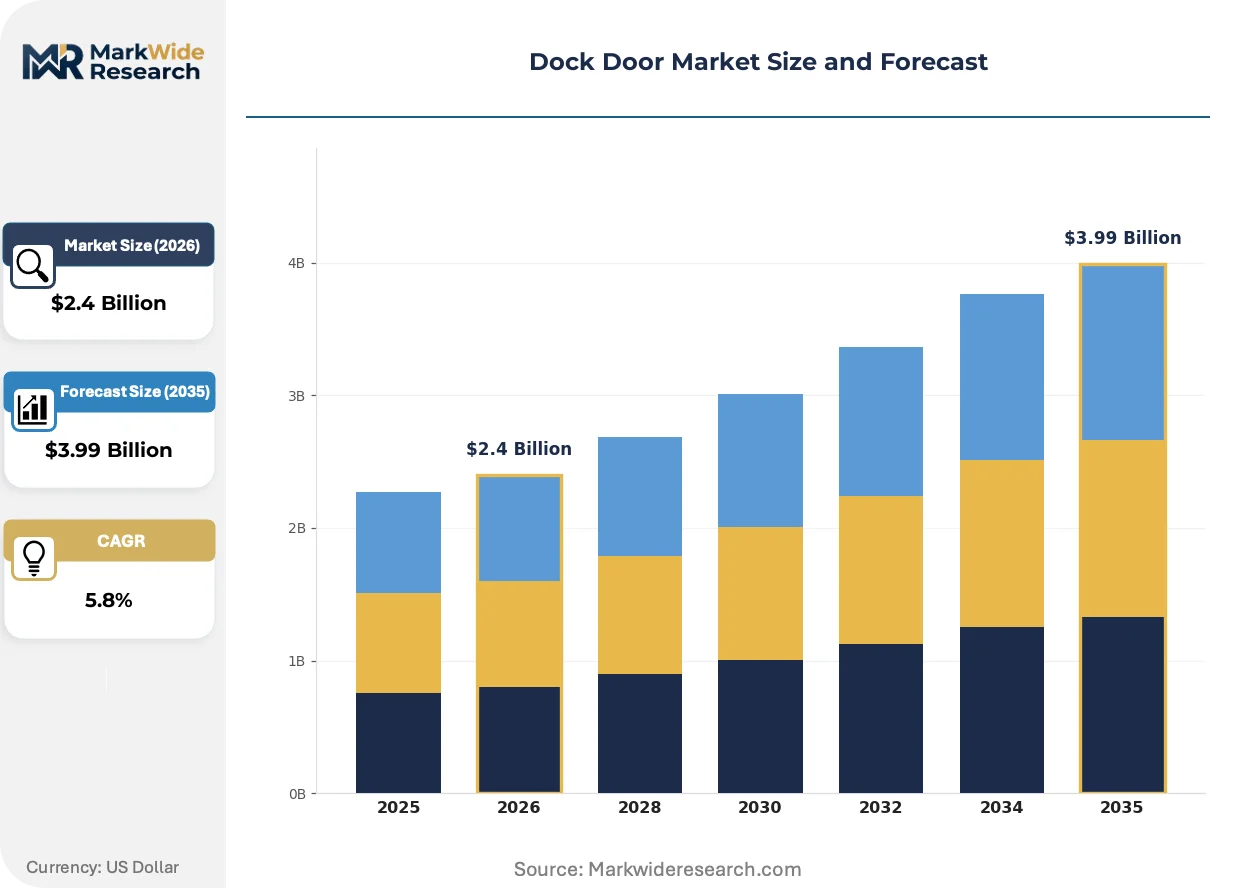
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roll-Up Doors, Sliding Doors, Swing Doors, Sectional Doors Material: Steel, Aluminum, Composite, Fiberglass Installation Type: Manual, Automatic, Semi-Automatic, Specialty End User: Warehouses, Distribution Centers, Manufacturing Facilities, Cold Storage |
| Companies Covered | Rite-Hite, ASSA ABLOY Group, Hörmann LLC, Blue Giant Equipment Corporation, Pentalift Equipment Corporation, DoorHan, ALUTECH Group, Overhead Door Corporation, Rytec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dock Door Market Strategic Shifts
Loading bay infrastructure is splitting between premium integrated ecosystems and modular retrofit solutions, with specification authority migrating from facilities managers to supply chain engineers.
Smart dock ecosystems combining automated doors, vehicle restraints, and levelers into unified control architectures are bifurcating the installed base. Third-party logistics operators with centralized engineering functions are specifying these systems at new construction sites. The technology is compressing competitive differentiation around software integration rather than hardware durability alone.
US Department of Energy commercial envelope standards are tightening thermal performance thresholds for loading bay openings. Facility operators must now document air infiltration rates and insulation continuity across door perimeters. Cold storage and pharmaceutical distribution verticals are responding fastest, specifying R-20 rated sectional doors with thermally broken frames.
Engineering specification authority is migrating from regional contractors to corporate supply chain teams. National distribution networks now centralize dock equipment decisions through capital engineering departments, displacing the traditional contractor-driven selection process. This concentration is most visible in grocery and parcel delivery networks operating multi-site fulfillment footprints.
Dock Door Market Segmentation
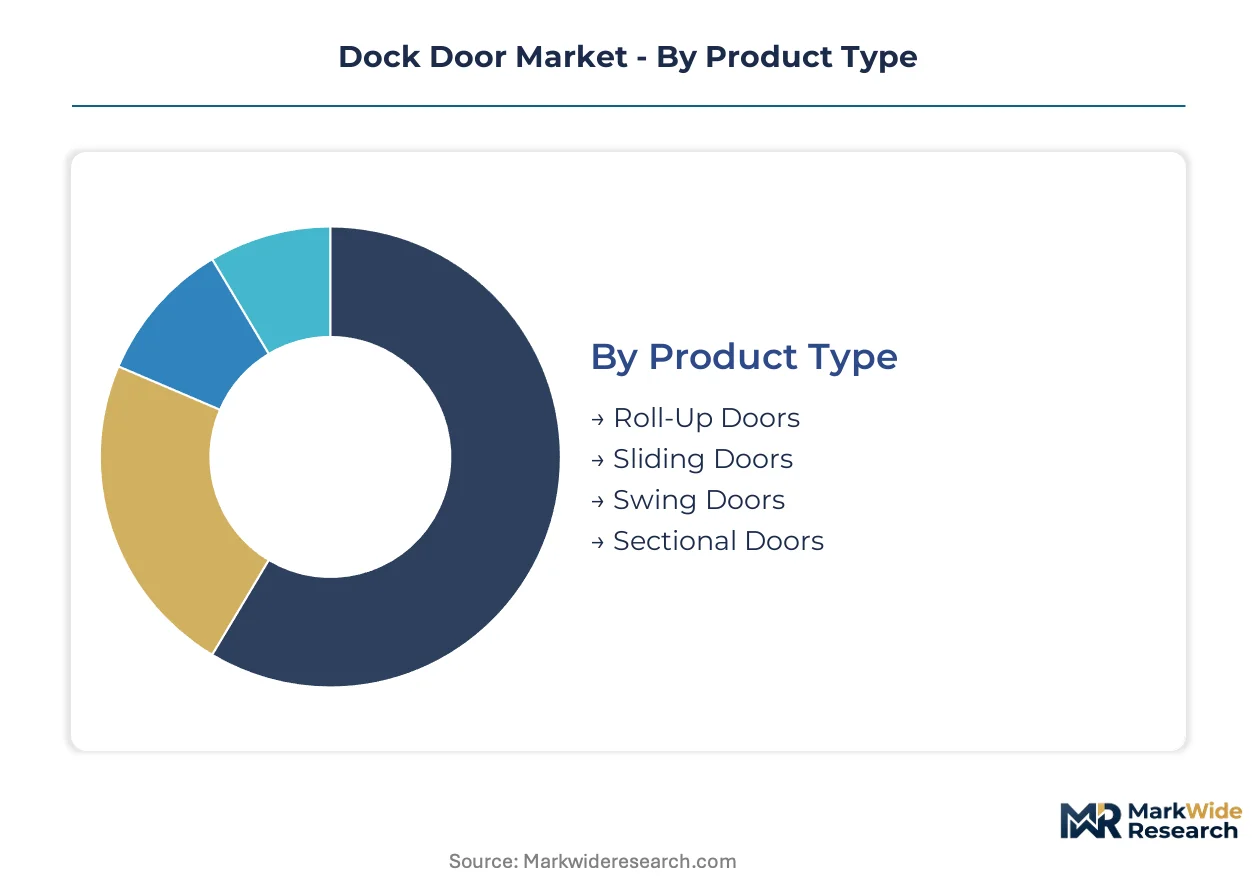
Dock door specification authority is migrating from regional contractors to corporate supply chain engineers, making segment alignment with centralized procurement frameworks critical for vendor positioning. Understanding where demand concentrates across product, material, and installation dimensions enables targeted capital deployment.
Product Type:
Domestic production dominates sectional and roll-up categories, while sliding and swing door segments rely more heavily on export-led supply chains serving multinational logistics operators.
- Sectional Doors:Constructed from interlocking steel or aluminum panels riding vertical tracks, these systems maximize clearance in facilities with height constraints. Demand concentrates in legacy warehouse retrofits across Dallas-Fort Worth and California's Inland Empire, where vertical track configurations preserve existing building envelopes. OSHA fall protection mandates are accelerating integrated restraint system pairings with sectional installations in temperature-controlled logistics.
- Roll-Up Doors:Coiling steel curtains wound onto overhead drums deliver compact storage and rapid cycle speeds. Cold storage facilities in automated distribution corridors are specifying insulated roll-up variants with R-20 thermal ratings to meet US Department of Energy envelope standards. The segment's integration with touchless trailer docking cycles is displacing manual operations in e-commerce fulfillment networks.
- Sliding Doors:Horizontal track systems suited to wide bay openings in heavy manufacturing and intermodal terminals.
- Swing Doors:Hinged panel designs retained in low-cycle applications and specialty agricultural or aviation facilities.
Sectional doors hold the largest share; momentum sits with roll-up doors.
Material:
Cost tier stratification separates premium composite and fiberglass offerings from commodity steel and aluminum segments serving price-sensitive retrofit markets.
- Steel:Galvanized and stainless steel variants deliver structural durability for high-cycle distribution environments. US Department of Energy efficiency mandates are compressing upgrade cycles for uninsulated steel installations, forcing operators toward thermally broken frame designs. Raw material price volatility in galvanized inputs is compressing margins for sectional door manufacturers.
- Composite:Fiberglass-reinforced polymer cores with steel or aluminum facing layers achieve superior thermal performance without weight penalties. Pharmaceutical distribution and cold chain infrastructure investments are driving composite specification in automated distribution corridors. The segment commands premium positioning where R-value continuity across door perimeters is mandatory.
- Aluminum:Corrosion-resistant extrusions favored in coastal and chemical processing environments.
- Fiberglass:Pultruded profiles offering dielectric properties for utility and data center applications.
Steel dominates installed volume; composite is climbing the fastest.
Installation Type:
Customer type bifurcation separates enterprise distribution centers specifying automatic ecosystems from regional warehouse operators prioritizing manual and semi-automatic capital preservation.
- Automatic:Sensor-activated door cycles synchronized with vehicle restraints and dock levelers through building management platforms. Third-party logistics operators with centralized engineering functions are specifying these systems at new construction sites in Dallas-Fort Worth and the Inland Empire. Conveyor throughput matching requirements are mandating touchless trailer docking cycles.
- Manual:Chain-hoist or push-up operation retained in secondary distribution markets and low-cycle manufacturing facilities. Capital-constrained warehouse operators are preserving existing door frames through modular retrofit sealing technologies rather than full automatic replacement.
- Semi-Automatic:Motor-assisted operation with manual initiation, bridging cost and functionality for mid-tier distribution centers.
- Specialty:Explosion-rated, cleanroom, and radiation-shielded configurations for pharmaceutical and nuclear applications.
Manual installations retain the largest base; automatic systems are gaining share fastest.
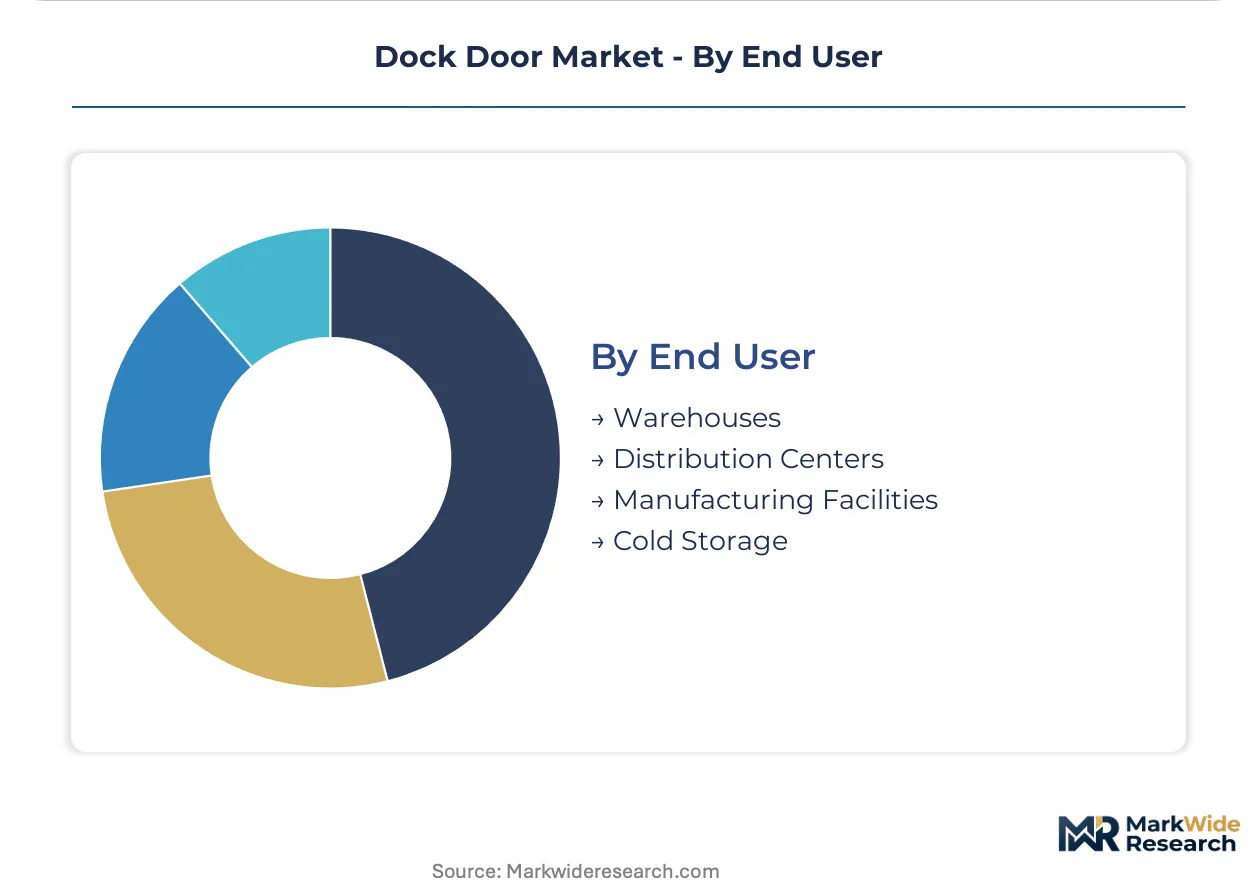
End User:
Application maturity varies sharply, with distribution centers and cold storage driving technology adoption while manufacturing facilities and warehouses lag in upgrade cycles.
- Distribution Centers:High-cycle environments with automated sorting infrastructure demanding synchronized dock door, leveler, and restraint system programming. E-commerce fulfillment networks are expanding dock door density to match conveyor throughput demands. National grocery and parcel delivery networks now centralize equipment decisions through capital engineering departments.
- Cold Storage:Temperature-controlled logistics facilities requiring R-20 rated sectional doors with thermally broken frames to minimize energy loss. US Department of Energy commercial envelope standards are tightening thermal performance thresholds for loading bay openings in this vertical. Pharmaceutical distribution operators are responding fastest to air infiltration documentation requirements.
- Warehouses:General storage facilities with variable cycle demands and legacy infrastructure constraints.
- Manufacturing Facilities:Production-integrated loading bays with specialized dimensional and environmental requirements.
Distribution centers command the largest share; cold storage shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in loading bay equipment are reshaping regional manufacturing footprints, with fabrication capacity concentrating near automated distribution corridors while component sourcing spans multiple continents.
United States
OSHA fall protection mandates and US Department of Energy envelope standards are accelerating dock door replacements across temperature-controlled logistics. The Dallas-Fort Worth metro anchors the largest concentration of new automated distribution centers, where e-commerce fulfillment networks are expanding dock density to match conveyor throughput. Texas and California's Inland Empire together account for the majority of domestic automatic installation demand.
Germany
REACH compliance and CE marking requirements for industrial entrance systems elevate specification thresholds for cross-border logistics operators. The country's engineering fabricators supply automated entrance systems that compete on building management platform integration density. Bavaria and North Rhine-Westphalia host the densest clusters of dock leveler and restraint system manufacturing serving European cold chain infrastructure.
China
GB standards for commercial building energy efficiency and MIIT industrial upgrading programs are compressing upgrade cycles for legacy warehouse stock. Yangtze River Delta and Pearl River Delta manufacturing bases export steel sectional door components while domestic demand concentrates in automated logistics parks near Shanghai and Shenzhen. Dual carbon goals are pushing specification toward thermally broken frame designs.
Japan
METI energy conservation standards for commercial facilities mandate air infiltration documentation across loading bay openings. Kanto and Kansai industrial corridors specify high-cycle roll-up doors for pharmaceutical distribution and precision manufacturing. JIS certification requirements shape supplier qualification timelines for multinational logistics operators with centralized procurement functions.
India
BIS thermal performance standards and PLI scheme incentives for cold chain infrastructure are driving insulated steel door demand. Maharashtra and Gujarat host the fastest-expanding automated distribution corridors, where third-party logistics operators are consolidating specification authority through capital engineering departments. CDSCO pharmaceutical distribution regulations accelerate R-20 rated sectional door installations in temperature-controlled verticals.
Dock Door Market Competitive Environment
Concentration sits with diversified industrial entrance specialists and captive hydraulic component producers, while mid-tier assemblers face margin compression from raw material volatility and certification barriers. The vendor base stratifies across three archetypes: integrated building entrance platforms, dock equipment pure-plays, and regional steel fabricators. M&A activity targets software integration capabilities, and capacity expansion clusters near automated distribution corridors in Texas and California.
Among diversified entrance specialists, ASSA ABLOY Group and Hörmann LLC occupy positions defined by building management platform convergence, while Rite-Hite exemplifies the dock equipment pure-play archetype through captive manufacturing of hydraulic components. These three anchors represent contrasting strategic postures: European platform integration, German engineering scale, and North American vertical control over critical subsystems.
| Leading Market Players |
|---|
| Rite-Hite |
| ASSA ABLOY Group |
| Hörmann LLC |
| Blue Giant Equipment Corporation |
| Pentalift Equipment Corporation |
| DoorHan |
| ALUTECH Group |
| Overhead Door Corporation |
| Rytec Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with galvanized steel mills lock in both supply access and price visibility for sectional door manufacturers serving automated distribution corridors in Texas and California. These arrangements insulate tier-one fabricators from raw material volatility while forcing mid-tier assemblers into spot market exposure.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. ISO 9001 certification tiers and thermally broken frame specifications differentiate price bands, with R-20 rated composite doors commanding substantial premiums over uninsulated steel alternatives. Pricing pressure stems from galvanized steel input volatility compressing margins at the standard tier. Regional warehouse operators in secondary markets exhibit highest price sensitivity, while national third-party logistics operators with centralized procurement prioritize integration density over unit cost.
Supply Chain Analysis
Strategic stockpiling of hydraulic components and aluminum extrusions prevails among tier-one dock leveler manufacturers, whereas just-in-time inventory governs downstream door panel assembly. Supply concentration centers on China for steel coil, Germany for precision hydraulics, and domestic US fabrication for final assembly. The chain rests on captive production of dock levelers, single-source vulnerability for high-cycle door operators, and distribution runs through national distributor networks with regional contractor fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification authority fragmentation creates white-space opportunities as corporate supply chain engineers displace regional contractors in equipment selection. This demand-side shift fragments procurement into enterprise centralized frameworks and capital-constrained retrofit segments.
For Market Incumbents: Secure backward integration into hydraulic component production to defend against captive supply advantages held by Rite-Hite and similar pure-plays. Expand capacity in Dallas-Fort Worth and California's Inland Empire to match e-commerce fulfillment network buildouts. Certification investment in ISO 9001 and OSHA-compliant restraint systems preserves specification access to multinational logistics operators.
For New Entrants and Emerging Players: Retrofit sealing technology services represent a service-layer gap where incumbents under-serve capital-constrained warehouse operators. Target secondary distribution markets in the US Southeast and Midwest where legacy sectional door frames predominate. A modular upgrade path go-to-market angle bypasses entrenched automatic installation competitors while addressing DOE efficiency mandate compliance.
For Investors and Strategic Acquirers: Capital is best deployed toward software-integrated dock ecosystem specialists with building management platform connectivity. Long-term viability hinges on convergence with automated logistics infrastructure rather than hardware durability alone. Watch for inflection when third-party logistics operators centralize specification authority through capital engineering departments at multi-site fulfillment footprints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydraulic Components | Captive supply of dock levelers insulates margin compression from steel volatility. |
| Building Management Platform Convergence | Integration density with ASSA ABLOY and similar platforms secures enterprise specification. |
| Modular Retrofit Sealing Technology | Capital-constrained operators in secondary markets preserve frames while meeting DOE standards. |
| Temperature-Controlled Logistics Specialization | R-20 rated composite doors capture pharmaceutical and cold chain infrastructure investment. |
| Automated Distribution Corridor Expansion | Capacity in Texas and California matches e-commerce conveyor throughput demands. |
Study Parameters
Cross-validation between facility engineering interviews and regulatory filing analysis anchors the qualitative findings. Primary fieldwork engaged maintenance directors at distribution centers, OEM procurement teams for dock equipment, aftermarket service heads, and plant engineers at cold storage facilities. Secondary sources included OSHA enforcement records, US Department of Energy commercial envelope standard documentation, customs trade data for steel and aluminum inputs, and SEC filings from diversified industrial entrance specialists. Bottom-up installation data triangulated against top-down construction spending patterns across automated distribution corridors.
Sensitivity analysis tested demand assumptions across the projection horizon. The analytical framework modeled product type, material grade, installation automation level, and end-use vertical dimensions. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers including e-commerce fulfillment network expansion and regulatory upgrade cycle compression. Forecast inputs incorporated conveyor throughput matching requirements and thermal performance certification timelines.
Forecasts assume regulatory continuity in US Department of Energy envelope standards and OSHA fall protection mandates; material policy shifts would require re-modeling. Supply chain assumptions reflect stable galvanized steel pricing and hydraulic component availability. Revision becomes warranted when raw material volatility exceeds historical bands or when specification authority recentralization accelerates beyond modeled rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Excavator Wheels Market
Construction Equipment
Powered Screed Market
Construction Equipment
France Construction Equipment Market
Construction Equipment
Vertical Mill Market
Construction Equipment
Backhoe Loaders Market
Construction Equipment
Global Tablet Press Machine Market
Construction Equipment
Laser Welding Equipment Market
Construction Equipment
Welding Fume Extraction Equipment Market
Construction Equipment
Cutter Suction Dredger (CSD) Market
Construction Equipment
Global Airport Snow Removal Vehicles and Equipment Market
Construction Equipment
Thermal Spray Equipment Market
Construction Equipment
Arc Welding Equipment Market
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
Concrete NDT Testing Equipment Market
Construction Equipment
Asia Pacific Construction Equipment Rental Market
Construction Equipment
Fixed Crane Market