
 Vietnam Crane Market | 2026-2036
Vietnam Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Crane Market Analytics
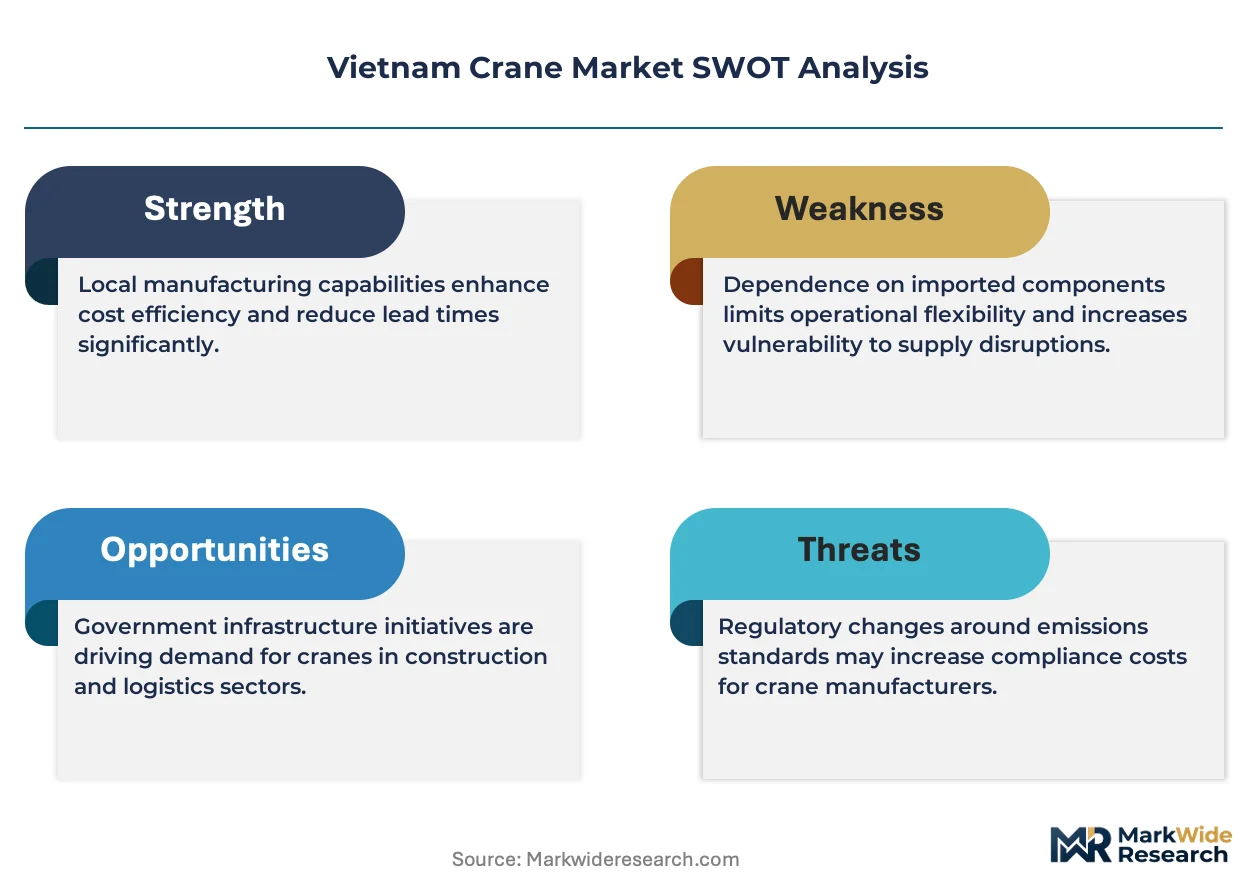
Telematics integration with load-moment indicators is rewriting how crane fleets manage uptime and safety compliance in Vietnam. Konecranes PLC leverages its port equipment heritage to anchor container handling contracts at Cai Mep-Thi Vai deepwater terminals. Liebherr-International AG sustains premium positioning through tower crane manufacturing scale at its regional hub strategy. Palfinger Marine Vietnam Co Ltd specializes in offshore pedestal cranes for Vietnam's expanding oil and gas platform maintenance sector.
A crane is a machine equipped with ropes, wire ropes, chains and sheaves for lifting and moving heavy materials, with load capacities ranging from under one ton to over one thousand tons depending on configuration and boom geometry. Its primary industrial purpose centers on vertical displacement and horizontal transport of construction materials, manufactured components, and bulk cargo across jobsites, factories, and port facilities. Mobile cranes command the largest installed base in Vietnam due to flexibility across dispersed infrastructure sites, while tower cranes capture disproportionate revenue per unit from high-rise residential towers in Hanoi and Ho Chi Minh City. Electric crane technology is gaining fastest traction as factory end-users face carbon intensity scrutiny from export customers.
Vietnam's Ministry of Construction enforces crane installation and operation standards through Circular 09, mandating third-party inspection certificates that filter out aging mechanical fleets. The country's national standards body applies BIS-aligned lifting equipment protocols for imported cranes, creating compliance barriers for non-certified Asian suppliers. The General Department of Vietnam Customs coordinates with the Ministry of Industry and Trade on machinery import duty classifications that influence total cost of ownership for European versus Chinese-origin equipment. Stakeholders must monitor how impending amendments to the Law on Construction reshape crane operator licensing requirements and rental company liability frameworks.
Market Dynamics
Circular 09 certification mandates from Vietnam's Ministry of Construction are filtering aging mechanical crane fleets from rental markets, forcing capital rotation toward electric-hydraulic models and compressing residual values for non-compliant equipment.
Growth Catalysts
- North-South Expressway Infrastructure:Megaprojects spanning 2,000 kilometers are accelerating crawler crane deployment for bridge piling and precast segment lifting across multiple provinces.
- Telematics Integration:Load-moment indicators paired with fleet management software are rewriting uptime optimization and safety compliance protocols for rental operators.
- Cai Mep-Thi Vai Port Expansion:Deepwater terminal capacity additions are anchoring demand for ship-to-shore container handling cranes and rubber-tired gantry systems.
Market Restraints
- Steel Input Volatility:Boom and mast fabrication costs fluctuate with regional steel pricing, compressing margin visibility for domestic crane fabricators.
- European Equipment Cost Premium:Import duty classifications coordinated by Vietnam Customs and the Ministry of Industry and Trade elevate total cost of ownership for EU-origin cranes versus Chinese alternatives.
- Skilled Operator Scarcity:Licensing requirements under impending Law on Construction amendments are widening the gap between certified personnel and fleet expansion needs.
Strategic Opportunities
- Dong Nai-Binh Duong Industrial Cluster:Factory automation and export manufacturing growth are creating concentrated demand for overhead bridge cranes in automated warehousing.
- Offshore Platform Maintenance:Vietnam's oil and gas sector expansion is opening specialized demand for pedestal cranes with marine-grade corrosion resistance.
- Carbon Intensity Compliance:Export-facing manufacturers are prioritizing electric crane technology to satisfy customer supply chain decarbonization audits.
Industry Challenges
- Third-Party Inspection Bottlenecks:Circular 09 certification timelines are stretching equipment commissioning schedules and delaying project handovers.
- Legacy Fleet Obsolescence:Aging mechanical cranes face accelerated depreciation as rental companies struggle to place non-compliant units in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Crane Market |
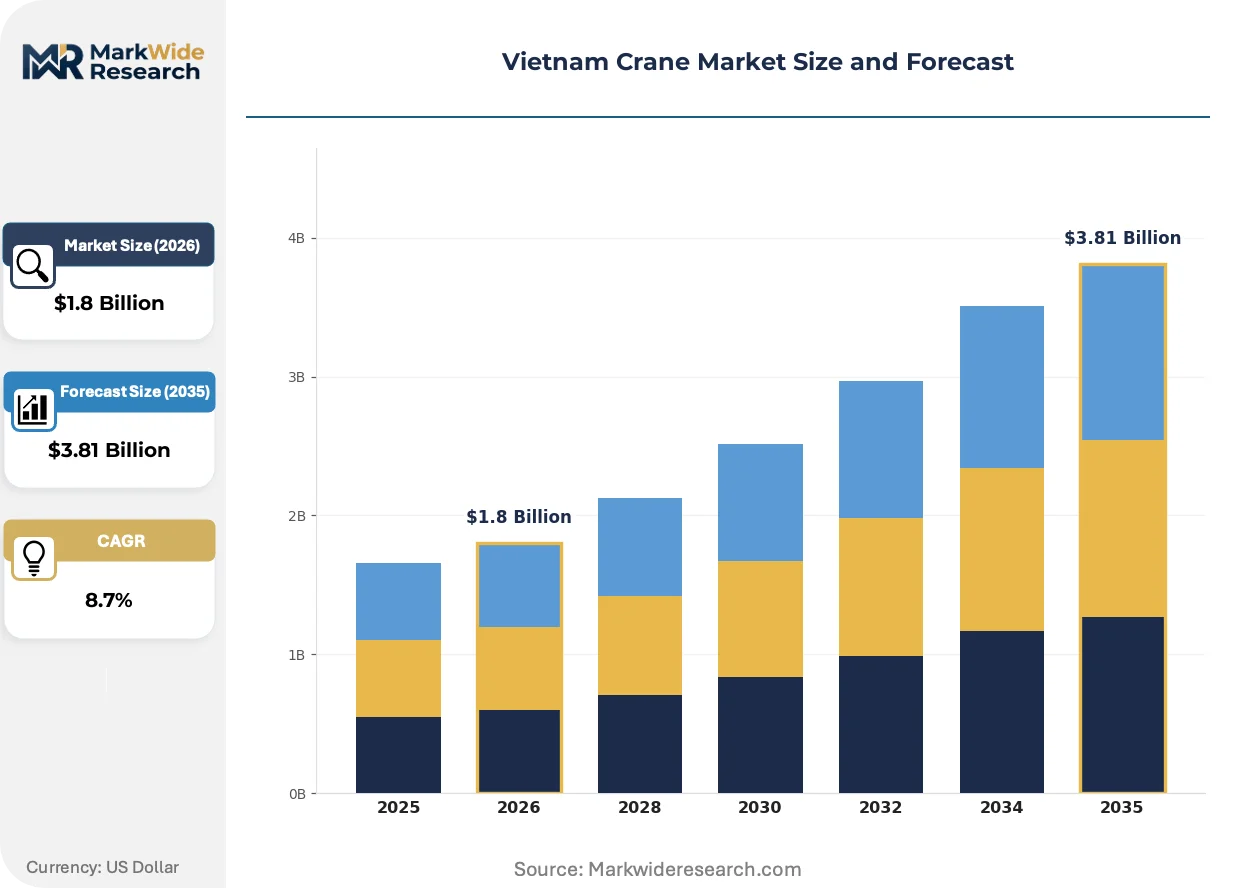
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Crane, Tower Crane, Overhead Crane, Crawler Crane End User: Construction, Manufacturing, Shipping, Mining Application: Heavy Lifting, Load Handling, Transportation, Site Development Technology: Hydraulic, Electric, Pneumatic, Mechanical |
| Companies Covered | Cargotec OYJ, Palfinger Marine Vietnam Co Ltd, Konecranes PLC, Favelle Favco Group, Vietnam Steel Structures and Lifting Equipment JSC, Liebherr-International AG, Sumitomo Heavy Industries Construction Cranes Co Ltd, Quang Lien Crane Elevator Co Ltd, Tadano Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Crane Market Evolving Landscape
Digital instrumentation and predictive maintenance protocols are displacing reactive service models across Vietnam's crane rental sector, compressing downtime windows and reshaping fleet management economics.
Telematics platforms integrating load-moment indicators with cloud-based fleet dashboards are digitizing how rental operators schedule preventive maintenance and demonstrate safety compliance to project owners. Construction conglomerates in Ho Chi Minh City are adopting these systems fastest, using real-time data to negotiate insurance premiums and liability terms. The structural consequence is a widening capability gap between digitized fleets and mechanical-only competitors.
Circular 09 enforcement by Vietnam's Ministry of Construction is mandating third-party inspection certificates that filter out aging equipment and elevate documentation burdens for importers. Industrial consequence includes accelerated replacement cycles for rental fleets and consolidation pressure on smaller operators lacking capital for certified replacements. Tower crane segments in Hanoi high-rise construction are responding fastest, with project owners now pre-qualifying only Circular 09-compliant equipment.
Rental service unbundling is separating crane supply from operator provision and maintenance liability across Vietnam's infrastructure sector. EPC contractors are shifting toward bare-rental agreements with self-managed operator pools, displacing full-service contracts. This pattern concentrates in the Dong Nai-Binh Duong industrial corridor where multinational manufacturers prefer direct control over certified personnel and maintenance scheduling.
Vietnam Crane Market Segmentation
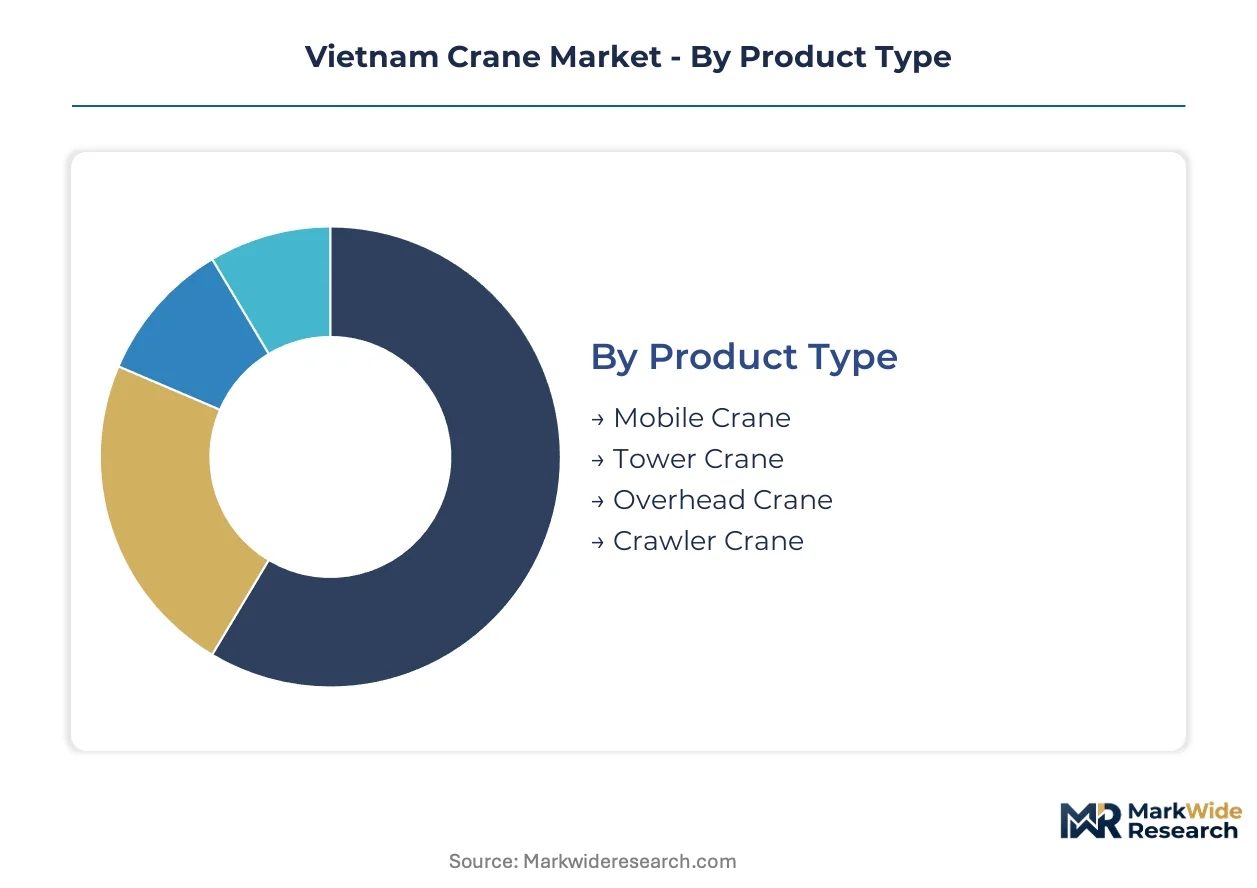
Crane segmentation in Vietnam reflects divergent capital intensity and replacement cycles across infrastructure verticals. Rental fleet composition and end-user procurement patterns vary sharply by product mobility, power source, and project duration.
Product Type:
Mobile cranes turn over fastest in rental fleets due to road-wear depreciation and multi-site deployment stress, while overhead bridge units in factory settings cycle slowest with decade-plus service lives.
- Mobile Crane:Truck-mounted and all-terrain configurations dominate dispersed infrastructure sites across Vietnam's North-South expressway corridor. Telematics integration is accelerating fastest here as rental operators track utilization across province-hopping deployments.
- Tower Crane:Fixed-base luffing and hammerhead designs anchor high-rise residential construction in Hanoi and Ho Chi Minh City. Circular 09 certification mandates are compressing replacement cycles for aging mechanical units in this segment.
- Overhead Crane:Bridge and gantry systems serve automated warehousing in the Dong Nai-Binh Duong industrial cluster.
- Crawler Crane:Lattice-boom and telescopic crawler units handle heavy piling and precast lifting on megaproject bridge sites.
Mobile cranes dominate installed base. Tower cranes are where expansion concentrates.
End User:
Cost tier stratification separates capital-rich EPC contractors from price-sensitive factory maintenance departments.
- Construction:General contractors and specialized infrastructure EPCs deploy the full crane type spectrum from mobile units for roadwork to tower cranes for vertical building. Circular 09 compliance documentation now gates pre-qualification for public sector megaprojects.
- Manufacturing:Electronics and textile exporters in northern industrial zones drive overhead crane demand for automated material handling. Carbon intensity audits from European customers are shifting procurement toward electric-hydraulic models.
- Shipping:Terminal operators at Cai Mep-Thi Vai deepwater ports require ship-to-shore and rubber-tired gantry systems.
- Mining:Coal and mineral extraction sites in Quang Ninh province utilize heavy-lift crawlers for equipment maintenance.
Construction commands the largest fleet volume. Manufacturing is climbing the fastest on export factory automation.
Application:
Volume concentration tracks project scale, with heavy lifting and load handling separating capital-intensive infrastructure from repetitive factory workflows.
- Heavy Lifting:Bridge segment placement, turbine installation, and industrial equipment positioning demand high-capacity crawler and all-terrain mobile units. North-South expressway bridge piling sites concentrate this demand across multiple provinces.
- Load Handling:Warehouse pallet movement, container stacking, and assembly line feeding utilize overhead bridge and gantry configurations. Dong Nai-Binh Duong logistics parks are expanding this application fastest.
- Transportation:Road and rail cargo transfer operations deploy mobile cranes for intermodal flexibility.
- Site Development:Land clearing and foundation preparation utilize lighter mobile units for material redistribution.
Heavy lifting dominates capital deployment. Load handling is where fleet digitization concentrates.
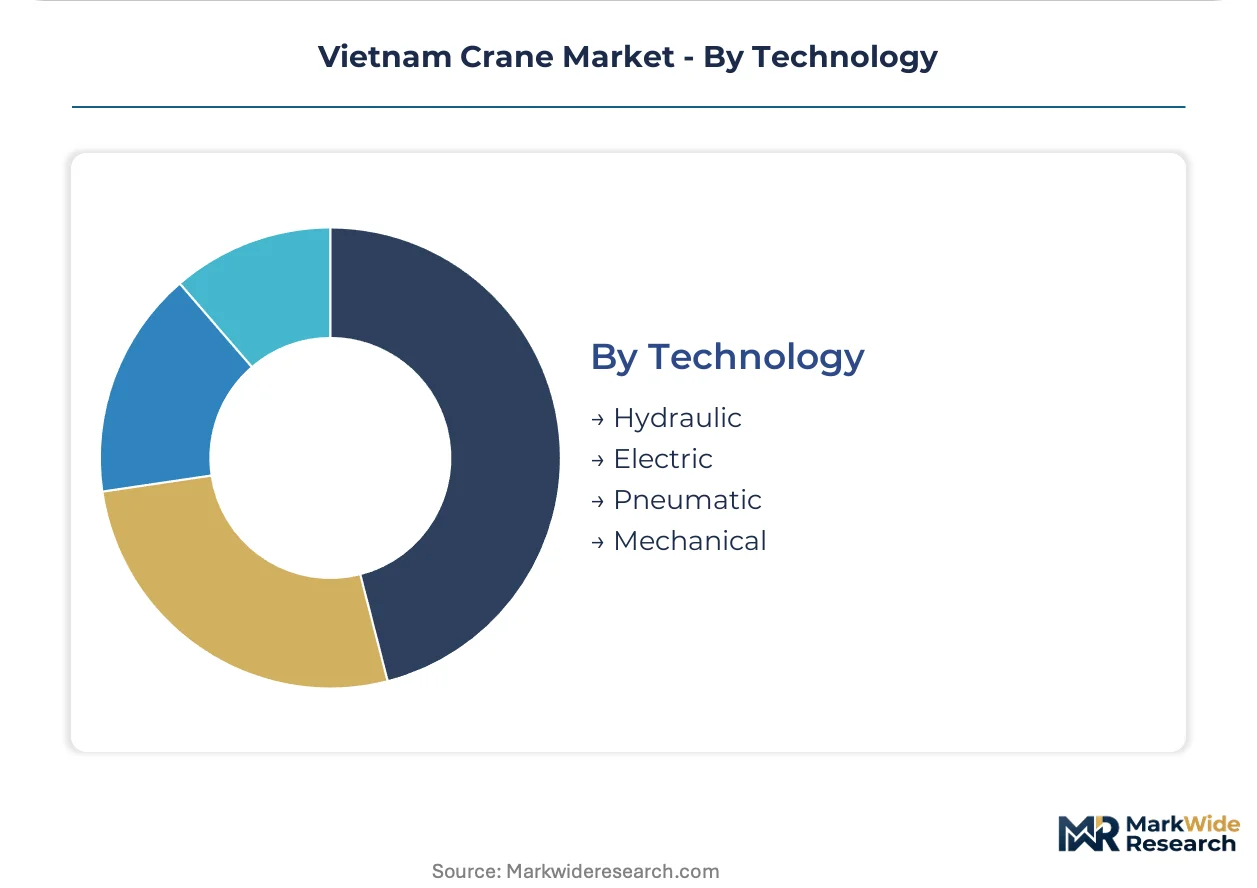
Technology:
Maturity curves separate legacy mechanical systems facing obsolescence from electric-hydraulic platforms capturing regulatory preference.
- Hydraulic:Fluid-power actuation systems deliver precise load control for mobile and crawler crane booms. Vietnam's rental market retains substantial hydraulic penetration due to technician familiarity and parts availability.
- Electric:Motor-driven hoists and trolleys are displacing mechanical systems in factory overhead cranes. Export-facing manufacturers prioritize this technology to satisfy supply chain decarbonization audits from European customers.
- Pneumatic:Compressed-air systems serve specialized explosion-risk environments in chemical processing.
- Mechanical:Gear and clutch-based legacy systems face accelerated depreciation under Circular 09 certification filters.
Hydraulic systems dominate current installed base. Electric platforms are gaining share fastest on factory compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's crane equipment flows northward into China and southward into ASEAN manufacturing hubs, with domestic absorption concentrated in three industrial corridors. The country's infrastructure buildout creates distinct demand pockets across its geography.
Ho Chi Minh City Metro
High-rise residential towers and metro line construction dominate mobile and tower crane deployment. Circular 09 enforcement by Vietnam's Ministry of Construction filters aging mechanical fleets from rental pools. The Thu Thiem new urban area and District 2 logistics zones anchor demand for electric-hydraulic models.
Dong Nai-Binh Duong Industrial Cluster
Electronics and textile exporters drive overhead bridge crane procurement for automated warehousing. Carbon intensity audits from European customers accelerate electric crane adoption. Bien Hoa and Thuan An industrial parks concentrate factory automation investments.
Hanoi Capital Region
Public sector megaprojects including the Nhat Tan bridge extension and Red River urban development sustain tower crane demand. The Ministry of Construction's operator licensing requirements under pending Law on Construction amendments tighten personnel standards. Long Bien and Gia Lam districts host the densest equipment rental yards.
Cai Mep-Thi Vai Deepwater Port Zone
Container terminal expansion anchors demand for ship-to-shore cranes and rubber-tired gantry systems. Vietnam Customs coordinates with the Ministry of Industry and Trade on import duty classifications affecting European versus Chinese-origin equipment. Ba Ria-Vung Tau province hosts the deepest vessel berths in Southeast Asia.
North-South Expressway Corridor
Bridge piling and precast segment lifting across 2,000 kilometers accelerate crawler crane deployment. Provincial construction departments apply BIS-aligned lifting equipment protocols for imported machinery. Quang Ngai and Khanh Hoa provinces host the most active bridge construction sites.
Vietnam Crane Market Competitive Landscape
On the supply side, the industry is bifurcated between European premium fabricators and Asian volume producers, with domestic Vietnamese assemblers occupying a mid-tier position. Market structure reflects import dependency for high-capacity units versus local fabrication for standard overhead systems. Three archetypes dominate: port equipment specialists leveraging maritime heritage, diversified industrial machinery conglomerates with regional hub strategies, and domestic joint ventures serving factory automation demand. Competitive moves center on telematics integration partnerships and fleet certification compliance services.
Among European-origin specialists, Liebherr-International AG and Konecranes PLC exemplify divergent positioning archetypes. Liebherr-International AG occupies a position within the premium tower and mobile crane segment, while Konecranes PLC anchors container handling specialization at deepwater terminals. Palfinger Marine Vietnam Co Ltd represents the offshore pedestal crane niche serving oil and gas platform maintenance. Domestic Vietnamese fabricators including Vietnam Steel Structures and Lifting Equipment JSC and Quang Lien Crane Elevator Co Ltd sit within the standard overhead bridge crane tier, supplying factory automation demand in the Dong Nai-Binh Duong corridor.
| Leading Market Players |
|---|
| Cargotec OYJ |
| Palfinger Marine Vietnam Co Ltd |
| Konecranes PLC |
| Favelle Favco Group |
| Vietnam Steel Structures and Lifting Equipment JSC |
| Liebherr-International AG |
| Sumitomo Heavy Industries Construction Cranes Co Ltd |
| Quang Lien Crane Elevator Co Ltd |
| Tadano Ltd |
| Others |
Value Network & Pricing Analysis
Undercapacity in European-origin crawler crane fabrication is concentrating pricing power with premium suppliers while compressing margins for Vietnamese rental operators forced into accelerated fleet replacement under Circular 09. Steel input volatility and import duty differentials between EU and Chinese equipment are amplifying total cost of ownership spreads across the installed base.
Pricing Analysis
The technology-generation pricing gap separates electric-hydraulic models commanding premium lease rates from aging mechanical units facing accelerated depreciation. Pricing stratifies across Circular 09-certified premium tiers, import-origin brand tiers, and non-compliant residual-value economy tiers. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the mechanical resale tier is intensifying because rental companies cannot place non-compliant units in secondary markets. Factory automation buyers in Dong Nai-Binh Duong exhibit lowest price sensitivity due to carbon audit compliance requirements, while provincial infrastructure contractors show highest sensitivity to daily rental rates.
Supply Chain Analysis
Extended payment terms from 90 to 180 days are becoming standard for ship-to-shore crane procurement at Cai Mep-Thi Vai, stretching working capital for European fabricators. Supply concentrates in Germany, China, and Finland for high-capacity lattice-boom and port handling systems. Boom and mast fabrication draws from regional steel mills in China and South Korea, while electric drivetrain components source from Japanese and German suppliers. Single-source vulnerability in certified hydraulic component supply creates commissioning bottlenecks under Circular 09 inspection timelines. Distribution runs through Ho Chi Minh City-based rental fleet operators with province-hopping deployment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Vietnam's crane rental sector creates niche capture opportunities as Circular 09 compliance filters consolidate fleet ownership toward capitalized operators capable of certified equipment rotation.
For Market Incumbents: Build certification-compliance moats through captive third-party inspection partnerships and telematics-integrated fleet management platforms. Accelerate replacement cycles for aging mechanical units before residual value collapse. Defensive consolidation into Dong Nai-Binh Duong factory automation demand leverages vertical integration into overhead crane maintenance contracts. Channel control through bare-rental agreement standardization displaces full-service competitors. For New Entrants and Emerging Players: Pursue offshore pedestal crane specialization serving Ba Ria-Vung Tau oil and gas platform maintenance, where marine-grade corrosion resistance creates technical barriers. Target the Quang Ninh mining equipment maintenance segment with heavy-lift crawler units for coal extraction sites. White-space exists in electric-hydraulic overhead bridge systems for northern electronics exporters facing European carbon audits. Go-to-market through direct EPC contractor relationships bypasses established rental intermediary networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across telematics-integrated rental fleets as Circular 09 mandates compress replacement cycles and elevate documentation technology spend. Long-term viability centers on fleet scale sufficient to amortize compliance infrastructure across utilization pools. Acquisition targets include domestic Vietnamese fabricators with Dong Nai-Binh Duong customer relationships and European joint ventures with port equipment heritage. The signal to watch is Ministry of Construction amendments to the Law on Construction reshaping operator licensing liability frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Circular 09 Certification Investment | Third-party inspection partnerships gate pre-qualification for public sector megaprojects. |
| Telematics Platform Integration | Load-moment indicator digitization compresses downtime windows and rewrites fleet economics. |
| Electric-Hydraulic Fleet Transition | Carbon intensity compliance satisfies European customer supply chain decarbonization audits. |
| Dong Nai-Binh Duong Geographic Expansion | Factory automation demand concentrates in electronics and textile export manufacturing clusters. |
| Offshore Pedestal Crane Specialization | Marine-grade corrosion resistance opens oil and gas platform maintenance contracts. |
Research Methodology
A spread of perspectives from crane rental fleet managers, EPC contractor procurement leads, Ministry of Construction regulatory officers, and port terminal operations heads converged on the working assumptions shaping this analysis. Primary field engagement combined structured interviews with secondary validation through Vietnam Customs machinery import classifications, Ministry of Industry and Trade duty circulars, and BIS-aligned lifting equipment protocol documentation. Bottom-up equipment deployment tracking across the North-South expressway corridor triangulated with top-down market sizing from rental fleet composition surveys.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling capacity utilization in European fabrication against Vietnamese absorption rates. Segmentation dimensions spanned product mobility class, power source technology, end-use vertical, and regional industrial cluster. CAGRs derived from equipment replacement cycle compression under Circular 09 enforcement and megaproject pipeline visibility. Industry-specific forecast inputs incorporated steel price volatility indices and telematics adoption curves from Ho Chi Minh City rental operators.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese equipment suppliers establishing certified service networks would shift outcomes. Macroeconomic deviation in regional steel pricing, regulatory amendments to operator licensing requirements, or technological breakthroughs in battery-electric crane propulsion would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
GCC Construction Equipment/Machinery Rental Market
Construction Equipment
Bitumen Sprayer Market
Construction Equipment
Snow Removal Market
Construction Equipment
Mortar Testing Equipment Market
Construction Equipment
Concrete Grinder Market
Construction Equipment
France Construction Equipment Market
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
Truck Mounted Concrete Mixer Market
Construction Equipment
Industrial and Commercial Floor Scrubbers Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
Bulldozer Market
Construction Equipment
Construction Helmet Market
Construction Equipment
Gear Grinding Machine Market
Construction Equipment
Europe Air Compressor Market
Construction Equipment
Heating Roller Press Calender Machine Market
Construction Equipment
Fogging Machine Market