
 Dust Suppression Fog Cannon Market | 2026-2036
Dust Suppression Fog Cannon Market Size, Share, and Industry Trends Forecast 2026-2036
Dust Suppression Fog Cannon Market Insights
Chinese fog cannon manufacturers are repositioning toward higher-margin electrostatic and waterless systems for export markets. HENNLICH ENGINEERING leverages its Central European manufacturing base to anchor premium stationary installations across German quarrying operations. DUZTECH AB competes through Nordic-engineered high-pressure platforms optimized for sub-zero mining environments. Qingdao TOYO Industry Company dominates domestic Chinese construction sites with cost-optimized mobile units while extending distribution into Southeast Asian infrastructure projects.
A dust suppression fog cannon is a mechanized aerosol generation system that propels atomized water droplets—typically 10–200 microns in diameter—through pressurized nozzles or centrifugal disc packs to agglomerate airborne particulate matter. These systems operate at pressures ranging from 10 to 80 bar and serve primarily to suppress respirable dust in open-pit mining, demolition, and bulk material handling where conventional static sprinklers prove ineffective. Mobile fog cannon configurations lead volume shipments in emerging markets due to lower capital barriers and site-to-site flexibility, while stationary systems command margin pools in permanent mining installations where continuous duty cycles justify infrastructure investment. High-pressure technology occupies the fastest-expanding segment as operators pursue smaller droplet spectra for superior PM2.5 and respirable silica capture efficiency.
EPA enforcement of National Ambient Air Quality Standards and MSHA's respirable crystalline silica rule directly shape product specifications and replacement demand across North American mining and demolition sectors. REACH and the EU Green Deal's industrial emissions framework compel European OEMs to document chemical safety of wetting agents and reduce water consumption in cannon operation. Australia's Work Health and Safety Regulations and state-level environmental protection acts in Western Australia and Queensland mandate real-time dust monitoring paired with engineered suppression, creating specification pull for integrated cannon-sensor systems. Stakeholders must monitor evolving interoperability standards between fog cannon fleets and site-wide digital air quality management platforms.
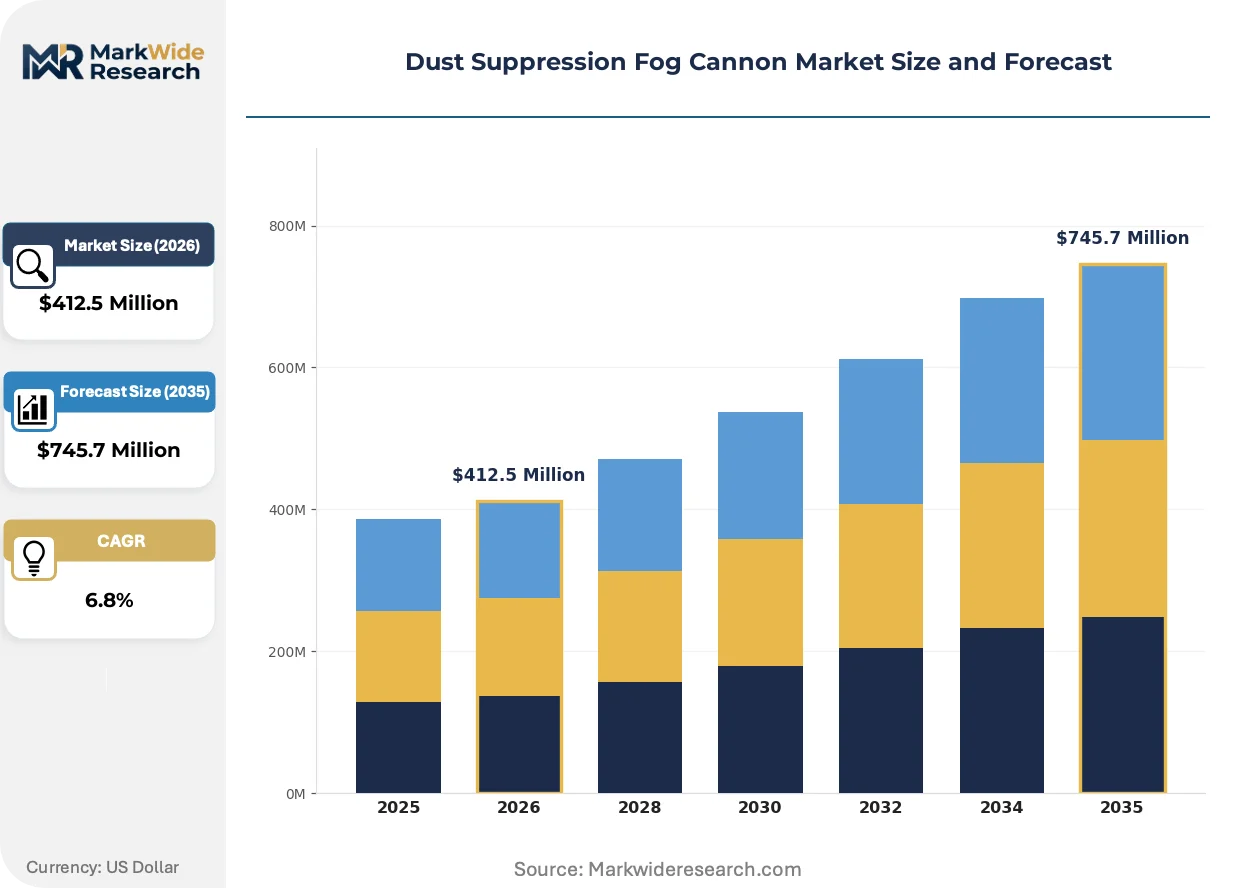
Market Dynamics
High-pressure atomization technology is compressing droplet spectra below 50 microns, forcing equipment replacement cycles across open-pit mining and demolition sectors as operators chase PM2.5 compliance thresholds.
Growth Catalysts
- MSHA respirable crystalline silica enforcement:Underground and surface mining operators in the United States face mandatory exposure limits, accelerating specification upgrades toward high-pressure cannon systems with real-time monitoring integration.
- Western Australia iron ore expansion:Pilbara basin producers are procuring integrated cannon-sensor fleets to satisfy Work Health and Safety Regulations and state environmental protection mandates.
- Electrostatic agglomeration maturation:Waterless suppression platforms are penetrating German quarrying and Chilean copper corridors where water scarcity constrains conventional wet systems.
Market Restraints
- Specialized alloy nozzle supply concentration:Precision-machined ceramic and tungsten carbide components concentrate among Central European and Japanese suppliers, exposing lead time volatility.
- High-pressure pump capex intensity:80-bar rated positive displacement pumps and corrosion-resistant manifold assemblies inflate upfront system costs versus conventional sprinkler infrastructure.
- REACH chemical documentation burden:Wetting agent formulations require full toxicity dossiers under EU chemicals regulation, extending product registration timelines for additive-dependent cannon operators.
Strategic Opportunities
- Southeast Asian infrastructure buildout:Indonesian and Vietnamese construction sectors remain underpenetrated by automated suppression, creating first-mover positioning for mobile cannon distributors.
- EU Green Deal industrial emissions framework:Carbon border adjustments and water efficiency mandates are incentivizing electrostatic and recycled-water cannon retrofits across cement and steel processing.
- Digital air quality platform convergence:API-standardized cannon fleets integrating with site-wide IoT sensor networks are opening recurring software revenue streams for OEMs.
Industry Challenges
- Field calibration expertise scarcity:Proper droplet size distribution validation and nozzle wear monitoring require specialized technicians absent in remote mining labor pools.
- Legacy sprinkler infrastructure lock-in:Permanent water line investments and established maintenance contracts impede cannon system substitution at mature quarrying sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dust Suppression Fog Cannon Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile, Stationary, Towable, Fixed Technology: High-Pressure, Low-Pressure, Electrostatic, Waterless End User: Mining, Construction, Agriculture, Industrial Application: Road Construction, Demolition, Aggregate Handling, Air Quality Management |
| Companies Covered | HENNLICH ENGINEERING, WLP S.r.l, DUZTECH AB, Spraystream, PROTECT A/S, FRUTIGER Company AG, Qingdao TOYO Industry Company, Enveks, Gemmo Group s.r.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dust Suppression Fog Cannon Market Trends and Innovations
Atomization hardware, regulatory telemetry mandates, and procurement digitization are simultaneously reshaping equipment specifications, compliance workflows, and vendor-customer relationships across dust-intensive industries.
Ultrasonic atomization is decentralizing droplet generation away from centralized high-pressure pump skids toward distributed nozzle arrays with individual piezoelectric drivers. Australian iron ore operators are piloting these modular systems for targeted dust hooding at crusher discharge points. The architecture collapses hydraulic infrastructure requirements while enabling zone-specific suppression intensity adjustments.
REACH and the EU Green Deal's industrial emissions framework are compelling wetting agent disclosure and water consumption documentation across European cement and steel processing. OEMs must now certify chemical safety dossiers for surfactant additives and demonstrate closed-loop water recycling rates. German quarrying clusters are responding by specifying electrostatic and waterless platforms that eliminate chemical compliance exposure entirely.
Site-wide digital air quality management platforms are compressing cannon procurement decisions into integrated fleet-sensor contracts. Mining operators in Western Australia and Chile now require API interoperability between cannon controllers and third-party dust monitoring networks. Equipment vendors are unbundling hardware from software subscriptions, with telemetry-enabled service agreements displacing traditional capital sales in permanent installations.
Dust Suppression Fog Cannon Market Segmentation
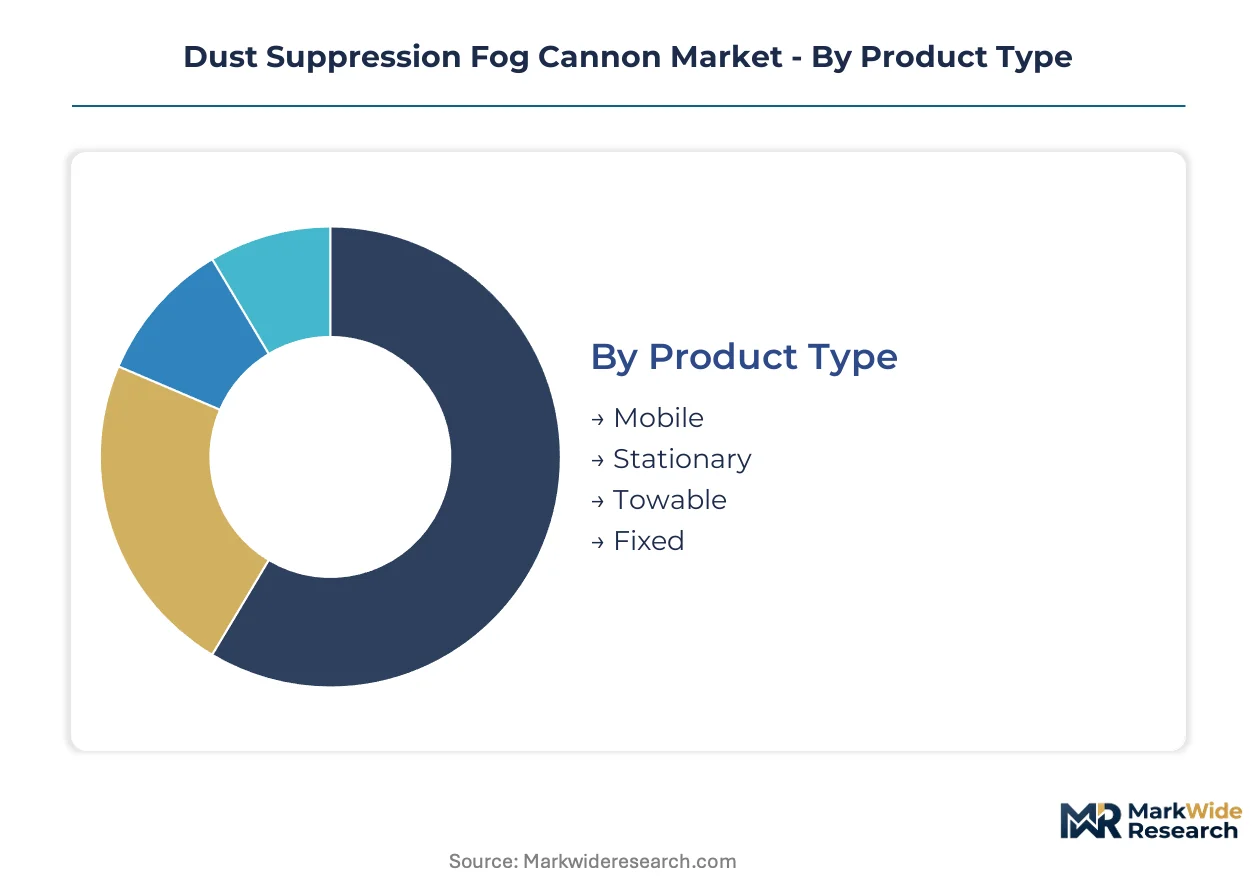
Segmentation in the dust suppression fog cannon market reveals distinct procurement patterns across mobility requirements, atomization physics, and regulatory exposure. Equipment buyers prioritize capital efficiency in emerging markets while mature mining jurisdictions specify integrated compliance architectures.
Product Type:
Mobile configurations dominate shipment volumes through lower capital barriers and site flexibility, while stationary systems command premium positioning in permanent installations with continuous duty cycles.
- Mobile:Self-propelled or trailer-mounted units with onboard water tanks and diesel power packs serve construction and short-term mining contracts. Demand concentrates in Indonesian infrastructure corridors and Vietnamese quarrying operations where capital constraints favor rental and lease procurement models.
- Stationary:Skid-mounted or foundation-anchored systems with permanent water and electrical infrastructure serve Pilbara iron ore crushers and Chilean Atacama copper concentrators. Western Australian Work Health and Safety Regulations mandate these installations for continuous-process dust sources.
- Towable:Highway-legal trailer configurations bridge mobility and permanence for multi-phase demolition and aggregate screening operations.
- Fixed:Integrated structural installations with dedicated pumping stations serve cement clinker handling and steel slag processing facilities.
Mature deployment sits with stationary systems in Australian and Chilean mining corridors. Newer deployment is concentrated in mobile units across Southeast Asian construction markets.
Technology:
Pressure-rated atomization platforms split the market between proven hydraulic systems and emerging electrostatic alternatives, with water scarcity and chemical compliance driving technology selection.
- High-Pressure:Positive displacement pumps delivering 40-80 bar through ceramic or tungsten carbide nozzles generate sub-50 micron droplets optimized for PM2.5 and respirable silica capture. MSHA enforcement in US surface and underground mining accelerates specification upgrades from legacy low-pressure infrastructure.
- Low-Pressure:Centrifugal fan-driven systems operating below 10 bar serve non-regulated construction dust and agricultural humidification where capital cost outweighs capture efficiency requirements.
- Electrostatic:Corona discharge agglomeration of particulate matter without water consumption penetrates German quarrying clusters under EU Green Deal water efficiency mandates.
- Waterless:Dry fog and electrostatic precipitation hybrids eliminate wetting agent documentation burdens under REACH for cement and steel processing in water-stressed jurisdictions.
Technology maturity favors high-pressure installations in regulated mining jurisdictions. Steepest expansion trajectory belongs to electrostatic platforms in European and Middle Eastern water-constrained operations.
End User:
Customer segmentation tracks regulatory intensity, with mining procurement driven by occupational exposure limits and construction demand responding to project-based environmental permitting.
- Mining:Open-pit and underground hard rock operations specify integrated cannon-sensor fleets for real-time respirable silica compliance. Western Australia and Chile concentrate replacement demand as operators retrofit legacy sprinkler infrastructure.
- Construction:Road building and urban demolition contractors favor mobile rental fleets with rapid deployment capabilities. Vietnamese and Indonesian infrastructure buildout sustains volume procurement despite lower per-unit pricing.
- Agriculture:Orchard humidification and livestock dust control applications favor low-pressure fan systems with minimal technical servicing requirements.
- Industrial:Cement kilns, steel slag handling, and bulk material terminals specify corrosion-resistant high-pressure platforms with closed-loop water recycling.
Procurement maturity clusters in mining end users with established maintenance protocols. Emerging deployment concentrates in construction sectors with first-time automation adoption.
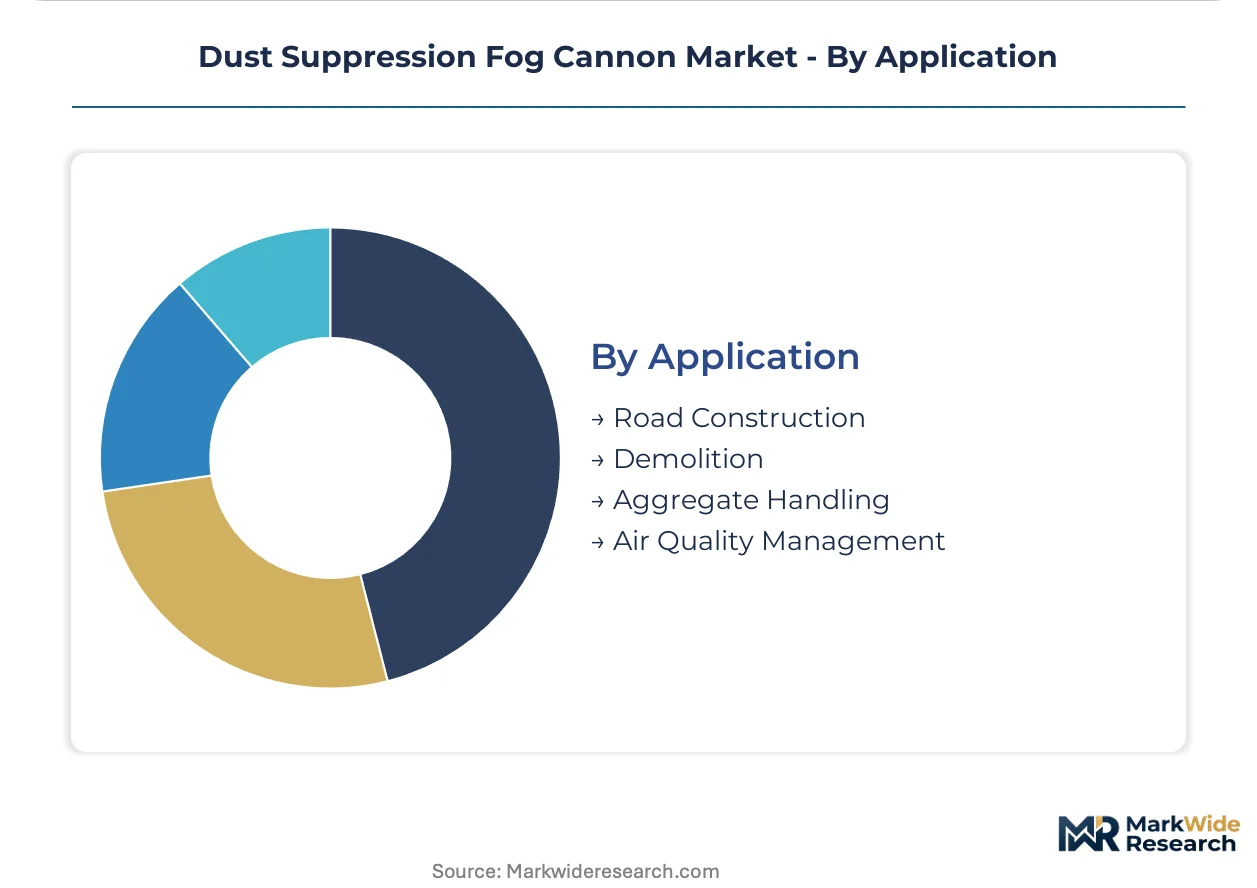
Application:
Use-case segmentation aligns equipment specifications with particulate emission characteristics and regulatory monitoring requirements.
- Road Construction:Mobile cannon fleets accompany asphalt milling and aggregate crushing operations where PM10 emissions trigger municipal air quality violations.
- Demolition:High-pressure systems with rapid-aiming turrets address silica-laden concrete fracture dust in urban containment zones.
- Aggregate Handling:Crusher discharge points and conveyor transfer stations in quarries specify stationary installations with zone-specific suppression intensity.
- Air Quality Management:Municipal and industrial perimeter defense applications deploy electrostatic and waterless platforms for continuous ambient monitoring compliance.
Application maturity resides in aggregate handling with decades of operational precedent. Fastest-gaining application is air quality management as jurisdictions expand perimeter monitoring mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron ore deposits in Western Australia's Pilbara basin and copper reserves in Chile's Atacama Desert anchor procurement demand for high-pressure fog cannon systems. Mining operators in both corridors face tightening respirable silica exposure limits. Equipment specification patterns diverge sharply between water-abundant and water-stressed jurisdictions.
United States
Surface and underground mining operators across Appalachia and the Mountain West are retrofitting legacy sprinkler infrastructure. MSHA respirable crystalline silica enforcement mandates real-time dust monitoring integration at crusher discharge points. Arizona's copper belt and Wyoming's Powder River Basin coal fields concentrate replacement demand for high-pressure cannon fleets.
Australia
Pilbara iron ore producers are procuring integrated cannon-sensor systems to satisfy Western Australia's Work Health and Safety Regulations. BHP and Rio Tinto operations near Port Hedland specify stationary installations with continuous duty cycles. Queensland's Bowen Basin coal mines are following suit with similar engineered suppression mandates.
Germany
Quarrying clusters in North Rhine-Westphalia and Bavaria are specifying electrostatic agglomeration platforms under EU Green Deal water efficiency mandates. KBA-aligned emissions frameworks push OEMs toward waterless technology documentation. The country's cement processing belt favors closed-loop recycled-water retrofits to eliminate REACH wetting agent compliance burdens.
Chile
Atacama copper concentrators face acute water scarcity constraints that favor dry fog and electrostatic precipitation hybrids. State-owned Codelco operations near Calama are piloting waterless suppression for tailings dust control. Antofagasta Minerals' Los Pelambres expansion incorporates high-pressure systems with brackish water compatibility.
China
Domestic construction sites in the Yangtze River Delta and Pearl River Delta absorb cost-optimized mobile units from indigenous manufacturers. Shandong Province's aggregate processing corridor is upgrading to automated suppression for municipal air quality compliance. Beijing-Tianjin-Hebei environmental enforcement drives perimeter defense procurement around bulk material terminals.
Dust Suppression Fog Cannon Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electrostatic and waterless technology platforms for premium positioning. The vendor base stratifies across three maturity levels: legacy hydraulic specialists, regional mobile equipment fabricators, and technology-forward clean-tech entrants. Competitive intensity concentrates on M&A activity for nozzle alloy supply chains and strategic partnerships for digital air quality platform integration.
Within the European premium tier, HENNLICH ENGINEERING and DUZTECH AB exemplify geographic specialization archetypes—Central European manufacturing anchoring stationary installations versus Nordic-engineered platforms for sub-zero environments. Qingdao TOYO Industry Company represents the scale-driven Chinese contingent serving domestic construction and Southeast Asian infrastructure export markets. These three occupy positions that map cleanly onto the technology-mobility matrix: premium stationary, extreme-environment mobile, and cost-optimized volume supply.
| Leading Market Players |
|---|
| HENNLICH ENGINEERING |
| WLP S.r.l |
| DUZTECH AB |
| Spraystream |
| PROTECT A/S |
| FRUTIGER Company AG |
| Qingdao TOYO Industry Company |
| Enveks |
| Gemmo Group s.r.l. |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal water efficiency mandates gate qualified supply and premium-tier pricing access for electrostatic and waterless platform manufacturers, while REACH chemical documentation burdens stratify wetting agent-dependent operators into compliance-cost tiers. Buyers in German quarrying clusters and Chilean copper corridors now require certified closed-loop water recycling rates as table stakes for contract eligibility, compressing margin pools for additive-reliant competitors.
Pricing Analysis
Warranty and telemetry service bundling separates premium stationary installations from unbundled mobile unit transactions in procurement contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence and after-sales service intensity, with MSHA-aligned real-time monitoring integration commanding substantial markups. Cost compression in economy-tier mobile configurations is intensifying because indigenous Chinese manufacturers are scaling export distribution into Southeast Asian infrastructure corridors. Construction contractors in Indonesian and Vietnamese markets exhibit highest price sensitivity, while Pilbara iron ore operators demonstrate lowest sensitivity due to continuous-duty replacement cycles.
Supply Chain Analysis
Dual-sourcing requirements for precision-machined ceramic and tungsten carbide nozzles mandate multi-supplier qualification across Central European and Japanese specialty alloy producers. Manufacturing draws from German precision machining clusters, Japanese ceramic sintering facilities, and Chinese pump assembly operations. Supply chain risk centers on single-source vulnerability for 80-bar rated positive displacement pump castings. Distribution runs through OEM direct sales for stationary mining installations and rental fleet operators for mobile construction deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dust suppression fog cannon market sits in a technology-transition phase, with electrostatic agglomeration platforms displacing legacy high-pressure hydraulic systems in water-stressed jurisdictions.
For Market Incumbents: Extend sensor-telemetry integration capabilities to defend against clean-tech entrants offering waterless platforms with embedded air quality analytics. Anchor backward integration into tungsten carbide nozzle supply chains to secure lead time advantages against ceramic component bottlenecks. Prioritize API-standardized controller development to maintain interoperability positioning against digital-native competitors. For New Entrants and Emerging Players: Enter via Vietnamese and Indonesian construction rental markets where automated suppression penetration remains minimal and capital constraints favor lease procurement models. Target mobile fleet operators with rapid-deployment diesel power pack configurations. Pursue white-label manufacturing partnerships with established pump suppliers to compress time-to-market for high-pressure platform launches. For Investors and Strategic Acquirers: Codelco's pilot deployment of waterless suppression at Calama tailings facilities is the leading indicator that electrostatic technology has crossed commercial viability thresholds for large-scale mining adoption. Position acquisition screening around mid-cap clean-tech entrants with proven corona discharge agglomeration IP and existing KBA or EPA regulatory pre-qualification. Long-term viability hinges on water scarcity intensification across copper and iron ore belts.| Strategic Initiative | Industry Significance |
|---|---|
| Nozzle Alloy Backward Integration | Captive supply of tungsten carbide components insulates OEMs from Japanese supplier lead time volatility. |
| API-Standardized Controller Development | Interoperability with Western Australian dust monitoring networks secures specification pull from BHP and Rio Tinto. |
| Electrostatic Platform R&D Scale-Up | Waterless technology eliminates REACH wetting agent documentation burdens for German cement processors. |
| Southeast Asian Rental Fleet Partnership | Channel control in Vietnamese infrastructure corridors captures first-mover positioning before indigenous competition consolidates. |
| Closed-Loop Water Recycling Certification | EU Green Deal compliance documentation opens premium-tier procurement in North Rhine-Westphalia quarrying clusters. |
Research Methodology
Independent corroboration across mine maintenance directors, plant engineers at cement processing facilities, OEM procurement teams, and aftermarket service heads underwrites the qualitative findings presented in this study. Primary fieldwork combined structured interviews with equipment specification leads at Pilbara iron ore operators and Chilean copper concentrators with secondary validation from EPA enforcement bulletins, MSHA respirable silica rulemaking dockets, and EU ECHA chemical safety dossier databases. Bottom-up shipment tallies by product configuration and top-down demand modeling by end-use sector were cross-referenced for convergence.
Rate-of-change decomposition across the analysis window isolates technology substitution effects from regulatory compliance pull and geographic expansion dynamics. Segmentation modeling tracked mobility configuration, atomization physics platform, end-use regulatory intensity, and application-specific emission characteristics. CAGRs were derived from installed base replacement cycles, greenfield project pipelines, and technology penetration curves. Forecast inputs incorporated MSHA enforcement timelines, EU Green Deal implementation phases, and water scarcity indices for major mining corridors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt shifts in EPA or MSHA enforcement intensity and unanticipated breakthroughs in electrostatic agglomeration efficiency. Deviation in tungsten carbide nozzle supply availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Pile Cage Welding Machine Market
Construction Equipment
Asia-Pacific Road Marking Machine Market
Construction Equipment
Concrete NDT Testing Equipment Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
Dozer Blade Market
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Jib Crane Market
Construction Equipment
Roadheaders Market
Construction Equipment
Porter Cable Air Compressor Market
Construction Equipment
Plasma Cutting Machine Market
Construction Equipment
Mobile Crushers and Screeners Market
Construction Equipment
US Aerial Work Platform Market
Construction Equipment
GCC Construction Machinery Market
Construction Equipment
Log Splitters Rental Market
Construction Equipment
Construction Equipment Tire Market
Construction Equipment
Truck Crane Market