
 Netherlands Floor Covering Market | 2026-2036
Netherlands Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Floor Covering Market Foresight
Premium specification-grade flooring is rotating through Dutch commercial channels as developers target BREEAM-NL and WELL certification thresholds. Interface, Inc. leverages its carbon-neutral tile program to anchor specification conversations with Rotterdam office developers. Forbo Flooring Systems sustains its position through linoleum manufacturing scale and Cradle to Cradle certification depth. Tarkett S.A. competes on heterogeneous vinyl breadth across healthcare and education verticals.
Floor covering encompasses surface materials installed over structural subfloors to provide wear resistance, acoustic dampening, and aesthetic finish in built environments. Technical specifications span wear-layer thickness measured in millimeters, slip-resistance ratings per DIN 51130, and VOC emission classifications under ISO 16000. The primary commercial purpose is protecting structural substrates while enabling spatial zoning and brand expression. Hardwood and laminate segments occupy mature residential replacement cycles with margin compression from imports. Vinyl commands commercial share through water resistance and rapid installation protocols. Carpet retains hospitality and office specification where acoustic performance carries premium weight.
Dutch market access hinges on compliance with BSI Nederland assessments, EU REACH substance restrictions, and CE marking under the Construction Products Regulation. The Woningwet imposes performance declarations that filter out uncertified imports from distribution channels. Stakeholders must monitor evolving Ecodesign requirements and embedded carbon disclosure rules that will reshape supplier qualification criteria.
Market Dynamics
The Netherlands floor covering market is being reshaped by the collision of EU Green Deal carbon disclosure mandates with Dutch Woningwet performance declarations, forcing rapid supplier recertification and compressing specification timelines for commercial developers.
Growth Catalysts
- EU Green Deal targets:Embedded carbon thresholds are accelerating specification-grade purchases of low-emission materials across Rotterdam and Amsterdam hospitality renovation pipelines.
- Randstad urban corridors:Commercial retrofit activity in these dense metropolitan zones outpaces national averages, concentrating demand for wear-resistant surfacing solutions.
- BREEAM-NL certification:Developers pursuing this sustainability benchmark are rotating premium flooring through Dutch commercial channels to meet point thresholds.
Market Restraints
- Import dependency:Hardwood and laminate segments face margin compression from uncertified Asian imports that bypass BSI Nederland assessments.
- REACH substance restrictions:ECHA compliance costs filter out smaller distributors unable to maintain substance documentation across complex supply chains.
- Technical flooring limitations:Carpet's moisture sensitivity constrains deployment in Dutch healthcare verticals where vinyl dominates specification.
Strategic Opportunities
- Eindhoven-Tilburg corridor:Underpenetrated logistics and light industrial construction in this southern Dutch region offers specification growth outside saturated Randstad markets.
- CE marking convergence:The Construction Products Regulation creates pathway for certified Dutch suppliers to access adjacent Belgian and German commercial markets.
- Digital specification platforms:BIM-integrated material selection tools are emerging as new channels for anchoring product conversations with Dutch architects and developers.
Industry Challenges
- Certification timeline compression:Accelerated Ecodesign requirement rollouts strain technical teams tasked with maintaining ISO 16000 VOC documentation.
- Skilled installer scarcity:Rapid installation protocol expertise for heterogeneous vinyl systems remains concentrated among aging Dutch flooring contractor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Floor Covering Market |
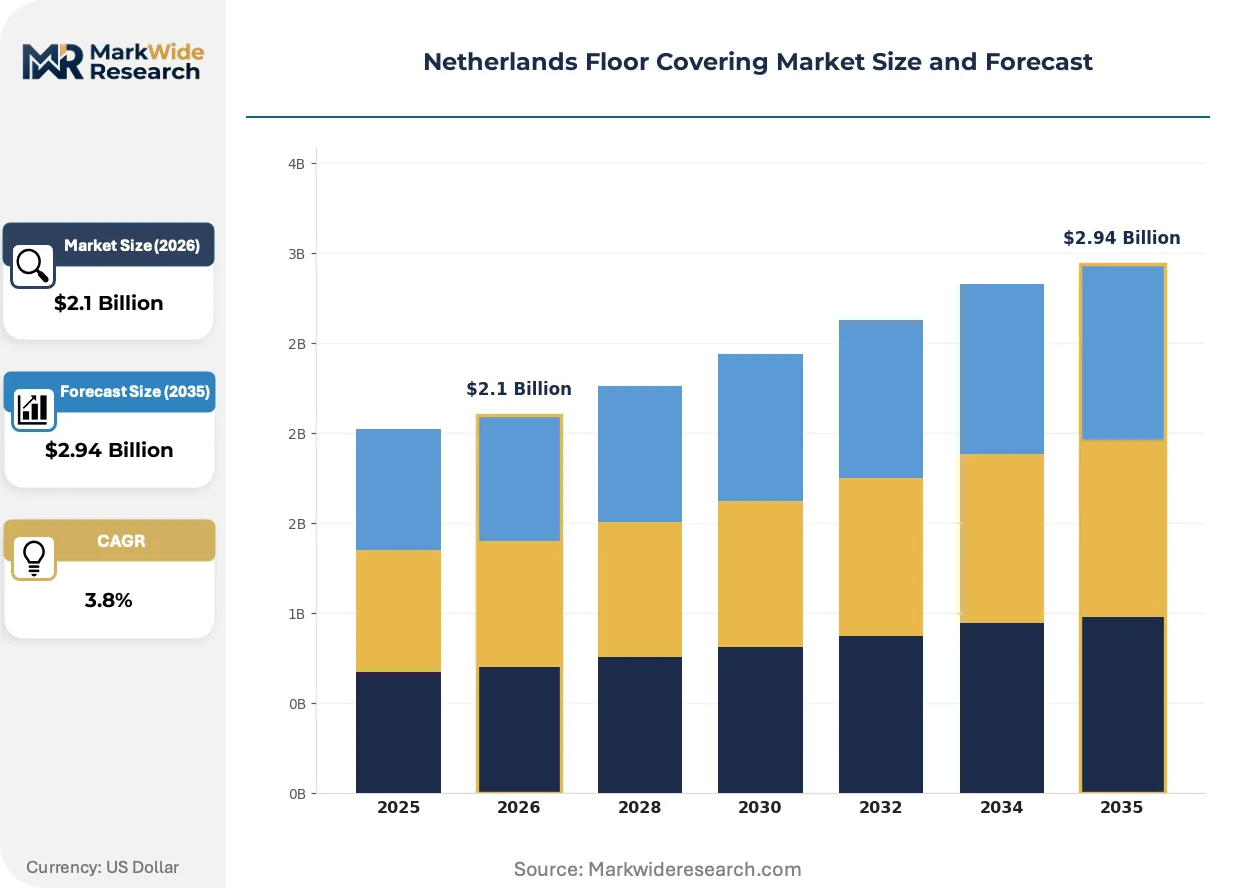
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpets, Vinyl, Laminate, Hardwood Installation Method: Glue Down, Floating, Nail Down, Loose Lay End User: Residential, Commercial, Hospitality, Industrial Maintenance Type: Regular Cleaning, Deep Cleaning, Repair Services, Replacement |
| Companies Covered | Interface, Inc., Gerflor, Tarkett S.A., Balta Group, Mannington Mills Inc., Forbo Flooring Systems, Beaulieu International Group, LG Hausys, Mohawk Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Floor Covering Market Shifts & Advancements
Carbon-neutral material programs and digital specification workflows are restructuring how Dutch developers evaluate surfacing options, compressing traditional decision cycles and elevating transparency requirements.
Biobased resilient flooring is displacing petroleum-derived vinyl in Dutch office specifications. Rotterdam developers targeting WELL certification are specifying these materials at accelerating pace. The shift is compressing market share for conventional heterogeneous vinyl in premium commercial segments.
EU Ecodesign requirements are mandating embedded carbon disclosure for construction products entering Dutch distribution. Manufacturers must now provide lifecycle data to maintain CE marking validity. Healthcare and education verticals are responding by pre-qualifying suppliers with verified environmental product declarations.
Architect-led specification is consolidating influence over Dutch commercial flooring decisions. Traditional distributor relationships are weakening as design firms build direct digital material libraries. This pattern is most visible in Amsterdam's BREEAM-NL certified office developments where specification authority has shifted upstream.
Netherlands Floor Covering Market Segmentation
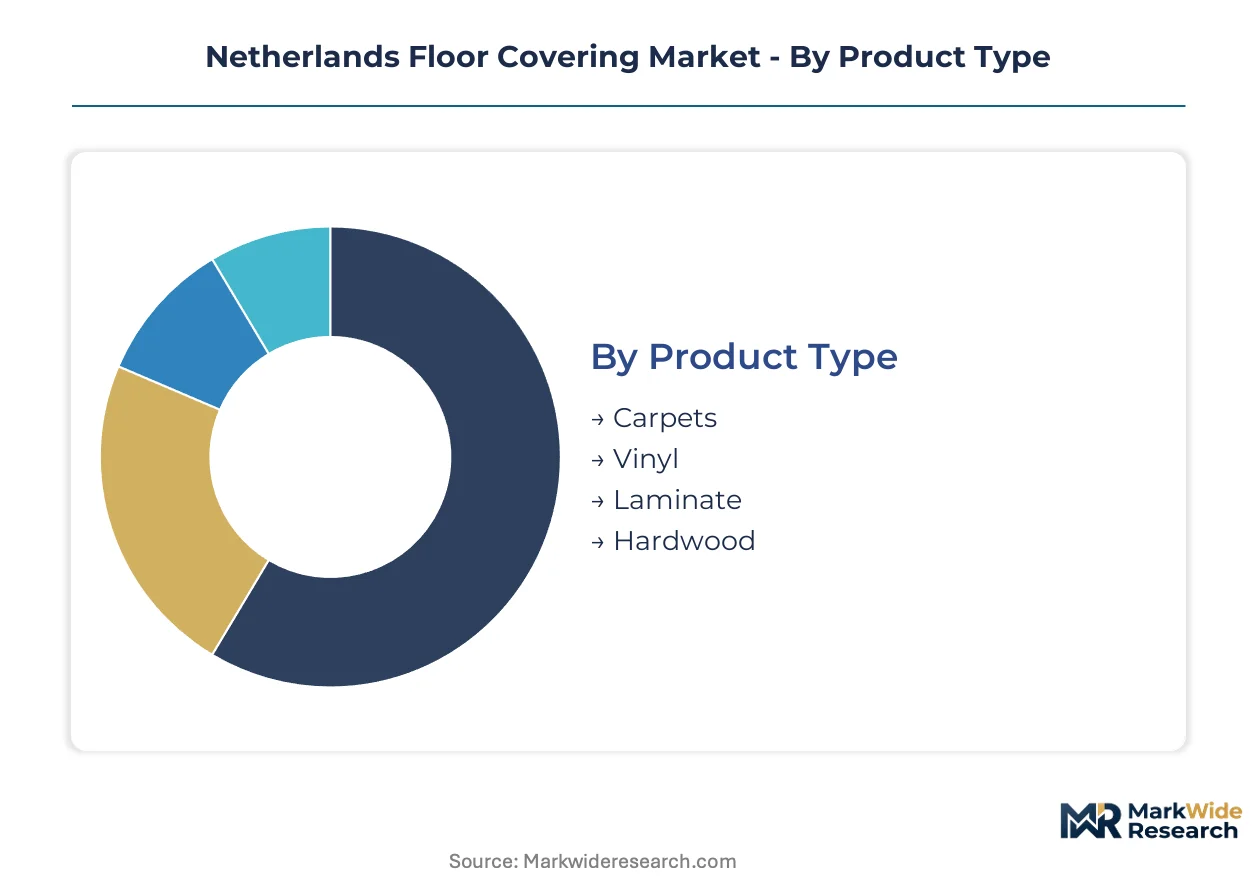
Segmentation in the Dutch floor covering market reveals how regulatory pressure and installation economics reshape competitive boundaries. Understanding these divides exposes where substitution threats concentrate and where specification authority has shifted upstream to architects and developers.
Product Type:
Vinyl and laminate face the most intense substitution pressure as biobased resilient materials displace petroleum-derived alternatives in BREEAM-NL certified projects.
- Carpets:Tufted and woven textile surfaces with pile construction measured in ounces per square yard. Demand concentrates in Amsterdam and Rotterdam hospitality renovations where WELL certification mandates acoustic dampening performance.
- Vinyl:Polymer-based resilient surfacing with wear-layer thickness ranging from 0.3mm to 0.7mm for commercial grades. Rotterdam office developers specify heterogeneous vinyl systems for water resistance in healthcare and education verticals where rapid installation protocols compress project timelines.
- Laminate:Fiberboard core with decorative paper overlay and aluminum oxide wear layer. Dutch residential replacement cycles show margin compression from uncertified Asian imports bypassing BSI Nederland assessments.
- Hardwood:Solid or engineered timber planks with natural oil or polyurethane finishes. Premium oak and ash grades dominate heritage property restorations in Utrecht and The Hague conservation districts.
Vinyl anchors the volume base while biobased alternatives gain share at the steepest rate in premium commercial specifications.
Installation Method:
Cost tier differentiation separates specification-grade systems from mass-market alternatives, with labor scarcity driving automation investment in Randstad corridors.
- Glue Down:Full-spread adhesive application creating permanent bond to subfloor. Commercial healthcare specifications in Eindhoven-Tilburg corridor demand this method for dimensional stability under rolling loads.
- Floating:Interlocking edge systems resting on underlayment without subfloor attachment. Dominates Dutch residential laminate and engineered hardwood installations where speed and reversibility carry weight.
- Nail Down:Mechanical fastening through tongue-and-groove planks into wood subfloors. Solid hardwood restoration projects in historic Amsterdam canal houses retain this traditional method.
- Loose Lay:Friction-backed systems relying on weight and perimeter retention. Emerging in temporary commercial fit-outs where lease terms demand rapid decommissioning.
Floating installation commands the greatest volume while glue-down specifications expand most quickly in healthcare and education verticals.
End User:
Application-specific performance requirements fragment supply chains, with certification thresholds filtering supplier pools differently across verticals.
- Residential:Owner-occupied and rental housing stock across Randstad and peripheral provinces. Replacement cycles concentrate in aging post-war housing undergoing energy retrofit coordination.
- Commercial:Office, retail, and institutional spaces governed by BREEAM-NL point systems. Amsterdam Zuidas and Rotterdam Central District developments drive specification-grade rotation.
- Hospitality:Hotels, restaurants, and event venues with high-traffic wear patterns. Schiphol corridor and historic city center renovation pipelines concentrate demand for stain-resistant and acoustic-optimized surfacing.
- Industrial:Warehousing, logistics, and light manufacturing facilities. Eindhoven-Tilburg logistics corridor presents underpenetrated growth outside saturated Randstad markets.
Commercial specifications anchor revenue concentration while industrial end-use climbs the fastest as southern Dutch logistics construction accelerates.
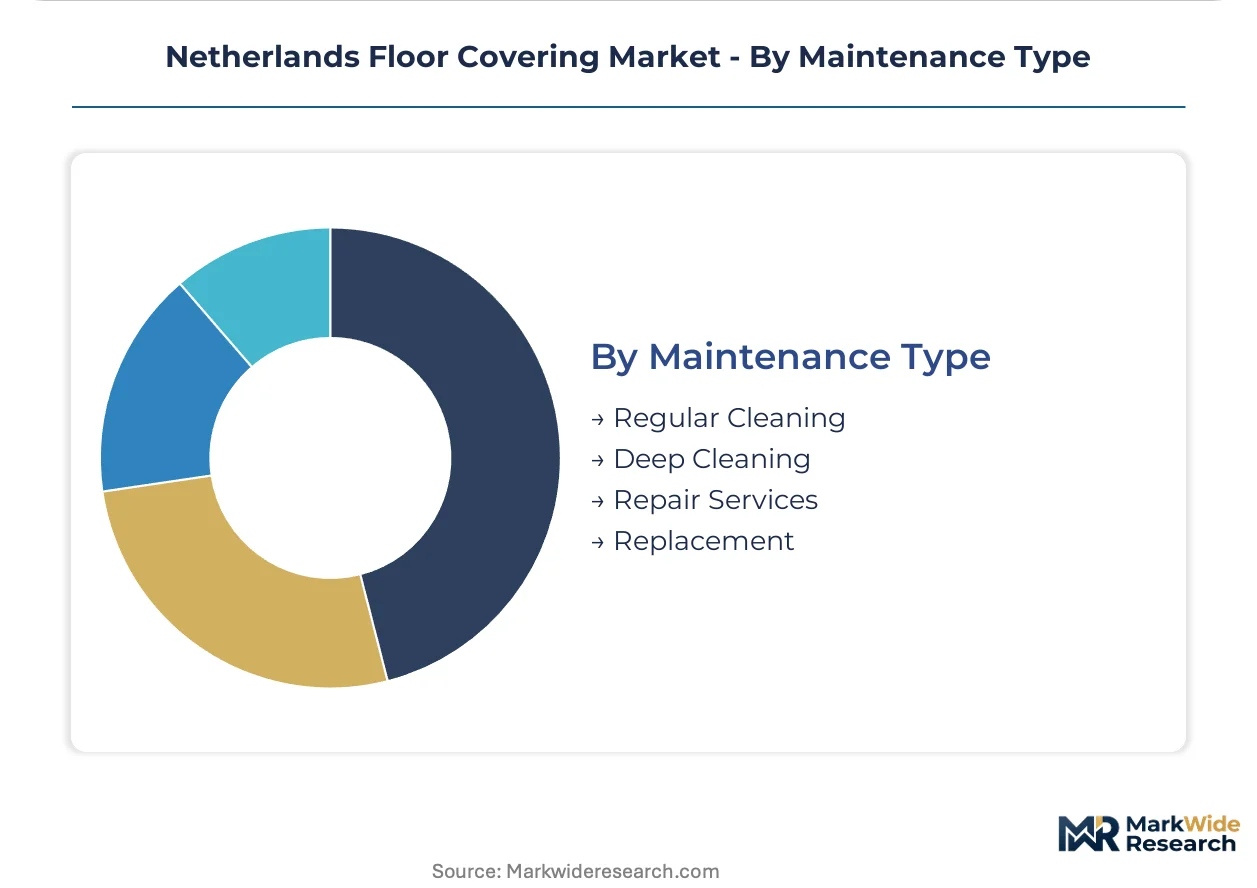
Maintenance Type:
Customer type stratification separates recurring service revenue from capital replacement cycles, with contract structures determining supplier economics.
- Regular Cleaning:Scheduled surface maintenance including vacuuming, damp mopping, and pH-neutral cleaning protocols. Hospitality operators in Amsterdam prioritize these programs to preserve warranty validity and appearance retention.
- Deep Cleaning:Periodic restoration using extraction equipment or rotary brush systems. Commercial office landlords specify these intervals to meet BREEAM-NL indoor environmental quality criteria.
- Repair Services:Localized remediation of damage including plank replacement, seam welding, or patch integration. Aging Dutch flooring contractor networks concentrate this capability in Randstad urban corridors.
- Replacement:Full surfacing removal and new material installation. Residential replacement cycles show elongation as laminate durability improves and consumer renovation priorities shift to kitchen and bath.
Regular cleaning generates the steadiest recurring revenue while deep cleaning services gain share fastest as certification maintenance requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive residential replacement buyers in peripheral provinces contrast sharply with specification-driven commercial developers in Randstad corridors, where certification premiums command elastic budgets and project timelines compress procurement decisions.
Randstad
Amsterdam Zuidas and Rotterdam Central District developments anchor specification-grade flooring demand, with BREEAM-NL certification thresholds filtering supplier pools. The Woningwet imposes performance declarations that accelerate low-emission material rotation. Hospitality renovation pipelines in historic canal districts concentrate acoustic-optimized carpet specifications.
Brabant
Eindhoven-Tilburg logistics corridor presents underpenetrated industrial flooring growth as warehouse construction accelerates outside saturated northern markets. EU Green Deal embedded carbon disclosure mandates reshape supplier qualification criteria. Light manufacturing facilities in this southern region specify glue-down vinyl systems for dimensional stability under rolling loads.
Rotterdam Port Zone
Commercial retrofit activity outpaces national averages as post-industrial waterfront redevelopment expands specification conversations. REACH substance restrictions filter out smaller distributors unable to maintain documentation. Carbon-neutral tile programs anchor procurement decisions with developers targeting WELL certification thresholds.
Utrecht
Heritage property restorations in conservation districts sustain premium hardwood demand for solid oak and ash grades. Aging flooring contractor networks concentrate repair service capability here. Residential replacement cycles show elongation as laminate durability improves and renovation priorities shift.
Northern Netherlands
Peripheral provinces exhibit highest price elasticity as mass-market laminate and vinyl imports bypass BSI Nederland assessments. Floating installation dominates residential applications where speed and reversibility carry weight. Deep cleaning service penetration remains lowest in this cost-sensitive region.
Netherlands Floor Covering Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with carbon-neutral program developers commanding specification premiums while scale manufacturers compete on heterogeneous vinyl breadth. The market structures around three tiers: multinational flooring systems houses with full portfolio coverage, regional specialists anchored in linoleum or carpet manufacturing heritage, and import-dependent distributors serving price-sensitive residential channels. Consolidation pressure concentrates among mid-scale European manufacturers facing REACH compliance cost burdens. Strategic moves center on Cradle to Cradle certification depth and BIM-integrated specification platform partnerships.
Within the multinational tier, Interface, Inc., Tarkett S.A., and Forbo Flooring Systems occupy positions defined by sustainability program architecture and manufacturing scale. Interface exemplifies carbon-neutral tile program leadership in Rotterdam office specifications. Tarkett represents heterogeneous vinyl breadth across healthcare and education verticals. Forbo anchors its position through linoleum manufacturing heritage and certification depth. These three entities illustrate how Dutch market access hinges on compliance infrastructure rather than product differentiation alone.
| Leading Market Players |
|---|
| Interface, Inc. |
| Gerflor |
| Tarkett S.A. |
| Balta Group |
| Mannington Mills Inc. |
| Forbo Flooring Systems |
| Beaulieu International Group |
| LG Hausys |
| Mohawk Industries |
| Others |
Supply & Pricing Matrix
Long-term specification contracts with Rotterdam and Amsterdam developers lock in both supply access and price visibility for BREEAM-NL certified materials, compressing spot-market exposure for premium flooring tiers while anchoring margin stability for compliant suppliers.
Pricing Analysis
EU Green Deal embedded carbon disclosure mandates dictate the pricing tier structure across Dutch commercial flooring, separating Cradle to Cradle certified products from uncertified imports. Price differentiation hinges on certification depth and wear-layer performance grade, with specification-grade heterogeneous vinyl commanding premiums over mass-market laminate. Cost compression in residential tiers intensifies as Asian imports bypass BSI Nederland assessments. Peripheral province buyers exhibit highest price elasticity, while Randstad commercial developers absorb certification premiums without volume trade-offs.
Supply Chain Analysis
Just-in-time inventory preferences dominate Dutch distribution channels, with specification-grade materials flowing directly from Belgian and German manufacturing hubs to Randstad project sites. Raw material dependencies center on petroleum-derived resins, linseed oil for biobased alternatives, and aluminum oxide wear-layer compounds. Single-source vulnerability concentrates in specialized acoustic backing substrates for hospitality carpet specifications. Distribution runs through architect-led digital specification platforms that bypass traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled installer scarcity for rapid-deployment vinyl systems constrains market expansion, creating competitive advantage for suppliers who control certified contractor networks or invest in installation training infrastructure.
For Market Incumbents: Shield specification-grade market share by deepening Cradle to Cradle certification portfolios and anchoring BIM-integrated material libraries with Amsterdam and Rotterdam design firms. Vertical integration into installer training programs addresses capability gaps that threaten project timelines. Channel control through direct architect relationships neutralizes import-driven price erosion in peripheral provinces. For New Entrants and Emerging Players: Lead with biobased resilient flooring formulations targeting WELL certification thresholds in Rotterdam office retrofits, where petroleum-derived vinyl faces accelerating displacement. The Eindhoven-Tilburg logistics corridor offers underpenetrated industrial flooring growth outside saturated Randstad competition. Go-to-market execution should anchor on CE marking convergence enabling adjacent Belgian and German market access. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale European manufacturers with existing BSI Nederland compliance infrastructure and linoleum manufacturing heritage, positioned to capture specification premium rotation. Long-term viability across the analysis window depends on Ecodesign readiness and embedded carbon documentation capabilities. Watch for REACH substance restriction expansions that filter out smaller competitors as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Cradle to Cradle Certification Investment | Deepens specification access for BREEAM-NL and WELL certified Dutch commercial developments. |
| BIM-Integrated Specification Platform Partnership | Shifts procurement influence upstream to architect-led digital material selection workflows. |
| Installer Training Infrastructure Buildout | Addresses skilled contractor scarcity that constrains rapid-deployment vinyl system adoption. |
| Biobased Resilient Formulation Development | Captures share from petroleum-derived vinyl in Rotterdam WELL-certified office specifications. |
| Eindhoven-Tilburg Corridor Market Entry | Accesses underpenetrated logistics construction growth outside saturated Randstad urban zones. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with flooring contractors, specification architects, and procurement managers at Dutch commercial developers, combined with secondary validation against BSI Nederland certification databases, EU ECHA substance restriction filings, and construction permit records for Randstad and Brabant corridors. Bottom-up triangulation across product-level shipment data and top-down reconciliation with sectoral construction output statistics anchored volume estimates.
Across the analysis window, forecasts model product type, installation method, end-use vertical, and regional construction pipeline dimensions. CAGRs derive from regression analysis of historical specification-grade adoption rates and regulatory compliance cost trajectories. Key inputs include Woningwet performance declaration timelines and EU Ecodesign rollout schedules.
The analysis sits within stated boundaries; outcomes outside sustained BREEAM-NL certification adoption or accelerated REACH restriction enforcement would require recalibration. Forecasts reflect assumptions on installer capacity expansion and biobased material cost parity achievement. Revision becomes warranted when embedded carbon disclosure thresholds cross implementation thresholds ahead of modeled schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Germany Flooring Market
Flooring, Carpets, and Rugs
Area Rugs Market
Flooring, Carpets, and Rugs
Resilient Flooring Market
Flooring, Carpets, and Rugs
North America Carpet Tile Market
Flooring, Carpets, and Rugs
Global Non-Resilient Flooring Market
Flooring, Carpets, and Rugs
United States Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
GCC Flooring Market
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
Wooden Floor Market
Flooring, Carpets, and Rugs
US Flooring Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
Stone Flooring Market
Flooring, Carpets, and Rugs
India Floor Covering Market
Flooring, Carpets, and Rugs
Textured Variegates Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market