
 Europe Non-Resilient Floor Covering Market | 2026-2036
Europe Non-Resilient Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Non-Resilient Floor Covering Market Foresight
Healthcare and education construction is shifting toward specification-grade porcelain and ceramic systems across Western Europe. Tarkett leverages its linoleum heritage to anchor sustainable institutional contracts in France and Belgium. Mohawk Industries competes through ceramic technology leadership and manufacturing scale in Spain and Italy. Forbo Flooring specializes in linoleum formulations that meet stringent indoor air quality protocols for Nordic school districts.
Europe non-resilient floor covering comprises rigid surface materials including ceramic tile, porcelain, natural stone, laminate, and linoleum, typically installed via glue-down, floating, or grouted methods with wear-layer ratings from AC3 to PEI 5 for commercial traffic loads. These materials serve moisture-prone and high-abrasion environments where dimensional stability and chemical resistance exceed resilient alternatives. Ceramic tile and porcelain command the largest installed base in Southern Europe, where stone fabrication clusters in Italy and Spain sustain export-oriented margin pools. Laminate occupies the value-engineered residential renovation segment, while linoleum resurfaces in public-sector specifications driven by bio-based content requirements.
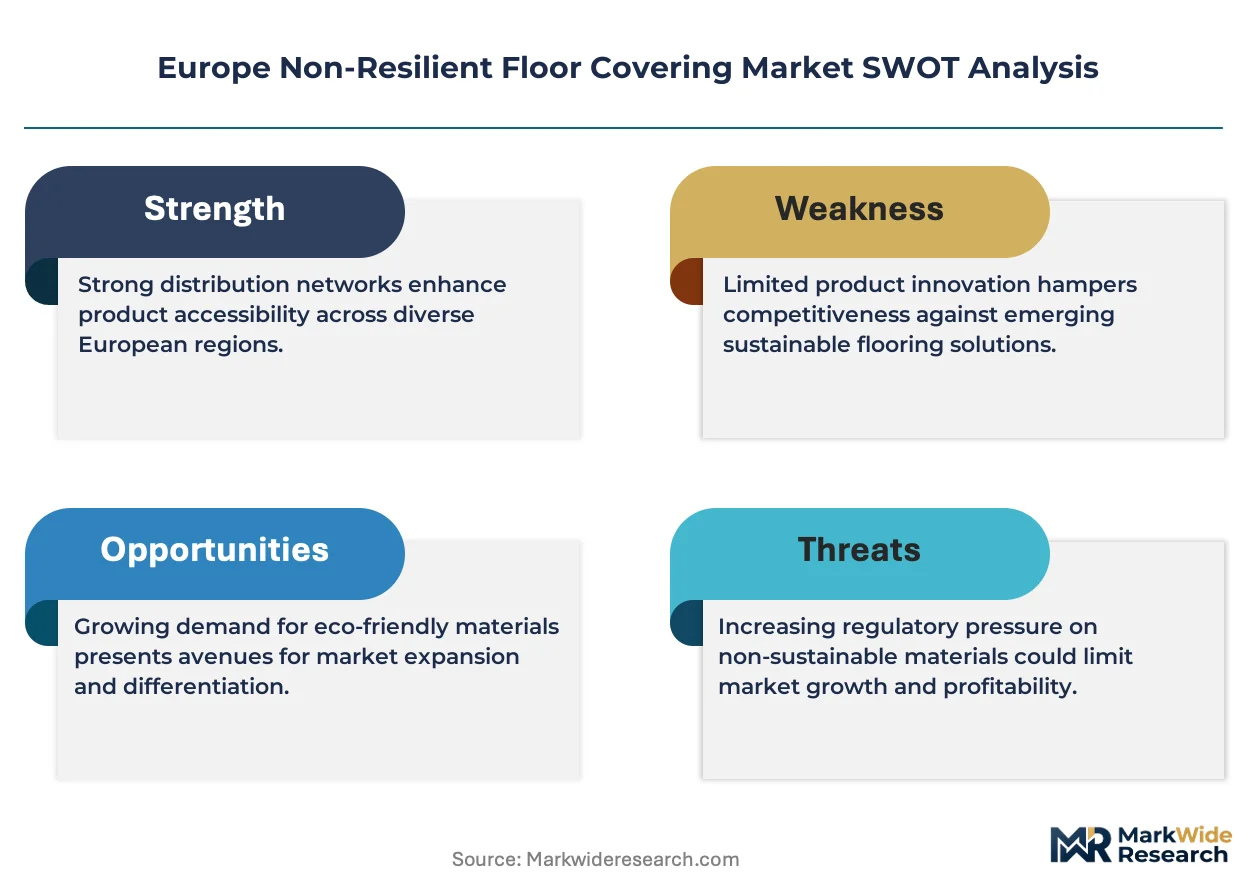
The EU Green Deal and F-Gas Regulation shape material compliance pathways, while CE marking under the Construction Products Regulation governs slip resistance and fire-reaction performance declarations. Germany's KBA-adjacent building codes and France's RE2020 environmental regulations tighten embodied-carbon thresholds for public procurement. ECHA REACH restrictions on phthalate plasticizers redirect vinyl formulation strategies toward non-orthophthalate chemistries. Stakeholders must monitor evolving EPD verification requirements and national renovation-wave funding disbursements to align product portfolios with specification timelines.
Market Dynamics
Renovation mandates across Germany, France, and the Nordics are compressing specification timelines and forcing rapid material substitution toward low-carbon flooring systems. Public procurement rules now embed embodied-carbon thresholds that disqualify conventional alternatives.
Growth Catalysts
- Building Energy Act mandates:Germany's renovation requirements are accelerating floor-system replacements in commercial and residential stock.
- Healthcare construction:Infection-control specifications in France's hospital pipeline favor non-porous porcelain surfaces over resilient alternatives.
- RE2020 environmental regulations:France's building code revisions prioritize bio-based linoleum in public-sector tenders.
Market Restraints
- Natural gas price volatility:Ceramic and porcelain firing costs in Italy and Spain fluctuate with energy input swings.
- Supply concentration in Carrara:Premium stone fabrication clusters create single-source vulnerability for specification-grade marble.
- ECHA REACH phthalate restrictions:Vinyl-adjacent chemistries face formulation redirection toward non-orthophthalate alternatives.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Finland's school renovation waves specify linoleum for indoor air quality compliance.
- Digital specification platforms:BIM-integrated product libraries are shortening architect decision cycles for ceramic selection.
- EU Green Deal funding:National renovation-wave disbursements in Belgium and Netherlands subsidize low-carbon flooring retrofits.
Industry Challenges
- EPD verification bottlenecks:Third-party environmental product declaration timelines lag behind procurement deadlines.
- Skilled installer scarcity:Grouted ceramic and natural stone installation requires certified trades that retire faster than training pipelines replenish.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Non-Resilient Floor Covering Market |
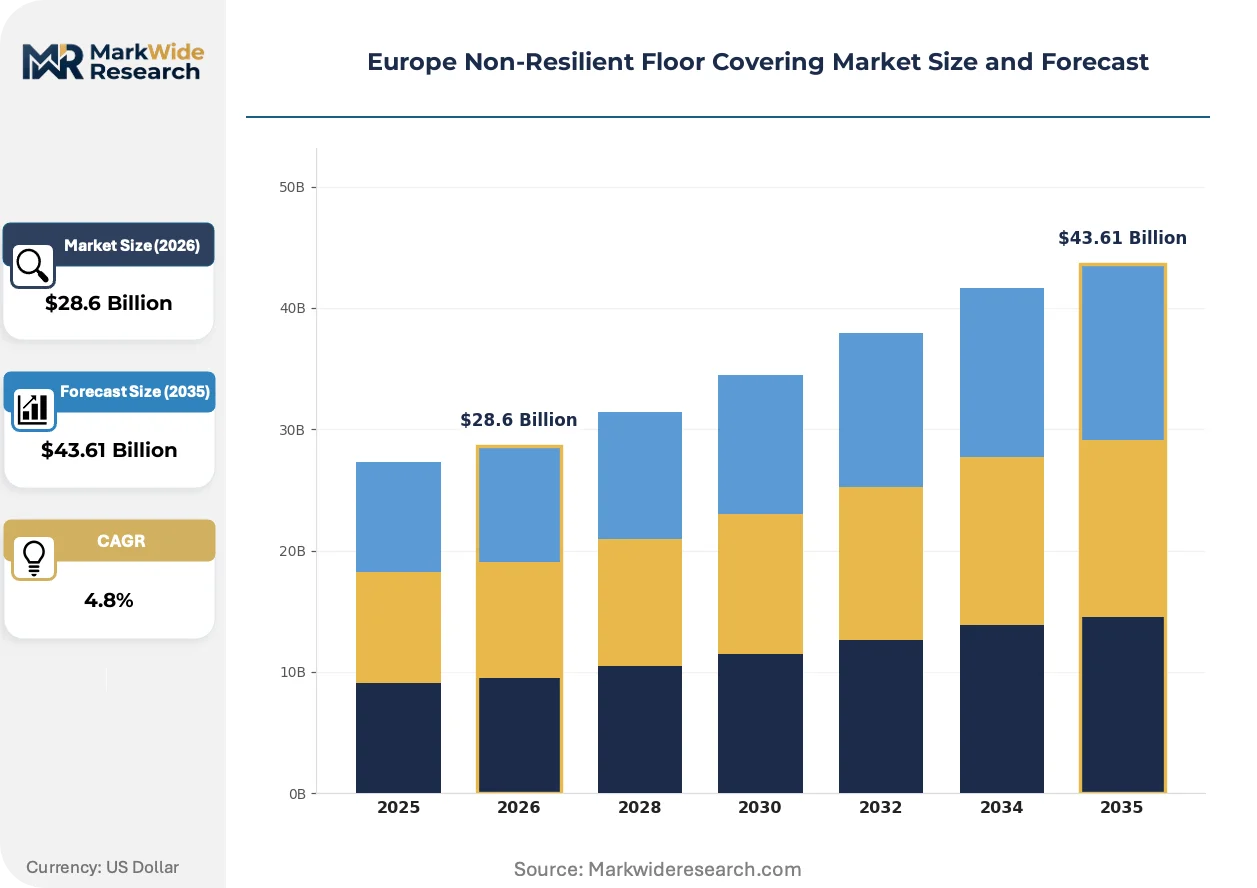
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, Laminate, Ceramic Tile, Stone Tile End Use: Residential, Commercial, Institutional, Hospitality Material: Linoleum, Porcelain, Glass, Natural Stone Installation Method: Glue Down, Floating, Click Lock, Grouted |
| Companies Covered | Tarkett, Mohawk Industries, Shaw Industries Group, Beaulieu International Group, Forbo Flooring, Berry Alloc, Parador, Porcelanosa Group, Johnson Tiles, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Non-Resilient Floor Covering Market Shifts & Advancements
Digital tools and regulatory carbon accounting are rewiring how architects, contractors, and facility managers evaluate flooring materials. Specification decisions now integrate lifecycle data earlier in design phases.
Thin-format large porcelain slabs are absorbing specification share from traditional tile formats and natural stone in commercial lobbies and transit hubs. Airport authorities in Spain and Italy specify these for reduced grout maintenance and dimensional stability under rolling loads. The technology is absorbing margin from stone fabricators while compressing installation labor hours.
France's RE2020 regulation and Germany's KBA-adjacent building codes are tightening embodied-carbon disclosure requirements for public construction. Manufacturers must submit verified EPDs to qualify for institutional tenders. Ceramic producers in Italy and Spain are responding by electrifying kilns and sourcing renewable energy to meet threshold compliance.
Facility managers in Nordic office clusters now bundle flooring replacement with energy retrofit contracts rather than treating them as separate capex lines. Integrated service agreements covering material, installation, and maintenance are displacing traditional product-only procurement. This pattern is most visible in Denmark and Sweden where property owners face simultaneous building-code and carbon-reporting deadlines.
Europe Non-Resilient Floor Covering Market Segmentation
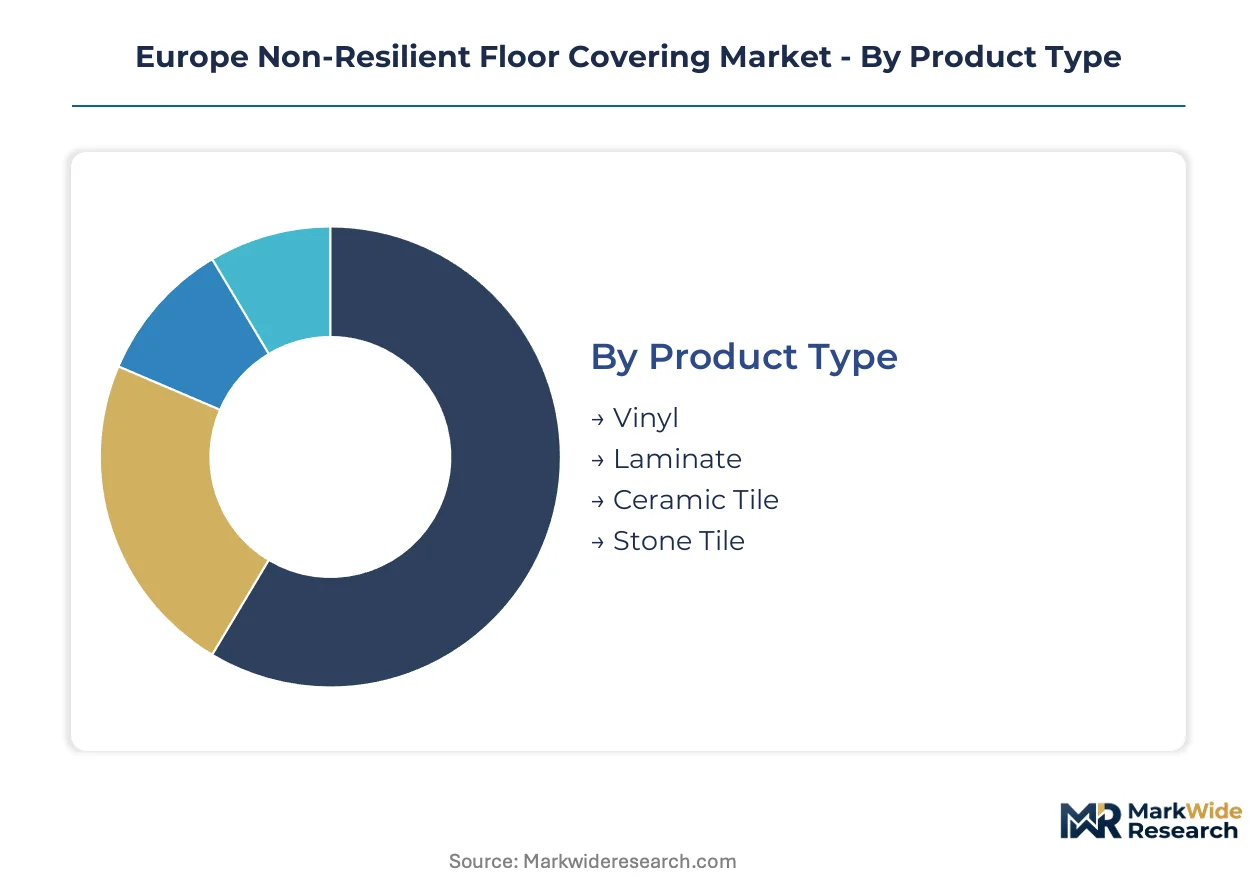
Segmentation in the Europe non-resilient floor covering market reveals how material properties, installation constraints, and end-use specifications fragment procurement decisions across national renovation programs. Each dimension carries distinct margin structures and regulatory compliance burdens.
Product Type:
Supply concentration clusters around ceramic technology leadership in Italy and Spain, with laminate fabrication scaling in Germany and Poland to serve renovation-driven residential demand.
- Ceramic Tile:Fired clay bodies with PEI wear ratings anchor Southern European production. Hospital construction in France and transit infrastructure in Spain specify large-format porcelain for dimensional stability under mechanical loads.
- Laminate:HDF core boards with aluminum oxide wear layers dominate value-engineered residential retrofit. German Building Energy Act renovation mandates accelerate floating-floor installations in multi-family housing stock.
- Vinyl:ECHA REACH phthalate restrictions force formulation pivots toward non-orthophthalate plasticizers.
- Stone Tile:Carrara fabrication clusters create single-source vulnerability for premium marble specifications.
Today's leader: Ceramic Tile. Tomorrow's challenger: Laminate.
End Use:
Cost-tier stratification separates specification-grade institutional contracts from residential renovation volume, with public procurement rules embedding embodied-carbon thresholds that reshape competitive positioning.
- Institutional:Schools, hospitals, and government buildings demand infection-control surfaces and verified EPDs. Nordic districts specify linoleum for indoor air quality compliance; French RE2020 mandates bio-based content.
- Commercial:Office clusters across Denmark and Sweden bundle flooring replacement with energy retrofit contracts. Thin-format porcelain slabs absorb specification share from natural stone in lobby and transit applications.
- Residential:Germany's renovation wave drives laminate and engineered ceramic demand in multi-family housing.
- Hospitality:Premium stone and large-format porcelain serve high-traffic hotel and restaurant environments.
Institutional contracts command premium pricing through compliance complexity. Residential volume offers scale but compresses margins.
Material:
Volume concentration favors porcelain across Southern European manufacturing bases, while linoleum resurfaces in public-sector specifications driven by bio-based procurement mandates.
- Porcelain:Vitrified ceramic with water absorption below 0.5% dominates commercial and institutional specification. Italian and Spanish producers electrify kilns to meet EU Green Deal carbon thresholds.
- Linoleum:Oxidized linseed oil and cork composite formulations satisfy France's RE2020 bio-content requirements. Belgian and Dutch school districts specify Forbo and Tarkett systems for indoor air quality protocols.
- Natural Stone:Carrara marble and Spanish limestone fabrication face skilled installer scarcity and extended lead times.
- Glass:Specialty mosaic and decorative applications serve niche hospitality and luxury residential segments.
Porcelain holds installed base dominance. Linoleum is gaining share fastest in public tenders.
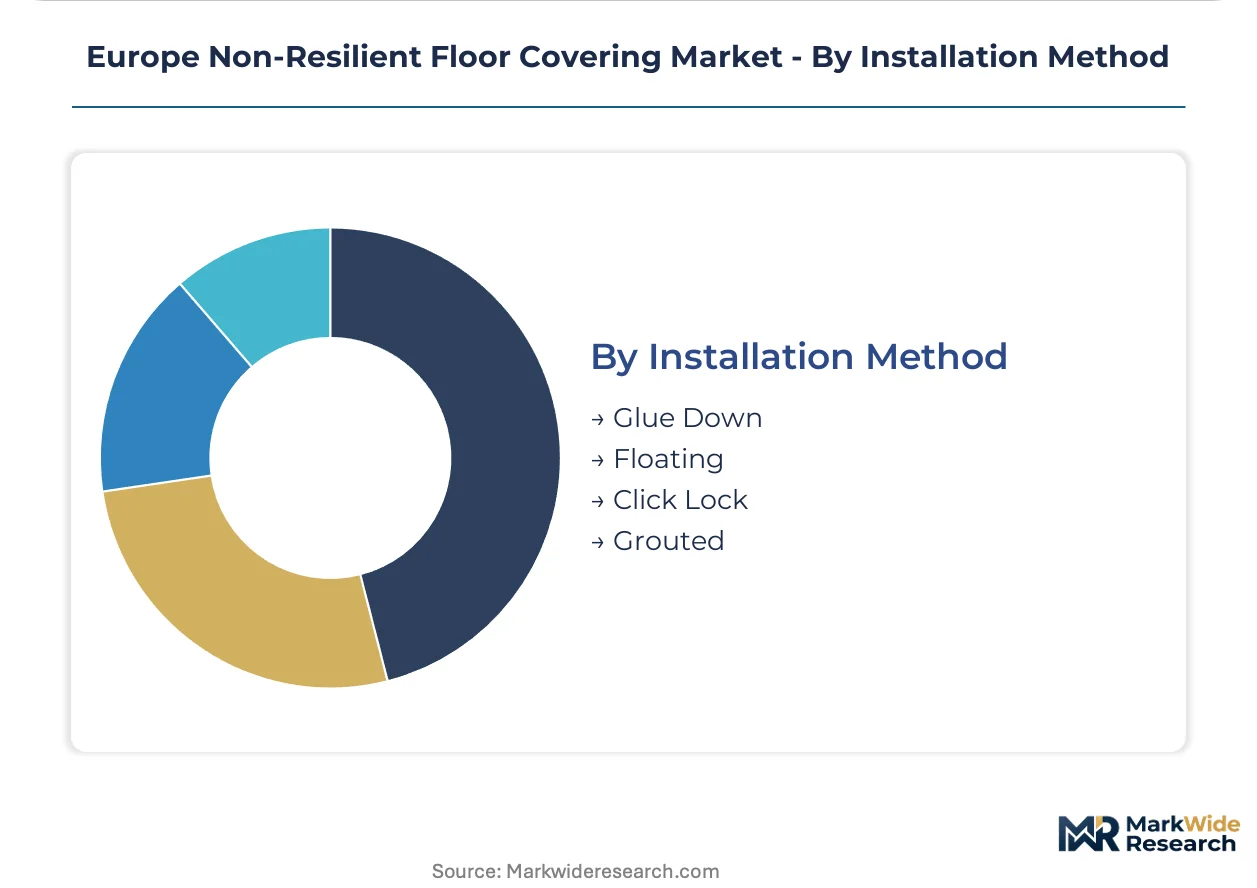
Installation Method:
Customer-type stratification separates professional grouted systems from DIY-friendly floating floors, with skill scarcity creating margin protection for certified trades.
- Grouted:Ceramic and natural stone installation demands certified tile setters whose retirement rates exceed training pipeline output. Premium commercial specifications in France and Italy absorb higher labor costs for durability guarantees.
- Floating:Click-lock laminate and engineered systems enable rapid residential renovation without subfloor preparation. German and Polish manufacturing clusters optimize for this installation efficiency.
- Glue Down:Sheet vinyl and linoleum applications require substrate moisture testing and adhesive specification matching.
- Click Lock:Mechanical joining systems accelerate installation timelines in residential and light commercial retrofit.
Grouted systems defend margins through capability scarcity. Floating methods expand addressable volume through labor substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian and Spanish ceramic fabrication clusters anchor European non-resilient flooring supply, with Sassuolo and Castellón kilns firing specification-grade porcelain for institutional and commercial specification across the continent.
Germany
Building Energy Act renovation mandates accelerate floor-system replacements in multi-family housing stock across North Rhine-Westphalia and Bavaria. KBA-adjacent building codes tighten embodied-carbon disclosure thresholds for public procurement. Laminate manufacturing clusters in the Mittelstand belt optimize floating-floor production for rapid residential retrofit timelines.
France
Hospital construction pipelines in Île-de-France and Auvergne-Rhône-Alpes specify non-porous porcelain for infection-control surfaces. RE2020 environmental regulations mandate bio-based linoleum content in public-sector tenders. Specification-grade ceramic demand concentrates in Lyon and Marseille transit infrastructure projects.
Italy
Sassuolo ceramic districts electrify kilns to meet EU Green Deal carbon thresholds for verified EPD submission. CE marking under the Construction Products Regulation governs slip resistance declarations for export-bound porcelain. Premium stone fabrication in Carrara faces skilled installer scarcity and extended lead times for commercial lobby specifications.
Spain
Castellón tile producers scale thin-format large porcelain slab output for airport and transit hub applications in Madrid and Barcelona. F-Gas Regulation compliance shapes material specification pathways for climate-controlled commercial environments. Andalusian limestone quarries supply Mediterranean hospitality renovation projects with natural stone alternatives.
Sweden
School renovation waves across Stockholm and Gothenburg specify linoleum for indoor air quality compliance under Nordic building protocols. Property owners bundle flooring replacement with energy retrofit contracts to meet simultaneous building-code and carbon-reporting deadlines. Skåne district procurement favors bio-based flooring systems with verified environmental product declarations.
Europe Non-Resilient Floor Covering Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers reposition around low-carbon procurement mandates and embodied-carbon disclosure requirements. The vendor base spans multinational flooring conglomerates with ceramic technology leadership, specialized linoleum formulators serving institutional air-quality specifications, and regional laminate fabricators optimized for renovation-driven residential volume. Three archetypes define competitive positioning: electrified ceramic producers with verified EPD pipelines, bio-based flooring specialists capturing public-sector tenders, and scale-driven laminate manufacturers serving value-engineered retrofit demand. M&A activity and kiln electrification investments represent the dominant competitive moves as players defend margin position against energy input volatility.
Among the named European flooring specialists, Tarkett anchors the bio-based linoleum segment through its French and Belgian heritage in institutional contracting. Mohawk Industries exemplifies ceramic technology leadership with manufacturing scale concentrated in Southern European kiln clusters. Forbo Flooring occupies a position within the Nordic specification tier, serving school district procurement with formulations aligned to stringent indoor air quality protocols. These three entities represent distinct competitive archetypes—heritage sustainability positioning, scale-driven ceramic dominance, and regional air-quality specialization—rather than overlapping strategic postures.
| Leading Market Players |
|---|
| Tarkett |
| Mohawk Industries |
| Shaw Industries Group |
| Beaulieu International Group |
| Forbo Flooring |
| Berry Alloc |
| Parador |
| Porcelanosa Group |
| Johnson Tiles |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap ceramic producers across Italy's Sassuolo district anchor supply discipline through generational kiln ownership, insulating pricing power from quarterly earnings pressure while concentrating margin capture in specification-grade porcelain tiers.
Pricing Analysis
Distributor margins absorb energy cost volatility before reaching institutional buyers, compressing net pricing visibility at the project level. Three-tier pricing structure across specification-grade porcelain, value-engineered ceramic, and economy laminate segments separates infection-control hospital contracts from residential retrofit volume. Cost compression in the laminate tier intensifies because Polish and German manufacturers compete on floating-floor installation speed. Residential renovation buyers exhibit highest price sensitivity, while Nordic school districts prioritize indoor air quality certification over unit cost.
Supply Chain Analysis
Natural gas supply rests on Norwegian pipeline flows and LNG terminal capacity, exposing Italian and Spanish kiln operators to input cost swings that propagate through ceramic pricing. Kaolin clay deposits in Ukraine and Portugal, plus feldspar from Turkey, feed Southern European fabrication clusters. Single-source vulnerability concentrates in Carrara marble quarries for premium commercial specifications. Distribution runs through specification houses serving architect-led procurement in France and Germany, bypassing retail channels for institutional contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where France's RE2020 bio-based mandates and Germany's Building Energy Act renovation requirements generate sustained specification demand for low-carbon flooring systems.
For Market Incumbents: Hedge against electrification cost exposure by securing renewable energy offtake agreements for kiln operations in Italy and Spain. Acquire certified tile-setter training pipelines to defend installation margins against retirement-driven scarcity. Prioritize EPD verification acceleration to maintain eligibility for French and German public tenders as disclosure deadlines tighten. For New Entrants and Emerging Players: The mid-market price gap between premium porcelain and economy laminate offers white-space capture for thin-format large slab producers with electrified production. Target Swedish and Finnish school renovation waves with linoleum formulations meeting Nordic indoor air quality protocols. Lead with BIM-integrated product libraries to shorten architect specification cycles against established catalogues. For Investors and Strategic Acquirers: Valuations sit cheapest among regional laminate fabricators lacking EPD infrastructure but holding renovation-wave distribution access. Long-term viability favors producers with backward integration into renewable energy supply and captive raw material sourcing. Watch ECHA REACH enforcement intensity on phthalate restrictions as the inflection signal for vinyl-adjacent chemistry pivots.| Strategic Initiative | Industry Significance |
|---|---|
| Kiln Electrification Investment | Italian and Spanish producers secure EU Green Deal compliance for verified EPD submission. |
| Backward Integration into Renewable Energy | Ceramic manufacturers lock in cost predictability against natural gas price volatility. |
| Certified Installer Training Pipeline | Grouted system specialists defend margin pools as tile-setter retirement outpaces replenishment. |
| BIM-Integrated Product Library Launch | Digital specification tools compress architect decision cycles for large-format porcelain selection. |
| Bio-Based Formulation Expansion | Linoleum producers capture French RE2020 and Nordic school district procurement mandates. |
Research Methodology
Coverage spans Western and Northern Europe, with primary inputs from each national renovation program. The research combines interviews with ceramic plant managers, architect specification leads, school district procurement officers, and distributor channel heads with secondary validation from CE marking databases, ECHA REACH regulatory filings, national building code revisions, and trade flow customs records. Bottom-up project pipeline analysis triangulates against top-down construction spending forecasts.
Granularity-level modeling operates at the intersection of material type, installation method, and end-use sector across the projection horizon. Product-level forecasts incorporate PEI wear ratings, bio-based content thresholds, and embodied-carbon disclosure requirements as segment-defining dimensions. CAGRs derive from construction permit trajectories, renovation-wave funding disbursement schedules, and substitution elasticity between ceramic and resilient alternatives. Energy input cost curves and skilled labor availability feed scenario-weighted outputs.
Caveats apply where EPD verification bottlenecks or natural gas price spikes could materially shift the outlook for specification-grade supply. Forecasts reflect assumptions around regulatory enforcement consistency and national funding continuity. A small set of named triggers—ECHA REACH expansion, RE2020 threshold tightening, and Nordic building code revisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Saudi Arabia Vinyl Flooring Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
North America Wood Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
Foam Flooring Products Market
Flooring, Carpets, and Rugs
Asia Pacific Flooring Market
Flooring, Carpets, and Rugs
Sheet Flooring Market
Flooring, Carpets, and Rugs
Middle East Flooring and Carpet Market
Flooring, Carpets, and Rugs
US Wood Flooring Market
Flooring, Carpets, and Rugs
India Laminate Flooring Market
Flooring, Carpets, and Rugs
Germany Floor Covering Market
Flooring, Carpets, and Rugs
ASEAN Laminate Flooring Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
China Luxury Vinyl Tile (LVT) Market
Flooring, Carpets, and Rugs
Taiwan Floor Covering Market