
 North America Carpet Tile Market | 2026-2036
North America Carpet Tile Market Size, Share, and Industry Trends Forecast 2026-2036
North America Carpet Tile Market Analytics
Multi-source procurement toward regional fiber suppliers is recalibrating cost structures across the value chain. Interface leverages closed-loop recycling infrastructure to sustain premium positioning in commercial specifications. Mohawk Industries anchors volume production through integrated yarn-to-tile manufacturing in Georgia. Shaw Industries Group Inc. differentiates via broadloom-to-tile conversion capabilities serving healthcare and education channels.
North America carpet tile denotes modular flooring units, typically manufactured in 18-inch or 24-inch square dimensions with bitumen or PVC backing systems, designed for selective replacement and reduced installation waste in high-traffic environments. The product type dimension shows modular tiles commanding the largest installed base while plank formats gain share in open-plan office reconfigurations. Material segmentation reveals nylon sustaining dominant specification rates in commercial applications, whereas polypropylene competes aggressively on price in multi-family residential conversions.
The EPA's recycled content recommendations and California Air Resources Board VOC limits shape material formulation decisions across domestic manufacturing. OSHA slip-resistance standards and NFPA fire codes further constrain product design parameters for healthcare and education end users. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and their implications for take-back program economics.
Market Dynamics
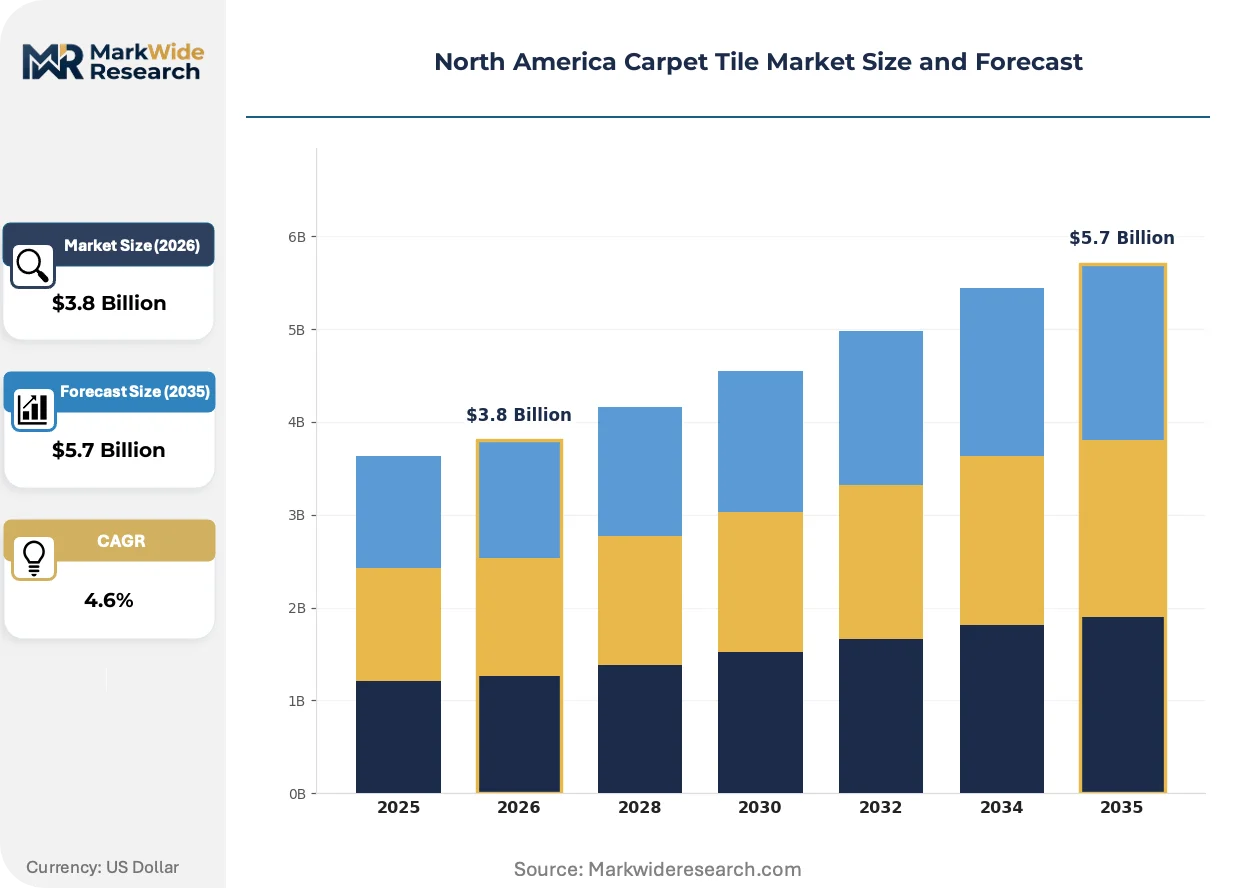
Corporate office renovations across the United States are expanding specification of modular carpet tile systems, while EPA recycled content guidelines and California's VOC emissions standards tighten material compliance requirements throughout the value chain.
Growth Catalysts
- Corporate Office Renovations:Commercial real estate repositioning in Texas and California construction corridors is driving selective replacement demand for 18-inch and 24-inch modular units in high-traffic environments.
- EPA Recycled Content Guidelines:Federal recommendations on post-consumer material incorporation are pushing manufacturers toward closed-loop recycling infrastructure and bitumen backing reformulation.
- OSHA Slip-Resistance Standards:Workplace safety mandates in healthcare and education channels are specifying textured surface treatments and enhanced traction coefficients for institutional installations.
Market Restraints
- Petrochemical Input Volatility:Nylon 6 and nylon 6,6 polymer prices fluctuate with crude oil derivatives, compressing margin stability for integrated yarn-to-tile producers in Georgia manufacturing clusters.
- Regional Supply Concentration:Domestic fiber extrusion capacity concentrates in the southeastern United States, creating geographic vulnerability to weather disruptions and logistics bottlenecks.
- Luxury Vinyl Tile Substitution:Rigid core LVT with attached pad is capturing multi-family residential conversion projects through lower installed cost and waterproof performance claims.
Strategic Opportunities
- Extended Producer Responsibility Frameworks:State-level take-back program mandates emerging in California and New York create first-mover advantage for manufacturers with established collection infrastructure.
- Plank Format Expansion:Open-plan office reconfigurations in Canadian commercial markets favor rectangular dimensions over traditional squares, enabling premium positioning through format differentiation.
- Healthcare Channel Penetration:Infection control protocols and NFPA fire code compliance requirements in US hospital systems favor PVC-backed modular systems with welded seam capabilities.
Industry Challenges
- Installation Certification Bottlenecks:Shortage of certified commercial flooring mechanics in Texas and California corridors is extending project timelines and inflating labor premiums for complex pattern-matching specifications.
- Legacy Inventory Integration:Broadloom-to-tile conversion capabilities require retraining specification sales teams and recalibrating distributor stocking patterns, creating channel friction during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Carpet Tile Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Tiles, Plank Tiles, Square Tiles, Mixed Format End User: Commercial Spaces, Residential Areas, Educational Institutions, Healthcare Facilities Installation Method: Direct Glue, Click-Lock, Adhesive, Loose Lay Material: Nylon, Polyester, Polypropylene, Natural Fiber |
| Companies Covered | Interface, Mohawk Industries, Tarkett, Shaw Industries Group Inc., Abbey Carpet & Floor, Bentley Mills, Inc., Engineered Floors LLC, Dixie Group Inc., Foss Floors, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Carpet Tile Market Evolving Landscape
Material formulation decisions are converging with digital specification tools and circular economy infrastructure, compressing product development cycles while expanding performance transparency across commercial procurement workflows.
Biobased nylon alternatives derived from castor oil feedstocks are expanding into corporate headquarters and government building specifications seeking LEED v4.1 materials credits. Facility managers in California and Texas are piloting these polymers for 50,000-square-foot-plus installations. This expansion is pressuring conventional petroleum-based nylon suppliers to accelerate renewable content roadmaps or surrender premium positioning in public-sector bids.
California Air Resources Board VOC limits are forcing reformulation of bitumen and PVC backing systems below 50 micrograms per square meter per hour emission thresholds. Manufacturers with in-house polymer compounding capabilities are internalizing testing protocols to accelerate certification timelines. Healthcare and education end users in the western United States are now requiring third-party verified emissions documentation as a gatekeeping criterion for project inclusion.
Building information modeling integration is reshaping how architects and contractors specify modular flooring, with 3D visualization tools enabling real-time pattern configuration and waste calculation. Commercial design firms in Toronto and Vancouver are requiring digital product libraries from suppliers, displacing traditional physical sample-based selection processes. This behavioral shift concentrates specification influence among manufacturers investing in parametric design plugin development and API connectivity with Autodesk and Trimble platforms.
North America Carpet Tile Market Segmentation
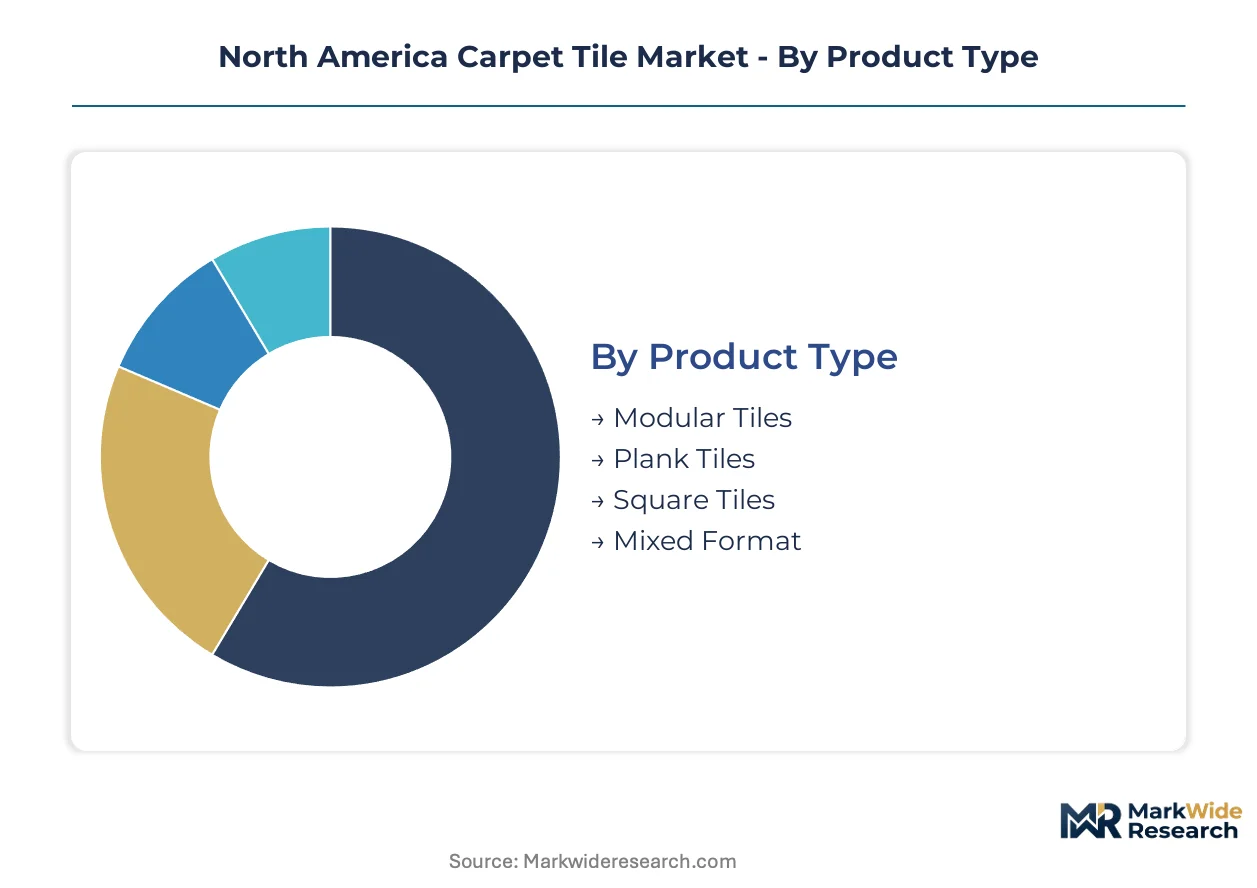
North America carpet tile segmentation reveals divergent capital requirements and margin profiles across manufacturing configurations. Product format and material chemistry drive equipment intensity, while end-user channels determine specification complexity and pricing power.
Product Type:
Capital intensity peaks with plank tile production due to specialized cutting and pattern-matching infrastructure. Modular and square formats leverage shared extrusion and tufting assets with lower retooling costs.
- Modular Tiles:Standard 18-inch and 24-inch square units with bitumen or PVC backing systems dominate high-traffic commercial replacements. Texas and California office renovations specify these for selective replacement and reduced installation waste in 50,000-square-foot-plus corporate campuses.
- Plank Tiles:Rectangular dimensions require precision cutting equipment and advanced pattern-matching software for open-plan reconfigurations. Canadian commercial markets in Toronto and Vancouver favor this format, enabling premium positioning through differentiated aesthetics.
- Square Tiles:Legacy format with established installation protocols serves budget-sensitive institutional projects. Standardized dimensions reduce pattern complexity and labor certification requirements.
- Mixed Format:Combination systems integrating multiple dimensions within single installations demand enhanced design support and project-specific manufacturing runs.
Modular tiles absorb the bulk of installed capacity; plank tiles are expanding most quickly.
End User:
Application diversity spans from price-sensitive residential conversions to specification-intensive healthcare systems. Channel requirements dictate backing chemistry, fire-code compliance, and warranty terms.
- Commercial Spaces:Corporate headquarters and government buildings drive specification of biobased nylon alternatives for LEED v4.1 materials credits. California and Texas facility managers pilot castor oil-derived polymers in large-format installations.
- Healthcare Facilities:Infection control protocols and NFPA fire code compliance favor PVC-backed modular systems with welded seam capabilities. US hospital systems require third-party verified emissions documentation below 50 micrograms per square meter per hour.
- Educational Institutions:K-12 and university projects balance durability requirements against constrained capital budgets. OSHA slip-resistance standards specify textured surface treatments for institutional safety.
- Residential Areas:Multi-family conversions face substitution pressure from rigid core LVT with waterproof performance claims. Polypropylene competes aggressively on price in this channel.
Commercial spaces command the largest specification volume; healthcare facilities generate the steepest margin premiums.
Installation Method:
Method selection determines subfloor preparation costs and project timeline elasticity. Glue-down systems require skilled labor certification, while floating formats reduce mechanical dependency.
- Direct Glue:Permanent adhesion for high-traffic environments demands precise subfloor leveling and moisture testing. Certified commercial flooring mechanics in Texas and California corridors command labor premiums for complex pattern-matching specifications.
- Adhesive:Pressure-sensitive and releasable formulations enable selective replacement without full demolition. Healthcare and education end users favor this for phased renovation schedules.
- Click-Lock:Mechanical interlocking reduces installation time and skill requirements. Residential and light commercial applications prioritize speed over maximum durability.
- Loose Lay:Friction-based installation eliminates adhesive entirely, suitable for temporary or rapidly reconfigurable spaces. Weight and backing texture determine stability performance.
Direct glue retains the largest installed base; click-lock is climbing the fastest in residential conversions.
Material:
Polymer chemistry dictates extrusion equipment scale and raw material hedging strategies. Nylon requires integrated yarn-to-tile manufacturing, while polypropylene permits outsourced fiber procurement.
- Nylon:Nylon 6 and nylon 6,6 sustain dominant specification rates in commercial applications despite petrochemical input volatility. Integrated manufacturing clusters in Georgia internalize polymer compounding to accelerate California Air Resources Board VOC certification timelines.
- Polypropylene:Lower density and cost profile competes in multi-family residential and budget institutional segments. Price-driven procurement tolerates higher replacement frequency.
- Polyester:Recycled content compatibility aligns with EPA recycled content guidelines and emerging extended producer responsibility frameworks. Post-consumer bottle feedstocks support circular economy positioning.
- Natural Fiber:Wool and sisal alternatives serve premium aesthetic specifications with limited moisture tolerance. Niche positioning in corporate headquarters seeking biogenic material narratives.
Nylon captures the majority of commercial specification value; polyester is gaining share fastest through recycled content mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial construction corridors in Texas and California absorb the dominant share of specification volume, with corporate office renovations and state-level emissions mandates recalibrating procurement patterns across the continent.
United States
Texas and California construction corridors drive selective replacement demand for 18-inch and 24-inch modular units in 50,000-square-foot-plus corporate campuses. EPA recycled content guidelines push manufacturers toward closed-loop recycling infrastructure and bitumen backing reformulation. Georgia manufacturing clusters anchor integrated yarn-to-tile production with in-house polymer compounding capabilities.
Canada
Open-plan office reconfigurations in Toronto and Vancouver favor rectangular plank formats over traditional squares, enabling premium positioning through format differentiation. Provincial building codes in Ontario and British Columbia align with LEED v4.1 materials credit requirements for government and corporate headquarters. Quebec distributors serve as secondary procurement nodes for Atlantic commercial markets.
Mexico
Nearshoring manufacturing investments in Nuevo León and the Bajío Region create incremental demand for commercial flooring in expanded industrial facilities. Mexican federal environmental standards lag California Air Resources Board thresholds, permitting cost-competitive specification for budget-sensitive projects. Mexico City Metro area concentrates specification influence among multinational corporate tenants.
Southeast United States
Florida and Georgia educational institutions balance durability requirements against constrained capital budgets, specifying textured surface treatments for OSHA slip-resistance compliance. Hurricane resilience codes in Miami-Dade and Broward counties favor PVC-backed modular systems with moisture-resistant performance. Atlanta serves as the dominant logistics hub for southeastern distribution networks.
North America Carpet Tile Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated manufacturers internalize polymer compounding to accelerate certification timelines. The market structures around three tiers: multinational flooring conglomerates with captive fiber extrusion, regional specialists focused on format differentiation, and conversion-oriented players migrating from broadloom production. Strategic archetypes include closed-loop recycling operators, healthcare channel specialists, and residential price competitors. M&A activity and geographic expansion into Canadian markets represent the dominant competitive vectors.
Within the integrated manufacturing tier, Interface and Mohawk Industries exemplify divergent approaches to circular economy positioning, while Shaw Industries Group Inc. occupies a distinctive conversion-focused niche. Interface represents the closed-loop recycling archetype with established collection infrastructure. Mohawk Industries anchors volume production through Georgia-based yarn-to-tile integration. Shaw Industries Group Inc. exemplifies the broadloom-to-tile transition strategy serving institutional channels.
| Leading Market Players |
|---|
| Interface |
| Mohawk Industries |
| Tarkett |
| Shaw Industries Group Inc. |
| Abbey Carpet & Floor |
| Bentley Mills, Inc. |
| Engineered Floors LLC |
| Dixie Group Inc. |
| Foss Floors |
| Others |
Value Network & Pricing Analysis
California Air Resources Board VOC limits gate qualified supply and premium-tier pricing access for carpet tile manufacturers serving western commercial markets. Compliance with sub-50 micrograms per square meter per hour emission thresholds requires in-house polymer compounding capabilities that concentrate production economics among integrated operators.
Pricing Analysis
Volume-margins split sharply between commodity polypropylene residential tiles and specification-grade nylon commercial systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and LEED v4.1 materials credit eligibility. Price erosion runs through multi-family residential conversions as rigid core LVT captures substitution demand. Healthcare facility buyers exhibit lowest price sensitivity due to infection control protocol requirements, while residential developers prioritize installed cost minimization.
Supply Chain Analysis
Multi-supplier qualification mandates from Texas and California facility managers require carpet tile buyers to maintain dual-sourcing relationships with Georgia-based integrated manufacturers and regional specialists. Raw material dependencies center on nylon 6 and nylon 6,6 polymers, bitumen backing compounds, and PVC resin systems. Supply chain risk concentrates in southeastern United States fiber extrusion clusters vulnerable to hurricane disruption. Distribution runs through Atlanta logistics hubs serving commercial flooring contractors and specification sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America carpet tile market sits in a material-transition phase as biobased nylon alternatives displace petroleum-derived polymers in corporate headquarters and government building specifications.
For Market Incumbents: Cement closed-loop recycling infrastructure advantages by accelerating castor oil-derived polymer scale-up before conventional suppliers reformulate. Expand Georgia manufacturing clusters with in-house polymer compounding to compress California Air Resources Board certification timelines. Defend against rigid core LVT substitution by emphasizing welded seam capabilities in healthcare channel specifications. For New Entrants and Emerging Players: Canadian commercial markets in Toronto and Vancouver represent underserved buyer archetypes seeking plank format differentiation for open-plan reconfigurations. Mexico's Nuevo León nearshoring corridor offers white-space demand from expanded industrial facilities with less stringent federal environmental standards. Pursue specification influence through building information modeling plugin development and Autodesk platform integration. For Investors and Strategic Acquirers: State-level extended producer responsibility framework adoption in California and New York is the leading indicator that collection infrastructure valuation premiums will widen across the analysis window. Target manufacturers with established take-back programs and bitumen backing reformulation capabilities. Watch for biobased nylon pilot installation announcements above 50,000 square feet as inflection signals for renewable content roadmaps.| Strategic Initiative | Industry Significance |
|---|---|
| Biobased Nylon Scale-Up | Castor oil-derived polymer investments secure LEED v4.1 positioning in Texas and California government bids. |
| Closed-Loop Recycling Infrastructure | Collection network expansion enables compliance with emerging New York and California take-back mandates. |
| Plank Format Manufacturing Capacity | Precision cutting equipment investments capture premium positioning in Toronto and Vancouver commercial markets. |
| In-House Polymer Compounding | Internal testing protocols accelerate sub-50 micrograms per square meter per hour VOC certification timelines. |
| Building Information Modeling Integration | Autodesk and Trimble API connectivity concentrates specification influence among commercial design firms. |
Research Methodology
Document review covered EPA recycled content guidelines, California Air Resources Board technical bulletins, and NFPA fire code documentation, complemented by interviews with commercial flooring contractors, facility managers at Texas and California corporate campuses, specification sales directors, polymer compounding engineers, and healthcare procurement officers. Secondary sources included SEC 10-K filings from integrated flooring manufacturers, customs trade data on nylon fiber imports, and LEED project registration databases. Bottom-up volume modeling triangulated against top-down construction spending forecasts.
Cross-referencing historical installation data against industry panel input anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, material chemistry, end-user channel, installation method, and regional construction corridor. CAGRs derived from polynomial trend fitting adjusted for petrochemical input volatility and regulatory compliance cost trajectories. Forecast inputs incorporated commercial real estate repositioning velocity and state-level extended producer responsibility legislative tracking.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nylon polymer price volatility and California VOC threshold tightening. Projections reflect assumptions on corporate renovation cycle duration and biobased nylon cost parity achievement. Deviation in rigid core LVT waterproof performance claims or federal recycled content mandate expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Decorative Rugs Market
Flooring, Carpets, and Rugs
China Floor Covering Market
Flooring, Carpets, and Rugs
Laminate Flooring Market
Flooring, Carpets, and Rugs
US Resilient Flooring Market
Flooring, Carpets, and Rugs
India Carpets and Rugs Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market
Flooring, Carpets, and Rugs
Saudi Arabia Vinyl Flooring Market
Flooring, Carpets, and Rugs
Wooden Floor Market
Flooring, Carpets, and Rugs
Stone Flooring Market
Flooring, Carpets, and Rugs
ASEAN Laminate Flooring Market
Flooring, Carpets, and Rugs
Sheet Flooring Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
China Engineered Wood Flooring Market
Flooring, Carpets, and Rugs
Global Flooring and Carpet Market
Flooring, Carpets, and Rugs
Foam Flooring Products Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market