
 Japan Condominiums and Apartments Market | 2026-2036
Japan Condominiums and Apartments Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Condominiums and Apartments Market Foresight
Modular construction and prefabricated unit assembly is reconfiguring how Japanese developers deliver housing stock at scale. Sekisui House Limited leverages its steel-frame modular system to compress build timelines for high-rise towers. Mitsui Fudosan Co., Ltd. anchors premium positioning through integrated neighborhood development combining retail, office, and residential functions. Daiwa House Industry Co., Ltd. extends manufacturing scale from single-family homes into multi-family prefabricated structures.
Japan condominiums and apartments comprise individually owned residential units within multi-dwelling structures governed by the Act on Building Unit Ownership, with floor areas typically ranging from twenty to one hundred square meters and managed through mandatory owners' associations. These properties serve as primary shelter, investment vehicles, and rental income generators in one of the world's most urbanized societies. Luxury and mixed-use facility types concentrate margin pools in central Tokyo and Osaka, while affordable and studio product types attract first-time buyers and single-person households amid demographic contraction. High-rise construction dominates new supply in waterfront redevelopment zones, whereas low-rise and gated community formats persist in suburban family corridors.
METI energy-efficiency mandates and the Building Standards Act shape material specifications, seismic performance thresholds, and insulation requirements for all new multi-unit construction. JIS standards for structural steel and concrete reinforcement govern quality benchmarks, while local municipal ordinances in Yokohama, Nagoya, and Kyoto impose additional environmental assessment protocols. Stakeholders must track how the national ZEB roadmap and evolving condominium management regulations alter replacement demand cycles and retrofit investment thresholds.
Market Dynamics
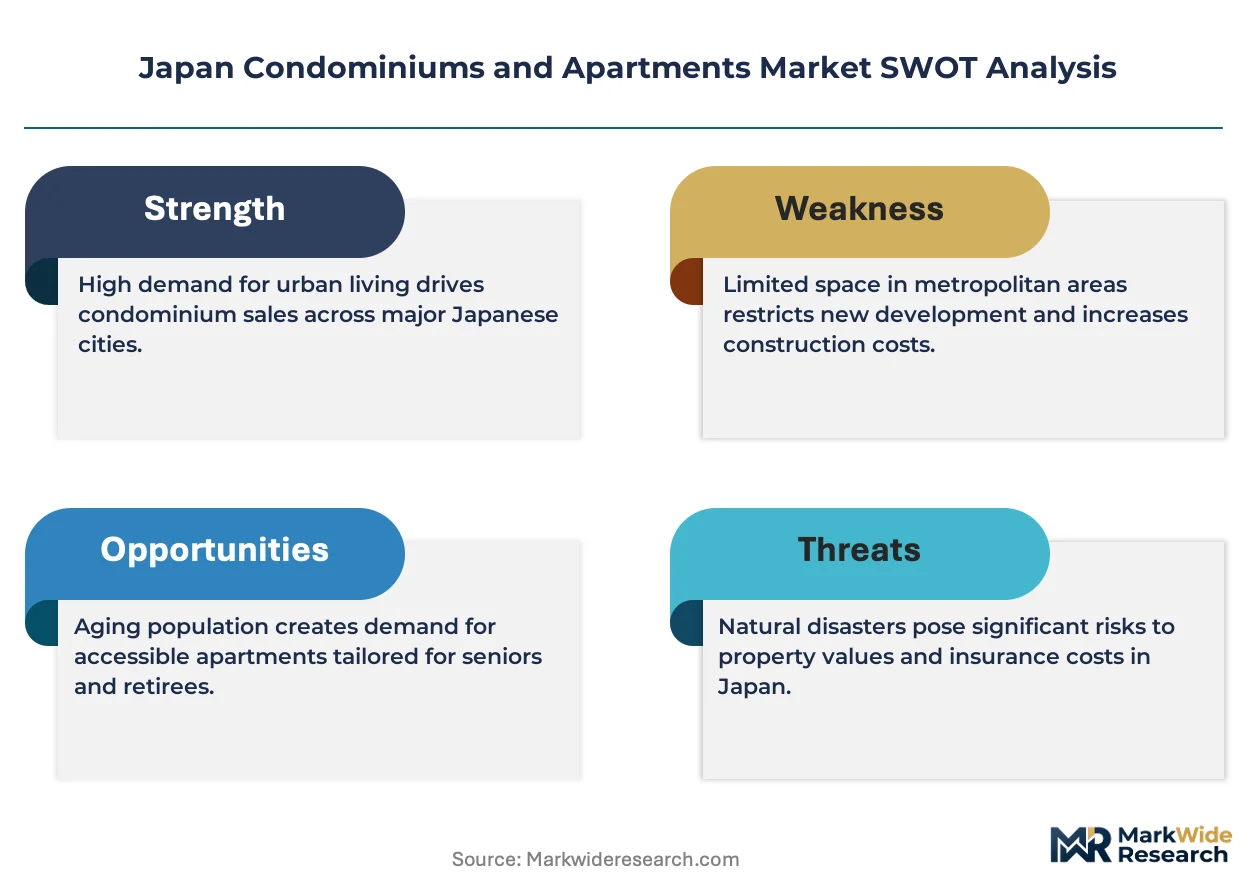
Japan's condominium and apartment sector faces structural pressure from demographic contraction colliding with METI's ZEB-ready housing mandates, forcing developers to absorb higher material costs while serving shrinking household formation.
Growth Catalysts
- Foreign corporate transferee inflows:Tokyo's 23 wards absorb rising demand from multinational assignees seeking proximity to headquarters clusters, tightening vacancy rates in Minato and Shibuya wards.
- Prefabricated steel-frame modular systems:Factory-based unit assembly compresses construction timelines by 30-40% versus conventional cast-in-place methods, enabling faster inventory turnover.
- Regional first-time buyer activation:Municipal housing subsidies in Fukuoka and Sapporo unlock mortgage access for younger households priced out of Greater Tokyo.
Market Restraints
- Imported structural timber cost volatility:Yen depreciation elevates laminated wood and engineered lumber expenses for low-rise wooden-frame apartments.
- Condominium management association dysfunction:Aging buildings in Osaka and Nagoya face delayed seismic retrofits due to owner disputes over special assessment levies.
- Land scarcity in central business districts:Redevelopment site availability concentrates in waterfront zones, limiting infill opportunities.
Strategic Opportunities
- Sapporo cold-climate housing stock:Underpenetrated premium insulation and triple-glazed window specifications address Hokkaido's heating load intensity.
- Integrated retail-office-residential mixed-use:Station-adjacent developments capture rent premiums from convenience-seeking single-person households.
- METI ZEB roadmap compliance:Net-zero energy building certification creates pricing power for developers achieving primary energy balance.
Industry Challenges
- Seismic engineer talent scarcity:Specialized structural calculation expertise for high-rise base-isolation systems concentrates among aging practitioners.
- Owners' association digitization lag:Paper-based management practices delay maintenance scheduling and financial transparency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Condominiums and Apartments Market |
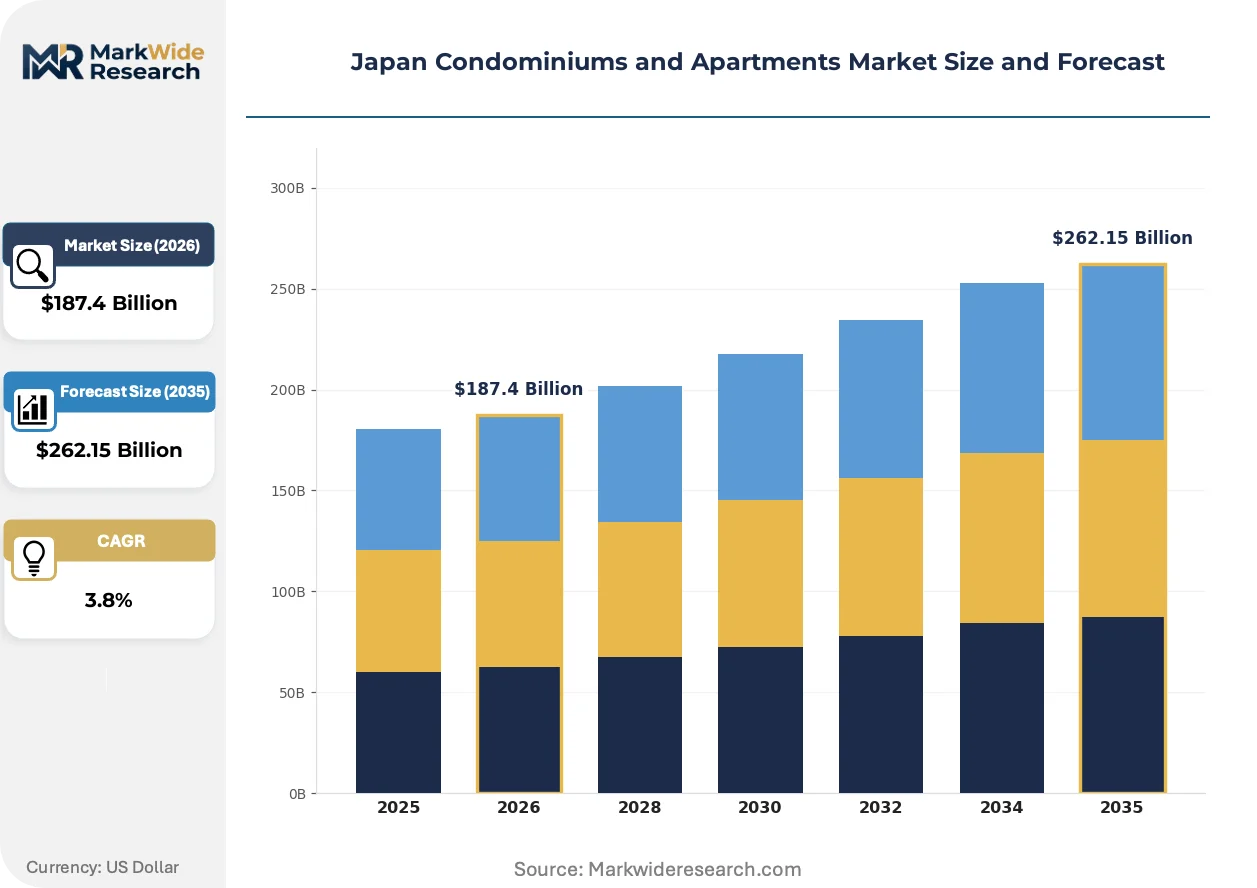
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $262.15 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury, Mid-Range, Affordable, Studio End User: Investors, First-Time Buyers, Renters, Seniors Facility Type: High-Rise, Low-Rise, Mixed-Use, Gated Community Sales Channel: Real Estate Agency, Direct Purchase, Online Listing, Auction |
| Companies Covered | Sekisui House Limited, Sumitomo Forestry Co., Ltd., Mitsui Fudosan Co., Ltd., Kajima Corporation, Sumitomo Realty & Development Co., Ltd., Panasonic Homes Co., Ltd., Tokyu Land Corporation, Nomura Real Estate Development Co., Ltd., Daiwa House Industry Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Condominiums and Apartments Market Shifts & Advancements
Japan's multi-family housing delivery is pivoting toward factory precision and energy performance, with regulatory mandates and buyer preferences converging on measurable outcomes rather than speculative amenities.
Cross-laminated timber and steel hybrid structural systems are hybridizing traditional Japanese post-and-beam methods with European mass timber engineering. Mid-rise developers in Nagoya and Kyoto adopt these composites for 8-12 story buildings, satisfying both seismic code and carbon accounting requirements. The technology is hybridizing supply chains as domestic sawmills partner with Austrian engineering firms for joint-venture production facilities.
METI's Building Energy Efficiency Act amendments tighten insulation standards for all new multi-unit construction effective fiscal year 2025. Developers must now submit whole-building energy simulation models before permitting approval, adding 4-6 months to pre-construction phases. High-rise towers in Tokyo Bay redevelopment zones face the steepest compliance costs, prompting some sponsors to pivot toward smaller-scale projects in Yokohama where municipal subsidies offset certification expenses.
Single-person households now dominate new condominium absorption, displacing family-oriented three-bedroom units from developer pipelines. This demographic pivot compresses average unit sizes below 50 square meters and elevates demand for built-in storage and flexible partition systems. Osaka's Namba and Umeda districts exhibit the most pronounced shift, with 70% of new completions targeting solo occupants aged 35-50.
Japan Condominiums and Apartments Market Segmentation
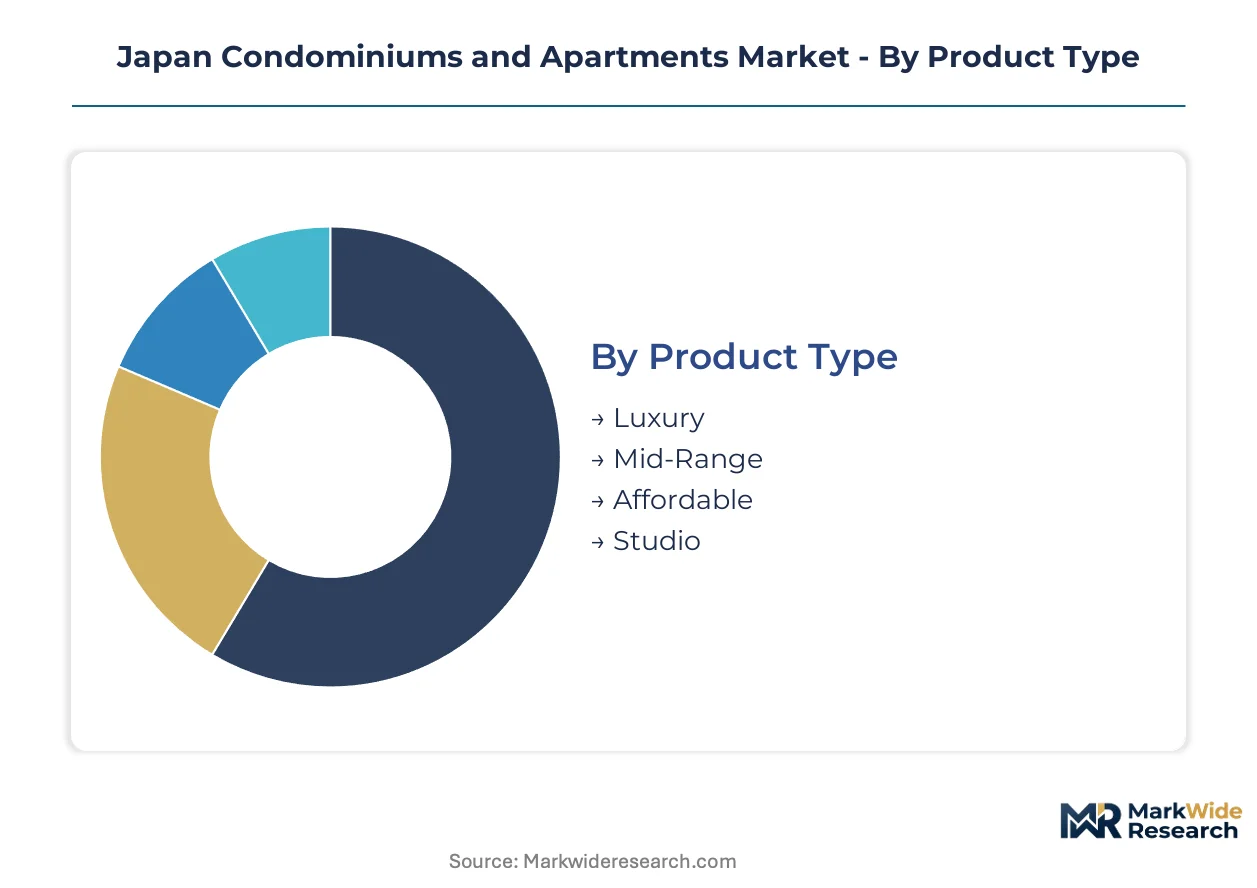
Segmentation in Japan's condominium and apartment market reveals how demographic contraction and METI energy mandates reshape product pipelines. Developers must align unit specifications with distinct buyer liquidity profiles and regulatory compliance tiers.
Product Type:
Inventory velocity varies sharply across price tiers, with studio and affordable units turning over fastest while luxury stock absorbs capital over extended marketing cycles.
- Luxury:Premium-grade finishes and base-isolation systems command pricing power in Minato and Shibuya wards. Foreign corporate transferees and domestic high-net-worth households concentrate absorption here, though METI ZEB compliance adds 6-8 months to pre-construction timelines.
- Mid-Range:Standard specifications targeting family households in Yokohama and Chiba prefecture. Municipal subsidies in regional hubs accelerate mortgage approvals for this tier, compressing sales cycles versus central Tokyo equivalents.
- Affordable:Compact layouts under 50 square meters serve first-time buyers in Fukuoka and Sapporo. JIS-compliant seismic reinforcement maintains structural integrity at lower cost points.
- Studio:Single-occupant configurations dominate Osaka's Namba and Umeda pipeline, with 70% of new completions targeting solo households aged 35-50. Built-in storage and flexible partitions maximize functional density.
Mid-Range anchors the volume base while Studio gains share at the steepest rate.
End User:
Buyer motivation splits between yield-seeking capital deployment and shelter-first consumption, with regulatory treatment diverging across these profiles.
- Investors:Yield-focused purchasers target station-adjacent studios in Tokyo's 23 wards for rental income stability. METI depreciation rules and mortgage tax deductions shape holding period calculations.
- First-Time Buyers:Younger households in regional cities leverage municipal subsidies and reduced down-payment requirements. Sapporo and Fukuoka municipal housing programs unlock access previously constrained by Greater Tokyo pricing.
- Renters:Transient demand for flexible lease terms persists among corporate assignees and students. This segment rarely purchases, instead filtering demand into landlord acquisition decisions.
- Seniors:Downsizing households from suburban detached homes seek barrier-free designs and proximity to medical facilities. Universal design mandates under the Building Standards Act elevate specification requirements.
First-Time Buyers drive absolute transaction counts while Investors expand most quickly in central ward supply.
Facility Type:
Structural format determines land use efficiency, seismic engineering complexity, and amenity integration potential across development sites.
- High-Rise:Steel-frame towers exceeding 20 stories dominate Tokyo Bay and Osaka waterfront redevelopment. Base-isolation systems and whole-building energy simulation models add compliance layers under METI's Building Energy Efficiency Act amendments.
- Low-Rise:Wooden and steel hybrid construction persists in suburban family corridors. Cross-laminated timber adoption spreads in Nagoya and Kyoto for 8-12 story mid-rise applications.
- Mixed-Use:Integrated retail-office-residential formats capture rent premiums from convenience-seeking single-person households. Mitsui Fudosan anchors premium positioning through neighborhood-scale development.
- Gated Community:Enclave formats with shared security and maintenance services attract senior downsizers and family households seeking managed environments. Owners' association governance structures determine long-term asset condition.
High-Rise concentrates development capital while Mixed-Use climbs the fastest as station-adjacent land scarcity intensifies.
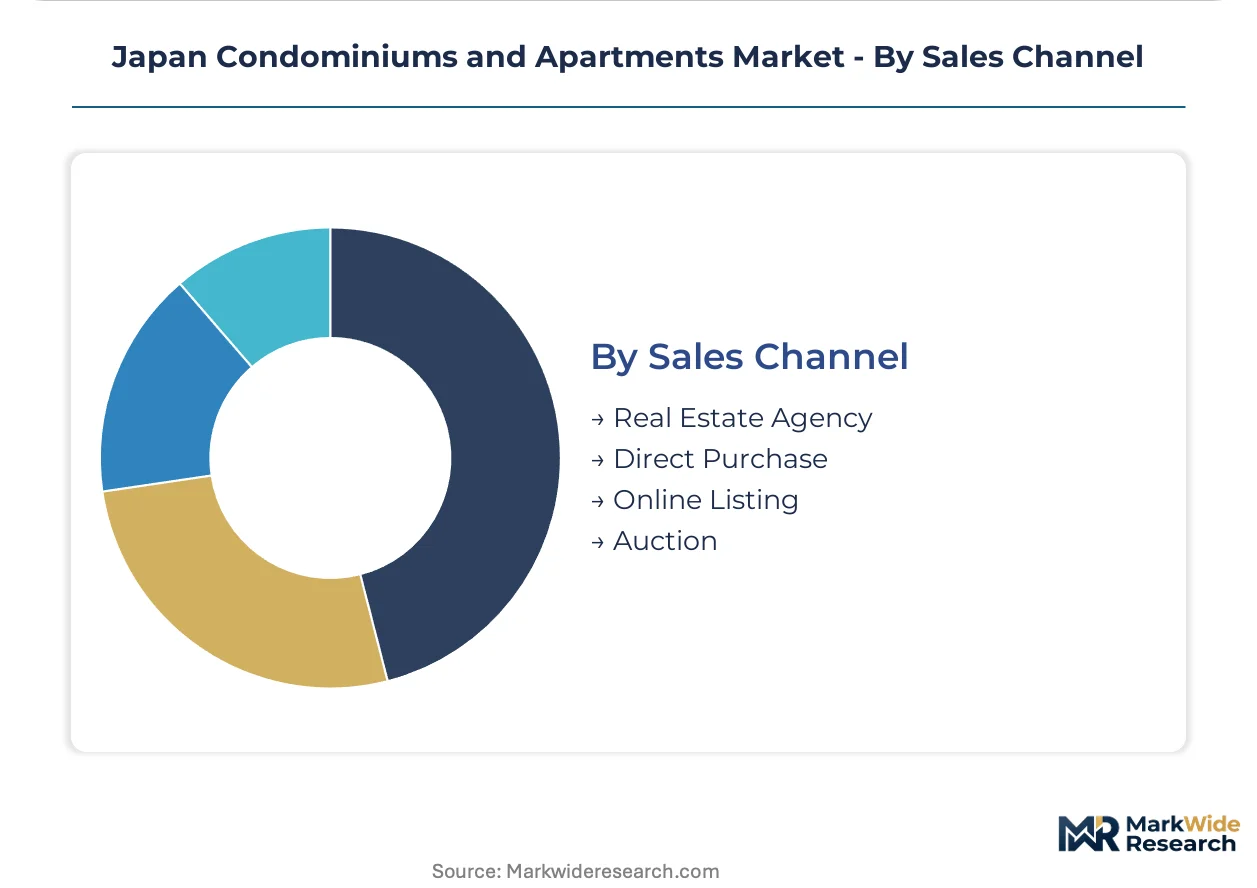
Sales Channel:
Transaction pathway selection reflects buyer sophistication, urgency, and price sensitivity across market cycles.
- Real Estate Agency:Broker-mediated sales dominate standard transactions, with agency networks controlling inventory visibility in regional markets. Commission structures typically absorb 3-5% of transaction value.
- Direct Purchase:Developer-to-buyer transactions bypass intermediary fees for new construction. Sekisui House and Daiwa House leverage brand recognition to channel buyers through proprietary sales offices.
- Online Listing:Digital platforms aggregate resale inventory, compressing information asymmetry for comparison shoppers. Transparency on maintenance fees and owners' association financials remains uneven.
- Auction:Distressed and estate-sale properties transact through court-supervised bidding. Judicial scrivener involvement adds procedural complexity and timeline uncertainty.
Real Estate Agency maintains transaction volume leadership while Online Listing expands most rapidly among younger buyer cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign corporate transferees and first-time buyers concentrate demand in distinct geographic pockets, with METI energy mandates and municipal subsidy programs reshaping where developers commit capital across Japan's urban hierarchy.
Kanto/Tokyo
Minato and Shibuya wards absorb multinational assignee demand, tightening vacancy rates for studio and one-bedroom inventory. METI's Building Energy Efficiency Act amendments force whole-building energy simulation submissions before permitting approval. Tokyo Bay waterfront redevelopment zones concentrate high-rise steel-frame towers exceeding 20 stories, though compliance costs prompt some sponsors toward smaller-scale Yokohama projects.
Kansai/Osaka
Namba and Umeda districts exhibit the steepest pivot toward single-occupant configurations, with 70% of new completions targeting solo households aged 35-50. Aging condominium stock in central wards faces delayed seismic retrofits due to owner association dysfunction over special assessment disputes. Osaka's municipal housing programs unlock mortgage access for younger households priced out of Greater Tokyo.
Chubu/Nagoya
Cross-laminated timber and steel hybrid structural systems spread across 8-12 story mid-rise applications, hybridizing Japanese post-and-beam methods with European mass timber engineering. JIS standards for structural steel govern quality benchmarks for these composite builds. Nagoya's municipal ordinances impose additional environmental assessment protocols beyond national baselines.
Kyushu
Fukuoka municipal housing subsidies accelerate first-time buyer activation among younger households seeking alternatives to Greater Tokyo pricing. Regional developer pipelines emphasize compact layouts under 50 square meters with JIS-compliant seismic reinforcement at lower cost points. Fukuoka's station-adjacent land scarcity intensifies mixed-use integrated formats capturing rent premiums.
Hokkaido
Sapporo cold-climate housing stock remains underpenetrated for premium insulation and triple-glazed window specifications addressing heating load intensity. Municipal housing programs in Sapporo unlock mortgage access previously constrained by down-payment requirements. Hokkaido's demographic profile favors barrier-free universal design mandates under the Building Standards Act for senior downsizers.
Japan Condominiums and Apartments Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale advantages in manufacturing integration clash with neighborhood-scale development expertise. The vendor base clusters around three strategic archetypes: steel-frame modular system operators, integrated mixed-use neighborhood developers, and manufacturing-scale prefabricated housing specialists. Dominant competitive moves include backward integration into factory-based unit assembly and portfolio diversification across retail-office-residential combinations.
Among integrated development specialists, Mitsui Fudosan Co., Ltd. and Tokyu Land Corporation occupy positions emphasizing station-adjacent neighborhood-scale projects. Sekisui House Limited represents the modular manufacturing archetype with steel-frame system capabilities. Daiwa House Industry Co., Ltd. exemplifies scale-driven prefabricated production extending from single-family into multi-family structures. These three names anchor the competitive topology without exhausting the participant set.
| Leading Market Players |
|---|
| Sekisui House Limited |
| Sumitomo Forestry Co., Ltd. |
| Mitsui Fudosan Co., Ltd. |
| Kajima Corporation |
| Sumitomo Realty & Development Co., Ltd. |
| Panasonic Homes Co., Ltd. |
| Tokyu Land Corporation |
| Nomura Real Estate Development Co., Ltd. |
| Daiwa House Industry Co., Ltd. |
| Others |
Supply & Pricing Matrix
Osaka's Namba and Umeda districts concentrate prefabricated unit assembly capacity, compressing build timelines and transmitting cost efficiencies downstream to Tokyo buyers. METI's Building Energy Efficiency Act amendments force developers to absorb 4-6 months of pre-construction compliance costs, tightening margins on standard-specification inventory.
Pricing Analysis
Cost-plus contracts with steel and concrete indexation dominate developer-procurement relationships, exposing margins to yen-denominated commodity volatility. Three-tier pricing structure across premium, standard, and economy levels separates base-isolated luxury towers in Minato from JIS-compliant affordable stock in Fukuoka. Pricing pressure stems from imported structural timber cost volatility as yen depreciation elevates laminated wood expenses. First-time buyers in regional hubs exhibit highest price sensitivity; foreign corporate transferees in Tokyo's 23 wards show lowest.
Supply Chain Analysis
Japan's export-control regime on seismic base-isolation technology limits technology transfer to domestic engineering consortiums, concentrating specialized expertise among aging practitioners. Manufacturing draws from domestic steel mills, Austrian-engineered mass timber joint ventures, and South Korean precision component suppliers. Cross-laminated timber and steel hybrid systems create single-source vulnerability as domestic sawmill partnerships mature. Distribution runs through developer-direct sales offices and real estate agency networks controlling regional inventory visibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as foreign corporate transferee inflows tighten central Tokyo vacancy rates and unlock pricing power for station-adjacent inventory.
For Market Incumbents: Build regulatory compliance moats through METI ZEB certification capabilities that smaller developers cannot replicate. Sekisui House and Daiwa House should deepen backward integration into factory-based unit assembly to offset timber cost volatility. Channel control through proprietary sales offices defends against digital platform disintermediation threatening agency commission structures. For New Entrants and Emerging Players: Sapporo's cold-climate housing stock offers underpenetrated white space for premium insulation and triple-glazed window specifications. Fukuoka municipal subsidy programs unlock first-time buyer segments with lower competitive density than Greater Tokyo. Station-adjacent mixed-use formats in regional hubs provide the most penetrable entry vector for yield-focused capital deployment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors steel-frame modular system operators with manufacturing scale advantages over pure-play land developers. Long-term viability hinges on regulatory compliance capabilities across the METI ZEB roadmap. Acquisition targets should demonstrate owners' association digitization platforms that resolve paper-based management dysfunction. Watch foreign corporate transferee assignment volumes as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Manufacturing Scale-Up | Sekisui House's steel-frame system compresses high-rise build timelines by 30-40% versus conventional methods. |
| ZEB Certification Investment | METI compliance creates pricing power for developers achieving net-zero energy balance in Tokyo Bay towers. |
| Cross-Laminated Timber Joint Venture | Domestic sawmill partnerships with Austrian engineering firms hybridize supply chains for 8-12 story Nagoya builds. |
| Owners' Association Digitization | Platform investment resolves paper-based management dysfunction delaying seismic retrofits in aging Osaka stock. |
| Regional Municipal Subsidy Access | Fukuoka and Sapporo housing programs unlock first-time buyer mortgage access previously constrained by down-payment requirements. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with condominium developers, seismic engineering consultants, municipal housing officers, and owners' association managers; and secondary validation through METI regulatory filings, JIS standards documentation, municipal subsidy program disclosures, and prefectural construction permit databases. Bottom-up unit absorption modeling triangulated against top-down GDP and household formation projections.
Forecast inputs span product type segmentation across luxury, mid-range, affordable, and studio tiers; facility type dimensions including high-rise, low-rise, mixed-use, and gated community formats; and end-user profiles splitting investor, first-time buyer, and senior downsizer demand. CAGRs derive from regression analysis against demographic contraction trajectories and METI energy mandate implementation schedules across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cross-laminated timber joint venture specialists or foreign modular construction entrants would shift outcomes. Material shifts in yen trajectory or METI ZEB roadmap acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condominium and Apartments
Global Condominiums and Apartments Market
Condominium and Apartments
Germany Condominiums and Apartments Market
Condominium and Apartments
Europe Condominiums and Apartments Market
Condominium and Apartments
Latin America Condominiums and Apartments Market
Condominium and Apartments
Spain Condominiums and Apartments Market
Condominium and Apartments
Canada Condominiums and Apartments Market
Condominium and Apartments
Condom Market
Condominium and Apartments
UAE Condominiums and Apartments Market
Condominium and Apartments
Italy Condominiums and Apartments Market
Condominium and Apartments
ASEAN Condominiums and Apartments Market
Condominium and Apartments
India Condominium and Apartments Market
Condominium and Apartments
Qatar Condominium and Apartment Market
Condominium and Apartments
Saudi Arabia Condominiums and Apartments Market
Condominium and Apartments
Asia-Pacific Condominiums and Apartments Market
Condominium and Apartments
Egypt Condominiums and Apartments Market