
 Asia Pacific Manufactured Homes Market | 2026-2036
Asia Pacific Manufactured Homes Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Manufactured Homes Market Outlook
Subscription-based maintenance and software-defined energy management is consolidating around manufactured housing platforms across the Asia Pacific. Daiwa House Industry leverages its captive supply of precision-engineered wall panels to dominate Japan's premium modular segment. Sekisui House sustains R&D intensity in seismic-resistant framing systems that anchor its technical reputation. CIMC Modular Building Systems competes on manufacturing scale, operating some of the largest automated production lines serving Australia's developer channel.
Manufactured homes are factory-built residential structures produced in controlled environments and transported to sites for installation, typically employing steel or timber frames with composite cladding and insulation rated to local wind and seismic codes. Their primary purpose is to deliver standardized, cost-controlled housing units faster than site-built alternatives while meeting national building performance thresholds. Multi-section and modular product types capture the strongest margin pools where developers seek volume efficiency without sacrificing design flexibility. Prefabricated construction methods are displacing traditional factory-built approaches in Australia as Hickory Group and Lendlease Group push design-build integration. Tiny homes remain a niche within the residential application category, constrained by zoning fragmentation rather than consumer interest.
Japan's METI enforces energy-efficiency benchmarks that filter into material specifications and manufacturing protocols, while Australia's National Construction Code governs structural and fire-safety compliance for factory-built units. China's GB standards and MIIT directives shape export-oriented production from Broad Sustainable Building and similar suppliers. India's BIS certification requirements for prefabricated structures are tightening as the country scales its affordable housing programs. Stakeholders must monitor how evolving national building codes interact with local zoning enforcement to determine viable deployment corridors.
Market Dynamics
Japan's METI energy-efficiency standards are compressing material procurement cycles across the Asia Pacific manufactured homes sector, forcing suppliers to requalify thermal performance specifications ahead of traditional replacement timelines. Australian state-level planning reforms are simultaneously accelerating development approval pathways for factory-built dwellings in southeastern corridors.
Growth Catalysts
- Australia's National Construction Code streamlining:Revisions to factory-built compliance pathways reduce approval timelines from 18 months to under 6 months for certified manufacturers, unlocking developer pipeline velocity in Victoria and New South Wales.
- Seismic-resistant framing R&D:Advanced cross-laminated timber and steel moment-frame systems developed for Japan's earthquake zones are migrating into Australian and New Zealand building codes as performance benchmarks tighten.
- Retiree downsizing clusters:First-time buyers and empty-nest households in suburban Adelaide, Brisbane, and Perth are forming concentrated demand pools for single-section manufactured dwellings with low-maintenance envelopes.
Market Restraints
- Structural steel input volatility:Galvanized steel coil prices fluctuate with Chinese export quotas and Australian dollar movements, compressing margin predictability for frame fabricators serving the developer channel.
- Zoning fragmentation:Local council overlays in Queensland and Western Australia restrict manufactured home placement to designated estates, limiting addressable land supply despite statewide planning reforms.
- Site-built substitution persistence:Volume homebuilders in Melbourne's outer growth corridors maintain cost competitiveness through project-scale purchasing power and established land banking positions.
Strategic Opportunities
- India's affordable housing scale-up:BIS certification alignment with factory-built construction methods opens procurement channels for 20 million urban housing units under national mission targets, with modular systems qualifying for interest subsidy linkage.
- Subscription maintenance bundling:Software-defined energy management platforms are attaching recurring revenue streams to manufactured housing sales, shifting vendor economics from one-time margin to lifetime value capture.
- CLT-photovoltaic envelope convergence:Cross-laminated timber roof cassettes with integrated solar thermal collectors address Japan's net-zero-ready building mandates while differentiating premium modular offerings.
Industry Challenges
- Seismic certification timeline compression:Japan's three-year structural performance reassessment cycles force continuous engineering documentation updates that strain mid-scale manufacturers without captive testing facilities.
- Installation crew skill scarcity:Qualified crane operators and module-sealing specialists command premium wages in Australia's southeastern corridor, where demand concentration outpaces vocational training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Manufactured Homes Market |
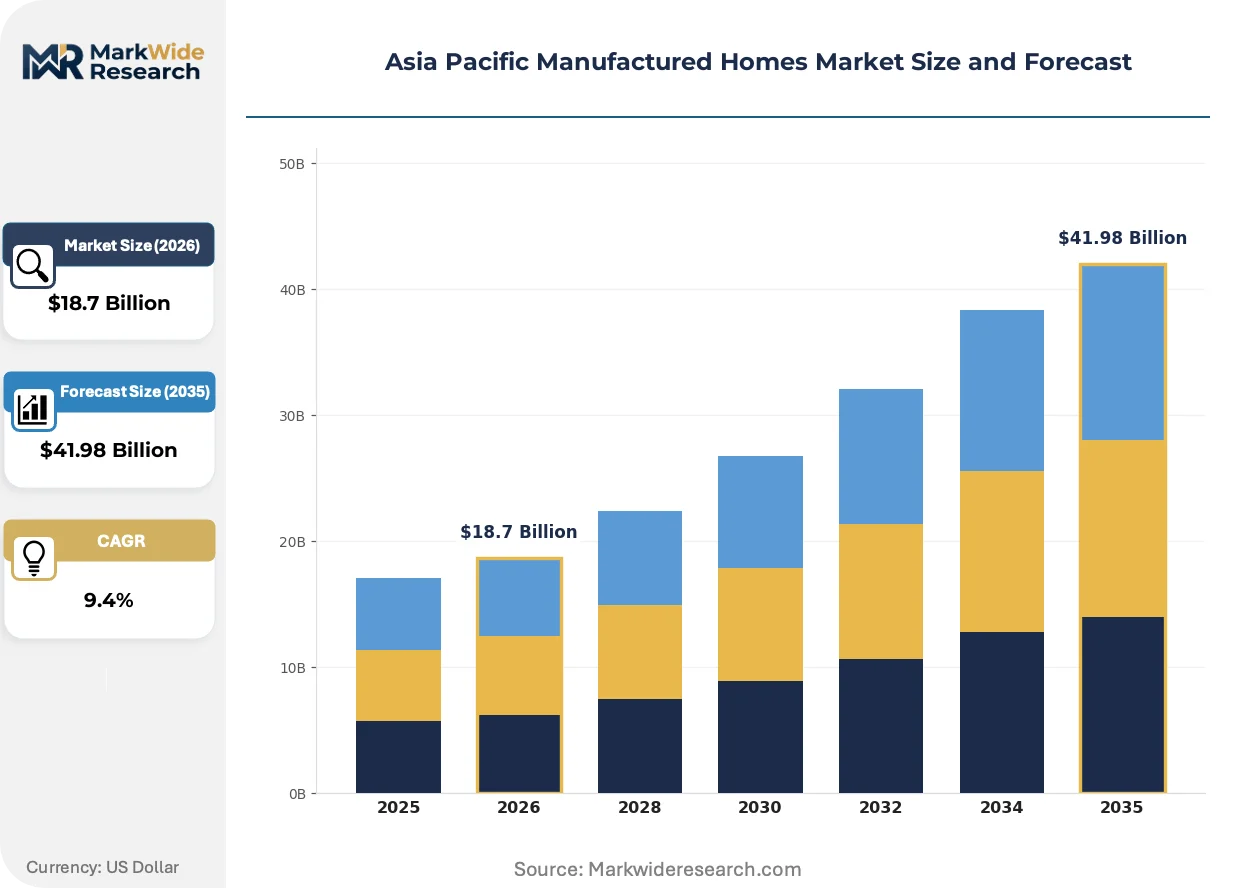
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Section, Multi-Section, Modular, Tiny Homes Application: Residential, Commercial, Vacation, Temporary Housing Construction Method: Traditional Factory-Built, Prefabricated, Hybrid, Stick-Built Customer Type: End-Users, Developers, Investors, Real Estate Agents |
| Companies Covered | Daiwa House Industry, Sekisui House, Panasonic Homes, Toyota Housing Corporation, Ichijo, CIMC Modular Building Systems, Broad Sustainable Building, Lendlease Group, Hickory Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Manufactured Homes Market Strategic Shifts
Digital fabrication and precision-engineered panelization are collapsing traditional trade sequencing in factory-built housing production across the Asia Pacific. Regulatory energy-performance ratchets and buyer preference for low-operating-cost dwellings are accelerating technology adoption curves.
Cross-laminated timber (CLT) wall and floor cassettes are replacing stick-frame construction in premium manufactured housing segments due to superior thermal mass and dimensional stability. Australian developers targeting 7-star NatHERS ratings are specifying CLT envelopes for multi-section modular projects in Canberra and Hobart. This material transition is modularizing supply chain relationships, as CLT fabricators assume panel-engineering responsibilities previously held by on-site framing contractors.
Japan's METI has tightened energy-efficiency benchmarks for prefabricated structures, mandating envelope U-values and airtightness testing that exceed prior voluntary standards. Manufacturers must now submit third-party verified performance data before factory certification renewal, adding documentation burden but filtering lower-performance competitors from premium segments. Australian suppliers exporting to Japan are reconfiguring insulation specifications to meet these thresholds, creating specification divergence between domestic and export product lines.
Developer procurement teams are consolidating vendor relationships around design-build integration capabilities rather than standalone module supply. Lendlease Group and Hickory Group in Australia now require BIM-to-factory data handoffs and installation supervision as standard contract terms, displacing traditional tender-based purchasing. This consolidation is most visible in Sydney's infill residential projects, where speed-to-occupancy drives total project return calculations.
Asia Pacific Manufactured Homes Market Segmentation
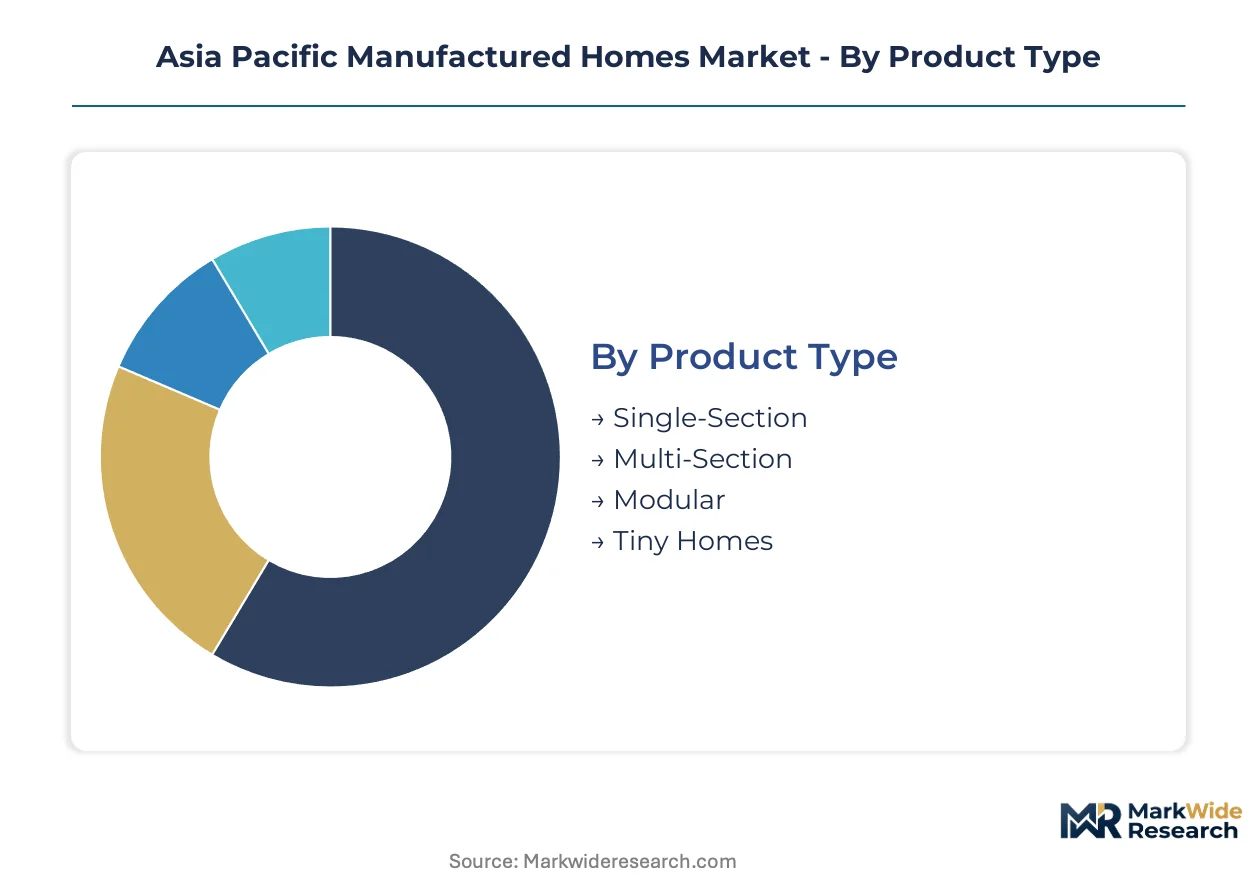
Segmentation in the Asia Pacific manufactured homes market reveals how procurement patterns diverge across buyer sophistication, regulatory exposure, and speed-to-occupancy requirements. Understanding these fault lines enables suppliers to align production configurations with margin-rich demand pools rather than competing on undifferentiated volume.
Product Type:
Buyers differentiate primarily by land constraints, budget ceilings, and permanence intentions rather than square footage alone.
- Single-Section:Compact factory-built units transported as complete modules, typically 14-18 meters in length with steel chassis for crane-offload placement. Demand concentrates in Adelaide's retiree corridors and Perth's outer suburban rings where first-time buyers prioritize entry cost over expansion flexibility. Australia's southeastern planning reforms accelerate approvals for these units in designated estates.
- Multi-Section:Two or more modules joined on-site to create larger footprints, requiring precision crane coordination and certified sealing crews. Victorian and New South Wales developers favor this format for infill projects where land values justify higher per-unit construction spend. The format captures premium margins where speed-to-occupancy drives project returns.
- Modular:Volumetric units built to 80-95% completion in factory conditions, including MEP rough-ins and finish carpentry. Japan's METI energy-efficiency mandates favor these systems for thermal performance verification prior to site delivery.
- Tiny Homes:Sub-37-square-meter transportable dwellings on wheeled or skidded foundations, constrained by zoning fragmentation across Queensland and Western Australia despite consumer interest.
Multi-Section leads volumes today; Modular is gaining share fastest.
Application:
End-use purpose determines specification intensity, from bare-bones temporary deployment to permanent residential finishes warranting 50-year structural guarantees.
- Residential:Permanent or semi-permanent dwellings meeting National Construction Code compliance for full-time occupancy. Australia's southeastern corridor dominates this segment where housing affordability pressures intersect with streamlined development pathways.
- Commercial:Workforce accommodation, retail kiosks, and remote office modules serving mining and infrastructure projects. Western Australia's Pilbara region and Queensland's Bowen Basin generate concentrated demand from resource sector procurement teams.
- Vacation:Secondary dwellings and holiday park installations prioritizing aesthetic customization over thermal performance. Coastal New South Wales and Victoria's Mornington Peninsula show strongest uptake where discretionary household spending supports design premiums.
- Temporary Housing:Rapid-deployment units for disaster relief, construction camps, and event infrastructure. India's affordable housing mission and Australia's emergency response protocols drive procurement through centralized government channels.
Residential anchors revenue concentration; Temporary Housing shows steepest expansion trajectory.
Construction Method:
Technical approach selection reflects trade-off calculations between upfront capital efficiency, site labor availability, and code compliance certainty.
- Traditional Factory-Built:Steel or timber frame assemblies produced in controlled environments with standardized material specifications. Australian volume manufacturers maintain this approach for single-section product lines where design repetition maximizes line efficiency.
- Prefabricated:Panelized and volumetric systems leveraging BIM-to-factory data handoffs, displacing traditional methods as Lendlease Group and Hickory Group mandate design-build integration. This method now dominates Sydney infill residential procurement.
- Hybrid:Combinations of factory-built modules with site-built elements such as concrete ground floors or masonry feature walls. Developers in Canberra and Hobart specify hybrid systems to achieve 7-star NatHERS ratings while managing transport logistics.
- Stick-Built:On-site framing with manufactured components, persisting in Melbourne's outer growth corridors where volume homebuilders leverage project-scale purchasing power and established land banking positions.
Traditional Factory-Built retains volume leadership; Prefabricated is climbing the fastest.
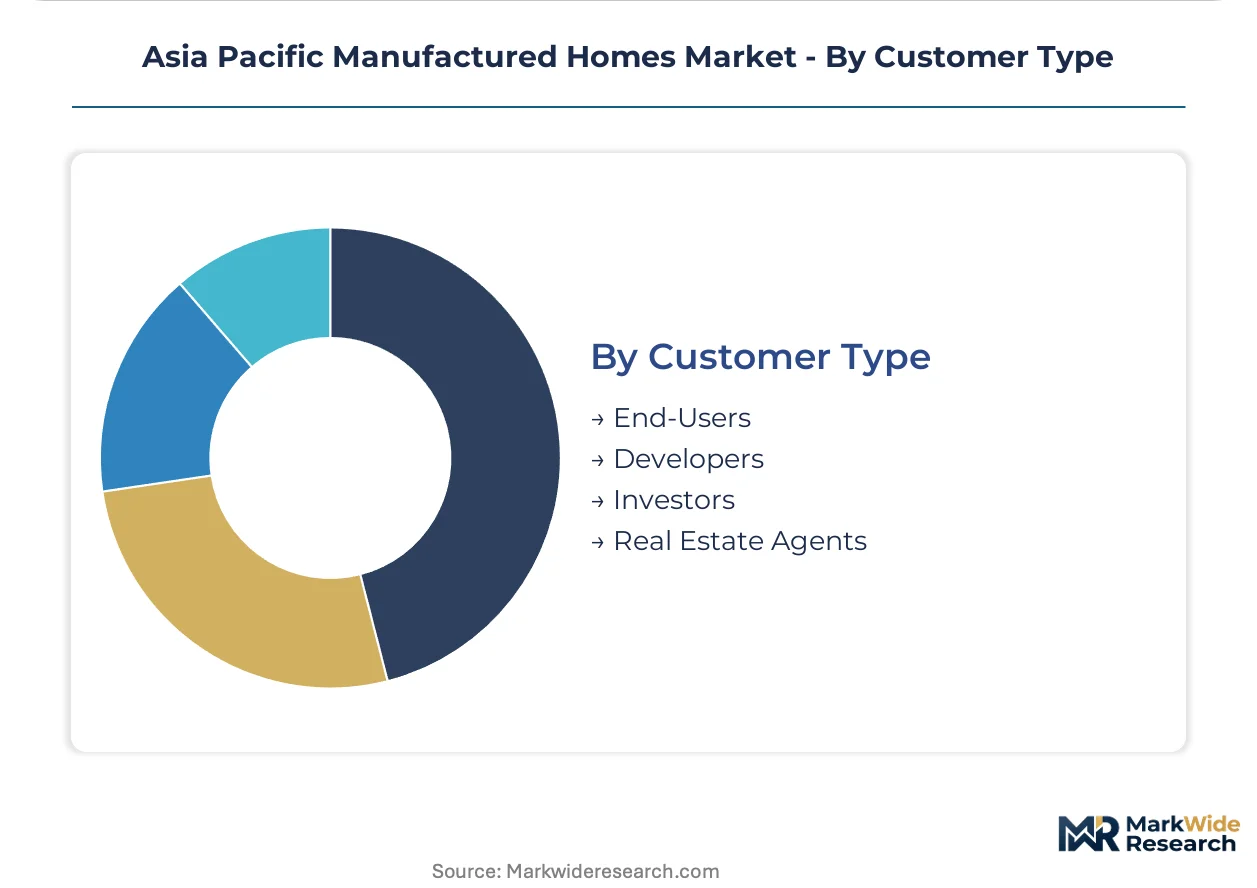
Customer Type:
Procurement sophistication spans individual households navigating zoning complexity to institutional investors underwriting multi-unit development pipelines.
- End-Users:Individual households purchasing single units for owner-occupation, typically retirees downsizing or first-time buyers entering suburban markets. Adelaide and Brisbane show concentrated demand pools where low-maintenance envelopes attract empty-nest households.
- Developers:Residential project sponsors requiring volume procurement, installation supervision, and warranty alignment across multi-unit deployments. Australia's southeastern corridor developer channel consolidates vendor relationships around design-build capabilities.
- Investors:Institutional and private capital deploying manufactured housing as yield-generating assets, particularly in Australia's build-to-rent sector and India's affordable housing mission-linked schemes.
- Real Estate Agents:Intermediaries facilitating land-module-package transactions, most active in Queensland and Western Australia where designated manufactured home estates require specialized placement services.
Developers dominate transaction value today; Investors are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's factory-built housing pipeline moves faster than Japan's certification-heavy premium segment, yet both markets are tightening energy-performance thresholds that reshape procurement patterns across the region.
Australia
First-time buyers and retiree downsizers in Adelaide and Brisbane are accelerating single-section manufactured home orders. The National Construction Code streamlines factory-built compliance pathways, cutting approval timelines to under six months. Victoria and New South Wales dominate volumes, where housing affordability pressures intersect with streamlined development corridors.
Japan
Seismic-resistant framing R&D anchors demand for premium modular systems in earthquake-prone zones. METI enforces tightening energy-efficiency benchmarks that mandate third-party verified envelope performance data. Tokyo and Osaka metropolitan areas concentrate procurement, as manufacturers requalify thermal specifications ahead of traditional replacement cycles.
China
Export-oriented production from Broad Sustainable Building and similar suppliers targets overseas markets with GB-standard compliance. MIIT directives shape material specifications for prefabricated structures. Yangtze River Delta and Pearl River Delta manufacturing clusters dominate automated production capacity serving regional developer channels.
India
Affordable housing mission targets are opening procurement channels for twenty million urban units, with modular systems qualifying for interest subsidy linkage. BIS certification requirements for prefabricated structures are tightening as national programs scale. Maharashtra and Gujarat industrial corridors are emerging as factory-built deployment zones for mission-linked schemes.
Asia Pacific Manufactured Homes Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with design-build integrators consolidating vendor relationships in Australia's developer channel while precision-engineered panel suppliers dominate Japan's premium tier. The market structures around three archetypes: captive supply chain operators, seismic-technology specialists, and scale-driven automated fabricators. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players seek to anchor multi-year developer contracts.
Among Japanese precision-engineered housing specialists, Daiwa House Industry and Sekisui House exemplify the premium modular archetype through their positions in seismic-resistant and energy-efficient system development. CIMC Modular Building Systems represents the scale-driven automated fabrication model, occupying a position among the largest production line operators serving Australia's volume developer channel. These three anchors illustrate how technical specialization and manufacturing scale define competitive positioning across the region's divergent regulatory environments.
| Leading Market Players |
|---|
| Daiwa House Industry |
| Sekisui House |
| Panasonic Homes |
| Toyota Housing Corporation |
| Ichijo |
| CIMC Modular Building Systems |
| Broad Sustainable Building |
| Lendlease Group |
| Hickory Group |
| Others |
Value Chain & Pricing Dynamics
Certified crane operators and module-sealing specialists in Australia's southeastern corridor command wage premiums that compress margin spreads between economy single-section units and premium multi-section modular dwellings. Labor-cost differentials in this concentrated demand zone force manufacturers to stratify pricing across three tiers—entry-level steel-frame products, mid-market CLT-envelope systems, and premium seismic-certified modular units—while METI-driven requalification cycles in Japan add compliance-cost layering to export product lines.
Pricing Analysis
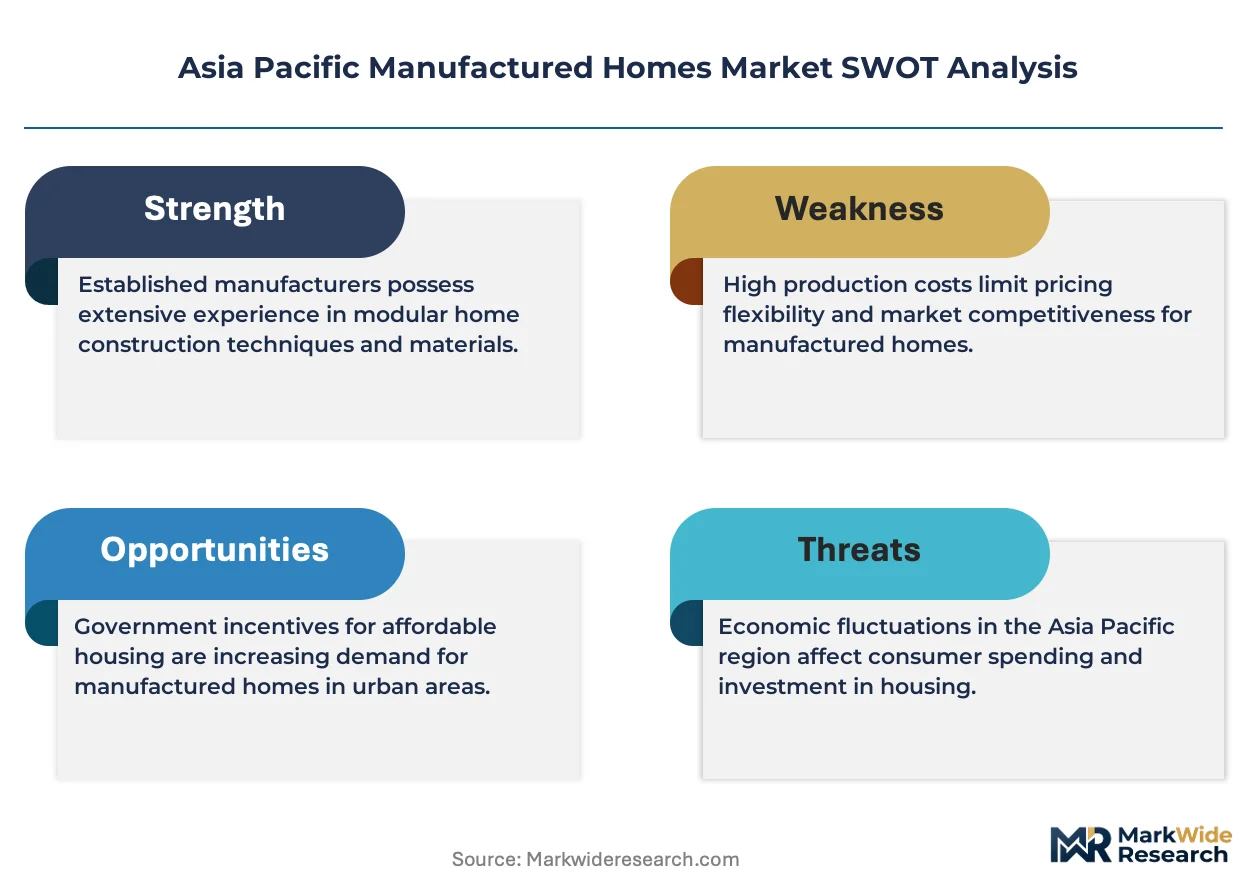
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for galvanized steel frame components across the Asia Pacific. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified seismic modular systems from NatHERS-compliant mid-market CLT units and basic steel-chassis single-section dwellings. Pricing pressure stems from Chinese export quota volatility on galvanized steel coil, compressing margin predictability for Australian frame fabricators. First-time buyers in Adelaide and Perth exhibit highest price sensitivity, while Victorian developers absorbing land-value premiums show lowest elasticity.
Supply Chain Analysis
Freight costs for oversized modular units from Chinese manufacturing clusters to Australian southeastern ports constrain procurement radius for volume developers. Supply concentrates in China, Japan, and Australia, with Yangtze River Delta automated lines feeding export markets and domestic Japanese producers serving METI-regulated premium segments. Raw material dependencies center on cross-laminated timber from European and Australasian sources, galvanized steel coil from Chinese mills, and high-performance insulation meeting Japan's U-value mandates. Single-source vulnerability persists in certified CLT panel supply, with distribution running through design-build integrators like Lendlease Group and Hickory Group displacing traditional tender-based purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific manufactured homes market functions as a stable compounder, with regulatory ratchets on energy efficiency and seismic performance creating sustained replacement demand and premium-tier expansion.
For Market Incumbents: Cement captive supply relationships with CLT fabricators and precision panel suppliers to lock in thermal performance specifications ahead of METI reassessment cycles. Defend against prefabricated construction displacement by embedding BIM-to-factory data capabilities and installation supervision into standard contract terms, as developer procurement teams now mandate design-build integration. For New Entrants and Emerging Players: India's affordable housing mission-linked procurement channels offer the most penetrable entry point, with BIS certification alignment opening interest-subsidy-linked volume contracts. Target Maharashtra and Gujarat industrial corridor deployments for mission-scale projects, and differentiate through subscription-based maintenance bundling that shifts vendor economics toward lifetime value capture rather than one-time margin competition. For Investors and Strategic Acquirers: Australian build-to-rent sector participants are the most active acquirer in this space, underwriting manufactured housing as yield-generating assets. Over a five-to-ten year horizon, prioritize mid-scale manufacturers with captive testing facilities capable of continuous seismic certification documentation. Monitor Japanese METI three-year structural performance reassessment cycles as an inflection indicator for compliance-cost filtering effects on competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CLT Panel Supply | Captive sourcing of cross-laminated timber secures 7-star NatHERS rating compliance for Australian premium modular projects. |
| Seismic Certification Testing Facility Investment | In-house structural performance documentation capacity filters lower-performance competitors from Japan's premium modular segments. |
| Subscription Maintenance Platform Launch | Software-defined energy management attaches recurring revenue streams to manufactured housing sales, shifting economics toward lifetime value. |
| BIS Certification Alignment for Indian Market Entry | Compliance with India's prefabricated structure standards unlocks procurement channels for affordable housing mission-linked volume contracts. |
| Design-Build Integration Capability Buildout | BIM-to-factory data handoffs and installation supervision meet Lendlease Group and Hickory Group contract requirements in Sydney infill residential. |
Study Parameters
Bottom-up residential application modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with modular production plant managers, developer procurement leads, crane operator training coordinators, and METI certification specialists were validated against secondary sources including Australian National Construction Code amendment records, Japanese METI energy-efficiency benchmark disclosures, Indian BIS prefabricated structure certification databases, and customs data on CLT panel imports. Triangulation between demand-side pipeline tracking and supply-side line utilization assessments ensures segmentation integrity.
Historical trendline analysis across product type, construction method, and customer type dimensions established baseline growth patterns. CAGRs were derived from regression analysis of approval velocity, land-value appreciation, and regulatory compliance cost trajectories over the projection horizon. Forecast inputs incorporated seismic code adoption timelines, affordable housing mission procurement schedules, and retiree demographic clustering patterns in suburban Australian corridors.
Inputs from regulatory filing databases and manufacturer certification records were available through the study window; gaps in real-time production line utilization data from Chinese export-oriented facilities introduce uncertainty bands around capacity expansion assumptions. Forecasts reflect documented assumptions about METI reassessment cycle timing and Australian state planning reform implementation pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Canada Residential Real Estate Market
Residential Real Estate Market
Japan Manufactured Homes Market
Residential Real Estate Market
UK Residential Real Estate Market
Residential Real Estate Market
United States Rental Rate for Residential Real Estate Market
Residential Real Estate Market
North America Tiny Homes Market
Residential Real Estate Market
Saudi Arabia Residential Real Estate Market
Residential Real Estate Market
ASEAN Manufactured Homes Market
Residential Real Estate Market
Egypt Manufactured Homes Market
Residential Real Estate Market
United States Manufactured Homes Market
Residential Real Estate Market
Bahrain Senior Living Market
Residential Real Estate Market
Indonesia Real Estate Market
Residential Real Estate Market
Real Estate Market
Residential Real Estate Market
Indonesia Residential Real Estate Market
Residential Real Estate Market
Germany Residential Real Estate Market
Residential Real Estate Market
Spain Residential Real Estate Market
Residential Real Estate Market
Vietnam Residential Real Estate Market