
 Malaysia Residential Real Estate Market | 2026-2036
Malaysia Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Residential Real Estate Market Foresight
Selangor is narrowing its affordable housing deficit through large-scale township projects. UEM Sunrise Berhad leverages its Iskandar Puteri landbank to dominate southern corridor development. Eco World Development Group Berhad differentiates through design-led, master-planned communities. S P Setia Berhad anchors market presence with integrated transit-oriented developments across Greater Kuala Lumpur.
Malaysia residential real estate encompasses completed and under-construction dwelling units traded through primary sales, sub-sales, and auction channels, with construction governed by the Uniform Building By-Laws and quality standards under the Housing Development Act. Terraced houses retain the largest transaction volume nationally, though condominiums capture the fastest price appreciation in urban centers. The mid-range price tier concentrates developer margin pools, while affordable housing segments face structural supply constraints despite government allocation mandates. First-time buyers encounter tightened loan-to-value thresholds, yet investors sustain liquidity in established secondary markets.
Bank Negara Malaysia, the Ministry of Housing and Local Government, and the Construction Industry Development Board collectively enforce lending caps, development licensing, and build-quality certification that shape market entry and product specifications. Compliance with the Housing Development Regulations and strata title frameworks determines project viability timelines and buyer protection standards. Stakeholders must monitor infrastructure allocation decisions under the National Physical Planning Council and assess how Iskandar Malaysia authority zoning revisions redirect demand flows between Johor and Selangor corridors.
Market Dynamics
Bank Negara Malaysia's debt service ratio thresholds are compressing first-time buyer access while institutional capital restructures developer funding models across the Klang Valley corridor.
Growth Catalysts
- Transit-oriented development zoning:Mass Rapid Transit expansion around Greater Kuala Lumpur is unlocking land value premiums and redirecting condominium demand toward rail-adjacent nodes.
- Johor-Singapore Special Economic Zone framework:Cross-border employment mobility agreements are sustaining rental yield premiums for mid-rise residential stock in Iskandar Puteri.
- Industrialized Building System mandates:CIDB certification requirements for modular construction methods are compressing project delivery timelines and reducing skilled labor dependency.
Market Restraints
- Steel and cement input volatility:Global commodity price swings transmit directly into construction cost escalation, squeezing developer margins on fixed-price contracts.
- Strata title issuance delays:State land office backlog and documentation disputes extend buyer financing completion timelines, freezing secondary market liquidity.
- Build-then-sell regulatory transition:Housing Development Act amendments shifting liability to post-completion sales are constraining speculative pre-construction funding.
Strategic Opportunities
- Sarawak digital economy corridor:Data center and renewable energy investments around Kuching are generating expatriate housing demand previously concentrated in Peninsular Malaysia.
- Green Building Index certification:Utility tariff incentives and ESG-linked institutional capital are creating price premiums for low-carbon residential developments.
- Fractional ownership platforms:Fintech-enabled co-investment structures are opening secondary market access to retail capital previously excluded by unit price thresholds.
Industry Challenges
- Quantity surveying and project management talent scarcity:Emigration of experienced professionals to Singapore and Australia is thinning supervisory capacity for complex township developments.
- Legacy system integration with digital land registry:State-level land administration modernization timelines lag behind federal e-conveyancing mandates, creating title verification friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Residential Real Estate Market |
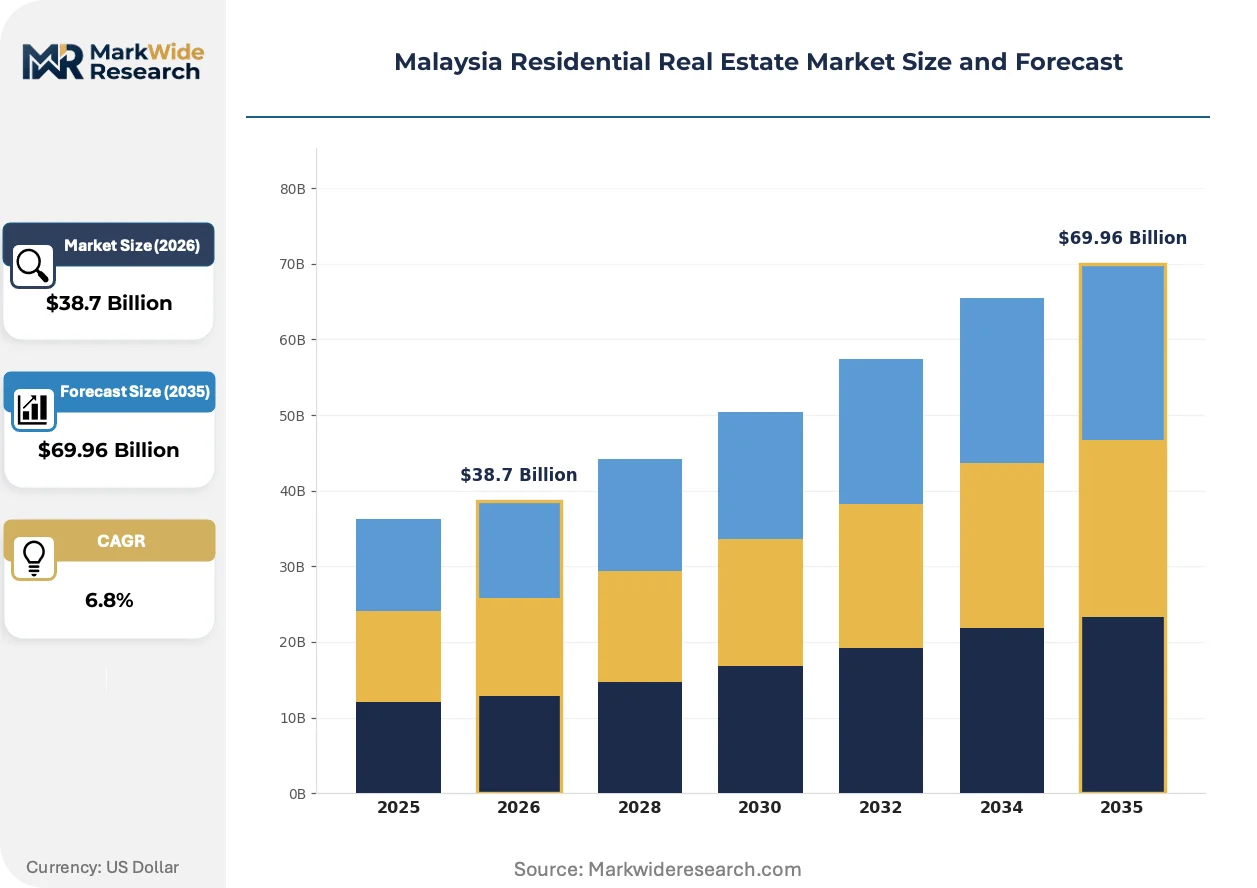
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Condominiums, Terraced Houses, Semi-Detached Houses, Bungalows Price Tier: Luxury, Mid-Range, Affordable, Budget Purchase Type: New Developments, Resale Properties, Foreclosures, Auctions Buyer Segment: First-Time Buyers, Investors, Foreign Nationals, Upsizers |
| Companies Covered | UEM Sunrise Berhad, Eco World Development Group Berhad, IOI Properties Group Berhad, Gamuda Land, Mah Sing Group Berhad, S P Setia Berhad, Sunway Property, Tropicana Corporation Berhad, Sime Darby Property Berhad, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Residential Real Estate Market Shifts & Advancements
Digital transaction infrastructure and sustainability certification are restructuring how residential stock is financed, marketed, and valued across Malaysian urban centers.
Building Information Modeling integrated with prefabrication workflows is collapsing traditional design-bid-build timelines. Developers in Selangor are adopting BIM-to-factory pipelines for terraced house typologies, compressing structural completion from eighteen to ten months. This acceleration is enabling phased launch strategies that match supply release to mortgage approval cycles.
The Ministry of Housing and Local Government's MyHousing 2.0 digital platform is mandating end-to-end online submission for development orders and strata title applications. This regulatory digitization is eliminating physical queue dependencies at state planning departments. Johor and Penang pilot jurisdictions report processing compression, though legacy document conversion bottlenecks persist in Kedah and Kelantan.
Institutional buy-to-rent capital is displacing individual landlord accumulation as the dominant rental stock formation mechanism. Employees Provident Fund and pension fund allocations into purpose-built rental housing are professionalizing property management standards. This shift concentrates most visibly in Cyberjaya and Iskandar Puteri, where single-entity ownership enables integrated amenity provisioning previously fragmented across individual strata owners.
Malaysia Residential Real Estate Market Segmentation
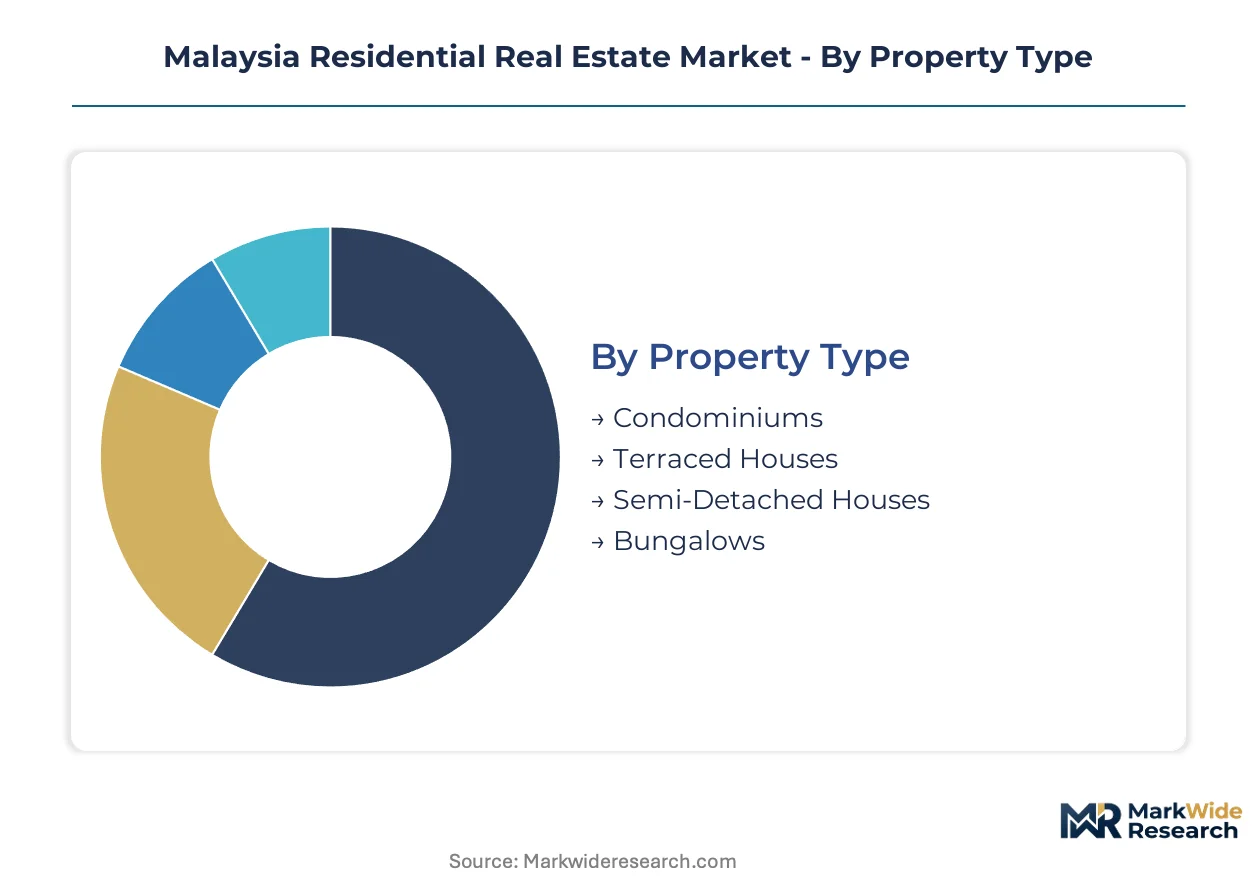
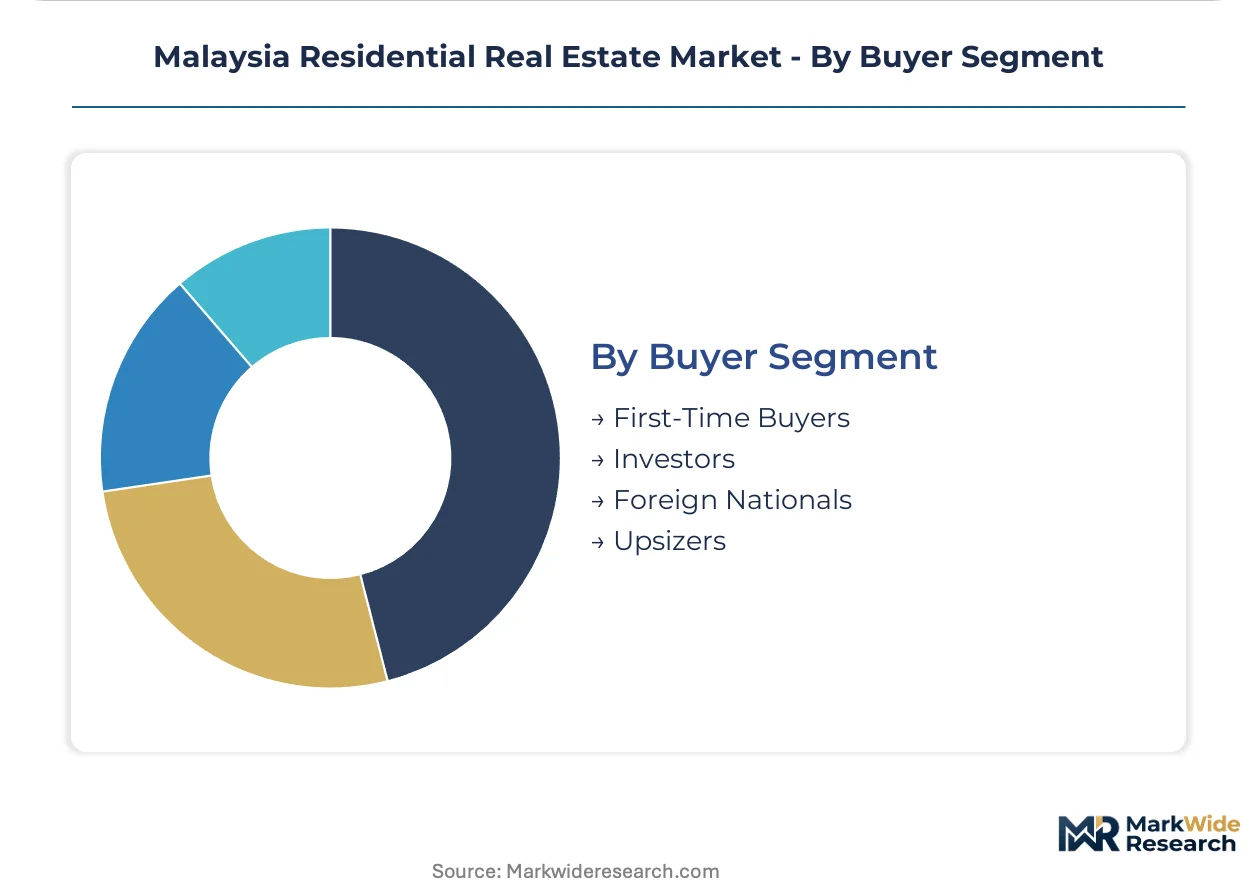
Segmentation in Malaysia's residential real estate market exposes divergent financing requirements, construction specifications, and buyer protection protocols across transaction types. Developers calibrate sales velocity, land use intensity, and warranty structures differently for each segment cluster.
Property Type:
After-sales service intensity varies sharply across structural typologies, with high-rise developments demanding perpetual strata management and landed properties requiring discrete defect liability periods.
- Condominiums:High-density vertical construction with shared facilities and strata title governance. Demand concentrates in Petaling Jaya and Mont Kiara where young professionals prioritize transit accessibility and security services over unit size.
- Terraced Houses:Intermediary-density row housing with individual land titles and limited common property. Volume leadership persists in Selangor's township corridors where extended families value incremental expansion flexibility and direct vehicular access.
- Semi-Detached Houses:Paired dwellings sharing one common wall with larger land footprints than terraced alternatives. UEM Sunrise and S P Setia dominate supply in southern Klang Valley nodes.
- Bungalows:Detached single-family residences on exclusive land parcels commanding premium pricing. Foreign national acquisition restrictions limit liquidity in Damansara Heights and Iskandar Puteri enclaves.
By volume, Terraced Houses leads. By growth pace, Condominiums is expanding most quickly.
Price Tier:
Construction cost structures and land acquisition premiums stratify developer margin profiles across pricing bands.
- Luxury:Developments priced above RM1.5 million with imported finishes, branded fittings, and concierge services. Eco World targets this segment in gated enclaves where foreign buyer eligibility under Malaysia My Second Home sustains transaction velocity.
- Mid-Range:RM500,000 to RM1.5 million bracket capturing the bulk of mortgage-approved demand. Bank Negara Malaysia's debt service ratio thresholds bite hardest here, compressing loan eligibility for dual-income households in Greater Kuala Lumpur.
- Affordable:Government-mandated price ceilings with subsidized land costs and standardized specifications. Selangor's Rumah Selangorku program dominates supply allocation though structural deficits persist against B40 household formation rates.
- Budget:Entry-level stock below RM300,000 concentrated in peripheral states with weaker infrastructure connectivity. Kedah and Kelantan land offices struggle with title issuance velocity for this segment.
Mid-Range captures the deepest buyer pool. Affordable faces the steepest supply-demand gap.
Purchase Type:
Regulatory liability frameworks and financing completion timelines diverge substantially across transaction channels.
- New Developments:Primary sales from licensed housing developers with progressive payment schedules and defect liability periods. Housing Development Act amendments are shifting liability structures toward post-completion sales models.
- Resale Properties:Secondary market transactions between individual owners with immediate possession transfer. Strata title issuance backlogs at Johor and Penang land offices freeze liquidity for condominium resales.
- Foreclosures:Lender-recovered properties sold below market clearing prices through judicial or non-judicial processes. Malaysian Banking Association members dominate supply pipeline.
- Auctions:Court-ordered or voluntary public sales with limited inspection windows and cash-heavy settlement requirements. Investors with unencumbered capital exploit pricing asymmetries in this channel.
New Developments command the highest transaction value per unit. Resale Properties transact at greatest frequency.
Buyer Segment:
Mortgage underwriting standards and stamp duty incentives calibrate accessibility differently across purchaser profiles.
- First-Time Buyers:Households with no prior residential property ownership accessing preferential loan-to-value ratios and duty exemptions. Bank Negara Malaysia's 70% financing cap for third properties does not constrain this cohort.
- Investors:Purchasers acquiring for rental yield or capital appreciation with existing property exposure. Real Property Gains Tax scheduling influences holding period decisions for this segment.
- Foreign Nationals:Non-citizens subject to minimum purchase thresholds and state-level approval requirements. Singaporean buyers concentrate in Johor Bahru corridor seeking value arbitrage against city-state pricing.
- Upsizers:Existing homeowners trading toward larger units or superior locations. Equity extraction from prior appreciation funds downpayment requirements in this segment.
First-Time Buyers anchor transaction volume. Foreign Nationals deliver the steepest price premiums per square foot.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's residential market consumption patterns diverge sharply between the Klang Valley's condominium-dense urban corridors and Johor's landed-property preference among cross-border Singaporean buyers. State-level planning mandates and infrastructure allocation decisions reshape where developer capital deploys.
Selangor
Young professionals in Petaling Jaya and Mont Kiara drive condominium absorption, with Mass Rapid Transit expansion redirecting demand toward rail-adjacent nodes. The state's Rumah Selangorku program mandates affordable housing quotas, though structural deficits persist against B40 household formation rates. UEM Sunrise and S P Setia anchor integrated transit-oriented developments across Greater Kuala Lumpur's southern corridor.
Johor
Singaporean buyers seeking value arbitrage sustain mid-rise residential demand in Iskandar Puteri, with cross-border employment mobility agreements supporting rental yield premiums. The Iskandar Malaysia authority revises zoning frameworks to redirect investment flows between residential and industrial allocations. Eco World leverages its Iskandar Puteri landbank to dominate southern corridor master-planned communities.
Kuala Lumpur
High-density vertical construction concentrates in the city center where strata title governance complexity and perpetual management demands reshape buyer calculations. Bank Negara Malaysia's debt service ratio thresholds compress loan eligibility for dual-income households in the RM500,000 to RM1.5 million bracket. Mah Sing Group and Sunway Property compete for condominium market share in established urban nodes.
Penang
Island land scarcity drives developer margin compression, with state planning departments piloting digital submission platforms under MyHousing 2.0 to accelerate approval timelines. Strata title issuance backlogs freeze secondary market liquidity for condominium resales. IOI Properties and Tropicana Corporation position premium developments in constrained coastal zones.
Sarawak
Data center and renewable energy investments around Kuching generate expatriate housing demand previously concentrated in Peninsular Malaysia. The state's digital economy corridor attracts institutional capital seeking purpose-built rental housing. Sime Darby Property extends its development footprint into East Malaysia's emerging urban centers.
Malaysia Residential Real Estate Market Competitive Landscape
Capability concentration sits with integrated township developers commanding landbank scale; scale advantage sits with diversified conglomerates accessing captive construction materials and financing channels. The market structures around three tiers: state-linked enterprises with legacy land holdings, design-led specialists differentiating through master-planning expertise, and volume-driven builders optimizing standardized typologies. Competitive moves center on phased launch strategies matching supply release to mortgage approval cycles, and backward integration into prefabrication workflows compressing structural completion timelines.
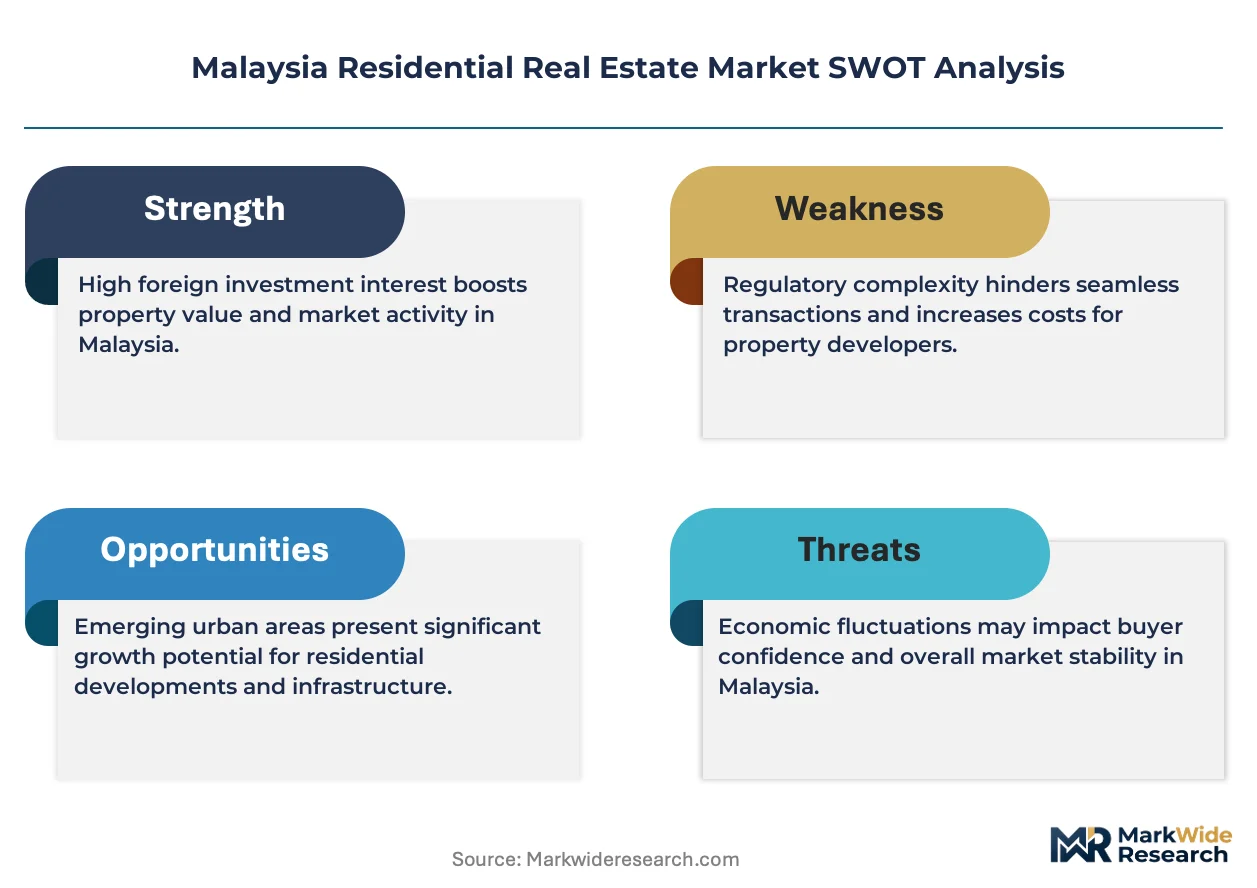
Within the design-led specialist tier, Eco World Development Group Berhad exemplifies aesthetic differentiation through gated enclaves targeting foreign buyer eligibility under Malaysia My Second Home. S P Setia Berhad anchors the integrated transit-oriented development vector, with rail-adjacent land positions in Greater Kuala Lumpur. UEM Sunrise Berhad represents state-linked landbank concentration, leveraging Iskandar Puteri holdings to capture Johor-Singapore Special Economic Zone spillover demand. These three occupy distinct competitive positions without direct overlap in geographic or product positioning.
| Leading Market Players |
|---|
| UEM Sunrise Berhad |
| Eco World Development Group Berhad |
| IOI Properties Group Berhad |
| Gamuda Land |
| Mah Sing Group Berhad |
| S P Setia Berhad |
| Sunway Property |
| Tropicana Corporation Berhad |
| Sime Darby Property Berhad |
| Others |
Supply & Pricing Matrix
Undercapacity in Malaysia's skilled construction labor pool is compressing project delivery timelines and forcing developers to front-load cost contingencies into unit pricing. This utilization squeeze simultaneously elevates subcontractor bargaining power and constrains developers' ability to absorb commodity volatility through margin compression.
Pricing Analysis
Project-based contracting dominates developer-subcontractor relationships, with fixed-price agreements transferring construction risk to builders while progressive payment schedules from buyers fund staged development releases. Price differentiation hinges on Green Building Index certification tier and transit-accessibility proximity, with rail-adjacent units commanding premiums over peripheral locations. Cost compression in the affordable housing tier is intensifying because CIDB modular construction mandates require capital-intensive prefabrication retooling. First-time buyers exhibit highest price sensitivity, while foreign nationals in Johor Bahru demonstrate lowest elasticity due to Singapore value arbitrage.
Supply Chain Analysis
Extended payment terms from major developers are straining mid-tier subcontractor cash flows, with supply-chain finance facilities increasingly intermediating working capital gaps. Raw material sourcing draws from China for steel reinforcement, Indonesia for cement clinker, and Thailand for ceramic finishes. Single-source vulnerability concentrates in specialized M&E components where Malaysian fabrication capacity remains underdeveloped. Distribution runs through developer-direct sales galleries for primary launches, with secondary market liquidity fragmented across individual brokers and auction houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's residential real estate is approaching a platform-economics inflection as MyHousing 2.0 digitization and fractional ownership fintech converge into integrated transaction ecosystems. This interoperability shift will restructure how capital aggregates around residential assets.
For Market Incumbents: Entrench landbank positions in rail-adjacent Klang Valley nodes ahead of Mass Rapid Transit expansion completion, while backward integration into prefabrication workflows secures CIDB compliance without subcontractor dependency. Fintech-enabled fractional ownership platforms threaten direct sales gallery dominance, making captive financing channels the critical defensive lever. For New Entrants and Emerging Players: Establish a beachhead in Sarawak's purpose-built rental housing segment, where data center-driven expatriate demand outpaces incumbent developer presence. The most penetrable white space sits in Kuching's institutional rental stock, with Green Building Index certification as the differentiated go-to-market angle against conventional speculative development. For Investors and Strategic Acquirers: Long-term, this sits as a yield-compression play because institutional buy-to-rent capital is professionalizing management standards and compressing individual landlord returns. Acquisition targets should emphasize township developers with integrated amenity provisioning capabilities. The signal to watch is Employees Provident Fund allocation shifts between direct development and REIT-style rental housing structures.| Strategic Initiative | Industry Significance |
|---|---|
| Transit-Oriented Development Expansion | Mass Rapid Transit proximity unlocks land value premiums in Greater Kuala Lumpur corridor. |
| Modular Construction Certification | CIDB Industrialized Building System compliance compresses delivery timelines and labor dependency. |
| Green Building Index Accreditation | Utility tariff incentives and ESG capital create pricing premiums for low-carbon developments. |
| Fractional Ownership Platform Launch | Fintech-enabled co-investment opens secondary market access to retail capital pools. |
| Purpose-Built Rental Housing Scale-Up | Employees Provident Fund allocations professionalize property management standards in Cyberjaya. |
Research Methodology
Operator-level perspectives from property development executives, construction project directors, mortgage underwriting specialists, and state planning department officials anchored the qualitative base. These primary insights were cross-validated against Bank Negara Malaysia lending guideline circulars, CIDB construction industry statistics, Housing Development Act regulatory filings, and National Property Information Centre transaction records. Bottom-up unit absorption modeling and top-down macroeconomic scenario triangulation produced convergent market sizing.
Scenario-bracketing around Bank Negara Malaysia policy rate trajectories and infrastructure allocation timelines bounded the projection uncertainty. Segmentation dimensions modeled encompass property type, price tier, purchase channel, and buyer archetype across the analysis window. CAGRs were derived from trend extrapolation moderated by regulatory intervention likelihood and construction cost elasticity estimates. Forecast inputs incorporated Iskandar Malaysia zoning revision impacts and MyHousing 2.0 digitization rollout velocity.
Sensitivities concentrate around debt service ratio threshold adjustments, steel and cement commodity price spikes, and strata title issuance backlog resolution timelines. Forecasts reflect documented assumptions about cross-border employment mobility and institutional capital allocation preferences. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Spain Residential Real Estate Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
Bahrain Senior Living Market
Residential Real Estate Market
Singapore Real Estate Market
Residential Real Estate Market
United States Rental Rate for Residential Real Estate Market
Residential Real Estate Market
United States Manufactured Homes Market
Residential Real Estate Market
UK Residential Real Estate Market
Residential Real Estate Market
India Residential Construction Market
Residential Real Estate Market
France Residential Real Estate Market
Residential Real Estate Market
Myanmar Residential Real Estate Market
Residential Real Estate Market
Spain Manufactured Homes Market
Residential Real Estate Market
France Manufactured Homes Market
Residential Real Estate Market
Malaysia Real Estate Market
Residential Real Estate Market
Indonesia Real Estate Market
Residential Real Estate Market
Qatar Residential Real Estate Market
Residential Real Estate Market
Egypt Residential Real Estate Market