
 Saudi Arabia Residential Real Estate Market | 2026-2036
Saudi Arabia Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Residential Real Estate Market Analytics
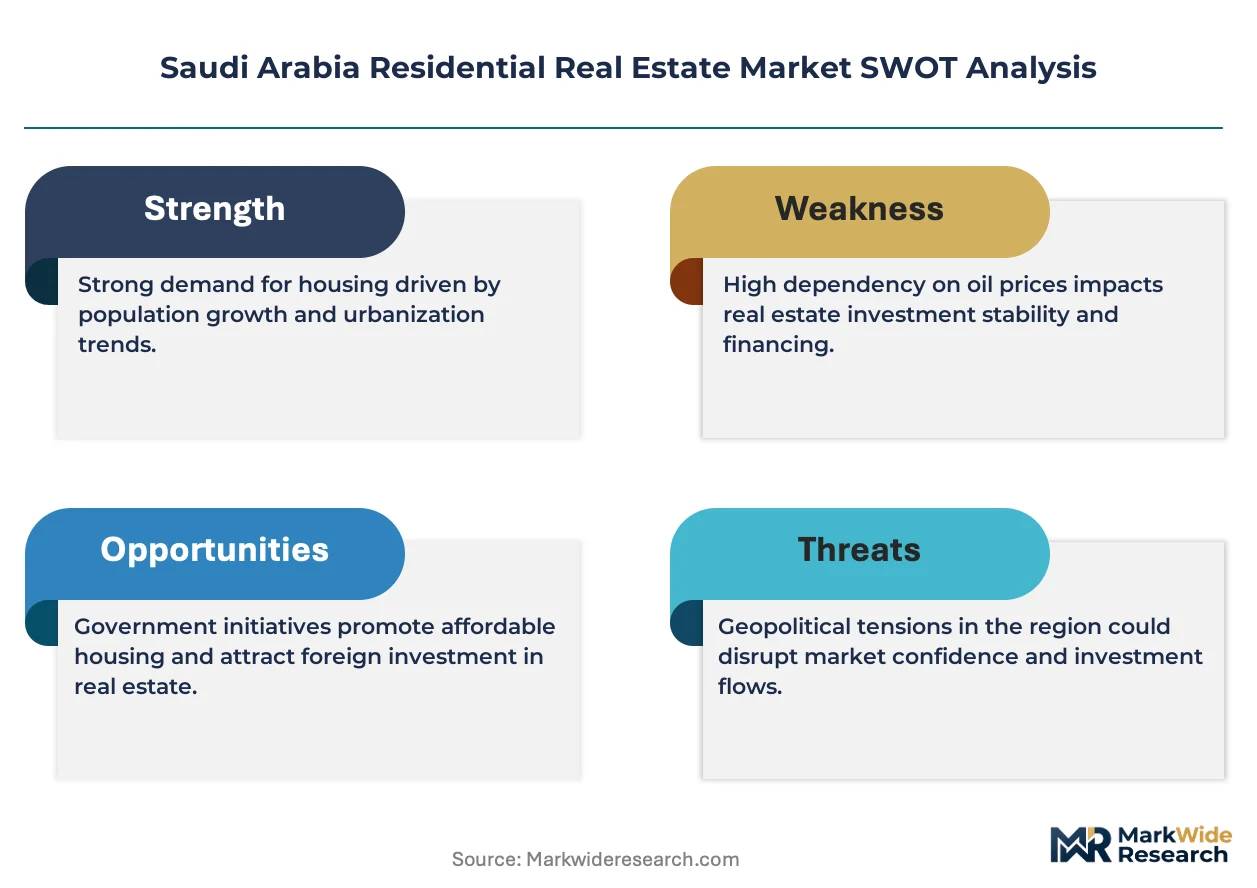
Young professional households and small investor landlords is rebalancing the buyer composition across Riyadh and Jeddah. Dar Al Arkan Real Estate Development Company anchors large-scale community development in secondary cities, while ROSHN Group dominates government-backed affordable housing supply through its integrated master-planning model. Kingdom Holding Company leverages its mixed-use tower portfolio to sustain premium positioning in central Riyadh.
Saudi Arabia residential real estate encompasses purpose-built housing units—apartments, villas, townhouses, and duplexes—constructed with reinforced concrete frames, thermal insulation meeting SASO energy efficiency grades, and smart home infrastructure for climate control and security management. These properties serve as primary dwellings for Saudi nationals and expatriates, plus income-generating assets for domestic investors seeking rental yield in a market with limited institutional alternatives. Apartments command the largest transaction volume in Riyadh and Jeddah due to land scarcity and mortgage accessibility for first-time buyers under the Sakani program. Villas retain premium margin pools in gated compounds near giga-project employment hubs, while townhouses capture fastest-growing demand from young families priced out of villa ownership but seeking more space than apartments provide.
The Saudi Building Code administered by the National Committee for Building Code enforces seismic resilience and fire safety standards that elevate construction costs but reduce long-term liability for developers. SASO's energy labeling requirements and the Saudi Green Building Forum's voluntary certifications are steering buyer preference toward thermally efficient units with lower utility burdens. The Real Estate General Authority's escrow regulations protect off-plan purchasers, tightening developer liquidity management and favoring capitalized players. Stakeholders must monitor how mortgage subsidy adjustments and giga-project delivery timelines reshape absorption rates in oversupplied sub-markets.
Market Dynamics
The Saudi Building Code and SASO energy efficiency mandates are compressing developer margins while redirecting capital toward thermally efficient construction methods and smart infrastructure integration.
Growth Catalysts
- Sakani mortgage subsidies:First-time Saudi buyers access preferential financing rates that compress apartment affordability gaps in Riyadh's northern corridor.
- Vision 2030 giga-projects:NEOM, Red Sea Global, and Qiddiya channel expatriate professional flows into Jeddah waterfront and Riyadh secondary nodes.
- Saudi Green Building Forum certifications:Voluntary efficiency ratings steer buyer preference toward lower-utility-burden units, accelerating thermal insulation upgrades.
Market Restraints
- Reinforced concrete and steel input volatility:Global commodity swings compress developer margins on mid-range apartment deliveries.
- Escrow liquidity requirements:Real Estate General Authority regulations tie developer working capital to construction milestones, favoring capitalized players.
- Land scarcity in prime corridors:Riyadh's northern zone and Jeddah waterfront face supply inelasticity that prices out young professional households.
Strategic Opportunities
- Dammam and Khobar corridor:Eastern Province cities absorb spillover demand from Riyadh saturation with lower entry price points.
- Townhouse hybrid formats:Young families priced out of villa compounds seek space-efficient alternatives between apartment and single-family typologies.
- Smart home infrastructure convergence:Climate control and security management systems merge with SASO energy labeling to create premium differentiation.
Industry Challenges
- Seismic engineering specialization:Saudi Building Code enforcement creates contractor capability gaps in secondary cities.
- Off-plan sales compliance timelines:Escrow documentation and milestone verification extend project cash conversion cycles.
- Utility integration complexity:Smart infrastructure deployment requires coordination between developers, SASO certifiers, and distribution utilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Residential Real Estate Market |
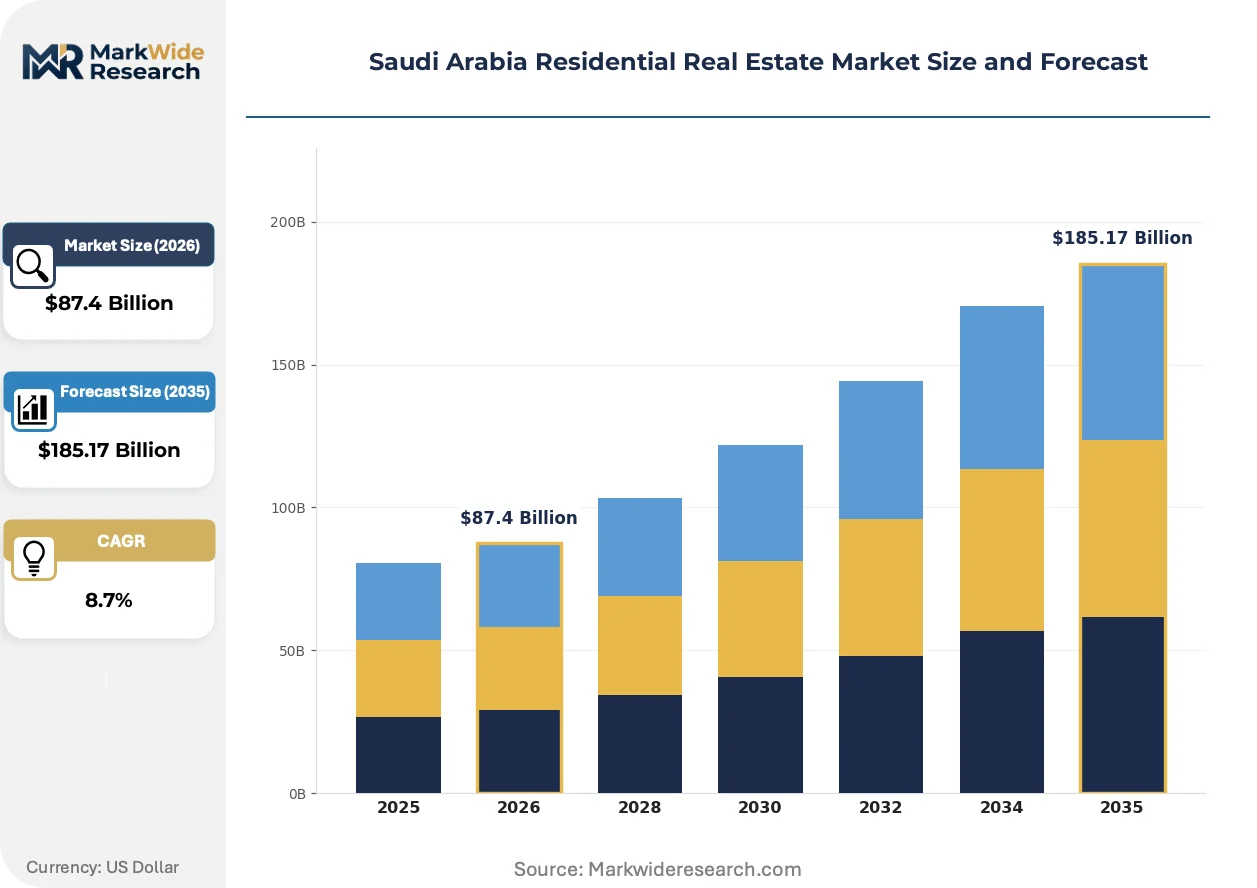
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $185.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Apartments, Villas, Townhouses, Duplexes Price Tier: Luxury, Mid-range, Affordable, Budget Buyer Type: First-time Buyers, Investors, Renters, Retirees Sales Channel: Online Platforms, Real Estate Agents, Direct Sales, Auctions |
| Companies Covered | Kingdom Holding Company, Taiba Investments Co., Jabal Omar Development Company, Abdul Latif Jameel, Arriyadh Development Co., Dar Al Arkan Real Estate Development Company, Al Saedan Real Estate Co., Jenan Real Estate Company, ROSHN Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Residential Real Estate Market Evolving Landscape
Construction technology and regulatory efficiency mandates are compressing traditional development timelines while elevating buyer expectations for integrated living environments.
Building information modeling is unifying architectural design, structural engineering, and MEP systems into single-workflow platforms. Mid-scale developers in Riyadh adopt these tools to compress pre-construction phases and reduce change-order costs. The technology is unifying previously siloed disciplines, enabling faster permit approvals under National Committee for Building Code review.
SASO's mandatory energy labeling requirements now apply to all new residential units, forcing insulation specification upgrades and HVAC efficiency tiers. Developers face compressed design cycles to meet grade thresholds before marketing launches. Riyadh's northern corridor projects respond by specifying double-glazed facades and variable refrigerant flow systems to secure premium positioning.
Young professional households now prioritize walkability and transit proximity over compound amenities, reversing previous gated-community preferences. This rotation pressures developers to acquire infill parcels near Riyadh Metro stations and Jeddah Corniche transit nodes. The shift is most visible in absorption rates for mid-range apartments within 500 meters of confirmed station locations.
Saudi Arabia Residential Real Estate Market Segmentation
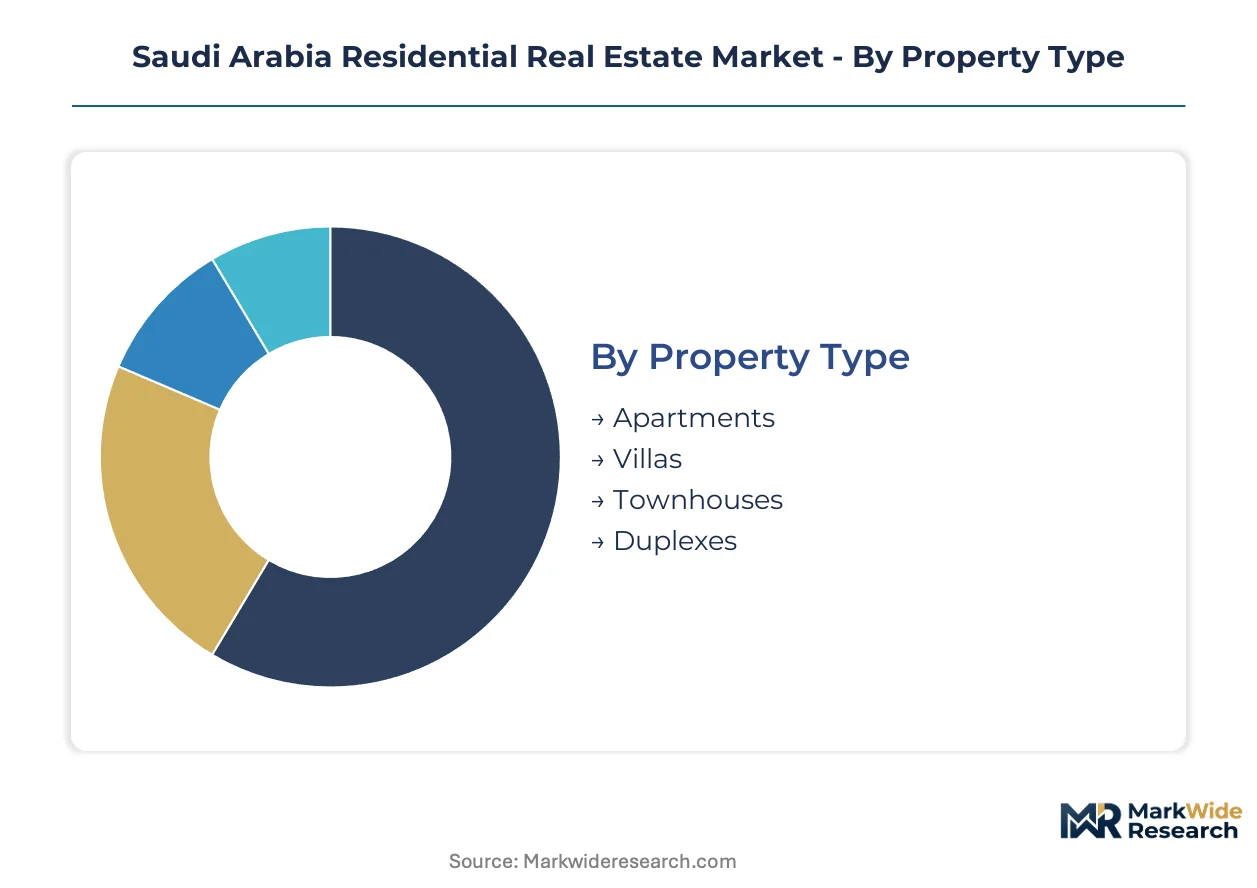
Segmentation reveals how Vision 2030 housing programs and regulatory mandates are concentrating demand across distinct buyer profiles and property configurations. Understanding these divides exposes where capital flows, construction codes, and financing subsidies create competitive advantage.
Property Type:
Upgrade cycles in Saudi residential real estate follow household lifecycle transitions and mortgage accessibility shifts under Sakani program revisions.
- Apartments:Reinforced concrete frame structures with SASO energy efficiency compliance dominate Riyadh's northern corridor and Jeddah waterfront. Young professional expatriates absorb mid-range units near giga-project employment nodes where land scarcity prevents villa development.
- Villas:Gated compound configurations with seismic resilience certification per Saudi Building Code retain premium positioning near NEOM and Qiddiya recruitment zones. Saudi national families prioritize these for multi-generational occupancy and rental yield security.
- Townhouses:Hybrid typologies bridge apartment density with villa space allocation. Young families priced out of compound ownership drive fastest absorption in Riyadh secondary nodes.
- Duplexes:Split-level configurations serve investor landlords seeking dual-tenancy income streams in Jeddah's redevelopment districts.
Apartments sit at the top of the volume ranking, with townhouses climbing the fastest.
Price Tier:
Cost stratification reflects construction material grade, location proximity to employment corridors, and eligibility for government subsidy programs.
- Luxury:Smart home infrastructure with variable refrigerant flow climate systems and double-glazed facades commands positioning in central Riyadh towers and Jeddah Corniche frontage. Kingdom Holding Company's mixed-use portfolio anchors this tier.
- Mid-range:Thermal insulation meeting SASO Grade B thresholds with basic security management systems captures Sakani-qualified first-time buyers. ROSHN Group's master-planned communities dominate supply here.
- Affordable:Escrow-compliant construction with reinforced concrete frames and standard HVAC efficiency serves Eastern Province spillover demand from Riyadh saturation.
- Budget:Minimal specification units in secondary cities face absorption risk from mortgage rate sensitivity and giga-project construction labor migration.
Mid-range units command the deepest buyer pool, though affordable inventory is expanding most quickly in Dammam and Khobar.
Buyer Type:
Customer composition rotates with expatriate professional inflows and domestic household formation rates shifting under economic diversification.
- First-time Buyers:Saudi nationals leveraging Sakani preferential financing concentrate in Riyadh's northern corridor apartments and ROSHN-planned communities.
- Investors:Small landlord portfolios seek rental yield in villa compounds near giga-project hubs where institutional alternatives remain limited.
- Renters:Expatriate professionals on fixed-term contracts drive absorption in Jeddah waterfront mid-range apartments with transit proximity.
- Retirees:Downsizing households transition from villa compounds to lower-maintenance townhouses in secondary cities.
First-time buyers represent the largest transaction volume base, with investors gaining share fastest in employment corridor proximities.
Sales Channel:
Channel mix evolution tracks digital platform maturity and Real Estate General Authority escrow documentation requirements extending transaction complexity.
- Online Platforms:Digital listing aggregators with virtual tour capabilities and mortgage pre-qualification integration compress search cycles for Riyadh and Jeddah apartment seekers.
- Real Estate Agents:Licensed brokers manage off-plan sales compliance, escrow milestone verification, and Saudi Building Code disclosure requirements for villa and townhouse transactions.
- Direct Sales:Developer-managed channels for ROSHN and Dar Al Arkan large-scale community projects bypass intermediary fees while controlling buyer qualification.
- Auctions:Distressed asset disposition and probate property clearing occur through court-supervised processes with limited retail buyer participation.
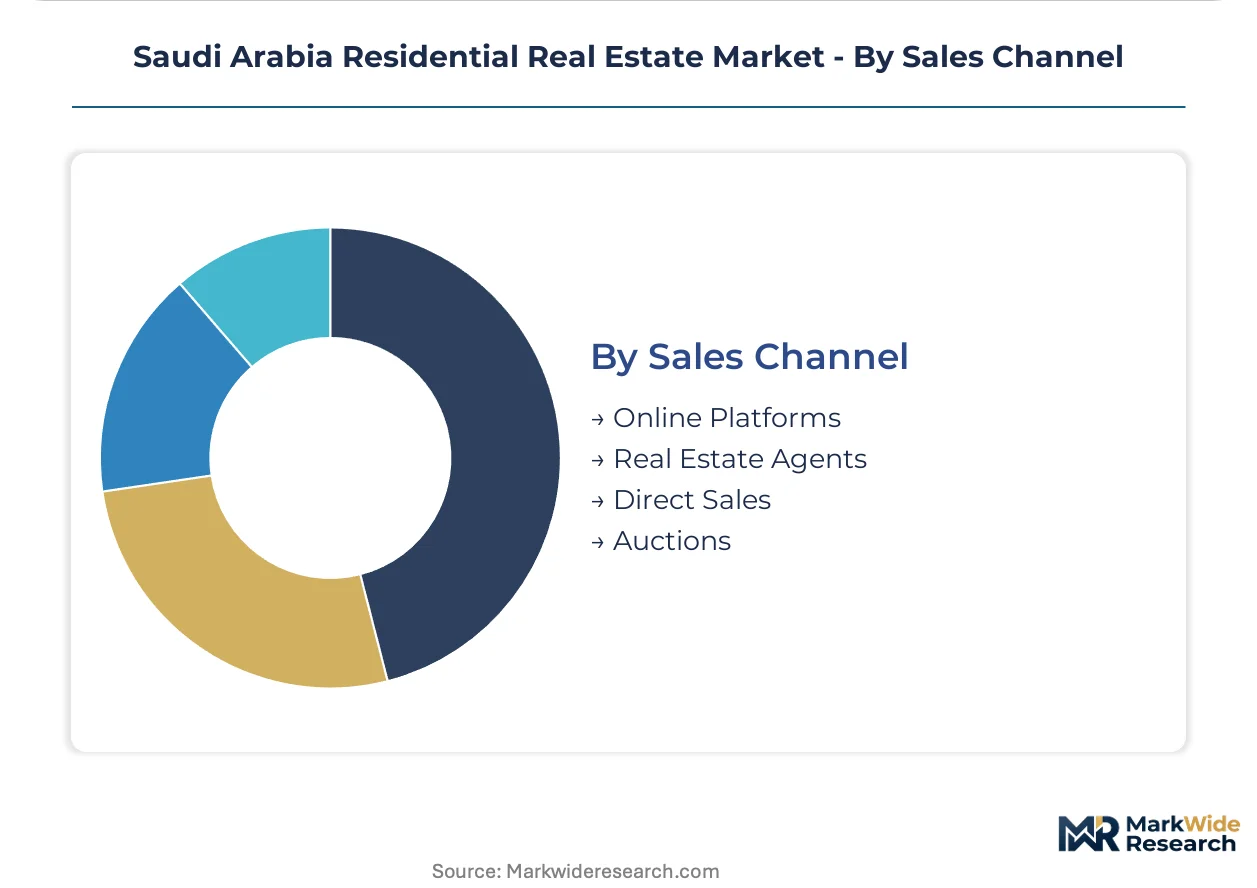
Real estate agents handle the highest transaction value flow, with online platforms capturing volume growth fastest among young professional segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between Riyadh's stringent building codes and secondary cities' compliance cost gaps is redirecting mid-range development capital toward the Eastern Province and peripheral corridors. Developers exploit these cost-of-compliance differentials while maintaining SASO energy efficiency thresholds.
Riyadh
Expatriate professionals and Sakani-qualified first-time buyers absorb mid-range apartments in the northern corridor. The Saudi Building Code enforcement through the National Committee for Building Code elevates seismic resilience standards. The King Abdullah Financial District and Diriyah Gate clusters concentrate premium villa compounds serving giga-project employment hubs.
Eastern Province
Dammam and Khobar capture spillover demand from Riyadh saturation with lower entry price points attracting young professional households. The Real Estate General Authority's escrow regulations apply uniformly but land costs compress compliance burdens. The Dammam metropolitan corridor anchors affordable inventory expansion with reinforced concrete frame construction.
Western Region
Jeddah's waterfront redevelopment zone channels expatriate absorption into transit-proximate apartments under Red Sea Global recruitment flows. SASO energy labeling requirements steer specification upgrades in Corniche-frontage towers. The Jeddah Economic City cluster concentrates mixed-use development with smart home infrastructure integration.
NEOM Northwest
The linear city project and Red Sea Global tourism infrastructure channel construction labor migration and temporary housing demand. Vision 2030 giga-project timelines reshape absorption patterns in oversupplied sub-markets. The Oxagon and Sindalah nodes concentrate modular residential deployment for project workforce accommodation.
Saudi Arabia Residential Real Estate Market Competitive Landscape
Portfolio diversification dominates the current landscape as developers rebalance exposure across price tiers and geographic corridors. The market structures around capitalized national champions with government backing, mid-scale regional specialists, and institutional investors seeking yield in compound assets. Three archetypes prevail: integrated master-planners, mixed-use tower developers, and community-scale specialists. M&A activity and strategic land banking constitute the primary competitive moves as players secure pipeline visibility through 2035.
Within the integrated master-planner tier, Dar Al Arkan Real Estate Development Company and ROSHN Group exemplify divergent capital structures serving distinct buyer pools. Kingdom Holding Company occupies a position on the premium-mixed-use vector with central Riyadh tower exposure. These entities represent how government-backed affordability mandates and private capital deployment models coexist within the same regulatory framework.
| Leading Market Players |
|---|
| Kingdom Holding Company |
| Taiba Investments Co. |
| Jabal Omar Development Company |
| Abdul Latif Jameel |
| Arriyadh Development Co. |
| Dar Al Arkan Real Estate Development Company |
| Al Saedan Real Estate Co. |
| Jenan Real Estate Company |
| ROSHN Group |
| Others |
Value Network & Pricing Analysis
Sovereign-backed master-planners and family-owned regional developers anchor supply concentration across Riyadh and Jeddah corridors, translating land-bank scale into pricing discipline that resists margin erosion from commodity volatility. Their capital depth absorbs Saudi Building Code compliance costs and escrow liquidity requirements that squeeze smaller competitors, reinforcing tiered pricing power across mid-range and affordable segments.
Pricing Analysis
Developer-direct sales channels bypass intermediary markups while real estate agent-managed transactions carry compliance-documentation premiums for off-plan villa and townhouse sales. Pricing stratifies across premium smart-home-integrated towers, Sakani-qualified mid-range apartments with SASO Grade B thermal efficiency, and affordable reinforced-concrete inventory in Eastern Province spillover markets. Cost compression in budget-tier units intensifies because reinforced concrete and steel input volatility compresses margins on standardized construction. First-time buyers under Sakani programs exhibit highest price sensitivity; luxury investors in central Riyadh towers demonstrate lowest elasticity.
Supply Chain Analysis
Material returns and refurbishment flows remain minimal in Saudi residential construction, though modular component reuse is emerging in NEOM workforce housing deployments. Supply draws from China for HVAC and smart home systems, Saudi Arabia for cement and reinforced concrete, and Turkey for steel structural components. Raw material dependencies center on Portland cement clinker, hot-rolled steel rebar, and low-e glazing units. Single-source vulnerability concentrates in Chinese-manufactured variable refrigerant flow climate systems. Distribution runs through developer-integrated procurement teams for large-scale community projects and specialized MEP contractors for tower developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Eastern Province development corridors present geographic-arbitrage opportunities against Riyadh's land scarcity and stringent National Committee for Building Code enforcement, with Dammam and Khobar offering 30-40% lower compliance-adjusted entry costs for comparable unit specifications.
For Market Incumbents: Deepen land-bank consolidation in secondary cities before regulatory arbitrage windows close. Acquire distressed mid-scale developers facing escrow liquidity constraints to secure pipeline visibility. Vertical integration into in-house MEP installation capabilities defends margins against contractor scarcity in seismic-engineering specializations. For New Entrants and Emerging Players: Young professional households priced out of Riyadh's northern corridor represent the most penetrable buyer archetype. Target Dammam and Khobar townhouse developments with space-efficient hybrid formats between apartment density and villa space allocation. Deploy direct-to-buyer digital sales channels with Sakani pre-qualification integration to bypass established agent networks. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional specialists with Eastern Province land positions and incomplete escrow-compliant pipelines. Long-term viability centers on developers with government-backed affordability mandates and integrated master-planning capabilities. Monitor giga-project construction labor migration patterns as inflection indicators for temporary housing demand absorption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Land-Bank Expansion in Eastern Province | Captures Riyadh spillover demand at lower compliance-adjusted entry costs. |
| Smart Home Infrastructure Integration | Differentiates premium positioning under SASO energy labeling mandates. |
| Escrow-Compliant Pipeline Completion | Secures buyer protection credentials required by Real Estate General Authority regulations. |
| Sakani Program Partnership | Unlocks preferential financing access for first-time Saudi buyer segments. |
| Seismic Engineering Capability Buildout | Addresses Saudi Building Code enforcement gaps in secondary city contractor markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with real estate development executives, Saudi Building Code compliance officers, mortgage program administrators at Sakani, escrow account managers, and MEP systems procurement leads with secondary validation. Secondary sources included Real Estate General Authority regulatory filings, SASO energy efficiency certification databases, National Committee for Building Code permit records, and customs data on construction material imports. Bottom-up unit absorption tracking and top-down market sizing triangulated volume estimates across property type and price tier segments.
Historical reference periods anchored growth trajectory assumptions across the projection horizon, with comparable-period analysis informing base-year calibration. Segmentation dimensions modeled encompassed property type, price tier, buyer archetype, and sales channel, supplemented by geographic corridor-specific regulatory enforcement intensity. CAGRs derived from trend extrapolation adjusted for policy intervention effects, incorporating giga-project delivery timelines and mortgage subsidy revision schedules as industry-specific forecast inputs.
Underlying measurement precision varies by segment; mid-range apartment absorption in Riyadh and Jeddah carries tighter precision than budget-tier inventory in secondary cities given data availability disparities. Forecasts reflect assumptions on expatriate professional inflow rates and construction milestone achievement patterns. Periodic stress-testing of base assumptions is recommended against mortgage rate sensitivity and commodity price volatility scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Germany Manufactured Homes Market
Residential Real Estate Market
France Manufactured Homes Market
Residential Real Estate Market
UK Real Estate Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
Global Manufactured Housing Market
Residential Real Estate Market
Malaysia Real Estate Market
Residential Real Estate Market
Spain Manufactured Homes Market
Residential Real Estate Market
Myanmar Residential Real Estate Market
Residential Real Estate Market
France Luxury Residential Real Estate Market
Residential Real Estate Market
India Manufactured Homes Market
Residential Real Estate Market
North America Tiny Homes Market
Residential Real Estate Market
Turkey Residential Real Estate Market
Residential Real Estate Market
Real Estate Market
Residential Real Estate Market
Mexico Residential Real Estate Market
Residential Real Estate Market
North America Real Estate Brokerage Market
Residential Real Estate Market
Armenia Real Estate Market