
 Multi-Item Patient Monitor Market | 2026-2036
Multi-Item Patient Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Item Patient Monitor Market Foresight
The EU Medical Device Regulation (MDR) is recalibrating design and post-market surveillance obligations for patient monitoring equipment sold across Europe. GE Healthcare leverages its deep installed base in acute care settings to sustain service revenue streams alongside hardware placements. Koninklijke Philips N.V. anchors its competitive stance through integrated informatics platforms that bridge bedside devices with enterprise data layers. Medtronic differentiates via specialized cardiac monitoring modules that occupy premium positions in electrophysiology labs.
A multi-item patient monitor simultaneously tracks multiple vital signs—electrocardiography, pulse oximetry, non-invasive blood pressure, respiration rate, and temperature—through modular parameter acquisition systems with sampling frequencies typically ranging from 125 Hz to 1000 Hz for waveform analysis. These devices serve as central nervous systems in acute care environments, enabling clinicians to detect physiological deterioration before critical events escalate. Portable monitors are gaining share fastest among product types as health systems prioritize patient mobility and step-down unit flexibility. Bluetooth-enabled wireless connectivity is displacing wired networks in retrofit installations, though cloud-based solutions remain concentrated in greenfield hospital constructions where IT infrastructure modernization budgets align with cybersecurity frameworks.
The FDA enforces premarket notification requirements under 21 CFR 870 for multi-parameter monitors, while the EU MDR mandates clinical evidence and post-market clinical follow-up for Class IIa and IIb devices. Japan's PMDA imposes additional electromagnetic compatibility testing that shapes product development cycles for manufacturers seeking access. Stakeholders must monitor evolving cybersecurity guidance from regulators, as networked monitoring architectures expand attack surfaces that demand continuous firmware validation and threat remediation protocols.
Market Dynamics
Bluetooth-enabled wireless connectivity is electrifying retrofit installations across acute care networks as hospitals dismantle legacy wired infrastructure to enable patient mobility and step-down unit flexibility. This shift compresses hardware refresh cycles and forces cybersecurity validation protocols to evolve in parallel with physical deployment.
Growth Catalysts
- EU MDR clinical evidence mandates:Post-market surveillance requirements for Class IIa and IIb devices are elevating quality thresholds that filter out marginal suppliers and concentrate procurement among validated manufacturers.
- Step-down unit expansion:Health systems are reconfiguring intermediate care spaces to handle higher-acuity patients, generating demand for portable monitoring platforms that travel with patients.
- Cloud-native greenfield construction:New hospital builds with modernized IT infrastructure budgets are embedding centralized patient data architectures from foundation to commissioning.
Market Restraints
- Semiconductor supply concentration:Discrete analog-to-digital converters and specialized signal processors face single-source dependencies from East Asian foundries.
- FDA 21 CFR 870 premarket notification:Electromagnetic compatibility validation and cybersecurity documentation extend product development timelines by 14-22 months for novel architectures.
- Disposable electrode cost volatility:Silver/silver chloride sensor materials fluctuate with precious metals markets, compressing margin on consumable revenue streams.
Strategic Opportunities
- Home-based acute monitoring:Hospital-at-home reimbursement expansion creates demand for FDA-cleared ambulatory multi-parameter systems with cellular backhaul.
- AI-augmented early warning scoring:Integration of predictive algorithms with waveform analysis enables deterioration detection 4-6 hours before conventional threshold alerts.
- Modular retrofit kits:Wireless parameter acquisition modules that clip onto existing bedside frames unlock upgrade revenue without full device replacement.
Industry Challenges
- Firmware validation talent scarcity:Continuous threat remediation protocols require embedded security engineers with medical device regulatory experience, a skill intersection in short supply.
- Legacy network integration friction:BACnet and proprietary nurse call systems in aging facilities resist seamless interoperability with IP-native monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Item Patient Monitor Market |
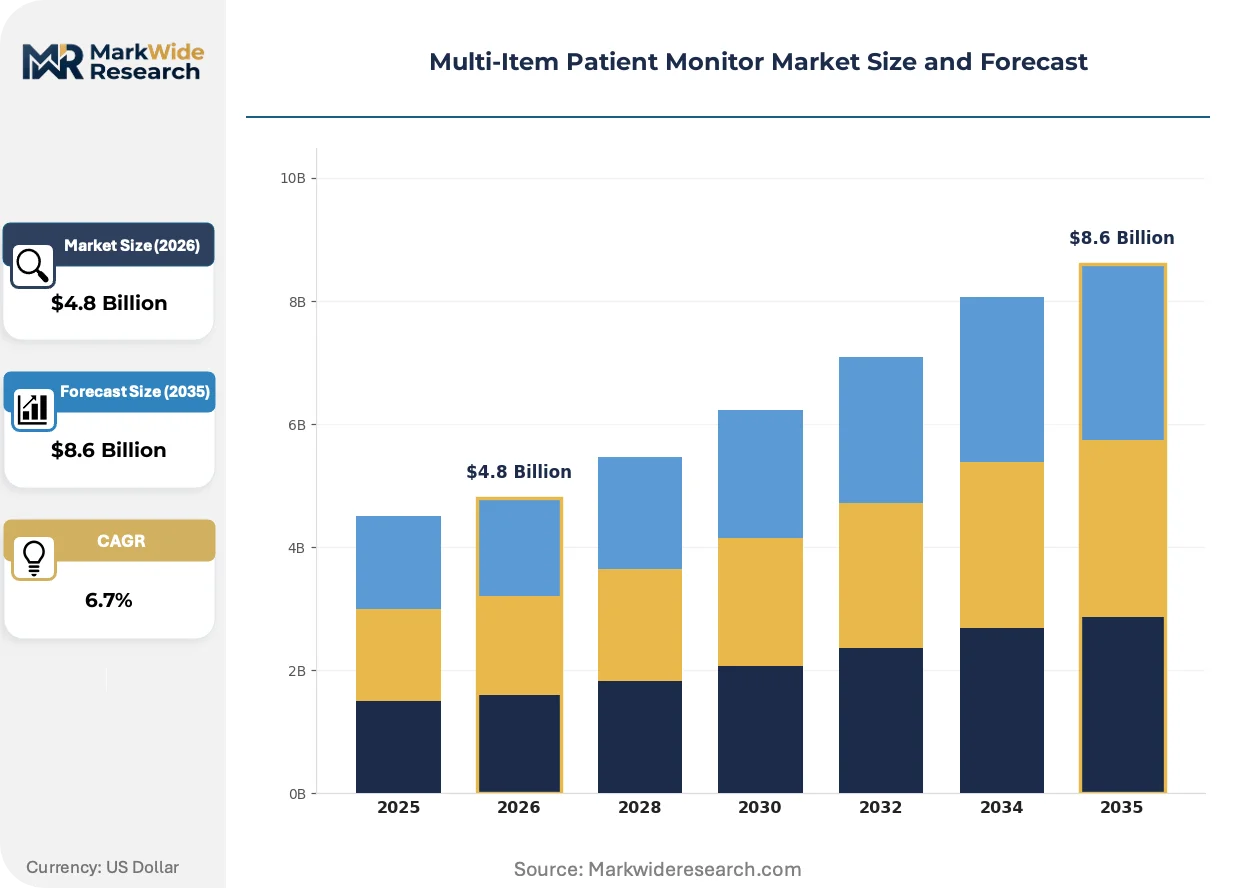
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Bedside Monitors, Wearable Monitors, Central Monitors End User: Hospitals, Home Care Providers, Emergency Services, Long-term Care Facilities Technology: Bluetooth, Wi-Fi, Wired Networks, Cloud-Based Solutions Application: Cardiology, Neurology, Anesthesia, Surgery |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Medtronic, Nihon Kohden Corporation, Mindray Medical International, Drägerwerk AG & Co. KGaA, Masimo Corporation, Spacelabs Healthcare, Schiller AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Item Patient Monitor Market Shifts & Advancements
Edge computing architectures are redistributing analytical workloads from central servers to bedside devices, enabling real-time waveform processing without latency vulnerability. This decentralization is reshaping hardware specifications and cybersecurity surface areas simultaneously.
Wireless parameter acquisition is electrifying clinical workflow design. Bluetooth 5.3 modules with medical-grade latency profiles now transmit 1000 Hz ECG waveforms without perceptible delay. Emergency departments and perioperative suites are adopting these untethered configurations fastest. The technology is electrifying competitive positioning around total cost of ownership rather than device price alone.
Japan's PMDA electromagnetic compatibility testing regime is tightening emission standards for networked devices. Manufacturers seeking market access must redesign shielding architectures and resubmit validation data. Cardiac catheterization labs and electrophysiology suites face the steepest compliance burden due to high-density RF environments.
Health system procurement committees now unbundle hardware acquisition from multi-year service agreements. Integrated delivery networks negotiate monitoring platforms separately from predictive maintenance and cybersecurity subscription tiers. This bifurcation is most visible in United States metropolitan markets where GPO consolidation has concentrated buyer leverage.
Multi-Item Patient Monitor Market Segmentation
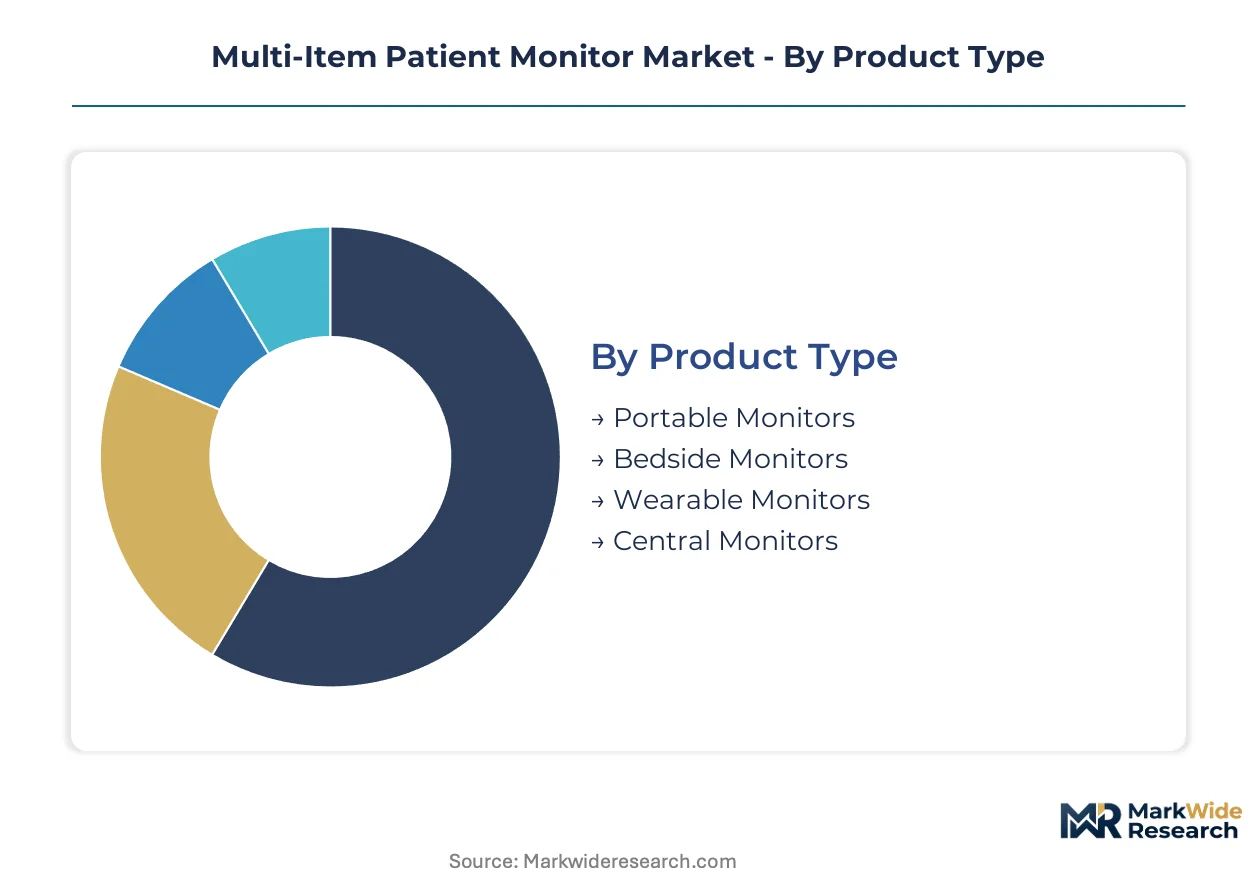
Multi-item patient monitors fragment across four distinct dimensions that reshape procurement economics and vendor competitive dynamics. Product type determines capital deployment intensity, while technology choice locks health systems into specific cybersecurity validation protocols. End user concentration and application specialization further stratify pricing power across the value chain.
Product Type:
Capital-intensity varies dramatically across this category, with bedside installations requiring the heaviest infrastructure investment and portable platforms demanding lighter upfront outlays but higher lifecycle service commitments.
- Portable Monitors:Battery-powered modular units with wireless parameter acquisition enable patient transport between acute care zones and step-down units. Demand concentrates in United States metropolitan health systems reconfiguring intermediate care spaces for higher-acuity patients, with Bluetooth 5.3 connectivity reducing cabling infrastructure costs.
- Bedside Monitors:Fixed-installation platforms with 1000 Hz waveform sampling serve as central nervous systems in intensive care units and emergency departments. Hospitals in Germany and France prioritize these for electrophysiology labs and cardiac catheterization suites where electromagnetic compatibility under EU MDR mandates rigorous shielding validation.
- Wearable Monitors:Ambulatory patches with multi-parameter sensing target hospital-at-home reimbursement expansion and post-acute monitoring.
- Central Monitors:Hub architectures aggregate data from multiple bedside units into nurse station displays, requiring substantial IT backbone investment.
Bedside monitors absorb the bulk of installed capacity in acute care networks; portable monitors are expanding most quickly as health systems prioritize patient mobility.
End User:
Procurement authority and volume scale diverge sharply across customer types, with integrated delivery networks wielding concentrated leverage against fragmented home care and long-term care purchasers.
- Hospitals:Acute care facilities with centralized patient data architectures drive demand for networked monitoring platforms. United States health systems facing FDA cybersecurity requirements for networked medical devices prioritize validated manufacturers with established service infrastructures.
- Home Care Providers:Dispersed operators with limited capital budgets favor rental and subscription models over outright purchase. Japan's PMDA electromagnetic compatibility testing shapes product availability for cellular-backhaul ambulatory systems targeting this channel.
- Emergency Services:Mobile intensive care units and ambulance fleets require ruggedized portable units with rapid deployment protocols.
- Long-term Care Facilities:Skilled nursing operators balance monitoring sophistication against Medicaid reimbursement constraints.
Hospitals command the dominant share of procurement volume; home care providers are climbing the fastest as reimbursement frameworks shift toward acute care in residential settings.
Technology:
Connectivity architecture determines both cybersecurity surface area and integration friction with legacy infrastructure, with wireless protocols gaining share in retrofit installations while cloud-native solutions concentrate in new construction.
- Bluetooth:Medical-grade 5.3 modules with sub-10ms latency now transmit high-fidelity ECG waveforms without perceptible delay. United States emergency departments and perioperative suites adopt these configurations fastest to dismantle legacy wired infrastructure.
- Wi-Fi:Enterprise-grade wireless enables seamless handoff across hospital zones but demands continuous firmware validation against evolving threat landscapes.
- Wired Networks:Ethernet-based installations persist in aging facilities where BACnet and proprietary nurse call systems resist IP-native interoperability.
- Cloud-Based Solutions:Centralized data architectures align with greenfield hospital constructions in Germany and the Netherlands where IT infrastructure modernization budgets match cybersecurity framework investments.
Wired networks retain the largest installed base; cloud-based solutions are gaining share fastest among new hospital builds with modernized IT budgets.
Application:
Clinical specialization dictates parameter module configuration and regulatory scrutiny intensity, with cardiac applications commanding premium positioning and anesthesia driving highest sampling frequency requirements.
- Cardiology:Specialized electrophysiology modules with arrhythmia detection algorithms occupy premium price tiers. Electrophysiology labs in France and Italy under EU MDR Class IIb device mandates require extensive clinical evidence and post-market surveillance documentation.
- Anesthesia:Multi-parameter integration with gas analysis and depth-of-consciousness monitoring demands 1000 Hz sampling for waveform fidelity.
- Neurology:EEG-compatible platforms with seizure detection capabilities serve epilepsy monitoring units and neuro-intensive care.
- Surgery:Perioperative suites require seamless integration with anesthesia information management systems and electronic health records.
Cardiology captures the steepest pricing premium; anesthesia represents the most technically demanding integration challenge across operating room workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's medical technology corridor anchors North American procurement of connected monitoring platforms as integrated health systems consolidate purchasing authority across metropolitan networks.
United States
Hospital-at-home reimbursement expansion accelerates demand for FDA-cleared ambulatory systems with cellular backhaul. The FDA enforces 21 CFR 870 premarket notification requirements with cybersecurity documentation extending development timelines. The Texas Medical Center in Houston deploys centralized patient data architectures across its fifty-one million square foot campus.
Germany
Electrophysiology labs in Baden-Württemberg require rigorous electromagnetic compatibility shielding under EU MDR Class IIb mandates. The EU Medical Device Regulation elevates clinical evidence thresholds that filter marginal suppliers from procurement shortlists. The Mannheim-Heidelberg medical technology cluster concentrates bedside monitor manufacturing for cardiac catheterization suites.
Japan
PMDA electromagnetic compatibility testing shapes product development cycles for manufacturers seeking market access. METI emission standards for networked devices are tightening in high-density RF environments. The Tokyo-Osaka corridor dominates domestic procurement of portable monitors with Bluetooth 5.3 connectivity for step-down unit flexibility.
France
Arrhythmia detection algorithms occupy premium price tiers in Parisian electrophysiology labs under EU MDR post-market surveillance obligations. The ANSM enforces vigilance reporting for Class IIa and IIb monitoring equipment. The Lyon-Grenoble medical device cluster specializes in modular parameter acquisition systems for anesthesia applications.
Netherlands
Greenfield hospital constructions in the Randstad region embed cloud-native monitoring architectures with modernized IT infrastructure budgets. The EU AI Act intersects with MDR requirements for algorithm-augmented early warning scoring systems. The Eindhoven health technology corridor drives wireless retrofit kit adoption across aging facility networks.
Multi-Item Patient Monitor Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with deep installed bases in acute care settings. Three archetypes dominate: integrated health technology platforms leveraging informatics layers, specialized cardiac monitoring module suppliers commanding premium electrophysiology positions, and modular retrofit specialists unlocking upgrade revenue without full device replacement. M&A activity concentrates on cybersecurity validation capabilities and wireless parameter acquisition engineering talent.
Among diversified health technology conglomerates, GE Healthcare and Koninklijke Philips N.V. exemplify platform-scale positioning through service revenue streams alongside hardware placements. Medtronic occupies a specialized tier representing premium cardiac monitoring differentiation. These three anchors illustrate how competitive positioning stratifies across integrated informatics capabilities, acute care installed base depth, and electrophysiology lab specialization rather than device price alone.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Medtronic |
| Nihon Kohden Corporation |
| Mindray Medical International |
| Drägerwerk AG & Co. KGaA |
| Masimo Corporation |
| Spacelabs Healthcare |
| Schiller AG |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists in European monitoring component manufacturing are consolidating analog-to-digital converter suppliers and shielding validation services, tightening pricing discipline among tier-two hardware vendors while forcing integrated health systems toward multi-year service bundling.
Pricing Analysis
Uptime-guarantee contracts now anchor value-based pricing for bedside monitor deployments, with three-tier pricing structure across premium, standard, and economy levels separating FDA-validated architectures from EU MDR Class IIa equivalents. Price differentiation stems from cybersecurity certification tier and after-sales predictive maintenance scope. Cost compression in portable monitor tiers is intensifying because Bluetooth 5.3 module commoditization is eroding hardware margins. Home care providers exhibit highest price sensitivity; electrophysiology labs in Germany and France show least sensitivity due to EU MDR compliance premiums.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based foundries supplying discrete signal processors and with Japanese manufacturers of medical-grade lithium-polymer cells. Component sourcing draws from South Korea for specialized display panels and from China for injection-molded housings. Raw material dependencies include silver/silver chloride for electrodes, copper for shielding, and rare-earth magnets for miniature pumps. Tariff exposure on Chinese-sourced PCBs presents structural risk. Distribution runs through GPO-negotiated direct contracts with integrated delivery networks and regional medical device distributors serving fragmented long-term care operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless parameter acquisition is displacing wired bedside architectures, compressing hardware refresh cycles and forcing cybersecurity validation protocols to evolve in parallel with physical deployment.
For Market Incumbents: Deepen firmware validation talent pipelines through embedded security engineering apprenticeships tied to FDA 510(k) submission experience. Expand service revenue capture via modular retrofit kits that clip onto existing bedside frames, defending against portable monitor specialists eroding installed base stickiness. Prioritize backward integration into medical-grade battery cell supply to offset East Asian single-source vulnerability. For New Entrants and Emerging Players: Launch via hospital-at-home reimbursement channels with FDA-cleared ambulatory systems featuring cellular backhaul, bypassing entrenched GPO relationships in acute care. Target dispersed home care providers in Japan facing PMDA electromagnetic compatibility barriers that slow incumbent product cycles. Pursue white-space in step-down unit wireless retrofit installations where IT infrastructure budgets lag greenfield construction timelines. For Investors and Strategic Acquirers: FDA cybersecurity guidance publication for networked medical devices is the leading indicator that validation-service multiples will expand disproportionately to hardware manufacturers. Frame long-term viability around informatics platform consolidation rather than device shipment volume. Monitor acquisition targets among cybersecurity validation boutiques with 21 CFR 870 submission track records and wireless parameter acquisition engineering teams.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Submission | Premarket notification with threat remediation documentation unlocks integrated health system procurement shortlists. |
| EU MDR Class IIb Pathway | Clinical evidence and post-market surveillance compliance filters marginal competitors from electrophysiology lab tenders. |
| Hospital System Partnership | Multi-year service agreements with GPO-negotiated pricing secure recurring revenue alongside hardware placements. |
| Software Companion Development | AI-augmented early warning scoring integration creates differentiation beyond waveform sampling specifications. |
| Reimbursement Strategy | Hospital-at-home coding alignment accelerates ambulatory monitor adoption in United States metropolitan markets. |
Research Methodology
FDA 510(k) filings, EU MDR technical documentation databases, and GPO contract award records formed the secondary backbone of this analysis. Primary interviews with hospital biomedical engineers, integrated delivery network procurement officers, and regulatory affairs specialists at monitoring device manufacturers were triangulated against customs data on analog-to-digital converter import flows and CMS Medicare reimbursement code utilization. Bottom-up shipment estimates by product type and technology were cross-validated against top-down health system capital expenditure surveys across the analysis window.
Bottom-up modeling segmented volume and value across portable, bedside, wearable, and central monitor architectures, with Bluetooth, Wi-Fi, wired, and cloud-based connectivity layers analyzed separately. End-user splits between hospitals, home care providers, emergency services, and long-term care facilities were calibrated against reimbursement framework shifts. CAGRs were derived from installed base replacement cycles, step-down unit expansion timelines, and greenfield hospital construction pipelines. Forecast inputs incorporated semiconductor supply lead time volatility and FDA premarket notification approval duration trends.
Regulatory timeline delays, semiconductor supply disruption, and hospital-at-home reimbursement coding changes are the dominant revision risks to projection assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Middle-East and Africa Hemodynamic Monitoring Market
Patient Monitoring
Epro, E-Patient Diaries and Ecoa Market
Patient Monitoring
Continuous Cardiac Monitoring Devices Market
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
Global Multi-Parameter Patient Monitoring Equipment Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
Blood Pressure Monitors Market
Patient Monitoring
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market
Patient Monitoring
Pain Monitoring Devices Market
Patient Monitoring
Global Hemodynamic Monitoring System Market
Patient Monitoring
China Patient Monitoring Market
Patient Monitoring
Patient Temperature Management Systems Market
Patient Monitoring
Monitoring Wristband Market
Patient Monitoring
MRI Pulse Oximeters Market
Patient Monitoring
Digital Patient Monitoring Systems Market
Patient Monitoring
Wearable Heart Monitoring Devices Market