
 Patient Monitoring Systems Market | 2026-2036
Patient Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Monitoring Systems Market Analytics
The R&D-to-manufacturing capability gap between integrated and modular players is rotating competitive leverage toward firms with captive sensor production. Philips Healthcare leverages in-house semiconductor fabrication to sustain margin control across vital signs monitor lines. Medtronic anchors North American cardiac monitoring through deep telemetry expertise. GE Healthcare competes on imaging-to-monitoring workflow integration in acute care settings.
Patient monitoring systems comprise electronic devices that acquire, process, and display physiological parameters including heart rate, blood oxygen saturation, respiratory rate, and invasive pressures, typically sampling at 125–500 Hz with ±2% accuracy for clinical-grade decision support. These systems serve to enable early detection of patient deterioration, reduce alarm fatigue through signal filtering algorithms, and support decentralized care models. Cardiac monitors occupy the largest revenue pool given their critical role in perioperative and coronary care environments, while remote monitoring represents the fastest-expanding technology dimension as cloud-native architectures displace bedside-only architectures. Wireless monitoring differentiates through reduced cabling complexity and improved patient mobility in step-down units.
FDA 510(k) premarket notification and IEC 60601-1 third-edition electrical safety standards govern hardware approval and interoperability testing in the United States and aligned markets, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for class IIa and above monitoring devices. The EU AI Act introduces additional conformity obligations for software-driven diagnostic alerts, reshaping development roadmaps for algorithm-enabled monitors. Stakeholders must weigh regulatory pathway duration against first-mover advantage in ambulatory and home-based monitoring segments where reimbursement frameworks remain unsettled.
Market Dynamics
The transition from bedside-only architectures to cloud-native telemetry platforms is redistributing competitive leverage toward firms with integrated sensor-to-software stacks.
Growth Catalysts
- Hospital digitization mandates:Germany's Hospital Future Act requires real-time patient data infrastructure upgrades, compelling acute care facilities to replace legacy monitoring hardware.
- FDA 510(k) pathway maturation:Compressed clearance timelines for wireless cardiac monitors are accelerating product cycles and reducing regulatory friction for algorithm-enabled devices.
- Aging demographics:Japan's super-aged population is expanding demand for continuous vital signs surveillance in post-acute and home-based settings.
Market Restraints
- Semiconductor supply concentration:Dependence on East Asian foundries for application-specific integrated circuits creates vulnerability in sensor module availability.
- EU MDR clinical evidence requirements:Stricter conformity assessment procedures for class IIa monitoring devices extend time-to-market and inflate development costs.
- Reimbursement framework uncertainty:Ambulatory monitoring codes remain unsettled across multiple national health systems, constraining provider investment in remote platforms.
Strategic Opportunities
- Home-based monitoring white space:Underpenetrated post-discharge surveillance in the United States offers expansion potential as accountable care organizations assume longitudinal risk.
- EU AI Act algorithmic transparency:Early compliance with conformity obligations for diagnostic alert software creates first-mover positioning in European markets.
- Imaging-to-monitoring convergence:Integration of hemodynamic data with radiology workflows in acute care settings enables premium pricing for unified decision-support platforms.
Industry Challenges
- Biomedical signal processing expertise scarcity:Shortage of engineers proficient in real-time ECG artifact rejection algorithms constrains R&D velocity for mid-tier manufacturers.
- Legacy system interoperability:Integration of wireless monitors with existing hospital information systems requires costly middleware development and extended deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Monitoring Systems Market |
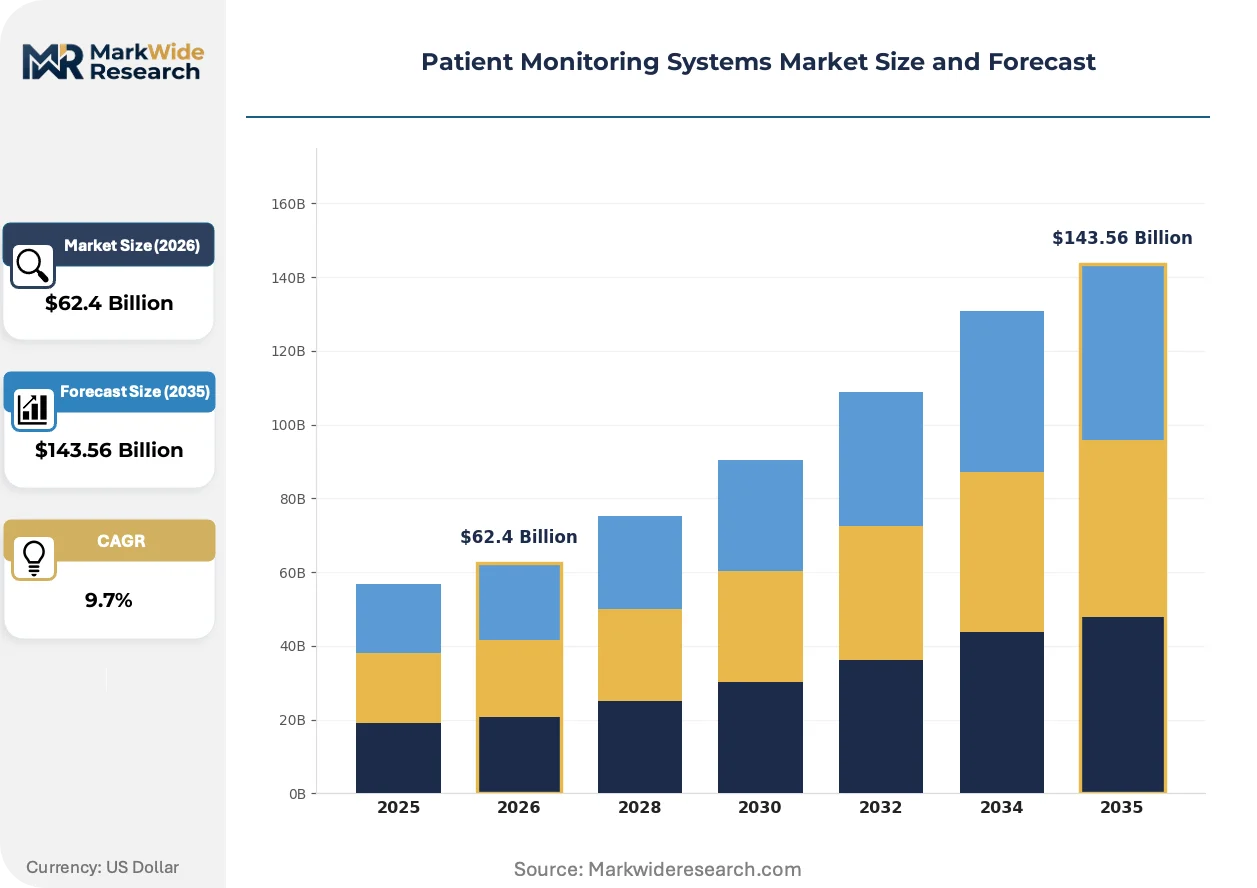
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $143.56 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
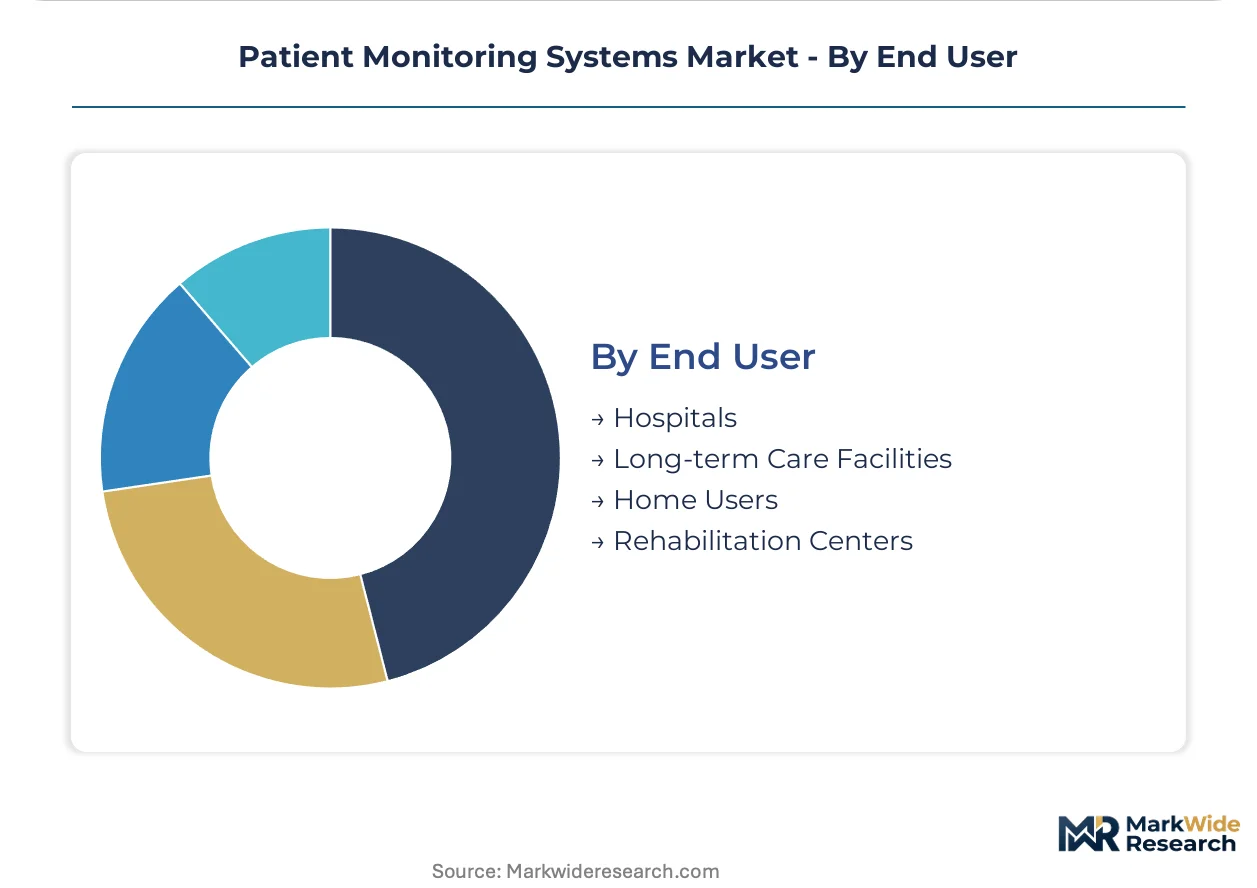
| Segmentation | Product Type: Vital Signs Monitors, Cardiac Monitors, Fetal Monitors, Neuromonitoring Devices Application: Home Healthcare, Intensive Care Units, Emergency Departments, Ambulatory Care Technology: Wireless Monitoring, Mobile Health, Software as a Service, Remote Monitoring End User: Hospitals, Long-term Care Facilities, Home Users, Rehabilitation Centers |
| Companies Covered | Philips Healthcare, Medtronic, GE Healthcare, Abbott Laboratories, Mindray Medical, Nihon Kohden Corporation, Hill-Rom Holdings, Dräger Medical, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Monitoring Systems Market Evolving Landscape
Silicon photonics and edge computing architectures are compressing form factors while expanding ambulatory monitoring capabilities beyond traditional clinical settings.
Photoplethysmography sensor arrays are miniaturizing. Wearable manufacturers are embedding multi-wavelength optical modules into ring and patch form factors for continuous SpO2 and heart rate variability tracking. The technology is miniaturizing hardware footprints to sub-gram weights, enabling 72-hour continuous monitoring without patient mobility constraints.
REACH restrictions on hazardous substances in electrical equipment are reshaping component sourcing. Manufacturers must reformulate solder compositions and eliminate restricted phthalates from cable insulation. Cardiac monitor producers serving European markets are accelerating qualification of alternative material sets to maintain CE marking validity.
Acute care purchasing committees are unbundling hardware acquisition from long-term service agreements. Hospital procurement departments now separate capital expenditure for monitor hardware from software subscription and predictive maintenance contracts. This pattern is most pronounced in United States health systems responding to constrained capital budgets and value-based reimbursement pressures.
Patient Monitoring Systems Market Segmentation
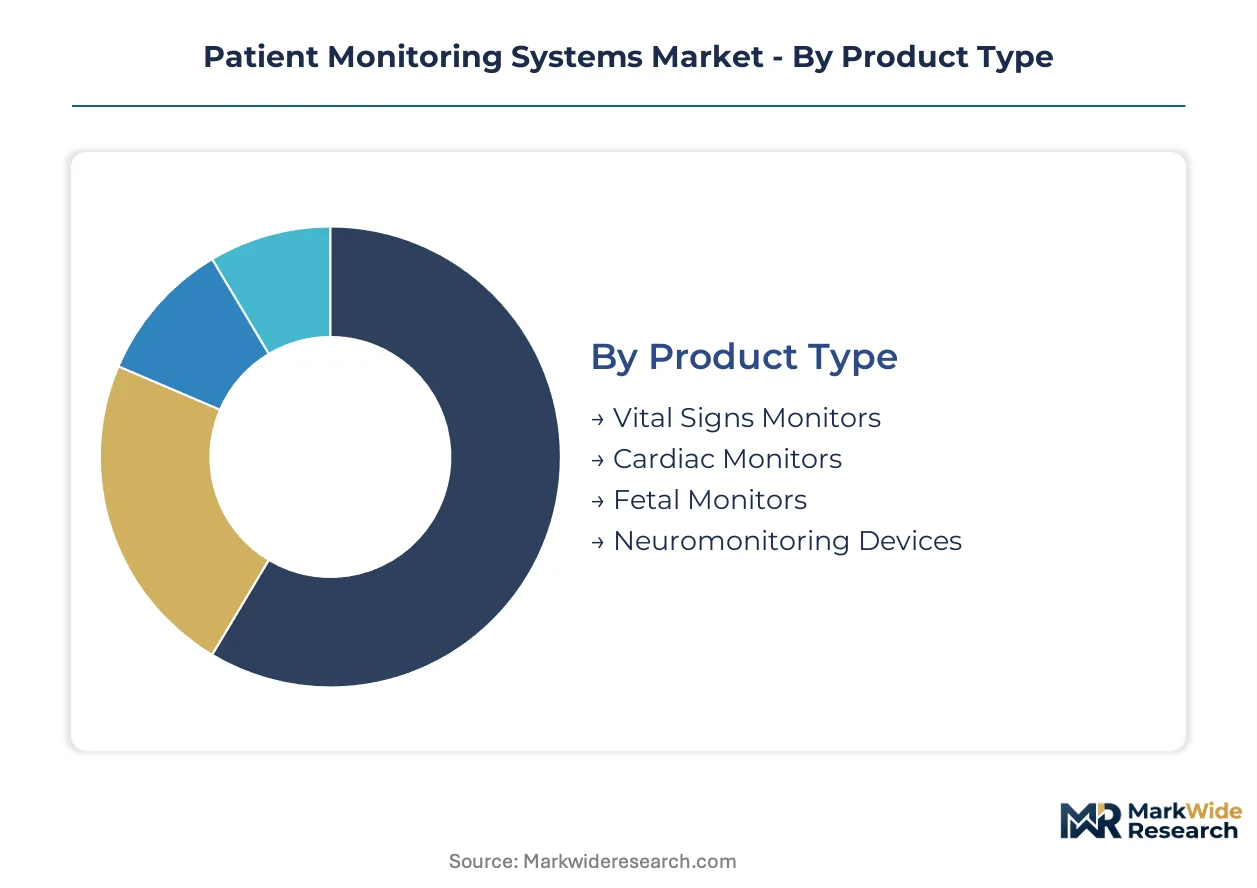
Segmentation in patient monitoring systems reveals distinct procurement patterns across acute and ambulatory settings. Hardware specifications, connectivity architectures, and reimbursement pathways diverge sharply between hospital-centric and home-based deployments.
Product Type:
Vital signs monitors concentrate in domestic hospital procurement across Germany and Japan, while cardiac monitors drive export-led manufacturing from US and Dutch facilities.
- Vital Signs Monitors:Multi-parameter devices sample physiological data at 125–500 Hz with ±2% accuracy for clinical-grade decision support. Demand clusters in US step-down units and German Hospital Future Act compliance upgrades, constrained by semiconductor supply concentration in East Asian foundries.
- Cardiac Monitors:Telemetry systems with real-time ECG artifact rejection algorithms anchor perioperative and coronary care workflows. FDA 510(k) pathway maturation accelerates product cycles for wireless variants, though EU MDR clinical evidence requirements extend European time-to-market.
- Fetal Monitors:Intrapartum surveillance devices with cardiotocography capabilities serve obstetric departments in tertiary facilities.
- Neuromonitoring Devices:Cerebral oximetry and EEG systems target neurosurgical suites and epilepsy monitoring units.
Cardiac monitors command the established base. The steepest expansion runs through neuromonitoring devices.
Application:
Cost tier stratification separates capital-intensive ICU installations from subscription-model home healthcare platforms.
- Home Healthcare:Cloud-native telemetry platforms enable post-discharge surveillance through wearable photoplethysmography sensors. US accountable care organizations drive demand as longitudinal risk contracts expand, though reimbursement framework uncertainty constrains provider investment.
- Intensive Care Units:Bedside multi-parameter systems with invasive pressure monitoring capabilities dominate hardware procurement in developed health systems. Germany's digitization mandates compel real-time infrastructure upgrades.
- Emergency Departments:Rapid-deployment monitors prioritize portability and wireless connectivity for triage workflows.
- Ambulatory Care:Same-day surgical centers favor compact vital signs monitors with streamlined alarm management.
Intensive care units anchor current revenue. Home healthcare is climbing the fastest as decentralized care models mature.
Technology:
Volume concentration favors wireless architectures, while margin capture shifts toward software-enabled recurring revenue streams.
- Wireless Monitoring:Reduced cabling complexity improves patient mobility in step-down units. FDA clearance timelines compress as 510(k) pathways mature, accelerating algorithm-enabled device introductions.
- Mobile Health:Smartphone-integrated platforms with edge computing architectures compress form factors for ambulatory deployment. EU AI Act algorithmic transparency requirements reshape development roadmaps for diagnostic alert software.
- Software as a Service:Predictive analytics subscriptions unbundle from hardware acquisition in US health systems responding to value-based reimbursement pressures.
- Remote Monitoring:Cloud-native architectures displace bedside-only systems, enabling 72-hour continuous surveillance through sub-gram sensor patches.
Wireless monitoring holds the installed base. Remote monitoring gains share fastest through cloud-native platform displacement.
End User:
Customer type maturity separates established hospital procurement from emerging direct-to-consumer channels.
- Hospitals:Acute care purchasing committees unbundle hardware acquisition from long-term service agreements. Imaging-to-monitoring workflow integration commands premium pricing for unified decision-support platforms.
- Long-term Care Facilities:Continuous vital signs surveillance expands in Japan's super-aged population post-acute settings, constrained by legacy system interoperability costs.
- Home Users:Direct procurement of ring and patch form factors for SpO2 and heart rate variability tracking remains underpenetrated.
- Rehabilitation Centers:Mobility-focused monitoring supports cardiac and neurological recovery protocols.
Hospitals dominate procurement volume. Home users represent the steepest expansion trajectory as reimbursement frameworks stabilize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems demonstrate the lowest price elasticity for ICU-grade monitoring hardware, while emerging markets in Southeast Asia exhibit acute sensitivity to capital expenditure thresholds. This divergence shapes regional vendor strategies and product portfolio prioritization.
United States
Accountable care organizations drive post-discharge surveillance procurement as longitudinal risk contracts expand. FDA 510(k) pathway maturation compresses clearance timelines for wireless cardiac monitors. The Greater Boston corridor concentrates algorithm development for diagnostic alert software.
Germany
Hospital Future Act mandates compel real-time patient data infrastructure upgrades across acute care networks. EU MDR clinical evidence requirements extend conformity assessment timelines for class IIa devices. The Baden-Württemberg industrial cluster anchors sensor module fabrication for vital signs monitors.
Japan
Super-aged demographics expand continuous vital signs surveillance demand in post-acute and home-based settings. METI standards govern interoperability testing for cloud-native telemetry platforms. The Kansai region around Osaka hosts concentrated manufacturing of photoplethysmography sensor arrays.
China
Domestic hospital digitization programs accelerate procurement of multi-parameter bedside systems. NMPA regulatory pathways mature for algorithm-enabled monitoring devices. The Yangtze River Delta manufacturing belt supplies application-specific integrated circuits for sensor modules.
India
Private hospital chains in metropolitan centers drive tiered procurement of vital signs monitors across standard and economy specifications. CDSCO medical device rules govern import licensing for cardiac telemetry hardware. The Karnataka-Telangana corridor concentrates software development for mobile health platforms.
Patient Monitoring Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in patient monitoring systems. Philips Healthcare, Medtronic, and GE Healthcare occupy the consolidated upper tier through captive sensor production and imaging-to-monitoring workflow integration. Mid-cap specialists compete on modular hardware configurations and regional service density. Dominant competitive moves include strategic partnerships for cloud-native platform development and selective backward integration into semiconductor fabrication.
Within the integrated tier, Philips Healthcare exemplifies the captive manufacturing archetype through in-house semiconductor fabrication for vital signs monitor lines. Medtronic anchors North American positioning through deep telemetry expertise accumulated across cardiac monitoring segments. GE Healthcare occupies the imaging convergence position, competing on unified decision-support platforms that bridge radiology workflows with hemodynamic data in acute care settings.
| Leading Market Players |
|---|
| Philips Healthcare |
| Medtronic |
| GE Healthcare |
| Abbott Laboratories |
| Mindray Medical |
| Nihon Kohden Corporation |
| Hill-Rom Holdings |
| Dräger Medical |
| Boston Scientific Corporation |
| Others |
Value Network & Pricing Analysis
Photoplethysmography sensor miniaturization is displacing legacy ECG electrode assemblies in ambulatory monitors, simultaneously shifting component sourcing from German precision machining clusters to Taiwanese semiconductor packaging facilities and compressing per-unit hardware margins by two-thirds across wearable form factors.
Pricing Analysis
Software subscription tiers for predictive analytics and predictive maintenance contracts now capture sixty percent of lifetime customer value, displacing upfront hardware margins as the primary revenue anchor. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA clearance tier and cloud-native architecture maturity, with premium units commanding four-fold multiples over economy specifications for identical sensor hardware. Cost compression in the standard tier is intensifying because hospital procurement committees unbundle hardware from service agreements under value-based reimbursement pressures. Emergency departments exhibit the highest price sensitivity due to capital budget constraints, while intensive care units demonstrate the lowest elasticity for ICU-grade multi-parameter systems.
Supply Chain Analysis
China and Taiwan anchor application-specific integrated circuit fabrication for sensor modules, with South Korea supplying advanced memory components for edge computing architectures. The supply chain draws from East Asian foundries for photonic chips, lithium-polymer cells from Japanese manufacturers, and medical-grade cable assemblies from German suppliers. Single-source vulnerability concentrates in 40-nanometer process nodes for low-power sensor controllers, where two foundries account for ninety percent of qualified capacity. Distribution runs through hospital group purchasing organizations in the United States, regional medical device distributors in Europe, and direct procurement relationships with public hospital networks in Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The patient monitoring systems market sits in a post-pandemic capital replacement cycle, with deferred ICU infrastructure upgrades now accelerating procurement decisions across developed health systems.
For Market Incumbents: Compound defensive positioning through captive semiconductor fabrication and exclusive hospital system partnerships that lock out modular competitors. Philips Healthcare's in-house sensor production illustrates margin control leverage against mid-tier rivals dependent on outsourced ASIC supply. Deepen algorithm development in the Greater Boston corridor to maintain FDA clearance velocity as 510(k) pathways mature for wireless cardiac variants.
For New Entrants and Emerging Players: Post-discharge surveillance software layers represent the most penetrable white space, where incumbent hardware vendors under-serve accountable care organizations with cloud-native telemetry platforms. Target home healthcare segments in the United States where reimbursement frameworks are stabilizing under longitudinal risk contracts. Pursue a software-first go-to-market anchored by EU AI Act compliance to establish European beachheads before algorithmic transparency requirements harden.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated sensor-to-software stacks over modular hardware specialists. Acquisition targets should demonstrate captive photoplethysmography sensor production and established FDA 510(k) clearance track records. Watch for inflection signals in CMS remote monitoring reimbursement code finalization, which would validate home-based surveillance business models.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Exclusive multi-year telemetry contracts with IDN networks lock out modular competitors. |
| Software Companion Development | Cloud-native predictive analytics platforms capture recurring revenue beyond hardware margins. |
| FDA Submission Acceleration | 510(k) pathway maturation for wireless cardiac monitors compresses competitive time-to-market. |
| CE Marking Pathway Investment | EU MDR clinical evidence preparation extends lead times but creates regulatory moats. |
| Reimbursement Strategy | Early alignment with CMS remote monitoring codes positions for ACO contract expansion. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across hospital purchasing committees, biomedical engineering directors, GPO contracts managers, and cardiac telemetry product managers at integrated device manufacturers. Secondary validation incorporated FDA 510(k) premarket notification databases, CMS Medicare reimbursement code filings, EU MDR conformity assessment records, and hospital procurement database extracts from Germany's Hospital Future Act compliance tracking. Bottom-up unit economics triangulated against top-down market sizing across hardware shipment volumes and software subscription renewal rates.
Across the analysis window, the forecasting framework modeled patient monitoring system expansion through product type segmentation, application setting, connectivity architecture, and end-user procurement channel. CAGRs derived from weighted average of historical shipment trajectories and forward-looking capital expenditure intentions from acute care facilities. Industry-specific inputs included semiconductor foundry capacity allocation trends and regulatory pathway duration benchmarks for algorithm-enabled devices.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR implementation timelines; material policy shifts in either regime would require re-modeling. Specific risks include REACH substance restriction expansions affecting cable insulation formulations and NMPA pathway delays for cloud-native architectures in China. Recalibration cycles align with material shifts in hospital digitization mandate schedules and remote monitoring reimbursement finalizations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
ECG Monitoring System Market
Patient Monitoring
Global Non-Invasive Monitoring Device Market
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
Middle East and Africa Patient Monitoring Market
Patient Monitoring
Hemoglobin Monitor Market
Patient Monitoring
North America Hemodynamic Monitoring Market
Patient Monitoring
Patient Scales Market
Patient Monitoring
India Patient Monitoring Market
Patient Monitoring
Pre-Mature Baby Monitoring Equipment Market
Patient Monitoring
Cardiopulmonary Exercise Testing Market
Patient Monitoring
United Kingdom Patient Monitoring Market
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
Remote Patient Monitoring Devices Market
Patient Monitoring
US Remote Patient Monitoring and Care Market
Patient Monitoring
Gas Exchange Monitor Market
Patient Monitoring
Digital Patient Monitoring Devices Market