
 Global Chemical Catalyst Market | 2026-2036
Global Chemical Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chemical Catalyst Market Analysis
Refinery demand is shifting toward higher-severity processing units that consume more zeolite-based cracking catalysts per barrel. BASF SE leverages its integrated refining catalyst portfolio across European and Asian licensing partnerships. Johnson Matthey PLC anchors its position through hydrogenation technology leadership in sustainable fuel applications. Evonik Industries AG specializes in high-purity organometallic catalysts for fine chemical synthesis.
Chemical catalysts are substances that accelerate reaction rates without permanent consumption, typically comprising supported metals, metal oxides, or molecular sieves with surface areas exceeding 100 m²/g, and function to reduce activation energy in industrial processes. Heterogeneous catalysts dominate installed capacity due to their separability and thermal stability in continuous-flow petrochemical operations. Homogeneous catalysts command premium pricing in pharmaceutical and fine chemical applications where stereoselectivity determines product value. Biocatalysts represent the fastest-expanding category as enzyme immobilization techniques mature for food and beverage processing.
The EPA enforces emission limits on catalyst regeneration cycles in U.S. refineries, while REACH mandates substance registration and hazard communication for catalyst precursors sold in Europe. China's MEE implements dual carbon targets that restrict high-energy catalyst production processes and favor low-temperature alternatives. Stakeholders must monitor regulatory divergence between jurisdictions to align R&D portfolios with diverging compliance thresholds.
Market Dynamics
Refinery operators in India and China are expanding fluid catalytic cracking capacity, tightening demand for zeolite-based catalysts while REACH compliance and China's dual carbon goals simultaneously reshape manufacturing standards across the value chain.
Growth Catalysts
- Polymerization catalyst demand:Specialty catalysts for polyethylene and polypropylene production are drawing investment as petrochemical complexes expand in the Middle East and Southeast Asia.
- EPA emission limits:Stricter U.S. regulations on catalyst regeneration cycles are forcing refinery upgrades that favor higher-activity cracking catalyst formulations.
- Enzyme immobilization:Maturing biocatalyst techniques for food and beverage processing are opening new application areas beyond traditional petrochemical uses.
Market Restraints
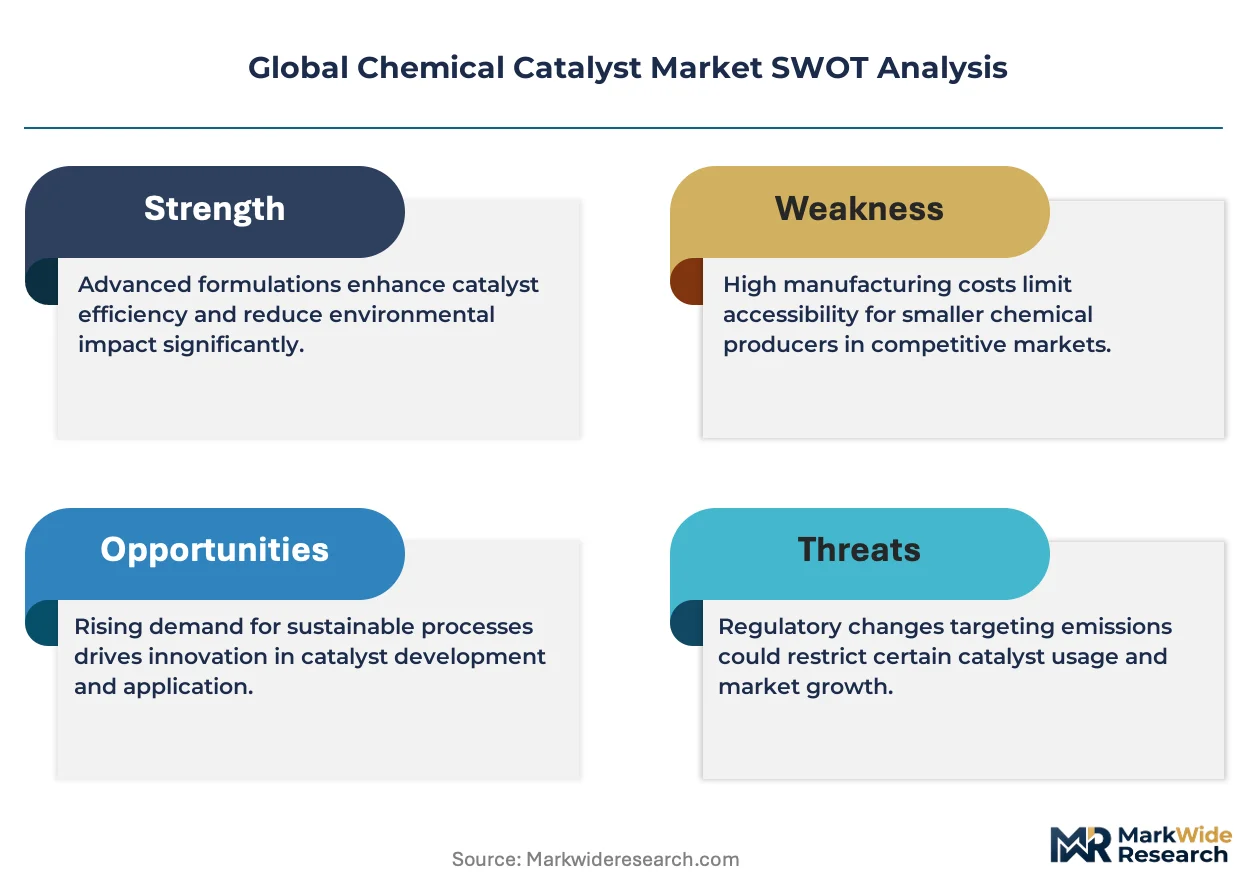
- Rare earth supply concentration:Zeolite catalyst production depends on lanthanum and cerium supply chains concentrated in China, creating input cost volatility and geopolitical exposure.
- REACH registration burden:European substance registration and hazard communication requirements for catalyst precursors impose fixed compliance costs that disadvantage smaller specialty catalyst suppliers.
- Biocatalyst performance limits:Enzyme thermal stability constraints restrict biocatalyst deployment in high-temperature refinery processes, capping substitution potential.
Strategic Opportunities
- India refinery expansion:Reliance Industries and Indian Oil Corporation are adding FCC capacity that will require long-term catalyst supply contracts with technology transfer provisions.
- Low-temperature alternatives:China's MEE dual carbon targets favor catalyst systems that operate at reduced temperatures, rewarding R&D investment in novel active site architectures.
- Hydrogenation for sustainable fuels:Biofuel and e-fuel producers need hydrogenation catalysts for hydrotreating applications, creating demand outside traditional petroleum refining.
Industry Challenges
- Organometallic synthesis expertise:Fine chemical catalyst production requires PhD-level organometallic chemists in short supply across Germany, Switzerland, and the United States.
- Multi-jurisdiction compliance:Catalyst manufacturers must simultaneously satisfy EPA emission rules, REACH substance restrictions, and China's GB standards, fragmenting product portfolios.
- Legacy refinery integration:New catalyst formulations must demonstrate compatibility with existing FCC unit designs without requiring capital-intensive reactor modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chemical Catalyst Market |
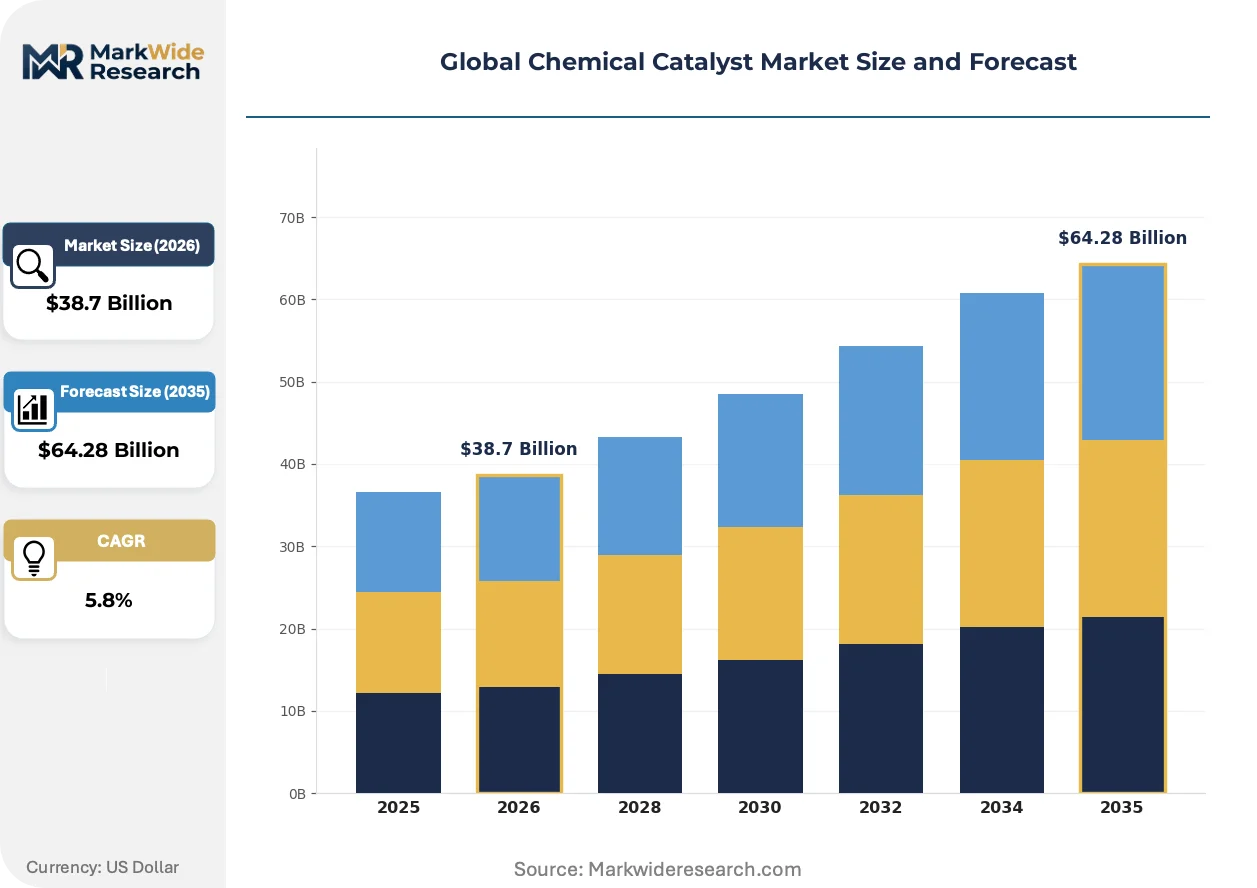
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heterogeneous, Homogeneous, Biocatalysts, Organocatalysts Application: Petrochemical, Fine Chemicals, Polymerization, Pharmaceuticals Technology: Steam Reforming, Catalytic Cracking, Hydrogenation, Dehydrogenation End User: Petrochemical Industry, Pharmaceutical Industry, Food & Beverage, Agrochemical Industry |
| Companies Covered | BASF SE, Clariant AG, Johnson Matthey PLC, Albemarle Corporation, W. R. Grace & Co., Evonik Industries AG, Haldor Topsoe A/S, Honeywell UOP, Axens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chemical Catalyst Market Emerging Trajectories
Digital catalyst screening platforms and modular reactor designs are compressing development timelines, while regulatory pressure on carbon intensity forces reformulation of established catalyst systems across multiple industrial verticals.
Single-site molecular catalysts with precisely defined active centers are modularizing polymerization process design. Polyethylene producers in South Korea and Saudi Arabia are adopting these systems to reduce off-spec product rates and enable rapid grade transitions. The technology is modularizing catalyst supply relationships, allowing end-users to switch between catalyst families without complete process revalidation.
REACH substance registration deadlines are tightening hazard communication requirements for catalyst precursors containing cobalt, nickel, and chromium compounds. European catalyst formulators must now submit extended safety data sheets before commercial distribution. Specialty chemical applications in pharmaceutical intermediates are most affected, with formulators accelerating substitution programs for flagged metal centers.
Refinery procurement departments are consolidating catalyst purchasing through integrated supply agreements that bundle technical service, spent catalyst reclamation, and performance guarantees. This model displaces traditional spot purchasing of commodity cracking catalysts in the U.S. Gulf Coast and Rotterdam refining clusters. Suppliers must now embed technical service teams at customer sites to secure long-term contracts.
Global Chemical Catalyst Market Segmentation
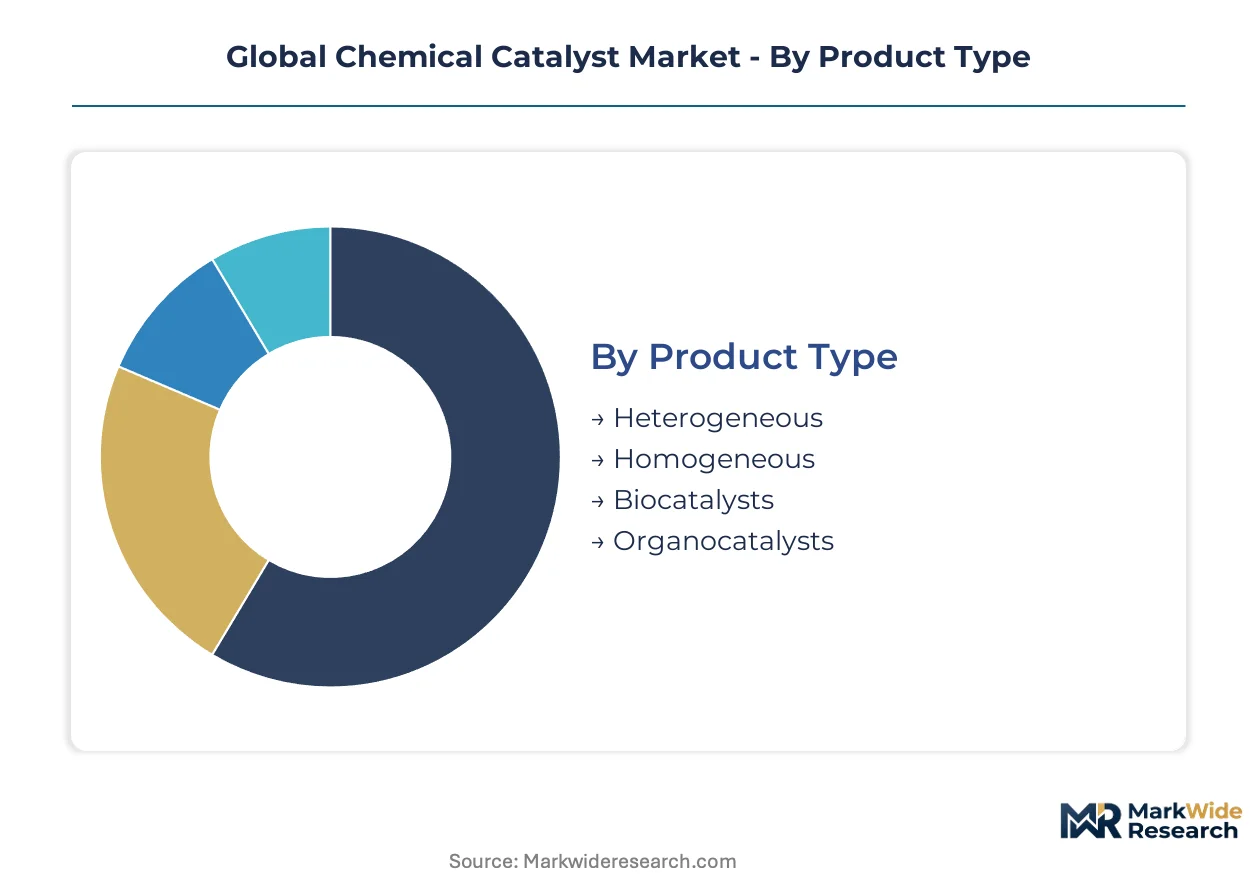
Catalyst buyers segment procurement by separability, thermal tolerance, and reaction specificity. The four-way split across product type, application, technology, and end user reveals where standard commodity formulations compete against engineered specialty systems.
Product Type:
The customization-vs-standardization spectrum runs from bulk heterogeneous powders to precision organometallic complexes with defined stereoselectivity.
- Heterogeneous:Solid-phase catalysts with surface areas exceeding 100 m²/g, comprising supported metals or zeolite molecular sieves. Demand concentrates in Indian and Chinese FCC unit expansions where thermal stability and separability in continuous-flow operations outweigh premium pricing.
- Homogeneous:Single-phase catalysts dissolved in reaction media, enabling precise active site control for stereoselective transformations. Fine chemical producers in Germany and Switzerland absorb premium pricing where enantiomeric purity determines product value.
- Biocatalysts:Immobilized enzyme systems maturing for food and beverage processing applications.
- Organocatalysts:Metal-free small-molecule activators gaining traction in pharmaceutical intermediate synthesis.
Leading the category by volume: Heterogeneous. Growing fastest: Biocatalysts.
Application:
Margin profiles diverge sharply between bulk petrochemical throughput and pharmaceutical batch specificity.
- Petrochemical:Zeolite cracking and hydrogenation catalysts consumed in high-tonnage refinery and steam cracker operations. Middle Eastern and Southeast Asian complex expansions drive contract volumes for long-term supply agreements with embedded technical service.
- Polymerization:Single-site molecular catalysts with precisely defined active centers. South Korean and Saudi Arabian polyethylene producers adopt these systems to reduce off-spec rates and enable rapid grade transitions without complete process revalidation.
- Fine Chemicals:High-purity organometallic catalysts for multi-step synthesis of pharmaceutical intermediates and agrochemical actives.
- Pharmaceuticals:Enantioselective catalysts for active pharmaceutical ingredient manufacturing under FDA and EMA quality guidelines.
Highest volume application: Petrochemical. Steepest expansion trajectory: Polymerization.
Technology:
Process temperature requirements and feedstock flexibility determine catalyst replacement cycles and supplier switching costs.
- Catalytic Cracking:Zeolite-based systems for heavy hydrocarbon conversion in FCC units. Indian Oil Corporation and Reliance Industries capacity additions in India tighten demand for rare earth-stabilized formulations despite lanthanum and cerium supply concentration in China.
- Hydrogenation:Metal sulfide and noble metal catalysts for hydrotreating and sustainable fuel production. Biofuel and e-fuel producers outside traditional petroleum refining create new demand centers for hydrotreating catalysts with sulfur tolerance specifications.
- Steam Reforming:Nickel-based catalysts for syngas and hydrogen production in ammonia and methanol plants.
- Dehydrogenation:Chrome-alumina and platinum-tin systems for olefin production from paraffin feeds.
Dominant installed base: Catalytic Cracking. Climbing the fastest: Hydrogenation.
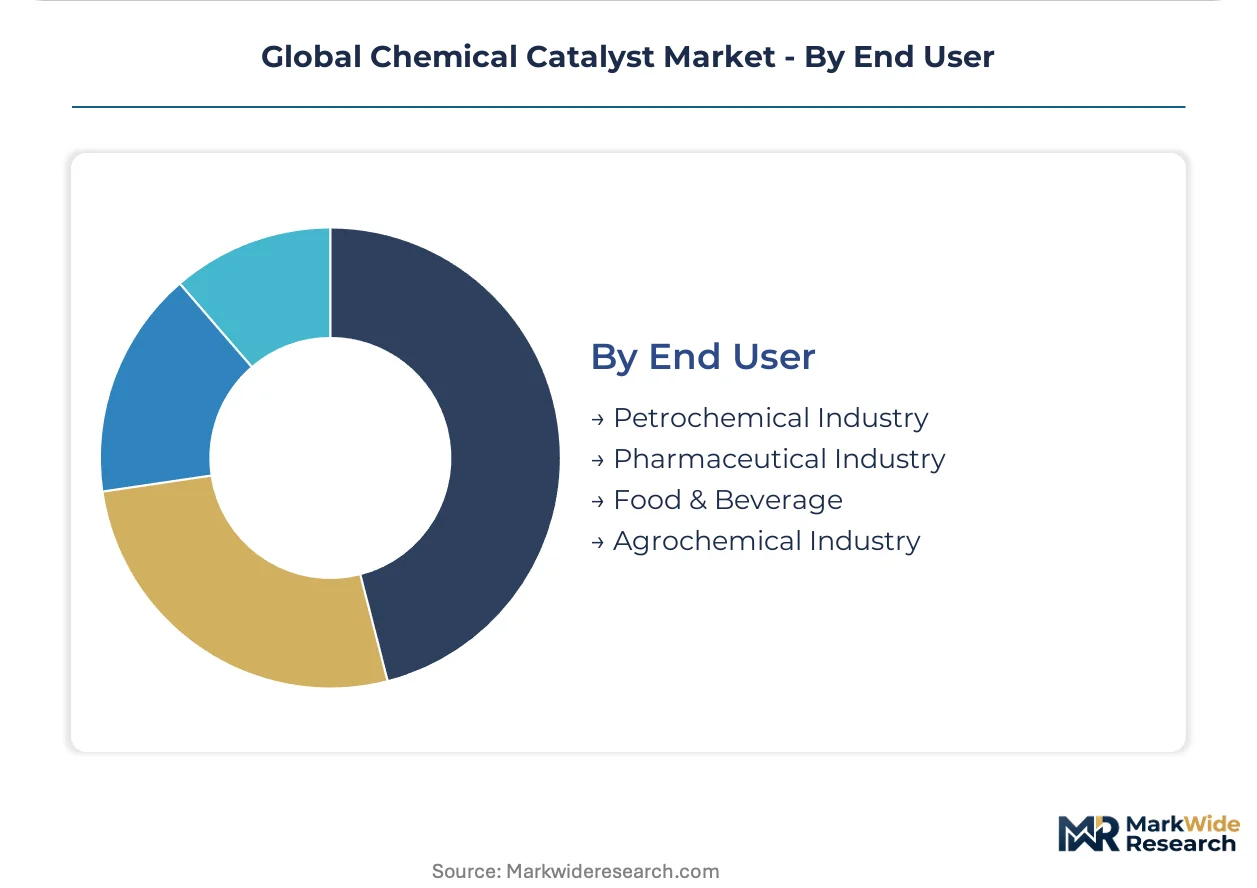
End User:
Procurement sophistication ranges from integrated petrochemical majors with captive technical teams to fragmented agrochemical formulators.
- Petrochemical Industry:Refinery and steam cracker operators with consolidated purchasing through bundled technical service, spent catalyst reclamation, and performance guarantee agreements. U.S. Gulf Coast and Rotterdam clusters displace spot purchasing with embedded supplier technical teams.
- Pharmaceutical Industry:Batch manufacturers requiring enantioselective catalysts with full regulatory documentation under FDA and EMA frameworks. REACH hazard communication requirements for cobalt, nickel, and chromium compounds accelerate substitution programs for flagged metal centers.
- Food & Beverage:Processors deploying immobilized enzyme systems for starch conversion and lipid modification.
- Agrochemical Industry:Formulators of herbicide and insecticide intermediates with intermediate technical requirements and price sensitivity.
Largest procurement volume: Petrochemical Industry. Gaining share fastest: Pharmaceutical Industry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates catalyst manufacturing capacity while the United States and Germany lead consumption of high-performance specialty formulations. India and Saudi Arabia anchor demand growth through refinery and petrochemical expansion programs. Regulatory divergence between EPA emission rules, REACH substance restrictions, and China's dual carbon targets fragments regional product portfolios.
United States
Refinery operators along the U.S. Gulf Coast are consolidating catalyst purchasing through bundled technical service agreements with embedded supplier teams. EPA emission limits on catalyst regeneration cycles force upgrades toward higher-activity cracking formulations. The Houston-Beaumont-Port Arthur cluster drives contract volumes for long-term supply with performance guarantees.
China
Fluid catalytic cracking capacity additions by Sinopec and PetroChina tighten demand for rare earth-stabilized zeolite catalysts despite lanthanum and cerium supply concentration risks. MEE dual carbon targets restrict high-energy production processes and favor low-temperature catalyst alternatives. The Yangtze River Delta and Pearl River Delta concentrate manufacturing plants serving domestic refinery and polymerization demand.
Germany
Fine chemical producers in Ludwigshafen and Leverkusen absorb premium pricing for homogeneous catalysts where enantiomeric purity determines product value. REACH substance registration and extended safety data sheet requirements for cobalt, nickel, and chromium compounds accelerate substitution programs. The country's national pharmaceutical regulator enforces strict documentation for catalysts used in active pharmaceutical ingredient manufacturing.
India
Reliance Industries and Indian Oil Corporation are adding FCC capacity that requires long-term catalyst supply contracts with technology transfer provisions. BIS standards and DGFT import policies shape procurement frameworks for refinery feedstock processing. The Gujarat refinery corridor and Maharashtra chemical belt concentrate demand for both cracking and hydrogenation catalyst systems.
Saudi Arabia
SABIC and Saudi Aramco petrochemical complex expansions drive contract volumes for single-site polymerization catalysts enabling rapid grade transitions. SFDA pharmaceutical quality guidelines and the country's national industrial development program influence specialty catalyst sourcing. The Jubail and Yanbu industrial cities anchor demand for high-tonnage refinery and steam cracker operations.
Global Chemical Catalyst Market Vendor Landscape
Top-tier vendors anchor integrated refining and petrochemical catalyst portfolios, while mid-tier specialists concentrate on single-technology niches or regional supply relationships. The structure splits between diversified chemical conglomerates with captive R&D infrastructure and focused catalyst houses competing on technical service intensity. Three archetypes dominate: integrated refining technology licensors, fine chemical organometallic specialists, and regional zeolite formulators serving FCC demand. Competitive moves center on long-term supply agreements with embedded technical teams and backward integration into rare earth precursor supply.
Within the integrated technology licensor tier, BASF SE and Johnson Matthey PLC exemplify the archetype of vendors bundling catalyst supply with process licensing and on-site technical service. Evonik Industries AG occupies a position among fine chemical specialists concentrating on high-purity organometallic systems for pharmaceutical and agrochemical synthesis. These three entities represent the span from commodity-scale refinery supply to precision stereoselective catalysis.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Johnson Matthey PLC |
| Albemarle Corporation |
| W. R. Grace & Co. |
| Evonik Industries AG |
| Haldor Topsoe A/S |
| Honeywell UOP |
| Axens |
| Others |
Supply Flow & Price Mechanics
Performance-grade divergence between rare earth-stabilized FCC formulations and commodity zeolite catalysts manifests in both pricing power and supply chain architecture across the value chain. Premium heterogeneous catalysts command extended payment terms and technical service bundling while standard grades compete on spot inventory availability.
Pricing Analysis
Short lead-time premiums for rare earth-stabilized zeolite catalysts reach substantial multiples over spot commodity grades in the U.S. Gulf Coast and Rotterdam clusters. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in standard-grade formulations is intensifying because Chinese lanthanum and cerium supply concentration feeds input volatility. Petrochemical majors with captive technical teams exhibit lowest price sensitivity while fragmented agrochemical formulators absorb highest procurement cost pressure.
Supply Chain Analysis
Direct-to-refinery channels handle hyperscale buyer demand through embedded technical service teams at Sinopec, Reliance Industries, and Saudi Aramco sites. Manufacturing gravity centers on China, Germany, and the United States with rare earth precursor dependencies drawing from Chinese mining operations. Single-source vulnerability in lanthanum and cerium supply chains creates geopolitical exposure for zeolite catalyst producers. Distribution runs through long-term supply agreements with performance guarantees rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as REACH registration burdens and rare earth cost volatility force smaller specialty catalyst suppliers toward acquisition or exit. Multi-jurisdiction compliance fragmentation rewards scaled players with captive regulatory affairs infrastructure.
For Market Incumbents: Lock in backward integration into rare earth precursor supply to neutralize Chinese supply concentration risk. Expand technical service teams at Indian refinery corridors to capture Reliance Industries and Indian Oil Corporation capacity additions. Hydrogenation technology leadership in sustainable fuel applications anchors defensible positioning against biocatalyst substitution threats. For New Entrants and Emerging Players: Regional zeolite formulators serving Middle Eastern FCC demand represent the most penetrable buyer archetype given SABIC and Saudi Aramco's openness to dual-source strategies. Low-temperature catalyst alternatives for China's MEE dual carbon compliance create white-space opportunity outside established petroleum refining. Partner with European fine chemical houses to access organometallic synthesis expertise scarce across Germany and Switzerland. For Investors and Strategic Acquirers: Re-rating potential sits with fine chemical organometallic specialists given REACH-driven substitution programs accelerating demand for flagged metal center alternatives. Five-to-ten year viability favors catalyst houses with captive R&D infrastructure and pharmaceutical regulatory documentation capabilities. Watch Indian refinery procurement consolidation as the signal for sector-wide contract structure transformation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Supply | Captive lanthanum and cerium sourcing neutralizes Chinese supply concentration and input cost volatility. |
| Long-term Supply Agreement with Technical Service | Embedded supplier teams at U.S. Gulf Coast and Rotterdam clusters displace spot purchasing models. |
| Green Manufacturing Transition | Low-temperature catalyst architectures align with China's MEE dual carbon targets and European REACH compliance. |
| Joint Venture for Regional Manufacturing | India's Gujarat refinery corridor and Maharashtra chemical belt demand localized production with technology transfer. |
| Acquisition of Organometallic Specialist | PhD-level synthesis expertise in Germany and Switzerland commands premium positioning in pharmaceutical intermediates. |
Methodological Framework
Document review covered SEC 10-K filings, customs and trade data from ACC and Cefic reports, and refinery procurement disclosures, complemented by interviews with plant managers at FCC unit operators, procurement leads at downstream petrochemical complexes, distribution channel partners, and technical R&D directors at catalyst formulators. Bottom-up volume modeling across heterogeneous, homogeneous, biocatalyst, and organocatalyst product types triangulated against top-down industry aggregation from regulatory submissions and production capacity databases.
Historical shipment data cross-referenced against panel input from catalyst procurement executives anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include catalyst separability class, application vertical, process technology type, and end-user procurement sophistication. CAGRs were derived from regression analysis of installed capacity additions and replacement cycle dynamics. Industry-specific inputs incorporated rare earth price indices and refinery utilization rates across the U.S. Gulf Coast, Rotterdam, and Singapore trading hubs.
Revisions become necessary when EPA emission rule amendments, REACH substance restriction updates, or Chinese dual carbon target accelerations materialize outside baseline assumptions. Forecasts reflect documented assumptions regarding refinery expansion timelines and polymerization capacity additions. Periodic stress-testing of base assumptions is recommended given regulatory divergence between jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Refinery Catalyst Market
Catalysts
Polymer Catalyst Market
Catalysts
Global Boron Trifluoride Methanol Complex Market
Catalysts
FCC Catalyst Additive Market
Catalysts
Catalase Market
Catalysts
Heterogeneous Catalyst Market
Catalysts
Catalyst Carrier Market
Catalysts
Refining Catalysts Market
Catalysts
North America Refining Catalysts Market
Catalysts
Aluminum-Nickel Catalyst Market
Catalysts
Petrochemical Catalyst Market
Catalysts
Oxalate Hydrogenation Catalyst Market
Catalysts
Industrial Catalyst Market
Catalysts
Global VOC Catalysts Market
Catalysts
Global Light Powered Catalyst Market
Catalysts
Global FCC Catalyst Market