
 Europe Lipids Market | 2026-2036
Europe Lipids Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Lipids Market Foresight
Specialized lipid chemistry expertise is collapsing across European universities, constraining formulation innovation for complex drug delivery systems. BASF SE leverages its Ludwigshafen integrated site to sustain captive phospholipid production for pharmaceutical clients. Croda International PLC anchors UK-based high-purity lipid supply for mRNA vaccine manufacturing. Lipoid GmbH dominates German pharmaceutical-grade lecithin refining with decades of solvent-free process specialization.
Lipids comprise a structurally diverse class of hydrophobic or amphiphilic organic molecules including phospholipids, sterols, triglycerides, and fatty acids, typically characterized by hydrocarbon chain lengths of 12 to 24 carbons with varying degrees of unsaturation. Their primary industrial purpose centers on emulsification, membrane formation, and active ingredient solubilization across food, pharmaceutical, and cosmetic matrices. Phospholipids command premium margins in pharmaceutical applications where purity grades exceed 99% for parenteral use. Fatty acids face commoditization pressure from Southeast Asian palm and coconut oil feedstock competition. Sterols extract value from pharmaceutical cholesterol demand and nutraceutical phytosterol heart-health positioning.
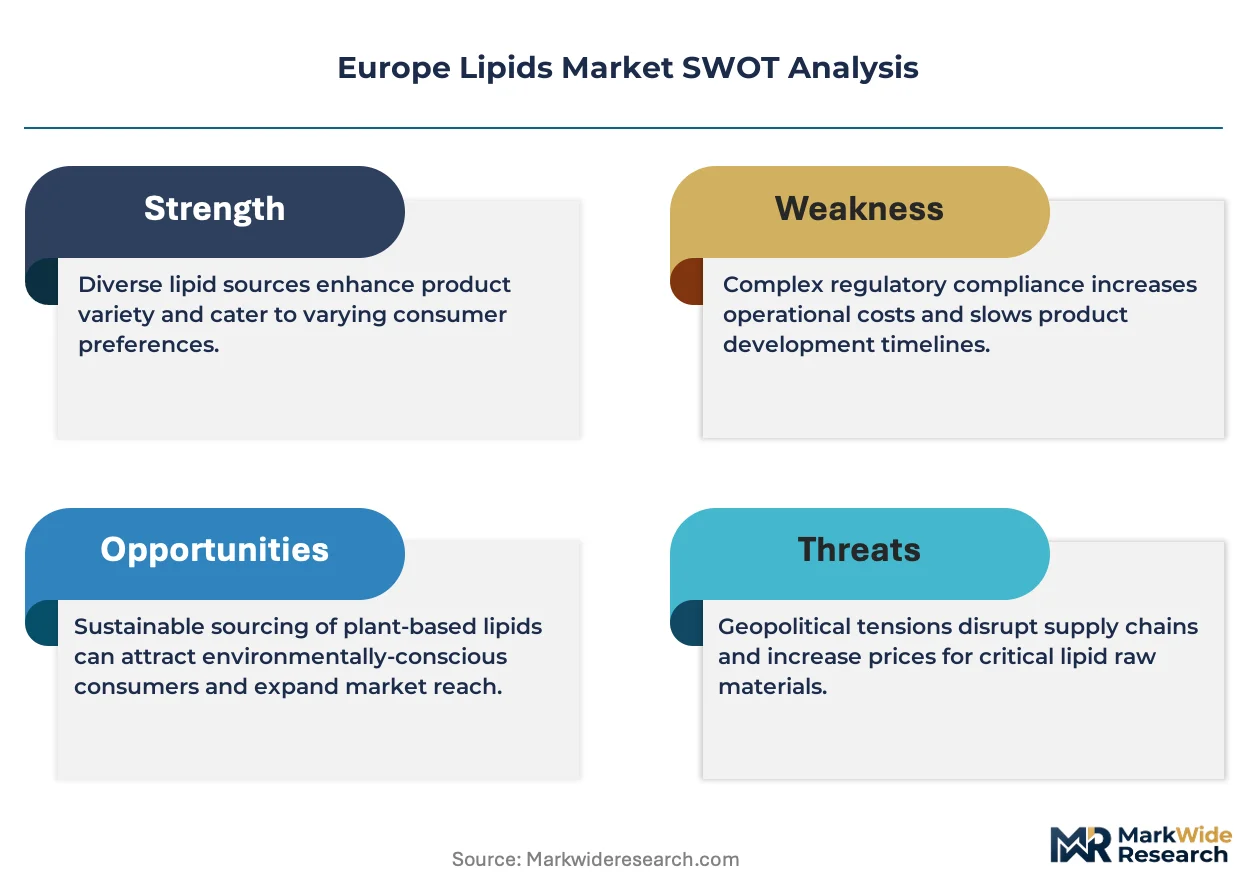
EMA's pharmaceutical excipient guidelines and EFSA's novel food safety assessments shape lipid ingredient market access timelines across EU member states. REACH registration requirements for imported lipid feedstocks add compliance layers that favor European-based refining capacity. The EU Green Deal's Farm to Fork strategy redirects agricultural subsidy flows toward oilseed crops with favorable fatty acid profiles. Stakeholders must monitor ECHA's evolving bioaccumulation criteria for long-chain saturated lipids that could restrict cosmetic and food applications without toxicological re-evaluation.
Market Dynamics
The EU Green Deal's bio-based chemical mandates are forcing a feedstock pivot across European lipid refiners, accelerating capital redeployment from petrochemical-derived processes toward plant-based extraction and enzymatic conversion technologies.
Growth Catalysts
- Pharmaceutical-grade phospholipid demand:mRNA vaccine manufacturing in Germany and France requires 99%-plus purity lecithin for lipid nanoparticle formulations, pulling investment into solvent-free refining capacity.
- REACH registration:Compliance requirements for imported feedstocks favor domestic refining infrastructure, protecting European producers from Southeast Asian commodity competition.
- Farm to Fork subsidies:Agricultural support flows now prioritize oilseed crops with optimized fatty acid profiles, securing regional feedstock supply for specialty lipid production.
Market Restraints
- Palm oil price volatility:Malaysian and Indonesian feedstock costs swing with weather patterns and export duties, compressing margins on standard-grade fatty acid derivatives.
- University chemistry program contraction:Specialized lipid formulation expertise is disappearing from academic institutions across France, Italy, and Spain, narrowing the talent pipeline for complex drug delivery development.
- ECHA bioaccumulation review:Evolving criteria for long-chain saturated lipids threaten cosmetic and food application approvals without costly toxicological re-evaluation.
Strategic Opportunities
- Central European biorefinery expansion:Poland and Hungary offer underutilized oilseed processing infrastructure convertible to pharmaceutical-grade lipid production with moderate capital investment.
- Green chemistry procurement mandates:EU public sector purchasing rules increasingly require bio-based content, creating guaranteed offtake channels for plant-derived emulsifiers and surfactants.
- Continuous processing convergence:Integration of membrane filtration with supercritical CO2 extraction reduces solvent use and batch-to-batch variation, appealing to cosmetic formulators seeking supply security.
Industry Challenges
- EMA excipient qualification timelines:Novel lipid ingredients face 18-to-24-month approval cycles for parenteral use, delaying revenue recognition and freezing formulation innovation budgets.
- Multi-site integration complexity:Consolidating batch records across legacy plants in different member states strains quality management systems during post-merger rationalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Lipids Market |
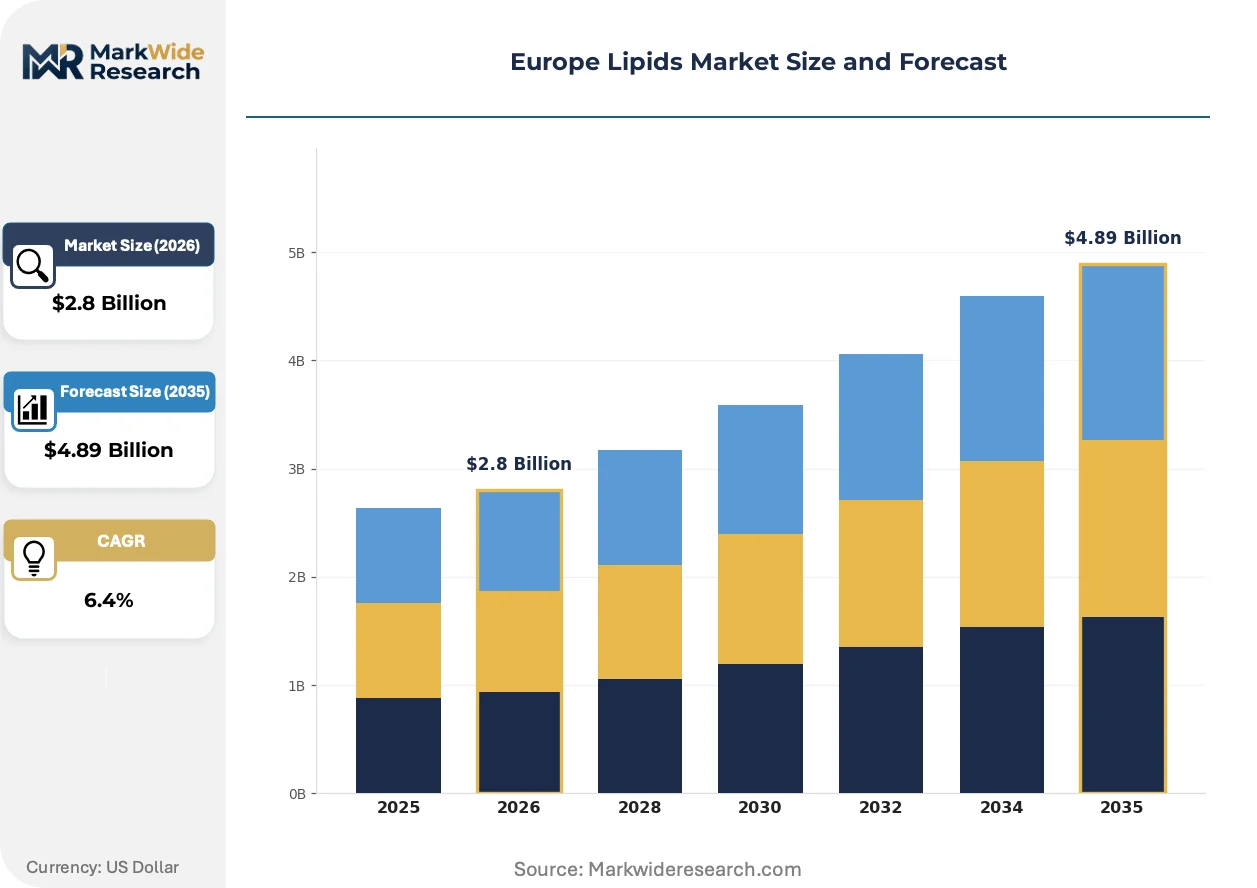
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phospholipids, Sterols, Triglycerides, Fatty Acids Application: Food & Beverages, Pharmaceuticals, Cosmetics, Nutraceuticals End User: Food Manufacturers, Personal Care Brands, Pharmaceutical Companies, Dietary Supplement Providers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, BASF SE, Koninklijke DSM N.V., Kerry Group plc, Evonik Industries AG, Merck KGaA, Croda International PLC, Lipoid GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Lipids Market Shifts & Advancements
Enzymatic interesterification and precision fermentation are displacing conventional chemical processing, while regulatory pressure on carbon intensity reshapes supplier selection criteria across pharmaceutical and personal care procurement functions.
Phospholipid production technology is bifurcating between high-purity chromatographic separation for injectable drug delivery and cost-optimized degumming for food emulsification. German pharmaceutical contractors are adopting the former at accelerated pace to secure mRNA supply chain qualification. This split is compressing mid-tier producers unable to serve either extreme, forcing strategic repositioning toward captive pharmaceutical relationships or commodity food additive volumes.
EFSA's novel food safety assessments now require comprehensive metabolomic profiling for lipid ingredients derived from new biological sources, extending market access timelines by 12 to 18 months. Industrial consequence includes frozen investment in algal and microbial lipid platforms until regulatory precedents clarify. Early movers in Dutch and Danish fermentation startups are absorbing these costs to establish first-mover dossier advantages for post-2030 applications.
Cosmetic brand procurement departments are consolidating supplier panels from twelve-plus vendors to three-to-four strategic partners with integrated sustainability certification. This concentration is displacing spot-market purchasing for commodity fatty acids and sterols. The shift is most visible in French and Italian luxury skincare manufacturing, where LCA-documented supply chains now command 15-to-20 percent price premiums over uncertified alternatives.
Europe Lipids Market Segmentation
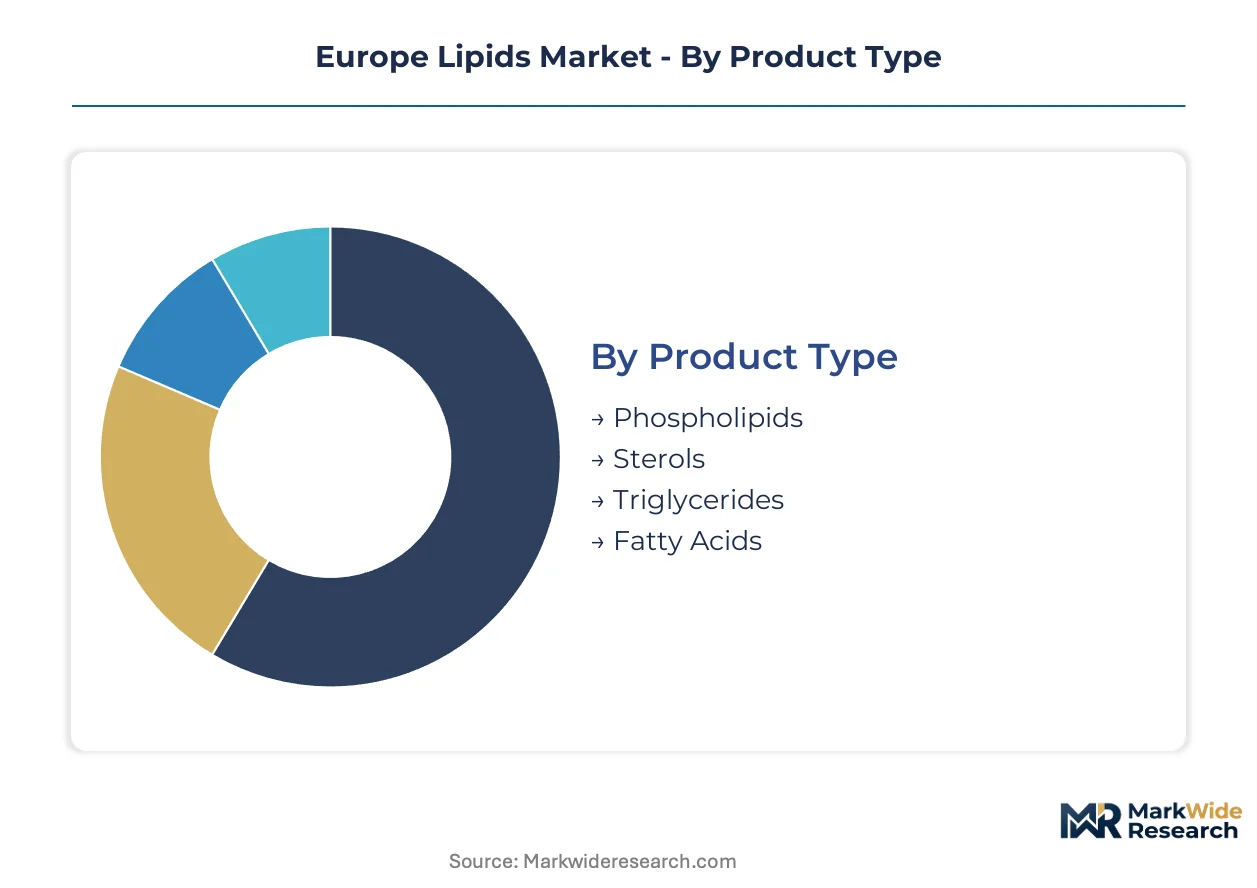
Regulatory purity thresholds fragment the Europe Lipids Market into technically distinct tiers. EMA pharmaceutical guidelines and EFSA novel food assessments create non-overlapping specification bands that reshape supplier economics.
Product Type:
EMA pharmaceutical guidelines enforce 99%-plus purity thresholds for parenteral phospholipids, while EFSA novel food assessments apply distinct safety benchmarks for sterol and fatty acid ingredients.
- Phospholipids:Amphiphilic molecules with glycerophosphate backbones and two fatty acid chains, typically 16 to 20 carbons. Germany's Ruhr industrial cluster concentrates demand for solvent-free refined lecithin serving mRNA lipid nanoparticle manufacturing. REACH registration requirements protect domestic refining capacity from Southeast Asian import competition.
- Sterols:Cyclopentanoperhydrophenanthrene ring structures including cholesterol and plant-derived phytosterols. Pharmaceutical cholesterol demand from French injectable drug manufacturers combines with heart-health positioning in Italian nutraceutical formulations. ECHA bioaccumulation review threats hang over long-chain saturated variants.
- Triglycerides:Glycerol esters with three fatty acids, primary energy storage lipids in biological systems. Food emulsification applications in Spain and Poland absorb standard-grade volumes.
- Fatty Acids:Aliphatic carboxylic acids with chain lengths from 12 to 24 carbons, saturated or unsaturated. Malaysian and Indonesian palm oil feedstock competition compresses margins on commodity derivatives.
Triglycerides handle the majority of throughput; phospholipids are the fastest mover on share.
Application:
Cost tier differentiation separates pharmaceutical-grade premiums from food-grade commodity economics across European formulation markets.
- Pharmaceuticals:Lipid nanoparticle delivery systems for mRNA therapeutics and parenteral emulsions. BASF SE's Ludwigshafen integrated site and Croda International PLC's UK facilities anchor high-purity phospholipid supply. EMA excipient qualification timelines extend 18-to-24 months, freezing innovation budgets.
- Cosmetics:Emollients, surfactants, and liposome carriers in skincare and haircare. French and Italian luxury manufacturers now demand LCA-documented supply chains with 15-to-20 percent price premiums over uncertified alternatives.
- Food & Beverages:Emulsifiers, texturizers, and nutritional fortification in processed foods. EFSA novel food safety assessments extend market access timelines for algal and microbial lipid platforms.
- Nutraceuticals:Phytosterol heart-health supplements and omega-3 fatty acid formulations. Dutch and Danish fermentation startups absorb regulatory costs to establish first-mover dossier advantages.
Food & Beverages handles the majority of throughput; pharmaceuticals is expanding most quickly.
End User:
Customer type concentration varies by volume commitment, technical specification tolerance, and supply chain certification requirements.
- Pharmaceutical Companies:mRNA vaccine contractors in Germany and France require batch-to-batch consistency documented through chromatographic purity certificates. Lipoid GmbH dominates German pharmaceutical-grade lecithin refining with decades of solvent-free process specialization.
- Food Manufacturers:Industrial-scale emulsifier procurement from Central European oilseed processors. Poland and Hungary offer underutilized infrastructure convertible to pharmaceutical-grade production.
- Personal Care Brands:Cosmetic procurement departments consolidate supplier panels from twelve-plus vendors to three-to-four strategic partners with integrated sustainability certification.
- Dietary Supplement Providers:Phytosterol and omega-3 capsule formulation with lower purity thresholds than pharmaceutical applications.
Food manufacturers handle the majority of throughput; pharmaceutical companies are climbing the fastest.
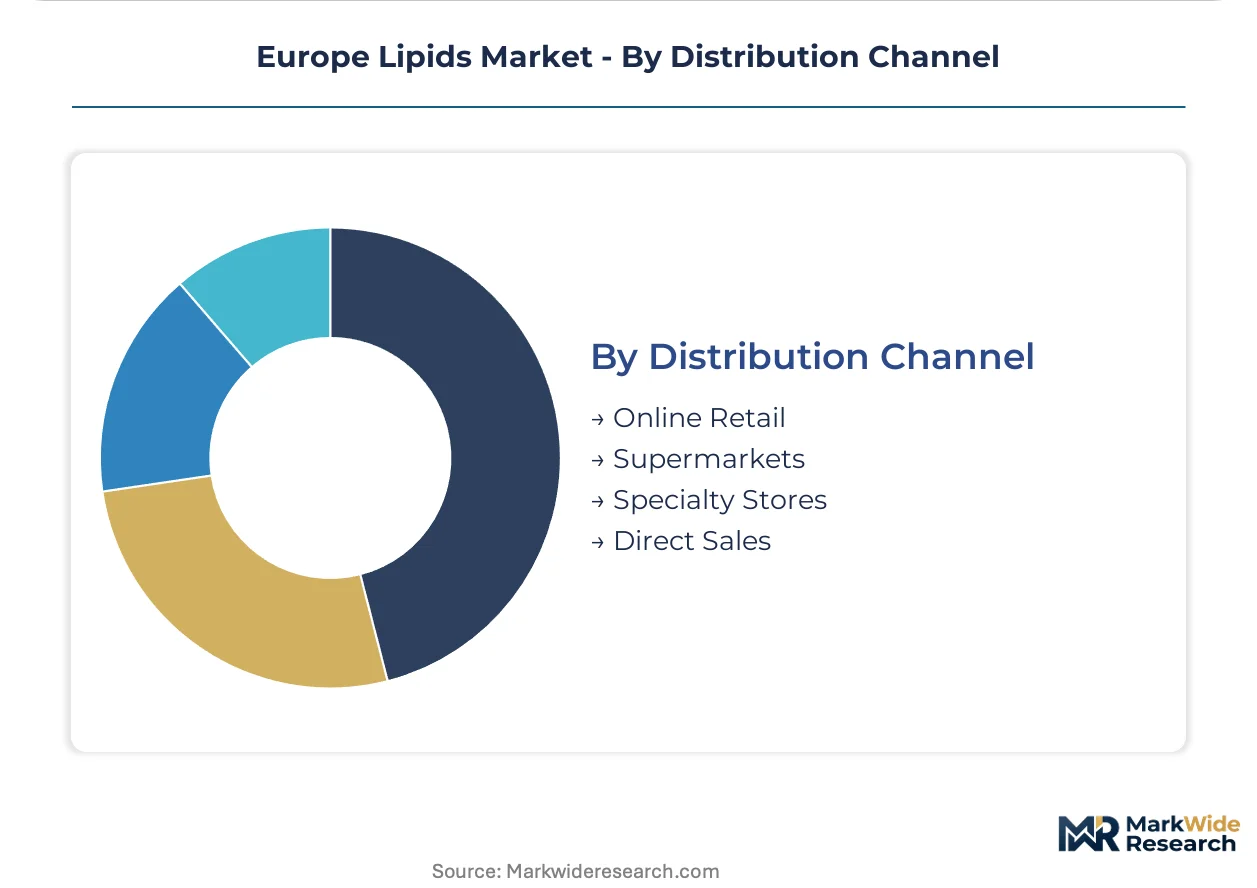
Distribution Channel:
Supply concentration in specialty chemical distribution creates divergent margin structures versus direct manufacturer relationships.
- Direct Sales:Long-term supply agreements between lipid refiners and pharmaceutical or cosmetic manufacturers. Captive relationships protect formulation knowledge and secure volume commitments.
- Specialty Stores:Nutraceutical and cosmetic ingredient distributors serving mid-tier formulators without direct refinery access.
- Online Retail:Small-volume specialty lipid sales to research institutions and artisanal cosmetic producers.
- Supermarkets:Consumer-facing omega-3 and phytosterol supplement products with minimal technical differentiation.
Direct sales handles the majority of throughput; specialty stores are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA pharmaceutical guidelines anchor demand concentration in Germany, where lipid nanoparticle manufacturing for mRNA therapeutics drives regional investment. The EU Green Deal's bio-based mandates reshape feedstock sourcing across member states, redirecting agricultural subsidies toward oilseed crops with optimized fatty acid profiles.
Germany
mRNA vaccine manufacturing in the Ruhr industrial cluster pulls solvent-free phospholipid refining capacity expansion. REACH registration requirements protect domestic refiners from Southeast Asian import competition. BASF SE's Ludwigshafen integrated site sustains captive production for pharmaceutical clients requiring 99%-plus purity grades.
France
Injectable drug manufacturers in the Paris-Saclay biocluster demand pharmaceutical-grade cholesterol for parenteral emulsions. ANSM enforces excipient qualification timelines extending 18-to-24 months for novel lipid ingredients. French luxury skincare manufacturers now pay 15-to-20 percent premiums for LCA-documented fatty acid supply chains.
United Kingdom
Croda International PLC anchors high-purity lipid supply for mRNA vaccine manufacturing from UK facilities. EFSA novel food safety assessments govern sterol and omega-3 ingredient market access timelines. The East Midlands oilseed processing corridor offers convertible infrastructure for pharmaceutical-grade lipid production.
Netherlands
Dutch fermentation startups absorb regulatory costs to establish first-mover dossier advantages for algal and microbial lipid platforms. ECHA bioaccumulation review criteria threaten cosmetic applications for long-chain saturated lipids. The Rotterdam port cluster handles Southeast Asian palm oil feedstock imports facing price volatility from Malaysian and Indonesian export duties.
Poland
Underutilized oilseed processing infrastructure in Central Europe offers conversion pathways to pharmaceutical-grade lipid production. EU Farm to Fork agricultural subsidies now prioritize regional oilseed crops with favorable fatty acid profiles. Poznań-based processors benefit from proximity to German pharmaceutical demand while operating below Western European cost structures.
Europe Lipids Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European lipid market. The vendor base separates into integrated chemical conglomerates with captive pharmaceutical relationships, mid-scale specialists with decades of process expertise, and commodity refiners exposed to Southeast Asian feedstock competition. Three archetypes dominate: solvent-free refining specialists serving parenteral drug delivery, integrated petrochemical players pivoting toward bio-based feedstocks, and regional oilseed processors capturing Farm to Fork subsidy flows. Competitive moves concentrate on capacity expansion for pharmaceutical-grade phospholipids and strategic partnerships securing mRNA supply chain qualification.
Within the integrated chemical tier, BASF SE and Evonik Industries AG exemplify players leveraging existing infrastructure to serve pharmaceutical clients with captive production models. Among specialists with decades of process expertise, Lipoid GmbH occupies a position representing solvent-free lecithin refining capabilities developed over multiple decades. Croda International PLC sits within the high-purity lipid segment, anchoring UK-based supply for mRNA manufacturing applications. These three companies illustrate how geographic proximity to pharmaceutical demand clusters, combined with regulatory compliance infrastructure, determines competitive positioning in a market where EMA excipient guidelines create significant barriers to entry.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| BASF SE |
| Koninklijke DSM N.V. |
| Kerry Group plc |
| Evonik Industries AG |
| Merck KGaA |
| Croda International PLC |
| Lipoid GmbH |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between German pharmaceutical contractors and Ruhr-based refiners lock in solvent-free phospholipid supply while anchoring price visibility against Malaysian palm oil volatility. These agreements insulate mRNA vaccine manufacturers from spot-market swings in feedstock costs.
Pricing Analysis
Phospholipid prices in Germany command 15-to-20 percent premiums over Polish standard-grade equivalents, reflecting EMA purity certification and chromatographic batch documentation. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and food-grade levels separates parenteral lecithin from emulsifier commodities. Cost compression in fatty acid derivatives is intensifying because Indonesian export duty fluctuations feed directly into refinery margin calculations. Food manufacturers exhibit highest price sensitivity, while pharmaceutical contractors absorb premiums for supply security.
Supply Chain Analysis
Rotterdam port handling of Southeast Asian palm oil feedstock creates a chokepoint exposing European refiners to Malaysian weather disruptions and Indonesian policy shifts. Supply concentrates in Germany for pharmaceutical-grade phospholipids, the Netherlands for algal lipid fermentation pilots, and Poland for oilseed crushing infrastructure. Raw material dependencies span Malaysian crude palm oil, Ukrainian sunflower seed, and rapeseed from EU Farm to Fork subsidized acreage. Single-source vulnerability runs through Rotterdam's bulk liquid storage terminals. Distribution runs through direct refinery-to-pharma relationships for high-purity grades, with specialty chemical distributors handling mid-tier cosmetic volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
mRNA lipid nanoparticle demand is reshaping European phospholipid economics, with EMA excipient guidelines creating a regulatory moat that accelerates incumbent consolidation and freezes out unqualified competitors.
For Market Incumbents: Compound solvent-free refining expertise into captive pharmaceutical relationships before Polish and Hungarian infrastructure conversions reach qualification maturity. BASF SE's Ludwigshafen integration model demonstrates how backward integration into oilseed processing secures margin control against Southeast Asian feedstock volatility. Prioritize EMA dossier maintenance over cosmetic-grade volume expansion. For New Entrants and Emerging Players: Lead with enzymatic interesterification capabilities serving French and Italian luxury cosmetic manufacturers demanding LCA-documented supply chains. Polish oilseed processors offer the most penetrable entry point, convertible to pharmaceutical-grade production at moderate capital intensity. Pursue green chemistry procurement mandates as guaranteed offtake channels. For Investors and Strategic Acquirers: Solvent-free lecithin specialists with decades of process expertise and existing EMA qualification represent the most defensible acquisition targets in a market where regulatory timelines stretch 18-to-24 months. Long-term viability hinges on positioning for post-2030 algal and microbial lipid platforms as EFSA precedents clarify. Watch ECHA bioaccumulation review outcomes as the signal for cosmetic application restrictions that would redirect investment toward unsaturated lipid variants.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Ruhr-based solvent-free refining additions secure mRNA vaccine supply chain qualification for German pharmaceutical contractors. |
| Backward Integration | Oilseed crushing control insulates margins from Malaysian and Indonesian export duty volatility affecting feedstock costs. |
| Green Manufacturing Transition | Enzymatic conversion technologies align with EU Green Deal bio-based chemical mandates and unlock public procurement channels. |
| Long-term Supply Agreement | Captive relationships with mRNA manufacturers protect formulation knowledge and freeze out unqualified competitors. |
| Joint Venture | Polish and Hungarian infrastructure partnerships convert underutilized oilseed processing to pharmaceutical-grade lipid production. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical formulation scientists, cosmetic procurement directors, oilseed processing plant managers, and specialty chemical distribution executives and refined through secondary validation against EMA excipient guidelines, EFSA novel food safety assessments, REACH registration databases, and EU Farm to Fork subsidy flow records. Bottom-up volume estimates from refinery capacity utilization and top-down demand segmentation from end-use application analysis were triangulated to constrain forecast variance.
Variance decomposition across product type, application tier, end-user concentration, and regional production hub dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Industry-specific forecast inputs incorporated mRNA vaccine manufacturing capacity expansion timelines and ECHA bioaccumulation review status.
Forecasts assume regulatory continuity in EMA pharmaceutical guidelines and EFSA novel food safety regimes; material policy shifts would require re-modeling of market access timelines and purity threshold economics. Practitioners should keep alternative scenarios live as EU Green Deal bio-based mandate enforcement intensity and Southeast Asian palm oil export policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Formate Brine Market
Bulk Chemicals
Europe Calcium Nitrate Market
Bulk Chemicals
Alkali Metal Hydroxides Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Sodium Bisulfite Market
Bulk Chemicals
Europe Caustic Potash Market
Bulk Chemicals
Soda Ash Market
Bulk Chemicals
Cobalt Acetate Crystals Market
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
Sodium Bicarbonate Market
Bulk Chemicals
M, P-Cresol Market
Bulk Chemicals
Diketene Market
Bulk Chemicals
Isophorone Market
Bulk Chemicals
USA and Canada Potassium Sulfate Market
Bulk Chemicals
Bio-Succinic Acid Market
Bulk Chemicals
Calcium Hydrogen Sulphite Market