
 Hydro-Processing Catalysts Market | 2026-2036
Hydro-Processing Catalysts Market Size, Share, and Industry Trends Forecast 2026-2036
Hydro-Processing Catalysts Market Foresight
IMO 2020 is hardening the cost-of-entry calculus for hydro-processing catalyst suppliers serving marine fuel desulfurization. Albemarle Corporation leverages its bromine and lithium supply chains to secure critical precursor materials for NiMo catalyst systems. Haldor Topsoe A/S anchors its position through proprietary BRIM technology for high-activity hydrotreating applications. Johnson Matthey PLC differentiates via advanced Pd-based catalyst formulations targeting renewable diesel saturation units.
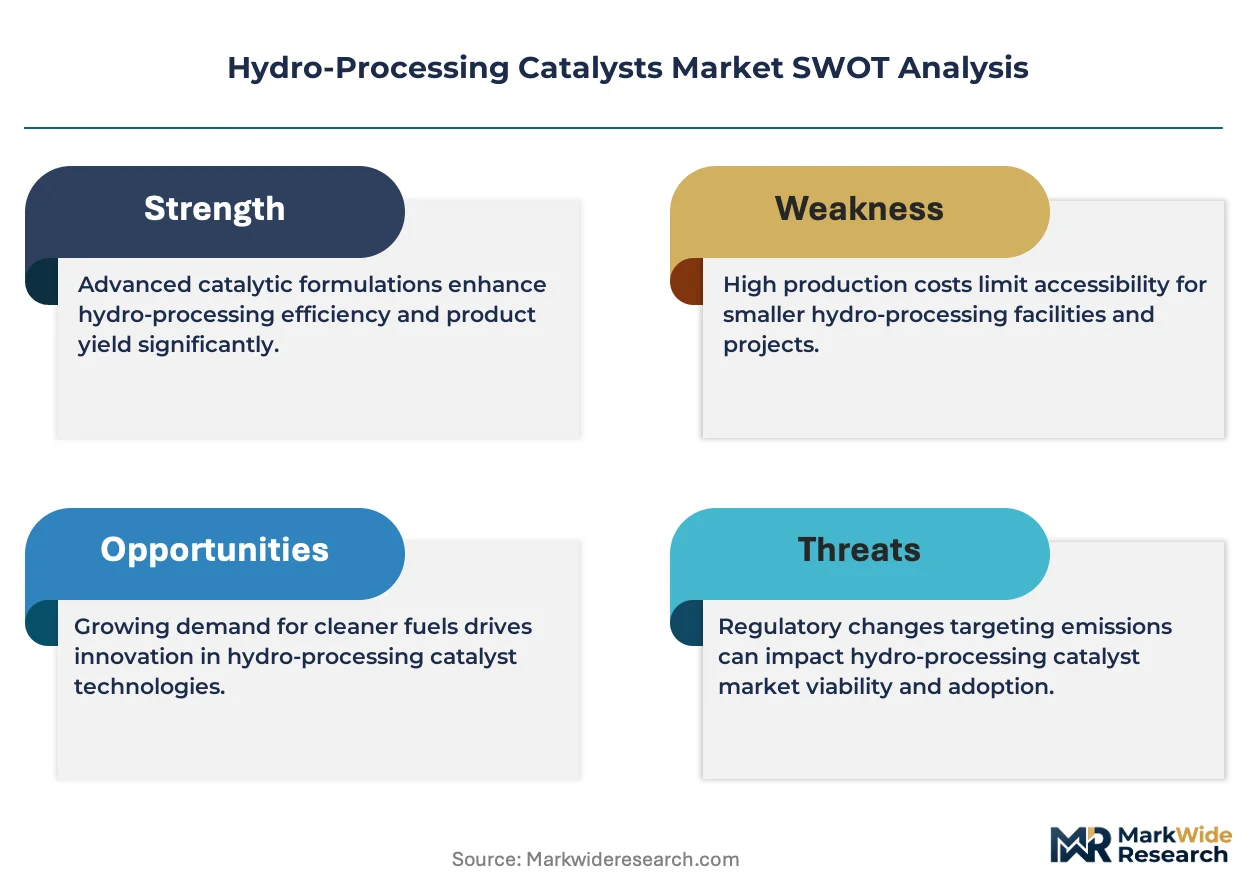
Hydro-processing catalysts are heterogeneous materials—typically alumina-supported combinations of cobalt-molybdenum, nickel-molybdenum, or palladium—engineered to remove sulfur, nitrogen, and oxygen heteroatoms while saturating aromatic rings under hydrogen pressure at 300–450°C and 30–130 bar. NiMo formulations dominate hydrotreatment applications where deep desulfurization of vacuum gas oil and diesel streams commands premium pricing. Fixed-bed technology occupies the majority of installed refinery capacity, though fluidized-bed systems are gaining traction in biorefinery hydroprocessing where feedstock variability demands superior heat and mass transfer.
The US EPA enforces Tier 3 gasoline sulfur standards that mandate 10 parts per million maximum, directly sustaining catalyst replacement cycles in North American refineries. REACH registration requirements in Europe constrain catalyst precursor imports while the EU Green Deal accelerates biorefinery catalyst qualification pathways. Stakeholders must monitor how renewable feedstock co-processing mandates in multiple jurisdictions reshape catalyst deactivation profiles and regeneration economics.
Market Dynamics
Refinery consolidation along the US Gulf Coast is concentrating procurement power among fewer buyers, forcing catalyst suppliers to absorb regeneration costs and extend performance guarantees to maintain offtake volumes.
Growth Catalysts
- IMO 2020 sulfur cap:Marine fuel desulfurization mandates drive replacement cycles for high-activity NiMo catalyst systems in residual hydrotreaters.
- Renewable diesel saturation:Biorefinery operators deploy Pd-based catalysts to hydrogenate triglycerides and meet ASTM D975 specifications.
- US Gulf Coast refining corridor:Capacity expansions at Port Arthur and Baytown complexes sustain bulk orders for deep hydrodesulfurization units.
Market Restraints
- Molybdenum price volatility:Concentrated mining in Chile and Peru exposes NiMo catalyst producers to input cost swings exceeding 30% annually.
- REACH registration friction:ECHA compliance costs block smaller Chinese precursor suppliers from European market entry.
- Catalyst lifetime extension:Improved regeneration protocols at ExxonMobil and Shell refineries compress replacement frequency by 15-20%.
Strategic Opportunities
- India's BS-VI fuel standards:Reliance Industries and Indian Oil Corporation seek qualified hydrotreating catalyst partners for 2025-2027 refinery upgrades.
- Co-processing mandates:EU Green Deal incentives reward refineries blending 20-30% renewable feedstocks, requiring novel catalyst deactivation management.
- Performance-based contracting:Catalyst suppliers pilot sulfur-removal-as-a-service models with guaranteed ppm outcomes rather than volume sales.
Industry Challenges
- Regeneration technician scarcity:Specialized knowledge of ex-situ oxidative regeneration for spent NiMo catalysts concentrates at Haldor Topsoe and Albemarle service centers.
- Biorefinery feedstock variability:Phosphorus and alkali metal contaminants in waste cooking oils accelerate catalyst poisoning beyond petroleum-derived deactivation profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydro-Processing Catalysts Market |
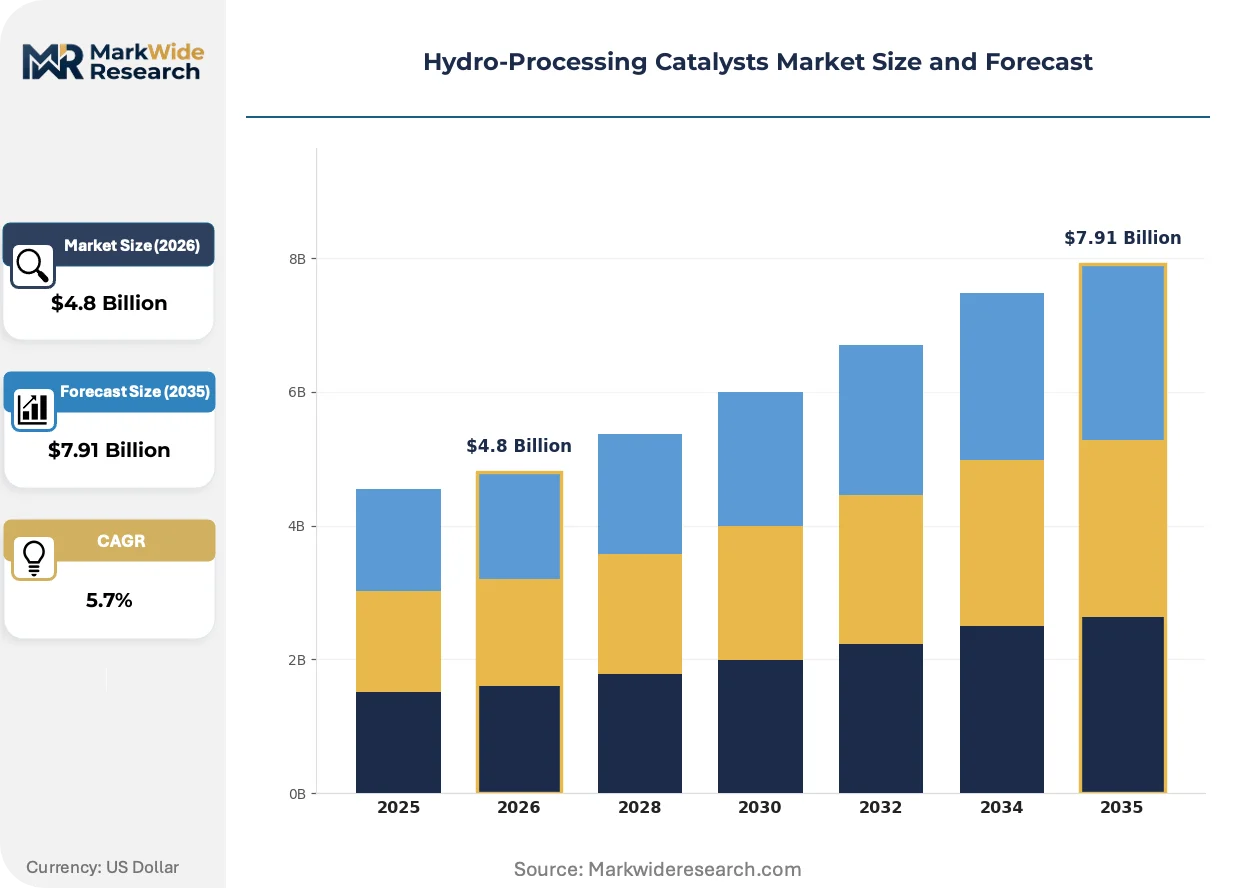
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CoMo, NiMo, Pd, Others Application: Hydrotreatment, Hydrocracking, Desulfurization, Saturation End User: Refineries, Petrochemical Plants, Chemical Manufacturers, Biorefineries Technology: Fixed Bed, Fluidized Bed, Moving Bed, Others |
| Companies Covered | Honeywell UOP, Johnson Matthey PLC, BASF SE, ExxonMobil Chemical Company, W. R. Grace & Co., Shell Catalysts & Technologies, Albemarle Corporation, Axens SA, Haldor Topsoe A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydro-Processing Catalysts Market Shifts & Advancements
Digital process control and advanced materials science are compressing the gap between laboratory catalyst qualification and commercial refinery deployment.
Zeolite-Y supported NiMo catalysts are integrating mesoporous architecture to improve diffusion of bulky sulfur molecules in vacuum gas oil hydrotreatment. European refiners at Rotterdam and Antwerp hubs pilot these formulations to achieve 15 ppm sulfur targets without reactor revamp. The technology is integrating real-time optimization algorithms that adjust hydrogen partial pressure based on feedstock quality fluctuations.
EPA Tier 3 gasoline standards mandate 10 ppm sulfur maximum, sustaining replacement demand for fixed-bed hydrotreaters at US Midwest refineries. The regulation forces catalyst suppliers to guarantee 48-month cycle lengths rather than historical 36-month benchmarks. California CARB amendments extend these requirements to capture winter gasoline blends, tightening specifications for benzene saturation co-catalysts.
Refinery procurement teams now unbundle catalyst supply from technical service contracts, sourcing NiMo formulations from low-cost Asian producers while retaining Albemarle or Haldor Topsoe for startup supervision. This bifurcation compresses supplier margins on commodity hydrotreating grades while preserving premium pricing for proprietary BRIM or ASCENT technology licenses. The shift is most visible among independent US refiners lacking captive catalyst research capabilities.
Hydro-Processing Catalysts Market Segmentation
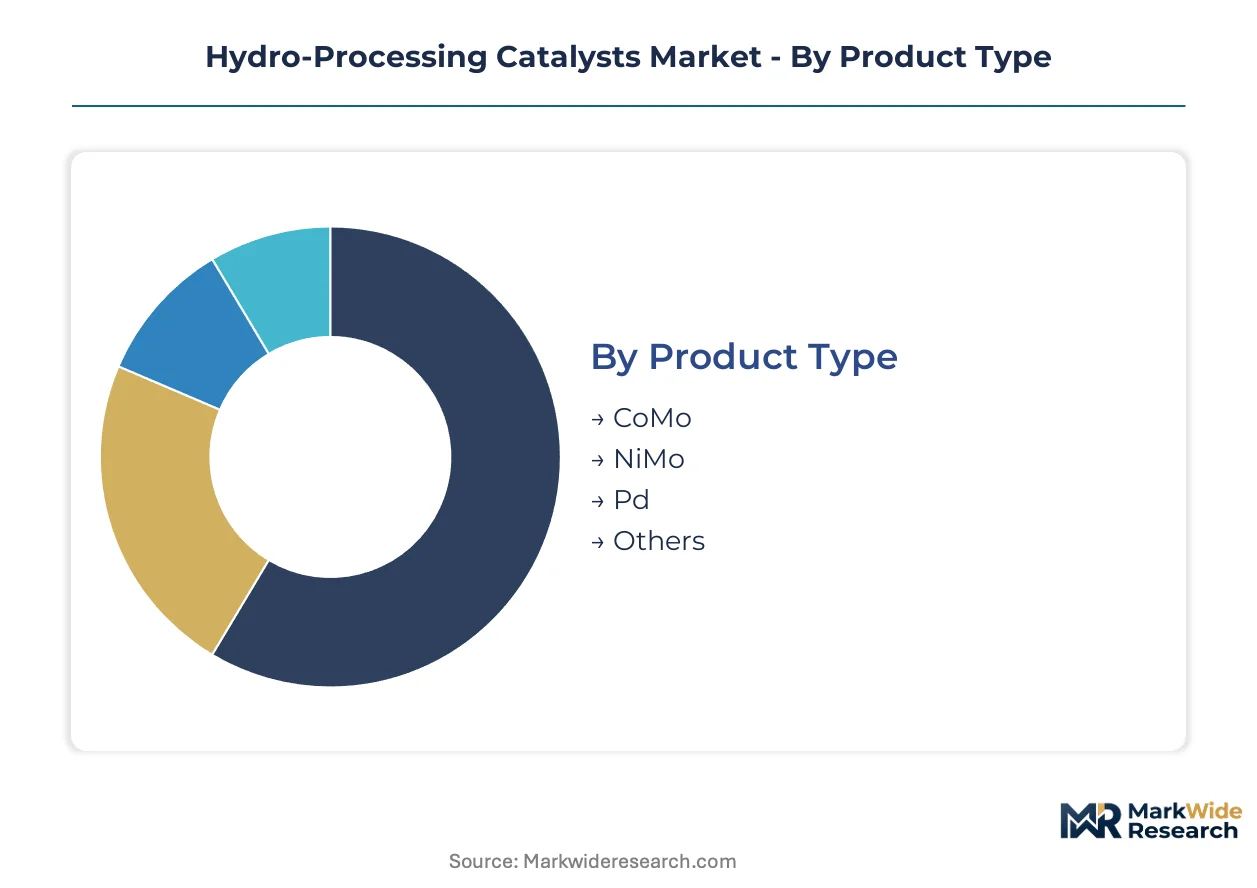
Catalyst selection in hydro-processing hinges on feedstock sulfur content, hydrogen partial pressure requirements, and regeneration economics. Refinery operators segment procurement by active metal loading, support material porosity, and guaranteed cycle length rather than commodity chemistry alone.
Product Type:
Active metal composition determines hydrogenation activity, sulfur tolerance, and poison resistance across refinery process trains.
- NiMo:Nickel-molybdenum formulations on gamma-alumina supports deliver superior hydrogenolysis activity for deep desulfurization of vacuum gas oil and diesel streams. Demand concentrates at US Gulf Coast refineries processing high-sulfur Maya and Venezuelan heavy crudes where 10 ppm sulfur targets require maximum hydrodesulfurization activity.
- CoMo:Cobalt-molybdenum systems dominate straight-run naphtha and distillate hydrotreating where moderate hydrogenation suffices and catalyst cost sensitivity runs higher. European refiners at Rotterdam and Antwerp hubs favor these formulations for gasoline pool sulfur reduction under EU fuel quality directives.
- Pd:Palladium catalysts enable selective saturation of triglycerides and fatty acid methyl esters in renewable diesel units.
- Others:Platinum and nickel-tungsten variants serve specialty hydrocracking and dewaxing applications.
Volume sits with CoMo for bulk hydrotreating; growth tilts toward NiMo for residual upgrading and Pd for biorefinery saturation.
Application:
Process chemistry requirements separate catalyst specifications by heteroatom removal depth and aromatic saturation intensity.
- Desulfurization:Deep hydrodesulfurization of gas oils and residuum streams consumes the majority of NiMo catalyst volume. EPA Tier 3 and IMO 2020 sulfur caps sustain replacement cycles at US and Asian refineries processing high-sulfur crude slates.
- Hydrotreatment:Straight-run distillate upgrading represents the baseline application with established catalyst regeneration protocols.
- Hydrocracking:Bifunctional catalysts combining acidic zeolite supports with hydrogenation metals convert heavy feeds into middle distillates and naphtha.
- Saturation:Renewable diesel producers deploy Pd-based systems to hydrogenate olefins and meet cold-flow specifications.
Desulfurization commands the largest installed base; saturation is climbing the fastest on biorefinery buildouts.
End User:
Scale economies and technical capabilities divide procurement patterns between integrated majors and specialty operators.
- Refineries:Petroleum refineries processing crude oil fractions represent the dominant consumption channel with continuous catalyst replacement schedules tied to turnaround cycles.
- Biorefineries:Renewable fuel producers require modified catalyst formulations tolerant of oxygenated feedstocks and phosphorus contaminants.
- Petrochemical Plants:Steam cracker feed pretreatment units demand high-activity hydrotreating to protect ethylene furnace coils.
- Chemical Manufacturers:Specialty chemical producers use smaller catalyst volumes for intermediate purification.
Refineries anchor current demand; biorefineries are gaining share fastest on renewable diesel capacity additions.
Technology:
Reactor configuration dictates catalyst particle size, shape, and mechanical strength requirements.
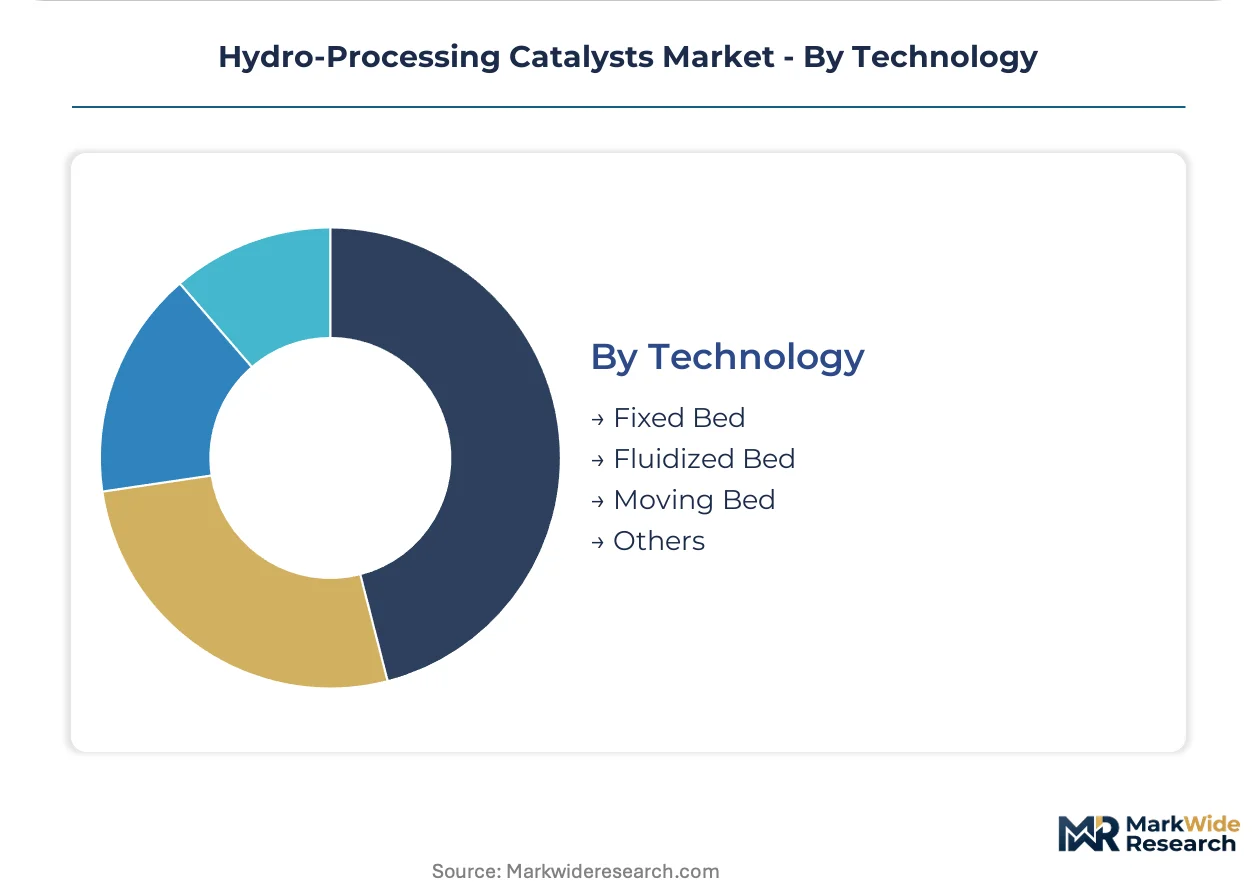
- Fixed Bed:Trickle-flow fixed-bed reactors occupy the majority of installed refinery capacity with established catalyst loading and unloading procedures. US Gulf Coast complexes at Port Arthur and Baytown rely on these systems for deep hydrodesulfurization with 48-month guaranteed cycle lengths.
- Fluidized Bed:Ebullated-bed and slurry-phase systems enable processing of heavy residuum and biocrude feeds with superior heat transfer.
- Moving Bed:Continuous catalyst replacement reactors allow online addition and withdrawal for residuum processing.
- Others:Structured reactors and membrane-assisted systems remain developmental.
Fixed bed holds the installed base; fluidized bed is expanding most quickly on biorefinery and heavy oil upgrading projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized refining corridors and free-trade zones concentrate hydro-processing catalyst procurement. Tax incentives for clean fuel production accelerate capacity clustering. Regulatory sulfur caps in major consuming markets sustain replacement demand cycles.
United States
EPA Tier 3 gasoline standards mandate 10 ppm sulfur maximum, sustaining catalyst replacement at Midwest refineries. The US Gulf Coast refining corridor concentrates demand at Port Arthur and Baytown complexes. Independent refiners unbundle catalyst supply from technical service contracts to compress procurement costs.
China
National fuel quality upgrades to China VI standards drive hydrotreating capacity additions at Sinopec and PetroChina facilities. MIIT emission regulations enforce sulfur reduction timelines for coastal refineries. The Yangtze River Delta and Shandong Peninsula host the majority of catalyst qualification programs for domestic suppliers.
India
BS-VI fuel standards implementation forces refinery upgrades at Reliance Industries and Indian Oil Corporation complexes. BIS certification requirements constrain imported catalyst formulations until local testing completes. The Gujarat refining belt and Maharashtra industrial corridor concentrate hydrotreater revamp activity through 2027.
Germany
REACH registration requirements block non-compliant catalyst precursor imports from Asian suppliers. The EU Green Deal accelerates biorefinery catalyst qualification for renewable diesel co-processing. The Rhine-Ruhr industrial region and Hamburg refining hub pilot mesoporous NiMo formulations for deep desulfurization.
Saudi Arabia
Saudi Aramco downstream integration sustains bulk catalyst orders for residuum hydrotreaters at Yanbu and Jubail complexes. The national petroleum regulator enforces Euro 5-equivalent sulfur specifications for domestic fuel pools. The Eastern Province refining cluster anchors Middle East demand for high-activity NiMo systems.
Hydro-Processing Catalysts Market Competitive Landscape
US and European producers anchor one tier; Asian specialists hold cost-advantaged positions in commodity formulations. The market structures around technology licensors, integrated chemical conglomerates, and regional fabrication specialists. Archetypes span proprietary BRIM-style technology holders, backward-integrated metal suppliers, and regeneration service providers. Competitive moves concentrate on performance-based contracting pilots and captive precursor supply chain control.
Among diversified chemical conglomerates, BASF SE and Albemarle Corporation exemplify backward-integrated archetypes with captive access to critical metal precursors. Johnson Matthey PLC occupies a position within the specialty formulation tier, representing advanced precious-metal catalyst suppliers targeting renewable diesel saturation applications. Haldor Topsoe A/S anchors the technology-licensing segment, exemplifying proprietary process package providers that bundle catalyst supply with reactor design expertise.
| Leading Market Players |
|---|
| Honeywell UOP |
| Johnson Matthey PLC |
| BASF SE |
| ExxonMobil Chemical Company |
| W. R. Grace & Co. |
| Shell Catalysts & Technologies |
| Albemarle Corporation |
| Axens SA |
| Haldor Topsoe A/S |
| Others |
Supply & Pricing Matrix
Refinery procurement consolidation along the US Gulf Coast is compressing catalyst replacement budgets and forcing suppliers to absorb regeneration costs within performance guarantees. This buyer-side pressure is fragmenting supplier margins across commodity NiMo formulations while preserving premium pricing for proprietary technology licenses.
Pricing Analysis
Short lead-time premiums of 15-25% apply to emergency catalyst replacements during unplanned refinery turnarounds, while spot inventory of standard CoMo grades trades at modest discounts to contracted volumes. Three-tier pricing structure across premium, standard, and economy levels separates BRIM-licensed NiMo systems from qualified Asian imports and unbranded commodity formulations. Price differentiation hinges on guaranteed cycle length and bundled technical service intensity. Cost compression in standard hydrotreating grades is intensifying because independent refiners unbundle supply from startup supervision. Independent US refiners exhibit highest price sensitivity; integrated majors with captive research capabilities show lowest.
Supply Chain Analysis
Molybdenum supply rests on concentrated mining operations in Chile and Peru, with cobalt feedstock anchored in the DRC and refined in China. Alumina support materials draw from Australian bauxite and Chinese smelter capacity, while palladium for renewable diesel applications sources from Russian and South African PGM producers. Single-source vulnerability concentrates in molybdenum disulfide precursor supply, where three producers control 70% of merchant availability. Distribution runs through catalyst loading contractors at major refining hubs, with regional fabrication specialists handling final extrusion and sulfiding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EPA Tier 3 and IMO 2020 sulfur regulations erect technical barriers that favor incumbents with proven qualification records and captive precursor supply.
For Market Incumbents: Cement market position by deepening backward integration into molybdenum and cobalt precursor refining to offset commodity price volatility, while extending performance-based contracting pilots that guarantee sulfur removal outcomes rather than catalyst volume. Threat from low-cost Asian producers penetrating standard CoMo grades demands accelerated BRIM technology licensing to independent refiners lacking in-house catalyst expertise. For New Entrants and Emerging Players: The 40-60% price gap between premium NiMo systems and unqualified Asian imports creates entry space for mid-tier formulations targeting India's BS-VI refinery upgrades and biorefinery saturation applications. White-space concentrates in renewable diesel Pd catalyst supply, where qualified producers remain scarce, and in ex-situ regeneration services for spent NiMo systems. Go-to-market should anchor on technical qualification partnerships with engineering contractors managing refinery revamp projects. For Investors and Strategic Acquirers: The window for entry favors catalyst regeneration service providers and regional fabrication specialists with established loading protocols at US Gulf Coast complexes. Long-term viability hinges on exposure to biorefinery buildouts and residuum upgrading capacity in the Middle East and India. Signal to monitor: ECHA REACH enforcement actions blocking Chinese precursor imports, which would reprice European market access for compliant holders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Refining | Captive molybdenum and cobalt supply secures margin protection against Chilean mining volatility. |
| Performance-Based Contracting Pilots | Sulfur-removal-as-a-service models shift revenue from volume to guaranteed ppm outcomes at US refineries. |
| Biorefinery Catalyst Qualification | Pd-based formulation approval for renewable diesel saturation opens fastest-growing demand segment. |
| Ex-Situ Regeneration Capacity Expansion | Specialized oxidative regeneration services capture value from extended catalyst lifecycles at Shell and ExxonMobil refineries. |
| India BS-VI Partnership Agreements | Technical collaboration with Reliance Industries and Indian Oil Corporation secures 2025-2027 refinery upgrade catalyst supply. |
Research Methodology
Independent corroboration across refinery procurement executives, catalyst technology licensors, and precious metals trading desks underwrites the qualitative findings on pricing dynamics and supply concentration. Primary interviews with plant managers at US Gulf Coast and Rotterdam-Antwerp refining complexes, supplemented by technical R&D directors at major catalyst producers, captured regeneration protocol evolution and feedstock co-processing challenges. Secondary validation drew from EPA enforcement disclosures, ECHA REACH registration databases, SEC 10-K filings by diversified chemical conglomerates, and customs data on molybdenum concentrate imports. Bottom-up catalyst volume estimates triangulated against top-down refinery capacity utilization models.
Historical reference periods anchored the forecast framework to pre-IMO 2020 baseline demand and post-implementation replacement cycle acceleration. Segmentation modeling spanned active metal composition, reactor technology configuration, and end-user scale tier across the projection horizon. CAGRs were derived from regression analysis of catalyst consumption intensity per barrel of hydrotreating capacity, incorporating assumptions on renewable diesel saturation unit buildouts and residuum processing expansions. Industry-specific inputs included biorefinery feedstock contaminant profiles affecting Pd catalyst deactivation rates.
Inputs from refinery procurement databases and precious metals market reports were available through the study window; gaps in real-time molybdenum spot pricing and confidential catalyst performance guarantees introduce uncertainty bands around supplier margin estimates. Forecasts reflect documented assumptions on regulatory sulfur cap enforcement and biorefinery co-processing mandate adoption. A small set of triggers warrants ongoing watch: ECHA REACH enforcement escalations, Chilean mining labor actions, and IMO marine fuel sulfur verification protocol changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Catalyst Carrier Market
Catalysts
Fuel Cell Catalyst Market
Catalysts
Fluid Catalytic Cracking Catalyst Market
Catalysts
North America Industrial Catalyst Market
Catalysts
Syngas to Ethylene Glycol Catalyst Market
Catalysts
Emission Control Catalyst for Marine Market
Catalysts
Secondary Reforming Catalyst Market
Catalysts
Hydrotreating Catalyst Market
Catalysts
CO2 Reforming Catalysts Market
Catalysts
North America Refining Catalysts Market
Catalysts
Platinum and Palladium Carbon Catalyst Market
Catalysts
Catalyst for Hydrogen Production from Water Electrolysis Market
Catalysts
Global Chemical Catalyst Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
Chemical Processing Catalysts Market
Catalysts
Heterogeneous Catalyst Market