

Oxalate Hydrogenation Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Oxalate Hydrogenation Catalyst Market Insights
Buyer concentration among large-scale chemical manufacturers is restructuring procurement dynamics across the oxalate hydrogenation catalyst supply base. HighChem Co., Ltd. leverages its integrated catalyst production capabilities to serve domestic Chinese oxalate hydrogenation projects. Johnson Matthey anchors its position through advanced precious-metal catalyst formulations tailored to selective hydrogenation requirements. BASF competes on global manufacturing scale and technical service networks spanning multiple industrial hydrogenation applications.
Oxalate hydrogenation catalysts are materials that accelerate the reduction of oxalate esters or oxalic acid derivatives to corresponding alcohols or glycols, typically employing supported metal systems operating under elevated hydrogen pressure and controlled temperature regimes. These catalysts serve as critical process enablers in the production of ethylene glycol and pharmaceutical intermediates where selective carbon-oxygen bond cleavage determines yield and purity. Heterogeneous catalyst types dominate current volume deployment due to their recoverability and compatibility with continuous-flow reactor systems. Pharmaceutical synthesis applications command premium pricing margins driven by stringent purity requirements and regulatory validation protocols. Bimetallic formulations represent the fastest-growing technology segment as alloy compositions deliver superior selectivity and poison resistance compared to single-metal alternatives.
EPA emissions standards for chemical manufacturing facilities shape catalyst selection criteria by penalizing processes with higher solvent intensity or byproduct generation. EMA guidelines for active pharmaceutical ingredient manufacturing impose validated process parameters that favor catalyst systems with demonstrated batch-to-batch consistency. China's MEE enforcement of dual carbon goals pressures domestic producers toward hydrogenation pathways with lower carbon footprints per unit output. Stakeholders must monitor evolving regional carbon accounting methodologies and their impact on catalyst lifecycle valuation models.
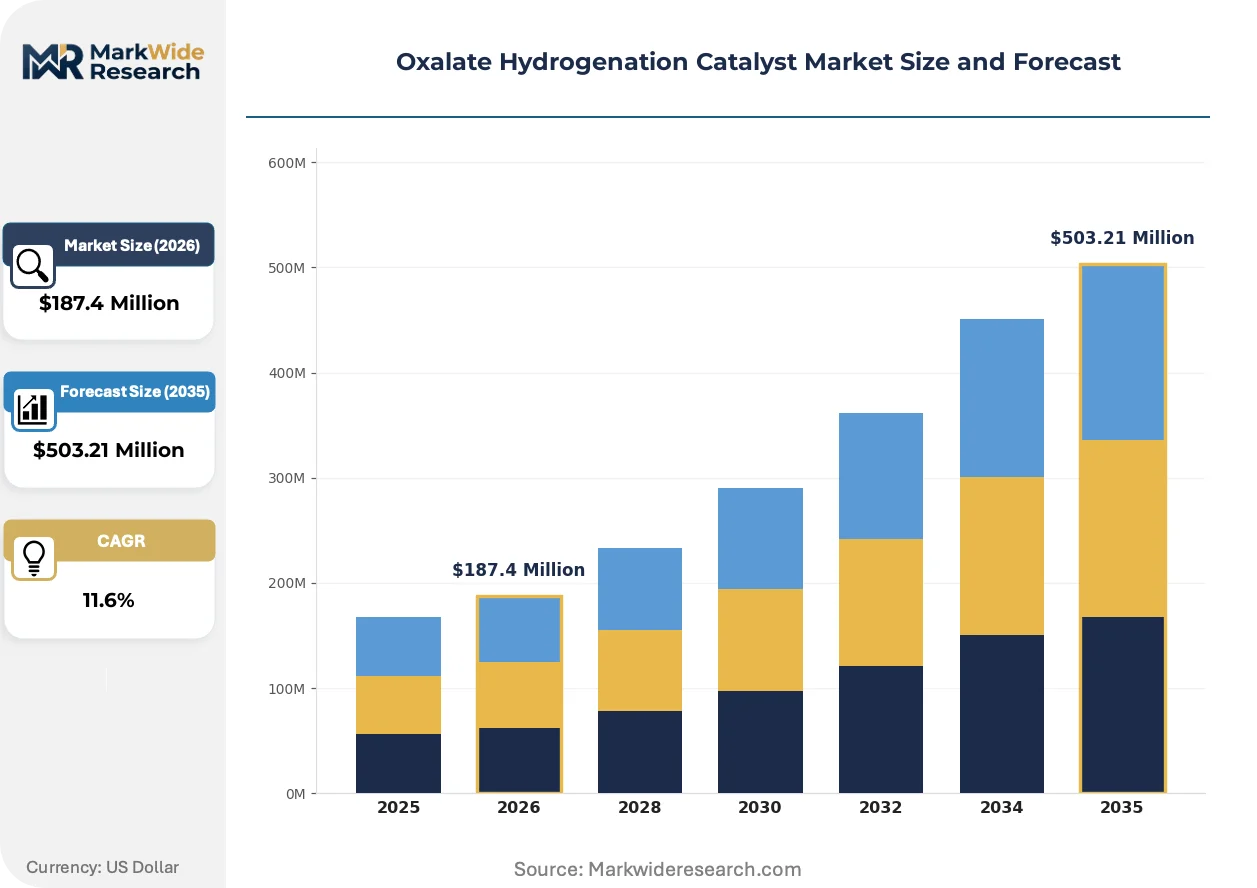
Market Dynamics
Buyer consolidation among ethylene glycol producers is restructuring catalyst procurement from spot purchasing toward multi-year supply agreements with technical service attachments.
Growth Catalysts
- Dual carbon policy enforcement:China's MEE is pressuring coal-to-chemical plants to adopt hydrogenation pathways with lower carbon intensity per ton of output, accelerating catalyst replacement cycles.
- Pharmaceutical purity mandates:EMA validation requirements for active pharmaceutical ingredient manufacturing favor catalyst systems with demonstrated batch-to-batch consistency, locking in premium suppliers.
- Coal-to-glycol capacity expansion:Domestic Chinese chemical producers are scaling oxalate-to-ethylene glycol conversion facilities, concentrating demand within integrated petrochemical complexes.
Market Restraints
- Precious metal cost volatility:Palladium and ruthenium price swings embedded in catalyst formulations create margin compression for hydrogenation operators with fixed-price offtake contracts.
- Single-source precursor dependence:High-purity alumina and titania support materials concentrate among Chinese specialty ceramic producers, exposing catalyst manufacturers to geographic supply risk.
- REACH registration complexity:ECHA substance authorization timelines for novel bimetallic formulations delay European commercialization by 18-36 months against domestic Chinese competitors.
Strategic Opportunities
- Biomass-derived oxalate feedstocks:Cellulosic waste-to-oxalate pilot projects in Brazil and India create demand for poison-resistant catalyst formulations tolerant of sulfur and nitrogen contaminants.
- Modular skid-mounted reactor systems:Distributed glycol production near downstream polymer plants favors compact catalyst loading designs with reduced turnaround maintenance requirements.
- Carbon border adjustment mechanism:EU CBAM implementation incentivizes European chemical producers to source catalysts with verified lifecycle carbon footprints, differentiating certified suppliers.
Industry Challenges
- Specialized hydrogenation engineering talent:Shortage of process chemists experienced in high-pressure catalytic systems limits scale-up velocity for novel bimetallic formulations.
- Extended catalyst qualification protocols:Pharmaceutical manufacturers require 12-24 month validation campaigns before approving catalyst changes, freezing supplier rotations.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxalate Hydrogenation Catalyst Market Trends and Innovations
Bimetallic alloy catalysts are displacing single-metal systems across selective hydrogenation applications, while regulatory carbon accounting and buyer consolidation reshape competitive positioning.
Supported ruthenium-copper bimetallic catalysts deliver superior selectivity toward ethylene glycol versus over-hydrogenation to ethanol, with pharmaceutical manufacturers adopting these formulations for high-purity intermediate production. Johnson Matthey and HighChem have expanded technical service teams to assist with reactor optimization, compressing the traditional catalyst specification timeline from 18 months to 9 months for qualified buyers. This technology is expanding into coal-to-chemical complexes in Inner Mongolia and Shanxi provinces where operators face MEE emissions intensity targets.
EPA New Source Performance Standards for chemical manufacturing facilities now penalize processes with higher solvent recovery requirements or hazardous byproduct generation rates, favoring hydrogenation pathways with cleaner mass balance profiles. EMA's updated guideline on elemental impurities in pharmaceuticals imposes stricter limits on catalyst-derived metal residues, forcing reformulation of legacy supported nickel systems. European glycol producers are responding by pre-qualifying catalyst suppliers against both REACH substance restrictions and impending carbon border documentation requirements.
Integrated service contracts bundling catalyst supply with performance guarantees and spent catalyst recovery are displacing traditional component purchasing among large ethylene glycol producers. BASF and Clariant have restructured sales organizations around dedicated account teams for top-ten chemical manufacturers, unbundling technical consulting from material invoices for mid-tier buyers. This model is most visible in China where Sinopec and Hengli Group negotiate total cost-of-ownership agreements spanning catalyst loading, monitoring, and regeneration services.
Oxalate Hydrogenation Catalyst Market Segmentation
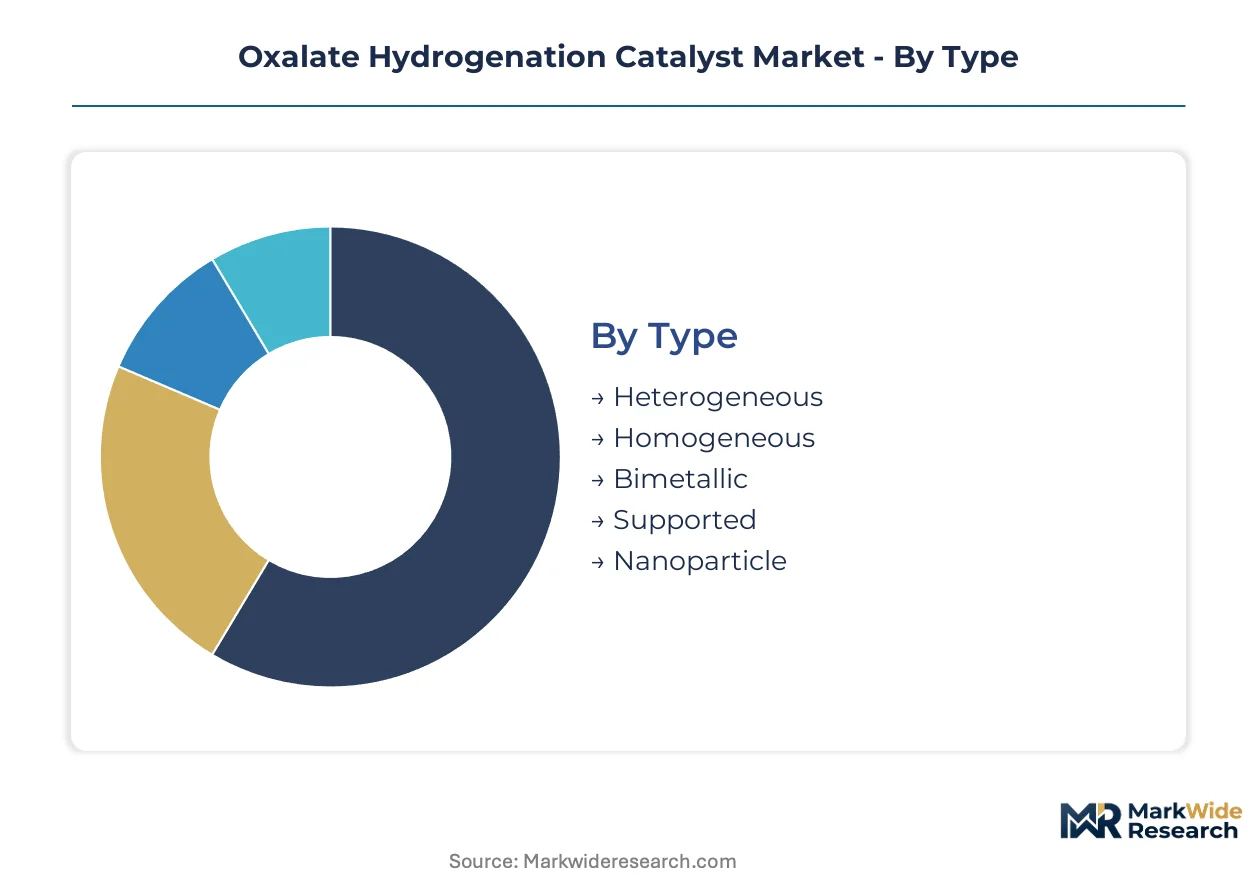
Catalyst selection criteria diverge sharply across end-use applications, with pharmaceutical purity mandates imposing stricter validation protocols than commodity chemical production. Understanding these segment boundaries enables suppliers to align formulation investments with margin structures and qualification timelines.
Type:
Supply concentration among Chinese alumina and titania producers shapes catalyst support availability and pricing volatility across all formulation categories.
- Heterogeneous:Supported metal catalysts on alumina, silica, or carbon carriers enable continuous-flow reactor operation with straightforward solid-liquid separation. Coal-to-glycol facilities in Shanxi and Inner Mongolia deploy these systems at scale under MEE emissions intensity targets, favoring recoverable catalyst architectures.
- Homogeneous:Molecular catalysts dissolved in reaction media deliver uniform active site accessibility for fine chemical synthesis. Research institutes and contract manufacturers in Germany and Switzerland utilize these systems for complex pharmaceutical intermediates where substrate specificity overrides catalyst recovery economics.
- Bimetallic:Alloy compositions of ruthenium-copper or palladium-nickel deliver superior selectivity and poison resistance versus single-metal alternatives.
- Supported:Metal deposition on engineered carriers controls particle dispersion and thermal stability under high-pressure hydrogenation conditions.
- Nanoparticle:Sub-10nm metal clusters maximize surface-area-to-volume ratios for enhanced mass transfer efficiency.
Heterogeneous catalysts absorb the bulk of installed capacity; bimetallic formulations are expanding most quickly.
Technology:
Cost tier differentiation separates mature hydrogenation infrastructure from emerging electrochemical and photocatalytic platforms requiring capital-intensive reactor redesigns.
- Hydrogenation:Direct molecular hydrogen addition across carbon-oxygen bonds operates at 50-150 bar pressure with supported metal catalysts. BASF and Johnson Matthey dominate supply contracts for ethylene glycol producers seeking proven process reliability.
- Transfer Hydrogenation:Hydrogen donors such as formic acid or isopropanol replace compressed hydrogen gas, enabling safer operation in batch pharmaceutical synthesis. EMA validation requirements favor these systems for active pharmaceutical ingredient manufacturing where explosive atmosphere risks must be minimized.
- Electrochemical Reduction:Electron-driven oxalate conversion at controlled electrode potentials eliminates hydrogen gas handling entirely.
- Photocatalysis:Semiconductor-mediated electron transfer under visible light irradiation offers ambient-temperature processing pathways.
- Biocatalysis:Engineered oxidoreductase enzymes achieve chirality-selective reductions impossible with conventional metal catalysts.
Hydrogenation retains the dominant share of commercial deployment; electrochemical reduction is gaining share fastest among sustainability-focused pilot projects.
Application:
Customer type segmentation reveals divergent procurement behaviors, with pharmaceutical buyers accepting 18-24 month qualification timelines that commodity chemical producers reject.
- Pharmaceutical Synthesis:High-purity intermediate production demands catalyst systems with batch-to-batch consistency and validated metal residue profiles. EMA's updated elemental impurity guidelines force reformulation of legacy nickel catalysts, locking in premium suppliers with documented regulatory compliance.
- Agrochemical Production:Herbicide and fungicide intermediates require cost-optimized hydrogenation at ton-scale volumes. Chinese agrochemical manufacturers in Jiangsu and Zhejiang provinces prioritize catalyst longevity over selectivity, accepting modest yield tradeoffs for extended operating cycles.
- Polymer Manufacturing:Ethylene glycol feedstock for polyester production concentrates demand among integrated petrochemical complexes.
- Fine Chemicals:Low-volume, high-value transformations support specialized catalyst formulations with rapid customization cycles.
- Specialty Chemicals:Performance additives and electronic-grade materials impose ultra-low metal contamination thresholds.
Polymer manufacturing commands the largest catalyst volumes; pharmaceutical synthesis delivers the steepest expansion trajectory.
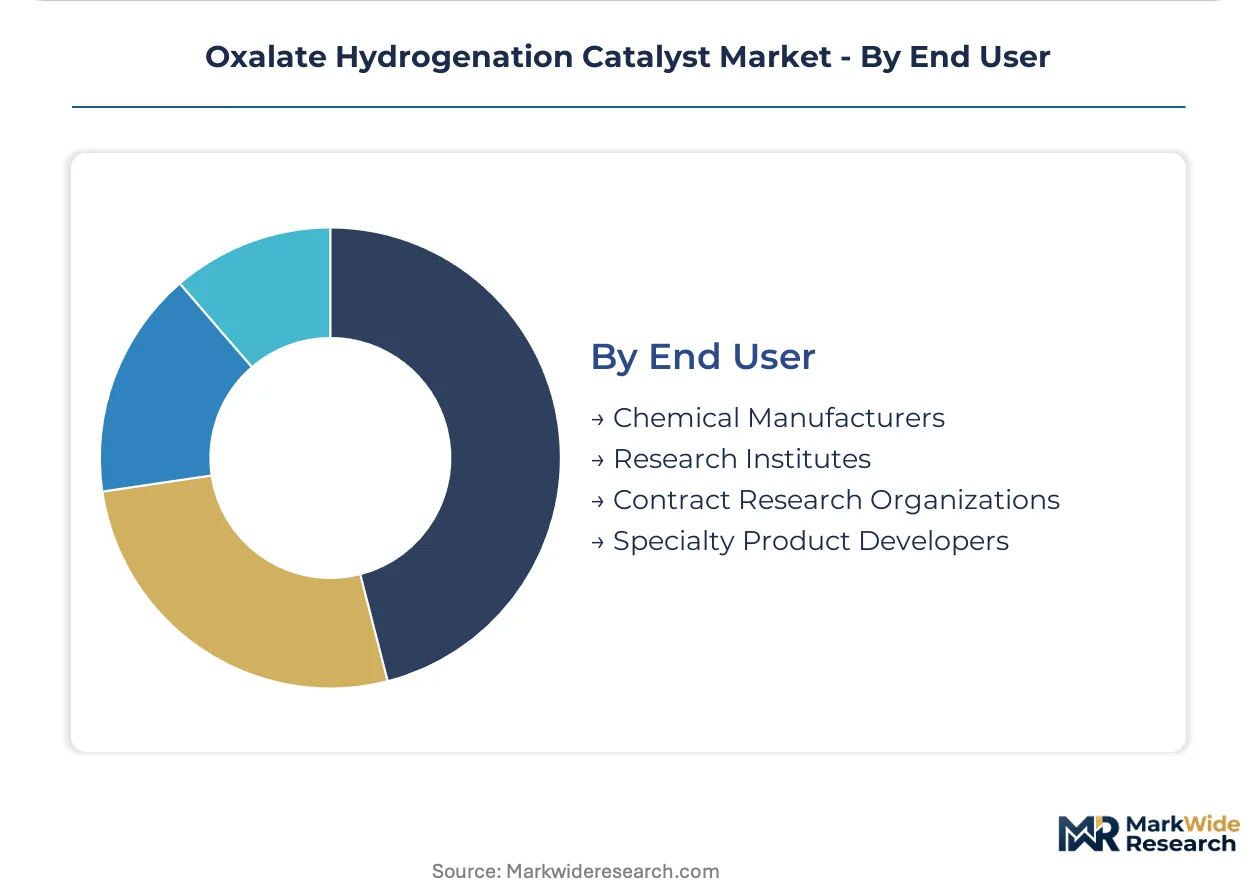
End User:
Volume concentration among top-ten chemical manufacturers is restructuring procurement from spot purchasing toward integrated service contracts with performance guarantees.
- Chemical Manufacturers:Integrated producers of ethylene glycol and industrial intermediates negotiate multi-year supply agreements bundling catalyst loading, monitoring, and regeneration services. Sinopec and Hengli Group in China have pioneered total cost-of-ownership contracts that compress supplier margins while locking in technical support.
- Research Institutes:Academic and government laboratories pilot novel bimetallic formulations and electrochemical platforms. China's Dalian Institute of Chemical Physics and Germany's Max Planck Institutes collaborate with catalyst suppliers on funded development programs, generating intellectual property that migrates to commercial licensing.
- Contract Research Organizations:Outsourced pharmaceutical synthesis providers demand flexible catalyst supply with rapid specification changes.
- Specialty Product Developers:Niche chemical producers require customized catalyst formulations for proprietary process routes.
Chemical manufacturers account for the dominant share of catalyst consumption; contract research organizations are climbing the fastest as pharmaceutical outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates oxalate hydrogenation catalyst procurement through its coal-to-glycol expansion programs. The United States and Germany anchor pharmaceutical-grade demand through validated manufacturing networks. India and Brazil represent emerging consumption nodes for both industrial and fine chemical applications.
China
Coal-to-ethylene glycol facilities in Shanxi and Inner Mongolia provinces drive catalyst consumption at industrial scale. MEE enforcement of dual carbon goals pressures operators toward hydrogenation pathways with lower emissions intensity per ton of output. Dalian Institute of Chemical Physics collaborates with domestic suppliers on bimetallic formulation development, accelerating technology transfer to commercial coal-chemical complexes.
United States
Pharmaceutical manufacturers along the Gulf Coast and in New Jersey require catalyst systems with validated batch-to-batch consistency for API synthesis. EPA New Source Performance Standards penalize chemical processes with higher solvent recovery burdens, favoring cleaner hydrogenation mass balance profiles. Houston-area petrochemical clusters source catalysts through multi-year technical service agreements rather than spot purchasing.
Germany
Fine chemical producers in Ludwigshafen and Leverkusen operate under EMA elemental impurity guidelines that force reformulation of legacy nickel catalyst systems. ECHA REACH registration timelines for novel bimetallic formulations delay European commercialization against faster Chinese regulatory pathways. Max Planck Institutes partner with catalyst suppliers on funded electrochemical reduction research, generating intellectual property for future licensing.
India
Contract research organizations in Hyderabad and Mumbai expand catalyst procurement for outsourced pharmaceutical synthesis. CDSCO alignment with ICH Q3D elemental impurity standards elevates supplier qualification requirements for metal residue documentation. Gujarat's specialty chemical corridor attracts catalyst technical service teams seeking proximity to agrochemical intermediate producers.
Brazil
Cellulosic waste-to-oxalate pilot projects in São Paulo state create demand for poison-resistant catalyst formulations tolerant of sulfur and nitrogen contaminants. ANVISA pharmaceutical manufacturing regulations impose validation protocols that favor established catalyst suppliers with documented regulatory histories. The country's national chemical regulator monitors catalyst-derived metal residues in imported API consignments.
Oxalate Hydrogenation Catalyst Market Competitive Landscape
Chinese producers anchor one tier through integrated supply chains and domestic coal-chemical relationships; European specialists hold premium positioning through precious-metal formulation expertise and pharmaceutical validation capabilities. The market structures around three archetypes: state-linked chemical conglomerates with captive demand, multinational catalyst houses with global technical service networks, and regional specialists focused on bimetallic innovation. Capacity expansion and strategic partnerships dominate competitive moves, with integrated service contracts displacing component purchasing among large ethylene glycol producers.
Within the multinational catalyst tier, BASF and Johnson Matthey occupy positions anchored by global manufacturing scale and precious-metal formulation heritage. HighChem Co., Ltd. represents the domestic Chinese archetype with proximity to coal-to-glycol project sites and integrated catalyst production capabilities. These three entities exemplify the geographic split between Asia-Pacific volume concentration and European premium positioning, with each sitting within distinct procurement ecosystems shaped by regulatory validation requirements and feedstock access.
| Leading Market Players |
|---|
| HighChem Co., Ltd. |
| Danhua Chemical Technology Co., Ltd. |
| Ningbo FarEast Catalytic Engineering Co., Ltd. |
| Shanghai Pujing Chemical Co., Ltd. |
| Haiso Technology Co., Ltd. |
| Shangqiu Guolong New Materials Co., Ltd. |
| BASF |
| Johnson Matthey |
| Clariant |
| Others |
Pricing and Supply Chain Analysis
Large-scale ethylene glycol producers in Shanxi and Inner Mongolia negotiate total cost-of-ownership contracts that compress supplier margins while embedding multi-year technical service guarantees, locking pricing power with volume-commitment buyers.
Pricing Analysis
Volume concentration among coal-to-chemical complexes drives contract-based long-term offtake structures, while pharmaceutical manufacturers absorb premium-mid-economy pricing differentiation tied to EMA validation tiers. Price differentiation hinges on certification grade and volume scale, with validated bimetallic formulations commanding substantial premiums over commodity heterogeneous alternatives. Cost compression in standard-grade catalysts is intensifying because Chinese domestic suppliers expand alumina support production capacity. Contract research organizations exhibit highest price sensitivity due to project-based procurement cycles, whereas integrated petrochemical complexes prioritize performance guarantees over unit cost.
Supply Chain Analysis
Freight costs from Chinese specialty ceramic producers to European catalyst formulators create geographic arbitrage opportunities that domestic Asian suppliers exploit. High-purity alumina and titania support materials concentrate in China, with palladium and ruthenium precursors drawing from South Africa and Russia. Single-source vulnerability in engineered carrier substrates exposes formulators to MEE export licensing unpredictability. Distribution runs through direct technical service agreements for top-tier chemical manufacturers, with spot purchasing persisting among mid-scale agrochemical intermediates producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA's updated elemental impurity guidelines erect a cost-of-compliance barrier that locks out uncertified catalyst suppliers from pharmaceutical-grade revenue pools, creating durable moats for validated incumbents.
For Market Incumbents: Acquire bimetallic formulation patent portfolios to preempt substitute electrochemical reduction technologies from gaining commercial traction. Backward integration into high-purity alumina calcination capacity in Shanxi province mitigates single-source support material risk. Lock in Sinopec and Hengli Group through exclusive regeneration service attachments that extend contract durations beyond standard replacement cycles. For New Entrants and Emerging Players: Digital-channel technical consultation platforms offer low-capital entry into contract research organization procurement workflows. Brazil's cellulosic waste-to-oxalate pilot projects represent the most penetrable geography for poison-resistant catalyst introductions. Partner with Dalian Institute of Chemical Physics on funded development programs to secure intellectual property licensing pathways. For Investors and Strategic Acquirers: The window for entry favors regional specialists with demonstrated MEE compliance documentation and existing coal-chemical customer relationships. Long-term viability centers on carbon-accounting certification capabilities as EU CBAM implementation accelerates. Watch for ECHA REACH authorization timeline compression as the signal indicating European market accessibility inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Support Production | Captive supply of high-purity carriers insulates BASF and Johnson Matthey from Chinese export licensing volatility. |
| Long-term Supply Agreement with Performance Guarantees | Sinopec's total cost-of-ownership contracts with HighChem compress competitor access to domestic coal-to-glycol volume. |
| Joint Venture with Research Institutes | Max Planck Institute partnerships accelerate electrochemical reduction technology transfer to commercial licensing. |
| Green Manufacturing Transition Certification | Verified lifecycle carbon footprints differentiate European suppliers under impending EU CBAM documentation requirements. |
| Capacity Expansion in Coal-Chemical Corridors | Proximity to Inner Mongolia hydrogenation facilities reduces logistics costs and technical service response times. |
Research Methodology
Multi-period observation of MEE enforcement intensity, EMA validation protocol updates, and coal-to-glycol capacity commissioning anchored the trend analysis, supplemented by interviews with catalyst plant managers, procurement leads at ethylene glycol producers, technical R&D directors at multinational formulators, and distribution channel partners in specialty ceramics. Secondary validation drew from customs trade data, ACC and Cefic industry reports, SEC 10-K filings of listed chemical companies, and ECHA substance registration databases. Bottom-up catalyst consumption estimates triangulated against top-down ethylene glycol production forecasts.
Segment-weighting across catalyst type, application end-use, and regional regulatory cluster dimensions informed the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves applied to disclosed capacity expansion timelines and validated against procurement pattern shifts among top-ten chemical manufacturers. Industry-specific inputs included coal-to-chemical complex utilization rates and pharmaceutical batch validation cycle durations.
Inputs from EMA guideline release schedules and MEE enforcement bulletins were available through the study window; gaps in privately held catalyst loading data from Chinese coal-chemical operators introduce uncertainty bands around Asia-Pacific volume estimates. Forecasts reflect documented assumptions regarding dual carbon policy continuity and REACH authorization pathway stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.