
 Grease Resistant Packaging Market | 2026-2036
Grease Resistant Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Grease Resistant Packaging Market Foresight
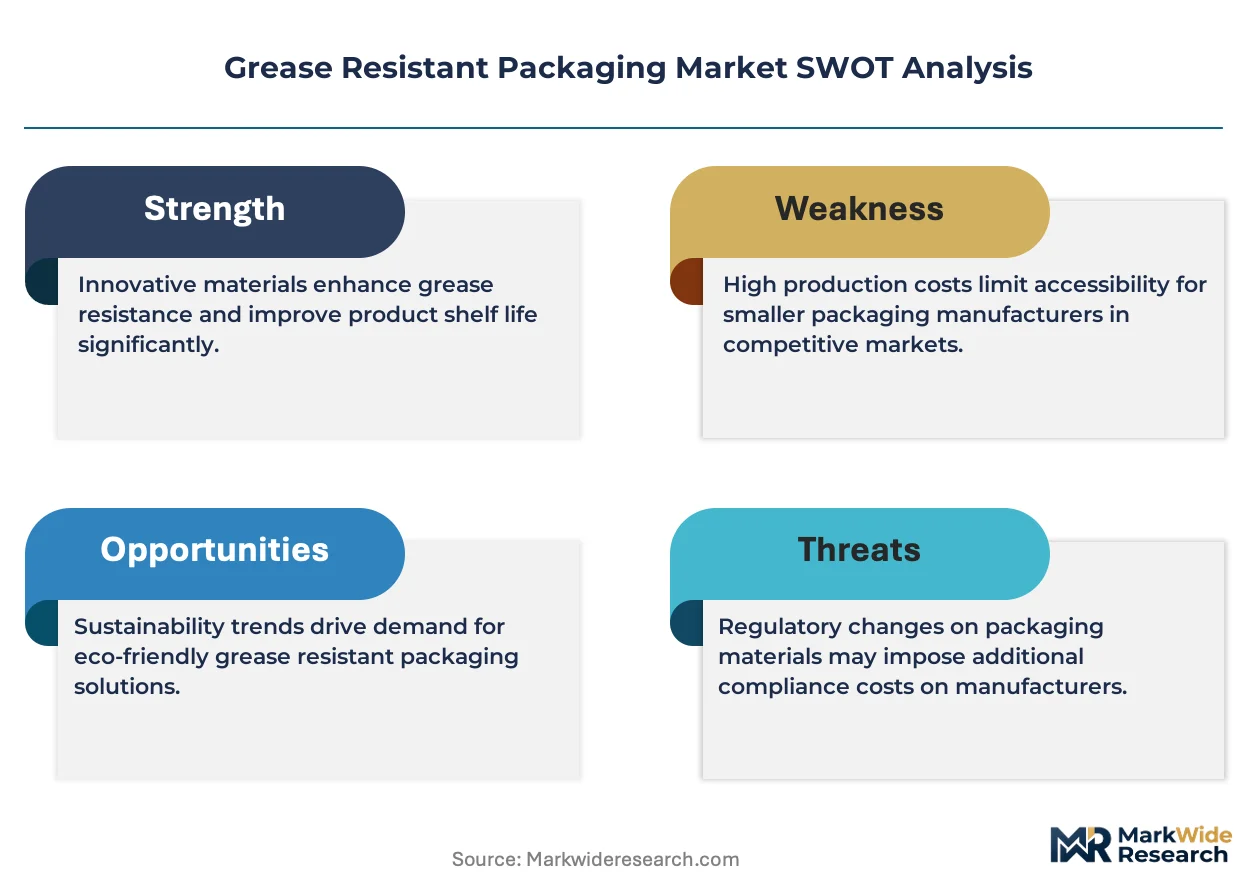
Aftermarket barrier-coating technology licensing is tilting margin pools away from commodity substrate production toward proprietary formulation supply. WestRock Company leverages its integrated pulp-to-package infrastructure to control coating application costs at scale. Amcor plc anchors its position through specialized extrusion-laminated films that meet emerging PFAS-free specifications across multiple food categories.
Grease resistant packaging denotes engineered containers, wraps, bags, and boxes incorporating hydrophobic and oleophobic barriers—typically fluorochemical-free coatings, extruded polyethylene, or bio-wax laminates applied at 10–40 gsm—to prevent oil and fat migration from fried, baked, or processed foods into outer surfaces and consumer hands. The primary commercial purpose centers on preserving food presentation quality, preventing packaging failure during transit, and eliminating consumer contact with grease-saturated materials. Composite material structures lead current volume owing to their cost-performance balance in fast-food clamshell and pizza box applications, while coated films represent the fastest-expanding segment as brands convert to recyclable single-substrate solutions. E-Commerce end-user demand is accelerating most sharply, driven by delivery-platform requirements for leak-proof performance across extended logistics chains.
FDA food-contact notification requirements and evolving EPA PFAS toxicity assessments are reshaping permissible barrier chemistries and accelerating supplier reformulation timelines. REACH restrictions in Europe and state-level bans enacted by California's DTSC and Washington's Department of Ecology further compress the addressable market for legacy fluorinated treatments. Stakeholders must monitor regulatory divergence between federal delay and state acceleration to calibrate R&D investment and inventory transition timing.
Market Dynamics
Fluorochemical-free barrier coating chemistry is restructuring competitive advantage away from substrate commodity production toward proprietary formulation control, compressing margins for uncoated board suppliers while elevating returns for integrated coating innovators.
Growth Catalysts
- California AB 1200 and Washington's PFAS ban:State-level prohibitions on per- and polyfluoroalkyl substances in food packaging are forcing quick-service restaurant chains to convert supply chains to compliant alternatives, creating immediate replacement demand.
- Quick-service restaurant delivery expansion:Platform economics for food delivery require leak-proof performance across extended logistics chains, accelerating specification upgrades for clamshells and pizza boxes.
- Bio-wax laminate R&D:Advances in plant-derived barrier coatings at 10–40 gsm application weights are achieving parity with legacy fluorinated treatments in oil resistance metrics.
Market Restraints
- Pulp price volatility:Kraft linerboard and recycled fiber input costs fluctuate with energy and logistics markets, squeezing integrated producers unable to pass through raw material swings.
- Coating chemical supply concentration:Specialty polymer and bio-wax additive production concentrates among European and North American chemical compounders, creating single-source vulnerability for Asia-Pacific converters.
- Performance gap in high-temperature applications:Fluorine-free alternatives exhibit reduced barrier integrity above 120°C, limiting penetration into fried poultry and hot sandwich segments.
Strategic Opportunities
- India quick-service penetration:Western and domestic fast-food chains are expanding drive-through and delivery infrastructure, creating first-mover advantage for PFAS-free packaging specification.
- Curbside pickup packaging:New format requirements for contactless handoff—sturdier bases, improved lid retention—favor structural innovations in molded fiber and reinforced board.
- EU Single-Use Plastics Directive alignment:National transposition across Germany, France, and Italy is accelerating substitution of plastic-lined containers with fiber-based barrier alternatives.
Industry Challenges
- Formulation chemist scarcity:Expertise in hydrophobic-oleophobic polymer science without fluorine chemistry remains concentrated among a narrow cohort of specialty chemical researchers.
- Food-contact notification timelines:FDA clearance for novel barrier substances requires 12–18 month review cycles, delaying commercialization of next-generation coatings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grease Resistant Packaging Market |
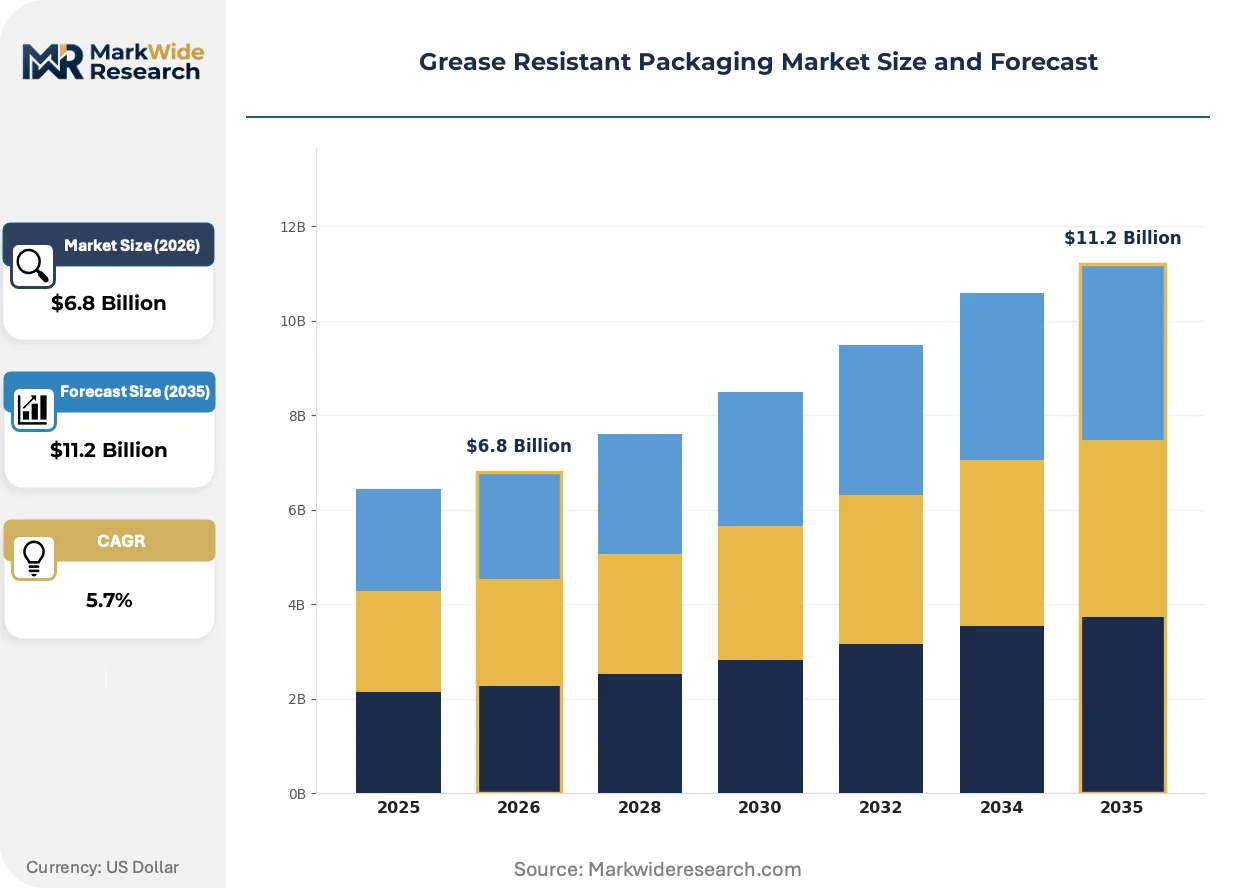
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
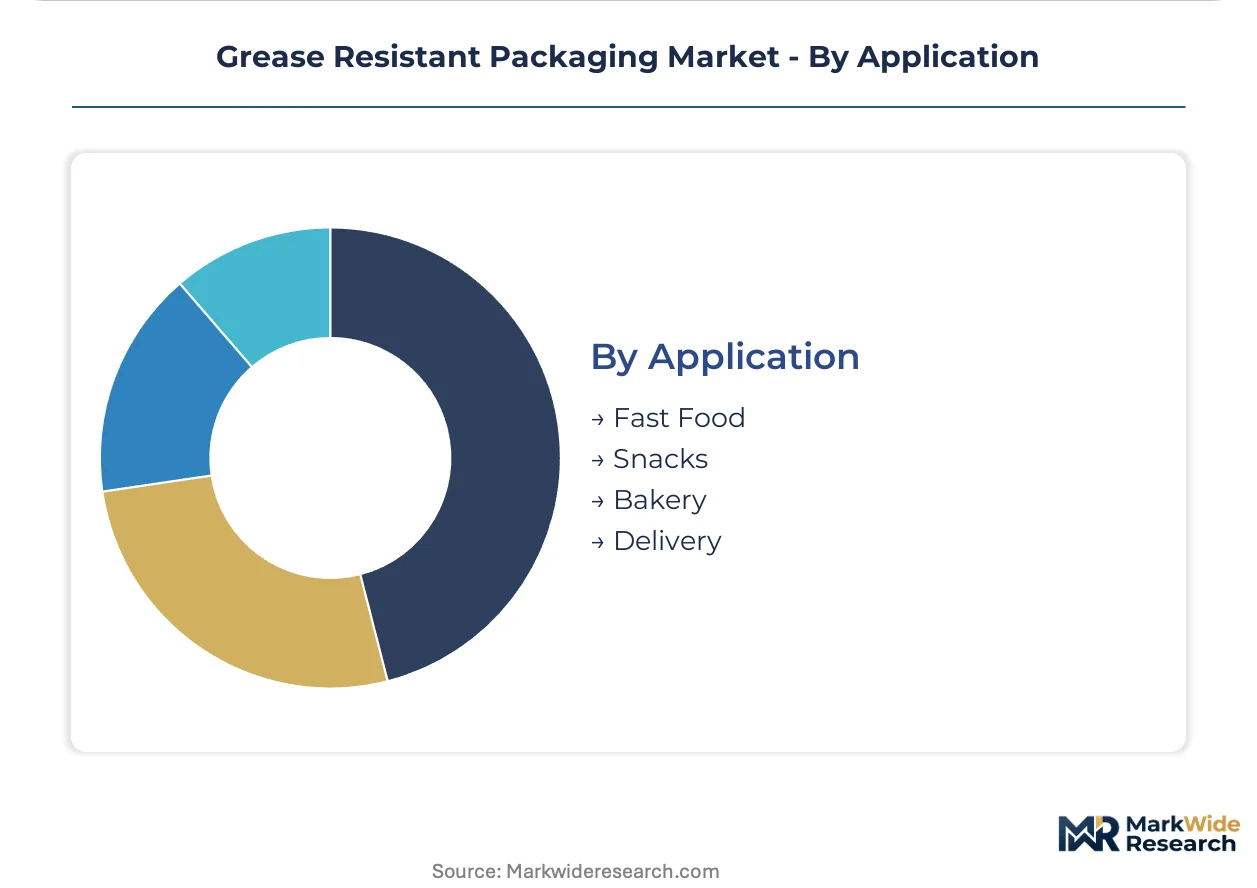
| Segmentation | Product Type: Containers, Bags, Wraps, Boxes Material: Paper, Plastic, Composite, Coated Films End User: Food Service, Retail, Manufacturing, E-Commerce Application: Fast Food, Snacks, Bakery, Delivery |
| Companies Covered | WestRock Company, Tetra Pak, Amcor plc, Klöckner Pentaplast, ProAmpac, Berry Global Group, Winpak Ltd., International Paper, Sealed Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grease Resistant Packaging Market Shifts & Advancements
Digital coating control systems and inline spectroscopy are enabling real-time barrier thickness optimization, reducing material over-application while tightening performance consistency across high-volume production runs.
Advanced extrusion-laminated polyethylene films are virtualizing the functional role of multi-layer composite structures by delivering equivalent grease resistance through single-substrate solutions. Quick-service chains in the United States and Germany are specifying these recyclable alternatives for burger wraps and fry cartons. The technology is virtualizing traditional substrate-plus-coating supply chains into streamlined mono-material platforms compatible with existing paper recovery streams.
REACH restrictions on persistent organic pollutants and EPA toxicity assessments for PFAS are compressing the addressable market for legacy fluorinated treatments across food-contact applications. European converters face accelerated reformulation deadlines under ECHA substance evaluation timelines. North American suppliers are responding with dedicated PFAS-free product lines to preempt state-level enforcement actions in California, Washington, and New York.
Third-party sustainability certification is displacing self-declared environmental claims as the primary procurement filter for national restaurant chains. Buyers now require BPI compostability or FSC chain-of-custody documentation before contract consideration, marginalizing uncertified competitors. This shift concentrates contract awards among integrated producers with captive certification infrastructure, most visible in the United States and United Kingdom procurement offices of top-ten food service operators.
Grease Resistant Packaging Market Segmentation
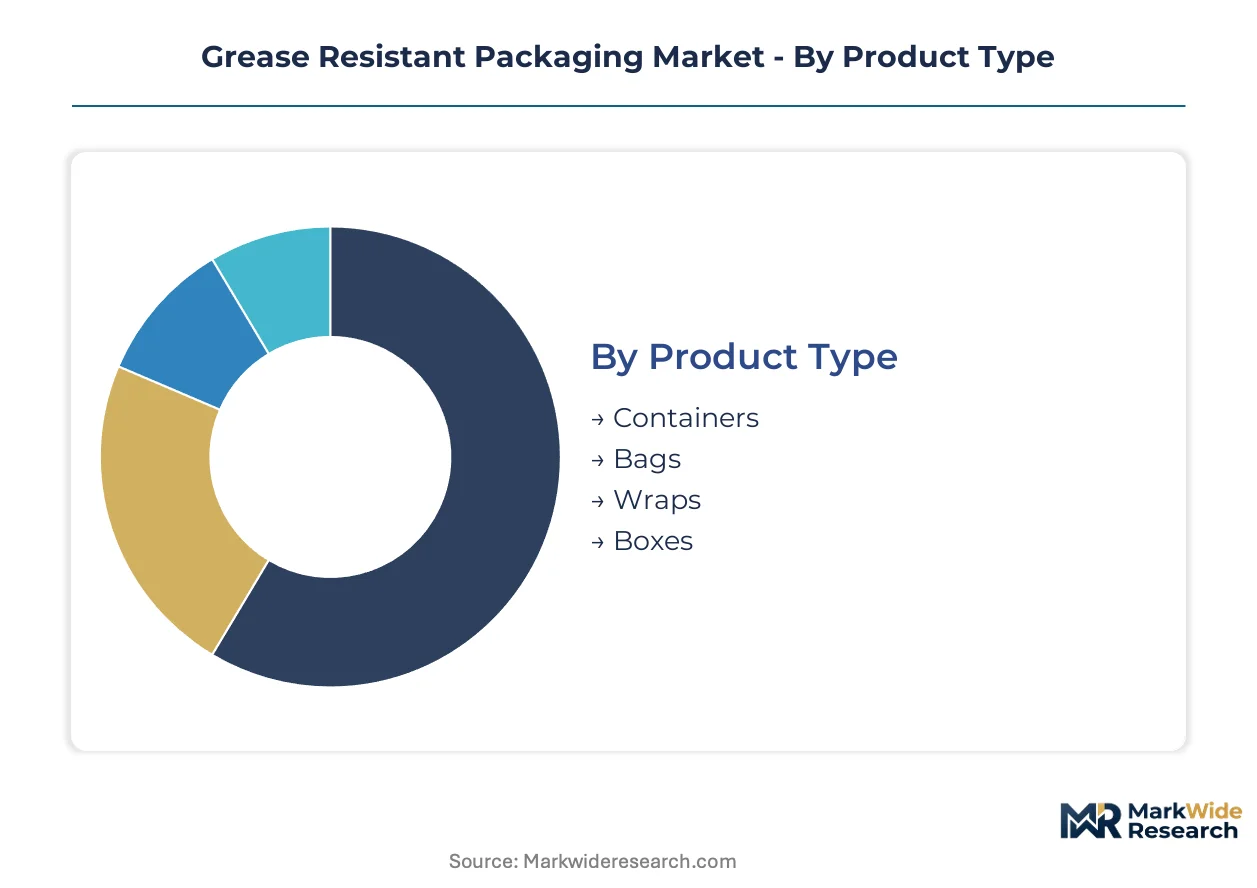
Grease resistant packaging segmentation reflects divergent technical requirements across temperature extremes, moisture exposure, and handling intensity. Cycle times vary dramatically: single-use delivery containers turn weekly while manufacturing bulk packaging contracts span multi-year agreements. Understanding these velocity differentials shapes inventory positioning and R&D allocation for suppliers.
Product Type:
Containers and boxes rotate through supply chains fastest, driven by quick-service restaurant throughput and delivery platform velocity. Wraps and bags move more slowly, anchored by retail and manufacturing procurement cycles.
- Containers:Molded fiber and paperboard clamshells with extruded polyethylene barriers dominate fried food applications. Quick-service chains in California and Washington specify these for PFAS-free compliance under state mandates. Replacement demand concentrates here as operators convert legacy stock ahead of enforcement deadlines.
- Boxes:Corrugated structures with bio-wax or polymer coatings at 15–30 gsm serve pizza and bakery segments. Germany and France drive specification upgrades through EU Single-Use Plastics Directive alignment. Structural rigidity requirements for stacked delivery logistics favor reinforced flute designs.
- Bags:Gusseted paper sacks with internal barrier layers handle snack and retail bulk applications. Shelf-stable product protection drives slower procurement cycles than food service disposables.
- Wraps:Thin-gauge coated papers for sandwich and burger encasement prioritize foldability and grease holdout. Quick-service chains specify these for drive-through and curbside handoff formats.
Boxes dominate installed base. Containers are where expansion concentrates.
Material:
Cost stratification runs from commodity uncoated paper through premium multi-layer composites to specialized coated films. Margin compression intensifies at the commodity end as substrate suppliers lose pricing power to integrated coating innovators.
- Composite:Multi-layer structures combining paperboard, polyethylene, and aluminum or metallized films deliver maximum barrier performance. Hot sandwich and fried poultry applications in the United States rely on these where temperature exceeds fluorine-free coating limits. Higher unit costs restrict penetration to premium quick-service tiers.
- Coated Films:Single-substrate solutions with extruded or laminated barrier layers enable mechanical recycling through mono-material construction. German and U.S. quick-service chains specify these for burger wraps and fry cartons to meet extended producer responsibility requirements. Technical advances are collapsing the performance gap with multi-layer alternatives.
- Paper:Uncoated or lightly treated kraft grades serve low-grease applications where cost minimization dominates. Pulp price volatility squeezes converters without backward integration into fiber supply.
- Plastic:Extruded polystyrene and polypropylene containers retain niche positions in high-temperature fried food segments. Regulatory pressure from FDA and state-level PFAS restrictions is accelerating substitution with fiber-based alternatives.
Composite materials anchor current volume. Coated films are climbing the fastest.
End User:
Customer concentration and specification authority vary sharply across this dimension. Food service operators wield unilateral procurement power while manufacturing buyers negotiate through long-term supply agreements.
- Food Service:Quick-service restaurants, casual dining chains, and institutional cafeterias drive specification-setting for the entire market. California AB 1200 and Washington's Department of Ecology mandates are forcing chain-wide supply chain conversions. Platform economics for delivery require leak-proof performance across extended logistics chains.
- E-Commerce:Third-party delivery platforms and direct-to-consumer meal kit services are emerging as independent specification authorities. Curbside pickup and contactless handoff formats favor structural innovations in lid retention and base stability.
- Retail:Grocery delis, bakeries, and prepared food counters procure through distributor intermediaries with slower cycle times than national chain direct purchasing.
- Manufacturing:Industrial bakeries and snack producers specify bulk packaging with multi-year contract horizons and stringent food-contact notification requirements from FDA.
Food Service dominates installed base. E-Commerce is where expansion concentrates.
Application:
Temperature exposure and handling intensity create distinct performance tiers. Fried food applications demand highest barrier integrity while bakery segments tolerate moderate grease resistance.
- Fast Food:Burgers, fried chicken, and hot sandwiches expose packaging to temperatures above 120°C and significant oil migration. Fluorine-free alternatives face performance constraints here, creating selective retention of composite structures. Quick-service chains in the United States are driving R&D investment to close this gap.
- Delivery:Extended logistics chains with variable orientation and temperature cycling require superior structural integrity and leak prevention. Platform requirements from delivery aggregators are accelerating specification upgrades for clamshells and pizza boxes.
- Snacks:Chips, crackers, and shelf-stable items involve lower temperature exposure and longer shelf-life requirements. Retail and manufacturing procurement patterns dominate.
- Bakery:Breads, pastries, and cakes present moderate grease and moisture challenges with emphasis on presentation preservation. Seasonal demand patterns create inventory management complexity for converters.
Fast Food dominates installed base. Delivery is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate the lowest price elasticity, absorbing premium costs for PFAS-free certification and extended producer responsibility compliance. Operators in India and Southeast Asia remain highly price-sensitive, prioritizing cost minimization over barrier performance specifications. This demand-elasticity gradient shapes regional supplier strategies and product mix allocation.
United States
Quick-service restaurant chains headquartered in Chicago and Atlanta are converting supply chains ahead of California AB 1200 and Washington Department of Ecology enforcement deadlines. FDA food-contact notification requirements compress commercialization timelines for novel barrier chemistries to 12–18 months. The Pacific Northwest corridor from Seattle to Portland anchors domestic production capacity for fluorochemical-free coated films.
Germany
Industrial bakeries in Munich and Stuttgart specify bulk packaging with multi-year contract horizons under EU Single-Use Plastics Directive alignment pressures. ECHA substance evaluation timelines under REACH accelerate reformulation deadlines for converters serving food-contact applications. The Baden-Württemberg cluster concentrates extrusion-laminated film innovation for recyclable mono-material platforms.
China
Domestic quick-service expansion in Shanghai and Beijing creates specification-setting opportunities for local barrier coating suppliers. SAMR food-contact material standards and provincial-level plastic restriction policies tighten permissible chemistries. The Yangtze River Delta manufacturing belt scales production of bio-wax laminate alternatives for export and domestic food service markets.
India
Western and domestic fast-food chains expanding drive-through infrastructure in Mumbai and Delhi-NCR generate first-mover demand for PFAS-free packaging specifications. FSSAI food safety regulations and state-level plastic ban implementations create compliance-driven procurement filters. The Maharashtra-Gujarat industrial corridor hosts emerging converting capacity for coated paperboard clamshells.
United Kingdom
National restaurant chains in London procurement offices require BPI compostability or FSC chain-of-custody documentation before contract consideration. Environment Agency guidance on persistent organic pollutants shapes barrier chemistry selection for food-contact materials. The Midlands packaging belt concentrates integrated producers with captive certification infrastructure serving quick-service and retail deli segments.
Grease Resistant Packaging Market Competitive Landscape
Integrated pulp-to-package conglomerates and specialized barrier-coating innovators split the market along the value chain. Consolidation concentrates among North American and European producers with captive fiber supply and in-house formulation capabilities. Three archetypes dominate: integrated paperboard converters controlling coating application costs at scale, extrusion-laminated film specialists delivering mono-material recyclability, and regional converters serving price-sensitive emerging markets. Capacity expansion and proprietary formulation licensing represent the dominant competitive moves as margin pools shift away from commodity substrate production.
Within the integrated converter tier, WestRock Company and International Paper exemplify scale-driven positions leveraging captive pulp infrastructure. Amcor plc occupies a specialized position among extrusion-laminated film innovators, while Berry Global Group represents the diversified packaging conglomerate archetype with broad geographic manufacturing footprints. These named entities anchor industry-level commentary on strategic positioning without implying specific tactical actions or market shares.
| Leading Market Players |
|---|
| WestRock Company |
| Tetra Pak |
| Amcor plc |
| Klöckner Pentaplast |
| ProAmpac |
| Berry Global Group |
| Winpak Ltd. |
| International Paper |
| Sealed Air |
| Others |
Supply & Pricing Matrix
The Shanghai-Los Angeles maritime corridor anchors cost dynamics for fluorochemical-free barrier coating inputs, compressing margins for converters without captive polymer supply while enabling premium pricing for integrated producers with backward control over formulation.
Pricing Analysis
Aftermarket formulation licensing and extended coating service contracts drive lifetime value capture beyond substrate sales. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified PFAS-free specifications from uncertified alternatives and commodity uncoated board. Pricing pressure stems from pulp price volatility and coating chemical supply concentration among European compounders. Food service operators in California and Washington demonstrate lowest price elasticity, absorbing certification premiums, while Asia-Pacific converters face acute cost sensitivity.
Supply Chain Analysis
Export-control restrictions on fluoropolymer precursor chemicals limit legacy barrier coating flows into food-contact applications. Raw material supply concentrates in the United States, Germany, and China, with specialty bio-wax additives drawing from North American and European chemical compounders. Kraft linerboard and recycled fiber feed from integrated pulp mills, creating single-source vulnerability for non-integrated converters. Distribution runs through quick-service restaurant procurement offices and third-party delivery platform specification committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where FDA food-contact notification requirements and state-level PFAS bans create entrenched switching costs for approved suppliers.
For Market Incumbents: Entrench position through captive certification infrastructure for BPI compostability and FSC chain-of-custody documentation, locking out uncertified competitors. Deepen upstream control over bio-wax laminate R&D to preempt formulation chemist scarcity. Expand extrusion-laminated film capacity in the Pacific Northwest corridor to serve California AB 1200 conversion timelines.
For New Entrants and Emerging Players: Pursue white-space opportunities in India's quick-service restaurant expansion, where Western and domestic chains are establishing first-mover PFAS-free specifications. Target curbside pickup packaging formats with structural innovations in molded fiber lid retention. Lead with digital coating control systems as a technical differentiation angle against legacy producers.
For Investors and Strategic Acquirers: Regional converters with captive pulp supply and in-house barrier formulation capabilities present the most defensible acquisition profile. Long-term viability rests on regulatory entrenchment through FDA notification clearances and state-level compliance infrastructure. Watch for ECHA substance evaluation timeline acceleration as an inflection signal for European asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Formulation Licensing | Captures margin pools shifting from substrate production toward proprietary barrier chemistry control. |
| Certification Infrastructure Investment | Secures BPI and FSC documentation required by top-ten food service procurement offices. |
| Extrusion-Laminated Film Scale-Up | Delivers mono-material recyclability for German and U.S. quick-service chain specifications. |
| Digital Coating Control Deployment | Enables real-time barrier thickness optimization reducing material over-application waste. |
| India Manufacturing Footprint | Positions for first-mover advantage in Western fast-food chain drive-through expansion. |
Research Methodology
The analysis maps fluorochemical-free barrier coatings, composite material structures, and coated film substrates, each validated through formulation chemists at specialty chemical suppliers, quick-service restaurant procurement directors, and coating equipment manufacturers. Primary interviews with FDA regulatory consultants, ECHA substance evaluation officers, and pulp mill technical directors combined with secondary validation from FDA food-contact notifications, ECHA restriction proposals, and SEC filings from integrated paperboard producers. Bottom-up volume modeling and top-down value triangulation anchored market sizing.
Assumptions held fixed include current FDA review timelines and state-level enforcement schedules, while coating performance parameters and pulp input costs varied across the projection horizon. Segmentation dimensions modeled encompass product type, material composition, end-user category, and application temperature exposure. CAGRs derived from regression analysis against quick-service restaurant unit expansion and delivery platform order growth. Industry-specific inputs included bio-wash laminate R&D advancement curves and EU Single-Use Plastics Directive national transposition timelines.
Sensitivities concentrate around FDA food-contact notification delays, ECHA accelerated substance evaluations, and pulp price volatility spikes. Forecasts reflect documented assumptions on regulatory enforcement pacing and coating performance parity achievement. Material shifts in California AB 1200 enforcement timing or breakthrough high-temperature fluorine-free formulations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Inflatable Packaging Market
Protective Packaging
Foam Protective Packaging Market
Protective Packaging
Void Fill Pillows Market
Protective Packaging
Protective Packaging Market
Protective Packaging
Secondary Containment Trays Market
Protective Packaging
North America Insulated Packaging Market
Protective Packaging
Foam Edge Protectors Market
Protective Packaging
Insulated Shippers Market
Protective Packaging
Insulated Styrofoam Shipping Boxes Market
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Fiber Cushioning Market
Protective Packaging
South Africa Protective Packaging Market
Protective Packaging
Molded Fiber Pulp Edge Protectors Market
Protective Packaging
Foam Packaging Inserts Market
Protective Packaging
Tamper Proof Packaging Market
Protective Packaging
Padded Dividers Market