
 Fiber Cushioning Market | 2026-2036
Fiber Cushioning Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Cushioning Market Insights
China is fragmenting as domestic converters add staple fiber and needle-punch capacity to serve regional appliance and automotive tiers. DuPont leverages its polymer science heritage to anchor premium synthetic fiber positions in North American electronics packaging. Freudenberg Performance Materials sustains European automotive seating contracts through vertical control over nonwoven roll goods. BASF competes on specialized polyurethane-fiber hybrid chemistries for furniture padding applications.
Fiber cushioning comprises engineered nonwoven or loose-fill structures manufactured from natural, synthetic, blended, or recycled fibers, typically bonded through thermal, chemical, or mechanical means to achieve specified compression set and resilience metrics; the material functions primarily to absorb mechanical shock, distribute static loads, and maintain dimensional stability across repeated use cycles in packaged goods and upholstered products. Recycled fiber gathers momentum as brands face Scope 3 emissions scrutiny, though margin pools remain thicker in synthetic fiber grades where supply contracts run multi-year. Automotive seating commands the largest application volume, while consumer electronics packaging represents the fastest structural expansion as unboxing experience standards tighten.
EPA hazardous substance rules and OSHA workplace exposure limits shape US manufacturing compliance costs for formaldehyde-based binders, while REACH substance restrictions in Europe accelerate phase-outs of certain flame-retardant chemistries in furniture padding. China's GB standards for indoor air quality in vehicle cabins force reformulation of fiber cushioning stacks used by domestic transportation manufacturing. Stakeholders must monitor how divergent chemical compliance regimes reshape supplier qualification timelines and raw material sourcing boundaries.
Market Dynamics
Recycled fiber grade availability is tightening as EU Green Deal compliance deadlines force converters to requalify entire supply chains before 2030 sustainability targets lock in.
Growth Catalysts
- E-commerce logistics expansion:Consumer electronics packaging specifications now mandate drop-test resilience that only engineered fiber cushioning achieves at specified compression sets.
- REACH substance restrictions:European flame-retardant phase-outs in furniture padding create immediate replacement demand for compliant fiber-bonded alternatives.
- Automotive cabin air quality mandates:China's GB standards force reformulation of seating stacks, pulling through higher-specification fiber grades from domestic converters.
Market Restraints
- Recycled fiber supply fragmentation:Post-consumer textile collection infrastructure remains concentrated in Germany and France, limiting converter access elsewhere.
- Formaldehyde-based binder compliance:EPA hazardous substance rules and OSHA exposure limits raise US manufacturing costs versus Asian competitors.
- Polyurethane foam substitution:Molded PU retains cost advantages in furniture padding where brands prioritize unit economics over circularity credentials.
Strategic Opportunities
- Underpenetrated appliance packaging in India:Domestic washing machine and refrigerator assembly is expanding without localized fiber cushioning supply.
- Needle-punch thermal bonding convergence:Mechanical bonding technology is displacing chemical binders in automotive applications where VOC limits tighten.
- EU Green Deal circularity incentives:Recycled content mandates in public procurement create preferential qualification pathways for compliant converters.
Industry Challenges
- Multi-jurisdiction certification timelines:REACH, EPA, and GB standard divergence forces parallel testing protocols that extend product launch cycles.
- Nonwoven roll goods integration complexity:Automotive seating suppliers face requalification costs when switching between thermal-bonded and needle-punch architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Cushioning Market |
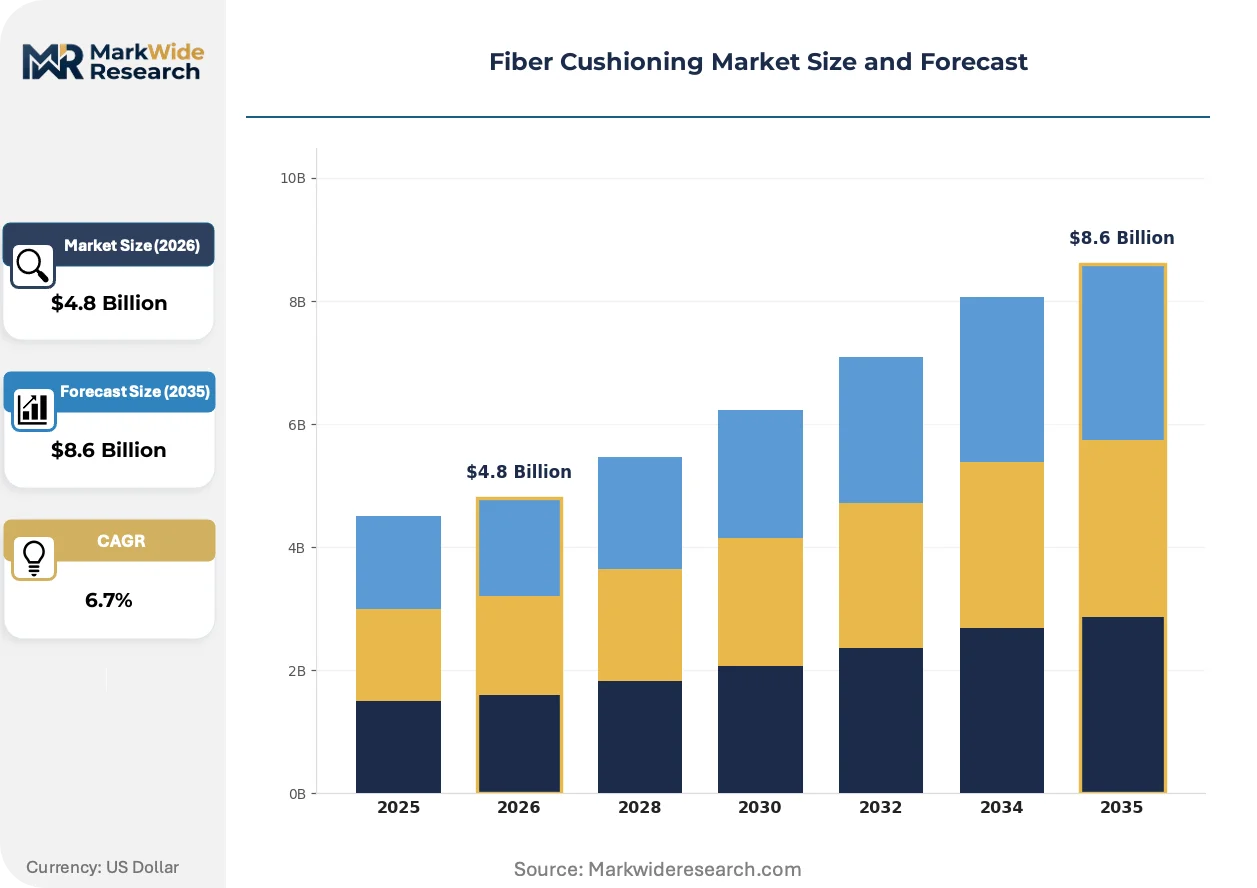
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Fiber, Synthetic Fiber, Blended Fiber, Recycled Fiber Application: Automotive Seating, Consumer Electronics Packaging, Furniture Padding, Sports Equipment Padding End User Industry: Transportation Manufacturing, Electronics Assembly, Home Furnishing, Athletic Goods Producers Distribution Channel: Retail Stores, Online Platforms, Wholesalers, Direct Sales |
| Companies Covered | DuPont, Freudenberg Performance Materials, Johns Manville, 3M, Huntsman Corporation, BASF, Toray Industries, UFP Technologies, Sealed Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Cushioning Market Trends and Innovations
Material science advances are compressing the performance gap between virgin and recycled fiber grades while regulatory clocks accelerate converter investment decisions.
Bi-component sheath-core fiber technology is hybridizing recycled PET feedstock with bio-based polyolefin sheaths to achieve thermal bonding without formaldehyde resins. Automotive seating suppliers in Germany's supply corridor are adopting these grades at contract renewal cycles. The technology is hybridizing cost structures across premium and standard product tiers previously separated by virgin fiber content.
REACH substance restrictions on halogenated flame retardants are forcing furniture padding reformulations across European manufacturing. ECHA authorization processes are compressing the viable chemistry set for fiber-bonded products. Upholstery segments serving contract hospitality are most affected, with buyers now specifying third-party certified alternatives ahead of regulatory deadlines.
Unboxing experience specifications from consumer electronics brands are reshaping packaging procurement. Direct-to-consumer fulfillment channels now require fiber cushioning that maintains aesthetic presentation through multiple handling cycles. This pattern is most visible in North American electronics packaging where brand damage claims have risen with return rates.
Fiber Cushioning Market Segmentation
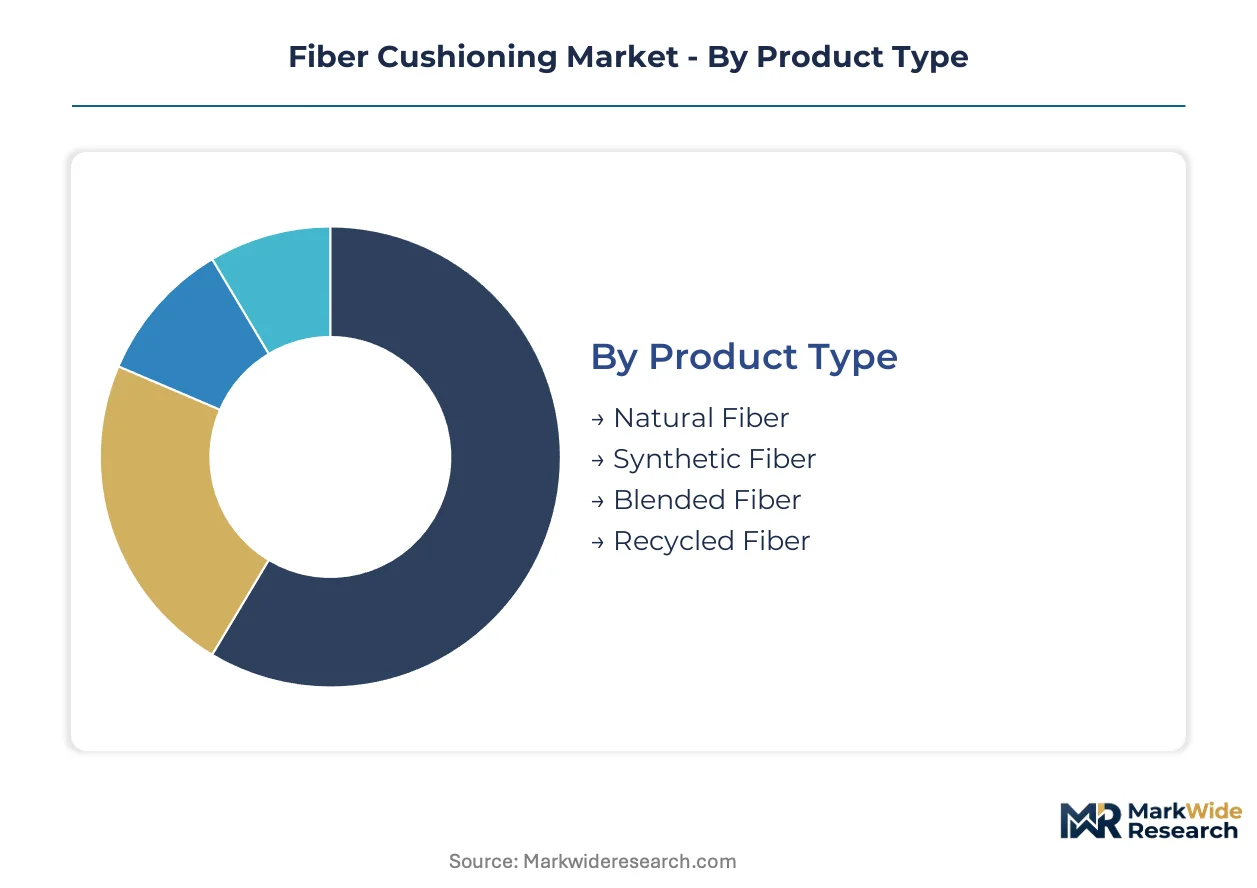
Fiber cushioning procurement splits across material chemistry, bonded architecture, and channel configuration. Each dimension carries distinct margin profiles and compliance exposure that reshape supplier qualification requirements.
Product Type:
Use-case spectrum spans virgin polymer performance to circular feedstock mandates across automotive and furniture supply chains.
- Synthetic Fiber:Virgin polyester and polypropylene staple fibers deliver calibrated compression set and resilience for drop-test specifications. Automotive seating contracts in Germany's supply corridor anchor demand, though REACH substance restrictions on certain flame-retardant chemistries force reformulation cycles.
- Recycled Fiber:Post-consumer PET and textile waste streams undergo mechanical processing to produce staple fiber with widening performance parity to virgin grades. EU Green Deal circularity incentives pull adoption in European public procurement, yet supply fragmentation across collection infrastructure limits converter access outside Germany and France.
- Natural Fiber:Jute, coir, and cotton-based structures serve furniture padding segments where bio-based credentials command premium positioning.
- Blended Fiber:Hybrid compositions balance cost, performance, and sustainability metrics for mid-tier appliance packaging applications.
Established volume favors synthetic fiber; emerging adoption favors recycled fiber.
Application:
Performance requirements diverge sharply between static load distribution and repeated mechanical shock absorption.
- Automotive Seating:Multi-layer fiber stacks achieve specified compression set and dimensional stability across temperature cycling. China's GB standards for cabin air quality force reformulation of bonding chemistries, pulling higher-specification grades through domestic converter capacity additions.
- Consumer Electronics Packaging:Engineered nonwoven and loose-fill structures must maintain aesthetic presentation through multiple handling cycles in direct-to-consumer fulfillment. E-commerce logistics expansion drives specification tightening for drop-test resilience.
- Furniture Padding:Upholstery segments balance unit economics against circularity credentials, with molded polyurethane foam retaining cost advantages in mass-market tiers.
- Sports Equipment Padding:Impact absorption specifications for helmets and protective gear demand specialized fiber density and resilience calibration.
Automotive seating captures the largest volume concentration; consumer electronics packaging climbs the fastest on unboxing experience standardization.
End User Industry:
Customer procurement maturity ranges from multi-year supply contracts to spot-market purchasing with limited technical qualification.
- Transportation Manufacturing:Tier-1 seating suppliers specify fiber grades through formaldehyde-free thermal bonding to meet VOC limits.
- Electronics Assembly:Brand-led packaging engineering teams mandate engineered fiber cushioning for drop-test compliance.
- Home Furnishing:Contract hospitality buyers now specify third-party certified flame-retardant alternatives ahead of regulatory deadlines.
- Athletic Goods Producers:Performance equipment manufacturers source specialized padding through direct technical partnerships.
Contract stability concentrates in transportation manufacturing; specification volatility characterizes electronics assembly.
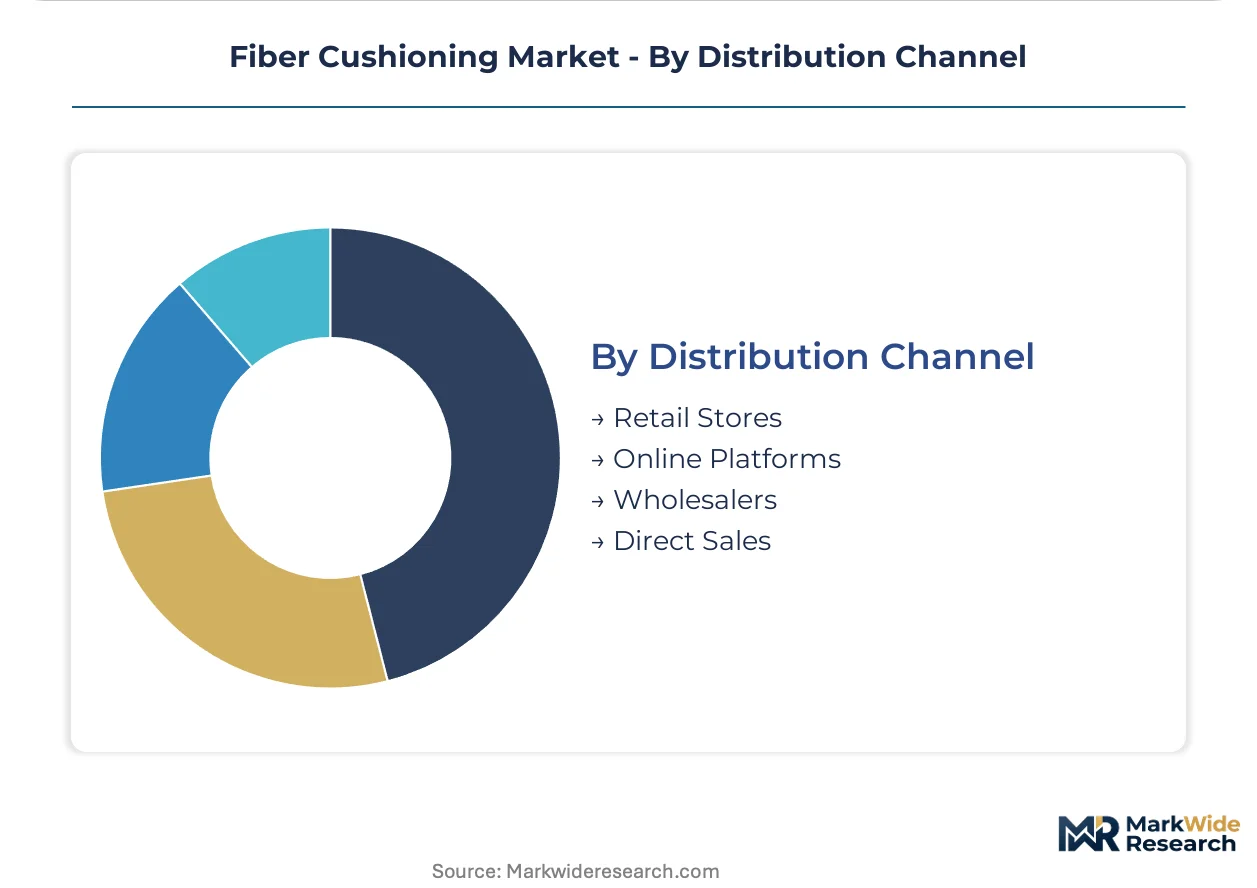
Distribution Channel:
Channel economics reflect order scale, technical service intensity, and inventory carrying cost allocation.
- Direct Sales:Converter relationships with automotive seating suppliers and electronics packaging engineers bypass intermediary margins for qualified volume.
- Wholesalers:Regional distributors serve furniture padding and appliance packaging segments with standardized grade availability.
- Online Platforms:Digital procurement channels gain traction in small-batch specialty fiber orders for prototyping and replacement markets.
- Retail Stores:Limited penetration given industrial specification requirements and bulk logistics constraints.
Technical complexity favors direct sales; geographic coverage expansion favors wholesalers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters in Germany's automotive supply corridor, China's Yangtze River Delta, and the US Southeast, with each region responding to distinct regulatory and demand pressures.
Germany
Automotive seating contracts from BMW, Mercedes-Benz, and Volkswagen anchor fiber cushioning demand through formaldehyde-free thermal bonding specifications. The EU Green Deal's 2030 circularity targets force converters to requalify recycled fiber supply chains ahead of compliance deadlines. The Stuttgart-Munich corridor concentrates needle-punch and thermal-bonding capacity serving Tier-1 seating suppliers.
China
Domestic appliance and automotive production tiers drive staple fiber and needle-punch capacity additions across regional converter networks. GB standards for cabin air quality in vehicle cabins mandate reformulation of bonding chemistries, pulling higher-specification grades through domestic supply chains. The Yangtze River Delta and Pearl River Delta clusters host expanding nonwoven roll goods production for electronics packaging and transportation seating.
United States
E-commerce logistics expansion and consumer electronics unboxing experience standards tighten packaging procurement specifications for drop-test resilience. EPA hazardous substance rules and OSHA workplace exposure limits raise manufacturing compliance costs for formaldehyde-based binders versus Asian competitors. The Southeast manufacturing belt—North Carolina, South Carolina, and Georgia—converts fiber cushioning for automotive seating and furniture padding serving domestic brands.
India
Washing machine and refrigerator assembly expansion proceeds without localized fiber cushioning supply, creating procurement gaps for domestic appliance manufacturers. BIS standards for furniture and automotive applications are tightening technical qualification requirements for imported and domestic grades alike. Maharashtra and Gujarat industrial corridors are attracting initial converter investments to serve regional transportation and appliance assembly.
France
Post-consumer textile collection infrastructure concentrates converter access to recycled fiber feedstock, with Paris and Lyon hubs processing material for EU circularity mandates. REACH substance restrictions on halogenated flame retardants accelerate reformulation timelines for furniture padding serving contract hospitality buyers. The Auvergne-Rhône-Alpes region hosts specialized nonwoven producers qualifying recycled grades for automotive and upholstery applications.
Fiber Cushioning Market Competitive Landscape
Synthetic fiber specialists and recycled fiber converters split the market across performance and circularity vectors. The vendor base organizes into three strategic archetypes: polymer science heritage players commanding premium electronics packaging positions, vertically integrated nonwoven roll goods producers sustaining automotive seating contracts, and regional converters scaling recycled fiber capacity to capture EU Green Deal procurement preferences. Capacity expansion and supply chain requalification represent the dominant competitive moves as regulatory deadlines compress investment timelines.
Within the polymer science heritage tier, DuPont anchors premium synthetic fiber positions in North American electronics packaging through material science capabilities. Freudenberg Performance Materials exemplifies vertical integration, with in-house control over nonwoven roll goods production sustaining European automotive seating relationships. BASF occupies a specialized position developing polyurethane-fiber hybrid chemistries for furniture padding applications where reformulation cycles accelerate.
| Leading Market Players |
|---|
| DuPont |
| Freudenberg Performance Materials |
| Johns Manville |
| 3M |
| Huntsman Corporation |
| BASF |
| Toray Industries |
| UFP Technologies |
| Sealed Air |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's Yangtze River Delta staple fiber sector compresses converter margins while simultaneously enabling aggressive pricing postures in export markets. German automotive seating suppliers leverage tight thermal-bonding capacity to sustain premium pricing tiers against REACH-compliant reformulation costs.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across European fiber cushioning procurement. Three-tier pricing structure across premium, standard, and economy levels separates virgin synthetic fiber grades from recycled content blends and basic natural fiber alternatives. Price differentiation hinges on certification tier—ECHA-authorized flame-retardant chemistries command substantial premiums over reformulated alternatives—and volume scale commitments from Tier-1 automotive seating suppliers. Cost compression in standard-grade recycled fiber is intensifying because EU Green Deal circularity mandates are pulling demand ahead of qualified supply expansion. Furniture padding buyers exhibit highest price sensitivity, prioritizing unit economics over circularity credentials, while electronics packaging engineers demonstrate lowest sensitivity due to drop-test compliance requirements.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for North American electronics packaging converters. Geographic supply concentration clusters in Germany, China, and the United States, with each hub serving distinct regulatory compliance requirements and end-use specifications. Raw material dependencies center on virgin PET resin, post-consumer textile waste streams, and bio-based polyolefin sheaths for thermal-bonding applications. Single-source vulnerability characterizes formaldehyde-free binder chemistry supply, where qualified alternatives remain limited under EPA hazardous substance rules. Distribution runs through direct converter relationships with automotive seating suppliers and electronics packaging engineers, bypassing intermediary margins for qualified volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Tier-1 automotive seating suppliers and consumer electronics brands, fragmenting converter negotiating leverage across multiple qualification-intensive procurement channels.
For Market Incumbents: Build certification moats around REACH-compliant and EPA-aligned bonding chemistries before regulatory deadlines lock in supplier qualification timelines. Pursue backward integration into nonwoven roll goods production to capture margin pools currently allocated to Freudenberg Performance Materials and similar vertically integrated competitors. Anchor capacity expansion in Germany's automotive supply corridor to defend against domestic Chinese converter additions serving regional appliance tiers. For New Entrants and Emerging Players: Pursue white-space positioning in India's underpenetrated appliance packaging segment, where washing machine and refrigerator assembly expansion proceeds without localized fiber cushioning supply. Target needle-punch thermal bonding convergence as the most penetrable technology vector, displacing formaldehyde-based chemistries in automotive applications where VOC limits tighten. Establish go-to-market partnerships with regional distributors in Maharashtra and Gujarat industrial corridors to bypass direct qualification barriers with established automotive seating suppliers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across recycled fiber grade capacity additions as EU Green Deal compliance deadlines compress investment timelines. Long-term viability favors converters with secured post-consumer textile feedstock arrangements in Germany and France, where collection infrastructure concentrates access. Acquisition target archetype: regional European converters with qualified recycled fiber supply chains and pending automotive seating contract renewals. Watch needle-punch thermal bonding adoption rates in German Tier-1 supplier requalification cycles as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Fiber Supply Chain Requalification | EU Green Deal deadlines force converter investment ahead of 2030 circularity targets locking in. |
| Formaldehyde-Free Thermal Bonding Scale-Up | EPA and REACH restrictions are eliminating incumbent chemistries from qualified supplier lists. |
| Needle-Punch Capacity Expansion | Mechanical bonding technology displaces chemical binders where automotive VOC limits tighten. |
| Backward Integration into Roll Goods | In-house nonwoven production captures margin pools and sustains automotive seating contract renewals. |
| Regional Converter Investment in India | Domestic appliance assembly expansion proceeds without localized fiber cushioning supply availability. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews across fiber cushioning value chains. Plant managers at German and Chinese nonwoven converters, procurement leads at Tier-1 automotive seating suppliers, electronics packaging engineers at North American brands, and distribution channel partners in European furniture padding segments provided operating data. Secondary validation drew from ECHA substance restriction databases, EPA hazardous substance filings, Chinese GB standard documentation, SEC 10-K disclosures from listed materials companies, and customs trade flow records. Bottom-up capacity and demand estimates were triangulated against top-down market sizing from production cluster analysis.
Calibration against historical capacity utilization rates and contract renewal cycles anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry tier, bonded architecture type, application performance specification, end-user industry procurement maturity, and regional regulatory compliance cluster. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion schedules. Industry-specific forecast inputs incorporated automotive seating content per vehicle trends and consumer electronics unboxing experience specification tightening.
Sensitivities concentrate around REACH authorization timelines for halogenated flame retardants, EPA enforcement intensity on formaldehyde workplace exposure, and Chinese GB standard implementation pace for cabin air quality. Forecasts reflect documented assumptions on recycled fiber grade performance parity achievement and needle-punch thermal bonding adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Static Shielding Bags Market
Protective Packaging
Secondary Containment Trays Market
Protective Packaging
Molded Fiber Pulp Edge Protectors Market
Protective Packaging
South Africa Protective Packaging Market
Protective Packaging
Anti-Corrosive Packaging Market
Protective Packaging
Tamper Proof Packaging Market
Protective Packaging
Protective Wrapping Paper Market
Protective Packaging
Adhesive Bubble Wrap Market
Protective Packaging
Foam Mesh Sleeves Market
Protective Packaging
Grease Resistant Packaging Market
Protective Packaging
Void Fill Pillows Market
Protective Packaging
Insulated Styrofoam Shipping Boxes Market
Protective Packaging
Foam Packaging Inserts Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Europe Protective Packaging Market
Protective Packaging
Global Packaging Inserts and Cushions Market