
 Thermal Insulated Mailers Market | 2026-2036
Thermal Insulated Mailers Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Insulated Mailers Market Analytics
Advanced multi-layer barrier films with phase-change material integration is reshaping thermal protection architecture in insulated packaging. Sealed Air Corporation leverages its global manufacturing footprint to dominate high-performance foam mailer production. Cold Chain Technologies anchors its position through specialized pharmaceutical-grade temperature assurance systems. Sonoco Products Company differentiates via rigid mailer engineering for sensitive electronics and diagnostic shipments.
Thermal insulated mailers are engineered envelope-style containers constructed from laminated substrates—typically polyethylene films, metallized barriers, or kraft-paper composites bonded to expanded polystyrene or aerogel insulation layers—designed to maintain internal temperature stability across ambient thermal excursions for periods ranging from 24 to 96 hours. Foam mailers lead volume share in e-commerce fulfillment due to lightweight economics and adequate protection for short-duration transit, while bubble mailers capture premium positioning in cosmetics and nutraceutical channels where moisture resistance and crush protection converge. Rigid mailers command the highest unit margins in pharmaceutical cold-chain applications where dimensional stability prevents vial breakage and maintains validated thermal performance corridors.
The EPA regulates insulating material emissions under TSCA Section 6, while the EU Green Deal's packaging waste directive mandates recyclability thresholds that constrain styrofoam-dependent product lines. FDA 21 CFR Part 211 guidelines on drug distribution temperature controls directly shape pharmaceutical mailer specifications and qualification protocols. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York, as these jurisdictions often prefigure broader federal packaging mandates that will force material transitions and compliance cost reallocations across supplier networks.
Market Dynamics
The EU Green Deal's packaging waste directive is forcing material transitions across thermal mailer supply chains, compressing styrofoam-dependent product lines while accelerating bio-based barrier film development.
Growth Catalysts
- Pharmaceutical cold-chain expansion:Biologics and vaccine distribution networks in Germany, France, and the Netherlands require validated temperature assurance systems for 24-96 hour transit windows.
- F-Gas Regulation compliance:The EU's phasedown of hydrofluorocarbon blowing agents is redirecting insulation material innovation toward aerogel and vacuum panel technologies.
- E-commerce perishables penetration:Fresh meal-kit and specialty food platforms in North America and Europe are adopting multi-layer barrier films with phase-change material integration.
Market Restraints
- Petrochemical input volatility:Expanded polystyrene and polyethylene film production remains exposed to crude oil price swings, compressing margin stability for foam mailer manufacturers.
- Recyclability threshold mandates:The EU Green Deal's 2030 packaging recyclability targets impose technical limits on metallized barrier composites that dominate premium thermal protection tiers.
- Alternative packaging substitution:Reusable rigid containers with integrated cooling elements are capturing pharmaceutical cold-chain volume from single-use mailers in regulated European corridors.
Strategic Opportunities
- Indian pharmaceutical export corridors:CDSCO's alignment with WHO temperature assurance guidelines is creating qualification pathways for EU-compliant mailer suppliers.
- Phase-change material convergence:Integration of bio-based phase-change materials with kraft-paper composites is opening cosmetics and nutraceutical channels seeking moisture-resistant crush protection.
- Extended producer responsibility tailwinds:California and New York state-level EPR pre-legislation is incentivizing mailer redesign ahead of anticipated federal mandates.
Industry Challenges
- Thermal validation expertise scarcity:Pharmaceutical mailer qualification against FDA 21 CFR Part 211 temperature control guidelines requires specialized metrology talent that concentrates in established manufacturing clusters.
- Legacy equipment retooling costs:Transition from expanded polystyrene to aerogel or cellulose-based insulation layers demands capital-intensive lamination line upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Insulated Mailers Market |
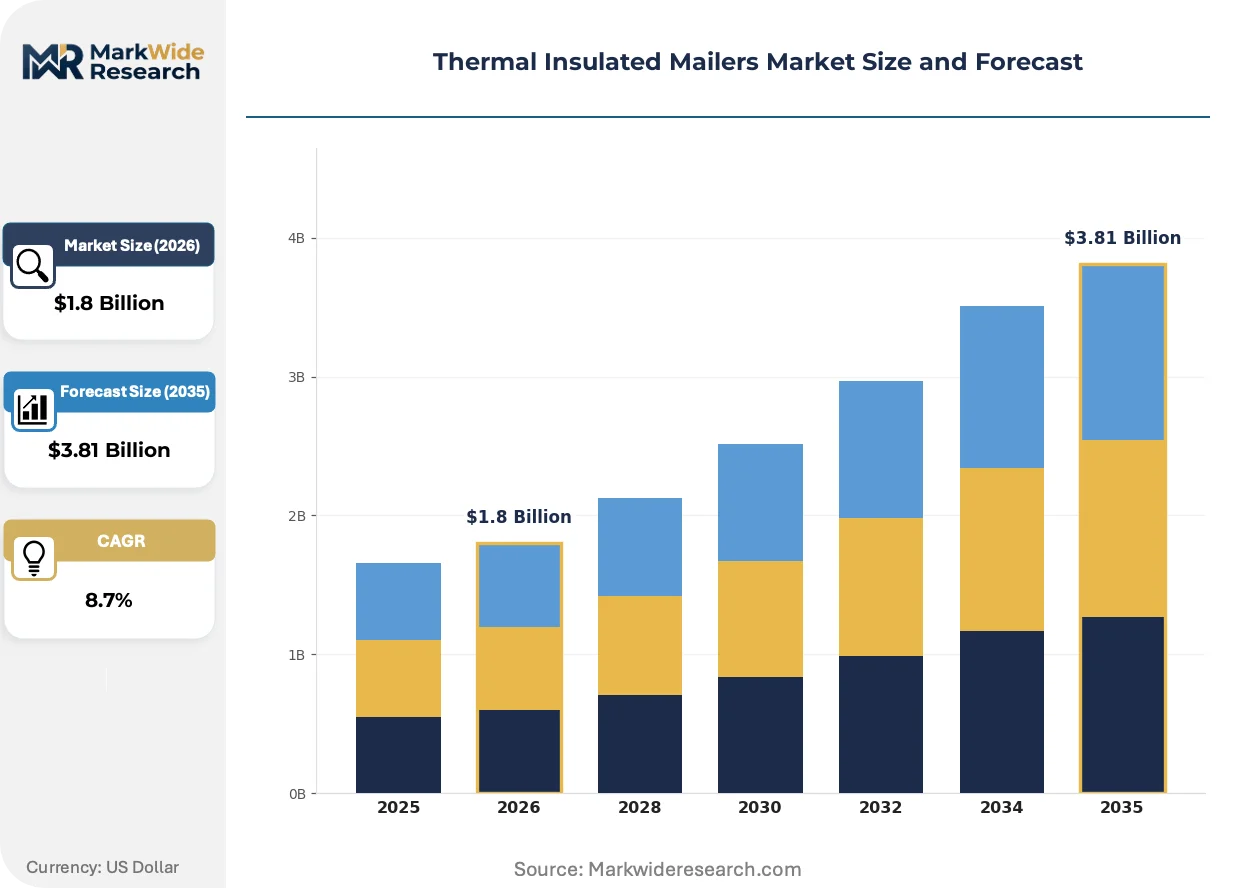
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Mailers, Bubble Mailers, Rigid Mailers, Padded Mailers Material: Polyethylene, Polypropylene, Kraft Paper, Styrofoam End User: E-commerce, Food & Beverage, Pharmaceuticals, Cosmetics Thermal Performance: Temperature Control, Heat Retention, Cold Chain, Insulation Efficiency |
| Companies Covered | Sealed Air Corporation, Cold Chain Technologies, Sonoco Products Company, DS Smith Packaging, International Paper Company, Pregis Corporation, 3M Company, Pelican BioThermal, Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Insulated Mailers Market Evolving Landscape
Multi-layer barrier architecture is virtualizing traditional thermal protection design, compressing the performance gap between foam and rigid mailer categories while enabling new material combinations.
Aerogel-infused polyethylene films are virtualizing conventional expanded polystyrene insulation in pharmaceutical-grade mailers. Cold-chain logistics providers in Germany and the Netherlands are adopting these substrates for 72-hour validated corridors. The technology is virtualizing unit economics previously reserved for premium rigid mailers into lighter envelope formats.
The EU F-Gas Regulation's hydrofluorocarbon phasedown is redirecting blowing agent chemistry toward water-blown and hydrocarbon alternatives. Insulation manufacturers face reformulation timelines that compress product development cycles. Foam mailer suppliers serving French and Benelux pharmaceutical clusters are accelerating pilot programs with bio-based polyols.
Direct-to-patient pharmacy fulfillment is compressing traditional wholesale distribution hierarchies for temperature-sensitive therapeutics. Hospital systems and specialty pharmacies in the United States are bypassing cold-chain intermediaries through validated last-mile mailer networks. This channel disintermediation concentrates procurement leverage with integrated pharmacy benefit managers seeking outcome-based temperature assurance guarantees.
Thermal Insulated Mailers Market Segmentation
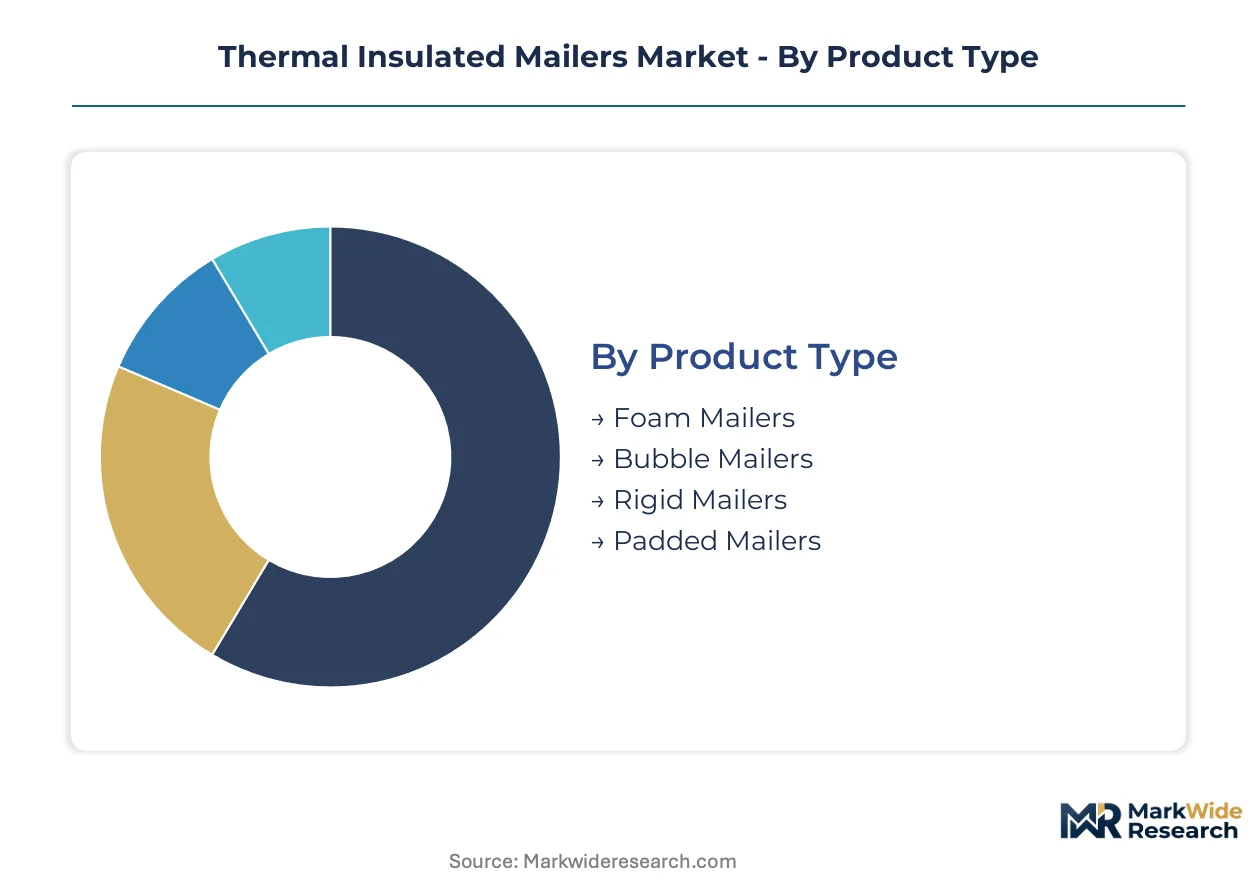
Segmentation in thermal insulated mailers reflects divergent service intensity requirements across pharmaceutical validation protocols and e-commerce fulfillment economics. Product architecture, material compliance, and thermal performance tiers each demand distinct aftermarket support structures.
Product Type:
After-sales service intensity varies dramatically by product type, with pharmaceutical-grade rigid mailers requiring thermal validation documentation and foam mailers demanding minimal post-purchase engagement.
- Foam Mailers:Lightweight expanded polystyrene or polyethylene foam laminates bonded to metallized barrier films provide 24-48 hour thermal protection for standard e-commerce fulfillment. Demand concentrates in German and Dutch pharmaceutical distribution networks seeking cost-effective short-duration transit solutions compliant with EU Green Deal recyclability thresholds.
- Bubble Mailers:Multi-layer polyethylene constructions with trapped-air insulation deliver moisture resistance and crush protection for cosmetics and nutraceutical shipments. French cosmetics direct-to-consumer channels favor these formats for their balance of thermal stability and unboxing aesthetics.
- Rigid Mailers:Engineered corrugated or molded pulp shells with integrated insulation layers command premium positioning in validated cold-chain corridors requiring dimensional stability.
- Padded Mailers:Fiber-based cushioning composites offer biodegradable alternatives for specialty food platforms seeking compostable packaging credentials.
Foam mailers hold the largest share; momentum sits with rigid mailers.
Material:
Material selection tracks cost tier stratification, with petrochemical-derived substrates dominating volume production and bio-based alternatives capturing regulatory-driven substitution premiums.
- Polyethylene:Metallized and co-extruded polyethylene films form the dominant barrier layer across thermal mailer architectures, offering moisture resistance and heat-seal compatibility. E-commerce fulfillment networks in the Netherlands rely on polyethylene-dominant constructions for automated packaging line compatibility.
- Polypropylene:Higher melting point and stiffness characteristics suit reusable mailer designs and rigid container applications where dimensional tolerance is critical.
- Kraft Paper:Unbleached cellulose substrates bonded to bio-based phase-change materials are expanding fastest in cosmetics and meal-kit channels seeking plastic-free positioning.
- Styrofoam:Expanded polystyrene faces compression from EU Green Deal packaging waste directives, with manufacturers accelerating transitions to aerogel and vacuum panel alternatives.
Polyethylene dominates volume; kraft paper composites are climbing the fastest.
End User:
Customer type segmentation reveals divergent procurement patterns, with pharmaceutical buyers emphasizing validated performance guarantees and food platforms prioritizing unit economics.
- Pharmaceuticals:Biologics and vaccine distribution networks require FDA 21 CFR Part 211-compliant temperature assurance systems with documented thermal corridor validation for 72-96 hour transit windows. CDSCO-aligned Indian export corridors are emerging as qualification-intensive growth vectors.
- E-commerce:General merchandise fulfillment drives volume consumption of foam and bubble mailer formats where lightweight shipping economics outweigh extended thermal duration requirements.
- Food & Beverage:Fresh meal-kit platforms in North America are adopting phase-change material integration for perishable last-mile delivery.
- Cosmetics:Premium skincare and nutraceutical brands favor moisture-resistant barrier films with temperature stability for active ingredient preservation.
Pharmaceuticals command premium margins; food and beverage channels are gaining share fastest.
Thermal Performance:
Performance tier segmentation structures pricing differentiation, with validated cold-chain specifications commanding multiples over basic insulation efficiency offerings.
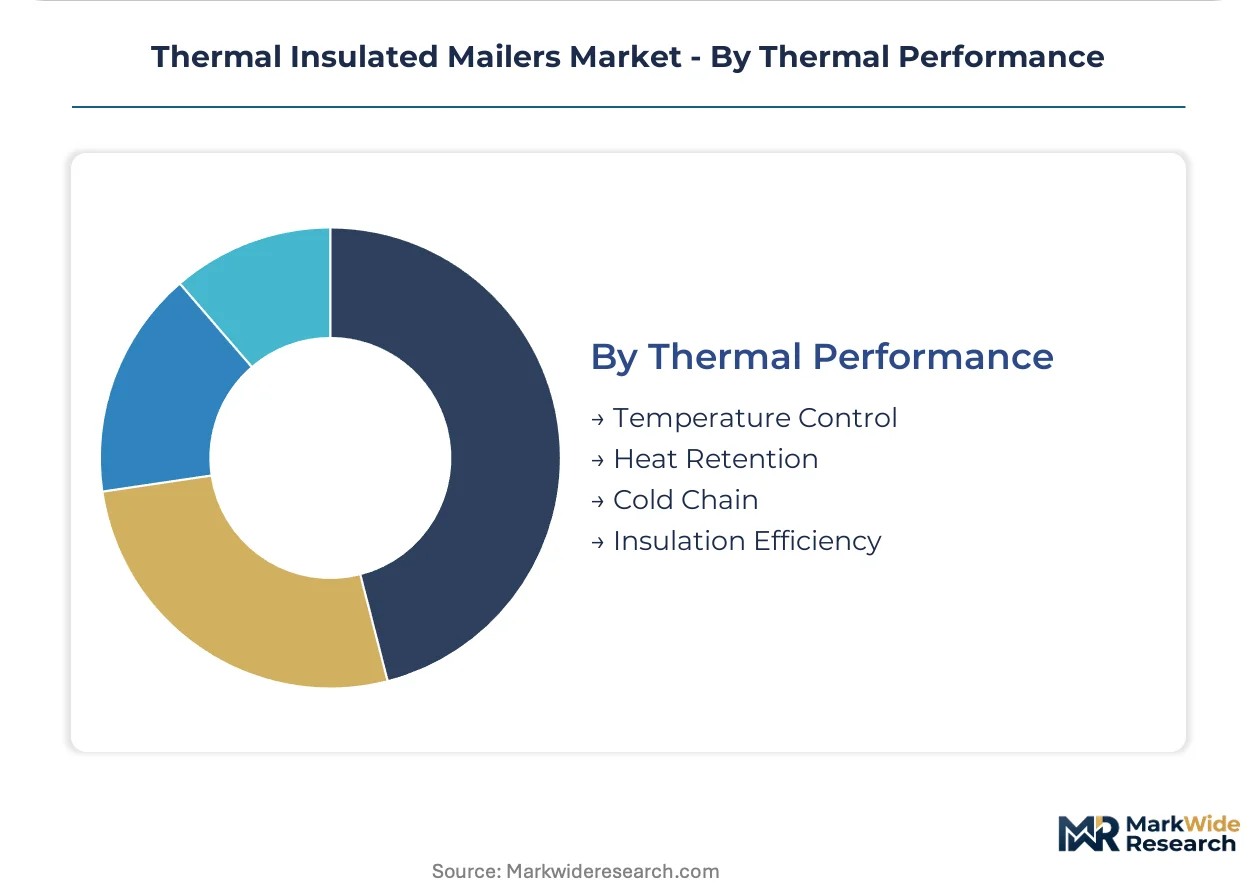
- Cold Chain:Validated 2-8°C temperature assurance for pharmaceutical distribution represents the most technically demanding performance tier, requiring phase-change material integration and real-time monitoring compatibility. German and Benelux logistics hubs anchor demand for these specifications.
- Temperature Control:Broad-range thermal stabilization for ambient-sensitive electronics and diagnostics supports shorter-duration protection without active cooling elements.
- Heat Retention:Thermal mass designs for hot food delivery and prepared meal applications leverage insulated pouch architectures.
- Insulation Efficiency:R-value optimization for cost-sensitive e-commerce applications prioritizes material minimization over extended duration performance.
Cold chain specifications hold the largest share; temperature control applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical cold-chain buyers concentrate procurement leverage in manufacturing clusters across Germany, the Netherlands, and the United States. E-commerce fulfillment networks drive volume economics in France and India. Regulatory compliance costs now vary sharply by jurisdiction, reshaping supplier qualification priorities.
Germany
Biologics manufacturing in Baden-Württemberg and Bavaria demands validated 72-96 hour thermal corridors for export distribution. The EU F-Gas Regulation's hydrofluorocarbon phasedown is accelerating aerogel insulation adoption among foam mailer suppliers. Frankfurt and Munich logistics hubs anchor qualification-intensive procurement for temperature-sensitive therapeutics.
United States
Direct-to-patient pharmacy fulfillment is compressing wholesale distribution hierarchies for specialty therapeutics. FDA 21 CFR Part 211 guidelines on drug distribution temperature controls shape mailer specifications and validation protocols. Hospital systems in Greater Boston and the Pacific Northwest are bypassing cold-chain intermediaries through validated last-mile networks.
Netherlands
Rotterdam and Amsterdam distribution corridors serve as EU pharmaceutical import gateways requiring EU Green Deal packaging waste compliance. The country's national pharmaceutical regulator enforces EMA-aligned temperature assurance standards for cross-border biologics transit. Automated packaging line compatibility drives polyethylene-dominant mailer specifications among Dutch e-commerce fulfillment centers.
France
Cosmetics direct-to-consumer channels in Île-de-France favor bubble mailer formats balancing thermal stability with unboxing aesthetics. ANSM oversight of pharmaceutical distribution reinforces cold-chain validation requirements for vaccine export corridors. Lyon and Marseille manufacturing clusters are piloting bio-based polyol formulations to meet EU F-Gas Regulation timelines.
India
CDSCO alignment with WHO temperature assurance guidelines is creating qualification pathways for EU-compliant mailer suppliers in pharmaceutical export corridors. Maharashtra and Gujarat manufacturing clusters are deepening demand for validated cold-chain packaging as biologics production scales. DGFT export incentive schemes are accelerating compliance investments among domestic packaging converters.
Thermal Insulated Mailers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation concentrates among integrated packaging conglomerates with global manufacturing footprints, while regional specialists capture niche validation-intensive segments. Two archetypes dominate: scale-driven material science platforms and cold-chain engineering specialists. Competitive moves center on portfolio diversification into bio-based materials and geographic expansion through distributor partnerships in emerging pharmaceutical corridors.
Within the scale-driven tier, Sealed Air Corporation and International Paper Company occupy positions anchored by global lamination and fiber-based packaging infrastructure. Cold Chain Technologies and Pelican BioThermal exemplify the engineering-specialist archetype, sitting within qualification-intensive pharmaceutical segments where thermal validation documentation commands premium positioning. Sonoco Products Company represents the diversified industrial packaging model, bridging rigid container engineering with temperature-assurance capabilities across electronics and diagnostic shipment channels.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Cold Chain Technologies |
| Sonoco Products Company |
| DS Smith Packaging |
| International Paper Company |
| Pregis Corporation |
| 3M Company |
| Pelican BioThermal |
| Berry Global Inc. |
| Others |
Value Network & Pricing Analysis
Expanded polystyrene resin production concentrates in German and Benelux petrochemical corridors, anchoring margin capture for foam mailer converters while downstream pharmaceutical buyers extract validation documentation premiums from rigid mailer specialists.
Pricing Analysis
Cost-plus contracts with polyethylene indexation dominate thermal mailer procurement between German pharmaceutical distributors and lamination suppliers. Price differentiation hinges on FDA 21 CFR Part 211 certification tier and volume scale, with qualified cold-chain specifications commanding substantial premiums over standard e-commerce formats. Cost compression in foam mailers is intensifying because EU Green Deal recyclability mandates force material transitions before economies of scale mature. E-commerce fulfillment networks exhibit highest price sensitivity, while biologics manufacturers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between US and Chinese polyethylene film suppliers dominates supply chain risk planning for North American mailer converters. Raw material sourcing draws from Saudi Arabian petrochemical feedstocks, German expanded polystyrene producers, and Japanese aerogel manufacturers. Single-source vulnerability concentrates in metallized barrier film coating capabilities, where Korean and Taiwanese suppliers control specialized deposition equipment. Distribution runs through integrated packaging distributors serving pharmaceutical clusters in Germany, the Netherlands, and Massachusetts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal validation expertise for pharmaceutical qualification protocols represents the critical capability gap, with FDA 21 CFR Part 211 documentation specialists concentrated in established German and US manufacturing clusters while demand outpaces trained talent pipelines.
For Market Incumbents: Build regulatory certification moats through accelerated CDSCO qualification investments in Indian pharmaceutical export corridors. Defensive moves center on backward integration into bio-based phase-change material production and captive supply of aerogel insulation substrates. The threat of reusable rigid containers with integrated cooling elements in European pharmaceutical channels demands counter-positioning through single-use mailer sustainability credentials. For New Entrants and Emerging Players: Mid-tier cosmetics and nutraceutical brands in France seeking plastic-free packaging alternatives represent the most penetrable entry point for kraft-paper composite mailers. Indian pharmaceutical export corridors aligned with WHO temperature assurance guidelines offer qualification-intensive white space with less entrenched incumbent presence. Go-to-market execution should leverage distributor partnerships with EU-compliant logistics providers already serving CDSCO-aligned manufacturing clusters. For Investors and Strategic Acquirers: Capital is best deployed toward cold-chain engineering specialists possessing FDA-validated thermal corridor documentation capabilities and established pharmaceutical manufacturer relationships. Long-term viability over the next decade rests on material science platforms capable of transitioning from petrochemical-derived substrates to bio-based barrier films without sacrificing performance specifications. The signal to watch is CDSCO enforcement consistency against WHO guidelines, which would accelerate compliance investments among domestic Indian packaging converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Phase-Change Materials | Captures margin pools from EU Green Deal-driven material substitutions while reducing petrochemical input exposure. |
| CDSCO Qualification Investment | Unlocks Indian pharmaceutical export corridors where WHO-aligned temperature assurance standards are tightening enforcement. |
| Aerogel Lamination Capacity Expansion | Positions suppliers for EU F-Gas Regulation compliance as hydrofluorocarbon blowing agents face phasedown timelines. |
| Direct-to-Patient Pharmacy Fulfillment Partnership | Bypasses wholesale distribution hierarchies in US specialty therapeutics channels where hospital systems seek validated last-mile solutions. |
| Extended Producer Responsibility Pre-Compliance | Anticipates California and New York state-level mandates that typically prefigure broader federal packaging regulations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical cold-chain logistics managers, packaging procurement leads at biologics manufacturers, thermal validation engineers, and e-commerce fulfillment operations directors. Secondary validation drew from FDA 21 CFR Part 211 guidance documents, EMA temperature assurance guidelines, EU Green Deal packaging waste directive filings, and CDSCO regulatory circulars. Bottom-up volume estimates from mailer production capacities were triangulated against top-down pharmaceutical distribution spend allocations.
Calibration against historical thermal performance qualification data and material cost trajectories informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, material compliance tier, end-use industry, thermal performance specification, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating pharmaceutical cold-chain expansion rates and e-commerce perishables penetration curves.
Macroeconomic conditions sit as an overlay; deviation in crude oil price volatility or EU carbon border adjustment implementation pace would shift the trajectory for petrochemical-derived substrate economics. Forecasts reflect assumptions about regulatory enforcement consistency and material substitution timelines that carry inherent uncertainty. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Grease Resistant Packaging Market
Protective Packaging
North America Insulated Packaging Market
Protective Packaging
Latin America Protective Packaging Market
Protective Packaging
Fiber Cushioning Market
Protective Packaging
Padded Mailers Market
Protective Packaging
Protective Packaging Market
Protective Packaging
Foam Mesh Sleeves Market
Protective Packaging
Packaging and Protective Packaging Market
Protective Packaging
Insulated Styrofoam Shipping Boxes Market
Protective Packaging
Asia-Pacific Protective Packaging Market
Protective Packaging
Insulated Shipping Boxes Market
Protective Packaging
Europe Protective Packaging Market
Protective Packaging
Secondary Containment Trays Market
Protective Packaging
Inflatable Packaging Market
Protective Packaging
Anti-Corrosive Packaging Market
Protective Packaging
Thermal Insulated Bubble Wrap Market