
 High Pressure Protective Packaging Film Market | 2026-2036
High Pressure Protective Packaging Film Market Size, Share, and Industry Trends Forecast 2026-2036
High Pressure Protective Packaging Film Market Outlook
Barrier-grade nylon coextrusion is reorganizing competitive tiers as converters race to meet oxygen transmission specifications below 0.5 cc/m²/day. Sealed Air Corporation leverages its captive resin compounding network to control specification drift across regional plants. Pregis LLC anchors North American electronics fulfillment with automated inflate-on-demand systems that reduce warehouse cube requirements. Mondi Group competes through European paper-film hybrid platforms that satisfy dual substrate sourcing strategies.
High pressure protective packaging film denotes multilayer flexible structures engineered to withstand internal inflation pressures exceeding 1 bar while maintaining seal integrity under dynamic load; typical constructions weld polythene sealant layers to oriented nylon or biaxially oriented polypropylene for puncture resistance during e-commerce parcel handling. Polypropylene dominates volume in lightweight electronics cushioning where stiffness-to-weight ratios justify material premiums, while nylon concentrates in medical supplies where burst strength validation under ISO 11607 sterilization protocols commands margin pools. Food packaging applications lag in high-pressure formats due to retort compatibility constraints, though modified atmosphere meat shipping is opening niche conversion opportunities.
FDA 21 CFR 177.1520 compliance governs polyolefin food-contact layers in US medical supply chains, while REACH Article 33 SVHC disclosure obligations force European converters to document phthalate-free plasticizer migration below 0.1% w/w across PVC alternatives. ECHA's restriction roadmap for microplastics in single-use packaging is forcing R&D pivot toward soluble film technologies before enforcement phases tighten. Stakeholders must monitor how California's SB 54 extended producer responsibility rules cascade into national distributor sourcing mandates.
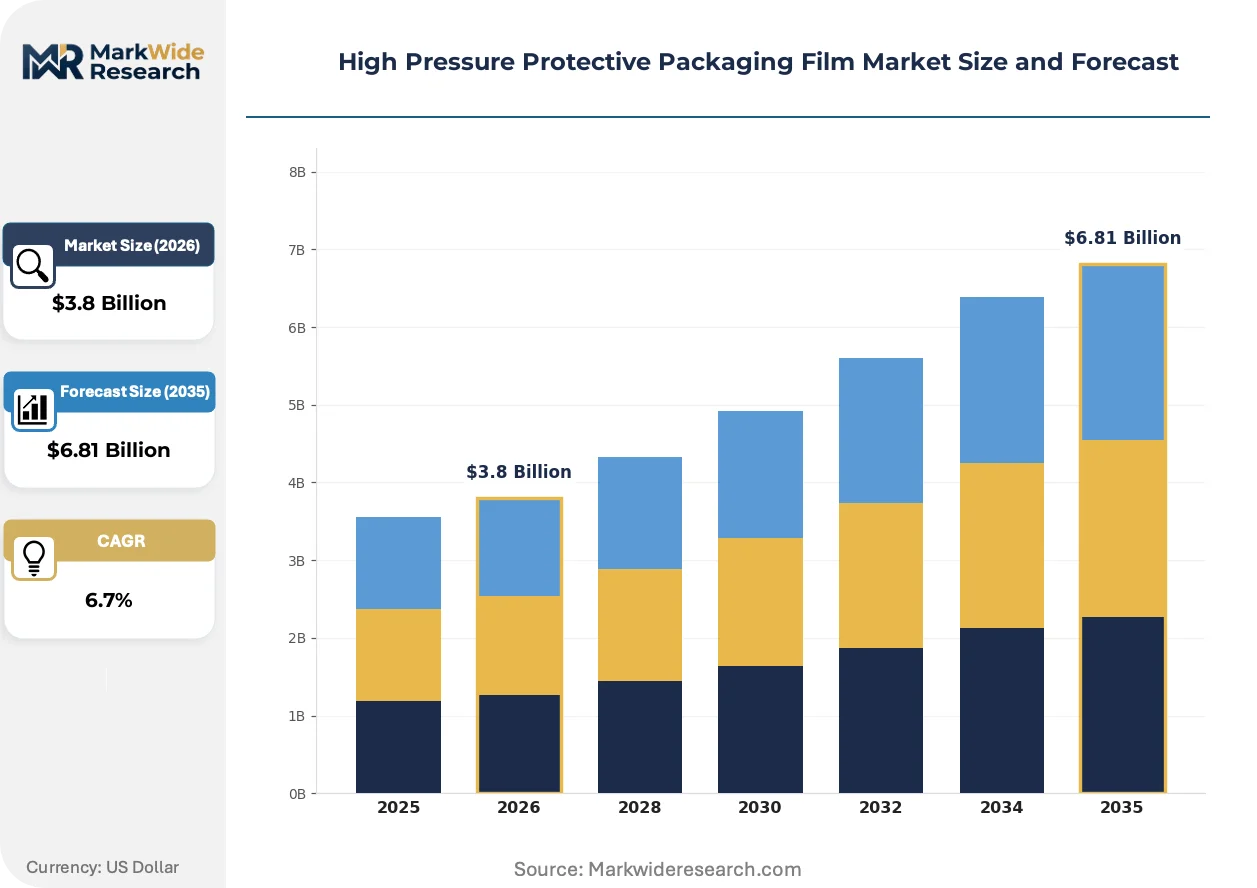
Market Dynamics
Europe's F-Gas Regulation and REACH compliance requirements are forcing converters to abandon high-GWP barrier chemistries, triggering a wave of capital redeployment toward lower-carbon coextrusion platforms.
Growth Catalysts
- Semiconductor logistics expansion:Electronics fulfillment networks handling fragile chip components are mandating high-pressure inflatable cushioning systems that exceed legacy bubble-wrap performance thresholds.
- Germany's automotive export corridor:Industrial parts shipments from Bavaria and Baden-Württemberg require burst-resistant films validated under dynamic load testing for transcontinental rail and sea routes.
- REACH Article 33 SVHC disclosure:European converters documenting phthalate-free plasticizer migration below 0.1% w/w are capturing medical supply contracts previously held by PVC-dependent competitors.
Market Restraints
- Nylon resin supply concentration:Caprolactam feedstock dependence on Belgian and German polymerization complexes creates vulnerability to energy-cost spikes and force majeure events.
- Retort compatibility constraints:High-pressure film structures face technical limitations in steam sterilization cycles above 121°C, blocking penetration into shelf-stable food packaging.
- Soluble film substitution threat:ECHA's microplastics restriction roadmap is accelerating R&D pivots toward water-dissolvable alternatives that could displace conventional multilayer constructions.
Strategic Opportunities
- Modified atmosphere meat shipping:Niche conversion opportunities are emerging for barrier-grade nylon coextrusions in premium protein cold-chain logistics requiring oxygen transmission below 0.5 cc/m²/day.
- California SB 54 extended producer responsibility:Distributor sourcing mandates cascading from state-level rules create first-mover advantage for converters with documented circularity pathways.
- Paper-film hybrid platforms:Dual substrate sourcing strategies combining kraft outer layers with high-pressure sealant films satisfy brand-owner sustainability scorecards without sacrificing inflation integrity.
Industry Challenges
- ISO 11607 sterilization validation timelines:Medical supply entrants face 18-24 month certification cycles for burst strength documentation under accelerated aging protocols.
- Multilayer coextrusion skill scarcity:Converters report difficulty recruiting technicians capable of calibrating nine-layer die geometries for oxygen barrier consistency within ±5% tolerance bands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Pressure Protective Packaging Film Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polythene, Polypropylene, PVC, Nylon Application: Food Packaging, Medical Supplies, Electronics Packaging, Chemical Packaging End User: Manufacturers, Retailers, Distributors, Logistics Providers Distribution Channel: Online Retail, Traditional Retail, Direct Sales, Wholesale |
| Companies Covered | Sealed Air Corporation, Pregis LLC, Amcor Plc, Berry Global Inc., Barton Jones Packaging Ltd, Mondi Group, Supreme Industries Limited, Storopack Hans Reichenecker GmbH, Rajapack Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Pressure Protective Packaging Film Market Strategic Shifts
Barrier-grade nylon coextrusion is bifurcating competitive tiers as specification drift becomes a primary risk factor in regional plant networks. Converters must now synchronize resin compounding across dispersed manufacturing footprints to maintain oxygen transmission consistency.
Automated inflate-on-demand systems are bifurcating warehouse operations for electronics fulfillment providers. Third-party logistics operators in North America are deploying these platforms to compress cube requirements by 40-60% versus pre-inflated cushion inventories. The technology is bifurcating capital allocation between real estate-light fulfillment models and traditional buffer-stock configurations.
ECHA's restriction roadmap for microplastics in single-use packaging is forcing formulation chemistry toward bio-based sealant layers. European converters are piloting polylactic acid blends and polyhydroxyalkanoate copolymers to preempt enforcement phases tightening in 2027-2030. Medical and food-contact segments face the steepest compliance curves due to existing FDA 21 CFR 177.1520 and REACH dual obligations.
Consolidated buying by e-commerce platform operators is compressing supplier negotiation cycles from annual to quarterly frameworks. Electronics fulfillment networks in Germany and the United States are unbundling after-sales packaging services from transportation contracts, creating direct procurement relationships with film converters. This disintermediation is most visible in semiconductor logistics corridors where damage-rate penalties now exceed material cost differentials.
High Pressure Protective Packaging Film Market Segmentation
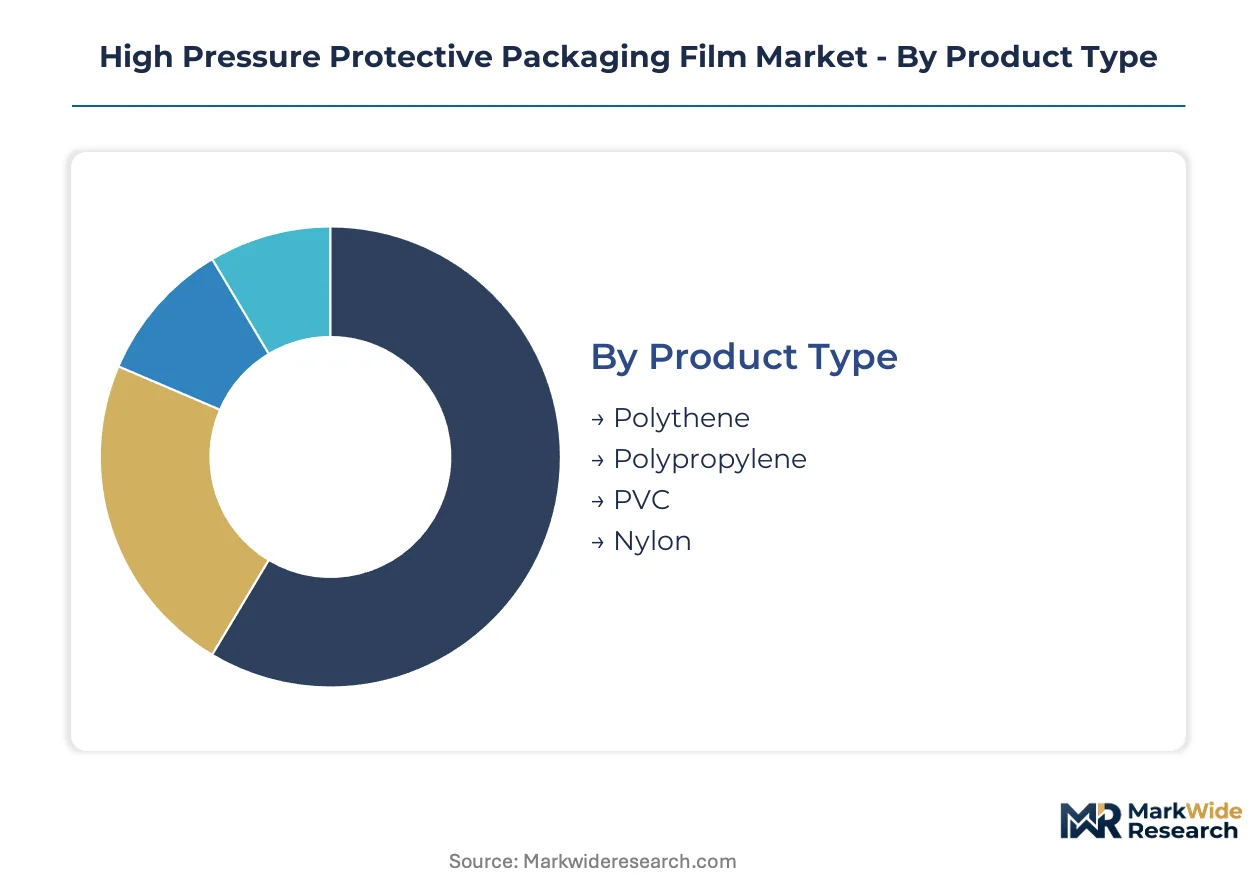
High pressure protective packaging film demand fragments across material chemistries, end-use specifications, and procurement channels. Each segment carries distinct technical requirements, regulatory burdens, and margin structures that reshape converter investment priorities.
Product Type:
Domestic consumption patterns concentrate polythene and polypropylene demand in North American electronics fulfillment networks, while nylon and PVC grades track export-oriented medical and industrial corridors in Germany and Belgium.
- Polythene:Linear low-density formulations weld to oriented nylon skins for e-commerce parcel cushioning. US electronics fulfillment networks in Texas and California specify this construction for automated inflate-on-demand systems handling semiconductor components.
- Polypropylene:Biaxially oriented structures deliver stiffness-to-weight ratios that justify material premiums in lightweight electronics cushioning. Bavarian automotive parts exporters specify burst-resistant PP-nylon laminates for transcontinental rail shipments to China.
- PVC:Phthalate-free formulations command medical supply contracts under REACH Article 33 disclosure rules. Belgian converters document plasticizer migration below 0.1% w/w to capture share from legacy PVC suppliers.
- Nylon:Caprolactam-based barrier grades achieve oxygen transmission below 0.5 cc/m²/day for modified atmosphere meat shipping.
Polythene holds the largest share; momentum sits with nylon as barrier specifications tighten across European protein cold chains.
Application:
Cost tiers separate commodity cushioning from validated medical and food-contact segments requiring extended certification timelines and specialized resin compounding.
- Electronics Packaging:Semiconductor logistics networks mandate inflation pressures exceeding 1 bar with dynamic load validation. Third-party logistics operators in Germany and the United States unbundle after-sales packaging from transportation contracts, creating direct procurement relationships with film converters.
- Medical Supplies:Multilayer structures face 18-24 month ISO 11607 certification cycles for burst strength documentation under accelerated aging protocols. FDA 21 CFR 177.1520 compliance governs polyolefin food-contact layers in US medical supply chains.
- Food Packaging:Retort compatibility constraints above 121°C block penetration into shelf-stable formats. Premium protein cold chains in France and Italy drive niche adoption of barrier-grade nylon coextrusions.
- Chemical Packaging:Puncture-resistant laminates handle industrial solvent containment with lower specification burdens than medical or food segments.
Electronics packaging anchors volume; medical supplies deliver the steepest margin expansion trajectory as certification barriers thin competitor fields.
End User:
Procurement concentration varies by scale, with logistics providers consolidating specifications across fulfillment networks while manufacturers retain bespoke formulation relationships.
- Logistics Providers:Consolidated buying by e-commerce platform operators compresses supplier negotiation cycles from annual to quarterly frameworks. Automated inflate-on-demand deployments reduce warehouse cube requirements by 40-60% versus pre-inflated cushion inventories.
- Manufacturers:Automotive and electronics OEMs in Germany's industrial corridor specify burst-resistant films validated under dynamic load testing for transcontinental routes.
- Distributors:California's SB 54 extended producer responsibility rules cascade into sourcing mandates favoring converters with documented circularity pathways.
- Retailers:Sustainability scorecards drive paper-film hybrid adoption combining kraft outer layers with high-pressure sealant films.
Logistics providers command the largest procurement volume; manufacturers represent the most stable long-term contracting relationships.
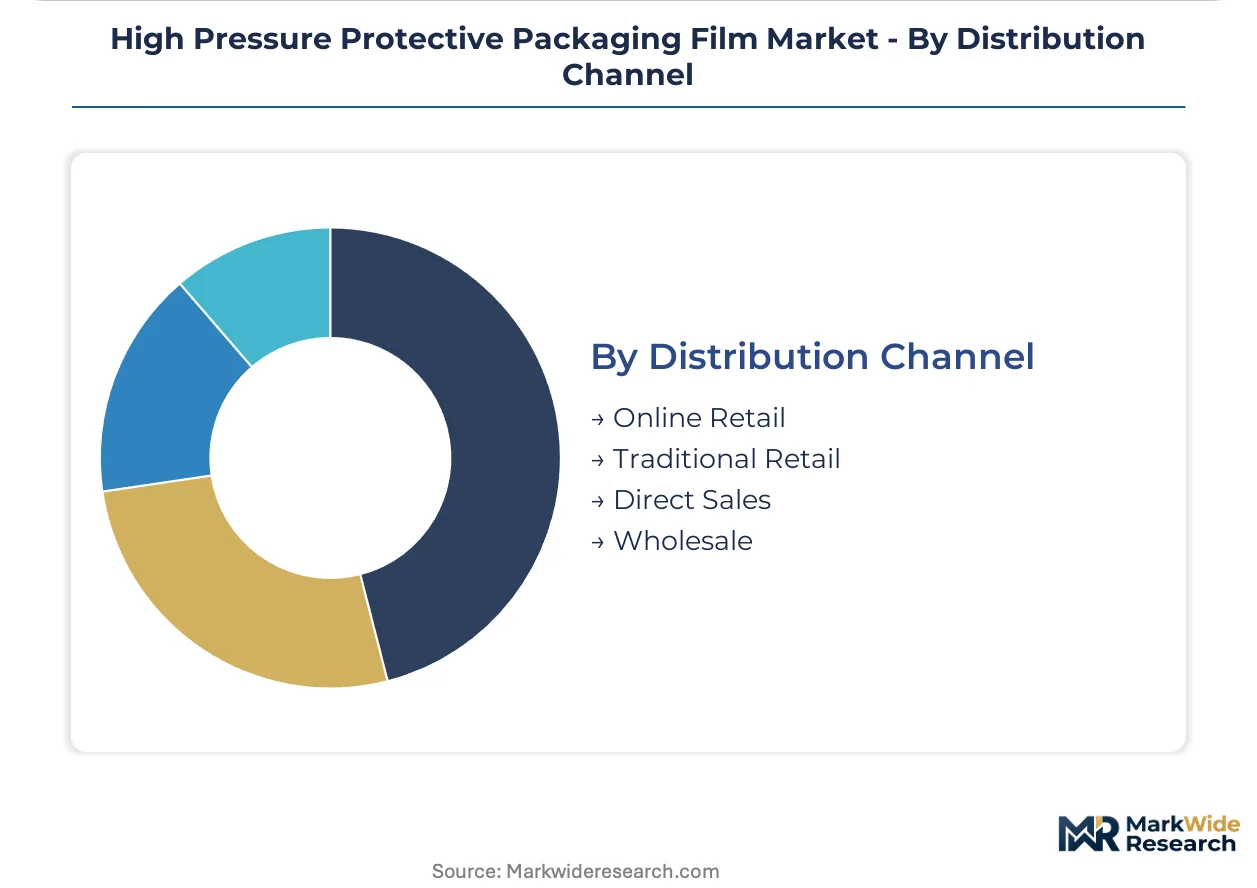
Distribution Channel:
Channel selection tracks customer scale and specification complexity, with direct sales dominating validated medical grades and wholesale channels handling commodity electronics cushioning.
- Direct Sales:Converters maintain captive technical service relationships for ISO 11607 sterilization validation and REACH Article 33 documentation. German medical supply converters deploy field engineers to calibrate nine-layer die geometries for oxygen barrier consistency.
- Wholesale:Distributors aggregate demand from mid-sized electronics manufacturers with standardized polythene specifications. Inventory pooling reduces working capital requirements for regional converters.
- Online Retail:Small-volume procurement of specialty grades for prototyping and short-run production. ECHA microplastics restriction roadmaps accelerate searchable demand for bio-based sealant alternatives.
- Traditional Retail:Limited penetration given technical specification requirements and batch traceability needs.
Direct sales capture the highest margin pool; wholesale channels expand most quickly as distributor consolidation standardizes procurement workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Caprolactam polymerization complexes in Belgium and Germany concentrate barrier-grade nylon supply, creating regional dependency patterns that reshape procurement strategies across industrial corridors.
United States
Semiconductor logistics networks in Texas and California mandate automated inflate-on-demand systems for fragile chip components. FDA 21 CFR 177.1520 compliance governs polyolefin food-contact layers in medical supply chains. Electronics fulfillment operators in Austin and Silicon Valley unbundle packaging from transportation contracts to secure direct converter relationships.
Germany
Automotive parts exporters in Bavaria and Baden-Württemberg require burst-resistant films validated under dynamic load testing for transcontinental rail routes. REACH Article 33 SVHC disclosure obligations force documentation of phthalate-free plasticizer migration below 0.1% w/w. The industrial corridor around Stuttgart anchors demand for high-pressure inflatable cushioning systems.
China
Dual carbon goals under MEE oversight accelerate R&D pivots toward bio-based sealant alternatives in Yangtze River Delta manufacturing zones. Electronics OEMs in Shenzhen and Shanghai specify stiffness-to-weight optimized constructions for lightweight component protection. Nylon resin import dependence creates vulnerability to Belgian and German supply disruptions.
Belgium
Caprolactam feedstock polymerization complexes in the Port of Antwerp region supply European barrier-grade nylon demand. ECHA microplastics restriction roadmaps force formulation chemistry toward water-dissolvable alternatives before 2027 enforcement phases. Converters document REACH compliance to capture medical supply contracts from PVC-dependent competitors.
India
PLI scheme incentives for electronics manufacturing concentrate packaging demand in Karnataka and Tamil Nadu industrial corridors. BIS standards govern material specifications for domestic medical device supply chains. Third-party logistics operators in Bengaluru deploy automated inflate-on-demand platforms to reduce warehouse cube requirements.
High Pressure Protective Packaging Film Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with resin compounding capabilities and multilayer coextrusion expertise separating premium-tier converters from commodity suppliers. The vendor base organizes around three strategic archetypes: integrated resin-to-film operators controlling specification drift, automated systems specialists compressing fulfillment cube requirements, and paper-film hybrid platforms satisfying sustainability scorecards. Dominant competitive moves include backward integration into captive resin compounding networks and geographic expansion through regional plant synchronization.
Among North American fabricators, Sealed Air Corporation and Pregis LLC occupy positions representing divergent strategic vectors—one anchored in resin supply control, the other in automated fulfillment integration. Mondi Group exemplifies the European paper-film hybrid archetype. These three entities collectively illustrate how competitive positioning fragments across material science, systems integration, and substrate diversification pathways.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis LLC |
| Amcor Plc |
| Berry Global Inc. |
| Barton Jones Packaging Ltd |
| Mondi Group |
| Supreme Industries Limited |
| Storopack Hans Reichenecker GmbH |
| Rajapack Limited |
| Others |
Value Chain & Pricing Dynamics
ISO 11607 sterilization validation timelines gate both supply qualification and price differentiation simultaneously, separating medical-grade converters who absorb 18-24 month certification cycles from commodity suppliers competing on volume terms. REACH Article 33 SVHC disclosure obligations in Europe and FDA 21 CFR 177.1520 compliance in the United States create tiered entry barriers that directly map to margin capture potential across electronics, medical, and food-contact segments.
Pricing Analysis
REACH Article 33 dictates the pricing tier structure by forcing documentation costs onto European converters seeking medical supply contracts. Three-tier pricing structure across premium, standard, and economy levels separates ISO 11607-validated medical grades from industrial cushioning and commodity electronics formats. Cost compression in standard-tier polythene formulations is intensifying because logistics providers consolidate buying power through quarterly negotiation frameworks. Electronics fulfillment networks show highest price sensitivity due to unbundled packaging procurement, while medical supply buyers prioritize certification continuity over unit cost.
Supply Chain Analysis
Strategic stockpiling of caprolactam feedstock dominates inventory strategy among European converters buffering against Belgian and German polymerization complex disruptions. Supply concentrates in Belgium, Germany, and China, with nylon resin dependence tethered to Port of Antwerp caprolactam facilities and Yangtze River Delta extrusion capacity. Raw material flows draw from petroleum-based polyolefins, bio-based sealant alternatives, and oriented nylon feedstocks. Single-source vulnerability to energy-cost spikes in European polymerization corridors threatens margin stability. Distribution runs through direct technical-service relationships for validated grades and wholesale pooling for standardized electronics specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks semiconductor capital expenditure cycles, with logistics provider procurement accelerating during chip fabrication capacity buildouts. Recovery positioning favors converters with pre-qualified medical certifications and regional plant synchronization capabilities.
For Market Incumbents: Secure backward integration into captive resin compounding networks to control specification drift across dispersed manufacturing footprints. Deepen certification moats by accelerating ISO 11607 validation pipelines before soluble film substitution threats mature. Defend against paper-film hybrid platforms by demonstrating inflation integrity parity in sustainability scorecard negotiations with German automotive exporters. For New Entrants and Emerging Players: Anchor in modified atmosphere meat shipping corridors across France and Italy where barrier-grade nylon coextrusion demand outpaces qualified converter supply. Target California SB 54 compliance services as a white-space entry point, offering documented circularity pathways to distributors facing extended producer responsibility mandates. Lead with automated inflate-on-demand system integration to capture logistics provider relationships unbundling packaging from transportation contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multilayer coextrusion platforms as nine-layer die geometry calibration demands specialized technician recruitment. Five-to-ten year viability favors integrated resin-to-film operators with regional plant networks synchronized for oxygen transmission consistency. Acquisition screening should prioritize converters with REACH Article 33 documentation infrastructure and Belgian or German caprolactam supply proximity. Monitor ECHA microplastics restriction roadmap enforcement phases as inflection signal for soluble film substitution pace.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Sealed Air Corporation's captive network controls specification drift across regional plants. |
| Automated Inflate-on-Demand Deployment | Pregis LLC compresses warehouse cube requirements by 40-60% for North American electronics fulfillment. |
| Paper-Film Hybrid Platform Development | Mondi Group satisfies dual substrate sourcing strategies for European sustainability scorecards. |
| ISO 11607 Sterilization Validation Investment | Medical supply converters capture margin pools through 18-24 month certification barriers. |
| Bio-Based Sealant Layer R&D Pivot | European converters preempt ECHA microplastics enforcement with polylactic acid blend pilots. |
Study Parameters
A spread of perspectives from extrusion plant managers, logistics procurement leads, medical device regulatory affairs directors, and resin compounding technical specialists converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC 10-K filings, ECHA restriction roadmap documents, FDA 21 CFR guidance updates, and European converters' REACH disclosure filings. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across the analysis window.
Segmentation dimensions modeled include material chemistry tier, end-use application specification, procurement channel structure, and regional regulatory cluster. CAGRs derived from slope analysis of historical shipment data and forward projection of semiconductor logistics expansion and automotive export corridor demand. Industry-specific forecast inputs incorporated caprolactam polymerization capacity utilization rates and automated inflate-on-demand system deployment trajectories.
Material uncertainties — force majeure events in Belgian and German polymerization complexes, ECHA microplastics restriction acceleration, soluble film technology substitution pace — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline stability and resin supply continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Insulated Styrofoam Shipping Boxes Market
Protective Packaging
North America Protective Packaging Market
Protective Packaging
Secondary Containment Trays Market
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Adhesive Bubble Wrap Market
Protective Packaging
Insulated Shipping Boxes Market
Protective Packaging
South Africa Protective Packaging Market
Protective Packaging
North America Insulated Packaging Market
Protective Packaging
Static Shielding Bags Market
Protective Packaging
Foam Edge Protectors Market
Protective Packaging
Asia-Pacific Protective Packaging Market
Protective Packaging
Middle East and Africa Protective Packaging Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Corrugated Bubble Wrap Market
Protective Packaging
Insulated Packaging Market
Protective Packaging
Thermal Insulated Mailers Market