
 Protective Packaging Market | 2026-2036
Protective Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Protective Packaging Market Insights
Market Context
German converters is restructuring capacity around fiber-based alternatives as brand owners phase out single-use plastics. Sealed Air Corporation leverages its global film extrusion footprint to serve electronics fulfillment hubs across Asia. Pregis anchors North American operations with automated inflatable systems for last-mile delivery networks. Sonoco Products Company competes through molded pulp tooling expertise in food service and industrial channels.
Technical Definition and Segment Structure
Protective packaging encompasses engineered materials and containers designed to absorb mechanical shock, vibration, and environmental stress during product transit, typically incorporating cellular foam structures, fluted fiberboard geometries, or air-entrained polymer films to maintain dimensional stability. Foam and corrugated boxes dominate value capture due to established recycling infrastructure and scale economies in converting operations. Biodegradable polymers represent the fastest-expanding material category as food delivery platforms in Europe and North America face EPR compliance deadlines. Electronics shipping and pharmaceutical transport concentrate margin pools where temperature integrity and electrostatic discharge specifications command premium validation protocols.
Regulatory Frame and Outlook
The EU Green Deal and REACH frameworks restrict persistent polymer additives in cushioning films, while FDA and EPA guidelines in the United States govern pharmaceutical packaging integrity and recycled content claims. ECHA substance evaluations and state-level extended producer responsibility laws in California and New York are forcing reformulation timelines across polyethylene and polypropylene supply chains. Stakeholders must monitor harmonization gaps between EU Packaging and Packaging Waste Regulation implementation and divergent US state mandates to avoid compliance fragmentation in cross-border fulfillment networks.
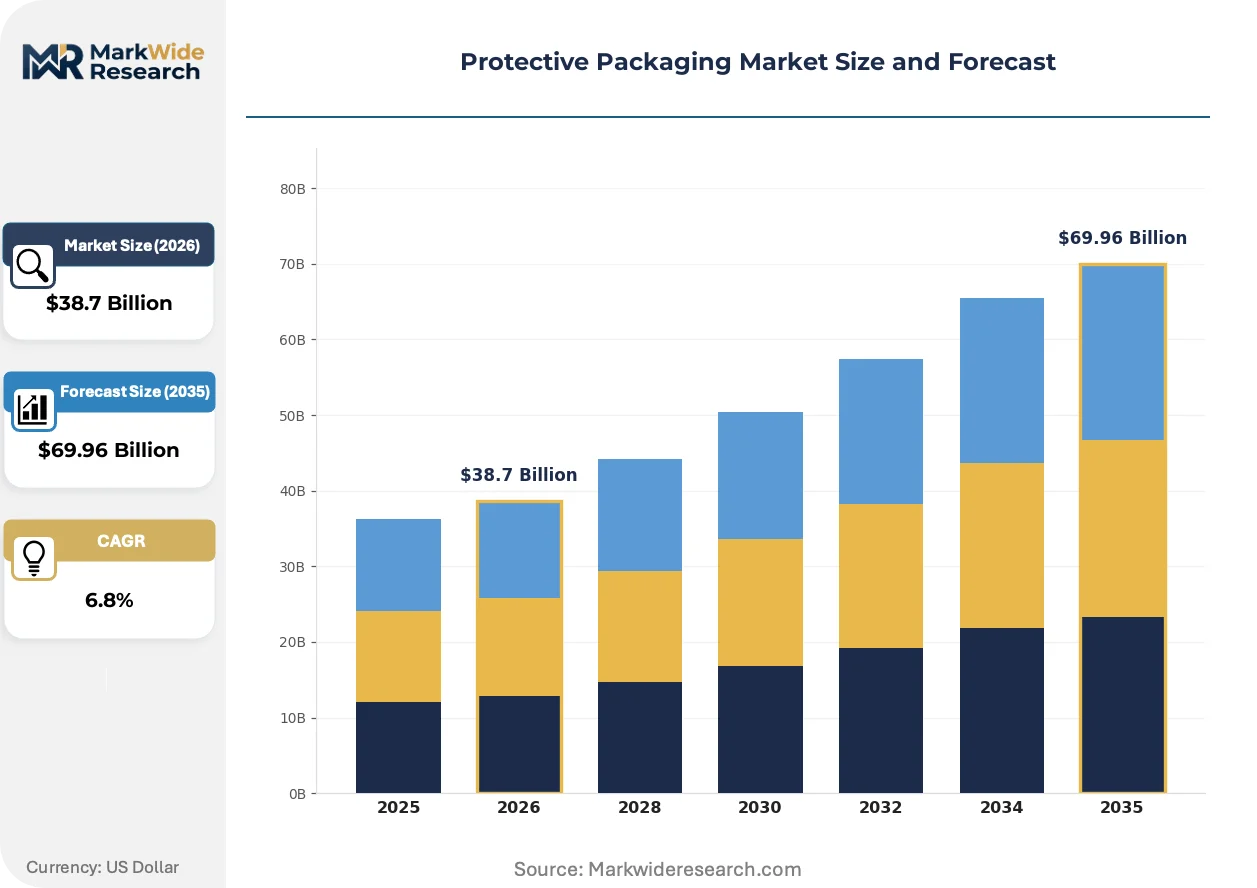
Market Dynamics
E-commerce fulfillment velocity is compressing packaging specification cycles from annual to quarterly reviews as electronics and pharmaceutical distributors demand just-in-time cushioning configurations.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content thresholds in cushioning films are pulling fiber-based alternatives into automotive parts distribution networks across Germany and France.
- Electronics fulfillment hubs:Asia-Pacific semiconductor assembly plants are specifying anti-static foam formats for chip shipments, expanding addressable demand for advanced polymer formulations.
- Automated inflatable systems:Last-mile delivery platforms in North America are retrofitting sortation facilities with on-demand air cushion generation, reducing dimensional weight penalties.
Market Restraints
- Polypropylene feedstock volatility:Crude-linked resin pricing swings compress converter margins and deter long-term supply contracts with food delivery platforms.
- Recycling infrastructure gaps:Multi-material laminated films lack stream-compatible recovery pathways in municipal waste systems across Italy and Spain.
- Biodegradable polymer performance ceiling:PLA and PHA cushioning materials fail drop-test specifications above 1.5 meters for heavy industrial components.
Strategic Opportunities
- India pharmaceutical cold chain:Temperature-validated insulated shippers for vaccine distribution remain underpenetrated relative to CDSCO serialization mandates.
- Reusable loop systems:Reverse logistics platforms for high-value electronics are piloting returnable molded pulp containers in German industrial corridors.
- Digital watermarks:AIM-standard invisible markers on fiberboard are enabling automated sortation compliance with extended producer responsibility schemes in California and New York.
Industry Challenges
- Composting certification timelines:TÜV Austria and BPI validation protocols for biodegradable films extend 14-18 months, delaying product launches past EPR compliance deadlines.
- Legacy ERP integration:Converter inventory systems struggle to track batch-level recycled content certificates required by EU Green Deal reporting frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protective Packaging Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Foam, Corrugated Boxes, Bubble Wrap, Padded Mailers, Air Pillows, Paper Wrap Material Type: Polyethylene, Polypropylene, Kraft Paper, Molded Pulp, PET, Biodegradable Polymers Application: Electronics Shipping, Pharmaceutical Transport, Food Delivery, Furniture Protection, Cosmetics Handling, Industrial Equipment End User Industry: Consumer Electronics, Healthcare Providers, Food & Beverage, Furniture Manufacturers, Personal Care, Heavy Machinery |
| Companies Covered | Sealed Air Corporation, Pregis, Sonoco Products Company, Smurfit Westrock, Amcor, Mondi, DS Smith, Ranpak Holdings, Storopack Hans Reichenecker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protective Packaging Market Trends and Innovations
Material science convergence with digital tracking is collapsing the traditional separation between physical protection and supply chain visibility, creating integrated performance requirements that reshape converter R&D priorities.
Expanded polystyrene alternatives derived from mycelium and agricultural waste are decentralizing molded pulp production from centralized paper mills to regional biomass processing facilities. Furniture and appliance manufacturers in the Netherlands and Belgium are qualifying these formats for 72-hour humidity exposure. The shift is compressing freight costs and lead times for bulky item cushioning.
REACH substance restrictions on persistent organic pollutants in polyurethane foams are forcing reformulation of electronics shipping inserts across EU member states. German automotive suppliers are accelerating qualification of water-blown foam systems to maintain CE marking compliance. The transition is elevating capital requirements for mid-tier converters lacking in-house chemical engineering capabilities.
Pharmaceutical distributors are consolidating packaging specifications around pre-qualified temperature assurance platforms, displacing custom-engineered solutions for generic biologic shipments. This specification compression concentrates purchasing power with three North American and two European contract packagers. The pattern is most visible in insulin and monoclonal antibody distribution networks where FDA validation protocols create switching costs.
Protective Packaging Market Segmentation
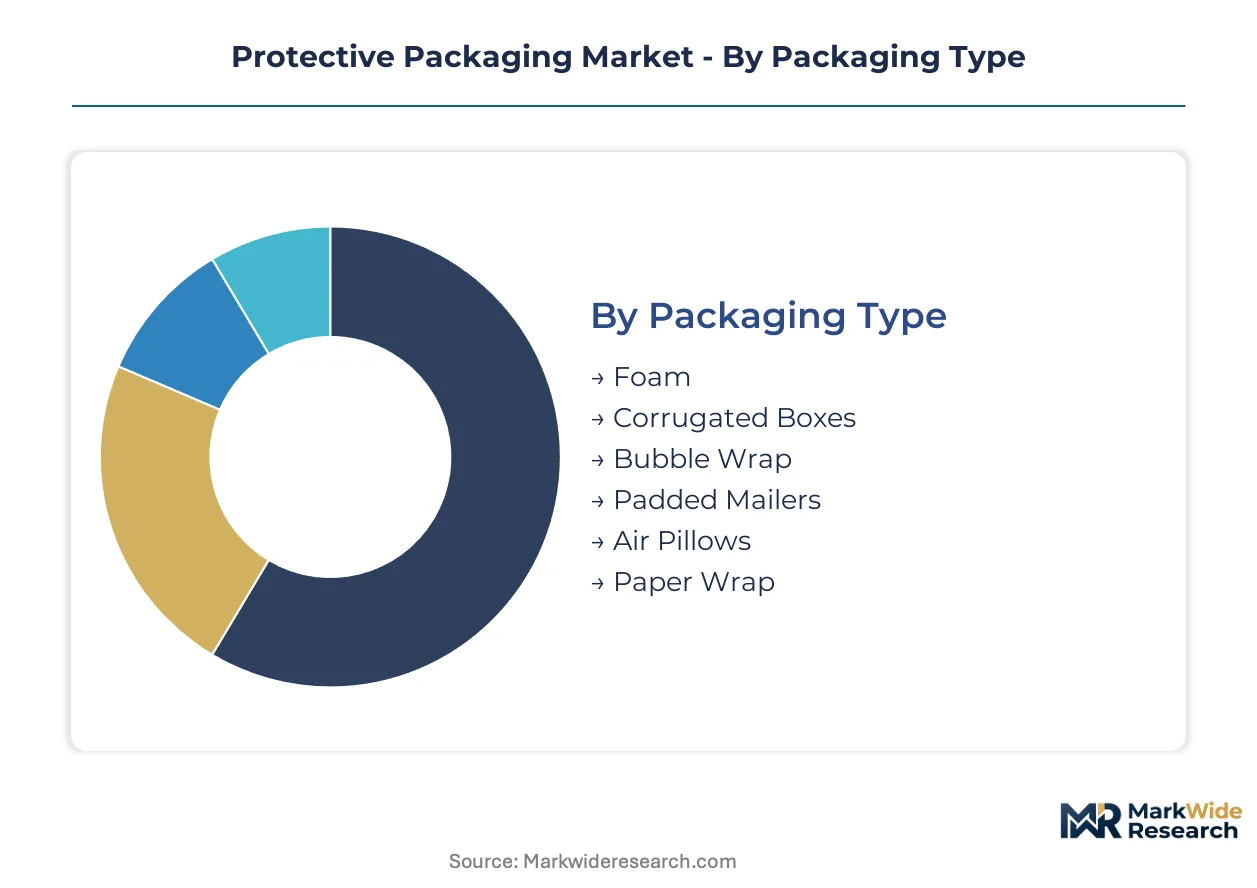
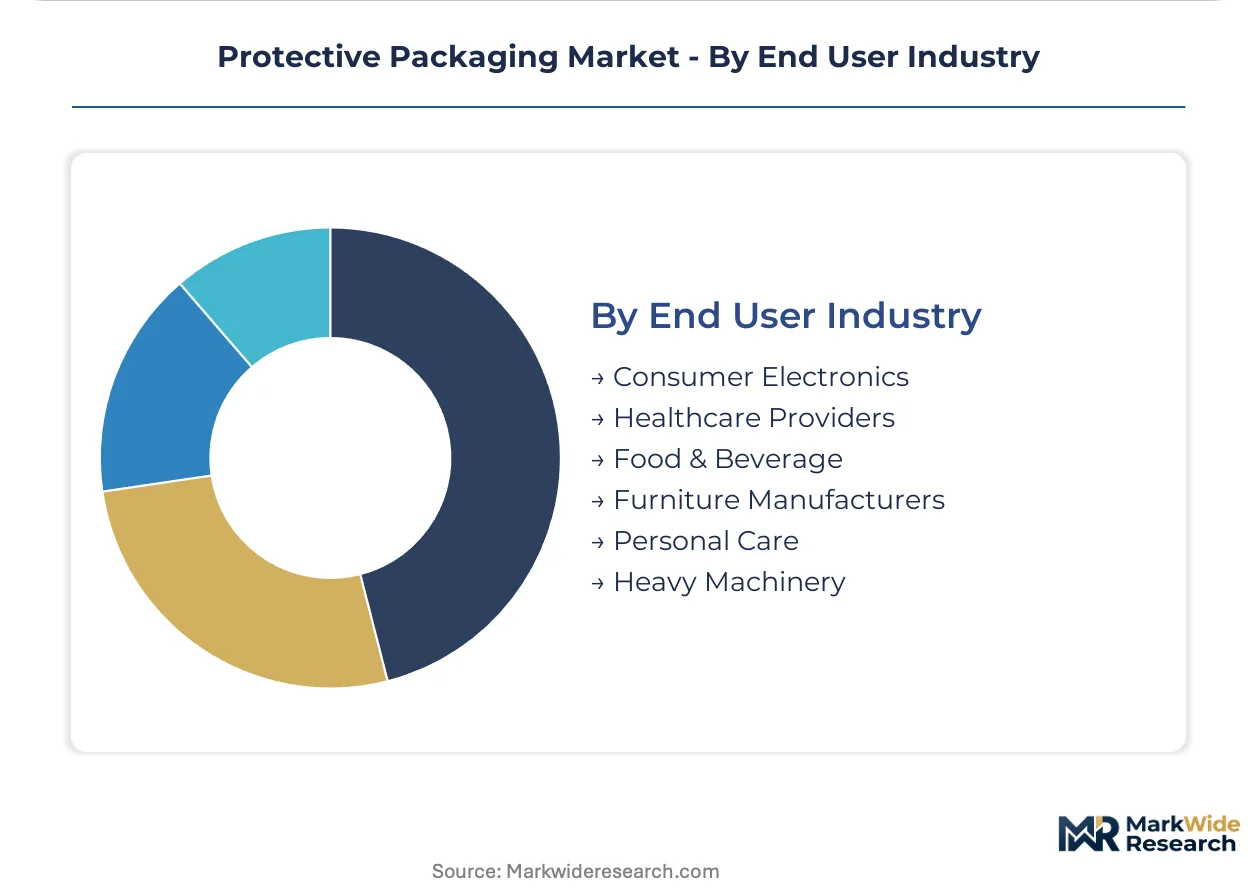
Protective packaging segmentation reflects divergent certification burdens across pharmaceutical, electronics, and food channels. Specification cycles compress where temperature validation or electrostatic discharge protocols apply, creating tiered margin structures that reshape converter investment priorities.
Packaging Type:
FDA validation protocols govern pharmaceutical foam formats, while REACH substance restrictions reshape corrugated specifications for EU electronics fulfillment.
- Foam:Polyurethane and expanded polystyrene structures absorb multi-axis shock in semiconductor shipments. German automotive suppliers specify water-blown formulations to maintain CE marking compliance amid REACH restrictions on persistent organic pollutants.
- Corrugated Boxes:Fluted fiberboard geometries integrate digital watermarks for automated sortation under California and New York extended producer responsibility schemes. E-commerce fulfillment hubs in the Netherlands specify humidity-resistant grades for 72-hour furniture protection cycles.
- Bubble Wrap:Air-entrained polyethylene films serve electronics distributors requiring anti-static surface resistivity below 10^11 ohms.
- Padded Mailers:Fiber-lined envelopes balance dimensional weight reduction with fiber-based EPR compliance for European book and cosmetic shipments.
- Air Pillows:On-demand inflatable systems reduce freight cube in North American last-mile networks.
- Paper Wrap:Kraft-based cushioning qualifies for TÜV Austria composting certification in Belgian food delivery platforms.
Foam sits at the top of the volume ranking, with paper wrap climbing the fastest.
Material Type:
Cost tiers separate commodity resins from certified biodegradable alternatives commanding 40-60% premiums in regulated European markets.
- Polyethylene:Linear low-density films dominate air pillow production with established recycling codes. California's SB 54 mandates drive post-consumer content integration for e-commerce mailers.
- Polypropylene:Biaxially oriented sheets provide clarity in electronics viewing windows. Crude-linked pricing volatility compresses converter margins and deters long-term supply contracts.
- Kraft Paper:Unbleached virgin and recycled fibers supply corrugated medium and wrap formats. Dutch furniture manufacturers qualify agricultural waste-derived alternatives for humidity exposure protocols.
- Molded Pulp:Thermoformed fiber structures replace expanded polystyrene in food service channels. BPI certification timelines extend 14-18 months, delaying launches past EPR deadlines.
- PET:Clear thermoformed trays serve pharmaceutical blister packaging with FDA validation requirements.
- Biodegradable Polymers:PLA and PHA formulations face performance ceilings above 1.5-meter drop tests for heavy industrial components.
Polyethylene maintains the broadest application base, with biodegradable polymers gaining share fastest in food delivery compliance channels.
Application:
Customer procurement patterns stratify between validated pharmaceutical platforms and specification-fluid e-commerce categories.
- Electronics Shipping:Anti-static foam and corrugated formats protect semiconductor assemblies. Asia-Pacific chip fabricators specify ionic contamination thresholds below 10 ppm for cleanroom compatibility.
- Pharmaceutical Transport:Temperature-assurance packaging for biologics requires FDA pre-qualification and CDSCO serialization alignment in India. Three North American contract packagers concentrate purchasing power for insulin distribution.
- Food Delivery:Fiber-based alternatives displace laminated films under EU Packaging and Packaging Waste Regulation recycled content thresholds.
- Furniture Protection:Mycelium-derived cushioning compresses freight costs for Netherlands and Belgium manufacturers.
- Cosmetics Handling:Premium unboxing experiences drive padded mailer specifications in French and Italian direct-to-consumer channels.
- Industrial Equipment:Heavy-gauge foam and corrugated combinations absorb forklift impact in German automotive parts distribution.
Electronics shipping leads by unit volume, with pharmaceutical transport expanding most quickly on cold chain infrastructure buildouts.
End User Industry:
Supply concentration in German industrial corridors and North American electronics hubs dictates regional converter capacity allocation.
- Consumer Electronics:Smartphone and laptop distributors compress packaging specification cycles to quarterly reviews. Sealed Air Corporation serves Asia-Pacific fulfillment hubs with film extrusion networks.
- Healthcare Providers:Hospital and pharmacy networks consolidate around pre-qualified temperature assurance platforms. FDA validation protocols create switching costs for generic biologic shipments.
- Food & Beverage:Meal kit platforms and quick-service chains face divergent EPR deadlines across EU member states and US states.
- Furniture Manufacturers:Flat-pack retailers in Sweden and Poland specify humidity-resistant fiberboard for export containerization.
- Personal Care:Cosmetic brands prioritize unboxing aesthetics in direct-to-consumer channels.
- Heavy Machinery:German automotive suppliers drive shock-absorbing foam specifications for just-in-time parts distribution.
Consumer electronics commands the largest addressable base, with healthcare providers showing the steepest expansion trajectory on biologics distribution growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive corridor generates denser cushioning demand per capita than India's pharmaceutical hubs, yet both markets face converging pressure from EPR compliance timelines and cold chain infrastructure gaps.
Germany
Automotive parts distribution networks in Bavaria and Baden-Württemberg specify water-blown polyurethane foams to satisfy REACH restrictions on persistent organic pollutants. The EU Packaging and Packaging Waste Regulation mandates recycled content thresholds that pull fiber-based alternatives into Stuttgart's just-in-time supply chains. Stuttgart's industrial cluster anchors shock-absorbing format qualification for CE-marked components.
United States
Electronics fulfillment hubs in California and Texas compress packaging specification cycles to quarterly reviews as smartphone distributors demand just-in-time cushioning. California's SB 54 mandates post-consumer content integration for e-commerce mailers, while New York's extended producer responsibility laws force reformulation timelines. The Pacific Northwest hosts pilot programs for returnable molded pulp containers in reverse logistics platforms.
China
Semiconductor assembly plants in the Yangtze River Delta specify anti-static foam formats with ionic contamination thresholds below 10 ppm for cleanroom compatibility. MIIT guidelines on dual carbon goals accelerate fiber-based alternative qualification in Shanghai's electronics corridors. Suzhou's chip fabrication cluster drives advanced polymer formulation demand for export shipments.
India
Pharmaceutical cold chain infrastructure for vaccine distribution remains underpenetrated relative to CDSCO serialization mandates, creating specification gaps for temperature-validated insulated shippers. Maharashtra's biologics manufacturers consolidate purchasing power around pre-qualified platforms. Mumbai-Pune corridor distributors face pressure to align FDA validation protocols with domestic regulatory requirements.
Netherlands
Furniture manufacturers in Randstad qualify mycelium-derived cushioning for 72-hour humidity exposure protocols, compressing freight costs for flat-pack export containerization. The EU Green Deal frameworks restrict persistent polymer additives in cushioning films used by Rotterdam's logistics hubs. Eindhoven's industrial region pilots decentralized biomass processing for agricultural waste-based molded pulp production.
Protective Packaging Market Competitive Landscape
North American producers anchor the automated inflatable systems tier; European specialists hold fiber-based alternative expertise. The vendor base stratifies across three tiers: multinational film extruders with global fulfillment footprints, regional corrugated converters with digital watermark integration capabilities, and niche biodegradable polymer formulators facing 14-18 month certification timelines. Strategic moves concentrate on capacity restructuring around fiber-based alternatives and M&A targeting automated inflatable system technology.
Within the multinational film extrusion tier, Sealed Air Corporation and Amcor occupy positions serving electronics fulfillment hubs with established recycling code infrastructure. Pregis exemplifies the automated inflatable systems archetype for last-mile delivery networks. Among fiber-based specialists, Smurfit Westrock and DS Smith represent corrugated converters integrating digital watermarks for extended producer responsibility compliance. Sonoco Products Company sits within the molded pulp tooling segment for food service and industrial channels. Mondi and Ranpak Holdings anchor kraft paper and paper wrap qualification for TÜV Austria composting certification timelines.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis |
| Sonoco Products Company |
| Smurfit Westrock |
| Amcor |
| Mondi |
| DS Smith |
| Ranpak Holdings |
| Storopack Hans Reichenecker |
| Others |
Pricing and Supply Chain Analysis
EU Packaging and Packaging Waste Regulation recycled content thresholds gate qualified supply access for converters serving German automotive and French electronics channels, with certified fiber-based alternatives commanding 40-60% premiums over commodity polyethylene films while excluding uncertified competitors from premium-tier procurement pools.
Pricing Analysis
Capacity additions in Southeast Asia are reshaping price floors for polyethylene air pillow films as Vietnamese and Thai extruders expand output for e-commerce fulfillment hubs. Three-tier pricing structure across certified sustainable, standard recyclable, and uncertified commodity tiers separates converters with TÜV Austria validation from those lacking composting certification. Cost compression in standard recyclable tiers is intensifying because crude-linked polypropylene resin swings compress converter margins. Food delivery platforms in Europe show highest price sensitivity due to EPR compliance deadline pressure, while pharmaceutical distributors demonstrate lowest sensitivity given FDA validation switching costs.
Supply Chain Analysis
Dual-sourcing requirements from German automotive OEMs and North American electronics distributors mandate multi-supplier qualification for polyurethane foam and corrugated fiberboard formats. Supply concentrates in Germany, China, and the United States for molded pulp tooling and automated inflatable system manufacturing. Raw material dependencies center on linear low-density polyethylene resin, unbleached kraft pulp, and water-blown polyurethane foam precursors. Single-source vulnerability runs through specialized anti-static additive suppliers serving semiconductor packaging channels. Distribution runs through converter-direct relationships with fulfillment hub operators and contract packaging networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The protective packaging market functions as a stable compounder, with e-commerce fulfillment velocity driving steady replacement demand for cushioning configurations across quarterly specification cycles.
For Market Incumbents: Anchor defensive positioning through backward integration into regional fiber pulping operations and captive supply of agricultural waste feedstocks for mycelium-derived alternatives. Sealed Air Corporation and Smurfit Westrock should accelerate digital watermark integration capabilities to lock in California and New York EPR compliance channels. Certification investment in TÜV Austria and BPI validation protocols creates switching costs against mid-tier converters lacking 14-18 month compliance timelines. For New Entrants and Emerging Players: E-commerce fulfillment platform procurement teams represent the most accessible channel partner type for biodegradable polymer formulators seeking initial volume traction. Target India's pharmaceutical cold chain infrastructure gap where temperature-validated insulated shippers remain underpenetrated relative to CDSCO serialization mandates. Pilot reusable loop systems with German electronics reverse logistics platforms as the go-to-market angle, leveraging decentralized biomass processing cost advantages against centralized paper mill incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier corrugated converters lacking automated inflatable system technology or digital watermark integration capabilities. The five-to-ten-year viability window favors targets with established FDA or CE marking validation protocols in pharmaceutical and electronics channels. Watch composting certification backlog clearance rates as the inflection signal for biodegradable polymer segment margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Pulping | Captive supply of agricultural waste feedstocks secures TÜV Austria certification timelines for EU automotive channels. |
| Digital Watermark Integration | AIM-standard invisible markers enable automated sortation compliance with California SB 54 and New York EPR mandates. |
| Water-Blown Foam Reformulation | REACH-compliant polyurethane systems maintain CE marking access for German automotive parts distribution networks. |
| Automated Inflatable System Deployment | On-demand air cushion generation reduces dimensional weight penalties in North American last-mile delivery platforms. |
| Reusable Loop System Pilot | Returnable molded pulp containers capture margin pools in German electronics reverse logistics corridors. |
Research Methodology
Bottom-up e-commerce fulfillment modeling reconciled against top-down converter capacity tracking forms the analytical core of this study. Primary interviews with packaging procurement managers at electronics distributors, pharmaceutical contract packagers, automotive supply chain directors, and corrugated converter operations heads combined with secondary validation from EU Packaging and Packaging Waste Regulation implementation reports, FDA 483 inspection databases, ECHA substance restriction updates, and SEC 10-K filings from listed packaging producers. Trade data from German Federal Statistical Office and US Census Bureau import records anchored regional demand calibration.
Historical trendline analysis of specification cycle compression and material substitution rates informed the projection framework across the analysis window. Segmentation dimensions modeled include packaging type, material certification tier, end-use application, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating EPR compliance deadline phasing and cold chain infrastructure buildout trajectories. Forecast inputs included semiconductor shipment volumes and biologics distribution growth patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance restriction expansions and biodegradable polymer drop-test performance breakthroughs. Deviation in EU member state EPR harmonization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Fiber Cushioning Market
Protective Packaging
Inflatable Packaging Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Protective Wrapping Paper Market
Protective Packaging
Anti-Corrosive Packaging Market
Protective Packaging
High Pressure Protective Packaging Film Market
Protective Packaging
North America Protective Packaging Market
Protective Packaging
Padded Mailers Market
Protective Packaging
Middle East and Africa Protective Packaging Market
Protective Packaging
Global Packaging Inserts and Cushions Market
Protective Packaging
Static Shielding Bags Market
Protective Packaging
Thermal Insulated Bubble Wrap Market
Protective Packaging
Packaging and Protective Packaging Market
Protective Packaging
Grease Resistant Packaging Market
Protective Packaging
Padded Dividers Market
Protective Packaging
Tamper Proof Packaging Market