
 Secondary Containment Trays Market | 2026-2036
Secondary Containment Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Secondary Containment Trays Market Analytics
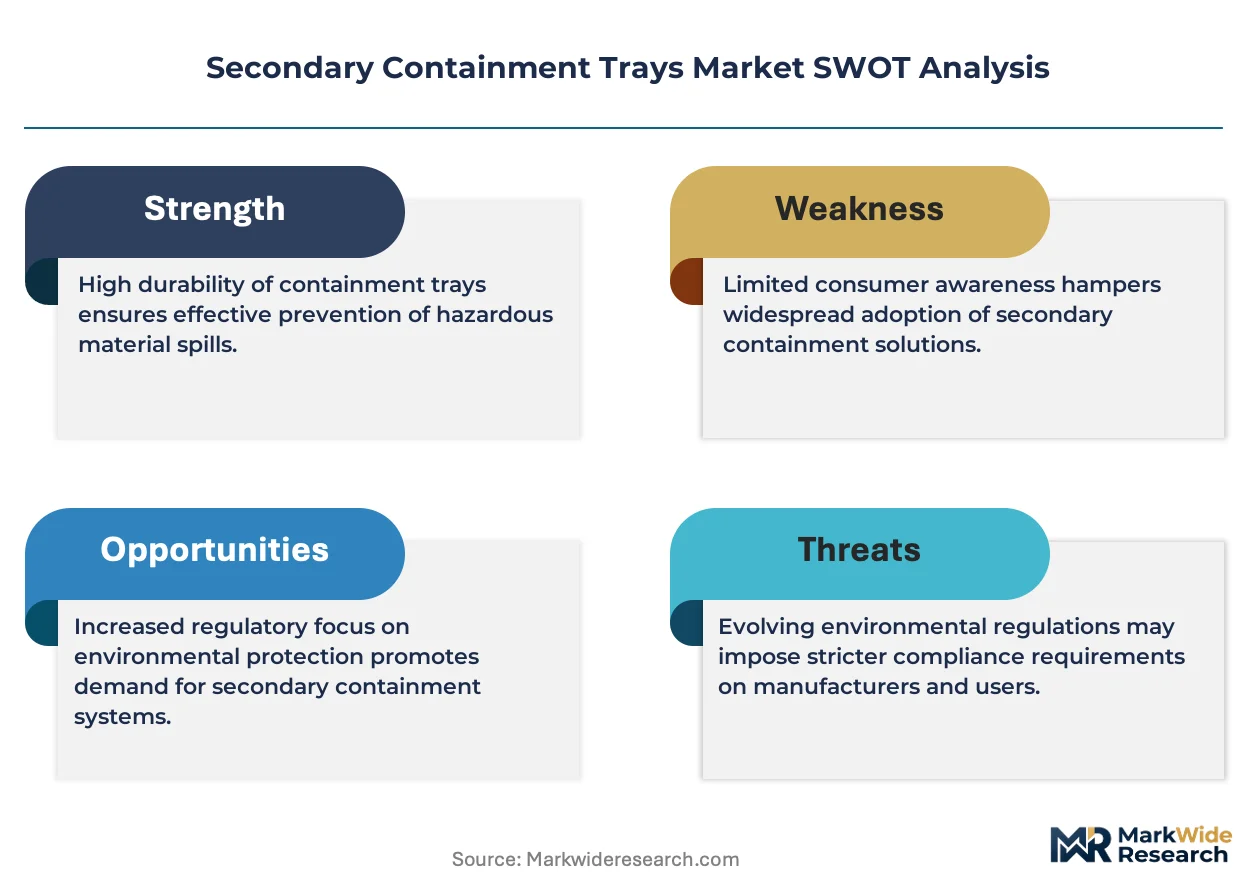
Heavy-duty specification-grade containment is rotating toward higher load-bearing and chemical-resistance ratings across industrial procurement. DENIOS leverages its European manufacturing footprint to serve German chemical clusters with certified bund systems. Eagle Manufacturing anchors North American distribution through extensive dealer networks focused on OSHA-compliant spill containment. UltraTech International differentiates via specialized polyethylene formulations engineered for aggressive solvent exposure.
Secondary containment trays are rigid or semi-rigid receptacles, typically fabricated from high-density polyethylene, steel, or fiberglass-reinforced polymers, designed to capture leaks, drips, or catastrophic spills from primary containers holding hazardous liquids. Their core industrial purpose is preventing soil and water contamination while ensuring worker safety during chemical transfer, storage, and handling operations. Polyethylene trays lead volume shipments due to corrosion immunity and lower installed cost, though steel variants retain margin pools in high-temperature and heavy-load applications. Custom sizing is expanding fastest among pharmaceutical cleanroom installations where dimensional precision integrates with automated workflow systems.
EPA Spill Prevention, Control, and Countermeasure rules and OSHA workplace safety standards directly shape product specifications and facility compliance timelines across the United States. REACH chemical authorization requirements and EU Seveso III directives on major accident hazards similarly drive retrofit demand throughout European industrial zones. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as these chemicals historically appear in certain tray coatings and could force material transitions across installed bases.
Market Dynamics
EPA Spill Prevention, Control and Countermeasure enforcement is compressing replacement cycles for aging containment infrastructure across US chemical facilities, forcing capital redeployment toward certified polyethylene systems before mandated compliance deadlines.
Growth Catalysts
- REACH Authorization Requirements:European chemical manufacturers must retrofit storage areas with compliant bund systems, creating sustained demand for corrosion-resistant containment across German and Dutch industrial clusters.
- Pharmaceutical Cleanroom Expansion:Biologics manufacturing facilities require precision-dimensioned trays that integrate with automated material handling systems, driving specification-grade procurement in US and European drug production centers.
- Refinery Downstream Investment:Petrochemical capacity additions along the US Gulf Coast are generating concentrated demand for high-volume polyethylene containment solutions at new cracking and derivative units.
Market Restraints
- HDPE Resin Price Volatility:Feedstock cost fluctuations for high-density polyethylene directly compress margins for tray fabricators, particularly those without long-term supply contracts with Gulf Coast polymer producers.
- Steel Tray Substitution Pressure:High-temperature chemical processing above polyethylene thermal limits retains demand for steel containment, fragmenting volume concentration and complicating procurement standardization.
- REACH Per-Fluorinated Substance Restrictions:Pending limitations on PFAS-containing coatings threaten existing installed bases, potentially forcing premature replacement of otherwise functional steel tray systems.
Strategic Opportunities
- Indian Chemical Manufacturing Expansion:Petrochemical investments under the country's PLI scheme and state-level industrial corridor development are creating first-mover positioning for containment suppliers establishing local fabrication partnerships.
- Modular Spill Response Integration:Convergence of IoT leak detection sensors with smart containment systems enables predictive maintenance contracts, shifting revenue from product sales to recurring service arrangements.
- EU Seveso III Retrofit Mandates:Major accident hazard directives are accelerating facility-wide containment upgrades at existing European chemical sites, extending replacement demand beyond new construction cycles.
Industry Challenges
- Polymer Welding Certification Shortage:Qualified technicians for FDA-compliant polyethylene fabrication remain scarce, constraining capacity expansion for pharmaceutical-grade containment production.
- Multi-Jurisdictional Compliance Complexity:Trays serving cross-border chemical logistics must simultaneously satisfy EPA, REACH, and transport regulations, extending product development timelines and testing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Secondary Containment Trays Market |
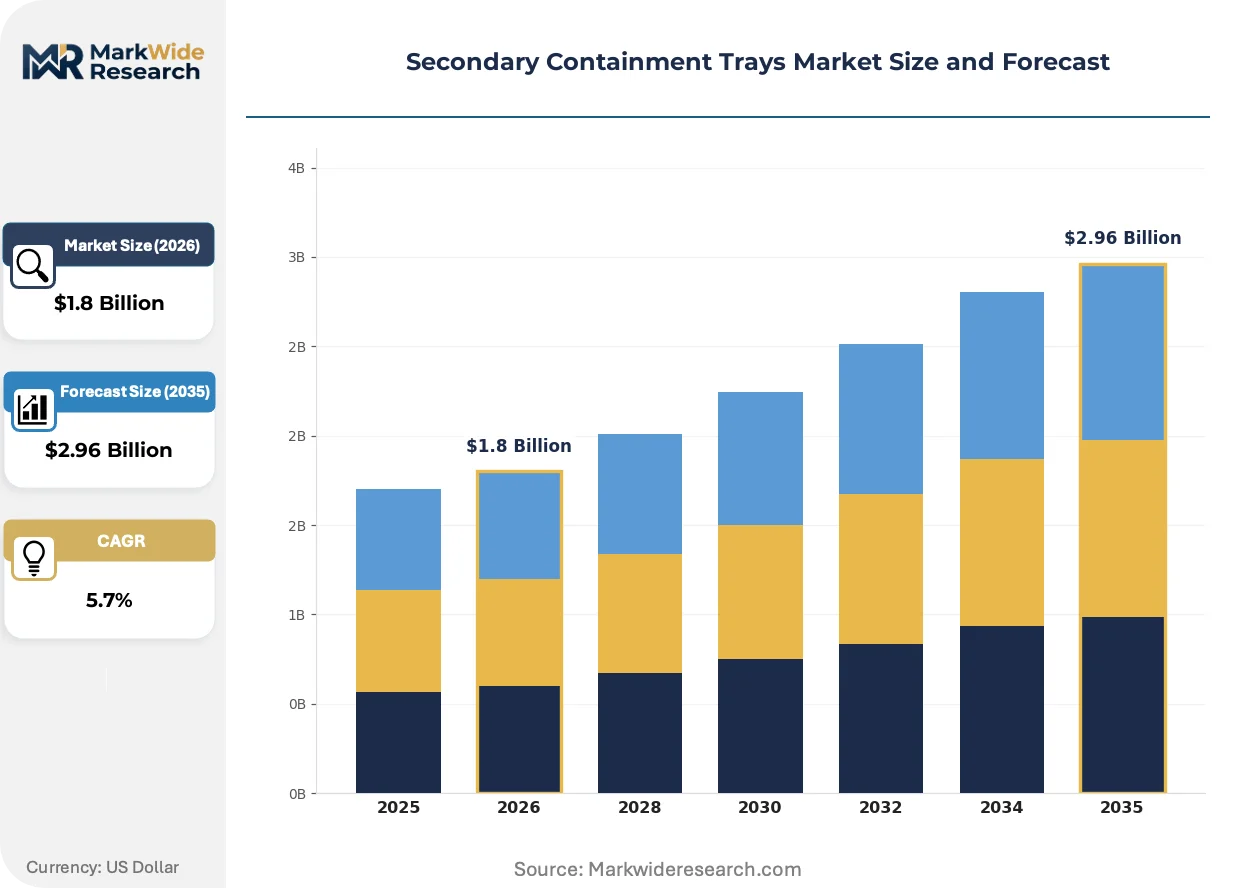
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Trays, Steel Trays, Polyethylene Trays, Fiberglass Trays End User: Chemical Industry, Pharmaceutical Sector, Oil & Gas, Environmental Agencies Application: Hazardous Waste Storage, Spill Prevention, Chemical Handling, Lab Safety Size: Small, Medium, Large, Custom |
| Companies Covered | DENIOS, Eagle Manufacturing, UltraTech International, Justrite Manufacturing, New Pig Corporation, ENPAC, Brady Corporation, SafeRack, SpillTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Secondary Containment Trays Market Evolving Landscape
Material science advances and regulatory digitization are restructuring how containment systems are specified, procured, and maintained across industrial facilities. Three developments are compressing traditional supply relationships while opening new service-based revenue models.
Modular composite containment is decomposing the installed base of permanent concrete bunds in chemical processing plants. Pharmaceutical manufacturers in Switzerland and Germany are adopting reconfigurable polymer systems that accommodate frequent production line changes. This technology is decomposing the historical preference for fixed infrastructure, enabling facility reconfiguration without demolition costs.
ECHA's expanding PFAS restriction proposals are forcing coating reformulations across steel tray manufacturers. Industrial consequence includes accelerated R&D spending on ceramic and epoxy alternatives that maintain chemical resistance without fluorinated compounds. Steel containment suppliers serving French and Belgian chemical clusters are most affected, with several accelerating polyethylene hybrid development programs to preserve market position.
Specification-grade buyers are consolidating vendor relationships around integrated spill response providers rather than component-only suppliers. Distributors serving US Midwest manufacturing are being displaced by direct manufacturer partnerships that bundle containment with training, inspection, and disposal services. This consolidation is most visible in automotive battery production facilities, where Tesla and Ford suppliers demand single-source accountability for entire spill prevention systems.
Secondary Containment Trays Market Segmentation
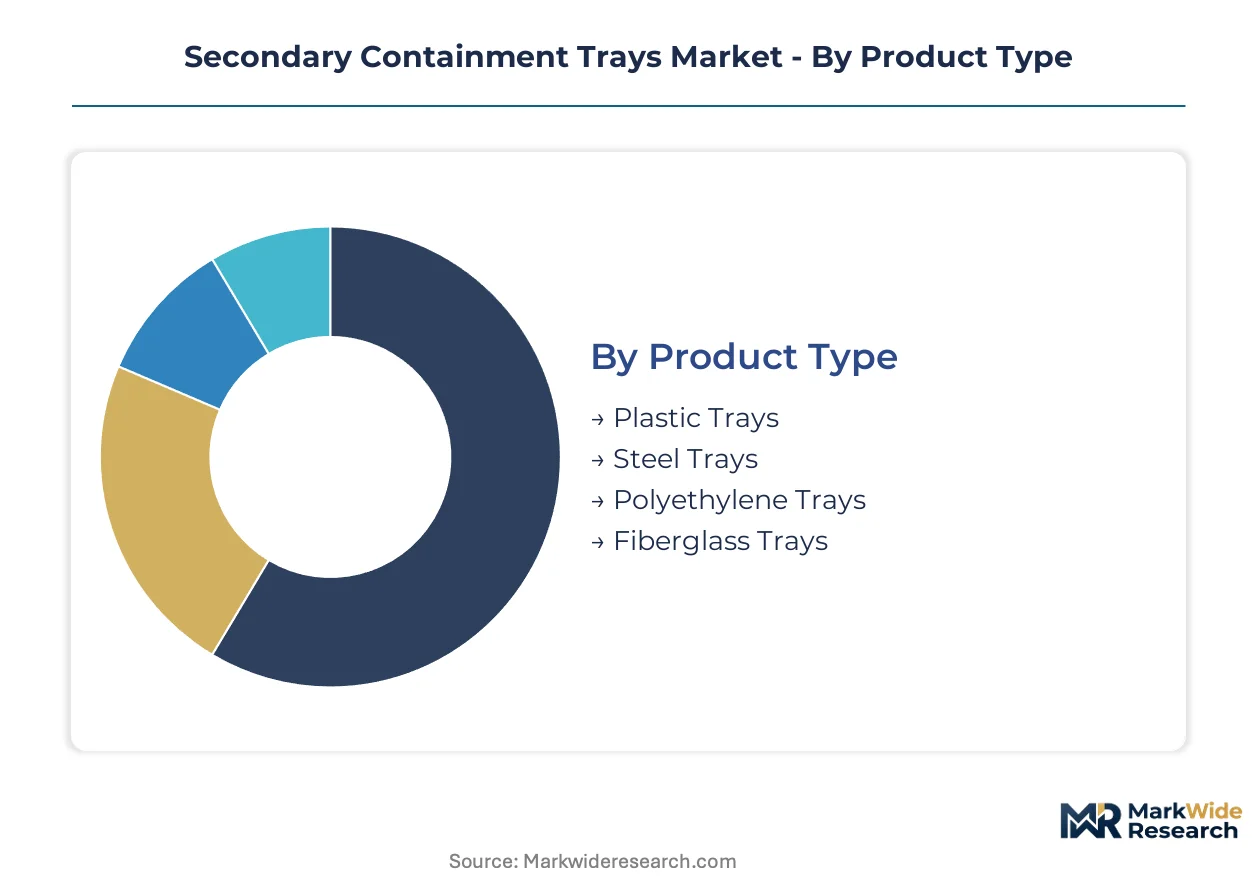
Secondary containment trays serve divergent compliance regimes across chemical handling, pharmaceutical manufacturing, and environmental remediation. Product specifications vary sharply by thermal exposure, chemical aggressiveness, and load-bearing requirements.
Product Type:
EPA SPCC and REACH chemical authorization rules differentiate material selection by corrosion resistance thresholds and thermal operating windows.
- Polyethylene Trays:Fabricated from high-density polyethylene with welded seams for aggressive solvent containment. Demand clusters along the US Gulf Coast petrochemical corridor where refinery expansions require corrosion-immune systems for sulfuric acid and caustic handling.
- Steel Trays:Carbon or stainless steel construction rated for temperatures exceeding polyethylene limits. Retains procurement priority at German chemical clusters processing high-temperature reaction intermediates where thermal stability overrides material cost.
- Plastic Trays:Injection-molded polypropylene or PVC variants for light-duty laboratory and maintenance applications. Common in university research facilities and small-scale chemical blending operations with lower regulatory scrutiny.
- Fiberglass Trays:Reinforced polymer composites combining structural rigidity with moderate chemical resistance. Deployed at wastewater treatment facilities and environmental remediation sites requiring UV stability.
Established volume favors polyethylene trays; emerging adoption favors fiberglass composites in infrastructure applications.
End User:
Customer procurement patterns separate by regulatory enforcement intensity and capital deployment scale.
- Chemical Industry:Bulk chemical manufacturers and specialty chemical producers operating under Seveso III and EPA RMP mandates. German BASF and Bayer facilities drive specification-grade bund system retrofits with mandatory third-party certification.
- Oil & Gas:Upstream drilling operations and downstream refineries requiring spill containment for hydrocarbon transfer. Texas and Louisiana petrochemical investments generate concentrated demand for high-volume modular systems.
- Pharmaceutical Sector:Biologics and active pharmaceutical ingredient manufacturers with FDA and EMA validation requirements. Swiss and Massachusetts drug production centers specify precision-dimensioned trays for automated fill-finish lines.
- Environmental Agencies:Federal and state remediation contractors managing superfund sites and emergency spill response. Procurement emphasizes rapid deployment and compatibility with diverse contaminant profiles.
Chemical industry procurement dominates current revenue; pharmaceutical sector specifications are climbing the fastest.
Application:
Use-case severity determines structural reinforcement, drainage integration, and sensor compatibility.
- Spill Prevention:Primary containment backup for drum storage and tanker unloading. EPA SPCC compliance deadlines accelerate replacement of aging concrete bunds with engineered polymer systems at US manufacturing facilities.
- Chemical Handling:Transfer stations and process equipment drip collection. Dutch and Belgian chemical clusters under REACH authorization mandates retrofit existing infrastructure with certified polyethylene containment.
- Hazardous Waste Storage:Accumulation points for RCRA-regulated waste streams prior to disposal. Requires secondary containment with 110% volume capacity and leak detection integration.
- Lab Safety:Benchtop and fume hood containment for research-scale chemical work. Specifications prioritize chemical compatibility matrices over structural load ratings.
Spill prevention commands the largest installed base; lab safety applications are gaining share fastest in academic and contract research markets.
Size:
Dimensional standardization versus customization reflects automation integration and facility constraints.
- Custom:Engineered dimensions for automated material handling systems and cleanroom integration. Swiss pharmaceutical manufacturers specify millimeter-precision trays for robotic dispensing lines.
- Large:Bulk storage applications for IBC totes and multiple drum arrays. Standard footprints accommodate forklift access and seismic anchoring at Texas chemical terminals.
- Medium:Single-drum and small tote configurations for maintenance shops and satellite storage. Dominates distributor inventory for general industrial procurement.
- Small:Benchtop and portable containment for laboratory and field sampling. Lightweight construction enables manual handling without material handling equipment.
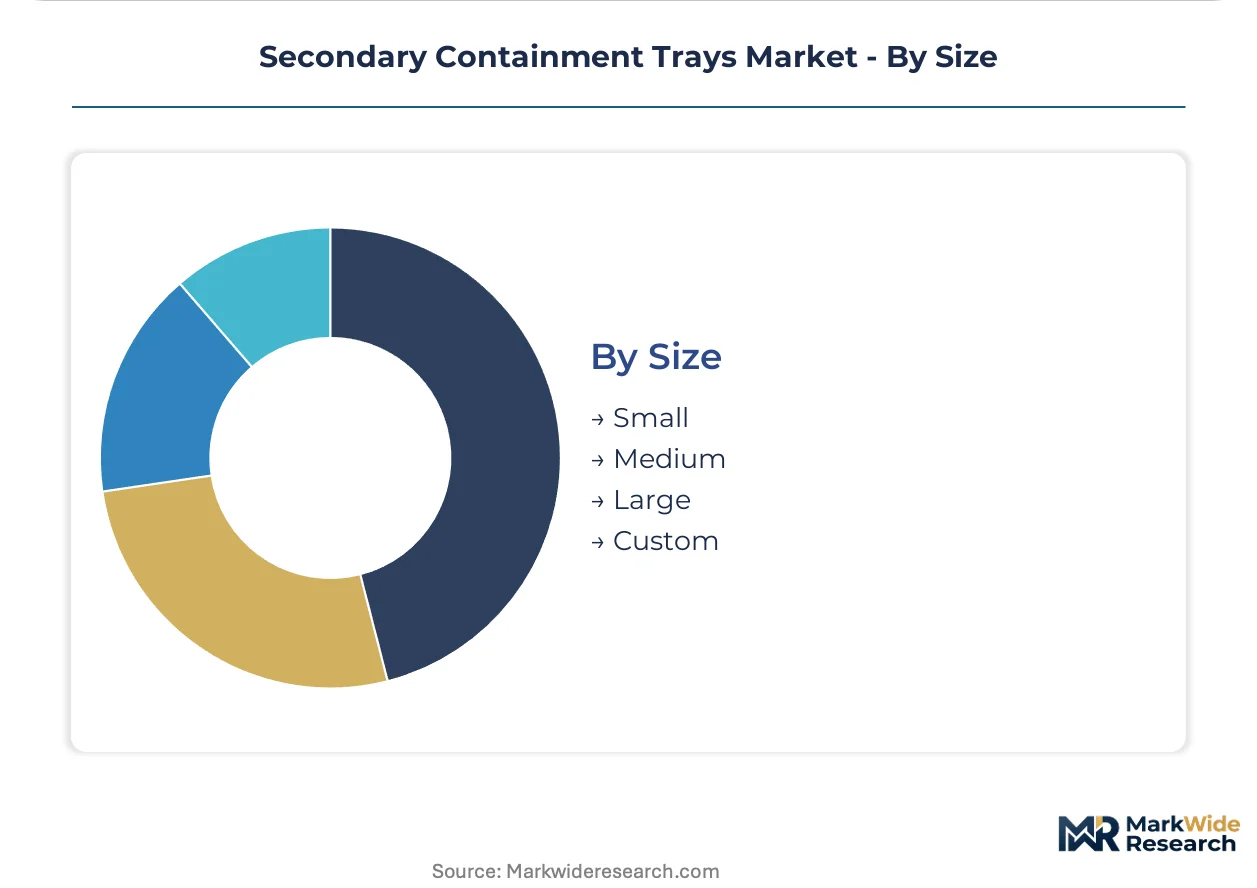
Medium sizes anchor volume shipments; custom specifications are expanding most quickly in pharmaceutical automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States Gulf Coast exhibit low price elasticity given EPA enforcement timelines, while Indian procurement remains highly sensitive to landed cost differentials. German chemical clusters prioritize certification grade over unit economics. Chinese buyers balance domestic supply availability against import lead times.
United States
Petrochemical capacity additions along the Texas and Louisiana Gulf Coast drive specification-grade polyethylene tray procurement. EPA SPCC enforcement compresses replacement cycles for aging concrete bunds at Houston-area refineries. Corpus Christi and Beaumont terminals anchor concentrated demand for high-volume modular systems.
Germany
BASF and Bayer facilities in Ludwigshafen and Leverkusen mandate third-party certified bund retrofits under Seveso III directives. REACH chemical authorization requirements force corrosion-resistant containment upgrades across North Rhine-Westphalia industrial zones. German chemical clusters retain steel tray preference for high-temperature reaction intermediates.
China
State-led petrochemical investments in Zhejiang and Jiangsu provinces expand domestic containment fabrication capacity. GB standards for hazardous material handling tighten compliance specifications at Ningbo and Shanghai chemical terminals. Local polymer supply reduces import dependency for tray manufacturers.
India
PLI scheme incentives for chemical manufacturing attract containment suppliers establishing fabrication partnerships in Gujarat and Maharashtra. Reliance Industries' Jamnagar refinery complex generates demand for high-capacity polyethylene systems. Domestic resin cost volatility constrains margin expansion for local fabricators.
Switzerland
Swissmedic validation requirements and precision manufacturing standards drive custom-dimensioned tray specifications at Basel pharmaceutical clusters. Novartis and Roche automated fill-finish lines demand millimeter-precision containment integration. Swiss biologics facilities pay premiums for FDA-compliant polyethylene welding certification.
Secondary Containment Trays Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. European specialists dominate certification-grade specifications while North American fabricators optimize throughput and distribution reach. Three archetypes populate the market: integrated polymer compounders with captive resin supply, precision fabricators serving pharmaceutical validation requirements, and volume distributors leveraging dealer network density. M&A activity concentrates among distributors acquiring regional fabrication capacity, while technology licensing agreements spread specialized polyethylene formulations across second-tier players.
Among established manufacturers, DENIOS anchors the European certification-tier with its German manufacturing footprint, Eagle Manufacturing exemplifies the North American distribution-optimized archetype through extensive OSHA-focused dealer networks, and UltraTech International occupies the specialized formulation segment with engineered polymer systems for aggressive solvent exposure. These three represent distinct competitive vectors rather than direct substitutes, with procurement patterns segmenting by end-use regulatory intensity and thermal-chemical operating windows.
| Leading Market Players |
|---|
| DENIOS |
| Eagle Manufacturing |
| UltraTech International |
| Justrite Manufacturing |
| New Pig Corporation |
| ENPAC |
| Brady Corporation |
| SafeRack |
| SpillTech |
| Others |
Value Network & Pricing Analysis
Steel-to-polyethylene material substitution across US Gulf Coast petrochemical facilities simultaneously shifts procurement geography toward domestic HDPE compounders and compresses installed-cost premiums that historically favored European steel fabricators.
Pricing Analysis
Service and inspection contract bundling drives lifetime value for specification-grade containment buyers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from OSHA-compliant industrial grades. Cost compression in standard polyethylene tiers is intensifying because Gulf Coast resin volatility transmits directly to fabricator margins. Environmental remediation contractors exhibit highest price sensitivity; Swiss pharmaceutical manufacturers show lowest elasticity given validation requirements.
Supply Chain Analysis
The United States and Germany anchor high-density polyethylene resin production and precision fabrication capacity respectively. Tray manufacturing draws from HDPE pellet feedstocks, welded-seam certification labor, and corrosion-resistant coating inputs. Single-source vulnerability concentrates in qualified polymer welding technicians for pharmaceutical-grade production. Distribution runs through industrial safety distributors and direct manufacturer partnerships serving large chemical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where EPA and REACH entrenchment creates switching costs that protect incumbent certification investments from price-based displacement.
For Market Incumbents: Compound defensive positioning by deepening captive resin supply relationships with Gulf Coast polymer producers and accelerating ceramic coating R&D to offset pending PFAS restrictions. Steel tray manufacturers face polyethylene substitution threats that demand hybrid product development to preserve thermal-application market share. For New Entrants and Emerging Players: Lead with modular IoT-integrated containment systems targeting Indian chemical corridor investments under PLI incentives where established certification relationships remain underdeveloped. Pharmaceutical cleanroom automation specifications offer the most penetrable white-space given scarce FDA-compliant welding capacity. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision fabricators with pharmaceutical validation capabilities over volume distributors. Long-term viability centers on recurring service revenue models displacing transactional product sales. Watch ECHA PFAS restriction finalization timing as inflection indicator for accelerated steel-to-polyethylene replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HDPE Resin | Captive polymer supply insulates DENIOS and Eagle Manufacturing from Gulf Coast feedstock volatility. |
| Pharmaceutical Welding Certification Investment | FDA-compliant fabrication capacity unlocks Swiss and Massachusetts biologics facility procurement. |
| IoT Sensor Platform Integration | Predictive maintenance contracts shift UltraTech International revenue toward recurring service arrangements. |
| Indian Fabrication Partnership | Local production presence captures Reliance Industries Jamnagar refinery demand under PLI scheme incentives. |
| PFAS-Free Coating Development | Ceramic and epoxy alternatives preserve steel tray market position against ECHA restriction enforcement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers, EHS compliance officers, industrial procurement managers, and polymer fabrication technicians. Secondary validation incorporated EPA enforcement databases, REACH authorization filings, customs trade records for HDPE resin movements, and ACC chemical industry expenditure surveys. Bottom-up volume estimates from facility-level containment retrofits were triangulated against top-down chemical production capacity projections.
Across the analysis window, forecasts model polyethylene versus steel material splits, pharmaceutical cleanroom automation penetration, and regional regulatory compliance deadlines. Segmentation dimensions include product type, end-user industry vertical, application severity tier, and dimensional standardization level. CAGRs derive from facility investment cycle timing, mandated replacement deadlines, and capacity expansion project pipelines. Industry-specific inputs encompass Seveso III retrofit mandates and FDA validation queue backlogs.
Forecasts assume regulatory continuity in EPA SPCC enforcement and REACH authorization regimes; material policy shifts would require re-modeling compliance-driven replacement demand. Specific risks include accelerated PFAS restriction timelines, HDPE resin supply disruptions, and pharmaceutical capital expenditure freezes. Recalibration cycles align with material shifts in regulatory enforcement intensity and petrochemical investment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
North America Protective Packaging Market
Protective Packaging
Padded Mailers Market
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Protective Packaging Market
Protective Packaging
Static Shielding Bags Market
Protective Packaging
Insulated Shipping Boxes Market
Protective Packaging
Tamper Proof Packaging Market
Protective Packaging
Insulated Shippers Market
Protective Packaging
Latin America Protective Packaging Market
Protective Packaging
Foam Packaging Inserts Market
Protective Packaging
Molded Fiber Pulp Edge Protectors Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Foam Edge Protectors Market
Protective Packaging
Insulated Styrofoam Shipping Boxes Market
Protective Packaging
High Pressure Protective Packaging Film Market
Protective Packaging
North America Insulated Packaging Market