
 Anti-Corrosive Packaging Market | 2026-2036
Anti-Corrosive Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Corrosive Packaging Market Analysis
German specialty film producers is decoupling from commodity polyethylene supply chains by investing in captive VCI masterbatch compounding. Cortec Corporation leverages its Minnesota-based R&D campus to sustain formulation leadership across military and civilian specifications. Daubert Cromwell anchors North American distribution through direct technical service teams embedded in Detroit automotive corridors. Branopac GmbH dominates European export documentation compliance, a capability that competitors struggle to replicate without localized regulatory staff.
Anti-corrosive packaging encompasses engineered barrier systems that incorporate volatile corrosion inhibitors, desiccants, or metallic coatings to prevent electrochemical degradation of ferrous and non-ferrous surfaces during transit and storage. These systems typically function through vapor-phase inhibition at concentrations below one part per million in sealed microclimates, with polyethylene and polypropylene substrates dominating flexible formats due to their moisture vapor transmission rates below 0.5 grams per square meter per day. Vapor Corrosion Inhibitors command the largest product-type position because automotive manufacturers specify them for just-in-time powertrain component deliveries. Coated Films represent the fastest-expanding category as oil and gas sector procurement shifts toward lighter-weight alternatives to traditional laminated aluminum structures. The Electronics Sector application segment concentrates margin pools around cleanroom-compatible formulations that exclude amine-based chemistries prohibited by semiconductor fabs.
EPA hazardous substance labeling requirements and OSHA workplace exposure limits govern VCI chemical handling in United States manufacturing facilities, while REACH registration obligations in Europe restrict certain nitrite-based inhibitor chemistries from cross-border commerce. The EU Green Deal's packaging waste directives are forcing material substitutions away from multi-layer laminates toward mono-material recyclable structures. Japan's METI maintains JIS standards for corrosion protection in precision machinery exports, creating a certification barrier for non-compliant suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory when formulation approvals do not transfer across borders.
Market Dynamics
REACH registration obligations and EPA hazardous substance labeling are forcing petroleum-derived substrate producers toward amine-free VCI chemistries, compressing formulation windows while elevating compliance costs for cross-border suppliers.
Growth Catalysts
- EU Green Deal packaging waste directives:Mono-material recyclable structures are displacing multi-layer laminates, creating upgrade cycles among machinery exporters seeking German certification.
- Automotive just-in-time powertrain logistics:Volatile corrosion inhibitor films are specified for overseas precision component shipments, tightening quality thresholds.
- Semiconductor fabrication cleanroom protocols:Amine-free formulations are mandatory for electronics sector procurement, filtering supplier pools to REACH-compliant compounders.
Market Restraints
- Petroleum-derived polyethylene feedstock volatility:Crude-linked resin costs compress margin predictability for commodity film converters.
- German specialty film supply concentration:Captive VCI masterbatch capabilities concentrate among integrated producers, raising entry barriers for external compounders.
- Nitrite-based inhibitor REACH restrictions:Cross-border commerce friction strands non-compliant inventory at European borders.
Strategic Opportunities
- Japanese precision machinery export certification:METI JIS standards create compliance moats for qualified suppliers in semiconductor-adjacent packaging.
- Oil and gas sector lightweighting mandate:Coated films are displacing laminated aluminum structures in subsea component logistics.
- Detroit automotive corridor technical service embedding:Direct field engineering relationships lock in multi-year VCI specification contracts.
Industry Challenges
- Formulation chemist talent scarcity:Vapor-phase inhibition expertise concentrates among aging specialists, constraining R&D throughput.
- Multi-jurisdiction approval timelines:Divergent EPA, REACH, and METI registration cycles delay product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Corrosive Packaging Market |
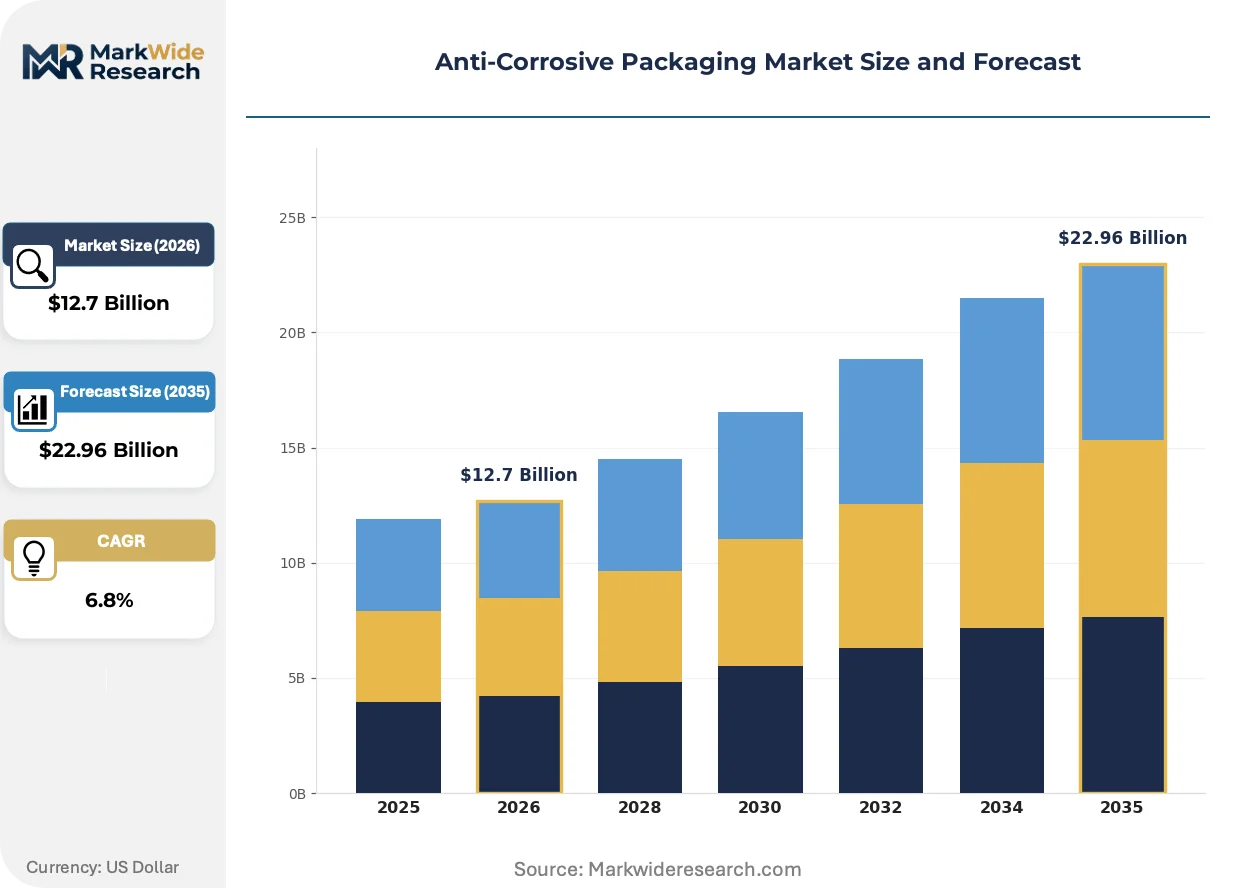
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $22.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vapor Corrosion Inhibitors, Coated Films, Laminated Materials, Rust Inhibiting Foams End User: Automotive Manufacturers, Oil & Gas Sector, Aerospace Industries, Electronics Sector Material: Polyethylene, Polypropylene, Aluminum, Steel Application: Shipping, Storage, Transportation, Export |
| Companies Covered | EXCOR, Zerust, Cortec Corporation, Branopac GmbH, Denso Corporation, Daubert Cromwell, Rust-X, VCI Packaging Pvt Ltd, Armor Protective Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Corrosive Packaging Market Emerging Trajectories
Active regulatory divergence between EPA, REACH, and METI regimes is fragmenting formulation standards while automation investments compress quality assurance cycles across precision manufacturing supply chains.
Smart VCI release monitoring systems are automating corrosion protection validation in sealed microclimates. Automotive tier-one suppliers are embedding these sensors in powertrain component packaging for real-time transit verification. This sensor integration is automating quality documentation, reducing manual inspection labor and compressing dispute resolution cycles between shippers and receivers.
REACH SVHC candidate list expansions are accelerating amine-free chemistry transitions across European electronics supply chains. Formulators are redesigning masterbatches around benzotriazole alternatives to maintain vapor-phase inhibition below one part per million. Semiconductor fabs in Germany and the Netherlands are rejecting legacy formulations, forcing packaging suppliers to maintain dual product lines for EU and non-EU destinations.
Buyer consolidation among automotive OEMs is compressing supplier qualification cycles and elevating technical service expectations. Tier-one powertrain manufacturers are unbundling packaging specification authority from logistics procurement, creating direct relationships with VCI compounders. This channel restructuring concentrates margin pools with formulation specialists capable of embedded engineering support in Detroit, Stuttgart, and Nagoya manufacturing corridors.
Anti-Corrosive Packaging Market Segmentation
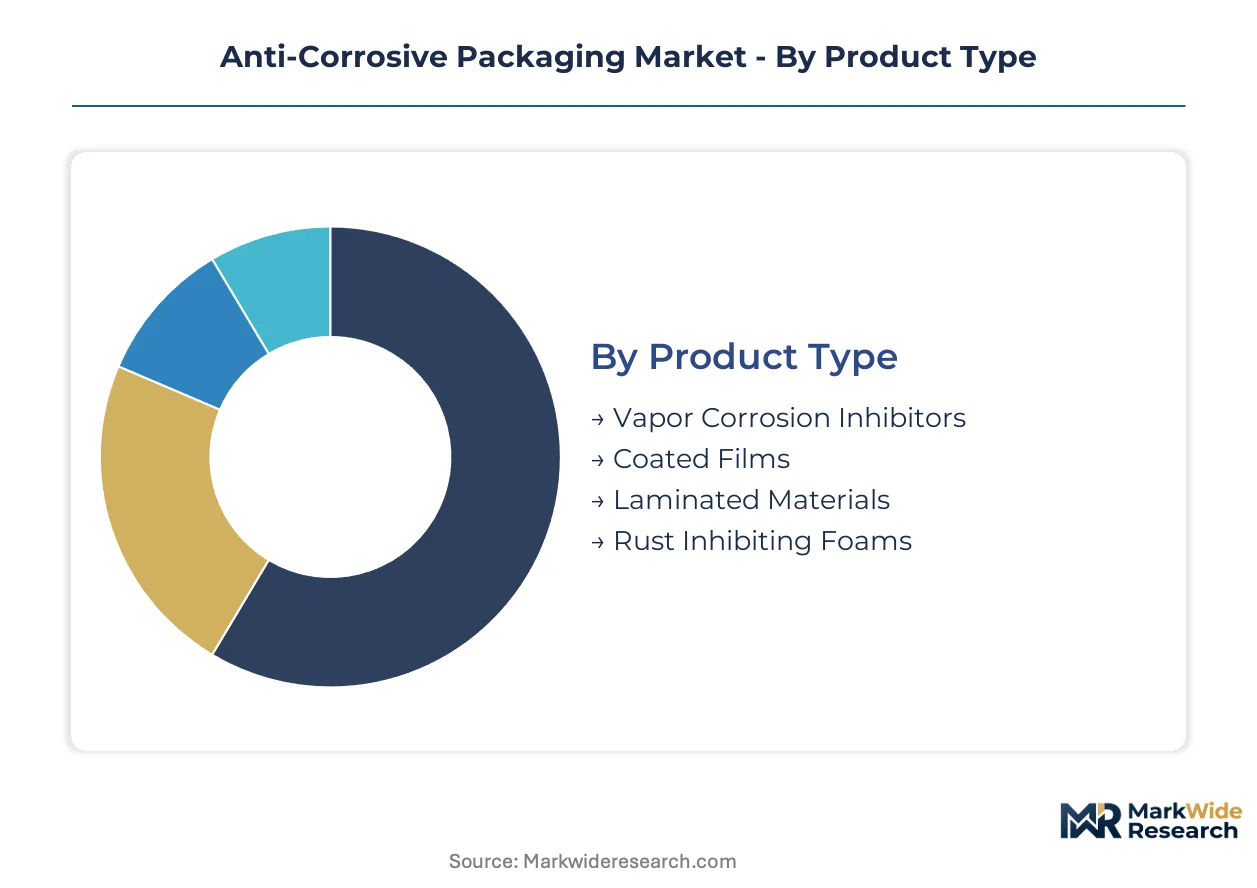
Anti-corrosive packaging segmentation reflects divergent technical specifications across precision manufacturing supply chains. Material choices and inhibitor chemistries carry distinct regulatory burdens that reshape supplier qualification criteria.
Product Type:
Buyers prioritize vapor-phase inhibition efficacy and substrate compatibility when selecting packaging formats for sensitive components.
- Vapor Corrosion Inhibitors:These formulations release protective molecules at sub-ppm concentrations into sealed microclimates. Automotive powertrain logistics in Germany and the United States specify VCI films for just-in-time overseas deliveries, with REACH-compliant amine-free chemistries commanding specification premiums.
- Coated Films:Single-layer structures with direct-applied corrosion inhibitors offer weight advantages over laminated alternatives. Oil and gas sector procurement in Norway and the Gulf of Mexico is shifting toward these lighter formats for subsea component logistics, displacing traditional aluminum-barrier constructions.
- Laminated Materials:Multi-layer polyethylene-aluminum composites deliver sub-0.5 g/m²/day moisture vapor transmission rates for extended storage applications.
- Rust Inhibiting Foams:Polyurethane-based cushioning systems integrate vapor-phase chemistries for irregularly shaped machinery components during export.
Vapor Corrosion Inhibitors lead on scale; Coated Films lead on momentum.
End User:
End-use concentration varies by corrosion risk tolerance and cleanroom compatibility requirements.
- Automotive Manufacturers:Powertrain component logistics demand vapor-phase protection for ferrous and non-ferrous surfaces during transoceanic shipment. Detroit and Stuttgart automotive corridors specify embedded technical service capabilities from VCI compounders.
- Electronics Sector:Semiconductor fabrication facilities in the Netherlands and Germany enforce amine-free formulation mandates. Cleanroom-compatible packaging excludes nitrite-based inhibitors, filtering supplier pools to REACH-registered compounders with benzotriazole alternatives.
- Oil & Gas Sector:Offshore equipment logistics require salt-spray resistance for extended exposure periods.
- Aerospace Industries:Precision turbine components specify low-outgassing packaging for high-altitude storage conditions.
Automotive Manufacturers anchor volume demand; Electronics Sector concentrates margin pools.
Material:
Substrate selection balances moisture barrier performance against recyclability mandates and feedstock cost volatility.
- Polyethylene:Low-density and linear-low-density grades dominate flexible VCI film production due to extrusion compatibility and sub-0.5 g/m²/day moisture vapor transmission rates. German specialty film producers are investing in captive masterbatch compounding to decouple from commodity resin supply chains.
- Polypropylene:Higher temperature resistance suits automotive underhood component packaging. Japanese precision machinery exporters specify PP-based formats for METI JIS-compliant certification.
- Aluminum:Foil laminates provide maximum moisture barriers for multi-year storage applications.
- Steel:Rigid containers and wraps serve heavy machinery with abrasion-resistant surface protection.
Polyethylene commands installed base; Polypropylene climbs fastest on specification upgrades.
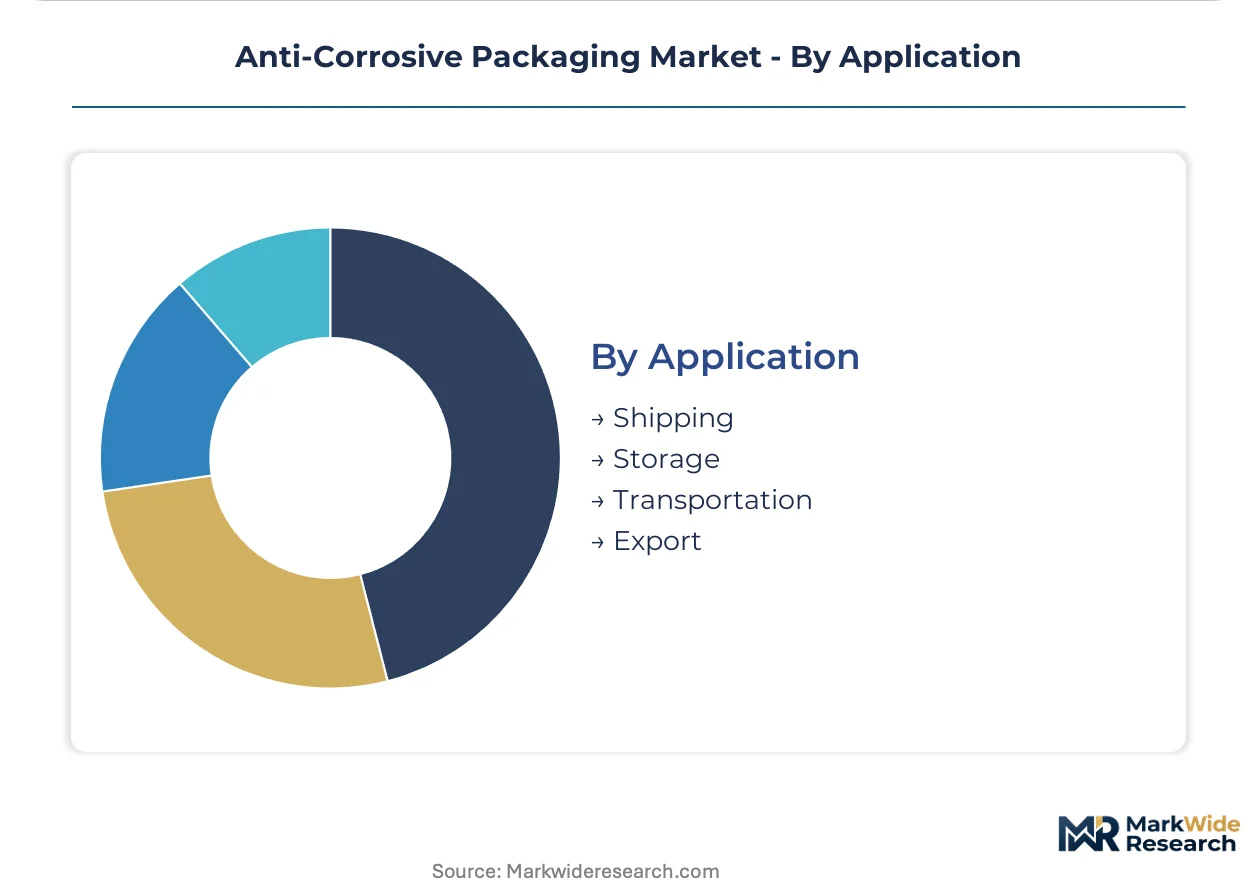
Application:
Application context determines packaging format complexity and documentation requirements.
- Shipping:Transoceanic container logistics drive VCI film specification for automotive and machinery exports. EPA hazardous substance labeling and OSHA exposure limits govern chemical handling in United States manufacturing facilities, while REACH registration restricts certain formulations from European commerce.
- Storage:Long-duration warehousing demands desiccant-integrated systems for humidity control in uncontrolled environments.
- Transportation:Multi-modal freight requires puncture-resistant formats for rail and truck vibration exposure.
- Export:Cross-border documentation compliance concentrates demand with suppliers maintaining localized regulatory staff in Germany and Japan.
Shipping captures volume concentration; Export concentrates compliance-driven premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as REACH compliance costs in Europe push some masterbatch compounding toward jurisdictions with streamlined chemical registration regimes. Suppliers are optimizing location decisions against the cost-of-compliance gap between EPA, ECHA, and METI frameworks.
United States
Automotive powertrain logistics in Detroit and the Southeast anchor VCI film consumption for transoceanic component shipments. EPA hazardous substance labeling and OSHA workplace exposure limits govern chemical handling in manufacturing facilities. Cortec Corporation leverages its Minnesota R&D campus to sustain formulation leadership across military and civilian specifications.
Germany
Industrial machinery exports from Stuttgart and the Ruhr region demand premium moisture-barrier specifications for precision components. EU Green Deal packaging waste directives force material substitutions away from multi-layer laminates toward mono-material recyclable structures. Branopac GmbH dominates export documentation compliance through localized regulatory staff embedded in Frankfurt logistics corridors.
Japan
Precision machinery exporters in Nagoya and Osaka specify polypropylene-based formats for METI JIS-compliant corrosion protection certification. Semiconductor fabrication facilities enforce amine-free formulation mandates that filter supplier pools. Cleanroom-compatible packaging requirements in Kyushu electronics clusters reject legacy nitrite-based inhibitors entirely.
China
Automotive component manufacturing in Shanghai and the Yangtze River Delta drives VCI film specification for domestic and export logistics. GB standards and MIIT regulations govern chemical handling in industrial packaging production. Local film converters are investing in captive masterbatch capabilities to reduce dependence on imported compound formulations.
India
Machinery and automotive component exports from Maharashtra and Gujarat generate demand for corrosion protection in humid port conditions. BIS certification requirements and DGFT export documentation rules shape supplier qualification criteria. VCI Packaging Pvt Ltd anchors domestic formulation capabilities against imported European and North American alternatives.
Anti-Corrosive Packaging Market Vendor Landscape
German specialty film producers anchor one tier through captive VCI masterbatch compounding; North American specialists hold another via embedded technical service teams in automotive manufacturing corridors. The vendor base stratifies across integrated compounders with backward resin control, formulation specialists licensing inhibitor chemistries, and regional converters dependent on external masterbatch supply. Three archetypes dominate: integrated producers with in-house compounding, formulation licensors with R&D depth, and distribution-heavy players with logistics relationships. Capacity expansion in captive masterbatch facilities and geographic extension of technical service teams represent the dominant competitive moves.
Within the integrated producer tier, Cortec Corporation and Branopac GmbH exemplify contrasting geographic anchoring strategies. Cortec occupies a position sustained by Minnesota-based R&D infrastructure serving military and civilian specification markets. Branopac sits within the European regulatory compliance tier, leveraging localized staff for export documentation advantages that external compounders struggle to replicate. Daubert Cromwell represents the technical service-embedded archetype, with positioning in North American automotive corridors built on direct field engineering relationships rather than manufacturing scale alone.
| Leading Market Players |
|---|
| EXCOR |
| Zerust |
| Cortec Corporation |
| Branopac GmbH |
| Denso Corporation |
| Daubert Cromwell |
| Rust-X |
| VCI Packaging Pvt Ltd |
| Armor Protective Packaging |
| Others |
Supply Flow & Price Mechanics
EU Green Deal packaging waste directives gate qualified supply for premium-tier pricing access, as mono-material recyclable structures displace multi-layer laminates and REACH-registered compounders capture specification premiums from machinery exporters seeking German certification.
Pricing Analysis
Distributor margins in automotive corridors absorb field engineering costs, compressing net returns for VCI film converters without embedded technical service teams. Pricing stratifies across premium, standard, and economy tiers based on REACH compliance status and moisture vapor transmission performance, with amine-free formulations commanding tier-one positioning. Cost compression in commodity polyethylene feedstock tiers is intensifying because crude-linked resin volatility erodes margin predictability. Tier-one automotive OEMs exhibit lowest price sensitivity due to just-in-time specification requirements, while regional machinery exporters in India and Southeast Asia drive volume at standard-tier economics.
Supply Chain Analysis
Domestic-content mandates in China's MIIT regulations and India's PLI scheme are reshaping sourcing patterns for VCI masterbatch production, pushing local film converters toward captive compounding capabilities. Geographic supply concentration centers on Germany, the United States, and Japan, where integrated producers control backward integration into specialty resin and inhibitor chemistry. Raw material dependencies draw from petroleum-derived polyethylene feedstocks, benzotriazole corrosion inhibitors, and desiccant substrates. Single-source vulnerability concentrates in German specialty film producers with captive VCI masterbatch capabilities. Distribution runs through direct technical service teams embedded in Detroit, Stuttgart, and Nagoya automotive corridors, supplemented by regional distribution partnerships for export documentation compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with REACH SVHC candidate list expansions driving demand for amine-free formulation transitions across European electronics supply chains.
For Market Incumbents: To counter nitrite-based inhibitor REACH restrictions, Cortec Corporation and Branopac GmbH should deepen backward integration into captive VCI masterbatch compounding in Minnesota and Frankfurt corridors respectively. Certification investment in METI JIS standards for Japanese precision machinery exports creates compliance moats that external compounders cannot replicate without localized regulatory staff.
For New Entrants and Emerging Players: Technical service partnerships with automotive tier-one suppliers in Detroit and Stuttgart represent the most penetrable entry vector, as powertrain manufacturers unbundle packaging specification authority from logistics procurement. Cleanroom-compatible amine-free formulations for semiconductor fabs in the Netherlands and Germany offer white-space positioning, with direct field engineering relationships enabling multi-year contract capture against distribution-heavy incumbents.
For Investors and Strategic Acquirers: Roll-up economics work for formulation specialists with REACH-registered chemistry libraries because regulatory approval timelines create 18-24 month barriers that fragment competitor response. Platform consolidation targets should emphasize integrated producers with backward resin control and embedded technical service capabilities. The signal to watch is buyer consolidation among automotive OEMs compressing supplier qualification cycles, as this concentrates margin pools with compounders capable of direct OEM relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive VCI Masterbatch Compounding | German specialty film producers decouple from commodity polyethylene supply chains through in-house production. |
| Amine-Free Formulation Transition | REACH SVHC expansions force benzotriazole chemistry redesigns for semiconductor cleanroom compatibility. |
| Technical Service Team Embedding | Direct field engineering in Detroit automotive corridors locks in multi-year powertrain specification contracts. |
| METI JIS Certification Investment | Japanese precision machinery export compliance creates regulatory moats for qualified packaging suppliers. |
| Smart VCI Sensor Integration | Automotive tier-one suppliers automate corrosion protection validation for real-time transit verification. |
Methodological Framework
Coverage spans the United States, Germany, Japan, China, and India, with primary inputs from each market combining interviews with VCI formulation chemists, automotive procurement directors at Tier 1 suppliers, semiconductor fab packaging engineers, and export logistics coordinators. Secondary validation draws from EPA hazardous substance filings, ECHA REACH registration databases, METI JIS standard documentation, and customs trade data for VCI film shipments. Bottom-up demand modeling triangulates against top-down macroeconomic indicators across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, end-use industry, material substrate, and application context dimensions. Segmentation modeling captures VCI films, coated films, laminated materials, and rust-inhibiting foams against automotive, electronics, oil and gas, and aerospace demand verticals. CAGRs derive from regression analysis of historical shipment data and forward projection of regulatory-driven substitution patterns, with specific inputs including REACH compliance cost trajectories and automotive just-in-time logistics expansion rates.
Revisions become necessary when regulatory divergence between EPA, ECHA, and METI frameworks accelerates formulation approval fragmentation, or when petroleum feedstock volatility disrupts polyethylene resin cost structures beyond historical bands. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Insulated Packaging Market
Protective Packaging
Protective Packaging Market
Protective Packaging
Asia-Pacific Protective Packaging Market
Protective Packaging
Insulated Shippers Market
Protective Packaging
Global Packaging Inserts and Cushions Market
Protective Packaging
Inflatable Packaging Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
Middle East and Africa Protective Packaging Market
Protective Packaging
Insulated Shipping Boxes Market
Protective Packaging
Latin America Protective Packaging Market
Protective Packaging
Grease Resistant Packaging Market
Protective Packaging
Corrugated Bubble Wrap Market
Protective Packaging
Tamper Proof Packaging Market
Protective Packaging
Foam Edge Protectors Market
Protective Packaging
Paper Cushion Systems Market
Protective Packaging
High Pressure Protective Packaging Film Market