
 Padded Dividers Market | 2026-2036
Padded Dividers Market Size, Share, and Industry Trends Forecast 2026-2036
Padded Dividers Market Analytics
REACH is rebalancing the cost-of-entry calculus for foam-based padded divider suppliers entering European distribution channels. Pelican Products leverages its captive supply of cross-linked polyethylene formulations to sustain margin stability amid substance restriction updates. SKB Cases anchors its competitive position through in-house production of injection-molded shell-and-divider systems for military and broadcast end users.
Padded dividers are configurable interior inserts, typically fabricated from open-cell or closed-cell foam matrices laminated with woven or non-woven facing materials, engineered to immobilize objects within rigid or semi-rigid containers during transit or storage. The assembly process involves die-cutting, water-jet profiling, or CNC routing to achieve precise cavity geometries matched to product footprints. Foam and synthetic product types dominate current volume, with synthetic gaining share as polyester and nylon facing materials replace leather in cost-sensitive e-commerce and transportation applications. The protection application commands the widest specification spread, while the display segment carries the highest margin pool due to color-matching and branding requirements.
EPA guidelines on volatile organic compound emissions shape domestic foam manufacturing standards, while OSHA workplace exposure limits affect cutting and lamination operations in US-based plants. The EU Green Deal and F-Gas Regulation indirectly pressure suppliers to reformulate blowing agents and reduce embodied carbon in divider substrates. Stakeholders must monitor evolving substance restriction lists and decide whether to regionalize material sourcing or pursue unified global formulations.
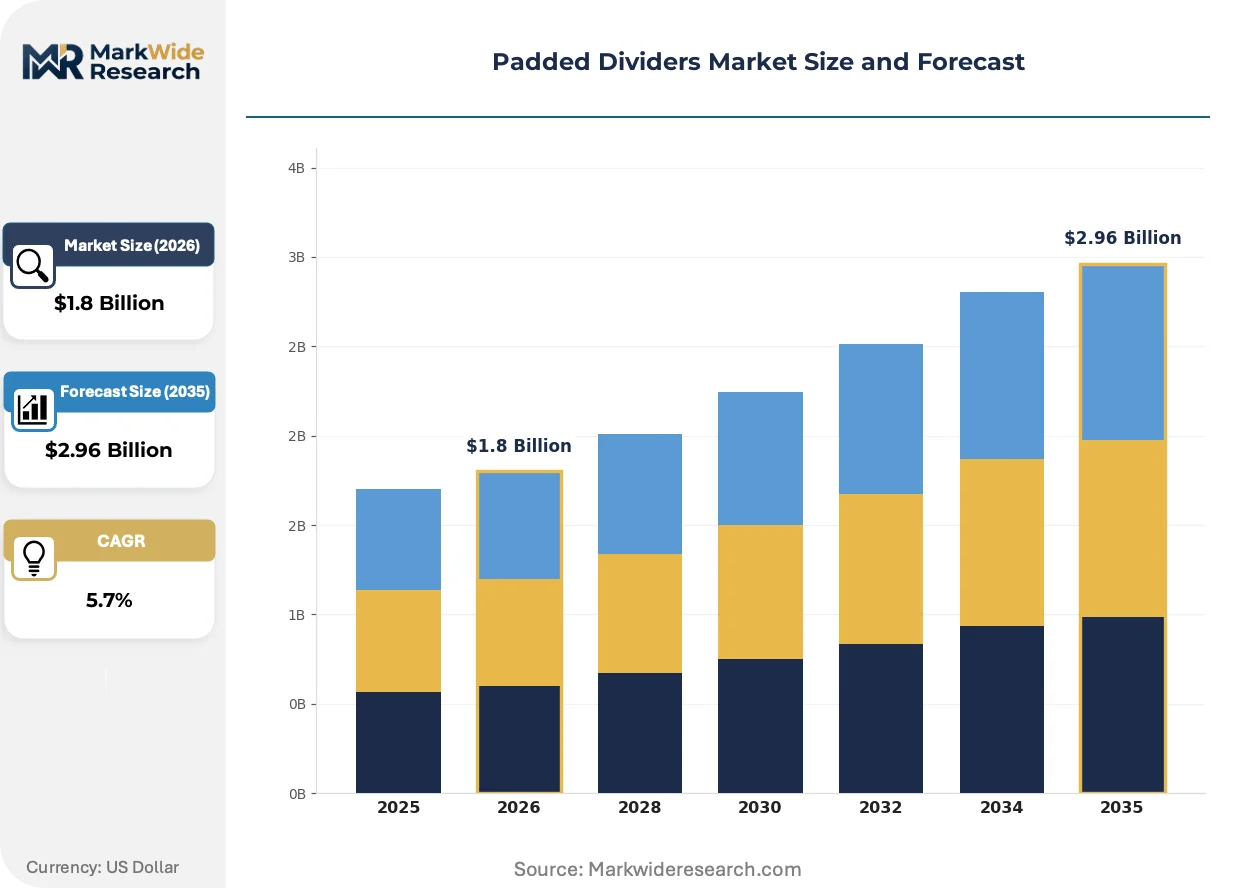
Market Dynamics
E-commerce fulfillment centers are compressing lead times for protective packaging specifications, forcing foam converters to retool die-cutting lines for lot sizes below 500 units while maintaining dimensional tolerances within 0.5 millimeters.
Growth Catalysts
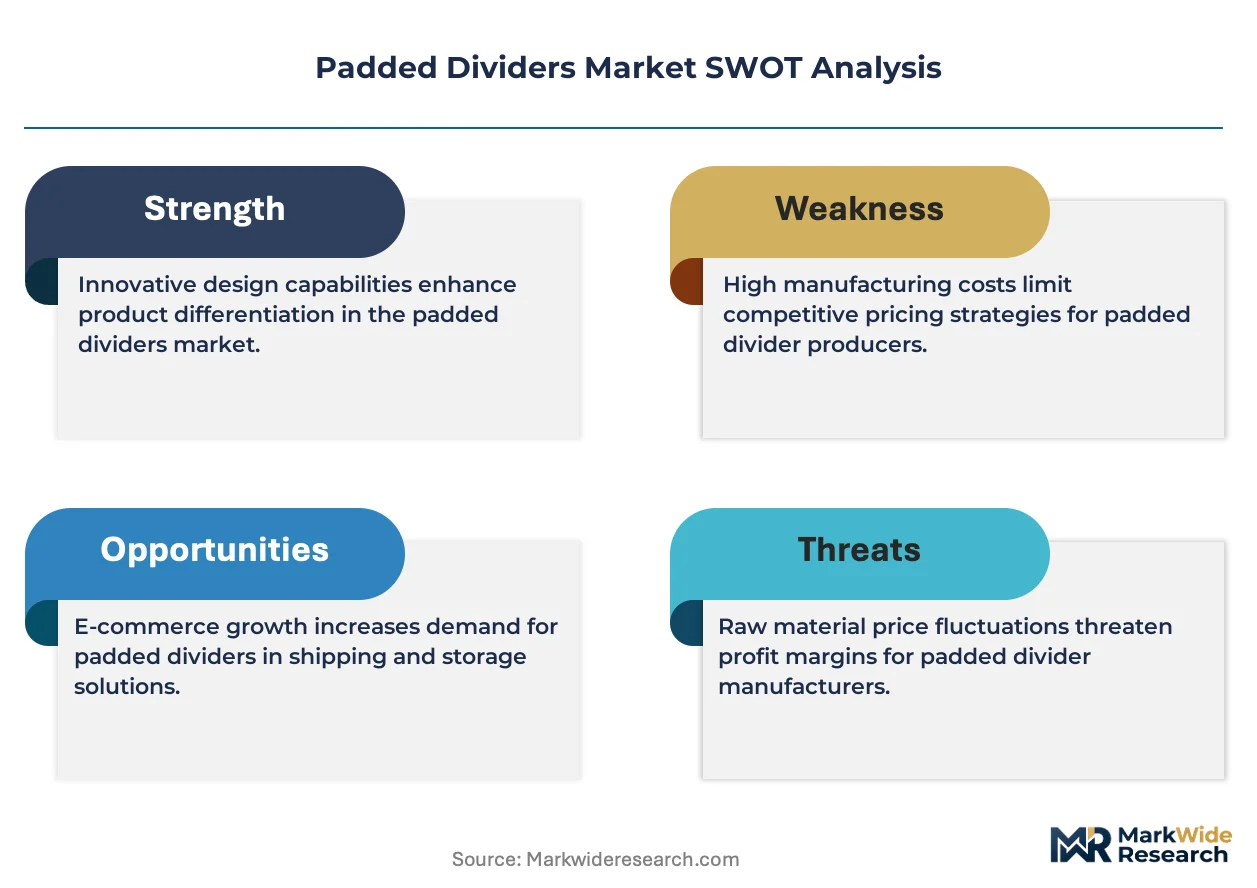
- REACH substance restrictions:ECHA's rolling updates on restricted foam blowing agents are accelerating migration toward water-blown polyurethane formulations in European distribution channels.
- Broadcast equipment logistics:Camera rig and lighting kit protection requirements from rental houses are sustaining demand for high-loft polyethylene divider systems with color-coded facing materials.
- Germany's industrial packaging corridor:Concentrated automotive parts distribution around Stuttgart and Wolfsburg generates recurring specification volume for anti-static foam divider assemblies.
Market Restraints
- Petrochemical feedstock volatility:TDI and MDI pricing swings compress margin stability for independent foam fabricators without captive resin supply.
- Chinese blown-molded shell competition:Low-cost polypropylene case imports from Zhejiang and Guangdong provinces displace domestic assembly opportunities in standard-duty transportation segments.
- Technical limitation of open-cell foams:Moisture absorption rates above 8% by weight disqualify polyurethane ester formulations from cold-chain pharmaceutical applications.
Strategic Opportunities
- India's electronics manufacturing clusters:Noida and Sri City assembly plants generate untapped demand for ESD-rated divider systems as smartphone and component production scales under PLI scheme incentives.
- Reusable shipper programs:Closed-loop packaging as a service models in Benelux grocery and cosmetics fulfillment create recurring revenue streams for divider refurbishment and reconfiguration.
- EU Green Deal carbon accounting:Embodied carbon disclosure requirements for transport packaging are favoring recycled-content PET felt dividers over virgin polyethylene in brand-owner sustainability scorecards.
Industry Challenges
- CNC programming talent scarcity:Water-jet and router operators with foam-specific kerf compensation skills command wage premiums above general fabrication trades.
- Multi-certification stacking:Military MIL-STD-810G, airline IATA Dangerous Goods, and medical ISO 11607 compliance for a single divider SKU extends validation timelines to 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Padded Dividers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Fabric, Leather, Synthetic End User: Retailers, E-commerce, Transportation, Storage Services Material: Polyester, Cotton, Nylon, Polyethylene Application: Shipping, Organization, Display, Protection |
| Companies Covered | Pelican Products, SKB Cases, B&W International, Nanuk, GWP Group, Topper Cases, Seahorse Protective Cases, Nefab Packaging, Menasha Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Padded Dividers Market Evolving Landscape
Digital fabrication workflows are collapsing the traditional sample-to-production pipeline, enabling same-day quotation from 3D product scans and automated nesting algorithms that optimize material yield.
Water-blown polyurethane foam chemistry is converging with digital cutting workflows to enable mass-customized divider cavities without hard-tooling lead times. Medical device field service teams are adopting these systems for instrument set configurations below 100 units. The technology is converging with cloud-based specification libraries that store cavity geometries for rapid re-ordering across distributed repair networks.
EPA volatile organic compound emission limits for foam manufacturing are tightening permissible styrene and toluene discharge rates from lamination and cutting operations. US-based plants are retrofitting thermal oxidizers and switching to hot-melt adhesive systems to maintain operating permits. Small-batch custom houses in California and Texas face disproportionate compliance costs relative to high-volume competitors with centralized abatement infrastructure.
Buyer concentration among omnichannel retailers is compressing specification cycles from annual to quarterly review periods. Procurement teams at major fulfillment networks now require divider suppliers to maintain finished goods inventory within 150 miles of each distribution node. This pattern is most visible in the automated sortation hubs serving the Northeast and Mid-Atlantic corridors, where slotting fees and velocity penalties for stockouts have become standard contract terms.
Padded Dividers Market Segmentation
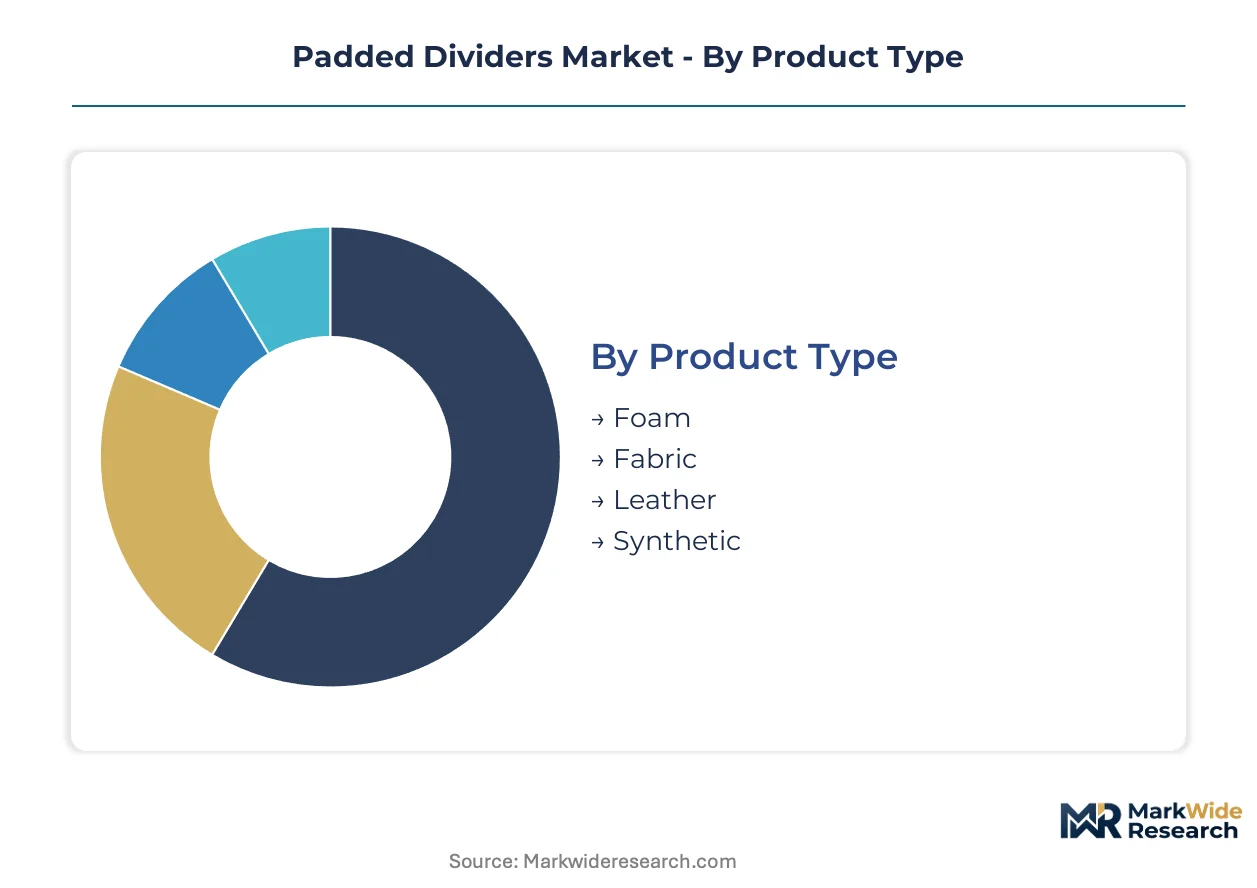
Padded dividers serve divergent performance requirements across protective shipping, precision storage, and branded presentation. Segmentation reveals how material selection and application context reshape procurement priorities and margin structures for foam converters and case manufacturers.
Product Type:
Buyers in this category differentiate primarily by durability requirements and cost sensitivity across use cycles.
- Foam:Open-cell and closed-cell polyurethane or polyethylene matrices provide shock absorption and vibration damping. E-commerce fulfillment centers in Germany's automotive corridor specify anti-static formulations for electronics handling.
- Synthetic:Polyester and nylon facing materials laminated to foam substrates displace leather in cost-sensitive transportation applications. REACH-compliant water-blown polyurethane chemistry is accelerating migration in European distribution channels.
- Leather:Premium hide facings with foam backing serve luxury goods presentation and high-end equipment cases. Boutique manufacturers in Italy and France sustain niche specification volume for artisanal production.
- Fabric:Woven cotton or canvas exteriors over padded cores address reusable shipper programs and lightweight organizational applications. Benelux grocery fulfillment networks favor recycled-content fabric constructions for closed-loop packaging models.
Volume sits with foam; growth tilts toward synthetic as regulatory pressure and cost optimization reshape material selection.
End User:
Procurement scale and specification velocity separate buyers, with fulfillment networks demanding inventory proximity and medical rental houses requiring color-coded customization.
- E-commerce:Omnichannel retailers compress specification cycles to quarterly reviews and mandate finished goods inventory within 150 miles of distribution nodes. Automated sortation hubs in the US Northeast impose slotting fees and velocity penalties for stockouts.
- Transportation:Airline logistics and freight forwarders require multi-certification compliance spanning IATA Dangerous Goods and MIL-STD-810G. Validation timelines extend to 14-18 months for single SKU qualification.
- Retailers:Brick-and-mortar chains specify dividers for in-store inventory organization and seasonal display reconfiguration. Volume concentrates in big-box electronics and home goods categories.
- Storage Services:Document management and fine art warehousing operators prioritize archival-grade materials with low outgassing profiles. Climate-controlled facilities specify moisture barriers for open-cell foam exclusions.
Revenue concentrates with e-commerce; margin expansion favors transportation due to certification barriers and contract duration.
Material:
Supply security and petrochemical feedstock exposure determine sourcing strategies for converters and brand owners.
- Polyethylene:Cross-linked and expanded formulations from Pelican Products and SKB Cases provide chemical resistance and dimensional stability. Captive resin supply insulates margin pressure from TDI and MDI pricing volatility.
- Polyester:Recycled-content PET felt constructions gain favor in EU Green Deal carbon accounting frameworks. Embodied carbon disclosure requirements favor post-consumer fiber over virgin polyethylene in sustainability scorecards.
- Nylon:High-tenacity woven facings deliver abrasion resistance for military and broadcast equipment logistics. Rental houses specify color-coded nylon facing materials for rapid kit identification.
- Cotton:Natural fiber padding addresses biodegradable packaging mandates and organic product handling. Limited moisture resistance restricts deployment to dry-climate storage and presentation applications.
Procurement volume clusters around polyethylene; sustainability-driven substitution is expanding polyester fastest.
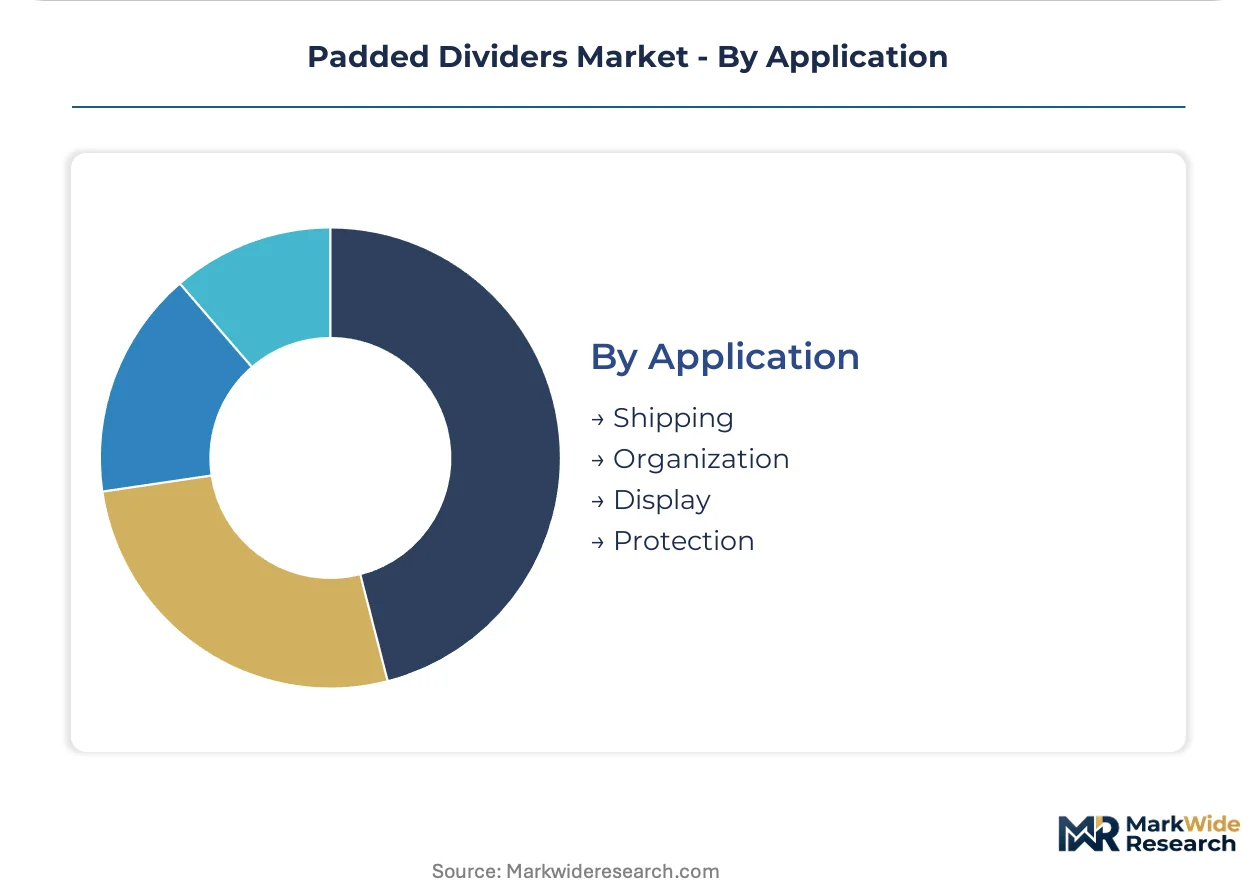
Application:
Performance specification and aesthetic requirement separate use cases, with protection demanding engineering tolerance and display commanding color-matching precision.
- Protection:Shock and vibration isolation for precision instruments, camera rigs, and medical devices requires cavity geometries within 0.5 millimeter tolerances. Digital fabrication workflows enable mass customization below 100-unit lot sizes.
- Display:Branded presentation and retail fixture applications carry the highest margin pool due to color-matching, logo integration, and surface finish requirements. Cosmetics and luxury goods sectors sustain premium specification volume.
- Shipping:Single-use and reusable protective inserts for parcel and freight transit balance material cost against damage rate reduction. E-commerce fulfillment centers drive specification compression toward sub-500-unit lot sizes.
- Organization:Drawer inserts, tool chest dividers, and workshop storage systems prioritize configurability and reconfigurability. Consumer and light industrial markets sustain steady replacement demand.
Protection commands the widest specification spread; display captures the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's electronics manufacturing clusters in Noida and Sri City operate under PLI scheme incentives, concentrating specification demand for ESD-rated divider systems as smartphone assembly scales.
United States
E-commerce fulfillment networks in the Northeast and Mid-Atlantic corridors compress specification cycles to quarterly reviews and mandate inventory proximity within 150 miles of distribution nodes. EPA volatile organic compound emission limits tighten permissible styrene discharge rates from foam lamination operations. Automated sortation hubs serving New York and Philadelphia impose slotting fees and velocity penalties for stockouts.
Germany
Automotive parts distribution around Stuttgart and Wolfsburg generates recurring specification volume for anti-static foam divider assemblies. REACH substance restrictions from ECHA accelerate migration toward water-blown polyurethane formulations in European channels. The industrial packaging corridor concentrates converter capacity and captive resin supply for cross-linked polyethylene formulations.
China
Blown-molded polypropylene case production in Zhejiang and Guangdong provinces supplies low-cost imports displacing domestic assembly opportunities in standard-duty transportation segments. The country's national environmental regulator enforces dual carbon goals pressuring reformulation of foam blowing agents. Pearl River Delta manufacturing clusters integrate digital cutting workflows for mass-customized divider cavities.
India
Electronics manufacturing clusters in Noida and Sri City generate untapped demand for ESD-rated divider systems as smartphone and component production scales under PLI scheme incentives. BIS certification requirements shape material selection for export-oriented assembly plants. Tamil Nadu and Karnataka industrial corridors attract foam converter investments to serve contract manufacturing growth.
Padded Dividers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated case-and-divider manufacturers with captive foam supply, independent foam converters serving custom specification houses, and regional fabricators competing on lot-size flexibility. Dominant competitive moves include backward integration into resin formulation and geographic expansion through distribution partnerships near e-commerce fulfillment nodes.
Among North American protective case specialists, Pelican Products and SKB Cases exemplify integrated manufacturing archetypes with in-house production capabilities. Pelican Products occupies a position anchored by cross-linked polyethylene formulation expertise, while SKB Cases represents the military and broadcast equipment logistics specialization tier. European presence concentrates through B&W International and Nanuk as distribution-focused entities serving regional specification requirements. These named companies illustrate how competitive positioning stratifies between integrated manufacturers with material control and specialists optimizing for certification-heavy transportation segments.
| Leading Market Players |
|---|
| Pelican Products |
| SKB Cases |
| B&W International |
| Nanuk |
| GWP Group |
| Topper Cases |
| Seahorse Protective Cases |
| Nefab Packaging |
| Menasha Corporation |
| Others |
Value Network & Pricing Analysis
Certification-ladder divergence between MIL-STD-810G qualified systems and standard-duty e-commerce inserts manifests in both margin structures and resin sourcing strategies. Premium transportation tiers command 3-4x material cost multiples through captive cross-linked polyethylene supply, while commodity fulfillment specifications face margin compression from spot-market TDI and MDI exposure.
Pricing Analysis
Short lead-time premiums dominate pricing architecture, with sub-500-unit digital fabrication lots commanding substantial markups over hard-tooled volume contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification stacking intensity, with transportation and medical tiers least price-sensitive due to validation timeline barriers. Cost compression in standard-duty segments is intensifying because Chinese blown-molded shell imports displace domestic assembly opportunities. E-commerce fulfillment centers exhibit highest price sensitivity, accepting material substitutions to maintain slotting fee compliance.
Supply Chain Analysis
Cross-linked polyethylene resin supply rests on German and US Gulf Coast petrochemical corridors, with specialty foam blowing agent production concentrated in Belgium and the Netherlands. Key inputs include TDI, MDI, and water-blown polyurethane formulations facing REACH-driven substitution pressure. Single-source vulnerability runs through specialty anti-static additive suppliers serving Stuttgart automotive corridor specifications. Distribution runs through converter networks maintaining finished goods inventory within 150 miles of e-commerce fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into resin formulation and captive foam production represents the decisive competitive lever, with Pelican Products and SKB Cases demonstrating margin insulation through upstream control over cross-linked polyethylene supply.
For Market Incumbents: Extend certification portfolio depth to capture transportation and medical rental house segments where validation timelines deter challenger entry. Fortify captive resin supply against TDI and MDI volatility through long-term offtake agreements with German and US Gulf Coast petrochemical producers. Deepen digital fabrication capacity to serve sub-500-unit medical device field service configurations without hard-tooling economics erosion. For New Entrants and Emerging Players: Launch via cloud-based specification libraries targeting India's Noida and Sri City electronics manufacturing clusters, where PLI scheme incentives concentrate untapped ESD-rated divider demand. Exploit CNC programming talent scarcity among incumbent foam converters by recruiting water-jet operators with kerf compensation expertise for precision medical applications. Pursue closed-loop packaging-as-a-service models in Benelux grocery and cosmetics fulfillment networks. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified packaging conglomerates seeking transportation certification capabilities. Five-to-ten year viability favors converters with demonstrated REACH compliance migration and water-blown polyurethane formulation expertise. Monitor ECHA substance restriction update velocity as inflection indicator for stranded asset risk in legacy foam chemistry portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Pelican Products demonstrates margin insulation through captive cross-linked polyethylene supply amid petrochemical volatility. |
| Digital Fabrication Capacity Expansion | Water-jet and CNC routing workflows enable mass customization below 100-unit medical instrument set configurations. |
| REACH Compliance Migration | Water-blown polyurethane chemistry substitution preserves European distribution channel access under ECHA substance restrictions. |
| Geographic Proximity Inventory Positioning | Finished goods within 150 miles of Northeast and Mid-Atlantic fulfillment nodes satisfies omnichannel retailer contract terms. |
| Certification Portfolio Diversification | MIL-STD-810G, IATA Dangerous Goods, and ISO 11607 stacking extends validation timelines and deters price competition. |
Research Methodology
Document review covered customs and trade data, SEC 10-K filings, and ECHA substance restriction registers, complemented by interviews with foam converter plant managers, e-commerce procurement leads at omnichannel retailers, military specification engineers, and medical device field service directors. Secondary validation drew from automotive OEM packaging specifications, airline IATA Dangerous Goods compliance documentation, and EU Green Deal carbon accounting frameworks. Bottom-up volume estimates from converter capacity utilization triangulated against top-down demand aggregation from end-use sector procurement patterns.
Historical shipment data cross-referenced against expert panel input on REACH implementation timelines and digital fabrication adoption curves. Segmentation dimensions modeled include product type tier, end-use vertical, material chemistry family, and application performance specification across the analysis window. CAGRs derived from regression analysis of input cost trajectories and substitution elasticity parameters, with petrochemical feedstock volatility and Chinese import penetration serving as primary forecast sensitivity inputs.
REACH substance restriction acceleration, e-commerce fulfillment network consolidation velocity, and water-blown polyurethane formulation scale-up delays are the dominant revision risks to volume and value projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Asia-Pacific Protective Packaging Market
Protective Packaging
Void Fill Pillows Market
Protective Packaging
Tamper Proof Packaging Market
Protective Packaging
Protective Packaging Market
Protective Packaging
Europe Protective Packaging Market
Protective Packaging
Foam Mesh Sleeves Market
Protective Packaging
Insulated Shipping Boxes Market
Protective Packaging
Padded Mailers Market
Protective Packaging
Foam Packaging Inserts Market
Protective Packaging
Inflatable Packaging Market
Protective Packaging
Foam Edge Protectors Market
Protective Packaging
Insulated Packaging Market
Protective Packaging
Anti-Corrosive Packaging Market
Protective Packaging
Thermal Insulated Mailers Market
Protective Packaging
Latin America Protective Packaging Market
Protective Packaging
South Africa Protective Packaging Market