
 South Africa Protective Packaging Market | 2026-2036
South Africa Protective Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Protective Packaging Market Analytics
SABS Mark certification is reorganizing competitive access in South Africa's protective packaging sector, filtering out uncertified converters from formal supply chains. Sealed Air Corporation leverages its global technical library to sustain premium foam-in-place installations across automotive tier-one suppliers. Mondi Group anchors kraft paper cushioning capacity through integrated pulp-to-paperboard operations near Richards Bay. Nampak competes in molded fiber and corrugated formats for beverage export protection, occupying a dominant share of the domestic cardboard protective segment.
Protective packaging encompasses engineered cushioning, blocking, bracing, and void-fill systems designed to absorb mechanical shock, vibration, and compression forces during distribution. PE foam formulations with closed-cell densities between 25-200 kg/m³ provide calibrated impact absorption for precision electronics and pharmaceutical cold-chain shipments. Foam and bubble wrap categories dominate unit volume in domestic e-commerce fulfillment, though margin pools concentrate in export-grade paper padding and biodegradable alternatives where SABS environmental labeling commands price premiums. Biodegradable options represent the fastest-growing material class as Fast-Moving Consumer Goods brands mandate compostable void-fill in supplier scorecards.
SABS, the Department of Forestry, Fisheries and the Environment, and the International Safe Transit Association shape product testing protocols, material bans, and cross-border acceptance criteria for South African protective packaging exports. Extended producer responsibility regulations under the National Environmental Management Waste Act are forcing converters to redesign multi-material laminates into mono-substrate recyclable formats. Stakeholders must monitor SABS draft standards on recycled content thresholds, as these will determine which domestic mills qualify for preferred supplier status in corporate procurement frameworks.
Market Dynamics
SABS Mark certification is reorganizing competitive access in South Africa's protective packaging sector, filtering out uncertified converters from formal supply chains and forcing procurement managers to requalify vendor bases around documented compliance.
Growth Catalysts
- E-commerce fulfillment scale-up:Gauteng and Western Cape distribution centers are expanding protective packaging procurement volumes as online retail penetration deepens across South African metropolitan markets.
- Automotive component exports:Johannesburg's industrial corridor hosts tier-one automotive suppliers requiring calibrated cushioning systems for precision parts shipped to European and Asian assembly plants.
- Extended producer responsibility mandates:National Environmental Management Waste Act regulations are compelling converters to redesign multi-material laminates into mono-substrate recyclable formats.
Market Restraints
- Pulp cost volatility:Integrated paperboard operations near Richards Bay face input price swings tied to global softwood pulp markets and port logistics disruptions.
- Converter concentration:Domestic molded fiber capacity clusters among a limited set of established players, creating supply vulnerability for beverage exporters requiring certified export-grade protection.
- Biodegradable performance gaps:Compostable void-fill alternatives still exhibit inferior moisture resistance compared to conventional polyethylene foam, limiting cold-chain pharmaceutical applications.
Strategic Opportunities
- KwaZulu-Natal port expansion:Richards Bay and Durban harbor modernization projects will increase export packaging throughput for automotive and agricultural machinery shippers.
- Supplier scorecard mandates:Fast-Moving Consumer Goods brands are embedding compostable void-fill requirements into procurement frameworks, creating certified converter preference.
- Closed-loop recycling systems:Converters partnering with retail reverse-logistics networks can capture post-consumer polyethylene foam for reprocessing into secondary cushioning products.
Industry Challenges
- SABS certification timelines:New material qualification protocols require extended laboratory testing periods, delaying product launches for converters introducing novel substrate formulations.
- Skills scarcity in polymer chemistry:Formulation expertise for closed-cell PE foam density calibration remains concentrated among a narrow technical workforce in Gauteng.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Protective Packaging Market |
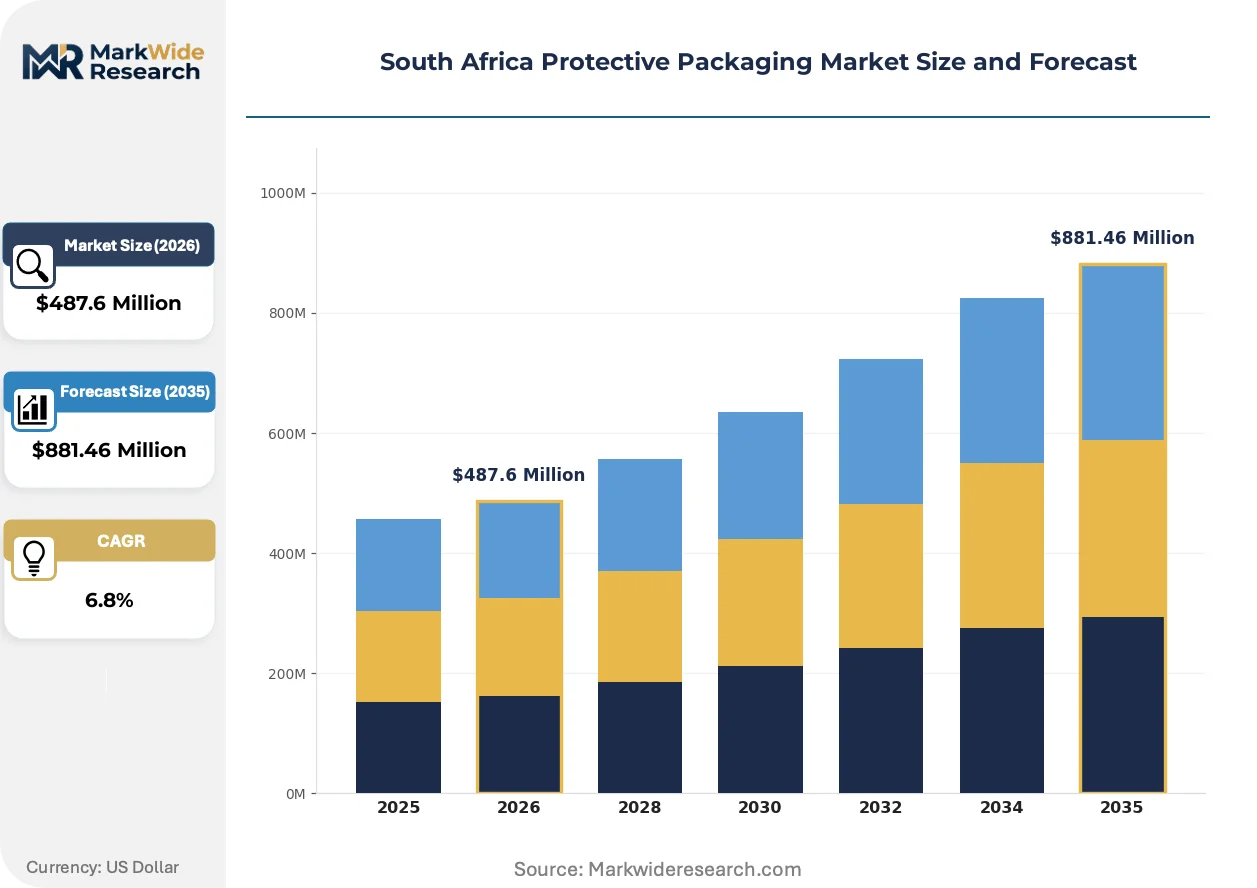
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bubble Wrap, Foam, PE Foam, Paper Padding End User: Electronics, Food & Beverage, Pharmaceuticals, E-commerce Material: Plastic, Cardboard, Paper, Biodegradable Options Application: Shipping, Storage, Retail Display, Export Packaging |
| Companies Covered | Sealed Air Corporation, Packman Industrial Packaging, VitaTex (Pty) Ltd, Dura Pack (Pty) Ltd, Amcor Ltd, Mondi Group, Nampak, Smurfit Kappa Group PLC, DS Smith, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Protective Packaging Market Evolving Landscape
Material science advances and regulatory stringency are converging to reshape how South African converters design cushioning systems, with certification-driven substitution and circular-economy integration dominating capital allocation decisions.
Molded pulp formulations derived from agricultural residues are displacing expanded polystyrene in consumer electronics export packaging. Johannesburg-based distributors serving smartphone and laptop shippers have accelerated adoption of this substrate over the past eighteen months. The shift is compressing demand for fossil-based foam-in-place systems among tier-two logistics providers lacking certified recycling infrastructure.
SABS draft standards on recycled content thresholds are forcing domestic paperboard mills to reconfigure furnish mixes and supplier qualification protocols. Converters dependent on imported kraft pulp face compliance timeline compression as the Department of Forestry, Fisheries and the Environment tightens cross-border waste shipment controls. Premium-positioned packaging suppliers with captive recycled fiber streams are capturing preferred supplier status in corporate procurement frameworks.
Consolidated buying by omnichannel retailers is compressing supplier bases and extending contract durations for certified protective packaging vendors. Mid-sized converters without SABS environmental labeling are losing shelf space to integrated competitors offering documented lifecycle assessments. The Western Cape wine export corridor exhibits the most pronounced concentration, with cooperative procurement pools replacing fragmented vineyard-level purchasing.
South Africa Protective Packaging Market Segmentation
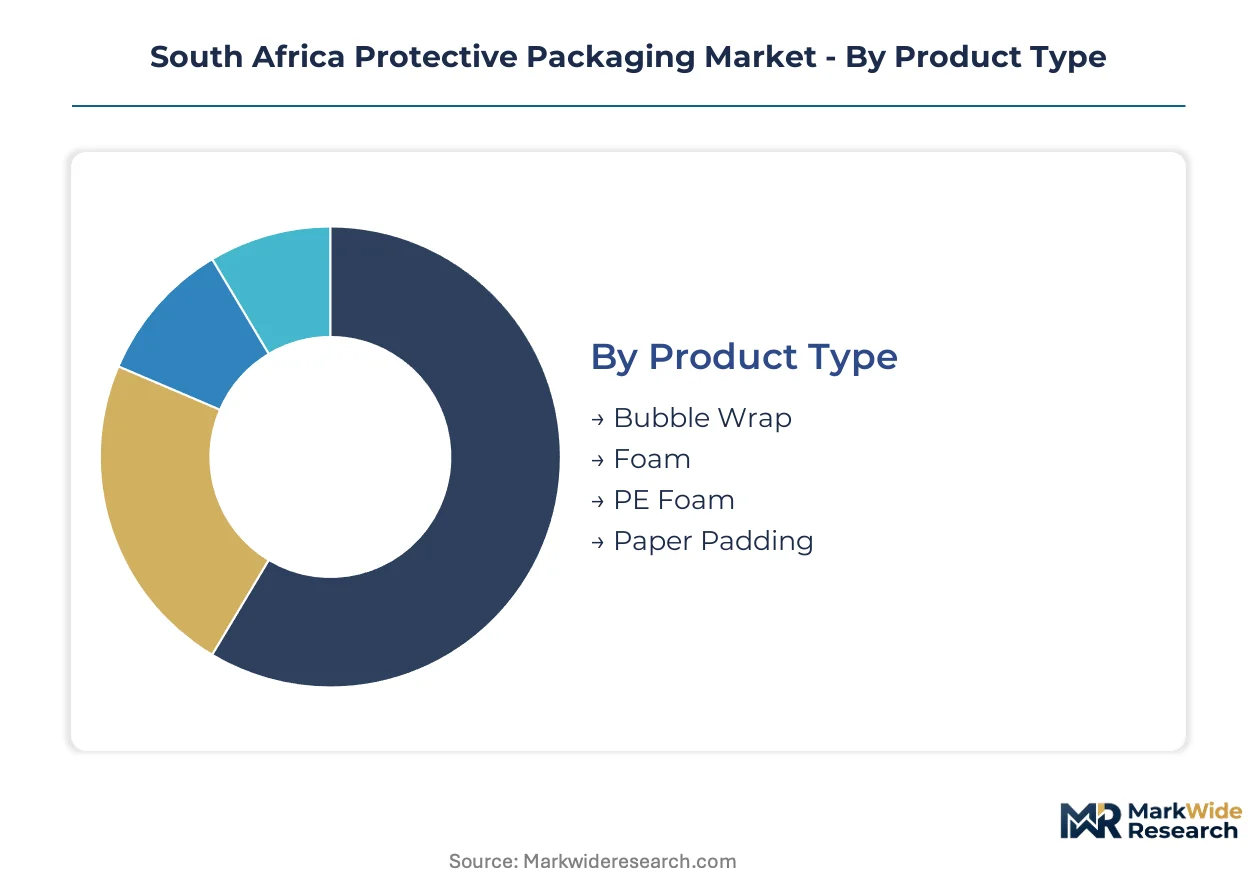
Channel configuration in South Africa's protective packaging sector varies sharply by segment, with e-commerce fulfillment centers demanding high-velocity void-fill while automotive exporters prioritize certified cushioning systems. SABS compliance requirements and port logistics constraints further differentiate how each segment flows through domestic distribution networks.
Product Type:
Channel mix splits between high-volume e-commerce fulfillment in Gauteng distribution centers and precision export packaging serving Johannesburg's automotive corridor.
- Bubble Wrap:Air-retention films with 10mm-50mm bubble diameters provide lightweight void-fill for consumer electronics and pharmaceutical shipments. Demand clusters in Cape Town e-commerce hubs where rapid pack-out speeds dominate procurement criteria. SABS-certified grades command supplier preference in formal retail supply chains.
- Foam:Expanded polystyrene and polyurethane systems deliver calibrated impact absorption for heavy machinery and automotive components. Johannesburg tier-one suppliers specify density-graded formulations for European export compliance. Moisture sensitivity limits adoption in KwaZulu-Natal's humid coastal logistics corridors.
- PE Foam:Closed-cell polyethylene with 25-200 kg/m³ density ranges serves precision electronics and cold-chain pharmaceutical distribution. Integrated converters near Richards Bay leverage captive resin supply for cost positioning.
- Paper Padding:Kraft-based cushioning and corrugated inserts protect wine exports through the Western Cape corridor. Recycled content thresholds under draft SABS standards are reshaping mill qualification protocols.
Bubble Wrap dominates installed base. PE Foam is where expansion concentrates.
End User:
Cost tier stratification separates premium certified packaging for regulated exports from economy-grade void-fill serving domestic e-commerce.
- Electronics:Smartphone and laptop distributors in Johannesburg require anti-static foam and molded pulp systems with documented drop-test certification. SABS Mark compliance filters supplier access to tier-one procurement frameworks.
- Food & Beverage:Wine exporters through Western Cape cooperative pools drive molded fiber and corrugated protection demand. Extended producer responsibility mandates are accelerating compostable substrate adoption.
- Pharmaceuticals:Cold-chain shipments require moisture-resistant closed-cell foam with validated thermal insulation performance. PE foam formulations with calibrated density profiles dominate this specification-intensive segment.
- E-commerce:Omnichannel retailers in Gauteng and Western Cape distribution centers procure high-velocity bubble wrap and paper void-fill. Consolidated buying is compressing supplier bases toward SABS-certified vendors.
Electronics commands premium pricing tiers. E-commerce is climbing the fastest in volume terms.
Material:
Volume concentration favors plastic and cardboard in established logistics channels, while margin pools shift toward certified biodegradable alternatives.
- Plastic:Polyethylene and polypropylene formulations deliver moisture resistance and impact absorption across automotive and electronics applications. Port logistics disruptions affecting Richards Bay resin supply create input cost volatility.
- Cardboard:Corrugated board and molded fiber protect beverage and agricultural machinery exports through Durban and Richards Bay harbors. Domestic recycled fiber supply constraints are tightening furnish mix options.
- Paper:Kraft wrapping and paper padding serve wine export and consumer goods distribution with lower environmental compliance burden. SABS draft standards on recycled content are forcing mill reconfiguration.
- Biodegradable Options:Compostable void-fill from agricultural residues displaces expanded polystyrene in electronics export packaging. Fast-Moving Consumer Goods supplier scorecards mandate certified compostable substrates.
Plastic and Cardboard dominate installed base. Biodegradable Options represent the steepest expansion trajectory.
Application:
Customer type differentiation separates high-frequency e-commerce shippers from capital-intensive export packaging requiring certified documentation.
- Shipping:Void-fill and cushioning systems for parcel distribution through domestic courier networks and international freight. Gauteng fulfillment centers drive procurement scale for standardized bubble wrap and foam formats.
- Storage:Long-term protective wrapping for inventory holding and warehouse buffer stock. Automotive component suppliers in Johannesburg specify UV-stable PE foam for extended storage cycles.
- Retail Display:Point-of-sale protection combining cushioning with aesthetic presentation for consumer electronics and premium beverages. Western Cape wine distributors prioritize molded pulp with branded surface finishing.
- Export Packaging:Certified cushioning systems meeting International Safe Transit Association protocols for cross-border shipment. SABS compliance and European destination requirements filter supplier participation.
Shipping dominates installed base. Export Packaging is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes concentrate in three distinct corridors: e-commerce fulfillment operators in Gauteng, automotive tier-one suppliers along Johannesburg's industrial belt, and wine export cooperatives through the Western Cape. Each corridor demands different certification tiers and material specifications.
Gauteng Province
E-commerce fulfillment centers in Johannesburg and Pretoria drive high-velocity procurement of bubble wrap and paper void-fill systems. The South African Bureau of Standards packaging compliance protocols filter supplier access to formal retail supply chains. Industrial parks in Midrand and Rosslyn host concentrated distribution infrastructure serving omnichannel retailers.
Western Cape
Wine export cooperatives and consumer electronics distributors dominate demand for molded pulp and corrugated protection formats. Extended producer responsibility regulations under the National Environmental Management Waste Act accelerate compostable substrate adoption. Cape Town's harbor logistics corridor channels certified export packaging toward European destinations.
KwaZulu-Natal
Richards Bay pulp-to-paperboard operations anchor kraft cushioning capacity for agricultural machinery and automotive component exports. Port modernization projects at Durban harbor expand throughput for protective packaging serving Asian and European markets. Humid coastal conditions limit expanded polystyrene adoption in favor of moisture-resistant PE foam systems.
Eastern Cape
Automotive component assembly plants in Gqeberha and East London require calibrated cushioning for precision parts shipped to European OEMs. The Department of Forestry, Fisheries and the Environment tightens cross-border waste shipment controls affecting recycled fiber supply. Coega Industrial Development Zone attracts packaging converters seeking export-oriented manufacturing platforms.
South Africa Protective Packaging Market Competitive Landscape
Player mix skews toward integrated paperboard producers and specialty foam converters with captive certification status. Domestic molded fiber capacity clusters among established operators, creating supply vulnerability for beverage exporters requiring SABS Mark documentation. Three archetypes dominate: integrated pulp-to-packaging conglomerates with Richards Bay fiber advantages, Gauteng-based foam specialists serving automotive tier-ones, and corrugated converters with wine export corridor relationships. Competitive moves concentrate on SABS certification acquisition and recycled content threshold positioning ahead of draft standard finalization.
Among integrated paperboard producers, Mondi Group and Nampak exemplify archetypes leveraging captive fiber streams and export corridor positioning. Sealed Air Corporation occupies the premium foam-in-place tier serving automotive precision parts distributors. Smurfit Kappa Group PLC and DS Smith represent European-headquartered corrugated specialists with South African operating subsidiaries. These five named entities anchor competitive dynamics without exhaustively mapping vendor fragmentation.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Packman Industrial Packaging |
| VitaTex (Pty) Ltd |
| Dura Pack (Pty) Ltd |
| Amcor Ltd |
| Mondi Group |
| Nampak |
| Smurfit Kappa Group PLC |
| DS Smith |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with kraft pulp indexation lock in supply access for integrated paperboard mills near Richards Bay while insulating tier-one automotive suppliers from spot market volatility. SABS Mark certification requirements add a compliance premium that separates certified converters from uncertified competitors in formal procurement channels.
Pricing Analysis
Cost-plus contracts with global softwood pulp indexation dominate procurement between Richards Bay integrated mills and Johannesburg automotive tier-ones. Three-tier pricing structure across SABS-certified premium, standard mill-grade, and spot-market economy levels filters supplier access by compliance tier. Cost compression in the economy tier intensifies because import-dependent converters face timeline pressure from draft recycled content standards. E-commerce fulfillment centers in Gauteng exhibit highest price sensitivity due to high-volume, low-margin void-fill procurement, while pharmaceutical cold-chain shippers accept premium PE foam pricing for validated thermal performance.
Supply Chain Analysis
South Africa and Brazil anchor global softwood pulp supply feeding Richards Bay paperboard operations, with resin feedstock drawing from Saudi Arabian and South Korean petrochemical complexes. Domestic molded fiber capacity rests on agricultural residue collection networks and imported kraft pulp furnish. Single-source vulnerability concentrates in certified PE foam formulation expertise clustered around Gauteng polymer chemistry specialists. Distribution runs through Durban and Richards Bay harbor logistics corridors serving European and Asian export destinations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarce SABS certification capacity and concentrated polymer chemistry expertise in Gauteng create bottlenecks that determine competitive access. Converters without documented compliance face exclusion from formal supply chains as procurement managers requalify vendor bases.
For Market Incumbents: Consolidate certification advantage by accelerating SABS Mark acquisition ahead of draft standard finalization, and secure captive recycled fiber streams through backward integration into post-consumer collection partnerships. Emerging biodegradable substrate specialists threaten premium positioning unless incumbents lock in compostable void-fill capacity. For New Entrants and Emerging Players: Lead with certified compostable void-fill formulations targeting Fast-Moving Consumer Goods supplier scorecard mandates in the Western Cape wine export corridor. Agricultural residue-based molded pulp for consumer electronics export packaging offers the most penetrable white space given SABS environmental labeling premiums. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors integrated pulp-to-packaging conglomerates with captive fiber streams and existing SABS certification. Long-term viability over the next decade hinges on positioning ahead of recycled content threshold enforcement. Watch SABS draft standard publication timelines as the inflection signal determining which domestic mills qualify for preferred supplier status.| Strategic Initiative | Industry Significance |
|---|---|
| SABS Certification Acceleration | Early compliance acquisition locks out uncertified competitors from formal retail supply chains. |
| Backward Integration into Recycled Fiber | Captive post-consumer collection secures furnish supply ahead of draft content threshold mandates. |
| Compostable Substrate Capacity Buildout | Agricultural residue processing lines capture Fast-Moving Consumer Goods supplier scorecard preference. |
| Port Logistics Partnership | Richards Bay and Durban harbor alliances reduce export packaging throughput bottlenecks. |
| Closed-Loop Recycling Systems | Retail reverse-logistics partnerships convert post-consumer PE foam into secondary cushioning products. |
Research Methodology
Initial hypotheses were tested against primary input from SABS certification officers, automotive tier-one procurement managers, e-commerce fulfillment center operators, and kraft paper mill technical directors, and refined through secondary validation against customs trade records, Department of Forestry, Fisheries and the Environment regulatory filings, South African Bureau of Standards draft documentation, and pulp price index data. Bottom-up segment sizing triangulated with top-down market reconstruction.
Variance decomposition across product type, end-user industry, material substrate, and geographic corridor dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories and value-per-unit trends calibrated against Richards Bay pulp cost movements and SABS compliance timeline assumptions.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce penetration, stable pulp cost corridors, or delayed SABS standard finalization would require recalibration. Forecasts reflect documented assumptions on certification adoption curves and recycled fiber supply availability. Recalibration cycles align with material shifts in regulatory enforcement timelines and harbor infrastructure completion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Europe Protective Packaging Market
Protective Packaging
Global Packaging Inserts and Cushions Market
Protective Packaging
Anti-Static Foam Packaging Market
Protective Packaging
Foam Packaging Inserts Market
Protective Packaging
Packaging and Protective Packaging Market
Protective Packaging
Protective Wrapping Paper Market
Protective Packaging
Tamper Proof Packaging Market
Protective Packaging
Middle East and Africa Protective Packaging Market
Protective Packaging
Protective Packaging Market
Protective Packaging
High Pressure Protective Packaging Film Market
Protective Packaging
Molded Fiber Pulp Edge Protectors Market
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Thermal Insulated Mailers Market
Protective Packaging
Fiber Cushioning Market
Protective Packaging
Insulated Shippers Market
Protective Packaging
Padded Mailers Market