
 Asia Pacific Modular Construction Market | 2026-2036
Asia Pacific Modular Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Modular Construction Market Insights
Buyer concentration is expanding across Asia Pacific's real estate developer segment as institutional capital pools into residential and commercial projects. Broad Group leverages its prefabricated high-rise technology to dominate urban density solutions in China. Sekisui House sustains manufacturing scale across Japan's precision-engineered housing supply chain. CIMC Modular Building Systems anchors export capacity for volumetric units serving Australia's remote resource projects.
Asia Pacific modular construction refers to offsite fabrication of building sections in controlled factory environments, with modules typically achieving structural tolerances within two millimeters before transport to final sites for assembly. The primary purpose centers on compressing project schedules, reducing material waste, and standardizing quality across dispersed geographic markets. Permanent modular leads volume share among product types due to its suitability for multi-story residential towers across dense Asian cities. Volumetric construction methods command premium positioning in healthcare and educational applications where MEP integration complexity demands factory-controlled conditions. Relocatable modular occupies niche demand from mining camps and disaster relief operations across Indonesia and the Philippines.
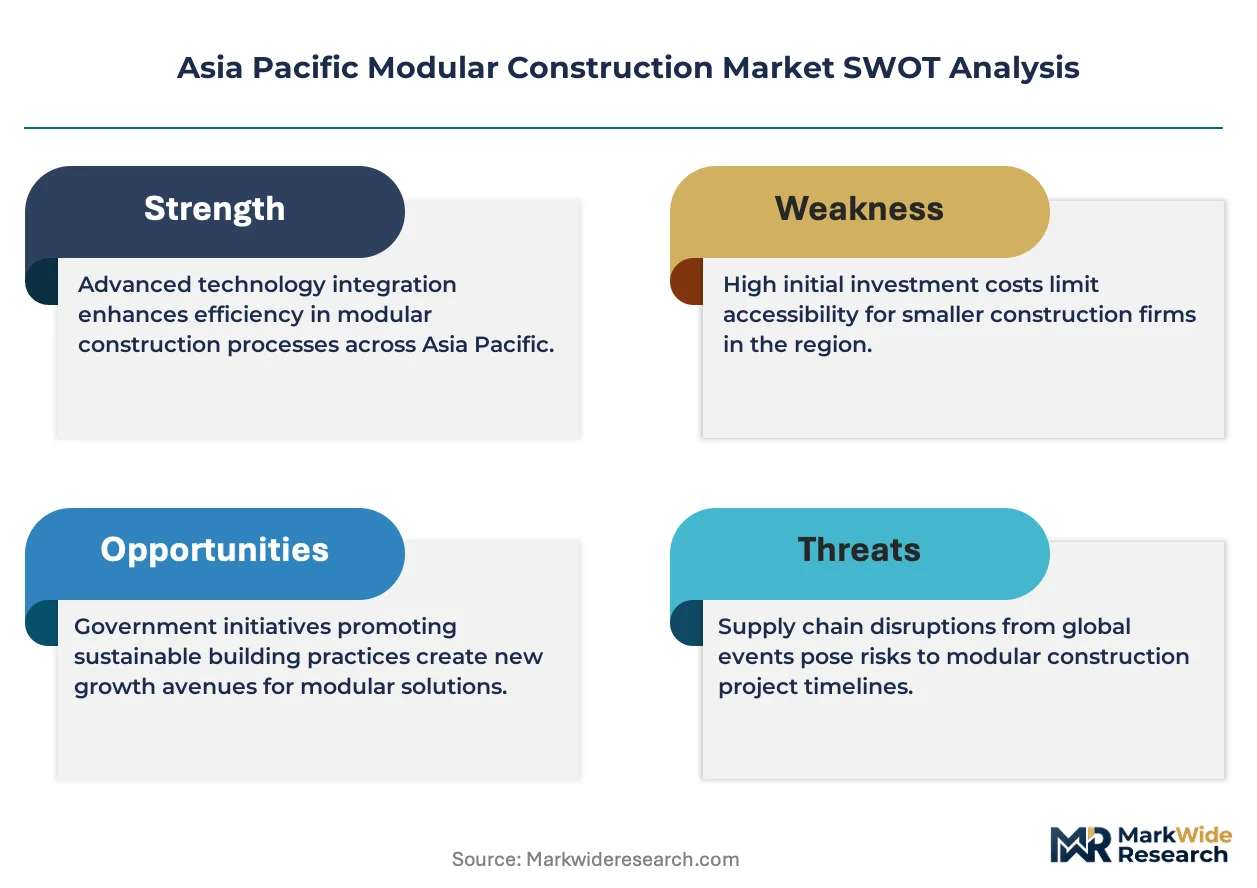
China's MEE enforces dual carbon compliance that penalizes on-site concrete pouring, redirecting public project procurement toward certified offsite fabricators. Australia's National Construction Code and Japan's JIS standards create divergent certification pathways that fragment cross-border module trade. India's BIS mandates structural testing protocols for factory-built components entering government housing schemes. Stakeholders must monitor how each national regulator calibrates carbon accounting rules to determine where module sourcing advantages shift across the region.
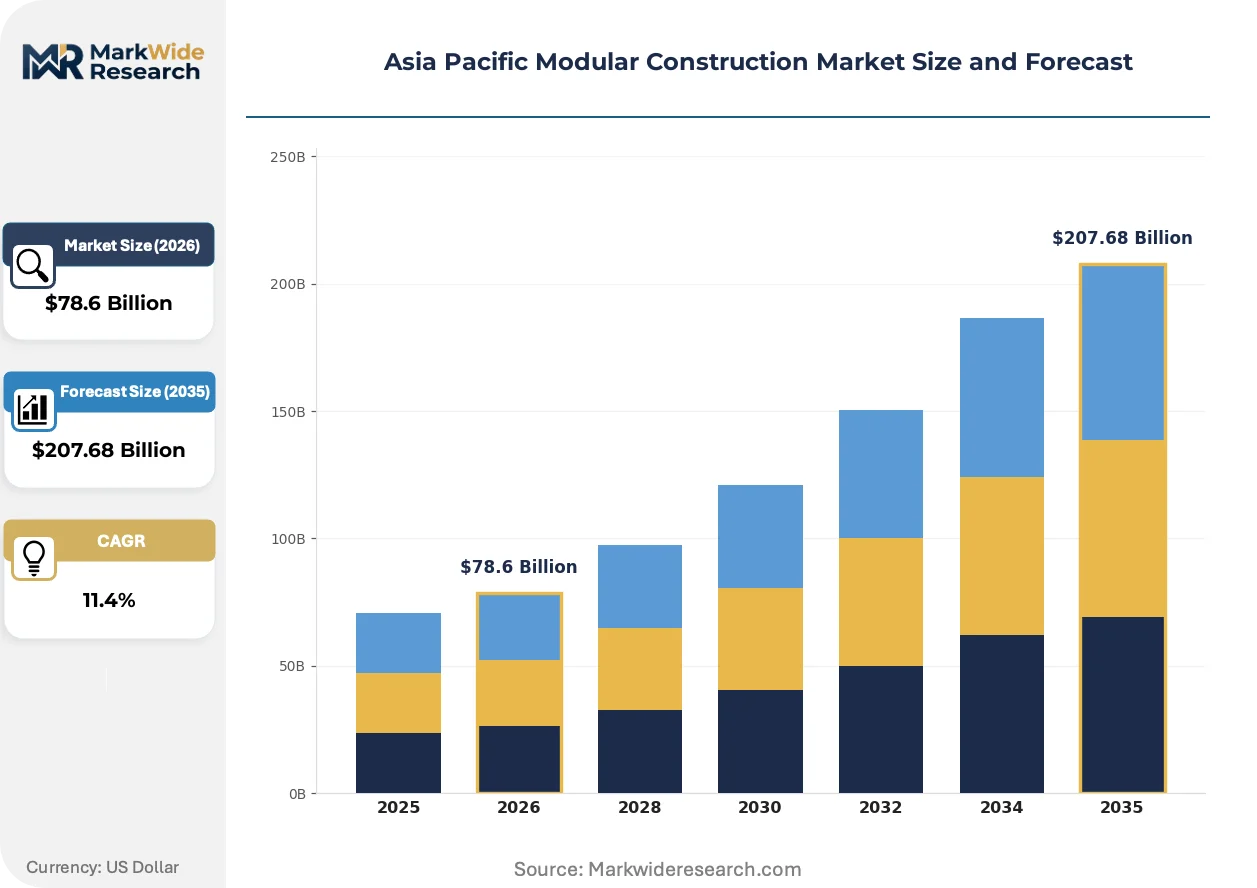
Market Dynamics
China's dual carbon goals from MEE are systematically penalizing on-site concrete pouring, redirecting public project procurement toward certified offsite fabricators across the region. This regulatory pressure cascade is compressing traditional construction timelines and forcing asset owners to restructure supplier relationships around factory-controlled delivery.
Growth Catalysts
- Affordable Housing Mandates:Southeast Asian governments are deploying volumetric units for rapid infrastructure delivery in urban corridors. Indonesia's Perumahan Rakyat program and the Philippines' Pambansang Pabahay initiative accelerate modular adoption for residential towers.
- Carbon Compliance Pressure:China's MEE enforcement redirects state-owned developer procurement toward certified offsite fabricators. Penalties for on-site emissions exceed cost premiums for factory-built modules in tier-one city projects.
- Cross-Laminated Timber Advancement:Engineered wood products enable mid-rise modular construction with lower embodied carbon. Japanese and Australian fabricators integrate CLT structural cores into hybrid steel-timber volumetric systems.
Market Restraints
- Steel Input Volatility:Hot-rolled coil price fluctuations in China and India compress fabricator margins. Long-term module contracts expose producers to unhedged commodity exposure across 12-18 month production cycles.
- Certification Fragmentation:Divergent pathways between Australia's National Construction Code and Japan's JIS standards fragment cross-border module trade. Exporters face redundant testing protocols for each destination market.
- Site-Built Substitution:Informal labor markets in Vietnam and Bangladesh sustain cost advantages for conventional construction. Low-rise residential projects in secondary cities resist modular premiums.
Strategic Opportunities
- Healthcare Infrastructure:Hospital expansion in India's tier-two cities creates demand for MEP-integrated volumetric units. Operating theater modules and isolation wards require factory-controlled cleanroom conditions.
- Remote Resource Projects:Mining camps across Western Australia and Papua New Guinea drive relocatable modular demand. Fly-in-fly-out workforce housing requires rapid deployment and redeployment capabilities.
- Digital Twin Integration:Convergence of BIM workflows with IoT-enabled module tracking reduces site integration errors. Singaporean developers mandate digital handoff protocols for government land sales.
Industry Challenges
- Skilled Technician Scarcity:Factory MEP integration requires certified electricians and plumbers with offsite fabrication experience. Training pipelines in Indonesia and the Philippines lag behind facility expansion.
- Transportation Geometry Constraints:Road width and bridge load limits restrict module dimensions in Vietnam's Mekong Delta and the Philippines' archipelago geography. Fabricators must design for disassembly or barge-based delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Modular Construction Market |
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $207.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent Modular, Relocatable Modular, Hybrid Modular, Modular Components Application: Residential Buildings, Commercial Structures, Educational Facilities, Healthcare Units Construction Method: Panelized, Precast, 3D Printing, Volumetric End User: Construction Firms, Real Estate Developers, Government Agencies, Private Investors |
| Companies Covered | Broad Group, Laing O'Rourke, Sekisui House, Larsen & Toubro, Red Sea International, Daiwa House Industry, Lendlease, CIMC Modular Building Systems, China State Construction Engineering Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Modular Construction Market Trends and Innovations
Digital fabrication workflows and sustainable material systems are compressing design-to-occupancy timelines across Asia Pacific modular construction. Factory automation and regulatory carbon accounting are converging to redefine competitive positioning.
Light-gauge steel framing systems are modularizing mid-rise residential construction across Chinese and Australian markets. Developers in Shenzhen and Melbourne specify cold-formed steel volumetric cores for 15-25 storey towers. This technology is modularizing structural assembly timelines from months to weeks while maintaining seismic compliance under divergent national codes.
Japan's METI has revised building energy efficiency standards to credit offsite fabrication for reduced construction-phase emissions. The amendment requires lifecycle carbon disclosure for public building procurements exceeding specified thresholds. Healthcare and educational project owners in Tokyo and Osaka now specify factory-built MEP modules to satisfy compliance timelines.
Asset owners are consolidating supplier relationships around design-build-operate contracts for institutional portfolios. Singaporean REITs and Australian superannuation funds now contract directly with modular fabricators for multi-project rollouts. This concentration is most visible in aged care and student housing verticals where standardized unit repetition accelerates capital deployment cycles.
Asia Pacific Modular Construction Market Segmentation
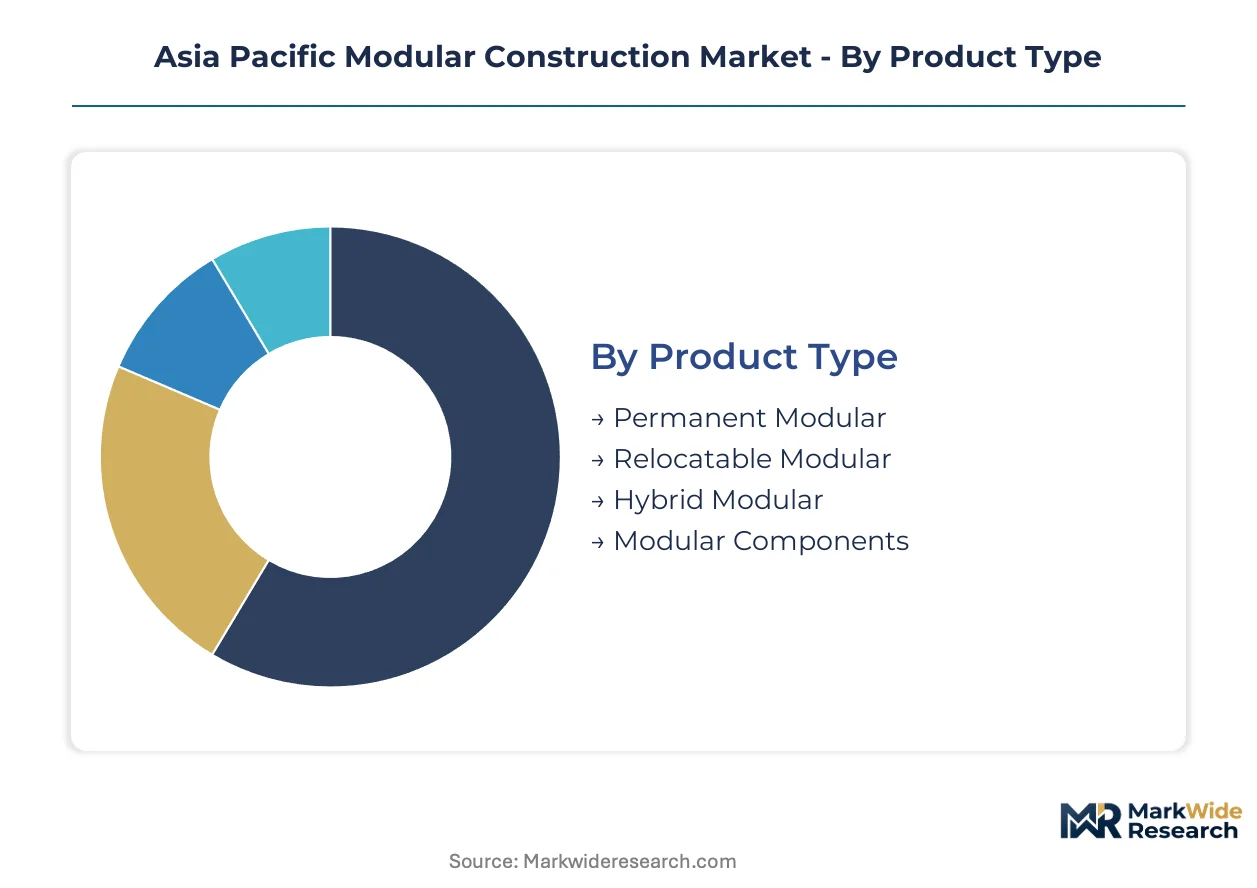
Modular construction in Asia Pacific fragments across four structural dimensions that determine procurement patterns and margin profiles. Product type governs capital intensity and reuse economics. Application verticals dictate regulatory exposure and MEP complexity. Construction method shapes supply chain geography and skilled labor requirements.
Product Type:
Integration depth varies sharply—permanent modular embeds into finished structures while relocatable units retain standalone mobility.
- Permanent Modular:Steel or concrete volumetric units designed for permanent structural integration with conventional foundations. Multi-story residential towers in Shenzhen and Melbourne specify these for 15-25 storey assemblies where seismic compliance is non-negotiable.
- Relocatable Modular:Self-contained units engineered for repeated transport and reassembly without structural degradation. Mining camps across Western Australia and Papua New Guinea drive demand where fly-in-fly-out workforce housing requires rapid redeployment cycles.
- Hybrid Modular:Systems combining factory-built volumetric cores with site-built structural envelopes.
- Modular Components:Discrete sub-assemblies such as bathroom pods or plant rooms for integration into conventional builds.
Permanent modular leads volumes today; relocatable modular is gaining share fastest.
Application:
End-use concentration clusters around urban density solutions and institutional infrastructure where schedule compression carries premium value.
- Residential Buildings:Volumetric apartment modules for high-density urban corridors where land costs justify factory premiums. Indonesia's Perumahan Rakyat program and the Philippines' Pambansang Pabahay initiative accelerate adoption for affordable housing towers.
- Healthcare Units:Operating theater modules and isolation wards requiring factory-controlled cleanroom conditions. Hospital expansion in India's tier-two cities creates sustained demand for MEP-integrated units where site-built alternatives face contamination risks.
- Commercial Structures:Office and retail shells with standardized repetition across portfolio developments.
- Educational Facilities:Classroom blocks and dormitory units for rapid campus expansion.
Residential applications dominate current procurement; healthcare units command the steepest expansion trajectory.
Construction Method:
Method selection trades off dimensional flexibility against labor substitution and carbon accounting advantages.
- Volumetric:Fully enclosed three-dimensional modules with integrated MEP and finishes. Premium positioning in healthcare and educational applications where factory-controlled conditions manage complexity that site-built alternatives cannot replicate.
- Panelized:Flat-pack wall, floor, and roof panels for site assembly into structural shells. Cold-formed steel panel systems from Japanese and Australian fabricators enable mid-rise construction with lower embodied carbon than conventional steel.
- Precast:Factory-cast concrete elements requiring crane-assisted placement and on-site connection.
- 3D Printing:Additive manufacturing of structural elements from concrete or polymer composites.
Volumetric methods anchor premium-tier pricing; panelized systems are expanding most quickly across mid-rise residential.
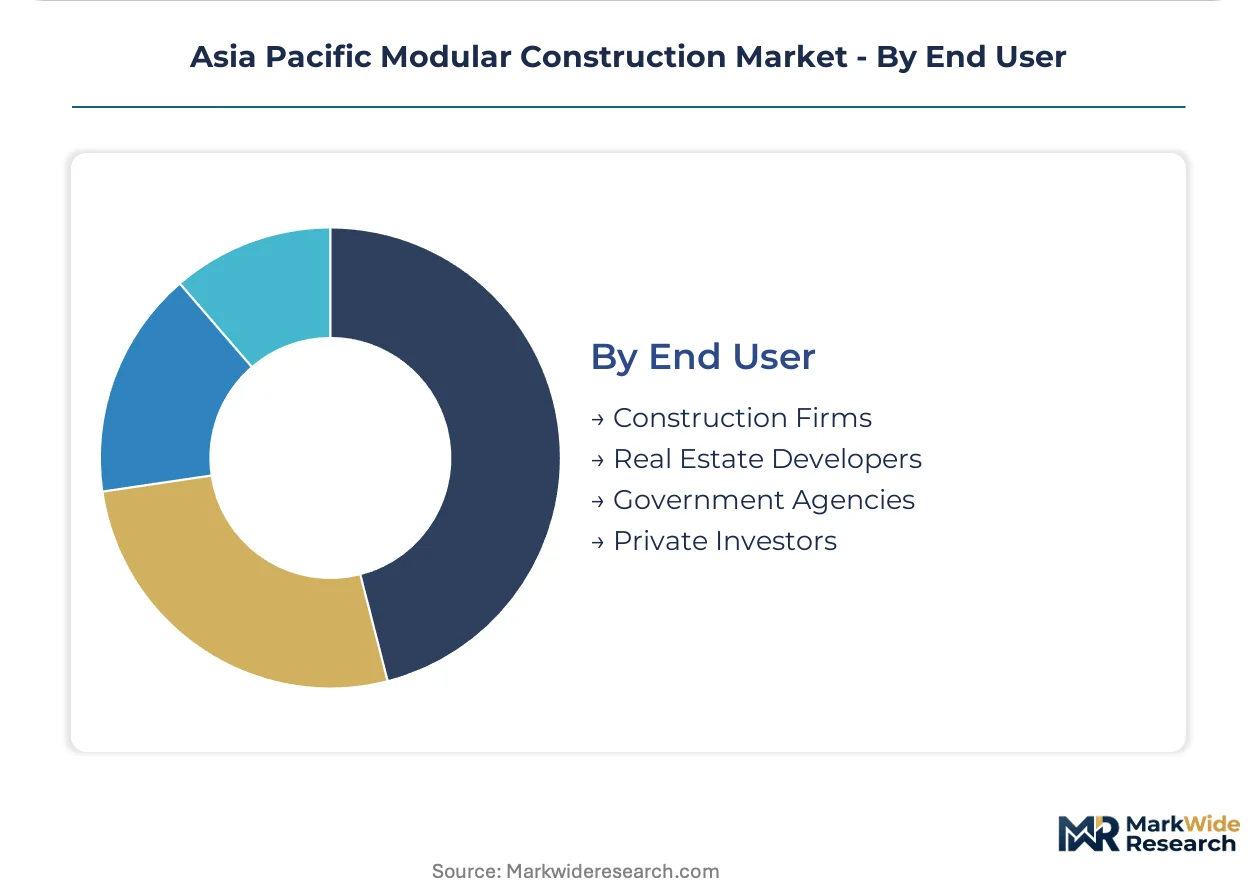
End User:
Procurement authority is consolidating around institutional capital pools with multi-project rollout capacity.
- Government Agencies:Public housing authorities and infrastructure ministries with mandate-driven procurement timelines. China's state-owned developers redirect procurement toward certified offsite fabricators under MEE dual carbon enforcement.
- Real Estate Developers:Institutional capital deploying standardized unit repetition across residential and aged care portfolios. Singaporean REITs and Australian superannuation funds contract directly with fabricators for multi-project rollouts.
- Construction Firms:General contractors integrating modular sub-assemblies into conventional project delivery.
- Private Investors:Smaller-scale developers and owner-occupiers with single-project procurement scope.
Government agencies lead current volumes; real estate developers are consolidating procurement authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's state-directed procurement dwarfs Australia's resource-driven demand, yet both markets now enforce factory-built delivery through divergent regulatory pathways. Carbon compliance in tier-one Chinese cities and labor scarcity in Australian remote sites compress timelines toward offsite fabrication. Southeast Asian governments are deploying volumetric solutions for mass housing mandates.
China
State-owned developers redirect procurement toward certified offsite fabricators under MEE dual carbon enforcement. Penalties for on-site concrete pouring now exceed factory module premiums in Shenzhen and Shanghai. The Yangtze River Delta anchors prefabricated high-rise production where Broad Group dominates urban density solutions.
Japan
Precision-engineered housing supply chains sustain manufacturing scale across Kanto and Kansai regions. METI's revised building energy efficiency standards credit offsite fabrication for reduced construction-phase emissions. Sekisui House and Daiwa House Industry anchor factory production in Osaka and Nagoya corridors.
Australia
Mining camps across Western Australia drive relocatable modular demand for fly-in-fly-out workforce housing. The National Construction Code creates certification pathways that fragment cross-border module trade with Asian suppliers. Lendlease and Laing O'Rourke consolidate procurement for remote resource projects.
India
Urban corridors deploy volumetric units for rapid infrastructure delivery under government housing schemes. BIS mandates structural testing protocols for factory-built components entering Perumahan Rakyat-equivalent programs. Larsen & Toubro anchors manufacturing capacity in Maharashtra and Gujarat for hospital expansion in tier-two cities.
Indonesia
The Perumahan Rakyat affordable housing program accelerates modular adoption for residential towers in Jakarta and Surabaya. Informal labor markets in secondary cities sustain cost advantages for conventional construction. Red Sea International and regional fabricators target mining camp and disaster relief operations across the archipelago.
Asia Pacific Modular Construction Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers. The vendor base organizes around three strategic archetypes: state-linked engineering groups with captive project pipelines, precision housing manufacturers with decades of factory automation, and export-oriented volumetric fabricators serving remote resource sites. Competitive moves concentrate on M&A for technology access and capacity expansion in ASEAN manufacturing zones.
Within the precision housing tier, Sekisui House and Daiwa House Industry exemplify decades-long factory automation investment. Among state-linked engineering groups, China State Construction Engineering Corporation and Larsen & Toubro occupy positions shaped by government procurement mandates. CIMC Modular Building Systems represents the export-oriented archetype, anchoring volumetric capacity for Australian and Middle Eastern resource projects.
| Leading Market Players |
|---|
| Broad Group |
| Laing O'Rourke |
| Sekisui House |
| Larsen & Toubro |
| Red Sea International |
| Daiwa House Industry |
| Lendlease |
| CIMC Modular Building Systems |
| China State Construction Engineering Corporation |
| Others |
Pricing and Supply Chain Analysis
Factory-certified MEP technicians in China's Yangtze River Delta anchor labor-cost differentials that separate premium volumetric modules from economy-grade panelized systems across Asia Pacific procurement tiers. Wage compression in Indonesian and Vietnamese fabrication facilities feeds pricing spreads between certified cleanroom units and standard residential modules.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for standard panelized residential modules. Project-based contract pricing dominates, with differentiation driven by JIS certification tier and volume scale commitments. Cost compression in economy-tier steel framing is intensifying because hot-rolled coil volatility remains unhedged across 12-18 month production cycles. Government housing agencies exhibit highest price sensitivity; Australian mining operators show lowest sensitivity due to fly-in-fly-out schedule premiums.
Supply Chain Analysis
Refurbishment flows for relocatable mining camp units create secondary supply streams from Western Australia back to Southeast Asian fabrication hubs. Manufacturing concentrates in China, Japan, and Australia, with steel coil, cross-laminated timber, and MEP components as critical inputs. Single-source vulnerability runs through Chinese hot-rolled coil supply for regional fabricators. Distribution runs through direct design-build-operate contracts with institutional capital pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific modular construction offers margin expansion through factory automation adoption and premium-tier volumetric positioning in healthcare infrastructure. Carbon compliance penalties in Chinese tier-one cities accelerate cost-down advantages for certified offsite fabricators.
For Market Incumbents: Hedge steel input exposure through backward integration into coil supply or long-term offtake agreements with Chinese mills. Defend positioning against emerging Indonesian panelized specialists by accelerating JIS-equivalent certification investments in ASEAN manufacturing zones. Prioritize MEP technician training pipelines to lock in cleanroom module premiums.
For New Entrants and Emerging Players: The premium-economy price gap in Indian tier-two city hospital expansion creates white-space entry. Target healthcare volumetric units where site-built alternatives face contamination risks and BIS testing mandates favor factory-controlled production. Pursue design-build-operate contract structures with state housing agencies to bypass developer procurement consolidation.
For Investors and Strategic Acquirers: Australian superannuation funds and Singaporean REITs are the most active acquirer in this space, consolidating around multi-project aged care and student housing rollouts. Acquisition targets should exhibit captive manufacturing capacity in ASEAN zones with demonstrated MEP integration capabilities. Watch for MEE carbon accounting rule calibration as inflection signal for procurement advantage shifts across the region.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Coil Supply | Secures input cost stability against Shanghai Futures Exchange volatility for fabricators. |
| JIS Certification Investment in ASEAN Facilities | Unlocks Japanese healthcare procurement where METI energy standards credit offsite fabrication. |
| Digital Twin Platform Deployment | Singaporean government land sales now mandate BIM-to-IoT handoff protocols for bidders. |
| Healthcare Volumetric Capacity Expansion | Operating theater modules command premium positioning where cleanroom conditions are non-negotiable. |
| Relocatable Modular Refurbishment Network | Western Australian mining camp redeployment cycles create recurring revenue streams. |
Research Methodology
Coverage spans China, Japan, Australia, India, and Southeast Asia, with primary inputs from each market cluster. The research combines interviews with modular fabrication plant managers, procurement leads at Australian resource operators, healthcare facility development executives, and government housing agency contract officers with secondary validation from BIS structural testing protocols, MEE dual carbon enforcement documentation, METI building energy efficiency amendments, and customs trade data for steel coil and CLT imports. Bottom-up project pipeline analysis triangulates against top-down regional construction spend estimates.
Granularity extends to product type, application vertical, construction method, and end user archetype across national regulatory clusters. CAGRs derive from modeled unit deployment volumes and average selling price trajectories over the projection horizon. Forecast inputs incorporate MEE penalty schedules for on-site concrete pouring, JIS certification pathway timelines, and fly-in-fly-out workforce housing replacement cycles.
Caveats apply where steel commodity volatility, regulatory harmonization failures, or transportation geometry constraints could materially shift the outlook. Forecasts reflect assumptions around carbon accounting rule stability and skilled technician training pipeline expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
South Korea 3D Printing Construction Market
Building Construction
Thailand Construction Market
Building Construction
Germany Prefabricated Buildings Market
Building Construction
Prefabricated Buildings Market
Building Construction
United Arab Emirates Infrastructure Market
Building Construction
Bangladesh Construction Market
Building Construction
GCC Green Buildings Market
Building Construction
China Modular Construction Market
Building Construction
US Modular Construction Market
Building Construction
Construction Market
Building Construction
Kuwait Construction Market
Building Construction
Spain Construction Market
Building Construction
US Offsite Construction Market
Building Construction
Eastern Europe Construction Market
Building Construction
Saudi Arabia Transportation Infrastructure Construction Market
Building Construction
GCC Advanced Buildings Materials Market