
 Ireland Data Center Construction Market | 2026-2036
Ireland Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Ireland Data Center Construction Market Insights
Hyperscale cloud buyers is unwinding traditional enterprise-led construction patterns across Ireland. Mercury Engineering leverages its electrical and mechanical capabilities to dominate turnkey delivery for major campus developments. Jacobs Engineering Group anchors its position through deep engineering design capacity tied to hyperscale power density requirements. Arup differentiates via sustainable design consulting that addresses Ireland's corporate sustainability reporting obligations.
Ireland data center construction encompasses the civil, mechanical, electrical, and structural build-out of facilities housing compute, storage, and networking infrastructure, typically requiring power densities exceeding 30 kW per rack and precision cooling to within one degree Celsius. These facilities serve as critical nodes in transatlantic data traffic routes, with Ireland's subsea cable landing points creating geographic advantage for latency-sensitive applications. Cooling Systems and Power Supply segments command the deepest margin pools, as thermal management and electrical resilience represent the largest capital allocations in Irish builds. Modular construction is gaining fastest traction among colocation operators seeking phased capacity deployment against constrained Dublin power quotas.
Ireland's planning authority An Bord Pleanála, the Commission for Regulation of Utilities, and EU taxonomy alignment requirements under the CSRD collectively shape project viability, site selection, and energy sourcing commitments. The CRU's grid connection queue management directly determines which projects advance, creating a regulatory bottleneck that filters developer capability. Stakeholders must monitor whether Ireland's forthcoming data center policy refresh will impose carbon intensity caps that reallocate development toward regional clusters outside Dublin.
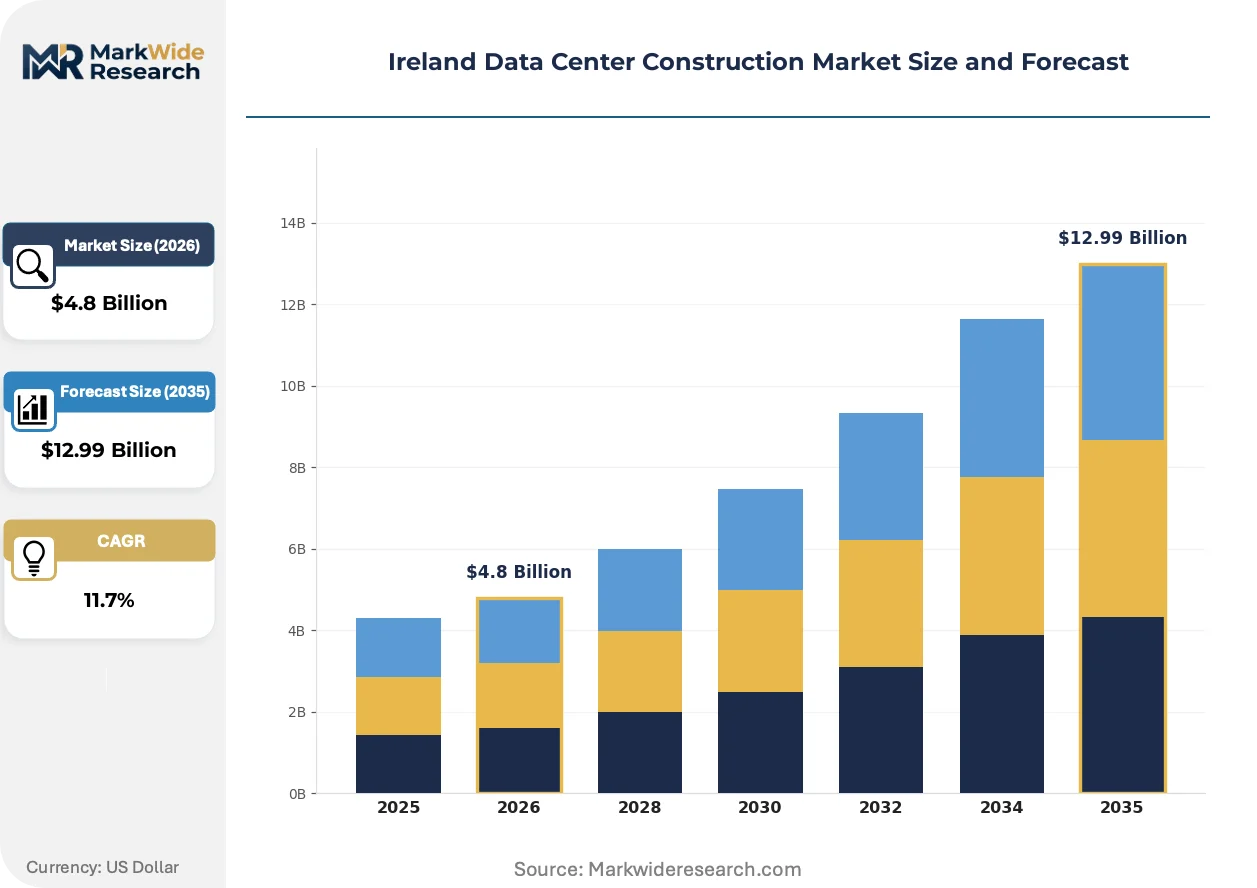
Market Dynamics
Hyperscale cloud operators are compressing traditional enterprise-led construction timelines across Ireland, with An Bord Pleanála's streamlined planning process for strategic infrastructure projects accelerating site-to-operation cycles for qualified developers.
Growth Catalysts
- CSRD alignment mandates:Corporate Sustainability Reporting Directive requirements are compelling data center operators to source renewable power and document carbon intensity, driving demand for sustainable construction practices in Irish facilities.
- Subsea cable landing concentration:Ireland's position as a termination point for transatlantic fiber routes creates geographic advantage for latency-sensitive financial services and cloud workloads requiring sub-10ms connectivity to North America.
- Liquid cooling adoption:Rack densities exceeding 50 kW in AI training clusters are rendering air-cooled designs obsolete, creating retrofit and greenfield opportunities for thermal engineering specialists across Greater Dublin.
Market Restraints
- Grid connection queue bottlenecks:The Commission for Regulation of Utilities manages interconnection requests through a capacity-constrained allocation process that delays project energization by 24-36 months for non-priority developments.
- Specialized labor scarcity:Ireland's pool of certified high-voltage electricians and precision cooling technicians remains insufficient to support simultaneous construction of multiple hyperscale campuses.
- Land banking concentration:Viable Dublin periphery sites with adequate power substation proximity are controlled by a limited number of property developers, inflating site acquisition premiums.
Strategic Opportunities
- Regional cluster development:Cork and Limerick offer untapped grid capacity and local authority planning frameworks that could absorb overflow demand from Dublin's constrained development pipeline.
- Modular prefabrication integration:Factory-built electrical rooms and cooling plants are compressing on-site construction schedules, enabling phased deployment against CRU power allocation tranches.
- Waste heat recovery commercialization:District heating network partnerships with Irish municipal authorities create secondary revenue streams that improve project returns for campus operators.
Industry Challenges
- Commissioning timeline compression:Hyperscale tenant requirements for 12-month delivery cycles strain traditional construction sequencing, demanding overlapping mechanical and electrical workstreams that elevate safety and quality risks.
- Supply chain reconfiguration friction:EU-origin switchgear and cooling equipment procurement faces extended lead times post-Brexit, forcing developers to qualify alternative component suppliers mid-project.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ireland Data Center Construction Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Cloud Providers, Colocation Operators, Enterprises, Government Technology: Cooling Systems, Power Supply, Racking Systems, Security Solutions Construction Type: New Build, Expansion, Retrofit, Modular Service Type: Design, Construction, Consulting, Project Management |
| Companies Covered | Mercury Engineering, Jacobs Engineering Group, Arup, AECOM Ireland Ltd, Turner & Townsend, BAM Ireland, Collen Construction, Mace Group, Kirby Group Engineering, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ireland Data Center Construction Market Trends and Innovations
Direct liquid cooling systems are displacing conventional air-handling architectures across Irish hyperscale projects, driven by thermal loads from GPU-intensive AI infrastructure that exceed air-cooling practical limits.
Immersion cooling using dielectric fluids is displacing chilled water systems in high-density compute halls. Microsoft and Amazon Web Services are piloting two-phase immersion designs in Dublin-adjacent facilities. This displacement is compressing mechanical plant footprints by 40 percent while enabling rack densities previously unattainable in Irish climate conditions.
An Bord Pleanála's revised strategic infrastructure guidelines compress planning determination timelines from 18 weeks to 8 weeks for qualifying data center projects. This regulatory acceleration favors developers with established track records and pre-submitted environmental impact assessments. Colocation operators with pipeline visibility are front-loading site preparation to exploit this procedural advantage.
Enterprise buyers are consolidating procurement authority into centralized real estate and infrastructure teams, displacing distributed IT-led facility decisions. This concentration shifts vendor relationships toward master service agreements with national contractors capable of multi-site delivery. Financial services verticals in Dublin's IFSC district exhibit the most pronounced procurement centralization, favoring turnkey EPC contracts over traditional design-bid-build structures.
Ireland Data Center Construction Market Segmentation
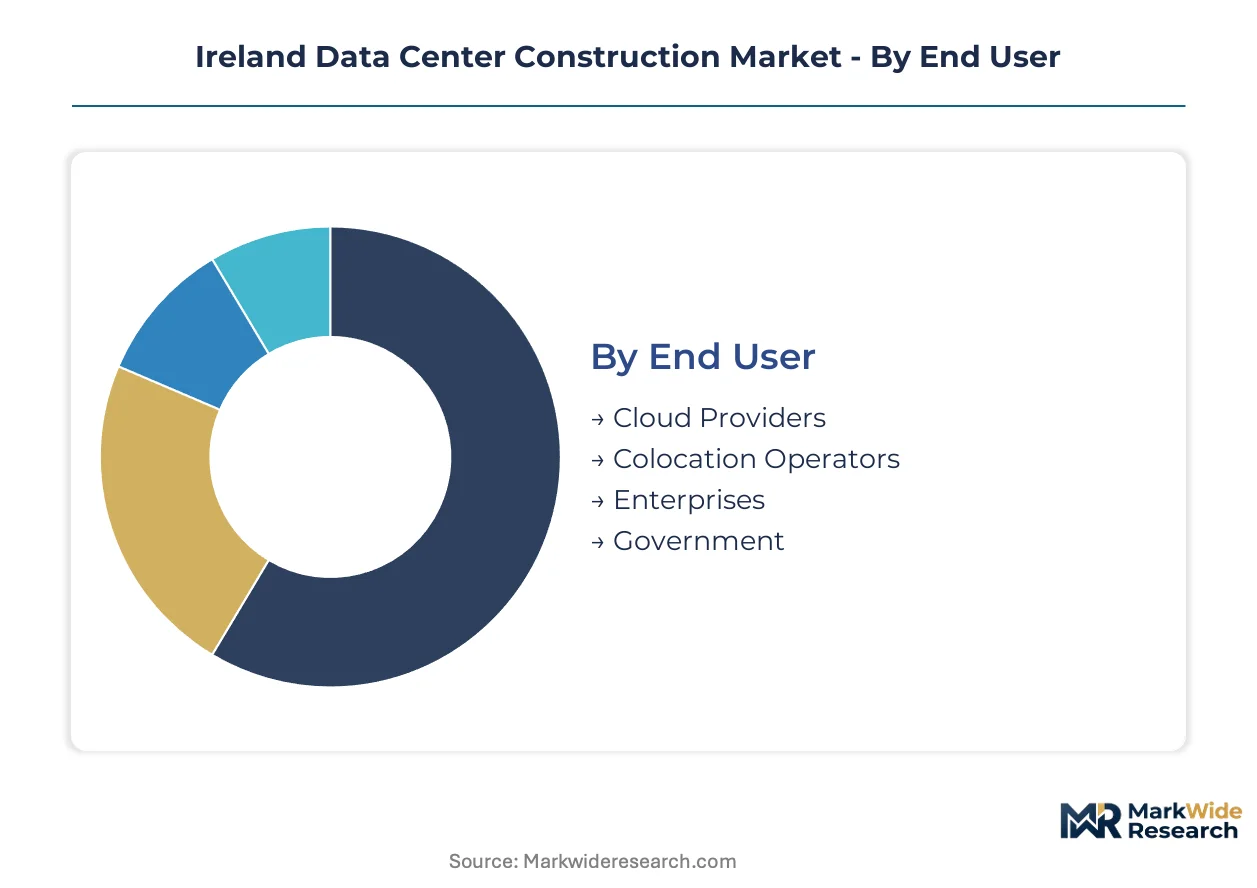
Segmentation reveals how capital allocation patterns diverge across Ireland's data center construction value chain. Cloud provider procurement centralization and hyperscale power density requirements are reshaping which construction segments capture margin concentration.
End User:
Margin pools concentrate most heavily with cloud providers, whose campus-scale commitments command premium engineering capabilities and accelerated delivery timelines.
- Cloud Providers:Hyperscale operators demand facilities exceeding 30 MW per campus with power densities above 50 kW per rack. Their procurement concentrates in Greater Dublin Area sites with subsea cable proximity, though An Bord Pleanála's streamlined approvals are compressing site-to-operation cycles for qualified developers.
- Colocation Operators:These providers pursue phased capacity deployment against constrained Dublin power quotas, favoring modular construction methods that align with CRU grid connection tranches. Their builds emphasize multi-tenant flexibility and rapid reconfiguration capacity.
- Enterprises:Financial services firms in Dublin's IFSC district drive demand for latency-sensitive facilities with sub-10ms transatlantic connectivity.
- Government:Public sector projects prioritize sovereign data residency requirements and EU Green Deal alignment in site selection criteria.
The dominant share belongs to Cloud Providers, while Colocation Operators is closing the gap fastest.
Technology:
Cooling and power infrastructure command the deepest margin pools, representing the largest capital allocations in Irish hyperscale builds.
- Cooling Systems:Direct liquid cooling and immersion designs using dielectric fluids are displacing conventional air-handling architectures. GPU-intensive AI training clusters exceeding 50 kW per rack render air-cooled designs obsolete across Greater Dublin facilities.
- Power Supply:High-voltage electrical infrastructure and uninterruptible power systems represent critical path items with extended procurement lead times. The CRU's grid connection queue management filters which projects advance based on substation proximity and capacity allocation.
- Racking Systems:Hot-aisle containment and intelligent power distribution units support density optimization in constrained floorplates.
- Security Solutions:Multi-layered physical and cyber protection frameworks address CSRD documentation requirements and financial services regulatory expectations.
Cooling Systems holds the dominant position, though Power Supply is expanding most quickly as grid interconnection bottlenecks elevate electrical resilience premiums.
Construction Type:
New build activity captures the largest revenue concentration, though modular methods are gaining traction among operators seeking deployment flexibility.
- New Build:Greenfield campus developments in Dublin periphery locations require comprehensive civil, mechanical, and electrical infrastructure with precision environmental controls. Land banking concentration among limited property developers inflates site acquisition premiums for viable substation-adjacent parcels.
- Modular:Factory-built electrical rooms and cooling plants compress on-site construction schedules, enabling phased deployment against CRU power allocation tranches. Colocation operators particularly favor this approach for capacity-matching demand curves.
- Expansion:Existing campus augmentation leverages established grid connections and operational infrastructure.
- Retrofit:Legacy facility upgrades address liquid cooling conversion requirements for AI workload accommodation.
New Build maintains the dominant share, while Modular is climbing the fastest as planning and power constraints favor phased deployment strategies.
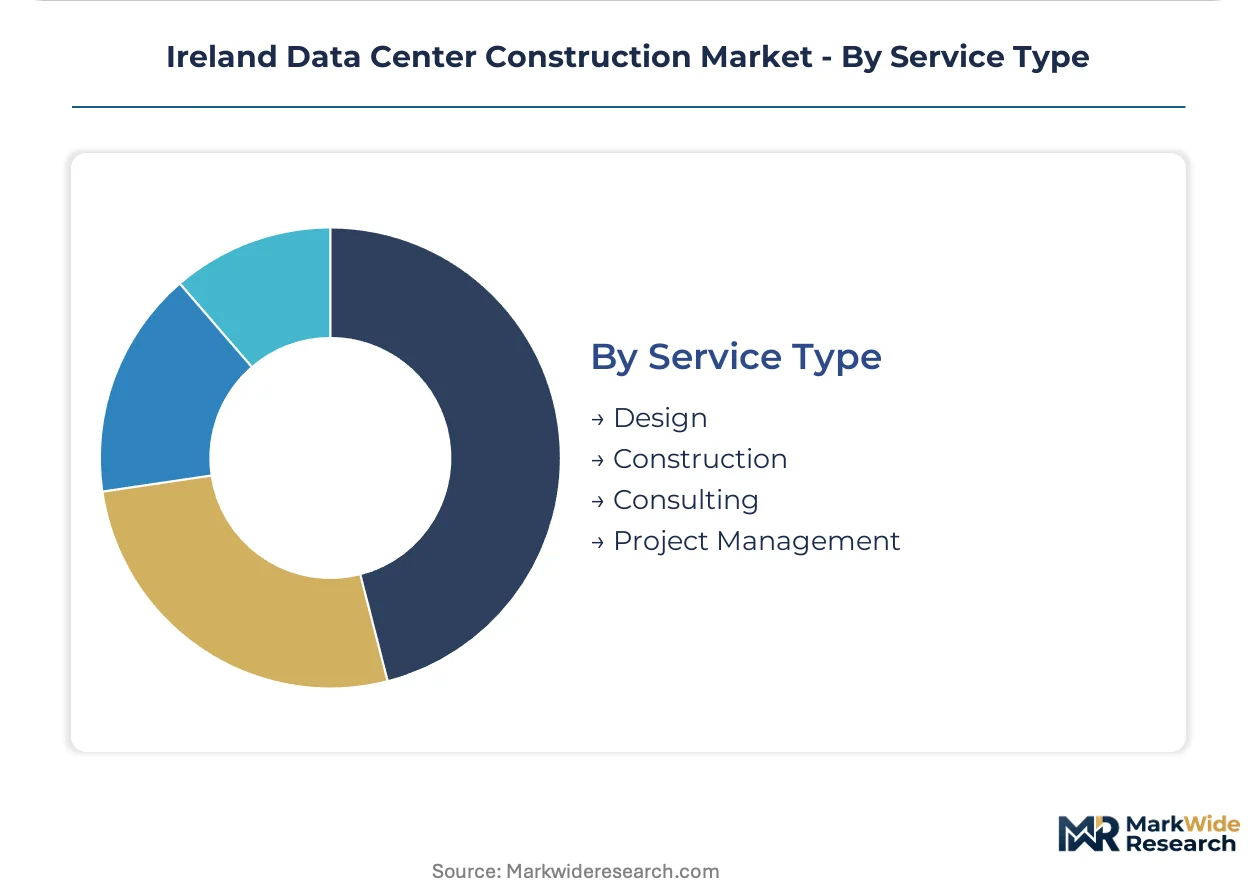
Service Type:
Construction execution commands premium pricing relative to advisory services, particularly for turnkey EPC contracts with hyperscale cloud operators.
- Construction:Turnkey delivery encompassing civil works, MEP installation, and commissioning dominates procurement patterns. Mercury Engineering and similar national contractors capture multi-site master service agreements through demonstrated hyperscale delivery capability.
- Design:Engineering design capacity tied to high-density power requirements anchors competitive positioning, with sustainable design consulting addressing Ireland's CSRD obligations.
- Consulting:Site selection and regulatory navigation services support An Bord Pleanála pre-application preparation.
- Project Management:Overlapping mechanical and electrical workstream coordination addresses compressed 12-month hyperscale delivery cycles.
Construction holds the dominant position, while Design is gaining share fastest as power density and sustainability requirements elevate engineering complexity premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud buyers concentrate procurement authority within Ireland's Greater Dublin Area, where land scarcity and power constraints intensify site competition. Colocation operators and financial services enterprises drive secondary demand clusters across regional cities. An Bord Pleanála's streamlined approvals favor developers with established environmental documentation.
Greater Dublin Area
Hyperscale cloud operators and financial services firms dominate demand for latency-sensitive facilities with sub-10ms transatlantic connectivity. An Bord Pleanála's revised strategic infrastructure guidelines compress planning determination timelines from 18 weeks to 8 weeks for qualifying projects. Tallaght and Clonee host active campus developments where Mercury Engineering and Jacobs Engineering Group execute turnkey delivery contracts.
Cork
Untapped grid capacity and local authority planning frameworks position Cork as an overflow destination for Dublin-constrained development. The Commission for Regulation of Utilities manages interconnection requests through capacity-constrained allocation processes that filter project advancement. Little Island and Cork Docklands attract initial hyperscale site investigations from operators seeking alternatives to Dublin's land banking concentration.
Limerick
Shannon Free Zone adjacent land parcels offer viable substation proximity with reduced acquisition premiums versus Dublin periphery sites. EirGrid's western transmission reinforcement programs determine which developments secure priority grid connection queue positions. Castletroy and Raheen industrial zones host preliminary colocation operator assessments for phased capacity deployment.
Galway
Medtech and pharmaceutical enterprise demand creates specialized data residency requirements aligned with EU Green Deal obligations. The country's national planning authority evaluates strategic infrastructure applications against regional development objectives. Oranmore and Ballybrit business parks concentrate initial facility inquiries from operators targeting western Ireland connectivity.
Ireland Data Center Construction Market Competitive Landscape
Player mix skews toward national contractors with demonstrated hyperscale delivery capability, creating a tiered structure where electrical and mechanical specialists command premium positioning. Engineering consultancies anchor design-phase competition through sustainable design credentials and high-density power expertise. Consolidation pressure operates through multi-site master service agreements that favor contractors with established An Bord Pleanála track records. Dominant competitive moves include turnkey EPC contract capture and modular construction capability integration.
Among Ireland-based contractors, Mercury Engineering occupies a position exemplifying electrical and mechanical turnkey specialization for campus-scale developments. Jacobs Engineering Group and Arup represent the engineering consultancy archetype, with the former anchoring design capacity tied to hyperscale density requirements and the latter exemplifying sustainable design consulting that addresses CSRD obligations. These three names illustrate how capability concentration across construction execution and advisory services defines competitive positioning.
| Leading Market Players |
|---|
| Mercury Engineering |
| Jacobs Engineering Group |
| Arup |
| AECOM Ireland Ltd |
| Turner & Townsend |
| BAM Ireland |
| Collen Construction |
| Mace Group |
| Kirby Group Engineering |
| Others |
Pricing and Supply Chain Analysis
Turnkey EPC contracts with fixed-price escalation clauses lock in both supply access and cost visibility for hyperscale operators committing to multi-year campus developments across Ireland. These structures transfer commodity volatility risk to contractors while securing priority allocation for electrical switchgear and precision cooling equipment with extended procurement lead times.
Pricing Analysis
Cost-plus contracts with steel and copper indexation dominate mechanical and electrical work packages across Irish data center builds. Price differentiation rests on contractor track record with An Bord Pleanála approvals and demonstrated hyperscale delivery capability. Cost compression in standard electrical installation packages is intensifying because EU-origin switchgear procurement faces extended lead times post-Brexit. Cloud providers exhibit the least price sensitivity, prioritizing schedule certainty over unit cost optimization, while regional colocation operators remain most responsive to capital expenditure variations.
Supply Chain Analysis
Germany and the Netherlands anchor precision cooling equipment fabrication for Irish hyperscale projects, while China dominates switchgear and cable assembly production. Factory-built electrical rooms and cooling modules draw from specialized manufacturing clusters in Denmark and Sweden. Single-source vulnerability concentrates in high-voltage transformer supply, where European foundry capacity constraints create allocation bottlenecks. Distribution runs through Dublin-based logistics hubs with just-in-time sequencing to active construction sites across Greater Dublin Area, Cork, and Limerick.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hyperscale cloud procurement centralization, compressing vendor margins and favoring contractors with demonstrated multi-site delivery capability. This consolidation fragments opportunities for smaller specialists unable to meet accelerated commissioning timelines.
For Market Incumbents: Secure multi-year master service agreements with cloud providers before regional competitors qualify for An Bord Pleanála's streamlined approval pathway. Deepen modular construction capabilities to address phased deployment demand against CRU power allocation tranches. Vertical integration into factory-built electrical room production defends margin position from specialist fabricators entering the Irish market. For New Entrants and Emerging Players: Lead with liquid cooling engineering specialization targeting AI training cluster retrofits in legacy Dublin facilities, where incumbent contractors lack thermal management expertise. Cork and Limerick offer the most penetrable geography given untapped grid capacity and reduced land banking concentration. Position through CRU grid connection queue navigation consulting to establish regulatory relationships before competing on construction execution. For Investors and Strategic Acquirers: Capital is best deployed toward electrical and mechanical specialists with established An Bord Pleanála track records and hyperscale commissioning experience. Long-term viability hinges on Ireland's forthcoming data center policy refresh and potential carbon intensity caps that would reallocate development toward regional clusters. Monitor EirGrid's western transmission reinforcement programs as the signal indicating which regional markets secure priority interconnection capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Prefabrication Integration | Factory-built electrical rooms compress on-site schedules against CRU power allocation tranches. |
| Liquid Cooling Capability Buildout | Direct liquid cooling engineering addresses GPU-intensive AI training cluster thermal loads exceeding air-cooling limits. |
| Regional Cluster Development | Cork and Limerick site qualification captures overflow demand from Dublin's constrained development pipeline. |
| Waste Heat Recovery Partnership | District heating network agreements with Irish municipal authorities create secondary revenue streams for campus operators. |
| CSRD Alignment Certification | Sustainable design consulting capabilities address corporate sustainability reporting obligations under EU taxonomy requirements. |
Research Methodology
The analysis maps electrical infrastructure, mechanical systems, civil works, and sustainable design consulting, each validated through EPC contractor executives, hyperscale cloud procurement officers, CRU regulatory affairs leads, and An Bord Pleanála planning consultants. Secondary validation draws from EirGrid transmission development statements, CRU grid connection queue publications, EU CSRD regulatory texts, and Irish construction industry tender databases. Bottom-up project pipeline assessment triangulates against top-down capital expenditure aggregation across cloud provider disclosures.
Consistency checks validated volume and value outputs against hyperscaler facility commitment announcements and national contractor order book disclosures. Segmentation modeling spans end user archetype, technology category, construction type, and service delivery model across the projection horizon. CAGRs derive from facility deployment pacing tied to CRU grid connection allocation schedules and An Bord Pleanála approval velocity. Forecast inputs incorporate power density evolution assumptions and modular construction adoption curves specific to Irish regulatory constraints.
The analysis sits within stated boundaries; outcomes outside sustained cloud provider demand commitment or significant EirGrid transmission reinforcement acceleration would require recalibration. Forecasts reflect assumptions regarding CRU queue management continuity and CSRD implementation timelines without material regulatory reversal. Recalibration cycles align with material shifts in hyperscale capital allocation patterns and Irish national data center policy formulation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Precast Construction Market
Building Construction
Modular and Portable Building Market
Building Construction
Asia Pacific Modular Construction Market
Building Construction
Russia Prefabricated Buildings Market
Building Construction
Malaysia Construction Market
Building Construction
Vertical Garden Construction Market
Building Construction
Saudi Arabia Transportation Infrastructure Construction Market
Building Construction
Oman Construction Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
GCC Advanced Buildings Materials Market
Building Construction
Kuwait Construction Market
Building Construction
Modular and Prefabricated Construction Market
Building Construction
Cold Storage Construction Market
Building Construction
UAE Construction Market
Building Construction
El Salvador Construction Market
Building Construction
China Building Construction Market