
 El Salvador Construction Market | 2026-2036
El Salvador Construction Market Size, Share, and Industry Trends Forecast 2026-2036
El Salvador Construction Market Insights
The El Salvador construction sector is pivoting away from uniform project portfolios as premium mixed-use developments and commodity-grade social housing diverge in specification, financing, and contractor capability. Salazar Romero S.A. de C.V. anchors the premium tier through in-house engineering capacity and vertical control over critical project phases. Inversiones Roble S.A. de C.V. competes across both tiers, leveraging its diversified real estate portfolio to sustain throughput during public procurement cycles. COPRESA dominates infrastructure rehabilitation, where FOVIAL contract concentration rewards firms with established government relationships and heavy equipment fleets.
Construction in El Salvador encompasses the assembly of structures using cement, steel, wood, and glass through processes ranging from cast-in-place concrete forming to prefabricated panel installation, serving residential shelter, commercial activity, industrial production, and public infrastructure. Residential construction leads by project volume, though infrastructure captures disproportionate capital flow through sovereign-backed financing. Mega projects remain sparse, concentrating margin pools in medium-scale commercial and industrial builds where Grupo Q Infraestructura and American Industrial Park S.A. de C.V. have established specialized delivery capabilities. Material type segmentation shows cement and steel commanding procurement budgets, with imported steel subject to tariff volatility that shapes contractor hedging behavior.
El Salvador's construction market operates under the national building code enforced by municipal planning departments, with environmental impact assessments overseen by the Ministry of Environment and Natural Resources (MARN) and labor safety standards set by the Ministry of Labor. The Central American Uniform Building Code harmonization initiative shapes cross-border contractor mobility and material certification requirements. Stakeholders must monitor whether fiscal space for FOVIAL and other public works agencies tightens under debt sustainability pressures, as this would shift contract availability toward private developers and reshape competitive positioning across the contractor base.
Market Dynamics
FOVIAL's road rehabilitation program channels sovereign financing toward heavy civil works, concentrating demand in firms with established government relationships and equipment fleets while squeezing smaller contractors from public procurement cycles.
Growth Catalysts
- FOVIAL Infrastructure Mandate:The national road rehabilitation initiative sustains cement and steel consumption through multi-year sovereign-backed contracts. Public investment flows disproportionately toward bridge reconstruction and highway expansion corridors.
- San Salvador Metropolitan Densification:Urban population concentration in the capital corridor accelerates mixed-use vertical development. Logistics hub construction reshapes peripheral zones as distribution centers anchor new commercial submarkets.
- Prefabricated Panel Systems:Modular construction methods compress project timelines for social housing developments. Standardized wall and floor components reduce on-site labor dependency while improving quality consistency.
Market Restraints
- Imported Steel Tariff Volatility:Discretionary tariff adjustments on foreign steel shipments create procurement budget uncertainty. Contractors hedge through forward purchasing, tying up working capital in inventory buffers.
- Municipal Permitting Fragmentation:Building code enforcement varies across San Salvador satellite municipalities. Inconsistent approval timelines extend pre-construction phases and compress viable project windows.
- Cement Supply Concentration:Domestic clinker production capacity limits constrain regional distribution flexibility. Price-setting power concentrates in integrated producers with captive limestone reserves.
Strategic Opportunities
- La Libertad Coastal Tourism Corridor:Underdeveloped Pacific coastline zones present resort and hospitality construction white space. Foreign direct investment incentives target hospitality infrastructure through tax abatement structures.
- Green Building Certification Uptake:EDGE certification adoption in commercial developments opens premium pricing for energy-efficient designs. International tenant requirements drive specification upgrades in Class A office stock.
- Digital Project Management Platforms:Cloud-based scheduling and cost control tools penetrate mid-tier contractor operations. Real-time collaboration software reduces rework rates and accelerates payment cycle documentation.
Industry Challenges
- Skilled Equipment Operator Scarcity:Heavy machinery certification programs fail to match FOVIAL project ramp rates. Experienced crane and earthmoving operators command wage premiums that erode bid competitiveness.
- Legacy Subcontractor Coordination:Fragmented specialty trade networks complicate integrated project delivery. Electrical and mechanical contractors operate on incompatible scheduling systems, generating interface conflicts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | El Salvador Construction Market |
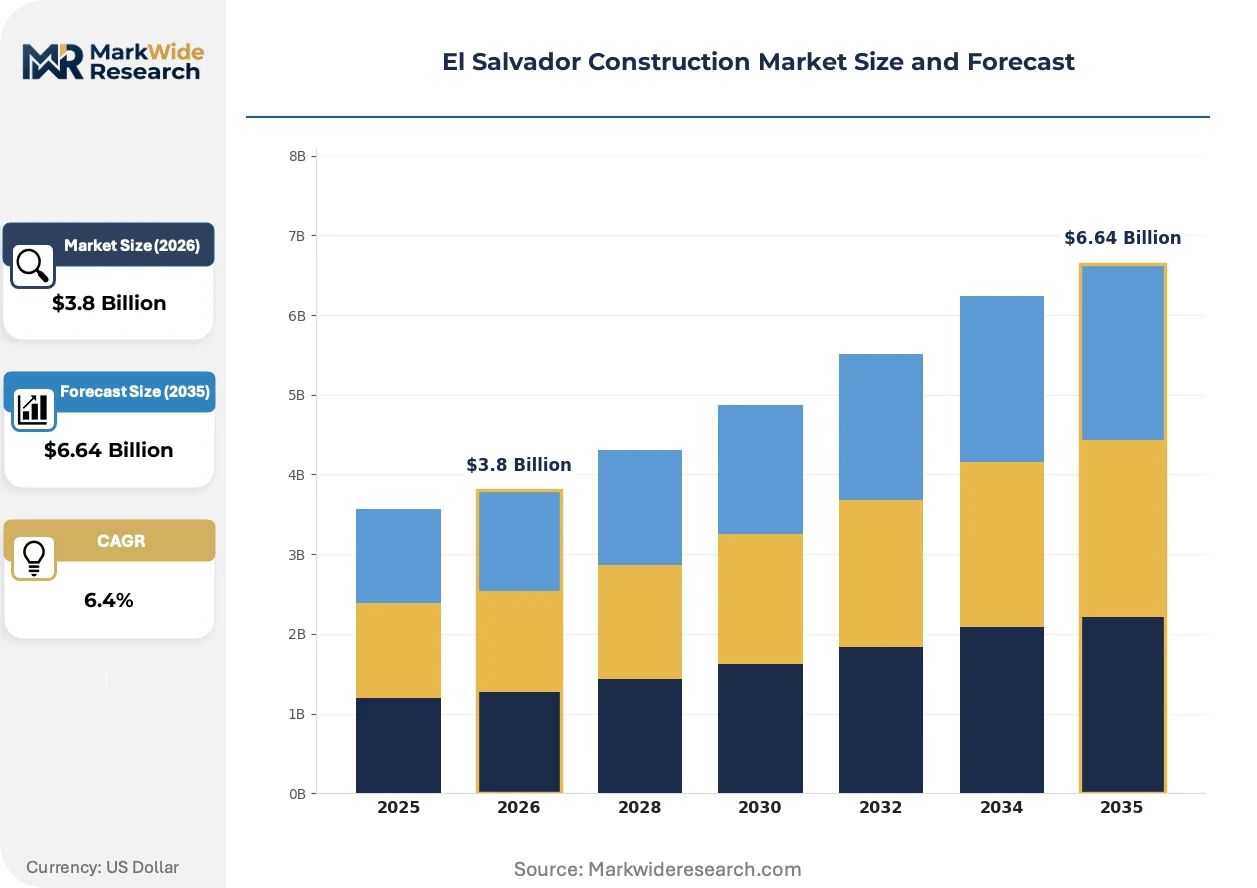
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Construction Type: Residential, Commercial, Industrial, Infrastructure Material Type: Cement, Steel, Wood, Glass Project Size: Small, Medium, Large, Mega End User: Developers, Contractors, Government, Private Clients |
| Companies Covered | Salazar Romero S.A. de C.V., Inversiones Roble S.A. de C.V., Construcciones Nabla S.A. de C.V., COPRESA, Agrisal Grupo, Grupo Q Infraestructura, American Industrial Park S.A. de C.V., Funter, Fovial, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
El Salvador Construction Market Trends and Innovations
Construction methodology in El Salvador is bifurcating between capital-intensive industrialized systems for premium developments and labor-retentive traditional methods for volume housing, with regulatory pressure and financing access determining which path projects follow.
Building Information Modeling software is penetrating medium-scale commercial projects as developers seek clash detection and quantity takeoff precision. Engineering firms serving the San Salvador corporate market adopt 3D coordination platforms to reduce field change orders. BIM-enabled preconstruction planning is converging with modular fabrication workflows, compressing traditional design-bid-build sequences into integrated delivery models.
The Ministry of Environment and Natural Resources enforces environmental impact assessments through MARN's revised screening protocols. Stricter watershed protection requirements extend review timelines for projects near sensitive hydrological zones. Developers in the Acelhuate River basin face expanded mitigation obligations, redirecting investment toward already-entitled parcels with cleared regulatory status.
Buyer concentration among institutional real estate investors reshapes contractor selection criteria. Pension fund and insurance-backed developers impose standardized reporting and safety metrics that disqualify traditional family-owned construction firms. Procurement through pre-qualified vendor lists consolidates award volume with established players holding ISO 45001 occupational health certifications and audited financial statements.
El Salvador Construction Market Segmentation
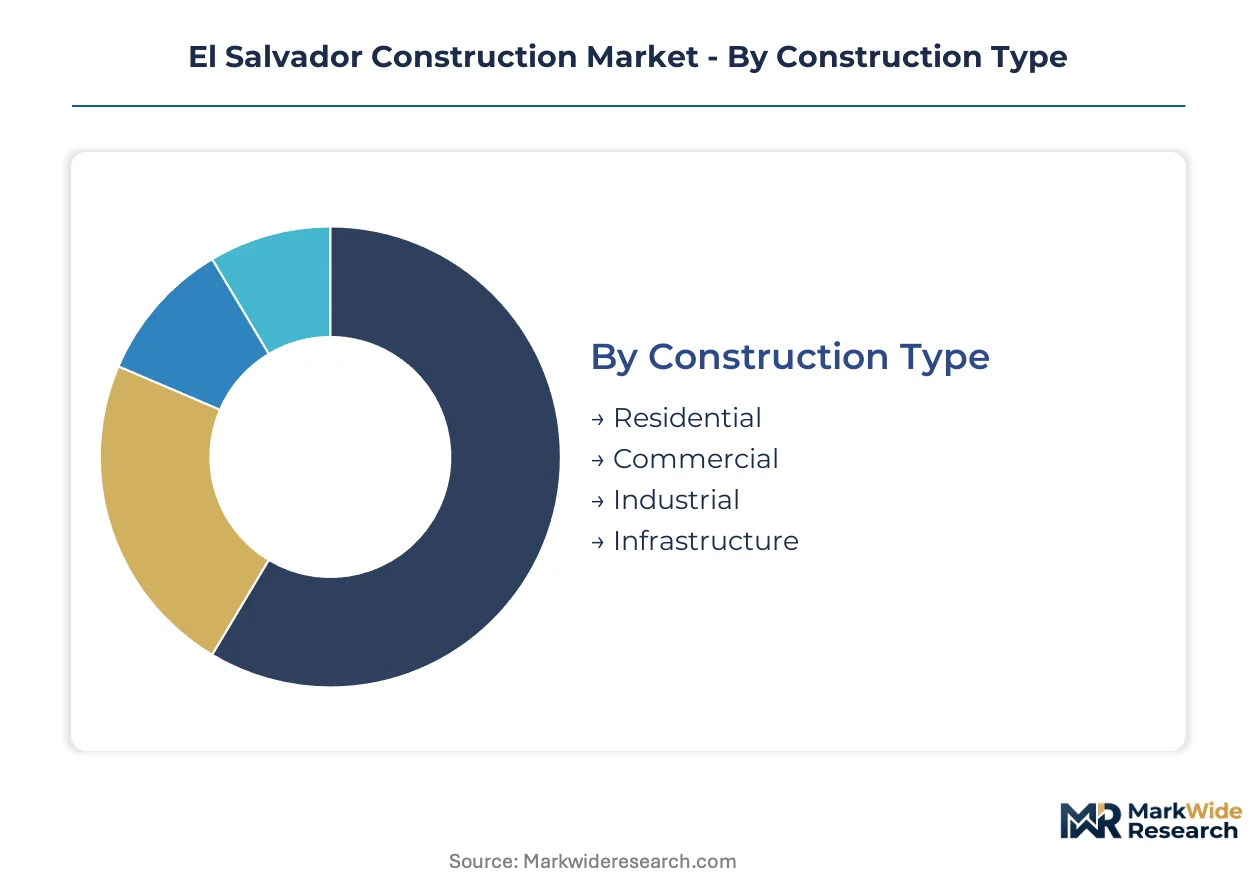
Construction activity in El Salvador fragments across project scale, material procurement, and client sophistication. Each segmentation axis reveals distinct capability requirements and margin structures that reshape contractor specialization.
Construction Type:
Technical specifications and delivery methodologies diverge sharply across building purpose, with seismic resistance standards and occupancy loads driving engineering complexity.
- Residential:Cast-in-place concrete dominates structural systems for single-family and multi-family housing. San Salvador's metropolitan corridor concentrates demand as urban densification accelerates vertical development and social housing programs expand.
- Commercial:Mixed-use developments integrate retail podium with office towers, requiring MEP coordination across variable occupancy schedules. Class A office stock in the capital drives specification upgrades as institutional investors impose international building certification requirements.
- Industrial:Warehouse and manufacturing facilities prioritize clear-span structural systems and heavy floor load ratings.
- Infrastructure:FOVIAL road rehabilitation and bridge reconstruction command sovereign-backed capital flows with multi-year procurement cycles.
Mature deployment sits with Residential volume construction. Newer deployment is concentrated in Commercial mixed-use vertical projects.
Material Type:
Procurement budgets concentrate in bulk commodities subject to import dependency and domestic production constraints, with price volatility shaping contractor hedging behavior.
- Cement:Domestic clinker production anchors supply, though regional distribution bottlenecks limit flexibility. Integrated producers with captive limestone reserves in San Vicente and La Libertad control price-setting.
- Steel:Rebar and structural sections face tariff-adjusted import pricing from regional mills. Forward purchasing ties working capital in inventory buffers as discretionary duties create procurement uncertainty.
- Wood:Framing lumber serves residential finishing and formwork applications, sourced from Central American suppliers.
- Glass:Curtain wall and fenestration systems rely on imported processed glass, with specification grades separating premium commercial from commodity residential applications.
Steel commands the steepest expansion trajectory as infrastructure rehabilitation accelerates rebar consumption. Wood maintains stable share in residential finishing.
Project Size:
Capital intensity and contractor qualification thresholds scale non-linearly with project magnitude, consolidating award volume among tiered capability classes.
- Small:Single-family housing and minor renovations operate through fragmented contractor networks with minimal bonding requirements.
- Medium:Commercial and industrial builds concentrate margin pools where specialized delivery capabilities differentiate bidders. Grupo Q Infraestructura and American Industrial Park S.A. de C.V. dominate this tier through pre-qualified vendor status.
- Large:Multi-phase developments and public works demand audited financials and ISO 45001 certification, disqualifying traditional family-owned firms.
- Mega:Projects exceed $100 million thresholds rarely, with contract concentration in FOVIAL highway corridors and potential coastal tourism infrastructure.
Medium-scale deployment captures disproportionate contractor investment. Large-project capability is expanding fastest as institutional procurement standards tighten.
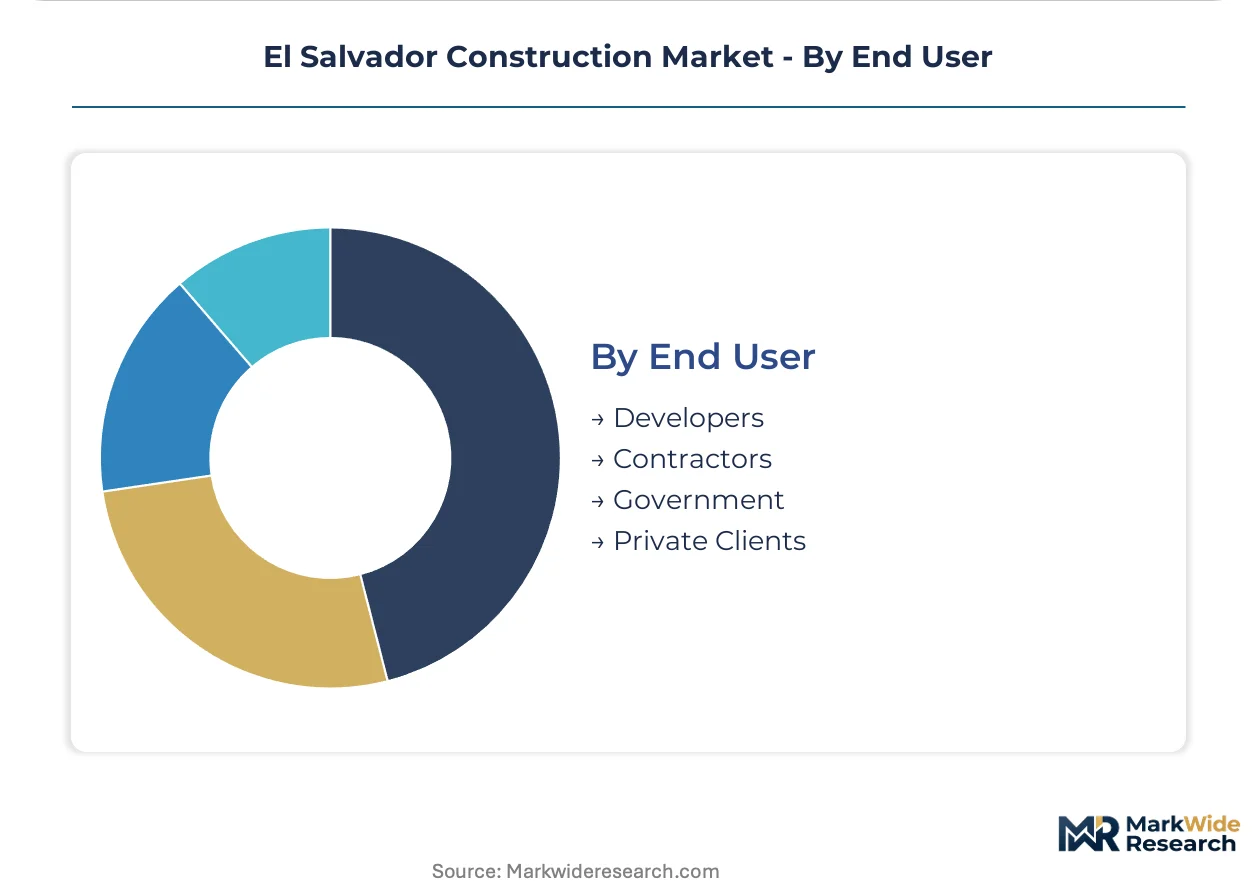
End User:
Client sophistication determines payment security, specification authority, and project delivery model selection across the construction value chain.
- Developers:Pension fund and insurance-backed real estate investors impose standardized reporting metrics and safety certifications that reshape contractor selection.
- Contractors:General contractors serving as project aggregators concentrate subcontractor coordination risk, with electrical and mechanical trade fragmentation generating interface conflicts.
- Government:FOVIAL and municipal agencies channel public investment through established relationship networks, squeezing smaller contractors from procurement cycles.
- Private Clients:Individual and corporate direct-hire projects vary widely in documentation rigor, with informal contracting prevalent in residential alterations.
Government procurement anchors established contractor revenue. Developer-driven projects are gaining share fastest as institutional capital deepens market participation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Salvador anchors construction demand through its metropolitan corridor, where urban densification and logistics hub development concentrate project activity across the capital region.
San Salvador Metropolitan Area
Vertical mixed-use developments and social housing programs drive cement consumption in the capital corridor. Municipal planning departments enforce the national building code with varying approval timelines across satellite municipalities. The San Salvador-Ilopango-Soyapango triangle concentrates Class A office construction as institutional investors impose international certification requirements.
La Libertad Department
Coastal tourism infrastructure and hospitality construction present underdeveloped Pacific corridor opportunities. The Ministry of Environment and Natural Resources enforces watershed protection protocols that extend review timelines for projects near sensitive hydrological zones. The La Libertad port zone and surrounding coastline attract resort development targeting foreign direct investment incentives.
San Vicente Department
Captive limestone reserves anchor domestic clinker production capacity for regional cement distribution. Integrated producers control price-setting through vertical control over raw material extraction. The San Vicente industrial corridor supplies construction material feedstock to San Salvador metropolitan demand centers.
Santa Ana Department
Industrial park construction and manufacturing facility builds prioritize clear-span structural systems and heavy floor load ratings. The national road rehabilitation initiative channels FOVIAL investment toward highway expansion corridors connecting western departments to the capital. Santa Ana's logistics positioning supports distribution center development serving regional commercial submarkets.
Ahuachapán and Western Border Zone
Cross-border commercial infrastructure and transportation links to Guatemala drive peripheral construction activity. The Central American Uniform Building Code harmonization initiative shapes contractor mobility and material certification across the frontier. Ahuachapán's position along the CA-1 Pan-American Highway corridor benefits from transit-oriented development pressures.
El Salvador Construction Market Competitive Landscape
Capital-heavy contractors with captive equipment fleets compete with asset-light project aggregators focused on subcontractor coordination and relationship-based procurement. The contractor base fragments across three capability tiers: integrated engineering firms with in-house design capacity, diversified real estate developers sustaining throughput across public and private cycles, and specialized infrastructure rehabilitators concentrating FOVIAL contract flow. Two competitive moves dominate positioning: backward integration into material supply chains and pre-qualification for institutional investor vendor lists through safety certification upgrades.
Within the integrated engineering tier, Salazar Romero S.A. de C.V. exemplifies vertical control over critical project phases. COPRESA anchors the infrastructure rehabilitation segment where government relationship networks concentrate award volume. Inversiones Roble S.A. de C.V. occupies a diversified position across both premium and commodity construction tiers.
| Leading Market Players |
|---|
| Salazar Romero S.A. de C.V. |
| Inversiones Roble S.A. de C.V. |
| Construcciones Nabla S.A. de C.V. |
| COPRESA |
| Agrisal Grupo |
| Grupo Q Infraestructura |
| American Industrial Park S.A. de C.V. |
| Funter |
| Fovial |
| Others |
Pricing and Supply Chain Analysis
MARN watershed protection protocols gate qualified supply for projects near sensitive hydrological zones, limiting eligible contractor pools and sustaining premium-tier pricing for cleared parcels in the Acelhuate River basin. Cement and steel procurement costs concentrate in integrated producers with captive limestone reserves, while tariff-adjusted steel imports compress margins for contractors without forward purchasing capacity.
Pricing Analysis
FOVIAL contract throughput anchors value-based pricing for infrastructure rehabilitation, with sovereign-backed payment security commanding bid premiums over private development work. Price differentiation separates ISO 45001-certified contractors eligible for institutional procurement from uncertified competitors excluded from pre-qualified vendor lists. Cost compression in commodity residential construction intensifies as social housing programs standardize specifications and compress viable margins. Developer-driven Class A office projects show least price sensitivity, absorbing green certification premiums and advanced MEP coordination costs.
Supply Chain Analysis
Domestic-content mandates in public procurement reshape sourcing toward regional clinker production anchored in San Vicente and La Libertad limestone reserves. Raw material dependencies center on imported structural steel from regional mills, domestic cement production, and Central American framing lumber. Supply chain risk concentrates in discretionary tariff exposure on foreign steel shipments, creating procurement budget uncertainty that shapes contractor hedging behavior. Distribution feeds from integrated producer networks through municipal contractor relationships, with FOVIAL contract concentration privileging established equipment fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic clinker production capacity constraints prop pricing power for integrated cement producers, sustaining margin pools despite competitive pressure in downstream construction services.
For Market Incumbents: To counter skilled equipment operator scarcity eroding bid competitiveness, Salazar Romero S.A. de C.V. and COPRESA should deepen in-house certification programs and anchor crane operator training pipelines. Backward integration into captive limestone reserves secures supply cost advantages as regional distribution bottlenecks persist. For New Entrants and Emerging Players: Digital project management platforms present a technology-first wedge for mid-tier contractors seeking pre-qualified vendor status through ISO 45001 certification and audited financial documentation. The La Libertad coastal tourism corridor offers the most penetrable geography, with resort construction white space and foreign direct investment incentives supporting hospitality infrastructure entry. For Investors and Strategic Acquirers: FOVIAL contract award acceleration is the leading indicator that sovereign fiscal space for infrastructure rehabilitation remains intact. Long-term viability favors contractors with diversified exposure across public procurement cycles and private development pipelines. Acquisition targets should demonstrate established government relationship networks and heavy equipment fleet ownership.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Reserves | Captive raw material supply insulates San Vicente producers from regional distribution bottlenecks. |
| ISO 45001 Certification Investment | Occupational health credentials unlock institutional investor pre-qualified vendor list access. |
| Digital Project Management Platform Deployment | Cloud-based scheduling tools reduce rework rates and accelerate payment cycle documentation. |
| Prefabricated Panel System Adoption | Modular construction compresses social housing timelines while reducing on-site labor dependency. |
| La Libertad Coastal Development Partnership | Resort construction joint ventures capture foreign direct investment incentive structures. |
Research Methodology
Trade publications, customs records, and municipal procurement databases formed the secondary backbone, cross-referenced with primary interviews involving FOVIAL program directors, cement plant managers, commercial real estate developers, and heavy equipment fleet operators. Bottom-up project pipeline enumeration triangulated against top-down construction spending flows from sovereign budget disclosures.
Historical trendline analysis tracked cement consumption patterns and steel import volumes across the projection horizon, with segmentation modeling across construction type, material category, project scale tier, and end-user sophistication. CAGRs derived from fitted growth curves adjusted for FOVIAL funding cycle phasing and urban densification trajectory in the San Salvador metropolitan corridor.
Several conditions sit outside the modeled scope, including discretionary tariff rate adjustments, sovereign debt sustainability pressures affecting FOVIAL fiscal space, and seismic event frequency affecting reconstruction demand spikes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Russia Prefabricated Buildings Market
Building Construction
Indonesia Commercial Construction Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
Middle East Data Center Construction Market
Building Construction
Tanzania Construction Market
Building Construction
Energy-Efficient Building Market
Building Construction
Turkey Commercial Construction Market
Building Construction
Prefabricated Construction Market
Building Construction
US Modular Construction Market
Building Construction
Africa Construction Market
Building Construction
Japan Construction Market
Building Construction
Australia Construction Market
Building Construction
China Prefabricated Buildings Market
Building Construction
Precast Construction Market
Building Construction
Dominican Republic Construction Market
Building Construction
Modular and Prefabricated Construction Market