
 Swiss Prefabricated Buildings Market | 2026-2036
Swiss Prefabricated Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Swiss Prefabricated Buildings Market Analytics
Swiss timber-frame producers is broadening factory capacity to meet cantonal housing targets. Prelco SA leverages automated panel manufacturing to serve Western Switzerland's dense urban corridors. Blumer Lehmann Gruppe anchors premium timber-hybrid systems for architecturally demanding commercial clients. Implenia competes through integrated design-build capabilities across major Swiss infrastructure and residential developments.
Prefabricated buildings are structures manufactured off-site in standardized sections or modules, then transported and assembled at final locations, with Swiss producers typically engineering wall panels to U-values below 0.20 W/m²K for Alpine climate compliance. The primary purpose is compressing construction schedules while guaranteeing thermal performance and structural precision under tight Swiss building codes. Modular Homes dominate residential volume as developers seek faster entitlement-to-occupancy timelines in high-cost cantons. Factory-built construction methods capture margin pools through labor efficiency and waste reduction in controlled manufacturing environments. Wood-based materials sustain leadership in Swiss prefabrication due to domestic forestry supply chains and cultural preference for renewable construction inputs.
Swissmedic does not regulate building products, but the Swiss Federal Office for the Environment enforces CO₂ reduction mandates that shape material selection and energy performance thresholds. SIA Swiss engineering standards and cantonal building codes collectively determine product compliance pathways and market access conditions. SEBI does not apply here; rather, KBOB federal procurement guidelines steer public project specifications toward low-carbon prefabricated solutions. Stakeholders must monitor evolving Minergie-P and Minergie-A certification thresholds as these labels increasingly filter bank financing and insurance terms for residential developments.
Market Dynamics
Cantonal housing targets and Minergie certification tightening are compressing traditional construction timelines while elevating factory-precision thermal performance requirements across Swiss metropolitan corridors.
Growth Catalysts
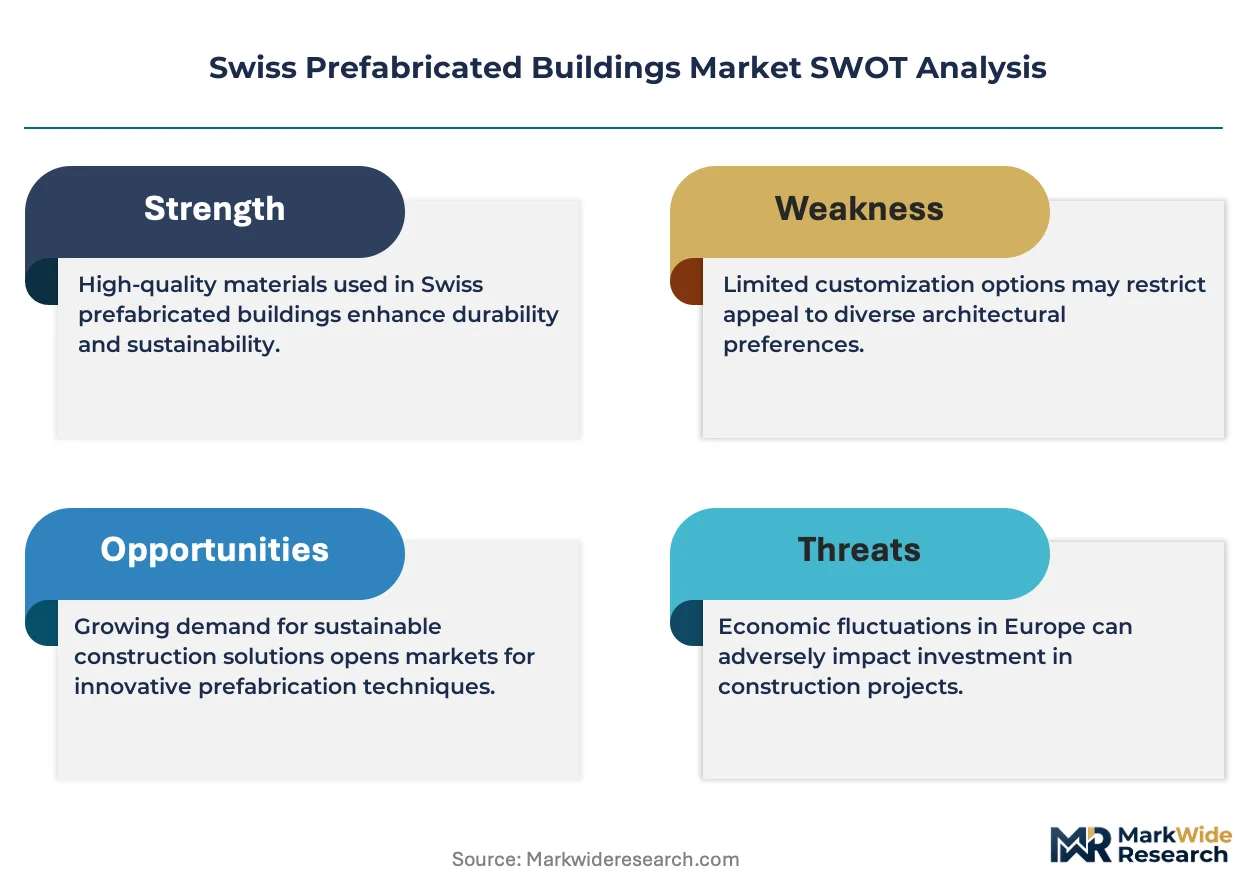
- Minergie-P Certification Thresholds:Swiss cantonal energy codes now mandate U-values below 0.20 W/m²K, pushing developers toward panelized systems that guarantee thermal performance compliance.
- Zurich Metropolitan Corridor Density:Housing shortages in Switzerland's economic engine are accelerating entitlement-to-occupancy timelines that only modular methods can satisfy.
- Cross-Laminated Timber Maturation:Domestic forestry supply chains and automated CNC manufacturing are reducing engineered wood costs while preserving architectural flexibility.
Market Restraints
- Transport Geometry Constraints:Alpine tunnel clearances and cantonal road weight limits restrict module dimensions to 4.0m width, fragmenting factory-to-site logistics.
- Skilled Installation Bottleneck:Swiss crane operators and module connection specialists command premium wages that erode manufacturing labor savings.
- Concrete Foundation Dependency:Swiss seismic codes require in-situ concrete basements, preventing full off-site completion and preserving weather-sensitive critical path elements.
Strategic Opportunities
- Ticino Cross-Border Production:Italian-speaking southern cantons offer access to Lombardy manufacturing capacity with favorable labor cost differentials.
- Deep Energy Retrofit Integration:Minergie-A certification for existing building envelopes creates demand for factory-produced facade replacement systems.
- KBOB Federal Procurement Alignment:Public sector construction mandates now prioritize embodied carbon metrics, favoring timber-hybrid prefabrication over conventional steel.
Industry Challenges
- Digital Twin Implementation Gap:Few Swiss general contractors possess BIM-to-factory data pipelines, forcing manual translation errors between design and CNC programming.
- Cantonal Code Fragmentation:Twenty-six distinct building authorities maintain non-harmonized approval timelines, complicating national rollout of standardized module designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swiss Prefabricated Buildings Market |
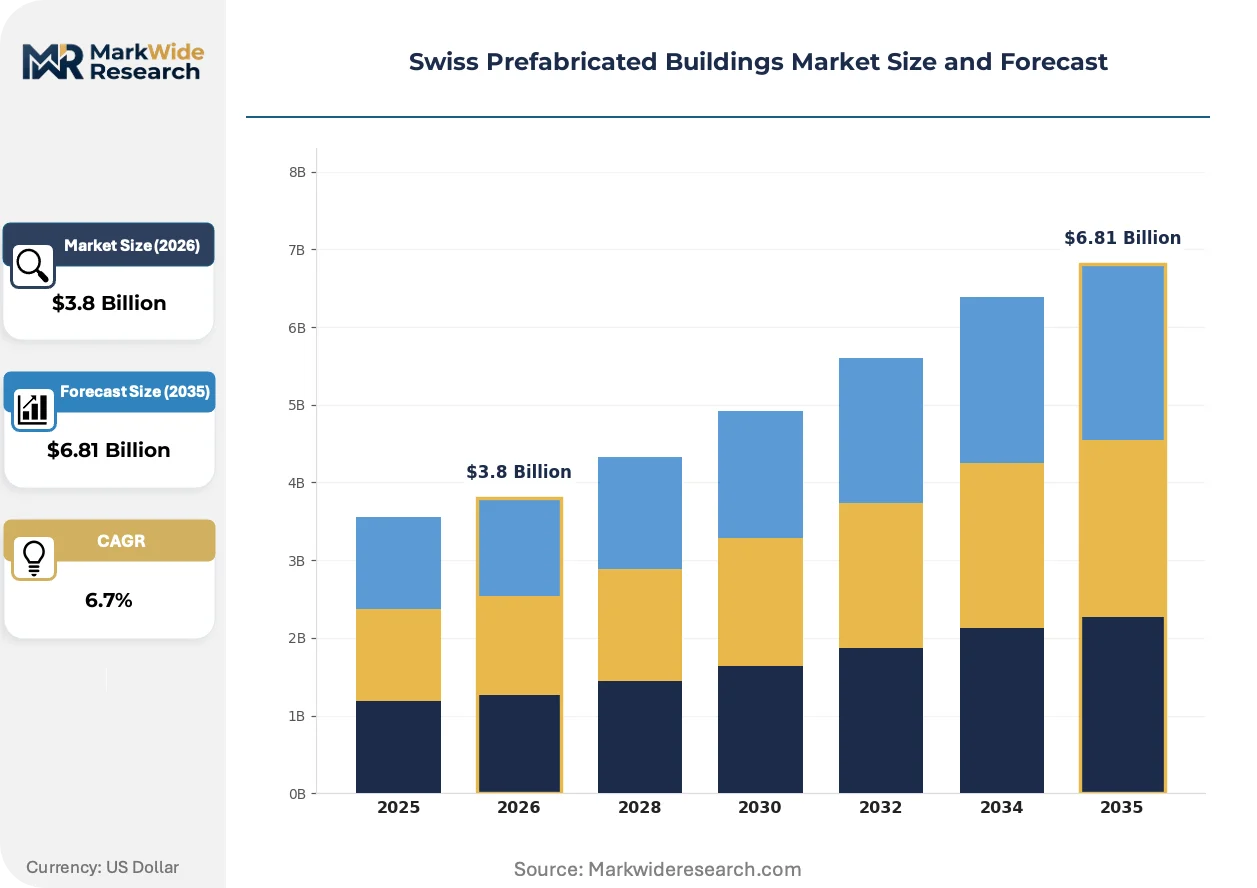
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Prefab Panels, SIPs, Prefabricated Modules Construction Method: Factory-built, On-site Assembly, Hybrid Systems, 3D Printing End User: Residential Developers, Commercial Builders, Contractors, Government Projects Material Used: Wood, Steel, Concrete, Composite Materials |
| Companies Covered | Prelco SA, Karmod, Swiss Krono, Blumer Lehmann Gruppe, Implenia, Baufritz, ALHO, Quadrin, Holzbau AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swiss Prefabricated Buildings Market Evolving Landscape
Swiss prefabrication is absorbing digital manufacturing methods from precision industries while regulatory pressure compresses permissible energy consumption in new construction.
Automated panel manufacturing is absorbing quality-control protocols from automotive assembly lines. Residential developers in Aargau and Basel-Land are deploying robotic fastening and laser-guided cutting to achieve sub-millimeter tolerances. This precision is absorbing warranty risk from general contractors and enabling longer structural guarantees.
Swiss Federal Office for the Environment CO₂ reduction mandates are reshaping material specification protocols. Embodied carbon thresholds now filter bank financing for multi-family residential projects. Developers targeting Minergie-A labels are responding by substituting cement-based systems for timber-hybrid assemblies with negative carbon profiles.
Design-build contracting is consolidating fragmented procurement stages. Zurich and Geneva developers now award single-source contracts covering architecture, engineering, and factory production. This compression is eliminating traditional tender-phase delays and aligning incentive structures across project stakeholders.
Swiss Prefabricated Buildings Market Segmentation
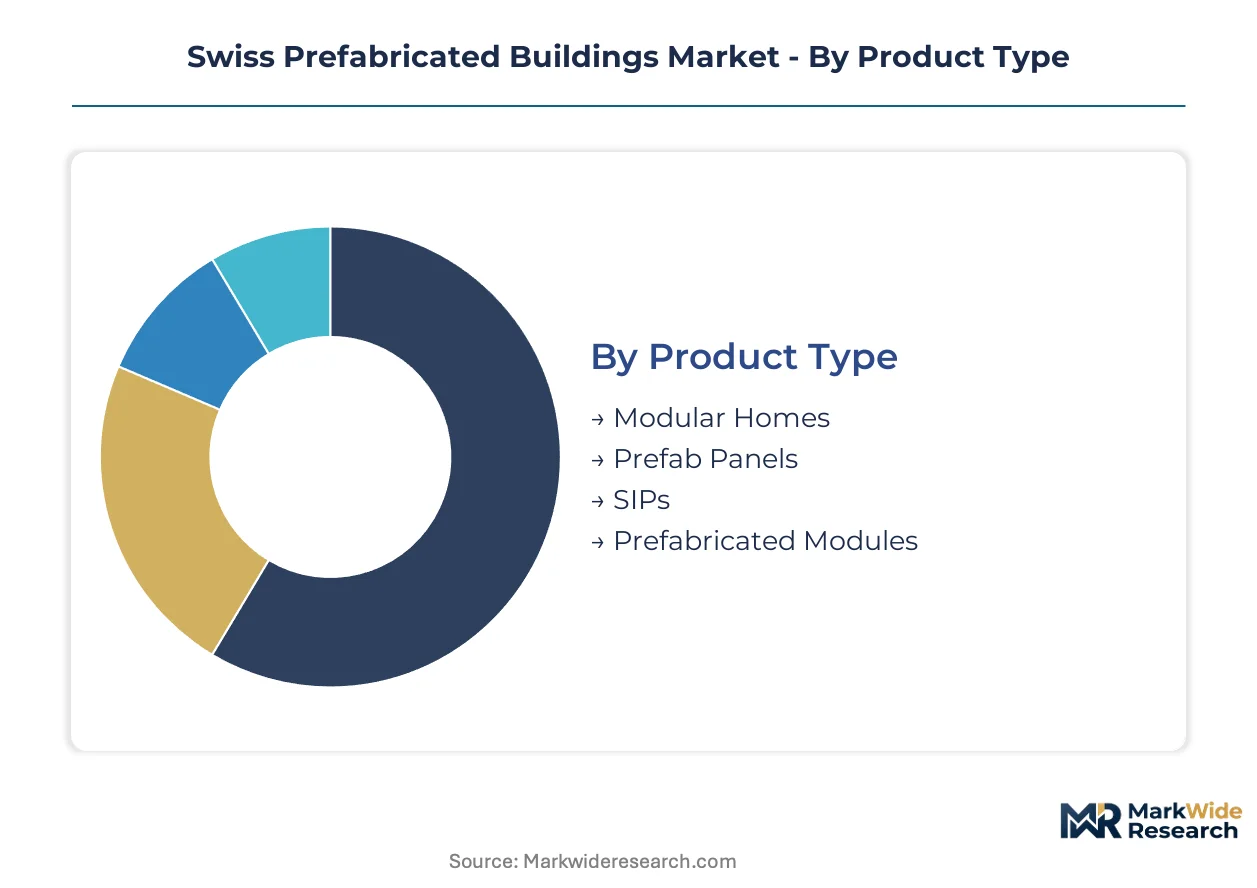
Segmentation reveals how Swiss prefabricated construction splits across technical approaches and procurement channels. Each dimension carries distinct margin profiles and regulatory exposure under cantonal building codes and Minergie standards.
Product Type:
Upgrade cycles vary dramatically across product categories, with thermal performance thresholds driving replacement demand in older building stock.
- Modular Homes:Complete volumetric units manufactured off-site with integrated MEP systems and interior finishes. Zurich and Geneva metropolitan corridors absorb the bulk of placements as developers compress entitlement-to-occupancy timelines in high-cost housing markets.
- Prefab Panels:Wall and roof assemblies produced in climate-controlled factories with guaranteed U-values below 0.20 W/m²K. Demand clusters in Aargau and Basel-Land cantons where developers value panelized flexibility for varied architectural massing.
- SIPs:Structural insulated panels combining OSB sheathing with rigid foam cores for rapid envelope assembly.
- Prefabricated Modules:Standardized volumetric units for bathrooms, kitchens, and technical rooms.
Volume placements concentrate in Modular Homes; the faster expansion belongs to Prefab Panels.
Construction Method:
Cost tiers separate capital-intensive automated production from labor-dependent site operations.
- Factory-built:Full off-site manufacturing under controlled conditions with robotic fastening and laser-guided cutting. Minergie-P certification requirements push mid-rise residential developers toward factory precision for thermal bridge elimination.
- On-site Assembly:Component delivery with final construction at project locations. Alpine tunnel clearances and cantonal road weight limits constrain module dimensions, preserving demand for site-finished connections in Ticino and Valais.
- Hybrid Systems:Combining factory-produced elements with traditional construction for structural cores or basements.
- 3D Printing:Additive manufacturing of concrete or polymer building components.
Factory-built methods capture the premium tier; hybrid configurations are climbing fastest as seismic codes mandate in-situ concrete foundations.
End User:
Customer type determines procurement sophistication and contract structure.
- Residential Developers:Multi-family project sponsors seeking design-build compression. KBOB federal procurement guidelines steer public-sector adjacent developments toward embodied carbon metrics, filtering material specifications.
- Commercial Builders:Office and retail construction specialists demanding architectural flexibility. Premium timber-hybrid systems serve this segment where visual expression commands price premiums.
- Contractors:General construction firms subcontracting prefabricated elements.
- Government Projects:Federal and cantonal public works with mandated sustainability thresholds.
Residential Developers dominate current volume; Government Projects are expanding most quickly as KBOB alignment tightens.
Material Used:
Supply concentration and embodied carbon profiles differentiate material choices.
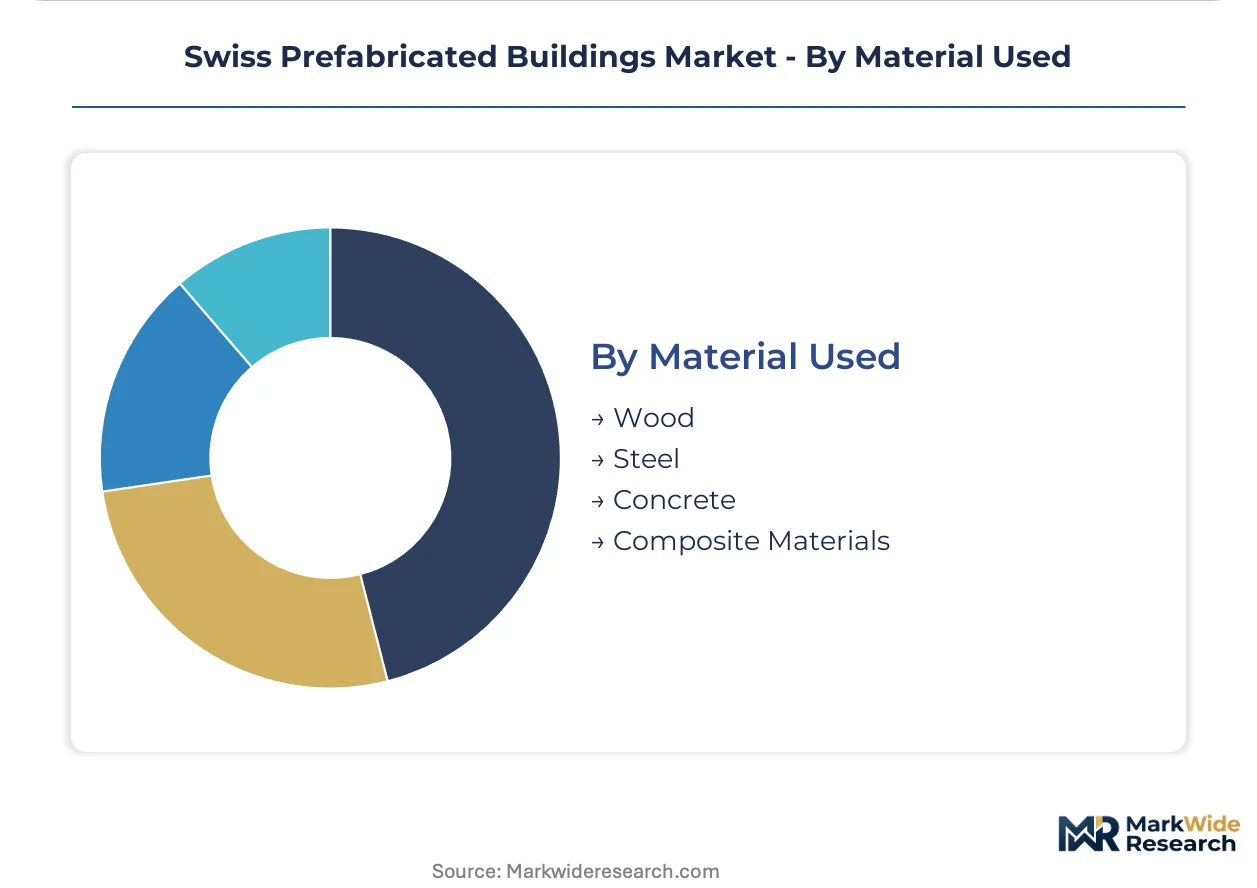
- Wood:Timber-frame and cross-laminated timber systems leveraging Swiss domestic forestry supply chains. Negative carbon profiles attract Minergie-A targeting developers facing bank financing screens.
- Steel:Light-gauge framing for non-combustible construction and long-span commercial applications.
- Concrete:Precast elements for seismic cores and foundation systems.
- Composite Materials:Fiber-reinforced polymers and hybrid assemblies.
Wood sustains the largest volume footprint; composite materials are gaining share fastest as technical performance thresholds advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss spruce and fir forests anchor domestic timber supply chains, feeding factory production across Alpine cantons while cantonal housing targets concentrate demand in metropolitan corridors.
Zurich Metropolitan Corridor
Entitlement-to-occupancy compression drives modular adoption as developers face land scarcity and elevated construction costs. SIA Swiss engineering standards enforce U-values below 0.20 W/m²K, pushing panelized systems over traditional stick-built methods. Winterthur and Schlieren host automated manufacturing facilities serving the dense northern housing belt.
Geneva-Lausanne Axis
Cross-border labor pools and premium real estate valuations sustain demand for architecturally demanding timber-hybrid systems. The Swiss Federal Office for the Environment enforces CO₂ reduction mandates that filter bank financing for multi-family projects. Rolle and Nyon cluster precision panel manufacturers supplying Lake Geneva's residential towers.
Basel-Land and Aargau
Industrial land availability and proximity to German supply chains support factory-built expansion. Cantonal building codes here harmonize more closely with Baden-Württemberg standards, easing cross-border component flows. Pratteln and Lenzburg host robotic fastening operations achieving sub-millimeter tolerances for mid-rise residential.
Ticino
Italian-speaking southern cantons access Lombardy manufacturing capacity with favorable labor cost differentials. Alpine tunnel clearances and cantonal road weight limits constrain module dimensions, preserving hybrid construction methods. Bellinzona and Locarno serve as logistics nodes for cross-border prefabricated component flows.
Bern and Central Switzerland
Federal government procurement under KBOB guidelines steers public projects toward embodied carbon metrics. The Minergie-A certification threshold creates demand for factory-produced facade replacement in deep energy retrofits. Thun and Lucerne anchor timber-frame production leveraging domestic forestry networks.
Swiss Prefabricated Buildings Market Competitive Landscape
Global majors compete with regional champions across factory automation and design-build integration, producing a tiered structure where scale-driven manufacturers sit alongside architecturally specialized boutiques. The vendor base splits between automated panel producers serving volume residential and timber-hybrid specialists commanding premium commercial contracts. Two archetypes dominate: precision manufacturers leveraging robotic fastening for thermal performance guarantees, and integrated design-build contractors compressing procurement stages. Capacity expansion and strategic partnerships constitute the primary competitive moves as firms secure cantonal housing pipeline access.
Among Swiss-based fabricators, Prelco SA exemplifies the automated manufacturing archetype with its panel production serving Western Switzerland's urban corridors. Blumer Lehmann Gruppe occupies a position within the premium timber-hybrid tier, anchoring architecturally demanding commercial engagements. Implenia represents the integrated design-build vector, consolidating fragmented procurement stages across major infrastructure and residential developments.
| Leading Market Players |
|---|
| Prelco SA |
| Karmod |
| Swiss Krono |
| Blumer Lehmann Gruppe |
| Implenia |
| Baufritz |
| ALHO |
| Quadrin |
| Holzbau AG |
| Others |
Value Network & Pricing Analysis
Swiss crane operators and module connection specialists in the Zurich metropolitan corridor command premium wages that widen spreads between factory-built premium tiers and on-site assembly economy offerings. Labor-cost differentials across Ticino's cross-border Lombardy access versus domestic Alpine manufacturing anchor a three-tier pricing structure that segments buyers by project complexity and thermal performance requirements.
Pricing Analysis
Warranty bundling separates premium timber-hybrid systems with 30-year structural guarantees from unbundled panel sales carrying limited defect coverage. Three-tier pricing structure across premium, standard, and economy levels reflects Minergie certification grade and volume scale, with Minergie-A labeled projects commanding substantial markups. Cost compression in standard-tier factory panels is intensifying because German cross-border suppliers are absorbing margin through automated production investments. Residential developers in high-cost cantons show least price sensitivity, while small commercial contractors in peripheral regions drive hard bargaining on transport-inclusive quotes.
Supply Chain Analysis
Single-source vulnerability sits with Austrian and German engineered wood suppliers dominating cross-laminated timber feedstock for Swiss factory production. Domestic forestry networks in Bern and Central Switzerland provide secondary spruce and fir sourcing, though automated CNC equipment draws from Italian and Austrian machinery builders. Tariff exposure on Lombardy-sourced components threatens Ticino-based assemblers serving southern cantons. Distribution runs through cantonal building material cooperatives with direct-to-developer factory contracts capturing volume in Zurich and Geneva corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as cantonal code fragmentation and digital twin implementation gaps force sub-scale fabricators toward acquisition or exit.
For Market Incumbents: Cement design-build integration capabilities to capture procurement compression demand from Zurich and Geneva developers facing entitlement-to-occupancy pressure. Acquire automated panel manufacturers in Aargau and Basel-Land to secure robotic fastening capacity before German competitors establish cross-border footholds. Minergie-P certification investment serves as the priority defensive lever against timber-hybrid specialists encroaching on mid-rise residential volume. For New Entrants and Emerging Players: Deep energy retrofit contractors targeting Minergie-A facade replacement represent an underserved buyer archetype with limited incumbent attention. Ticino's cross-border Lombardy manufacturing access offers the most penetrable geography for cost-positioned entry against domestic premium players. Pursue KBOB federal procurement alignment as the go-to-market angle for public-sector adjacent residential developments with mandated embodied carbon thresholds. For Investors and Strategic Acquirers: Re-rating potential sits with automated manufacturing specialists given Minergie certification tightening and bank financing screens filtering toward factory-guaranteed thermal performance. Long-term viability across the analysis window favors precision panel producers with established CNC-to-BIM data pipelines over site-dependent hybrid assemblers. Watch cantonal housing target acceleration in Zurich metropolitan corridor as the inflection signal for capacity utilization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Panel Manufacturing Scale-Up | Robotic fastening investments in Winterthur and Schlieren secure Minergie-P compliance capacity. |
| Cross-Border Lombardy Production Partnership | Ticino logistics nodes exploit favorable labor cost differentials for southern canton penetration. |
| Design-Build Contracting Consolidation | Single-source awards covering architecture through factory production eliminate tender-phase delays. |
| Minergie-A Certification Program Investment | Negative carbon profile timber-hybrid systems unlock bank financing screens for multi-family developers. |
| BIM-to-Factory Data Pipeline Development | Digital twin implementation bridges manual translation gaps between design and CNC programming. |
Research Methodology
Independent corroboration across factory operations directors, cantonal building authority officials, and residential development project managers underwrites the qualitative findings. Primary interviews with timber-frame production engineers, crane operator union representatives, and Minergie certification auditors combined with secondary validation from SIA Swiss engineering standards documentation, Swiss Federal Office for the Environment CO₂ mandate filings, and cantonal housing target publications. Bottom-up capacity assessments across automated manufacturing facilities and top-down demand modeling from entitlement pipeline data establish convergent estimates.
Rate-of-change decomposition across product type, construction method, end user, and material used dimensions structures the analytical framework. CAGRs derive from segment-level volume trajectories weighted by average selling price evolution, with cross-laminated timber cost curves and Minergie certification adoption rates serving as industry-specific forecast inputs. The projection horizon incorporates cantonal code harmonization assumptions and KBOB federal procurement guideline implementation pace.
Revisions become necessary when Alpine tunnel clearance regulations tighten, Lombardy labor cost differentials compress, or Minergie-P thresholds accelerate beyond current SIA standard trajectories. Forecasts reflect documented assumptions about factory automation investment cycles and cross-border component tariff stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Indonesia Infrastructure Market
Building Construction
Eastern Europe Construction Market
Building Construction
Modular and Portable Building Market
Building Construction
South Africa Prefabricated Buildings Market
Building Construction
Japan Construction Market
Building Construction
UAE Facade Market
Building Construction
North America Prefabricated Buildings Market
Building Construction
Middle East Data Center Construction Market
Building Construction
India Commercial Construction Market
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
UK Construction Market
Building Construction
Modular and Prefabricated Construction Market
Building Construction
Sweden New Construction Market
Building Construction
Ireland Data Center Construction Market
Building Construction
Europe Prefab Wood Buildings Market
Building Construction
ASEAN Prefab Wood Buildings Market