
 Tanzania Construction Market | 2026-2036
Tanzania Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Tanzania Construction Market Analytics
Mid-rise structural-grade concrete specifications are unwinding across Tanzania's commercial corridor. Advent Construction Ltd leverages captive batching plants to lock material costs in Dar es Salaam. Salem Construction Limited anchors its position through government road and bridge tenders. Becco Limited differentiates via specialized marine works at the Port of Dar es Salaam expansion.
Construction encompasses the assembly of civil, structural, and finishing elements into buildings and infrastructure using concrete with characteristic compressive strengths of 25-40 MPa, steel reinforcement per BS 4449 or equivalent, and engineered fill for subgrade stabilization. Its purpose is to create durable, code-compliant physical assets for habitation, commerce, and public service. Infrastructure project types currently lead contract value, while sustainable construction methods register the fastest uptake among donor-funded developments. Concrete dominates material procurement volumes, though steel intensifies in high-rise frames and industrial sheds.
Tanzania's Contractors Registration Board enforces competency grading for public works eligibility, while the Tanzania Bureau of Standards certifies cement and steel products under TBS standards derived from ISO frameworks. The National Environment Management Council mandates environmental impact assessments for projects exceeding defined thresholds, shaping project timelines and contractor compliance costs. Stakeholders must monitor alignment between local content procurement rules and imported equipment supply chains as project pipelines deepen.
Market Dynamics
Tanzania's construction sector pivots on the collision between donor-funded infrastructure pipelines and tightening local content procurement rules that force contractors to reconfigure supply chains around domestic cement and steel sourcing.
Growth Catalysts
- Standard-Tightened Material Certification:Tanzania Bureau of Standards cement and steel product certifications under TBS standards derived from ISO frameworks are filtering substandard imports and elevating domestic manufacturer capacity.
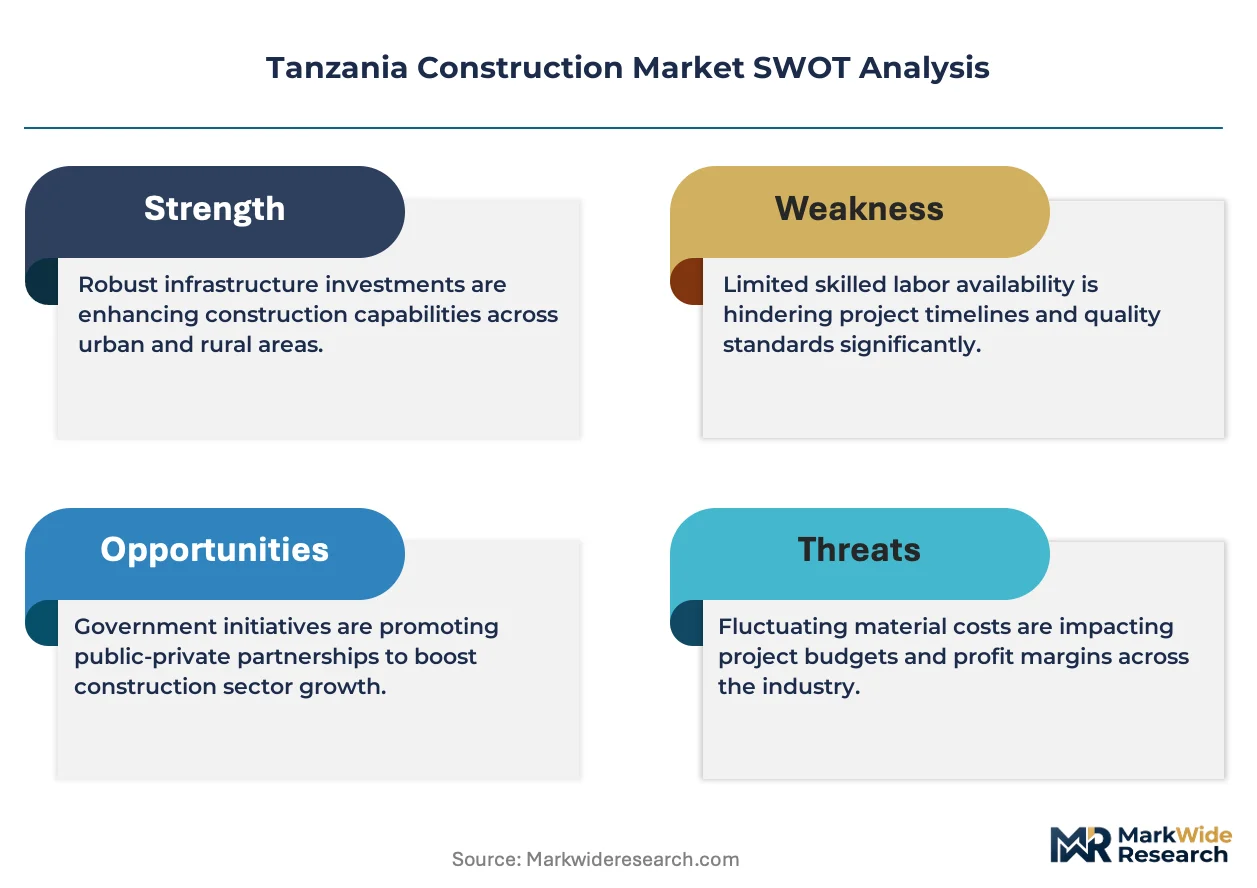
- Seismic Code Upgrades:National Building Code revisions mandating enhanced seismic and material standards are accelerating structural-grade concrete demand across Dar es Salaam's commercial corridor.
- Port Modernization Pipeline:Dar es Salaam Port expansion works are absorbing specialized marine construction capacity and creating spillover demand for coastal protection infrastructure.
Market Restraints
- Import Equipment Dependency:Heavy earthmoving and piling machinery remains concentrated in East Asian supply chains, exposing contractors to currency volatility and extended lead times.
- Clinker Supply Bottleneck:Domestic cement grinding capacity outpaces local clinker production, forcing reliance on imported intermediate feedstock subject to regional supply shocks.
- Skilled Labor Scarcity:Tanzania's Contractors Registration Board competency grading requirements exceed available certified technical personnel pools, constraining project mobilization speed.
Strategic Opportunities
- Secondary City Infrastructure:Mwanza and Dodoma urban expansion corridors present underpenetrated demand for mid-rise residential and commercial structural systems.
- Green Building Certification:Donor-funded developments are incorporating sustainable construction methods that reward contractors with environmental management credentials from the National Environment Management Council.
- Prefabrication Convergence:Modular concrete component manufacturing is converging with on-site digital layout technologies to compress high-rise project timelines in Dar es Salaam's dense urban core.
Industry Challenges
- Environmental Impact Assessment Delays:National Environment Management Council approval timelines for projects exceeding defined thresholds are extending pre-construction phases and inflating carrying costs.
- Batch Quality Consistency:Captive concrete batching plant operations face raw material variability challenges that threaten characteristic compressive strength compliance across multiple pour sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tanzania Construction Market |
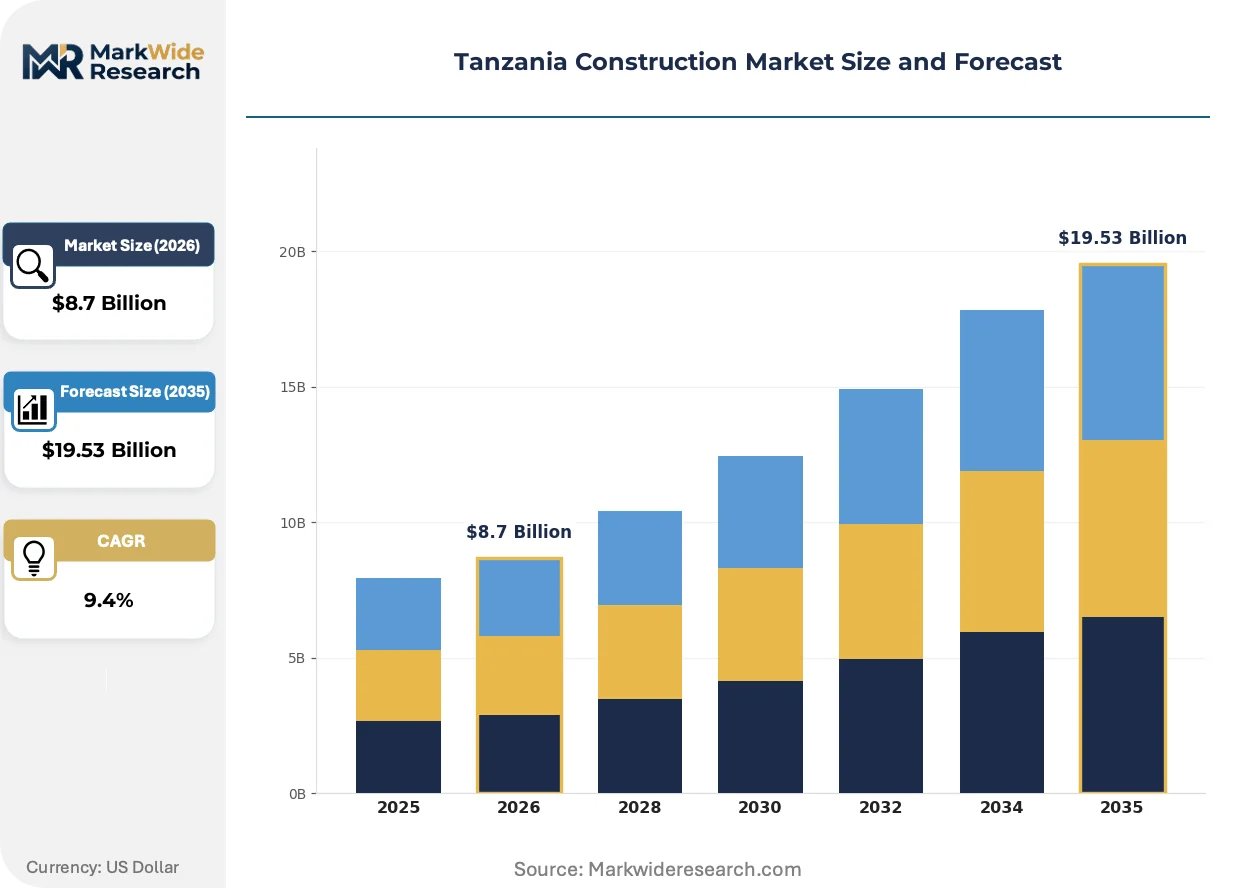
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Infrastructure, Industrial Material Used: Concrete, Steel, Wood, Sand End User: Government, Private Developers, NGOs, Contractors Construction Method: Traditional, Prefabricated, Modular, Sustainable |
| Companies Covered | Al Husseini Construction, Salem Construction Limited, Becco Limited, Imperial Construction Company, Masasi Construction Co Ltd, Mohammedi Builders Ltd, Advent Construction Ltd, Nordic Construction Company Limited, CSI Construction, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tanzania Construction Market Evolving Landscape
Digital fabrication and regulatory compression are actively reshaping how Tanzanian contractors deliver code-compliant assets. Technology adoption is splitting along project funding source lines, with donor-backed developments outpacing purely domestic procurement in method sophistication.
Structural-grade concrete specification is bifurcating across Tanzania's commercial corridor. Donor-funded projects specify 35-40 MPa characteristic compressive strength with full traceability documentation. Domestic private developments often accept 25-30 MPa with reduced testing protocols. This split is compressing mid-tier contractors between compliance cost burdens and price-competitive bidding environments.
Tanzania Bureau of Standards enforcement of TBS cement and steel certifications is hardening market access for uncertified imports. Industrial consequence includes accelerated investment in domestic grinding capacity and rebar rolling mills. Road and bridge tender participants are responding by locking multi-year supply agreements with certified domestic producers before bid submission.
Buyer concentration among government road and bridge tender authorities is compressing contractor margins and extending payment cycles. Large civil contractors are displacing smaller competitors through balance sheet capacity to absorb 180-day plus retention periods. This shift is most visible in Tanzania's central corridor highway rehabilitation programs where prequalification thresholds now exclude sub-Grade 6 registrants.
Tanzania Construction Market Segmentation
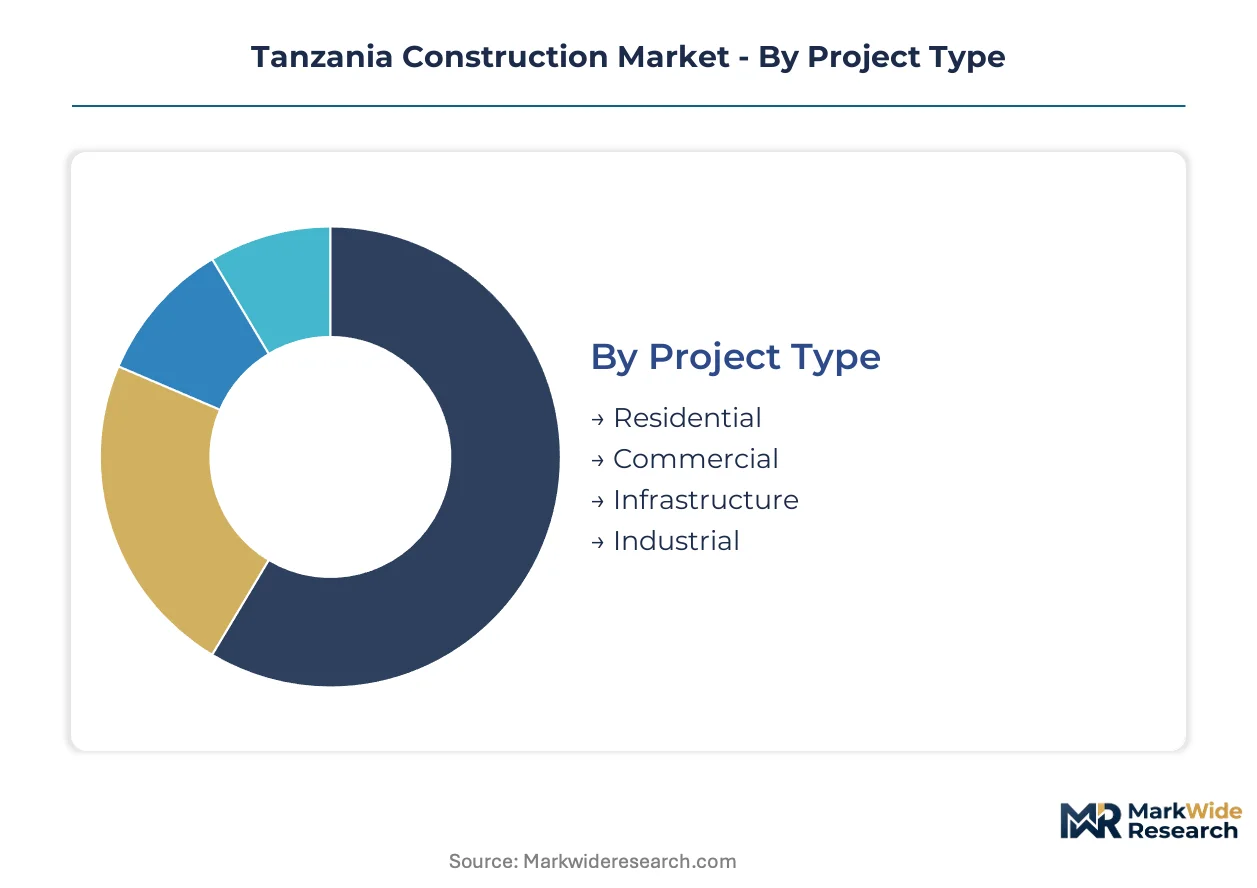
Tanzania's construction market fragments across project scale, material procurement patterns, and contracting authority types. Each dimension shapes contractor capability requirements, margin profiles, and regulatory compliance burdens in distinct ways.
Project Type:
Margins compress heaviest in government-tendered infrastructure while private commercial developments retain pricing power through faster payment cycles.
- Infrastructure:Road, bridge, and port works absorb the largest cement and steel volumes per contract. Tanzania Roads Agency and Tanzania Ports Authority tenders dominate Dar es Salaam and central corridor awards, though 180-day retention periods strain contractor liquidity.
- Commercial:Mid-rise office and retail structures in Dar es Salaam's CBD specify 35-40 MPa concrete with full testing documentation. Donor-funded developments here command premium pricing for seismic code compliance.
- Residential:Low-rise housing across secondary cities operates on thinner specifications and domestic financing.
- Industrial:Warehouse and manufacturing sheds concentrate in special economic zones with standardized shed designs.
The dominant share belongs to Infrastructure, while Commercial is closing the gap fastest.
Material Used:
Volume concentration tracks clinker grinding capacity location and Bureau of Standards certification enforcement intensity.
- Concrete:Characteristic compressive strengths of 25-40 MPa dominate procurement, with batching plant proximity determining landed cost in Dar es Salaam versus upcountry sites. Tanzania Bureau of Standards TBS cement certifications filter substandard imports and elevate domestic grinding capacity.
- Steel:Rebar per BS 4449 or equivalent intensifies in high-rise frames and industrial sheds. Domestic rolling mills are locking multi-year supply agreements with road and bridge tender participants.
- Wood:Timber framing persists in rural residential and low-cost applications.
- Sand:Engineered fill for subgrade stabilization draws from riverine deposits with variable grading compliance.
Concrete commands the volume lead, though Steel is gaining share fastest in vertical structural systems.
End User:
Contracting authority type dictates payment security, specification stringency, and local content enforcement pressure.
- Government:Central ministries and parastatals anchor the heaviest contract value through Tanzania Roads Agency and Tanzania Ports Authority pipelines. Prequalification thresholds now exclude sub-Grade 6 registrants from highway rehabilitation programs.
- Private Developers:Dar es Salaam commercial and residential sponsors offer faster mobilization but demand price-competitive bidding against mid-tier competitors.
- NGOs:Donor-funded developments incorporate sustainable construction methods and environmental management credentials from the National Environment Management Council.
- Contractors:Tier-1 firms self-perform on captive projects or joint ventures.
Government holds the contract value majority, yet Private Developers are expanding most quickly in urban residential.
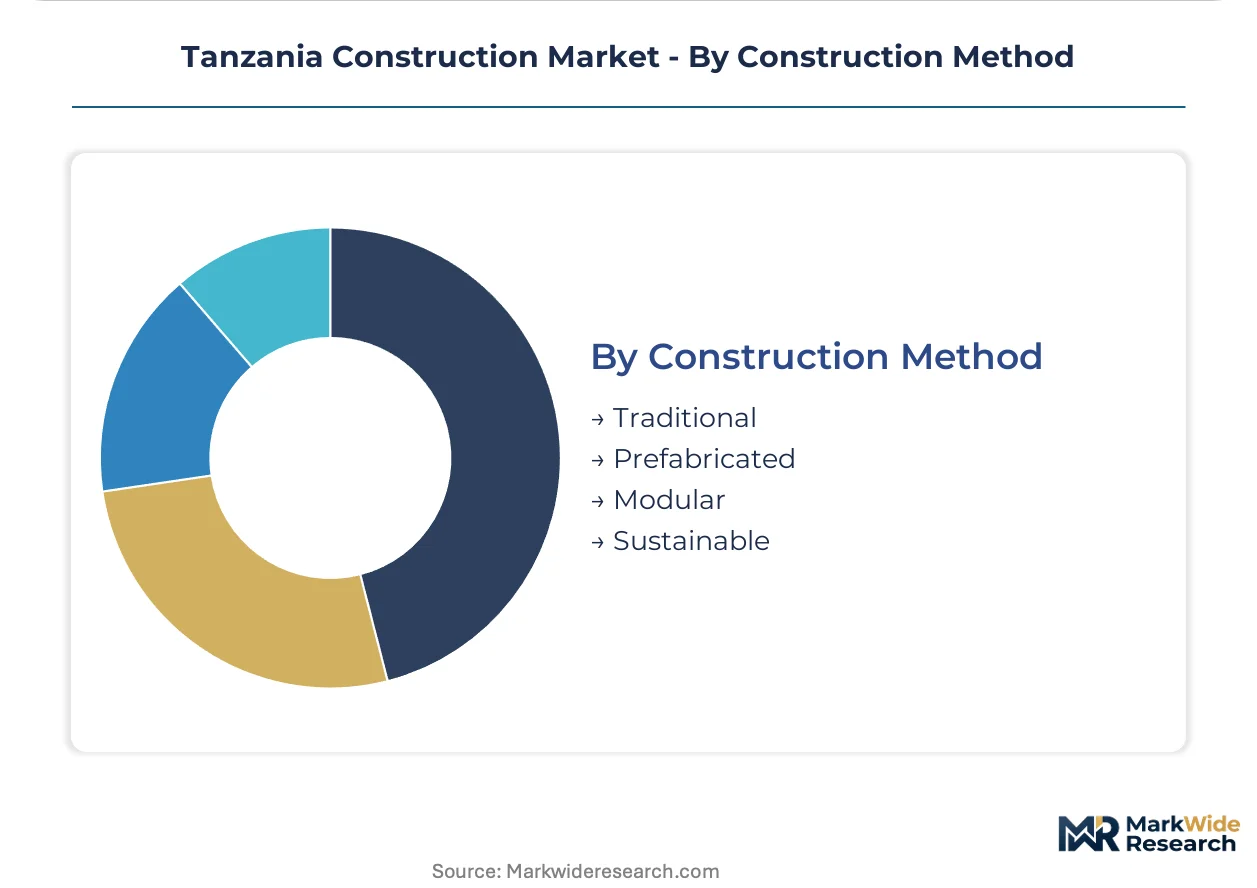
Construction Method:
Technology adoption splits along funding source lines, with donor-backed developments outpacing domestic procurement in method sophistication.
- Traditional:Cast-in-place concrete with on-site formwork dominates volume across all project types. Raw material variability challenges threaten characteristic compressive strength compliance across multiple pour sites.
- Sustainable:Green building certification requirements from donor-funded developments reward environmental management credentials and compress timelines through pre-approved material specifications.
- Prefabricated:Modular concrete component manufacturing converges with digital layout technologies in dense urban cores.
- Modular:Panelized systems remain nascent outside demonstration projects.
Traditional methods retain the execution share, while Sustainable approaches are climbing the fastest among donor-funded pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinker grinding capacity and Bureau of Standards certification enforcement concentrate construction material supply in Dar es Salaam, while road and bridge tenders extend contractor liquidity demands across Tanzania's central corridor.
Dar es Salaam
Dar es Salaam anchors the heaviest concentration of commercial and residential contract awards. Tanzania Bureau of Standards cement certifications filter substandard imports and elevate domestic grinding capacity. The Port of Dar es Salaam expansion absorbs specialized marine construction capacity and creates spillover demand for coastal protection infrastructure.
Dodoma
Dodoma's urban expansion corridors present underpenetrated demand for mid-rise residential and commercial structural systems. The National Building Code revisions mandating enhanced seismic standards accelerate structural-grade concrete demand. Government relocation programs concentrate public infrastructure investment in administrative district construction.
Mwanza
Mwanza anchors Lake Victoria regional trade infrastructure and secondary city growth. Tanzania Roads Agency central corridor highway rehabilitation programs extend prequalification thresholds that exclude sub-Grade 6 registrants. Industrial shed construction concentrates in special economic zones with standardized designs.
Arusha
Arusha supports tourism-linked commercial development and regional logistics infrastructure. National Environment Management Council environmental impact assessments shape project timelines for developments exceeding defined thresholds. Safari corridor hospitality construction specifies 35-40 MPa concrete with full testing documentation.
Zanzibar
Zanzibar's island geography constrains material supply chains and elevates marine logistics costs. Donor-funded developments incorporate sustainable construction methods that reward environmental management credentials. Coastal protection infrastructure absorbs specialized marine construction capacity from mainland contractors.
Tanzania Construction Market Competitive Landscape
Concentration sits with Grade 6 and above registrants who absorb extended retention periods through balance sheet capacity. Tanzania's Contractors Registration Board competency grading filters public works eligibility, compressing mid-tier competitors between compliance costs and price-competitive bidding. Three archetypes dominate: captive batching plant operators locking material costs, government tender specialists anchoring road and bridge pipelines, and marine works specialists capturing port modernization demand. Competitive moves center on multi-year supply agreements with certified domestic producers and balance sheet expansion to absorb 180-day plus retention periods.
Within the government tender specialist tier, Salem Construction Limited and Advent Construction Ltd exemplify archetypes that anchor public infrastructure pipelines. Becco Limited occupies a position among specialized marine contractors capturing port expansion works. These three represent the competitive positioning spectrum from material cost control through captive batching to niche marine capability at the Port of Dar es Salaam.
| Leading Market Players |
|---|
| Al Husseini Construction |
| Salem Construction Limited |
| Becco Limited |
| Imperial Construction Company |
| Masasi Construction Co Ltd |
| Mohammedi Builders Ltd |
| Advent Construction Ltd |
| Nordic Construction Company Limited |
| CSI Construction |
| Others |
Value Network & Pricing Analysis
Ninety-day equipment lead times from East Asian manufacturers compress contractor bidding windows and amplify price volatility for heavy earthmoving fleets. This inventory pressure concentrates pricing power among Grade 6 registrants who can pre-position machinery and absorb currency swings, while mid-tier competitors face margin erosion from spot-market equipment procurement.
Pricing Analysis
Tanzania Bureau of Standards cement and steel certifications dictate the pricing tier structure across Dar es Salaam's commercial corridor. Project-based contracting dominates, with price differentiation tracking certification grade and seismic compliance level. Cost compression in government-tendered infrastructure intensifies because 180-day retention periods force liquidity absorption. Private developers exhibit the lowest price sensitivity, prioritizing speed-to-completion over unit cost.
Supply Chain Analysis
Clinker inventory cycles of 45-60 days tether domestic cement grinding capacity to regional import flows from Kenya, Zambia, and Vietnam. Raw material dependencies center on imported clinker, BS 4449-equivalent rebar, and engineered fill from riverine deposits. Single-source vulnerability runs through East Asian heavy equipment supply chains. Distribution feeds from Dar es Salaam grinding clusters to upcountry batching plants via road freight networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tanzania's construction sector sits in early-cycle expansion, with donor-funded infrastructure pipelines and National Building Code revisions creating sustained demand tailwinds for seismic-compliant structural systems.
For Market Incumbents: Compound balance sheet capacity to absorb extended retention periods through multi-year supply agreements with Tanzania Bureau of Standards-certified domestic producers. Lock material costs via captive batching plant networks before bid submission. Counter the threat of prequalification threshold escalation by accelerating Grade 6 competency certification for technical personnel pools.
For New Entrants and Emerging Players: Differentiate on modular concrete component manufacturing converged with digital layout technologies. Target Dodoma and Mwanza urban expansion corridors where mid-rise residential and commercial structural systems remain underpenetrated. Pursue green building certification credentials from the National Environment Management Council to access donor-funded development pipelines.
For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned construction groups lacking succession liquidity or certification compliance infrastructure. Long-term viability hinges on alignment with Tanzania's local content procurement tightening and port modernization timelines. Watch National Environment Management Council approval velocity as the inflection indicator for project pipeline acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Batching Plant Network | Advent Construction Ltd locks material costs against Dar es Salaam price volatility through owned plants. |
| Government Tender Specialization | Salem Construction Limited anchors position via Tanzania Roads Agency road and bridge pipelines. |
| Marine Works Certification | Becco Limited captures Port of Dar es Salaam expansion demand through specialized coastal capability. |
| Green Building Credentialing | Donor-funded developments reward National Environment Management Council environmental management certification. |
| Multi-Year Supply Agreements | Road and bridge tender participants lock certified domestic cement and steel before bid submission. |
Research Methodology
Cross-validation between contractor interviews and Tanzania Bureau of Standards regulatory filings anchors the qualitative findings. Primary discussions with project directors at Grade 6 registrants, procurement officers at Tanzania Roads Agency, and batching plant operators combined with secondary analysis of TBS certification databases, Contractors Registration Board competency registries, and National Environment Management Council environmental impact assessment records. Bottom-up project pipeline tracking and top-down sector value triangulation frame the market sizing.
Sensitivity analysis around clinker import dependency and equipment lead-time assumptions stress-tests the analytical framework. Segmentation dimensions span project type, material specification tier, contracting authority, and construction method sophistication across the projection horizon. CAGRs derive from contract award velocity analysis and cement consumption intensity modeling. Forecast inputs include Tanzania Ports Authority capital expenditure pipelines and seismic code compliance cost curves.
Material uncertainties — currency volatility affecting East Asian equipment imports, regional clinker supply disruptions, and National Environment Management Council approval delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about donor funding continuity and local content enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
North America Modular Construction Market
Building Construction
Latin America Construction Market
Building Construction
Turkey Commercial Construction Market
Building Construction
Europe Prefabricated Buildings Market
Building Construction
Honduras Construction Market
Building Construction
Singapore Data Center Construction Market
Building Construction
Sweden New Construction Market
Building Construction
UK Construction Market
Building Construction
China Modular Construction Market
Building Construction
Pre-Engineered Building Market
Building Construction
Japan Commercial Construction Market
Building Construction
Guatemala Construction Market
Building Construction
3D Printing Building Construction Market
Building Construction
Global Dry Construction Market
Building Construction
Egypt Residential Construction Market
Building Construction
Ireland Data Center Construction Market