
 Arc Fault Detection Market | 2026-2036
Arc Fault Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Arc Fault Detection Market Insights
Aftermarket service revenue is rewriting value capture across the arc fault detection value chain. Schneider Electric leverages its installed base to sustain recurring calibration and firmware update contracts. ABB anchors European utility-grade deployments with IEC 62606-certified hardware platforms. Eaton competes on channel density, controlling electrical distributor relationships across North American contractor networks.
Arc fault detection encompasses electronic systems that identify hazardous arcing conditions in electrical circuits through signature analysis of current waveforms, typically operating at detection thresholds of 75 amperes per second with response times under 0.025 seconds to mitigate fire ignition risks. Arc Fault Circuit Interrupters occupy the dominant product tier as code-mandated baseline protection in residential and light commercial construction. Smart Breakers represent the fastest-expanding segment as grid-edge digitization enables remote monitoring and predictive load management. Monitoring Systems capture elevated margins in industrial settings where continuous insulation resistance tracking prevents unplanned downtime.
The US National Electrical Code through Article 210.12 mandates arc fault protection in residential dwelling units, while the EU's Construction Products Regulation enforces CE marking for fire safety equipment including arc detection devices. Germany's DIN VDE 0100-420 standard shapes product certification requirements across European markets. Stakeholders must monitor evolving harmonization between IEC 62606 and UL 1699 standards as dual-certification demands influence regional manufacturing strategies.
Market Dynamics
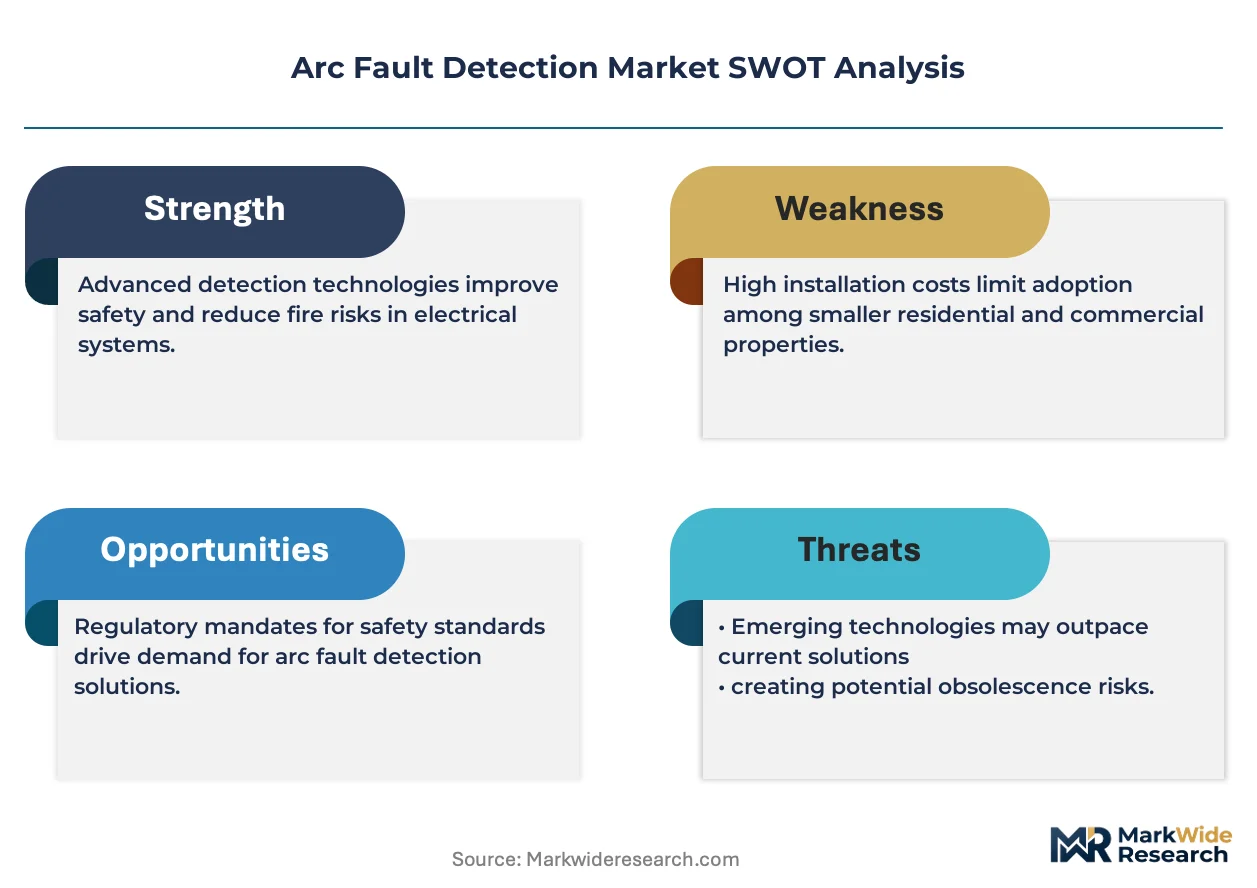
Retrofit mandates across aging electrical infrastructure are accelerating replacement cycles for conventional circuit protection, compelling asset owners to upgrade legacy panels with arc fault detection capabilities.
Growth Catalysts
- NEC Article 210.12:US residential construction codes mandate arc fault circuit interrupters in dwelling units, creating baseline demand for new installations and renovation projects.
- DIN VDE 0100-420:Germany's electrical installation standards drive retrofit demand across commercial and industrial facilities seeking compliance with updated safety protocols.
- Grid-edge digitization:Smart breaker adoption is accelerating as utilities deploy distributed energy resource management systems requiring granular circuit-level visibility.
Market Restraints
- Semiconductor input volatility:Detection algorithm processing chips face supply concentration risks from East Asian foundries, creating component availability bottlenecks.
- Copper price sensitivity:Busbars and current-carrying conductors represent 15-20% of bill-of-materials costs, exposing margins to commodity swings.
- Dual-certification burden:Manufacturers must simultaneously satisfy IEC 62606 and UL 1699 testing protocols, extending product development timelines.
Strategic Opportunities
- Industrial predictive maintenance:Continuous insulation resistance monitoring in manufacturing facilities creates recurring revenue streams beyond hardware sales.
- Remote firmware monetization:Cloud-connected devices enable subscription-based algorithm updates and threat signature libraries.
- Data center power quality:Hyperscale computing facilities demand arc fault detection integrated with power distribution unit intelligence.
Industry Challenges
- Nuisance trip calibration:Differentiating hazardous arcing from normal load switching requires sophisticated signal processing expertise that strains engineering talent pools.
- Legacy panel integration:Retrofitting arc fault capability into existing electrical infrastructure demands custom form factors and installation labor coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arc Fault Detection Market |
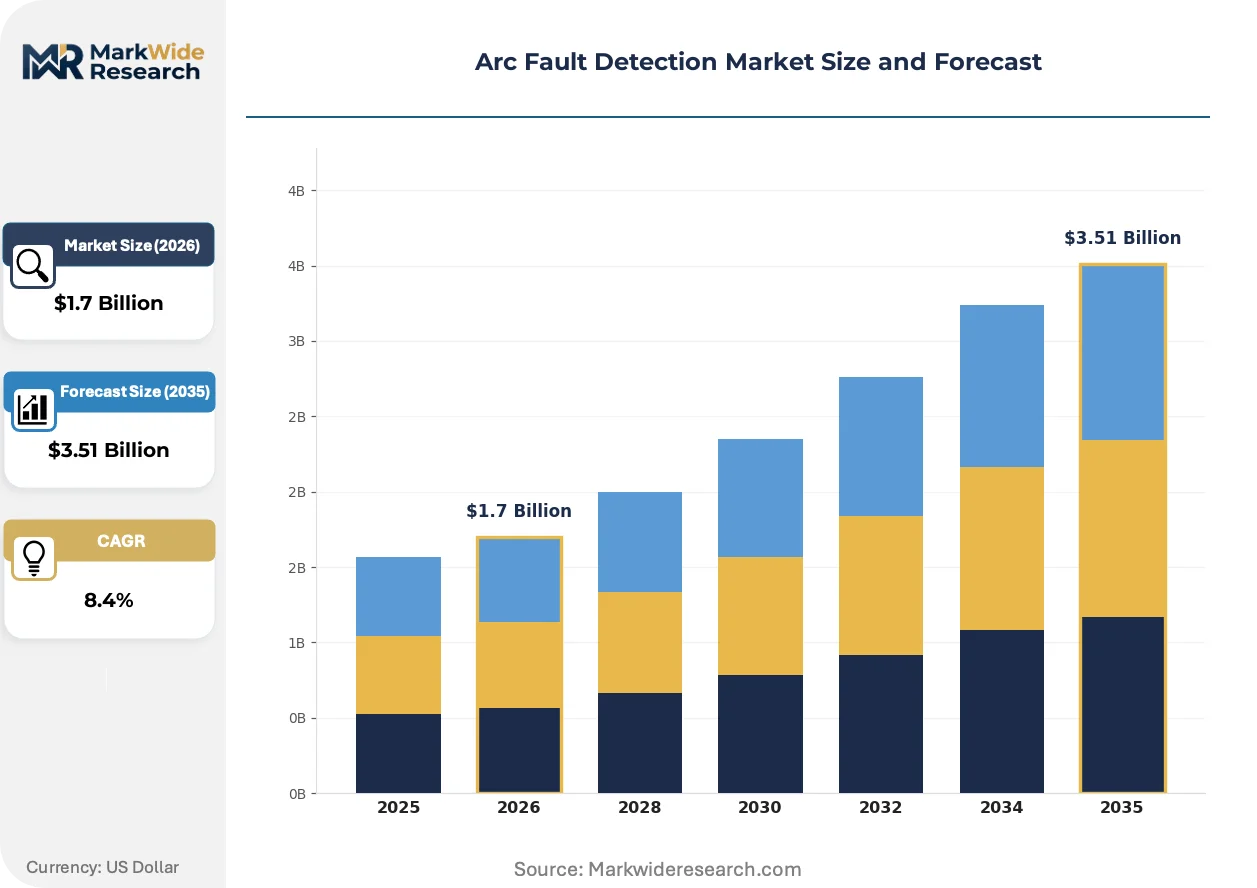
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $3.51 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arc Fault Circuit Interrupters, Smart Breakers, Monitoring Systems, Sensors Installation Type: Residential, Commercial, Industrial, OEM Service Type: Installation Services, Maintenance Services, Integration Services, Consulting End User: Utilities, Electrical Contractors, Homeowners, Facility Managers |
| Companies Covered | Schneider Electric, ABB, Eaton, Siemens, Hager Group, Legrand, OEZ s.r.o., ETI, Schrack Technik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arc Fault Detection Market Trends and Innovations
Signature analysis algorithms are advancing beyond threshold-based detection toward machine-learned pattern recognition, compressing response latencies while reducing false positives.
Artificial intelligence inference at the circuit breaker level is rendering obsolete conventional threshold-based detection methods that rely on fixed ampere-per-second triggers. Commercial building automation integrators are piloting neural network-trained devices across Class A and Class B fault categories. The shift toward edge-computing architectures is compressing hardware margins for legacy microcontroller-based platforms.
Harmonization efforts between IEC 62606 and UL 1699 standards are accelerating transatlantic product development convergence. Manufacturers pursuing dual-certification strategies are consolidating testing protocols to reduce redundant validation cycles. European industrial OEMs are driving adoption of unified test methodologies to streamline export qualification for North American markets.
Electrical contractors are consolidating procurement around distributor-integrated specification support rather than direct manufacturer relationships. Large-scale residential developers are demanding packaged panel solutions with pre-certified arc fault breakers from single-source suppliers. This channel consolidation is most pronounced across US Sun Belt metropolitan construction markets.
Arc Fault Detection Market Segmentation
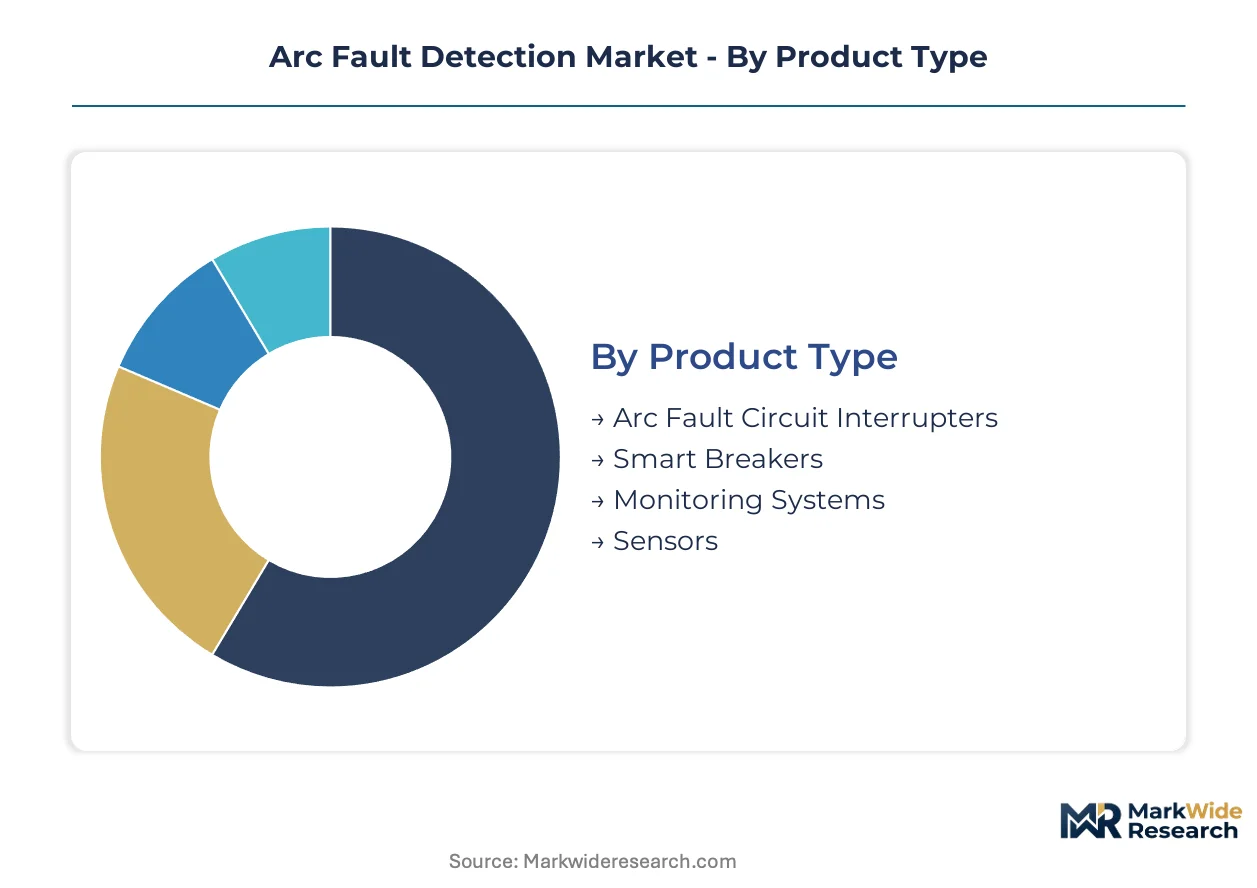
Segmentation in arc fault detection reveals how code mandates, infrastructure age, and digitization priorities split demand across hardware form factors and service relationships. Each dimension carries distinct margin profiles and competitive dynamics that shape vendor positioning.
Product Type:
Mature circuit protection hardware dominates revenue concentration while emerging intelligent platforms capture specification momentum in next-generation installations.
- Arc Fault Circuit Interrupters:Electromechanical devices with embedded microcontrollers detect hazardous arcing through current waveform analysis at 75 A/s thresholds. NEC Article 210.12 mandates these across US residential dwelling units, sustaining replacement demand in renovation and new construction markets.
- Smart Breakers:Grid-edge devices integrate communications modules for remote monitoring, load control, and predictive algorithm deployment. Utilities deploying distributed energy resource management systems in Germany and California specify these for circuit-level visibility into distributed solar and storage assets.
- Monitoring Systems:Continuous insulation resistance tracking platforms serve industrial facilities requiring uptime assurance.
- Sensors:Component-level detection elements embed into panel assemblies and OEM equipment.
Arc Fault Circuit Interrupters handle the majority of throughput; Smart Breakers are expanding most quickly on specification share.
Installation Type:
Cost tier segmentation separates code-mandated residential volumes from premium-priced industrial deployments requiring custom engineering.
- Residential:Single-family and multi-family dwelling installations driven by NEC compliance represent the highest-volume, lowest-margin tier with distributor-consolidated procurement.
- Commercial:Office, retail, and institutional buildings in Germany's retrofit markets demand DIN VDE 0100-420 certified solutions with documented inspection trails.
- Industrial:Manufacturing and processing facilities pay premiums for continuous monitoring and integration with building management systems.
- OEM:Original equipment manufacturers embed arc fault capability into panelboards, switchgear, and appliance assemblies at factory level.
Residential captures the highest unit volumes; Industrial commands the steepest price premiums per installation.
Service Type:
Recurring revenue potential concentrates in post-installation relationships where firmware updates and calibration sustain long-term vendor engagement.
- Installation Services:Electrical contractor labor for breaker replacement and panel upgrades, typically bundled with hardware in residential markets.
- Maintenance Services:Periodic calibration, nuisance trip investigation, and component replacement contracts. Schneider Electric structures multi-year service agreements around installed base access.
- Integration Services:System-level deployment connecting arc fault hardware with building automation and utility control platforms.
- Consulting:Engineering assessment of legacy infrastructure for retrofit feasibility and compliance pathway design.
Installation Services generates the largest immediate revenue pool; Maintenance Services is climbing the fastest as vendors pivot toward recurring contract models.
End User:
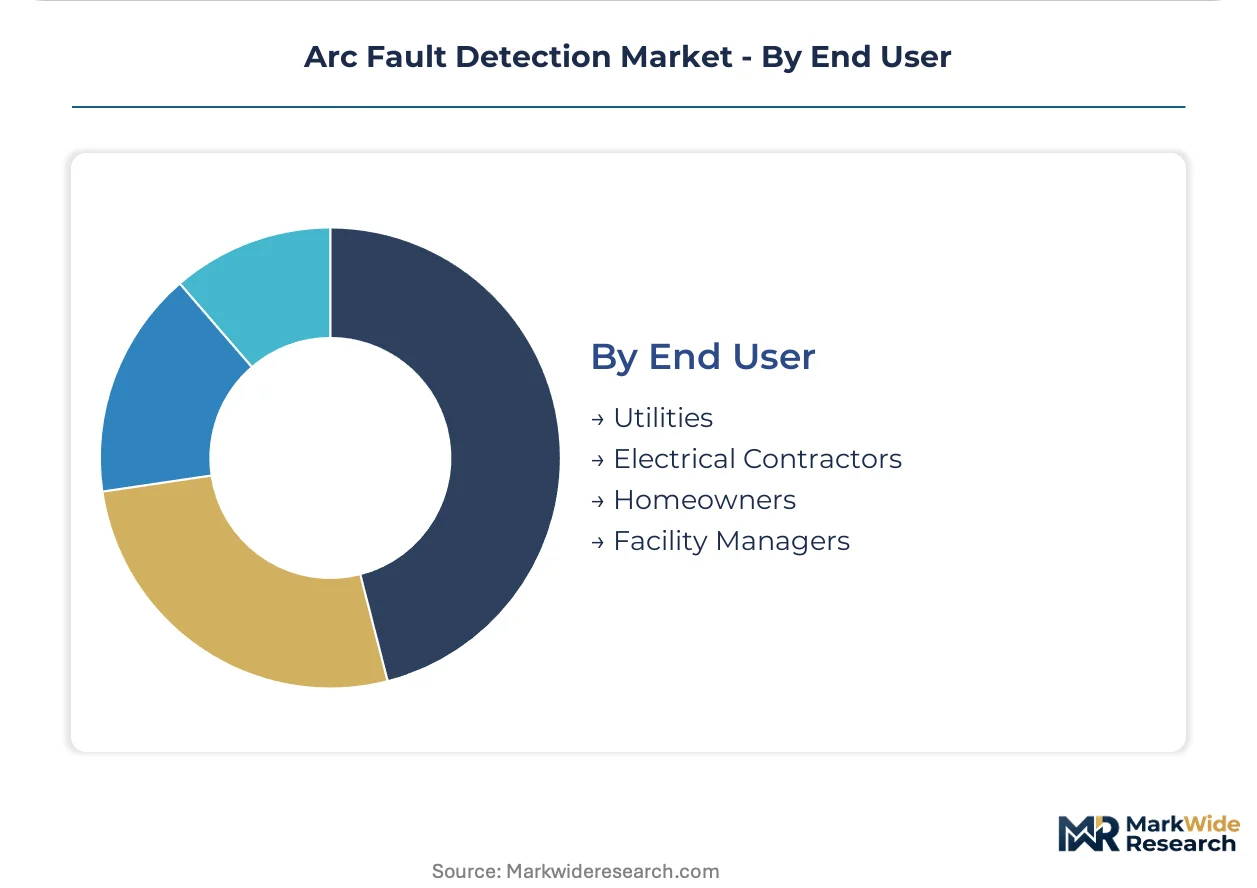
Customer type segmentation maps to decision authority—specifying engineers, purchasing contractors, regulatory-driven asset owners, and distributed residential buyers.
- Utilities:Grid operators in California, Texas, and Germany procure smart breakers for distribution network visibility and demand response orchestration.
- Electrical Contractors:Installation professionals consolidate procurement through distributor relationships, particularly across US Sun Belt metropolitan construction corridors.
- Homeowners:End consumers purchase replacement breakers for renovation projects and insurance-mandated upgrades, price-sensitive and brand-agnostic.
- Facility Managers:Commercial and industrial building operators prioritize uptime protection and insurance premium reduction through certified monitoring systems.
Electrical Contractors intermediate the majority of product flow; Utilities are gaining specification influence fastest as grid modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential buyers in Germany tolerate premium pricing for DIN VDE-certified retrofit solutions, while US electrical contractors squeeze margins through distributor-consolidated procurement. Industrial facilities in Japan pay steepest premiums for continuous monitoring integration.
United States
NEC Article 210.12 mandates arc fault circuit interrupters in all residential dwelling units, sustaining baseline demand across new construction and renovation markets. The Department of Energy's grid modernization grants accelerate smart breaker deployment for distributed energy resource integration. Electrical contractors across Texas and Arizona metropolitan corridors consolidate procurement through distributor-integrated specification support.
Germany
DIN VDE 0100-420 standards drive retrofit installations across aging commercial and industrial electrical infrastructure. The country's national electrical safety regulator enforces updated inspection protocols compelling facility upgrades. Manufacturing clusters in Bavaria and Baden-Württemberg specify continuous insulation resistance monitoring for uptime-critical production lines.
China
GB standards for electrical fire prevention tighten enforcement across high-rise residential and commercial construction. The Ministry of Emergency Management coordinates provincial-level safety inspections accelerating replacement of legacy protection devices. Yangtze River Delta manufacturing hubs pilot AI-enhanced arc fault detection for smart factory integration.
Japan
METI's building energy efficiency codes incentivize intelligent circuit protection with remote monitoring capabilities. JIS certification requirements shape product qualification pathways for domestic and export markets. Kanto region data center operators demand arc fault detection integrated with power distribution unit intelligence for hyperscale facilities.
Arc Fault Detection Market Competitive Landscape
Capability concentration sits with specialists mastering signature analysis algorithms; scale advantage sits with diversified electrical equipment conglomerates controlling distribution channels. The market structures around three tiers: multinational platform providers with integrated service ecosystems, regional manufacturers competing on code-compliance speed, and component specialists supplying detection sensors to OEM panel assemblers. Dominant competitive moves include distributor relationship lock-ups in high-growth construction corridors and firmware subscription models converting hardware sales into recurring revenue streams.
Within the multinational platform tier, Schneider Electric and ABB exemplify divergent geographic anchoring strategies. Schneider Electric leverages its installed base across European retrofit markets to sustain calibration and firmware update contracts. ABB occupies a position anchoring utility-grade deployments with IEC-certified hardware platforms in Germany and adjacent markets. Eaton represents the channel-density archetype, controlling electrical distributor relationships across North American contractor networks rather than pursuing direct specification influence.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Eaton |
| Siemens |
| Hager Group |
| Legrand |
| OEZ s.r.o. |
| ETI |
| Schrack Technik |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp freight corridor shapes cost dynamics across arc fault detection supply chains, with container rates from East Asian semiconductor foundries feeding into both supply concentration in detection algorithm processors and downstream price differentiation between IEC 62606 and UL 1699 certified product tiers.
Pricing Analysis
Long-term offtake contracts dominate utility-grade smart breaker procurement, while residential contractors transact on spot pricing through electrical distributors. Price differentiation stems from dual-certification status and firmware subscription bundling, with DIN VDE-compliant industrial units commanding premiums over baseline NEC-mandated residential breakers. Cost compression in the residential tier intensifies as Sun Belt distributors consolidate procurement volumes. Homeowners remain most price-sensitive, while German facility managers prioritize certification compliance over unit cost.
Supply Chain Analysis
Upstream feedstock for detection algorithm processors concentrates in Taiwan, South Korea, and mainland China, with microcontroller fabrication tethered to East Asian foundry capacity. Copper busbars, silver contacts, and epoxy resin housings represent critical material dependencies. Single-source vulnerability in semiconductor supply creates exposure to logistics chokepoints at the Port of Long Beach. Distribution runs through electrical distributor networks in North America and direct OEM relationships across European industrial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in signal processing engineering talent constrains algorithm development velocity, creating defensive moats for incumbents with established firmware ecosystems while limiting new entrant speed-to-market in nuisance trip calibration.
For Market Incumbents: Harden firmware subscription retention through multi-year calibration contracts anchored to installed base access. Deepen backward integration into semiconductor sourcing to mitigate foundry concentration risk. Prioritize IEC-UL harmonization investment to compress dual-certification timelines against emerging regional competitors. For New Entrants and Emerging Players: Pursue industrial predictive maintenance white space in Japanese data center and German manufacturing clusters where continuous monitoring penetration remains below utility-scale deployment. Target facility manager specification influence through insulation resistance tracking demonstrations rather than competing on breaker hardware margins. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electrical conglomerates with under-monetized arc fault detection divisions lacking recurring revenue infrastructure. Long-term viability hinges on algorithm update monetization conversion rates. Watch smart breaker attach rates in California and Texas utility pilots as inflection indicators for grid-edge specification momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Subscription Conversion | Transforms one-time hardware sales into recurring calibration and algorithm update revenue streams. |
| Dual-Certification Consolidation | Reduces redundant IEC 62606 and UL 1699 testing cycles for transatlantic product launches. |
| Distributor Relationship Lock-Up | Secures specification priority across Sun Belt metropolitan construction corridors through exclusive panel partnerships. |
| AI Inference Edge Deployment | Compresses response latencies below conventional threshold-based detection in Class A fault categories. |
| Industrial Monitoring Integration | Connects arc fault hardware with building management systems for uptime-critical Bavarian production lines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with electrical contractors, facility managers, utility procurement officers, and panelboard OEM engineers, cross-referenced against secondary sources including NEC code revision dockets, DIN VDE certification registries, FERC grid modernization filings, and customs trade data for semiconductor component flows. Bottom-up installation volume estimates triangulated against top-down construction spending allocations.
Calibration against historical adoption curves for comparable electrical safety mandates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, installation category, service relationship, and end-user decision authority, with CAGRs derived from regression analysis of code-mandated replacement cycles and grid-edge digitization investment trajectories. Utility smart grid capex disclosures and residential construction permit databases provided industry-specific forecast anchors.
Macroeconomic conditions sit as an overlay; deviation in copper commodity pricing and East Asian foundry utilization would shift the trajectory of hardware margins and component availability. Forecasts reflect assumptions regarding NEC adoption timeline continuity and IEC-UL harmonization progress. Cross-checking against Department of Energy grid modernization grant disbursement rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Moisture Detection Stickers Market
Detection and Regulation Devices
Portable Metal Detectors Market
Detection and Regulation Devices
Europe Portable Gas Detector Market
Detection and Regulation Devices
Temperature Detection Screen Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
Global Label-Free Detection Market
Detection and Regulation Devices
Global Gas Leak Detectors Market
Detection and Regulation Devices
Duct Smoke Detectors Market
Detection and Regulation Devices
Constant Current Regulator Market
Detection and Regulation Devices
Frequency Counter Market
Detection and Regulation Devices
Photoionization Detectors Market
Detection and Regulation Devices
Global Ultrasonic Air Bubble Detectors Market
Detection and Regulation Devices
Digital Underground Metal Detector Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Compliance Monitoring Devices Market
Detection and Regulation Devices
Automated Number Plate Recognition (ANPR) and Detection Sensors Market