
 Ultra Low Dropout Regulator (LDO) Market | 2026-2036
Ultra Low Dropout Regulator (LDO) Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra Low Dropout Regulator (LDO) Market Analytics
Automotive electronics is pivoting toward electrification and advanced driver-assistance platforms, reshaping procurement priorities across tier-one suppliers. Texas Instruments leverages its broad analog portfolio to anchor design wins across infotainment and battery management systems. Infineon Technologies dominates automotive-grade LDO supply through its vertically integrated fabrication network in Europe and Asia. ROHM Semiconductor specializes in ultra-low quiescent current architectures for start-stop vehicle applications.
An ultra low dropout regulator maintains output voltage regulation with minimal input-to-output differential, typically operating below 200 mV dropout at full load current to preserve system efficiency in battery-powered designs. CMOS technology leads volume production due to its compatibility with sub-micron digital processes and minimal static current draw, while GaN emerges in RF power amplifier biasing where switching noise rejection matters. Industrial controls represents a mature margin pool with long product lifecycles, whereas consumer electronics demands the fastest iteration cycles as smartphone OEMs compress design windows. BiCMOS variants occupy the premium tier by merging bipolar precision with CMOS density for instrumentation-grade stability.
The EPA enforces standby power limits that directly constrain LDO quiescent current specifications in US-bound equipment, while REACH compliance across Europe restricts hazardous substances in semiconductor packaging materials. China's SAMR aligns national GB standards with IEC frameworks for power converter efficiency tiers, creating dual certification burdens for multinational suppliers. Stakeholders must monitor how regional efficiency mandates diverge between North American and Asian testing methodologies when qualifying next-generation platforms.
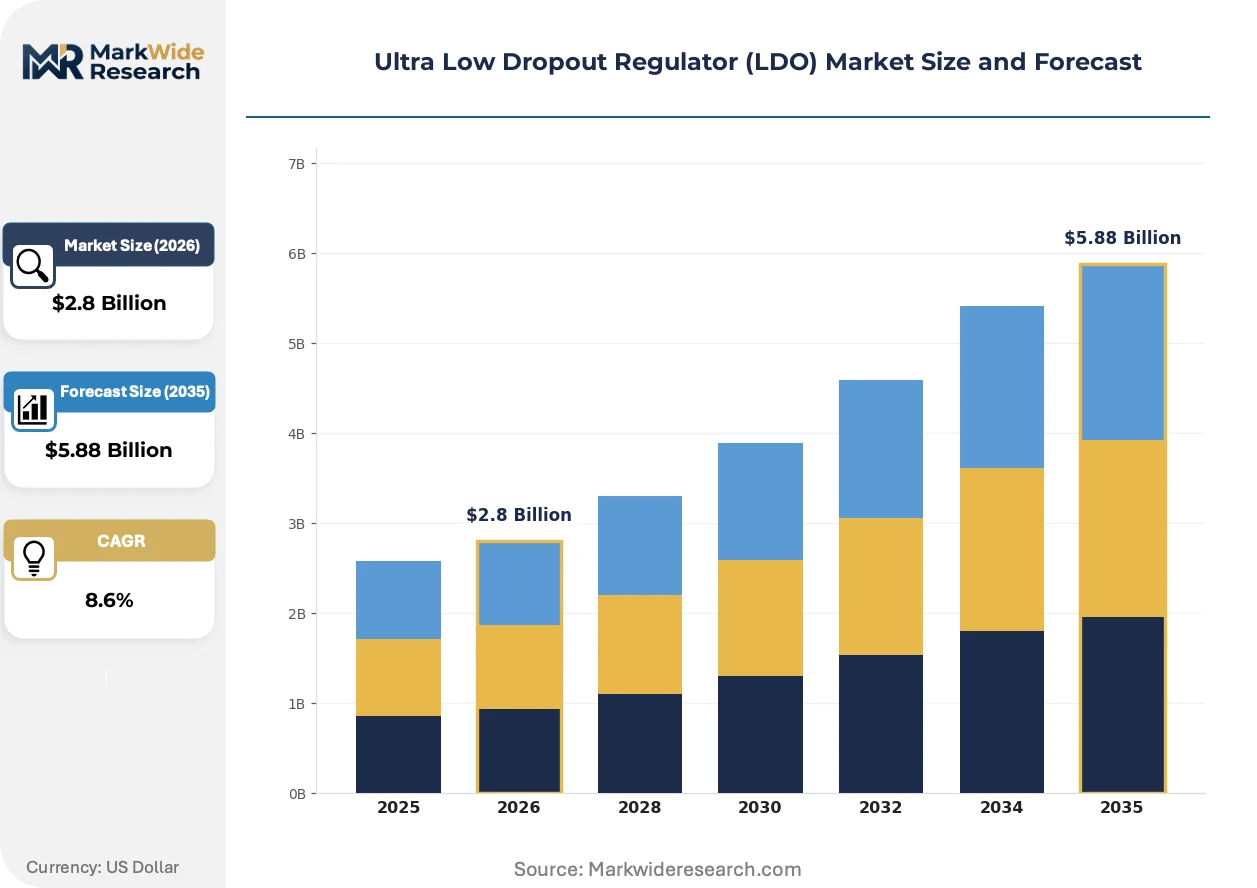
Market Dynamics
Automotive electrification and China's MIIT efficiency mandates are compressing design cycles for CMOS-based LDO architectures while concentrating procurement authority at tier-one module suppliers.
Growth Catalysts
- GB Standard Alignment:China's SAMR mandates stricter power efficiency tiers under GB regulations, forcing CMOS LDO adoption across domestic consumer electronics and industrial equipment supply chains.
- Automotive ADAS Integration:Advanced driver-assistance systems require ultra-low quiescent current regulators for camera modules and radar sensors, expanding LDO content per vehicle platform.
- East Asian Fabrication Clusters:South Korea's Gyeonggi Province and Taiwan's Hsinchu Science Park concentrate 300mm analog-capable foundry capacity, enabling cost-optimized LDO volume production.
Market Restraints
- Silicon Wafer Cost Volatility:300mm silicon-on-insulator substrates face price pressure from competing power semiconductor demand, squeezing gross margins on standard-grade LDOs.
- Foundry Concentration Risk:Analog-capable 40nm and larger process nodes concentrate at three major Taiwan-based foundries, creating geographic supply vulnerability.
- GaN Substitution in RF Biasing:Gallium nitride-based power stages displace LDOs in 5G base station and radar amplifier applications where switching noise tolerance has improved.
Strategic Opportunities
- BiCMOS Instrumentation Tier:Merging bipolar precision with CMOS density enables premium LDO architectures for test equipment and medical imaging with 10-year product lifecycles.
- India Electronics Manufacturing:PLI scheme incentives attract smartphone and appliance OEMs requiring locally sourced power management components.
- Industrial IoT Sensor Nodes:Sub-microamp quiescent current specifications open battery-powered environmental monitoring applications with decade-long deployment horizons.
Industry Challenges
- Analog Design Talent Scarcity:Mixed-signal LDO architecture expertise concentrates among engineers with 15-plus years of experience, constraining new product pipeline velocity.
- Dual Certification Burdens:Suppliers must qualify platforms under divergent EPA standby power testing methodologies and China's GB efficiency frameworks simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra Low Dropout Regulator (LDO) Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Linear Regulators, Switching Regulators, Low-Dropout Regulators, Voltage Reference Application: Consumer Electronics, Automotive Electronics, Telecommunication, Industrial Controls Technology: BiCMOS, BJT, CMOS, GaN End User: OEMs, Distributors, Retailers, Aftermarket Providers |
| Companies Covered | Texas Instruments, Analog Devices, onsemi, Infineon Technologies, STMicroelectronics, Microchip Technology, NXP Semiconductors, ROHM Semiconductor, Diodes Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra Low Dropout Regulator (LDO) Market Evolving Landscape
Silicon carbide and gallium nitride power stages are reshaping voltage regulation hierarchies, compressing the addressable space for traditional linear regulators while opening specialized biasing niches.
CMOS-based ultra low dropout architectures are overtaking BiCMOS alternatives in consumer electronics volume applications. Smartphone OEMs specify sub-100-microamp quiescent current for always-on camera and sensor subsystems. This technology shift is overtaking legacy bipolar designs in mid-tier handsets and wearables, forcing incumbent suppliers to retool 180nm process libraries or exit the segment.
REACH compliance across Europe restricts hazardous substances in semiconductor packaging materials, particularly lead-frame plating chemistries and mold compound flame retardants. LDO suppliers must reformulate qualified packages or risk exclusion from EU-bound industrial equipment. Medical device manufacturers face the tightest transition timelines as MDR certification cycles lock in component specifications years ahead of production.
Automotive tier-one suppliers now mandate AEC-Q100 Grade 0 qualification for start-stop system LDOs, compressing supplier approval cycles from 24 months to 14 months. Battery management system integrators in Germany's Baden-Württemberg cluster drive this acceleration, penalizing late qualification with volume allocation penalties. The specification escalation favors suppliers with captive automotive-grade fab capacity and existing Grade 0 portfolios.
Ultra Low Dropout Regulator (LDO) Market Segmentation
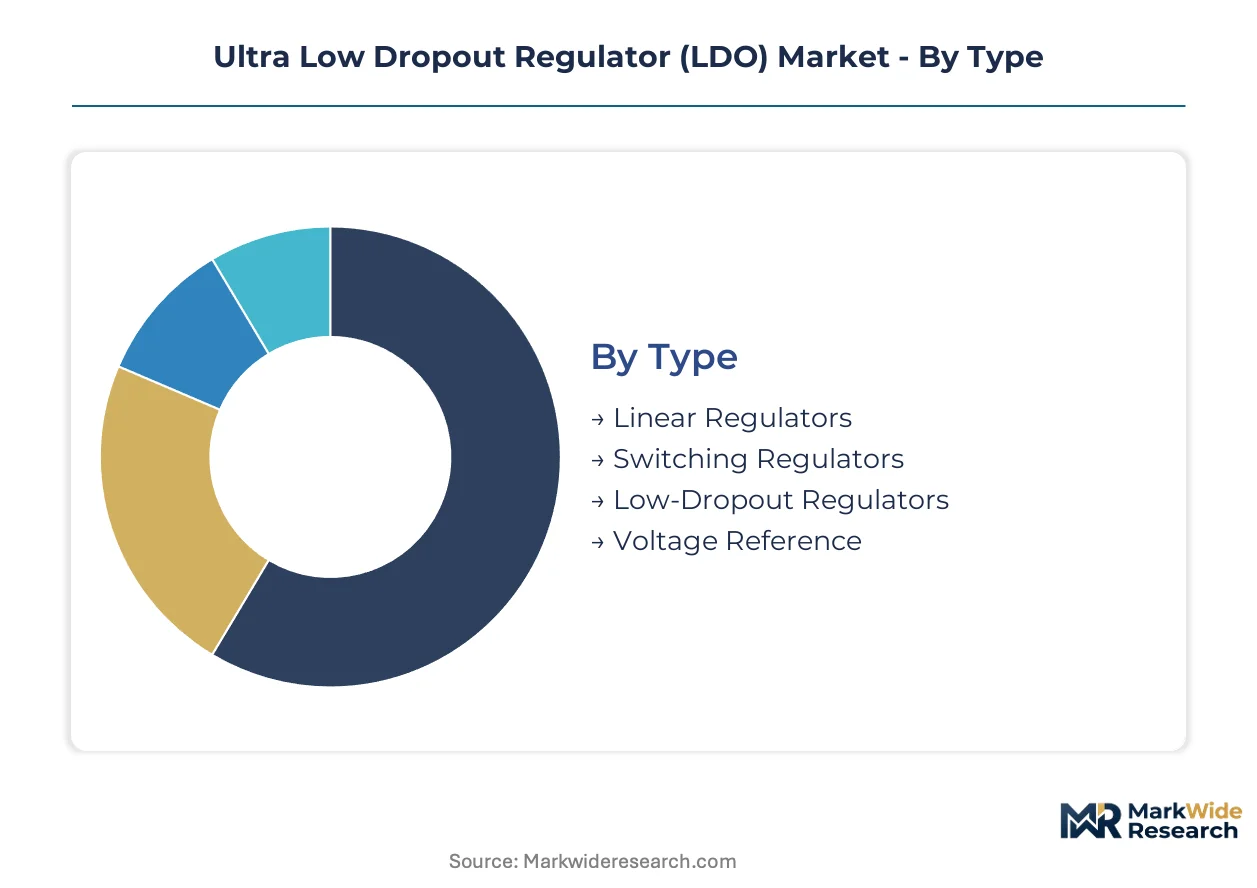
LDO procurement decisions hinge on trade-offs between dropout voltage, quiescent current, and noise performance that vary sharply across end-use environments. Segmentation reveals how automotive electrification and portable electronics are fragmenting technology roadmaps while concentrating volume in CMOS architectures.
Type:
Cost tier determines architecture selection, with premium applications absorbing higher silicon area for precision while commodity designs prioritize die size minimization.
- Linear Regulators:Simplest implementation using single-pass transistor topology without switching elements. Demand clusters in industrial sensor networks across Germany's Ruhr industrial belt, where electromagnetic compatibility requirements from KBA automotive directives favor noise-free operation over efficiency.
- Switching Regulators:Inductor-based buck or boost architectures achieving higher efficiency at cost of output ripple. Procurement concentrates in data center power distribution units in Loudoun County, Virginia, where EPA energy efficiency mandates for server infrastructure drive displacement of linear alternatives.
- Low-Dropout Regulators:Specialized linear subclass maintaining regulation with sub-200mV headroom. Smartphone camera modules in Shenzhen specify sub-50-microamp quiescent variants for always-on imaging subsystems.
- Voltage Reference:Precision temperature-compensated outputs for analog-to-digital converter biasing. Test equipment manufacturers in Tokyo's Ota ward require sub-10ppm drift specifications for instrumentation-grade stability.
Volume sits with Low-Dropout Regulators; growth tilts toward Switching Regulators.
Application:
Application maturity curves diverge sharply, with consumer electronics demanding 18-month design cycles while industrial controls lock specifications for decade-long production runs.
- Consumer Electronics:Smartphones, tablets, and wearables specifying sub-100-microamp quiescent current for battery endurance. Korea's Gyeonggi Province smartphone foundries drive CMOS LDO volume through compressed procurement timelines.
- Automotive Electronics:Battery management systems and ADAS camera modules requiring AEC-Q100 Grade 0 qualification. Tier-one suppliers in Baden-Württemberg mandate 14-month qualification cycles, penalizing late certification with volume allocation reductions.
- Telecommunication:5G base station power distribution and optical module biasing. China's MIIT efficiency standards under GB regulations push CMOS adoption in domestic equipment procurement.
- Industrial Controls:Programmable logic controllers and motor drive electronics with 10-year lifecycle requirements. European REACH compliance restricts packaging materials, forcing reformulation of qualified packages for EU-bound equipment.
Automotive Electronics commands premium pricing; Consumer Electronics expands most quickly.
Technology:
Process node availability constrains technology selection, with 40nm analog-capable foundry capacity concentrating at Taiwan-based facilities.
- BiCMOS:Merged bipolar-CMOS process delivering precision reference voltages with CMOS density. Medical imaging equipment in Boston's Route 128 corridor specifies BiCMOS LDOs for decade-long deployment horizons under FDA device regulations.
- BJT:Legacy bipolar junction transistor designs offering lowest noise floors at cost of higher quiescent current. Niche demand persists in professional audio equipment where signal integrity outweighs battery life constraints.
- CMOS:Dominant volume technology compatible with sub-micron digital processes and minimal static current draw. Smartphone OEMs in Taiwan's Hsinchu Science Park specify CMOS LDOs for sub-50-nanometer system-on-chip integration.
- GaN:Gallium nitride emerging in RF power amplifier biasing where switching noise rejection has improved. 5G base station deployments in Stockholm's Kista district displace traditional LDOs in high-frequency applications.
CMOS captures volume leadership; GaN gains share fastest in RF biasing niches.
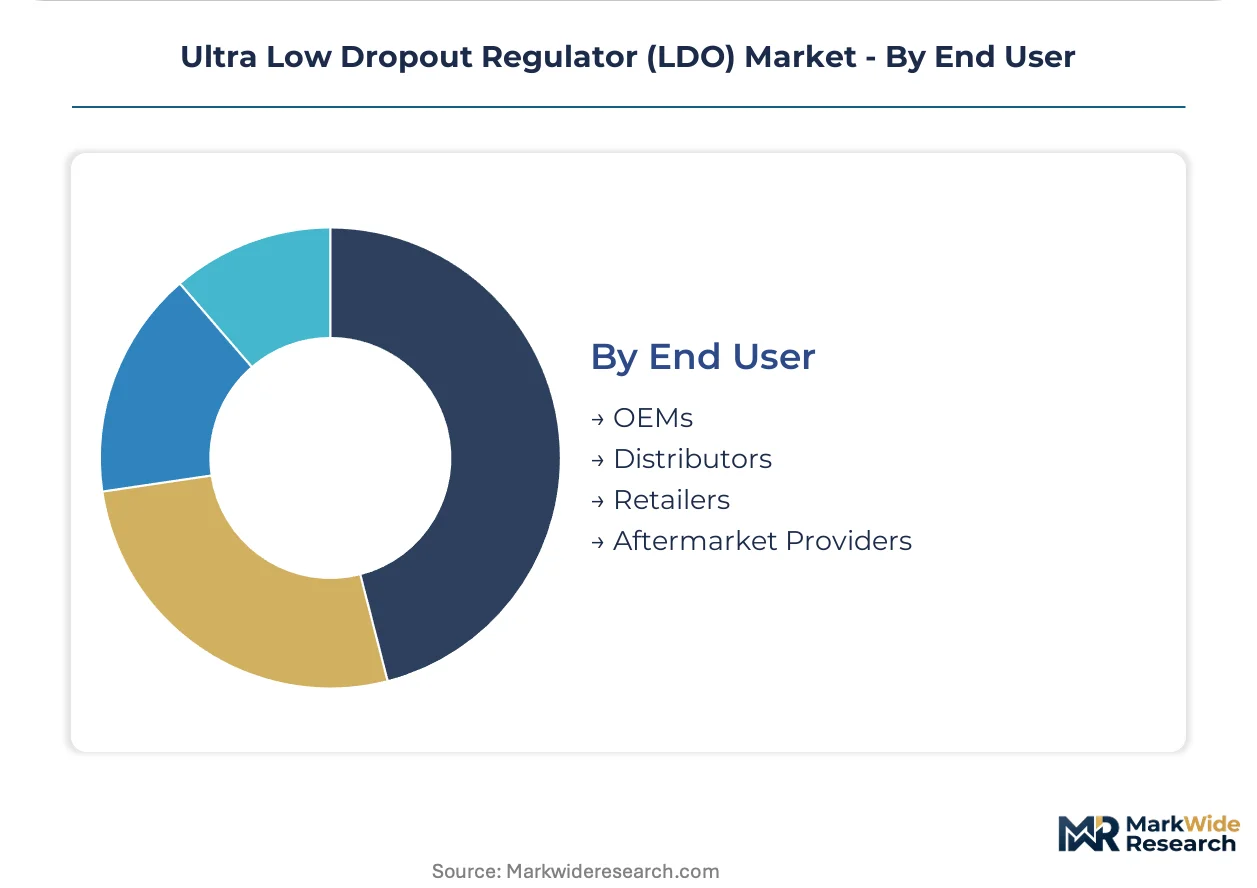
End User:
Channel structure determines margin capture, with direct OEM relationships locking multi-year supply agreements while aftermarket channels fragment pricing power.
- OEMs:Original equipment manufacturers integrating LDOs into system-level designs with captive specification authority. Automotive OEMs in Stuttgart negotiate 36-month pricing agreements with qualified suppliers.
- Distributors:Arrow, Avnet, and regional players stocking standard-grade LDOs for mid-volume industrial customers. Inventory concentration in Singapore's Changi logistics hub serves Southeast Asian contract manufacturers.
- Retailers:Component retailers serving hobbyist and repair markets with limited technical support requirements. Online channels in Shenzhen's Huaqiangbei electronics market dominate small-quantity procurement.
- Aftermarket Providers:Third-party repair and refurbishment services requiring drop-in replacements with minimal redesign. Automotive aftermarket in Michigan's Detroit corridor sources AEC-Q100 qualified parts for warranty-compliant repairs.
OEMs anchor volume commitments; Distributors provide the steepest expansion trajectory through design-win aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors CMOS LDO fabrication capacity through Taiwan's analog-capable foundry ecosystem, while China's MIIT efficiency mandates and South Korea's smartphone manufacturing clusters concentrate demand across three distinct regulatory environments.
United States
Automotive battery management systems and data center infrastructure drive LDO procurement from tier-one module suppliers. EPA standby power limits constrain quiescent current specifications for equipment bound across domestic and export markets. Design activity clusters in Silicon Valley and Austin, where fabless analog houses qualify CMOS architectures for consumer electronics integration.
Germany
Automotive electrification and industrial automation equipment absorb premium-grade LDO volumes from Baden-Württemberg tier-one suppliers. KBA automotive directives enforce electromagnetic compatibility standards that favor noise-free linear regulation over switching alternatives. The Ruhr industrial belt maintains demand for industrial sensor networks requiring long-lifecycle component qualification.
China
Domestic smartphone OEMs and 5G base station deployments compress CMOS LDO procurement timelines under MIIT efficiency mandates. SAMR aligns GB standards with IEC frameworks, creating dual certification burdens for multinational suppliers. Shenzhen's electronics manufacturing corridor specifies sub-50-microamp quiescent variants for always-on camera subsystems.
South Korea
Gyeonggi Province smartphone foundries drive volume demand for sub-100-microamp CMOS LDOs in flagship handset platforms. The country's national semiconductor regulator enforces power efficiency benchmarks aligned with global IEC frameworks. Samsung and LG supply chains anchor procurement authority with compressed 18-month design cycles.
Japan
Precision instrumentation and medical imaging equipment sustain BiCMOS LDO demand in Tokyo's Ota ward manufacturing corridor. METI industrial standards govern power management component efficiency tiers for domestic and export equipment. Automotive suppliers in Nagoya's Chubu region qualify AEC-Q100 Grade 0 variants for start-stop system integration.
Ultra Low Dropout Regulator (LDO) Market Competitive Landscape
Top-tier vendors anchor premium automotive and industrial segments, while mid-tier analog specialists capture consumer electronics volume through cost-optimized CMOS platforms. The vendor base stratifies across captive fab operators, fabless design houses, and diversified semiconductor conglomerates. Three archetypes dominate: vertically integrated European-Japanese automotive-grade suppliers, US-based broad analog portfolio vendors, and Asian-focused CMOS volume producers. Competitive moves concentrate on AEC-Q100 qualification acceleration and 40nm analog-capable foundry capacity reservation.
Within the automotive-grade tier, Infineon Technologies and ROHM Semiconductor exemplify vertically integrated fabrication strategies that compress supplier approval cycles. Texas Instruments anchors the broad analog portfolio archetype through design wins spanning infotainment and battery management systems. STMicroelectronics occupies a position bridging European industrial demand with Asian consumer electronics volume through diversified foundry relationships.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| onsemi |
| Infineon Technologies |
| STMicroelectronics |
| Microchip Technology |
| NXP Semiconductors |
| ROHM Semiconductor |
| Diodes Incorporated |
| Others |
Value Network & Pricing Analysis
Automotive tier-one suppliers in Baden-Württemberg demanding 14-month AEC-Q100 Grade 0 qualification cycles are forcing foundries to prioritize premium automotive capacity, compressing spot availability for standard-grade CMOS LDOs and widening price spreads between certified and uncertified tiers.
Pricing Analysis
Expedited lead-time premiums of 20-40% apply to automotive-grade CMOS LDOs as tier-one suppliers in Stuttgart negotiate 36-month pricing agreements while spot buyers absorb volatility. Three-tier pricing structure across AEC-Q100 Grade 0, industrial-grade, and consumer-grade tiers separates qualification investment from die cost. Pricing pressure stems from 300mm silicon-on-insulator substrate cost volatility competing with power semiconductor demand. Consumer electronics OEMs in Shenzhen exhibit highest price sensitivity, while medical device manufacturers in Boston's Route 128 corridor absorb premium BiCMOS pricing for decade-long lifecycle security.
Supply Chain Analysis
300mm silicon wafer supply rests on Japanese specialty chemical producers for photoresist and Taiwanese foundries for analog-capable 40nm process nodes. Raw material dependencies include silicon-on-insulator substrates, copper lead frames, and epoxy mold compounds subject to REACH restrictions. Single-source vulnerability concentrates at three Taiwan-based foundries controlling analog-capable capacity. Distribution runs through Arrow and Avnet aggregating design wins for mid-volume industrial customers, with Singapore's Changi logistics hub serving Southeast Asian contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
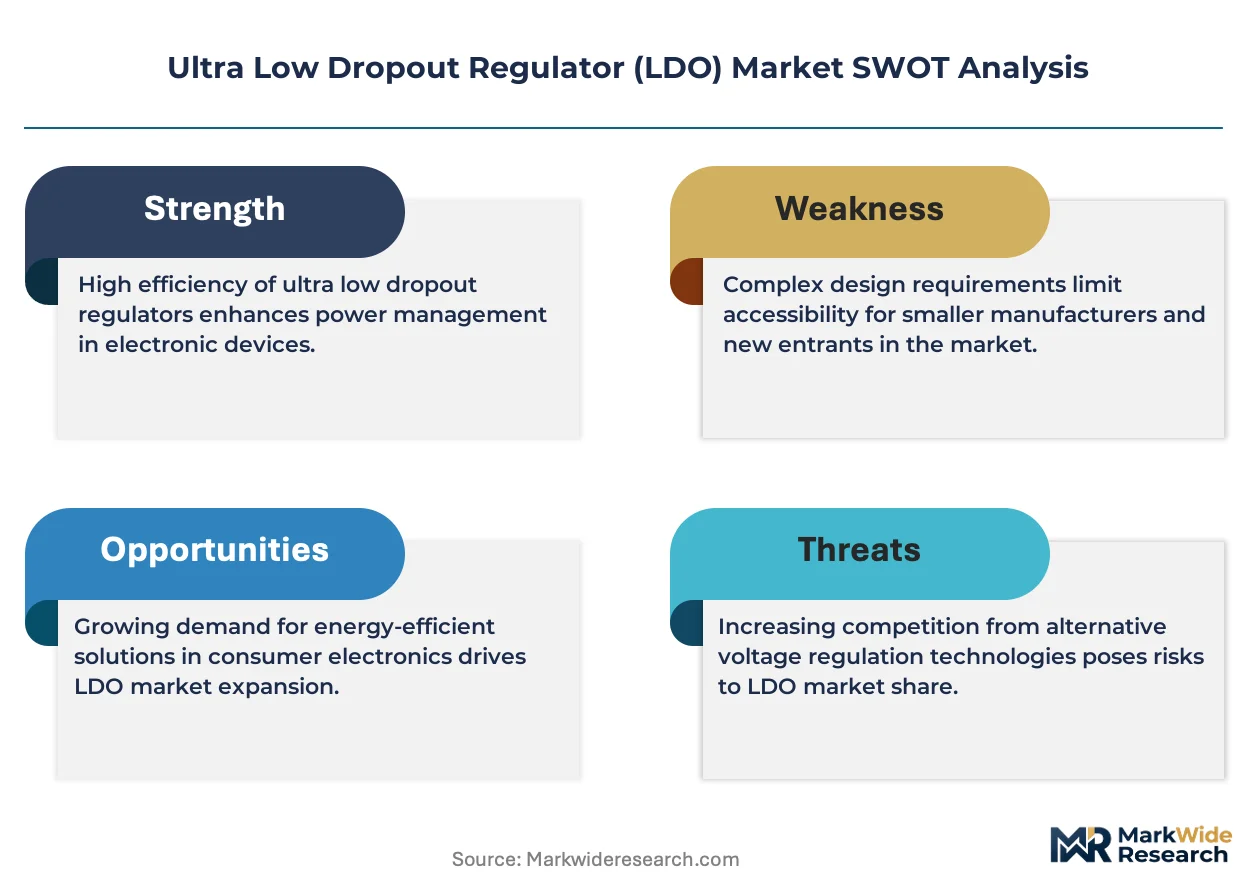
This market operates as a cost-of-compliance story where China's MIIT GB efficiency mandates and AEC-Q100 Grade 0 automotive qualification create barrier-to-entry moats favoring incumbent suppliers with captive fab capacity and existing certification portfolios.
For Market Incumbents: Deploy AEC-Q100 Grade 0 qualification acceleration as the priority lever against GaN substitution threats in RF biasing applications. Backward integration into 300mm analog-capable foundry capacity in Taiwan's Hsinchu Science Park secures allocation priority as automotive procurement concentrates at tier-one suppliers. Channel control through direct OEM relationships in Stuttgart and Baden-Württemberg locks 36-month pricing agreements that insulate margin erosion from spot market volatility. For New Entrants and Emerging Players: Distributors in Singapore's Changi logistics hub provide the fastest path to revenue for standard-grade CMOS LDOs serving mid-volume industrial customers. India's PLI scheme incentives for smartphone OEMs create the most penetrable geography for sub-100-microamp quiescent current variants. White-space targets include battery-powered industrial IoT sensor nodes requiring sub-microamp specifications and decade-long deployment horizons underserved by incumbent automotive-focused portfolios. For Investors and Strategic Acquirers: The window for entry favors vertically integrated analog specialists with captive automotive-grade fab capacity and existing AEC-Q100 Grade 0 portfolios. Long-term viability hinges on qualification pipeline velocity and foundry relationships spanning the projection horizon. Watch for MIIT GB standard enforcement intensity as the signal indicating whether Chinese domestic OEM procurement shifts decisively toward CMOS architectures or retains bipolar legacy designs.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Grade 0 Qualification Acceleration | Compresses supplier approval cycles from 24 months to 14 months for automotive tier-one allocation. |
| 40nm Analog-Capable Foundry Capacity Reservation | Secures allocation priority at Taiwan-based foundries as analog design talent scarcity constrains new entrants. |
| Sub-Microamp Quiescent Current Architecture Development | Opens battery-powered industrial IoT sensor node applications with decade-long deployment requirements. |
| REACH-Compliant Packaging Reformulation | Maintains EU market access as ECHA restrictions tighten on lead-frame plating chemistries and mold compounds. |
| India PLI Scheme Localization Partnership | Captures smartphone OEM procurement shifting to locally sourced power management components under BIS alignment. |
Research Methodology
Multi-period observation of AEC-Q100 qualification timelines, MIIT GB standard enforcement patterns, and foundry capacity utilization anchored the trend analysis, supplemented by interviews with analog design directors at fabless semiconductor houses, procurement managers at automotive tier-one suppliers in Baden-Württemberg, foundry account executives at Taiwan-based analog-capable facilities, and power management architects at smartphone OEMs in Shenzhen. Secondary validation drew from SEC 10-K filings, MIIT regulatory bulletins, ECHA REACH substance restriction updates, and IHS Markit vehicle production databases. Bottom-up die-cost modeling and top-down market sizing triangulated volume and value estimates.
Input-output matrices mapped CMOS process node availability against end-use demand segments across the projection horizon, modeling technology adoption curves by dropout voltage, quiescent current, and noise performance requirements. Segmentation dimensions included regulator architecture type, application vertical, process technology node, and end-user channel structure. CAGRs derived from regression analysis of historical penetration rates and forward-looking procurement intent signals from tier-one supplier roadmaps. Industry-specific forecast inputs incorporated EPA standby power limit trajectory and SAMR GB standard alignment pace with IEC frameworks.
Caveats apply where silicon wafer cost volatility, foundry concentration risk, or GaN substitution acceleration in RF biasing could materially shift the outlook. A small set of triggers—MIIT enforcement intensity, AEC-Q100 Grade 0 qualification pipeline velocity, and 300mm analog-capable capacity expansion decisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Voltage Detector Market
Detection and Regulation Devices
Electronic Article Surveillance Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Europe Trace Detection Market
Detection and Regulation Devices
X-Ray Detectors Market
Detection and Regulation Devices
Temperature Modulation Devices Market
Detection and Regulation Devices
Voltage Detection System Market
Detection and Regulation Devices
Positive Temperature Coefficient (PTC) Thermistor Market
Detection and Regulation Devices
Explosive Detectors Market
Detection and Regulation Devices
Magnetic Crack Detectors Market
Detection and Regulation Devices
Global Gas Sensors Market
Detection and Regulation Devices
Duct Smoke Detectors Market
Detection and Regulation Devices
Null Detector Market
Detection and Regulation Devices
Infrared Detection Chip Market
Detection and Regulation Devices
Digital Underground Metal Detector Market
Detection and Regulation Devices
Surge Suppression IC Market