
 Global Ultrasonic Air Bubble Detectors Market | 2026-2036
Global Ultrasonic Air Bubble Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ultrasonic Air Bubble Detectors Market Intelligence
Asian sensor foundries is rebalancing output toward medical-grade ultrasonic modules as OEMs diversify beyond consumer electronics. SONOTEC GmbH leverages its Dresden engineering base to dominate high-precision clamp-on designs for dialysis circuits. Sensaras LLC anchors North American supply through vertically integrated MEMS fabrication in New York. Introtek International competes on modular platforms that simplify integration for pharmaceutical tubing OEMs.
Ultrasonic air bubble detectors employ piezoelectric transducers operating at frequencies between 1 MHz and 10 MHz to identify gas inclusions in liquid-filled lines without fluid contact, serving critical safety functions in extracorporeal circuits and precision dosing systems. Inline detectors occupy the largest installed base due to permanent integration into hemodialysis machines and infusion pumps, while clamp-on variants register the fastest expansion as retrofit demand rises among wastewater operators and legacy pharmaceutical lines. Through-transmission technology leads in revenue terms because dual-transducer architectures deliver the reliability margins required by FDA and EMA for Class II medical devices.
FDA 510(k) premarket notification and EU MDR conformity assessment compel manufacturers to document acoustic sensitivity thresholds and biocompatibility profiles, raising barriers for unvalidated entrants. China's NMPA has harmonized its technical review standards with IEC 60601-1-8 alarm systems requirements, accelerating local certification timelines for domestic brands like Siansonic. Stakeholders must monitor divergence between FDA software-as-medical-device guidance and EU AI Act risk classification for next-generation detectors incorporating adaptive threshold algorithms.
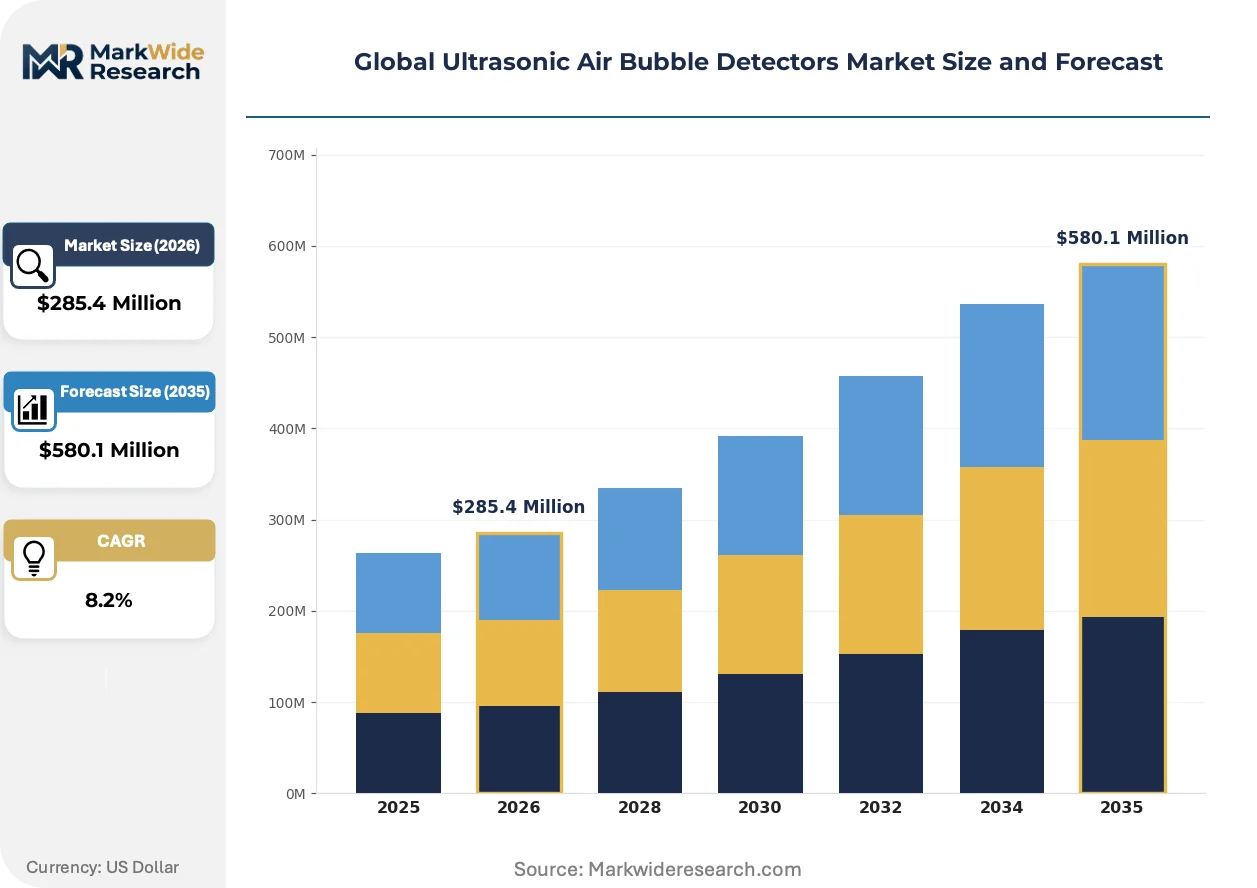
Market Dynamics
Clamp-on ultrasonic architectures are displacing inline installations across pharmaceutical and wastewater retrofit segments, compressing replacement cycles while forcing incumbent suppliers to reengineer transducer housings for non-invasive mounting.
Growth Catalysts
- EU MDR Class II device mandates:Tightened conformity assessment for hemodialysis safety sensors compels OEMs to source validated detectors, expanding procurement volumes for certified suppliers.
- Home dialysis expansion:Portable renal care devices require miniaturized bubble detection modules, pulling MEMS fabrication capacity toward medical-grade ultrasonic arrays.
- Frequency agility in transducer design:Tunable piezoelectric elements operating across 1-10 MHz ranges enable single detectors to serve multiple fluid viscosities, broadening addressable applications.
Market Restraints
- PZT ceramic supply concentration:Lead zirconate titanate feedstock for piezoelectric elements concentrates in Chinese refining operations, exposing transducer manufacturers to input volatility and export licensing friction.
- FDA 510(k) validation timelines:Extended acoustic sensitivity documentation requirements delay market entry for adaptive threshold algorithms, freezing software-enhanced products in premarket queues.
- Optical bubble detection substitution:Photoelectric sensors with comparable response times threaten clamp-on ultrasonic variants in non-medical fluid handling where biocompatibility certification is unnecessary.
Strategic Opportunities
- India's CDSCO harmonization pathway:Convergence with IEC 60601-1-8 alarm standards accelerates approval timelines for domestic manufacturers, opening import substitution opportunities in South Asian dialysis equipment supply chains.
- Adaptive AI threshold algorithms:Machine learning-enabled sensitivity adjustment converges with ultrasonic hardware, enabling predictive maintenance contracts and recurring revenue streams in critical care settings.
- Wastewater treatment retrofit demand:Legacy chemical dosing lines in municipal plants seek non-invasive bubble detection without line shutdown, creating aftermarket channels distinct from medical OEM supply.
Industry Challenges
- Acoustic engineer scarcity:Specialized expertise in piezoelectric transducer design and fluid dynamics modeling concentrates in German and Japanese industrial clusters, constraining R&D scaling for new entrants.
- Legacy system integration complexity:Proprietary communication protocols in installed hemodialysis machines resist standard digital outputs from modern detectors, forcing costly interface engineering for replacement sales.
- Biocompatibility certification timelines:ISO 10993 testing for blood-contacting sensor housings extends product development cycles, compressing window for technology refresh before design freeze deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ultrasonic Air Bubble Detectors Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $580.1 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Detectors, Portable Detectors, Clamp-on Detectors, Handheld Detectors Technology: Pulse-Echo, Through-Transmission, Time-of-Flight, Doppler, Phased Array Application: Pharmaceutical Manufacturing, Semiconductor Fabrication, Food Processing, Water Treatment Facilities, Chemical Processing End User: Biotech Firms, Electronics Manufacturers, Beverage Producers, Wastewater Operators |
| Companies Covered | Introtek International, Sensaras LLC, SONOTEC GmbH, Siansonic, BIOSONIX, Moog Inc., Meggitt PLC, TE Connectivity Ltd., Strain Measurement Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ultrasonic Air Bubble Detectors Market Strategic Shifts & Innovations
Sensor miniaturization and algorithmic sensitivity adjustment are compressing form factors while expanding detection reliability margins, reshaping procurement criteria across both medical device OEMs and industrial fluid handlers.
MEMS-based ultrasonic transducers are overtaking conventional bulk piezoelectric elements in portable dialysis and infusion pump applications. Wearable renal care device manufacturers in Germany and the United States are adopting chip-scale acoustic arrays to reduce housing volume by half. This shift is overtaking established ceramic transducer supply relationships and forcing foundries to requalify wafer-level packaging for medical reliability standards.
EU MDR Annex I general safety and performance requirements now mandate traceable acoustic sensitivity thresholds for Class II bubble detectors used in extracorporeal circuits. Manufacturers must document transducer degradation curves across sterilization cycles, adding validation costs that favor established suppliers with existing technical files. Hemodialysis machine producers in Italy and the Netherlands are consolidating supplier panels to reduce audit burden, concentrating procurement among pre-certified vendors.
After-sales service unbundling is separating hardware supply from calibration and recertification contracts. Hospital procurement departments in France and Japan now negotiate detector purchases independently from multi-year maintenance agreements, pressuring OEMs to disclose replacement part pricing and firmware update schedules. This fragmentation is most visible in academic medical centers with dedicated biomedical engineering staff capable of in-house acoustic validation testing.
Global Ultrasonic Air Bubble Detectors Market Segmentation
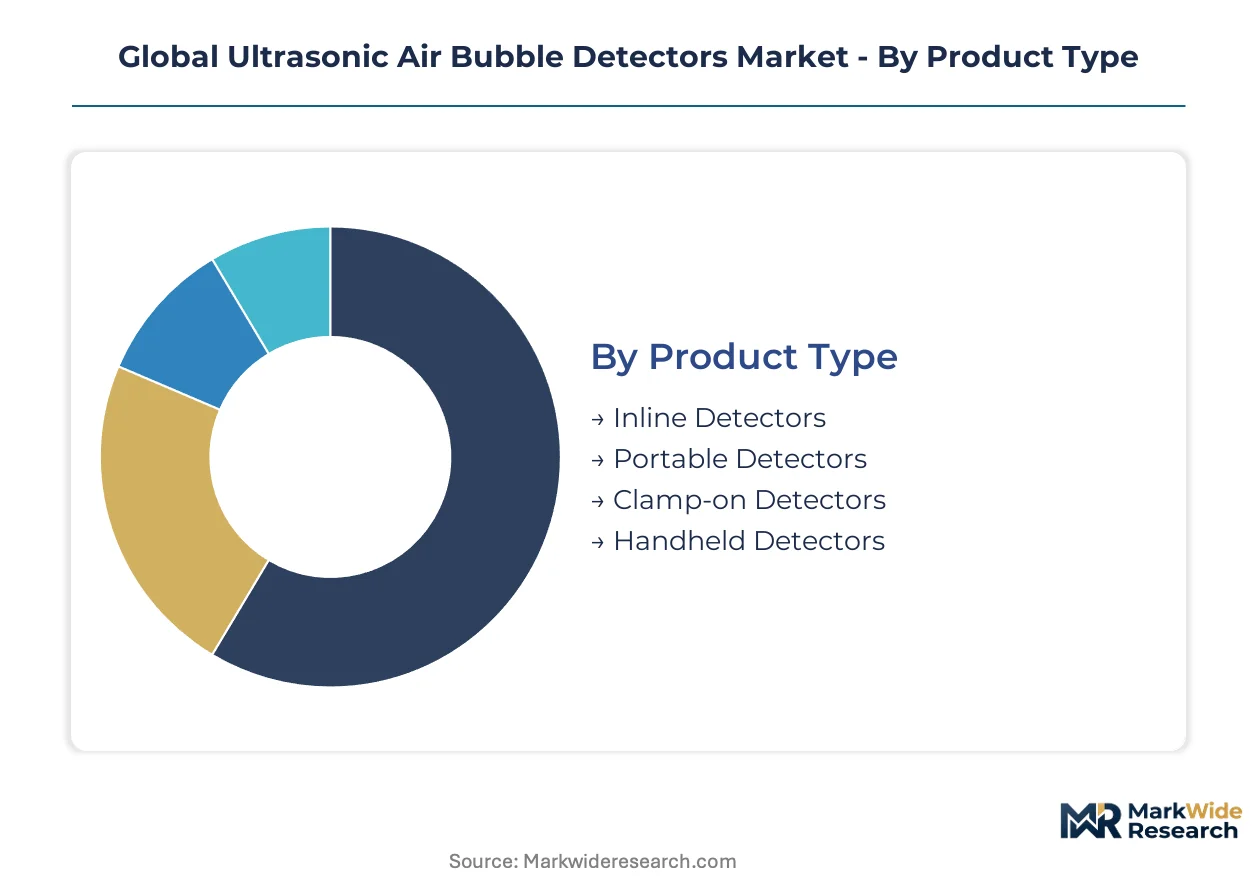
Segmentation reveals how ultrasonic air bubble detector architectures align with distinct integration depths and regulatory burdens across medical and industrial fluid systems. Procurement patterns diverge sharply between permanently embedded safety sensors and portable validation tools.
Product Type:
Integration depth separates permanently mounted safety-critical installations from mobile diagnostic equipment, with each tier carrying distinct validation requirements and replacement economics.
- Inline Detectors:These units mount permanently within fluid lines using bonded transducer housings that meet ISO 10993 biocompatibility standards for blood-contacting surfaces. Demand concentrates in hemodialysis machine production at Fresenius Medical Care and Baxter manufacturing facilities in Germany and the United States, where FDA 510(k) premarket notification requirements compel documented acoustic sensitivity thresholds across sterilization cycles.
- Clamp-on Detectors:Non-invasive architectures attach externally to existing tubing without line shutdown, utilizing elastomeric coupling gels to transmit ultrasonic energy through polymer walls. Wastewater operators in China's municipal treatment plants drive fastest expansion as retrofit demand accelerates without the biocompatibility certification burdens of medical applications.
- Portable Detectors:Battery-powered validation tools for field calibration and spot-checking of fluid lines in pharmaceutical packaging operations.
- Handheld Detectors:Compact single-point inspection devices for maintenance technicians verifying bubble presence in legacy chemical processing equipment.
Volume placements concentrate in Inline Detectors; the faster expansion belongs to Clamp-on Detectors.
Technology:
Signal processing architectures determine detection reliability margins and regulatory acceptance thresholds, with dual-transducer designs commanding premium positioning in safety-critical medical applications.
- Through-Transmission:Dual-transducer configurations position emitter and receiver on opposite tube walls, measuring acoustic attenuation across the fluid column to identify gas inclusions with quantifiable confidence intervals. This architecture dominates hemodialysis safety circuits where FDA Class II device mandates require documented failure-mode probabilities, with German dialysis equipment OEMs specifying through-transmission modules exclusively for extracorporeal blood lines.
- Pulse-Echo:Single-transducer designs emit ultrasonic pulses and analyze reflected echoes from acoustic impedance boundaries, reducing component count and housing complexity. Portable dialysis device manufacturers in Japan and the United States favor pulse-echo modules for home renal care equipment where miniaturization constraints override absolute sensitivity requirements.
- Time-of-Flight:Measures ultrasonic pulse transit time variations caused by gas-liquid interface disruptions in high-purity semiconductor chemical delivery systems.
- Doppler:Detects frequency shifts from moving bubble interfaces in flowing lines, applied primarily in industrial slurry processing where particle-laden fluids complicate transmission-based methods.
- Phased Array:Electronically steered beamforming enables spatial mapping of bubble distributions in large-diameter pharmaceutical mixing vessels.
Revenue concentration sits with Through-Transmission; the steepest expansion trajectory belongs to Pulse-Echo as portable medical applications multiply.
Application:
Fluid purity requirements and contamination consequences shape detector specification intensity, with human-safety applications imposing the most stringent validation protocols.
- Pharmaceutical Manufacturing:Parenteral drug filling lines require continuous bubble monitoring to prevent air embolism risks in injectable products, with EU MDR Annex I general safety mandates now extending to pharmaceutical packaging equipment. Italian and Dutch filling machine producers consolidate supplier panels to reduce audit burden, concentrating procurement among pre-certified ultrasonic vendors with existing technical files documenting transducer degradation curves.
- Water Treatment Facilities:Chemical dosing accuracy depends on bubble-free reagent delivery in membrane filtration and disinfection systems. Municipal operators in France and Japan now unbundle detector purchases from maintenance contracts, pressuring OEMs to disclose replacement part pricing and firmware update schedules.
- Semiconductor Fabrication:Ultrapure chemical delivery systems in Taiwan and South Korea fabs demand sub-millimeter bubble detection in photoresist and etchant lines.
- Food Processing:Aseptic beverage filling operations use clamp-on detectors to verify deaeration effectiveness without product contact.
- Chemical Processing:Corrosive fluid handling in German and Japanese petrochemical clusters requires chemically resistant transducer housings.
Procurement volume clusters in Pharmaceutical Manufacturing; Food Processing gains share fastest as clamp-on retrofit penetration accelerates.
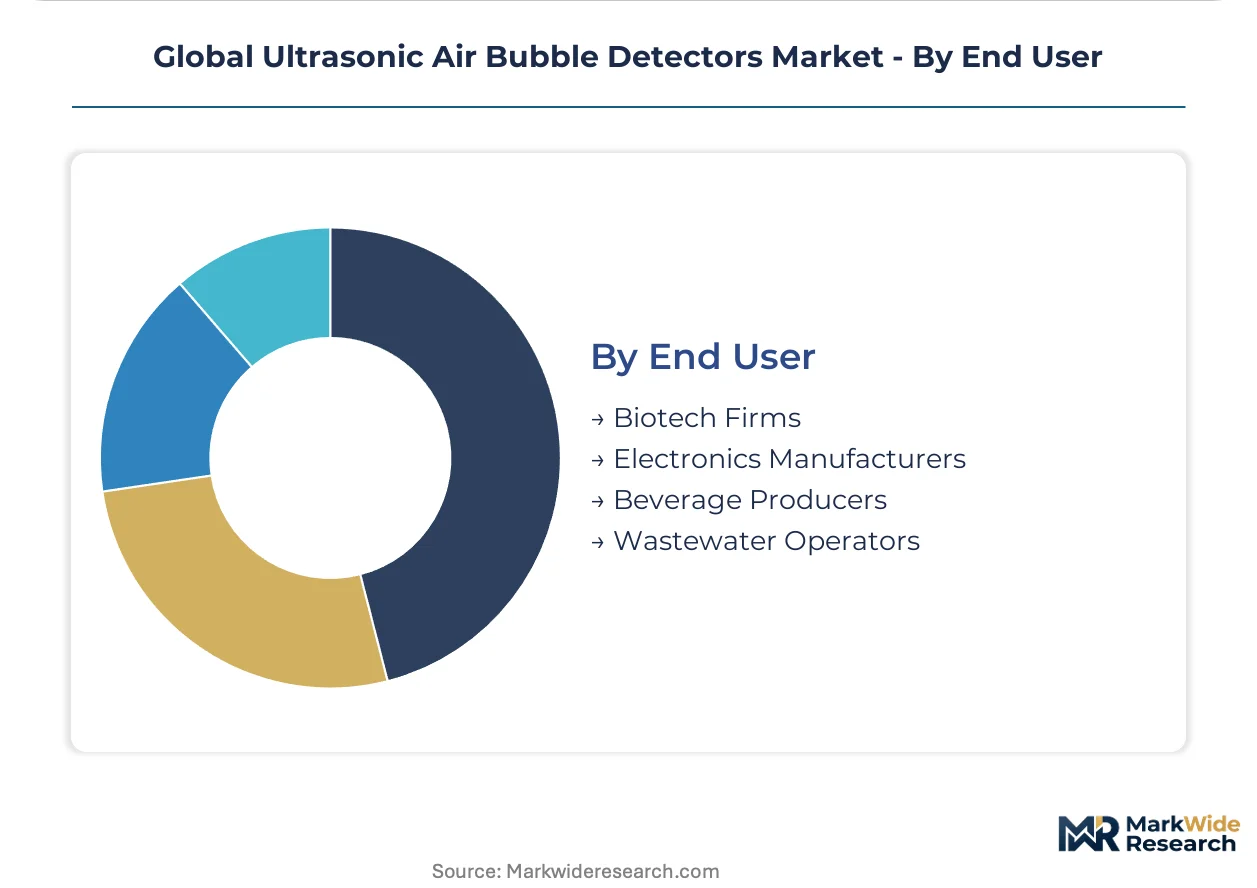
End User:
Customer technical capabilities and regulatory exposure determine whether detectors are sourced as integrated subsystems or standalone validation equipment.
- Biotech Firms:Cell culture perfusion systems and chromatography skids require continuous bubble detection to protect protein product integrity, with single-use bioreactor adoption driving demand for gamma-sterilizable detector modules. Massachusetts and California biotech clusters specify pre-validated sensor assemblies to compress facility commissioning timelines.
- Wastewater Operators:Municipal treatment plants in China's Yangtze River basin retrofit legacy chemical dosing lines with non-invasive clamp-on detectors, avoiding pipeline shutdown costs that would trigger regulatory discharge violations. This aftermarket channel operates with shorter procurement cycles and less stringent documentation requirements than medical OEM supply.
- Electronics Manufacturers:Semiconductor fabs in Hsinchu and Pyeongtaek integrate bubble detection into chemical delivery unit process equipment.
- Beverage Producers:Carbonated soft drink bottlers in São Paulo and Mexico City deploy portable detectors for line validation during product changeovers.
Revenue concentration aligns with Biotech Firms; Wastewater Operators expand most quickly as municipal infrastructure retrofit budgets grow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lead zirconate titanate refining operations concentrate in Chinese industrial zones, anchoring transducer feedstock supply for detector manufacturers worldwide. Germany, the United States, and China dominate installed capacity and regulatory standard-setting for medical-grade ultrasonic modules.
United States
Fresenius Medical Care and Baxter manufacturing facilities in Massachusetts and California drive inline detector procurement for hemodialysis machine production. FDA 510(k) premarket notification requirements compel documented acoustic sensitivity thresholds across sterilization cycles. The Greater Boston biotech cluster specifies pre-validated sensor assemblies to compress facility commissioning timelines for cell culture perfusion systems.
Germany
Dialysis equipment OEMs in Dresden and surrounding Saxony specify through-transmission modules exclusively for extracorporeal blood lines. EU MDR Annex I general safety and performance requirements mandate traceable acoustic sensitivity thresholds for Class II bubble detectors. Italian and Dutch filling machine producers consolidate supplier panels to reduce audit burden, concentrating procurement among German pre-certified vendors with existing technical files.
China
Municipal wastewater treatment plants in the Yangtze River basin retrofit legacy chemical dosing lines with non-invasive clamp-on detectors. NMPA harmonization with IEC 60601-1-8 alarm systems requirements accelerates local certification timelines for domestic brands. Shanghai and Shenzhen sensor foundries rebalance output toward medical-grade ultrasonic modules as OEMs diversify beyond consumer electronics.
Japan
Portable dialysis device manufacturers in Tokyo and Osaka favor pulse-echo modules for home renal care equipment where miniaturization constraints override absolute sensitivity requirements. METI standards align with international medical device quality frameworks. Hospital procurement departments in academic medical centers now negotiate detector purchases independently from multi-year maintenance agreements.
India
CDSCO harmonization with IEC 60601-1-8 alarm standards accelerates approval timelines for domestic manufacturers. Maharashtra and Karnataka-based dialysis equipment supply chains present import substitution opportunities as South Asian renal care infrastructure expands. Local biomedical engineering staff at academic medical centers perform in-house acoustic validation testing, enabling service unbundling.
Global Ultrasonic Air Bubble Detectors Market Key Industry Players
Global majors compete with regional champions across certification depth and transducer precision tiers. The vendor base stratifies between vertically integrated MEMS fabricators, specialized clamp-on designers, and diversified industrial sensor conglomerates. Three archetypes dominate: precision-focused German engineering houses, North American MEMS-integrated suppliers, and Asian cost-optimized volume producers. Competitive moves concentrate on backward integration into PZT ceramic supply and adaptive algorithm licensing partnerships.
Among German engineering houses, SONOTEC GmbH exemplifies the precision-focused archetype through its Dresden-based operations. Sensaras LLC anchors North American supply capabilities. Introtek International occupies a position within the modular platform tier, serving pharmaceutical tubing OEM integration requirements. Siansonic represents the Asian domestic certification pathway, leveraging NMPA harmonization to accelerate local timelines.
| Leading Market Players |
|---|
| Introtek International |
| Sensaras LLC |
| SONOTEC GmbH |
| Siansonic |
| BIOSONIX |
| Moog Inc. |
| Meggitt PLC |
| TE Connectivity Ltd. |
| Strain Measurement Devices |
| Others |
Cost & Logistics Intelligence
Lead zirconate titanate spot pricing volatility in Chinese refining zones cascades through transducer manufacturing into three distinct detector pricing tiers, with medical-grade modules commanding substantial premiums over industrial retrofit variants due to ISO 10993 biocompatibility certification burdens and FDA 510(k) validation documentation requirements.
Pricing Analysis
Service-bundling unbundling separates hardware procurement from multi-year calibration contracts, with hospital purchasing committees in France and Japan now negotiating detector acquisitions independently from maintenance agreements. Pricing stratifies across premium certified-medical, standard industrial-process, and economy wastewater-monitoring tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in the economy tier intensifies as optical bubble detection substitutes threaten non-medical applications. Wastewater operators exhibit highest price sensitivity; hemodialysis OEMs show lowest sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Single-source vulnerability sits with Chinese PZT ceramic refining operations that feed piezoelectric transducer fabrication worldwide. Manufacturing concentrates in Germany, the United States, and China for medical-grade modules, while sensor foundries in Japan and South Korea supply industrial variants. Raw material dependencies include lead zirconate titanate ceramics, MEMS wafer substrates, and biocompatible elastomeric coupling gels. Tariff exposure on Chinese-sourced PZT feedstock presents structural risk. Distribution runs through direct OEM supply contracts for inline detectors and industrial distributors for clamp-on retrofit applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into PZT ceramic supply and adaptive algorithm licensing partnerships define the current vertical-integration race, with control over piezoelectric feedstock emerging as the decisive upstream lever for margin defense.
For Market Incumbents: Anchor market position through captive PZT supply agreements with Chinese refiners and accelerated EU MDR technical file expansion to consolidate supplier panels. Optical bubble detection substitution in non-medical segments threatens clamp-on ultrasonic volumes. Certification investment in ISO 10993 biocompatibility testing capacity creates defensive moats against unvalidated entrants. For New Entrants and Emerging Players: Enter via India's CDSCO harmonization pathway for domestic dialysis equipment supply chains, where import substitution demand outpaces certified vendor availability. Wastewater retrofit applications in Chinese municipal plants present the most penetrable segment due to shorter procurement cycles and reduced documentation burdens. Partner with Shanghai sensor foundries rebalancing toward medical-grade output to bypass incumbent supply relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor MEMS-integrated mid-cap specialists in New York and Dresden industrial clusters where acoustic engineering talent concentrates. Long-term viability hinges on adaptive algorithm capabilities converging with hardware platforms over a multi-year technology refresh window. Watch FDA software-as-medical-device guidance divergence from EU AI Act risk classification as the critical inflection signal for next-generation detector valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PZT Supply | Captive feedstock from Chinese refiners insulates margin compression from export licensing friction. |
| EU MDR Technical File Expansion | Pre-certified documentation accelerates procurement consolidation among Italian and Dutch filling machine producers. |
| Adaptive AI Algorithm Licensing | Machine learning-enabled sensitivity adjustment enables predictive maintenance contracts in critical care settings. |
| India CDSCO Harmonization Entry | Convergence with IEC 60601-1-8 standards opens import substitution opportunities in Maharashtra dialysis supply chains. |
| MEMS Fabrication Capacity Addition | Wafer-level packaging requalification for medical reliability standards supports portable dialysis device miniaturization. |
Research Approach
Independent corroboration across primary interviews with dialysis equipment procurement directors, biomedical engineering leads at academic medical centers, and sensor foundry operations managers, combined with secondary validation through FDA 510(k) premarket notification databases, EU MDR technical file registries, and NMPA certification disclosure records, underwrites the qualitative findings. Bottom-up demand modeling from hemodialysis machine production forecasts and top-down market sizing from trade flow analysis triangulate volume estimates.
Rate-of-change decomposition across the projection horizon separates volume growth from price evolution and mix shifts toward clamp-on architectures. Segmentation dimensions modeled include product integration depth, signal processing technology, end-use application intensity, and geographic regulatory cluster. CAGRs derive from fitted growth curves against historical placement data and forward-looking OEM capacity announcements. Industry-specific inputs incorporate PZT ceramic price indices and dialysis equipment production schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export licensing disruptions for Chinese PZT feedstock or accelerated optical detection substitution in wastewater applications. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and foundry capacity rebalancing. Pandemic-era supply chain recalibration and geopolitical trade friction present specific revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Europe Trace Detection Market
Detection and Regulation Devices
Pedestrian Detection System Market
Detection and Regulation Devices
Indeflator Devices Market
Detection and Regulation Devices
Carbon Monoxide (Co) Detector Market
Detection and Regulation Devices
Constant Current Regulator Market
Detection and Regulation Devices
EMEA Frequency Control and Timing Devices Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Global Counterfeit Money Detection Market
Detection and Regulation Devices
Limiter Diodes Market
Detection and Regulation Devices
Water Leak Detector Market
Detection and Regulation Devices
Noise Monitoring Device Market
Detection and Regulation Devices
Hydrogen Detection Transmitters Market
Detection and Regulation Devices
Betavoltaic Device Market
Detection and Regulation Devices
Duct Smoke Detectors Market
Detection and Regulation Devices
Signaling Devices Market
Detection and Regulation Devices
Chemical Detection Armband Market