
 Global Noise Detection and Monitoring Market | 2026-2036
Global Noise Detection and Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Noise Detection and Monitoring Market Outlook
The capital-intensity divergence between integrated hardware-software platforms and standalone sensor vendors is unwinding competitive stability in the noise detection sector. Brüel & Kjaer leverages its Danish engineering heritage and calibration laboratory network to dominate high-precision industrial contracts. ACOEM Group anchors its position through predictive maintenance integration, bundling vibration and acoustic diagnostics for factory clients. Svantek differentiates via compact, field-rugged designs that appeal to environmental consultants and occupational health auditors.
Noise detection and monitoring encompasses the systematic capture, measurement, and analysis of acoustic energy across frequencies from infrasound to ultrasonic bands, typically quantified in decibels with A-weighting filters that approximate human hearing response. These systems serve regulatory compliance, occupational safety, environmental protection, and urban planning functions by establishing objective sound exposure baselines and triggering automated alerts when thresholds breach permitted limits. Fixed sensors and IoT-based solutions command the largest installed base, though AI-driven analytics represents the fastest-expanding margin pool as municipalities and industrial operators shift from raw data collection toward predictive noise mapping and automated source identification. Portable devices retain utility in construction site auditing and temporary event monitoring, but their hardware-centric economics face compression against subscription-based analytics platforms.
The US EPA maintains noise criteria under the Clean Air Act framework, while the EU enforces the Environmental Noise Directive mandating strategic noise maps for agglomerations exceeding 100,000 inhabitants. Japan's METI promotes smart city acoustic sensing through national digitization programs, and China's MEE integrates noise monitoring into provincial environmental quality index reporting. Stakeholders must track how regulatory granularity evolves from aggregate decibel limits toward frequency-specific nuisance standards and real-time public disclosure mandates.
Market Dynamics
The noise detection sector faces a structural pivot from hardware-centric sensor sales toward recurring-revenue analytics subscriptions, compressing margins for standalone equipment vendors while elevating platform economics for integrated solution providers.
Growth Catalysts
- EU Environmental Noise Directive:Member states must produce strategic noise maps for agglomerations exceeding 100,000 inhabitants, mandating municipal procurement of certified monitoring networks.
- Smart city infrastructure:Germany, Japan, and China are deploying IoT acoustic sensors as standard urban fixtures, embedding noise monitoring within broader environmental quality dashboards.
- Industrial predictive maintenance:Factory operators bundle acoustic diagnostics with vibration analysis to detect bearing failures and compressor anomalies before catastrophic downtime.
Market Restraints
- MEMS microphone supply concentration:Taiwanese and South Korean foundries dominate MEMS fabrication, exposing sensor vendors to geopolitical disruption and foundry allocation constraints.
- Calibration laboratory scarcity:ISO 17025-accredited acoustic calibration facilities cluster in Western Europe and Japan, creating logistics bottlenecks for field-deployed sensors requiring recertification.
- Frequency-specific nuisance standards:Emerging regulations targeting low-frequency industrial hum and infrasound from wind turbines demand hardware redesigns that obsolete existing sensor inventories.
Strategic Opportunities
- India smart city mission:The country's urban transformation program underfunds acoustic monitoring relative to air and water quality, creating first-mover whitespace for networked noise sensing.
- Edge AI convergence:On-device neural networks for source classification reduce bandwidth costs and enable real-time alerts without cloud dependency, appealing to bandwidth-constrained industrial sites.
- Construction site compliance:Temporary noise monitoring for urban infrastructure projects remains underserved by permanent-installation vendors, opening channel partnerships with equipment rental firms.
Industry Challenges
- Acoustic data science talent:The intersection of signal processing, machine learning, and environmental acoustics produces a shallow labor pool, slowing product development cycles for analytics platforms.
- Cross-border certification friction:Japan's METI Type Approval, the EU's CE marking under the Radio Equipment Directive, and FCC Part 15 compliance for US deployment create sequential testing timelines that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Noise Detection and Monitoring Market |
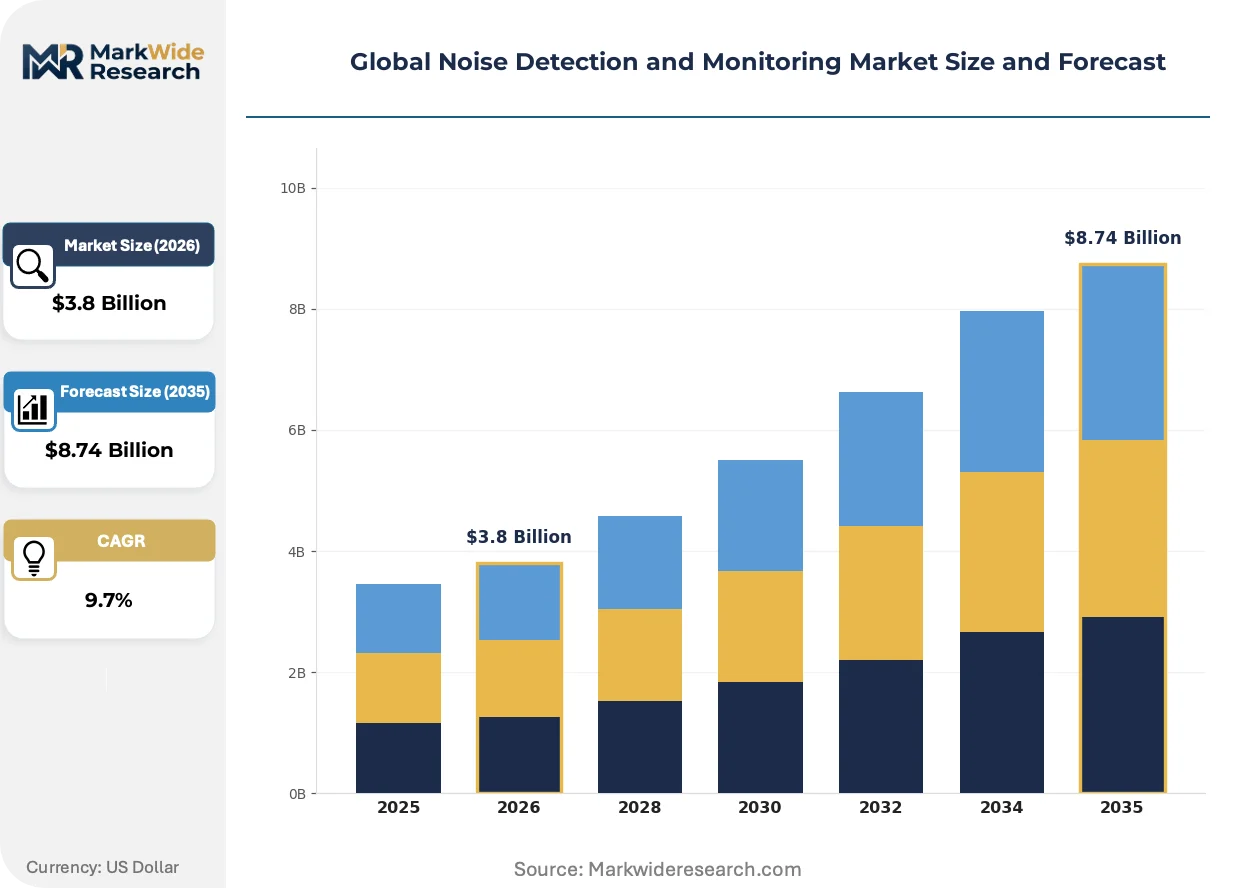
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Sensors, Portable Devices, Sound Level Meters, Acoustic Cameras Technology: Analog Systems, Digital Systems, IoT-based Solutions, AI-driven Analytics Application: Urban Planning, Environmental Monitoring, Industrial Safety, Traffic Management End User: Government Agencies, Construction Firms, Environmental NGOs, Research Institutions |
| Companies Covered | Cirrus Research Plc., Casella Inc., Brüel & Kjaer, ACOEM Group, Larson Davis, RION Co. Ltd., Svantek, Pulsar Instruments, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Noise Detection and Monitoring Market Strategic Shifts
Acoustic sensing is migrating from standalone decibel logging toward intelligent systems that classify noise sources and predict spatial propagation patterns.
Beamforming microphone arrays are fragmenting the traditional trade-off between spatial resolution and sensor density. Urban planners in Barcelona and Singapore deploy these systems to triangulate construction noise violations without dense grid installations. The technology compresses hardware counts while elevating enforcement precision, threatening economics for vendors selling high-volume low-cost nodes.
China's MEE has integrated real-time noise disclosure into provincial environmental quality index reporting, compelling industrial operators to install continuous monitoring with public-facing dashboards. Facilities in the Yangtze River Delta now treat acoustic transparency as a social license prerequisite. This regulatory architecture is accelerating replacement of legacy logging equipment with networked, API-accessible platforms.
Subscription-based analytics contracts are displacing perpetual hardware licenses among municipal buyers. German cities now procure noise mapping as a service rather than capital equipment, transferring operational risk to vendors. This purchasing pivot concentrates contract awards on platform providers with cloud infrastructure and data science capabilities, marginalizing hardware-only suppliers.
Global Noise Detection and Monitoring Market Segmentation
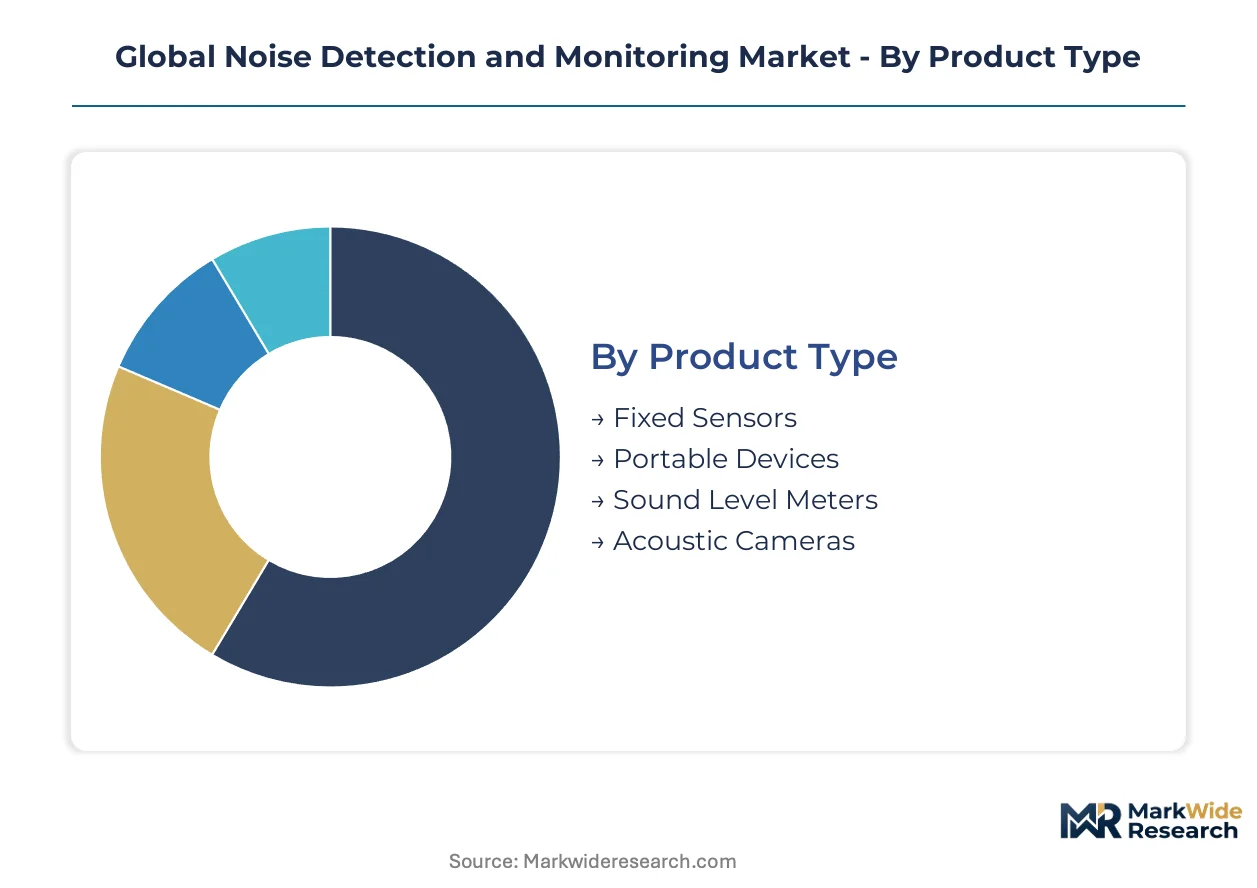
Noise detection and monitoring segments diverge sharply by procurement channel: municipal buyers favor integrated platforms with recurring service contracts, while industrial operators prioritize hardware durability and calibration traceability. Understanding these channel dynamics reveals where margin pools concentrate and which technology bundles command pricing power.
Product Type:
Fixed sensors and portable devices flow through contrasting channels—permanent installations via municipal RFPs and construction rentals through equipment leasing networks—while sound level meters and acoustic cameras serve specialized professional services.
- Fixed Sensors:Networked nodes with weatherproof enclosures and cellular backhaul dominate smart city deployments. German municipalities and China's Yangtze River Delta industrial zones drive replacement demand as legacy logging equipment reaches end-of-life.
- Portable Devices:Battery-powered units with field calibration certificates serve construction site auditing and temporary event monitoring. Rental firms in Japan and the United States bundle these with dust and vibration sensors for turnkey compliance packages.
- Sound Level Meters:Handheld Class 1 and Class 2 instruments remain essential for occupational health auditors and environmental consultants verifying regulatory compliance.
- Acoustic Cameras:Beamforming arrays with real-time source localization command premium pricing from industrial maintenance teams and urban enforcement agencies in Singapore and Barcelona.
By volume, fixed sensors lead. By growth pace, acoustic cameras are expanding most quickly.
Technology:
Cost tiers separate legacy analog hardware from digital platforms and AI-enabled services, with procurement budgets determining whether buyers accept higher upfront capital or shift toward subscription-based analytics.
- Analog Systems:Conventional decibel logging with limited connectivity persists in budget-constrained municipal fleets and developing market installations where network infrastructure remains unreliable.
- Digital Systems:DSP-based processing with SD card storage and USB extraction serves mid-tier environmental consultancies and small industrial operators seeking basic threshold alerting without cloud dependency.
- IoT-based Solutions:Connected sensors with API-accessible data streams and dashboard integration anchor smart city procurements in Germany, Japan, and China's provincial environmental quality networks.
- AI-driven Analytics:Cloud platforms with automated source classification and predictive noise mapping command the steepest expansion trajectory as municipalities shift from hardware ownership to service contracts.
By installed base, digital systems dominate. By margin expansion, AI-driven analytics is gaining share fastest.
Application:
Application segments map directly to regulatory enforcement intensity—urban planning and environmental monitoring carry compliance mandates, while industrial safety and traffic management follow voluntary adoption curves with sporadic enforcement.
- Urban Planning:Strategic noise mapping for agglomerations exceeding 100,000 inhabitants drives certified monitoring network procurement under the EU Environmental Noise Directive, with German cities leading implementation.
- Environmental Monitoring:Continuous industrial perimeter surveillance with public-facing dashboards is becoming mandatory in China's MEE provincial reporting frameworks and voluntary but expected in Japan's smart city programs.
- Industrial Safety:Occupational noise exposure monitoring with hearing conservation program integration serves factory operators in South Korea and the United States facing OSHA and MFDS enforcement.
- Traffic Management:Roadway noise monitoring with automatic number plate recognition correlation supports congestion pricing and low-emission zone enforcement in London and Milan.
By contract value, urban planning leads. By regulatory momentum, environmental monitoring is climbing the fastest.
End User:
Customer type determines purchasing authority and contract structure—government agencies issue multi-year framework agreements, while construction firms and NGOs operate on project-based procurement with compressed decision cycles.
- Government Agencies:Municipal environmental departments and national regulators in Germany, Japan, and China issue consolidated tenders for city-wide monitoring networks with decade-long service commitments.
- Construction Firms:Tier-1 infrastructure contractors in India and the United States rent temporary monitoring systems for urban tunneling and high-rise projects facing strict noise curfew enforcement.
- Environmental NGOs:Advocacy organizations deploy citizen-science sensor networks to document aviation and industrial noise violations, prioritizing low-cost open-source hardware.
- Research Institutions:Universities and national laboratories in the United States and Switzerland purchase calibrated reference-grade systems for psychoacoustic studies and standards development.
By procurement volume, government agencies lead. By activation speed, construction firms are accelerating fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes noise monitoring systems through industrial predictive maintenance contracts, while China deploys them for environmental transparency mandates—revealing a fundamental split between productivity-driven and compliance-driven procurement patterns across major markets.
United States
Industrial operators in the Great Lakes manufacturing belt and Gulf Coast petrochemical corridors drive demand for occupational safety monitoring. OSHA enforcement maintains baseline compliance requirements for hearing conservation programs. Houston and Detroit industrial clusters are replacing legacy logging equipment with networked sensors that integrate into plant-wide safety dashboards.
Germany
Automotive suppliers in Baden-Württemberg and chemical processors in North Rhine-Westphalia anchor industrial demand alongside municipal smart city deployments. The EU Environmental Noise Directive mandates strategic noise maps for cities exceeding 100,000 inhabitants. Stuttgart and Cologne are procuring certified monitoring networks with decade-long service commitments under framework agreements.
China
Provincial environmental quality index reporting requirements are compelling industrial facilities to install continuous perimeter surveillance. MEE integration of real-time noise disclosure into public dashboards creates transparency mandates. Yangtze River Delta manufacturing zones are treating acoustic monitoring as a social license prerequisite, accelerating replacement of standalone loggers with API-accessible platforms.
Japan
Smart city digitization programs promote IoT acoustic sensing as standard urban infrastructure alongside factory automation upgrades. METI national initiatives subsidize sensor deployment in municipal environmental networks. Osaka and Nagoya industrial corridors are bundling acoustic diagnostics with vibration analysis for predictive maintenance contracts.
India
Urban transformation programs underfund acoustic monitoring relative to air and water quality, creating whitespace for first-mover networked sensing vendors. The Smart Cities Mission allocates limited budgets for environmental monitoring expansion. Maharashtra and Karnataka infrastructure contractors are renting temporary noise monitoring systems for metro construction and high-rise projects facing strict curfew enforcement.
Global Noise Detection and Monitoring Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer structure where platform providers capture recurring service revenue while hardware vendors compete on calibration traceability and field durability. The upper tier bundles cloud analytics with sensor deployment, transferring operational risk to vendors through subscription contracts. Three archetypes dominate: precision instrumentation houses with laboratory calibration networks, predictive maintenance integrators combining vibration and acoustic diagnostics, and compact field-rigged specialists serving environmental consultants. Consolidation pressure is intensifying through strategic partnerships between sensor manufacturers and cloud infrastructure providers, alongside portfolio diversification into adjacent environmental monitoring modalities.
Within the precision instrumentation tier, Brüel & Kjaer and Larson Davis exemplify engineering heritage positions anchored by ISO 17025-accredited calibration capabilities. ACOEM Group occupies the predictive maintenance integration vector, representing the factory-focused archetype that bundles multi-physics diagnostics. Svantek sits within the compact field-specialist category, demonstrating how ruggedized designs serve mobility-dependent auditing applications. These three patterns—laboratory-grade precision, industrial predictive integration, and portable field performance—capture the competitive positioning spectrum without requiring detailed operational claims about individual firm strategies.
| Leading Market Players |
|---|
| Cirrus Research Plc. |
| Casella Inc. |
| Brüel & Kjaer |
| ACOEM Group |
| Larson Davis |
| RION Co. Ltd. |
| Svantek |
| Pulsar Instruments |
| 3M |
| Others |
Value Chain & Pricing Dynamics
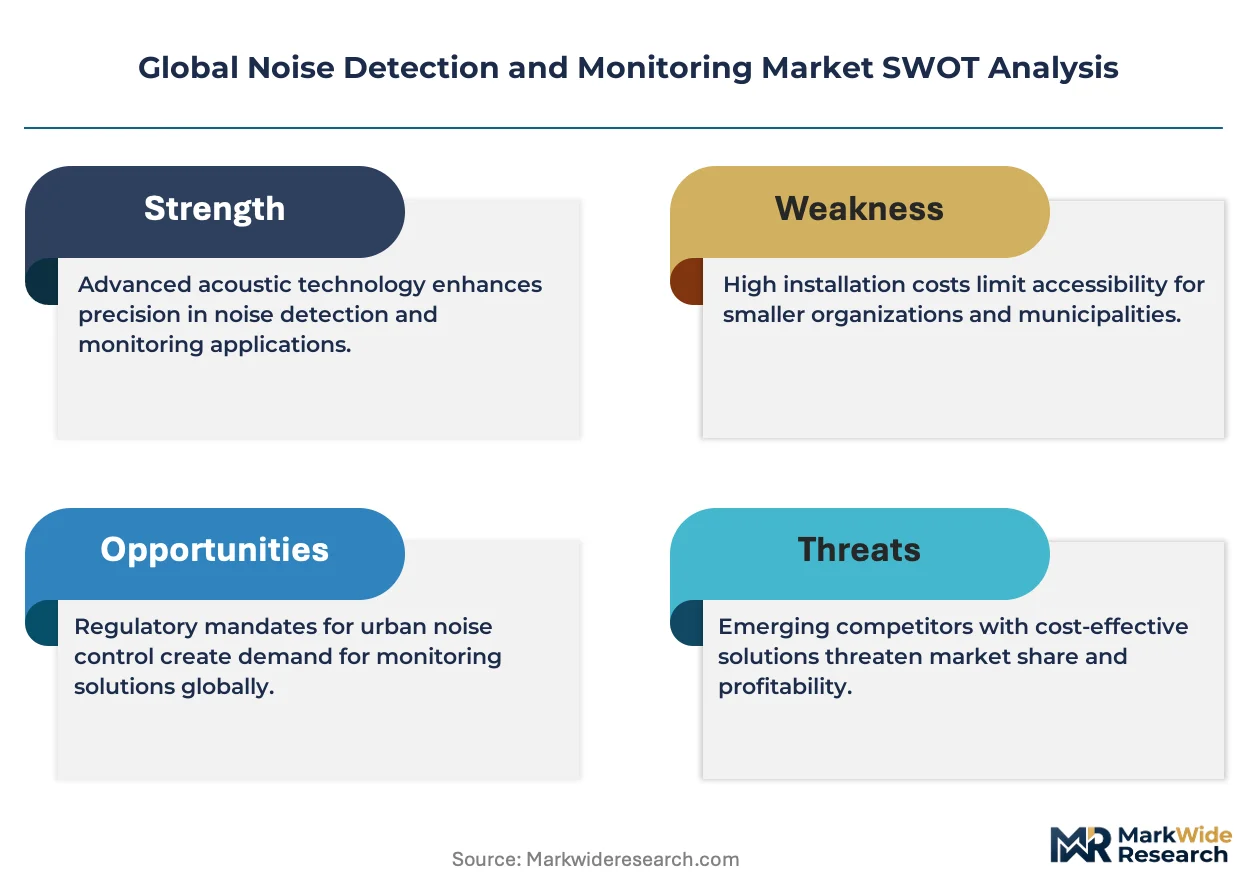
ISO 17025-accredited calibration regimes simultaneously gate supply qualification and stratify price tiers, forcing vendors to absorb laboratory logistics costs while buyers pay premiums for traceability certificates that unlock municipal contract eligibility.
Pricing Analysis
Long-term framework agreements with decade-long service commitments dominate municipal procurement in Germany and Japan, compressing upfront hardware margins while elevating lifetime value capture for integrated platform providers. Pricing stratifies across Class 1 precision instrumentation, Class 2 field-certified units, and uncertified economy sensors based on calibration traceability and frequency response bandwidth. Cost compression in standalone sensor tiers is intensifying as subscription-based analytics platforms displace perpetual licenses, forcing hardware-only vendors toward rental and leasing models. Construction firms in India exhibit highest price sensitivity, while research institutions in Switzerland and the United States demonstrate lowest sensitivity due to grant-funded capital budgets.
Supply Chain Analysis
Just-in-time component flows predominate among sensor assemblers, though strategic stockpiling of MEMS microphone dies has emerged among tier-1 vendors following foundry allocation constraints in Taiwan and South Korea. MEMS fabrication rests on Taiwanese and South Korean foundry capacity, while precision analog-to-digital converters and weatherproof enclosure polymers draw from German and Japanese specialty chemical suppliers. Single-source vulnerability concentrates in MEMS microphone supply, where two foundries control majority share of acoustic-grade fabrication. Distribution runs through direct municipal RFP channels for fixed installations and equipment rental networks for portable deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart city infrastructure investment cycles position this market for recovery, with municipal procurement acceleration in Germany, Japan, and China driving replacement demand as legacy logging equipment reaches end-of-life.
For Market Incumbents: Fortify calibration laboratory networks through backward integration into ISO 17025-accredited facilities, reducing logistics bottlenecks that delay field sensor recertification. Deepen cloud analytics capabilities to capture subscription revenue as German cities shift from hardware ownership to noise-mapping-as-a-service contracts, marginalizing hardware-only competitors. For New Entrants and Emerging Players: Lead with edge AI-enabled source classification targeting bandwidth-constrained industrial sites in South Korea and the United States, where on-device neural networks reduce cloud dependency and appeal to predictive maintenance integrators. India's underfunded Smart Cities Mission acoustic monitoring allocations present whitespace for first-mover networked sensing vendors willing to accept compressed margins for municipal reference installations. For Investors and Strategic Acquirers: EU Environmental Noise Directive enforcement milestones reshape the acquisition landscape, concentrating contract awards on platform providers with cloud infrastructure and data science capabilities. Five-to-ten-year viability favors vendors bundling vibration and acoustic diagnostics for factory predictive maintenance. Target acquisition archetype: compact field-rugged specialists with environmental consultant channel relationships. Revision becomes warranted when frequency-specific nuisance standards for low-frequency industrial hum cross implementation thresholds, obsoleting existing sensor inventories.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Acquisition | Backward integration into ISO 17025-accredited facilities reduces recertification logistics bottlenecks for German municipal contracts. |
| Edge AI Platform Launch | On-device neural networks for source classification appeal to bandwidth-constrained industrial sites in South Korea. |
| Smart City Framework Agreement | Decade-long service commitments in Stuttgart and Cologne transfer operational risk from municipalities to platform providers. |
| Predictive Maintenance Partnership | Acoustic-vibration diagnostic bundling secures factory automation upgrade contracts in Osaka and Nagoya industrial corridors. |
| Construction Rental Channel Expansion | Equipment leasing partnerships in Maharashtra and Karnataka capture temporary monitoring demand from metro infrastructure projects. |
Study Parameters
Cross-validation between municipal procurement databases and industrial operator maintenance records anchors the qualitative findings, combining primary interviews with smart city planning officers, factory maintenance directors, environmental consultancy principals, and calibration laboratory technical leads alongside secondary validation through EU Environmental Noise Directive compliance filings, China's MEE provincial environmental quality index disclosures, Japan's METI smart city digitization program documentation, and SEC filings from listed sensor manufacturers. Bottom-up sensor shipment analysis and top-down municipal budget allocation triangulation produce volume and value estimates.
Sensitivity analysis around MEMS foundry capacity assumptions and municipal procurement acceleration timelines informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, connectivity technology, deployment permanence, application regulatory intensity, and end-user procurement authority. CAGRs derive from installed base replacement cycles and analytics subscription penetration curves, with smart city infrastructure investment trajectories and industrial predictive maintenance adoption rates serving as key forecast inputs.
Forecasts assume regulatory continuity in EU Environmental Noise Directive enforcement, China's MEE real-time disclosure mandates, and Japan's METI digitization subsidies; material policy shifts would require re-modeling. Specific risk factors include frequency-specific nuisance standard implementation, MEMS foundry geopolitical disruption, and calibration laboratory capacity constraints. Revision becomes warranted when beamforming microphone array cost curves cross thresholds that accelerate spatial resolution adoption and compress node-density economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Superconducting Detector Market
Detection and Regulation Devices
Walk Through Metal Detector Market
Detection and Regulation Devices
Ultra Low Dropout Regulator (LDO) Market
Detection and Regulation Devices
Pin and Sleeve Devices Market
Detection and Regulation Devices
Global Inflation Device Market
Detection and Regulation Devices
Smart Water Leak Detector Market
Detection and Regulation Devices
Voltage Detector Market
Detection and Regulation Devices
Temperature Modulation Devices Market
Detection and Regulation Devices
Semiconductor Leak Detectors Market
Detection and Regulation Devices
Audio Signaling Devices Market
Detection and Regulation Devices
Global Gas Sensors Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Noise Monitoring Device Market
Detection and Regulation Devices
Europe Gas Detectors Market
Detection and Regulation Devices
Voltage Detection System Market
Detection and Regulation Devices
Portable Radar Detectors Market