
 Laser Self-Adhesive Tear Market | 2026-2036
Laser Self-Adhesive Tear Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Self-Adhesive Tear Market Analytics
Aftermarket authentication services is rewriting margin capture across the value chain, shifting profit pools from commodity substrate sales toward integrated verification platforms. 3M Company leverages its materials science portfolio to dominate high-performance polyester tear tapes with embedded holographic security features. Avery Dennison Corporation anchors North American demand through direct partnerships with pharmaceutical contract packagers requiring FDA-compliant tamper-evident solutions. Suzhou Image Laser Technology specializes in micro-optic laser engraving for Asian electronics manufacturers seeking component-level traceability.
Laser self-adhesive tear materials consist of pressure-sensitive substrates incorporating laser-reactive coatings that fracture along predetermined stress lines upon removal, typically specified with tear initiation forces between 50-200 grams per inch and visual void patterns visible under magnification. These materials serve primarily as tamper-evident seals and authentication layers across packaging, labeling, and industrial assembly applications. Specialty product types command premium positioning due to custom holographic interlayers and controlled tear propagation engineering, while single-sided configurations sustain volume leadership in standard pharmaceutical and retail applications. Paper-based materials retain cost-sensitive share in craft and promotional segments, though polyester substrates are displacing vinyl in automotive underhood labeling where thermal stability exceeds 150°C.
FDA serialization requirements under the Drug Supply Chain Security Act and EU MDR tamper-evident mandates reshape product specifications, compelling manufacturers to validate adhesive shear resistance and laser-mark permanence against harmonized test protocols. REACH substance restrictions on certain adhesive chemistries and California Proposition 65 disclosure obligations further constrain formulation flexibility, particularly for vinyl-backed constructions containing legacy plasticizers. Stakeholders must monitor evolving pharmaceutical track-and-trace regulations and automotive OEM specification migrations toward fully recyclable mono-material tear constructions.
Market Dynamics
Pharmaceutical serialization mandates from FDA and EU MDR are compressing specification cycles and forcing adhesive-laser coating convergence at the specification level rather than the procurement level.
Growth Catalysts
- Drug Supply Chain Security Act:FDA serialization requirements mandate tamper-evident seals with permanent laser-mark traceability, compelling contract packagers to validate adhesive shear resistance against harmonized protocols.
- Automotive parts authentication:Germany's OEM cluster around Stuttgart demands laser-etched tear tapes for underhood component traceability where thermal stability exceeds 150°C.
- Micro-optic engraving:Asian electronics manufacturers embed component-level traceability through laser-reactive coatings that fracture along predetermined stress lines upon removal.
Market Restraints
- REACH substance restrictions:ECHA limitations on legacy plasticizers in vinyl-backed constructions constrain formulation flexibility for pressure-sensitive adhesive suppliers.
- Polyester substrate cost volatility:Raw material fluctuations for high-performance films compress margins for manufacturers displacing paper in thermal-critical applications.
- California Proposition 65:Disclosure obligations for adhesive chemistries create compliance friction that extends qualification timelines for North American pharmaceutical packaging.
Strategic Opportunities
- Mono-material recyclable constructions:EU Green Deal circularity mandates create specification pull for fully recyclable tear tapes that eliminate multi-layer lamination complexity.
- Aftermarket authentication platforms:Integrated verification services shift profit pools from commodity substrate sales toward recurring-margin software-hardware bundles.
- Electronics component traceability:Asian contract manufacturers seek micro-optic laser engraving for chip-level provenance tracking in semiconductor supply chains.
Industry Challenges
- Adhesive-laser coating integration:Formulating pressure-sensitive substrates with laser-reactive layers that maintain 50-200 gram-per-inch tear initiation forces requires cross-functional expertise spanning materials science and optical engineering.
- Harmonized test protocol validation:Manufacturers must simultaneously satisfy FDA shear-resistance standards and EU MDR tamper-evident permanence criteria without duplicating qualification runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Self-Adhesive Tear Market |
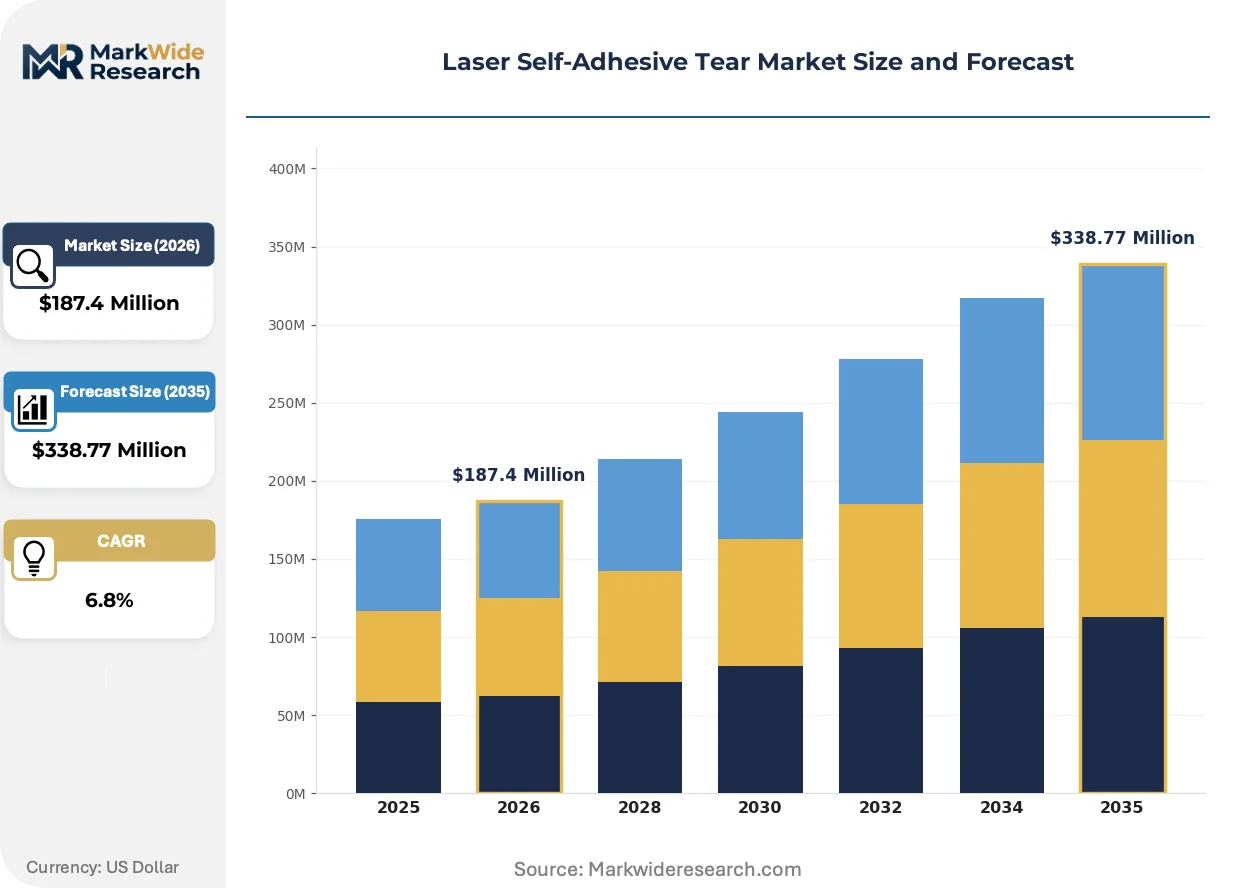
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Specialty, Removable Material: Paper, Vinyl, Polyester, Foam Application: Packaging, Labeling, Crafts, Industrial End User: Retail, Healthcare, Automotive, Electronics |
| Companies Covered | 3M Company, Avery Dennison Corporation, UPM Raflatac, Lintec Corporation, H.B. Fuller, Tesa SE, Wuxi Mu Lei Anti-counterfeit Packaging Technology, Suzhou Image Laser Technology, Bangla Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Self-Adhesive Tear Market Evolving Landscape
Laser-reactive coating technologies are collapsing the traditional separation between adhesive performance and optical security, creating integrated specification platforms that bundle tamper evidence with digital traceability.
Ultrafast picosecond laser marking systems are digitizing how pharmaceutical packagers embed serialized authentication data directly into tear tape substrates. Contract manufacturers serving FDA-regulated drug packaging are adopting these systems at accelerated qualification paces to meet November serialization deadlines. This technology is digitizing the transition from physical void patterns to machine-readable optical features that integrate with track-and-trace databases.
EU MDR tamper-evident mandates are forcing adhesive suppliers to reformulate shear-resistant chemistries that survive sterilization cycles while maintaining laser-mark permanence. Industrial consequence includes validated master file submissions to notified bodies for construction changes. Medical device packaging in Germany and Ireland faces the tightest compliance windows, with manufacturers accelerating dual-protocol testing to satisfy both EMA and FDA requirements.
Automotive OEMs are consolidating supplier qualifications around captive tear tape specifications that bundle material supply with authentication software licensing. Tier-1 labeling vendors in Stuttgart and Munich are displacing spot-buy relationships with multi-year platform contracts that embed holographic security feature updates. This consolidation is most visible in German automotive clusters where KBA type-approval documentation requires laser-etched provenance for safety-critical underhood components.
Laser Self-Adhesive Tear Market Segmentation
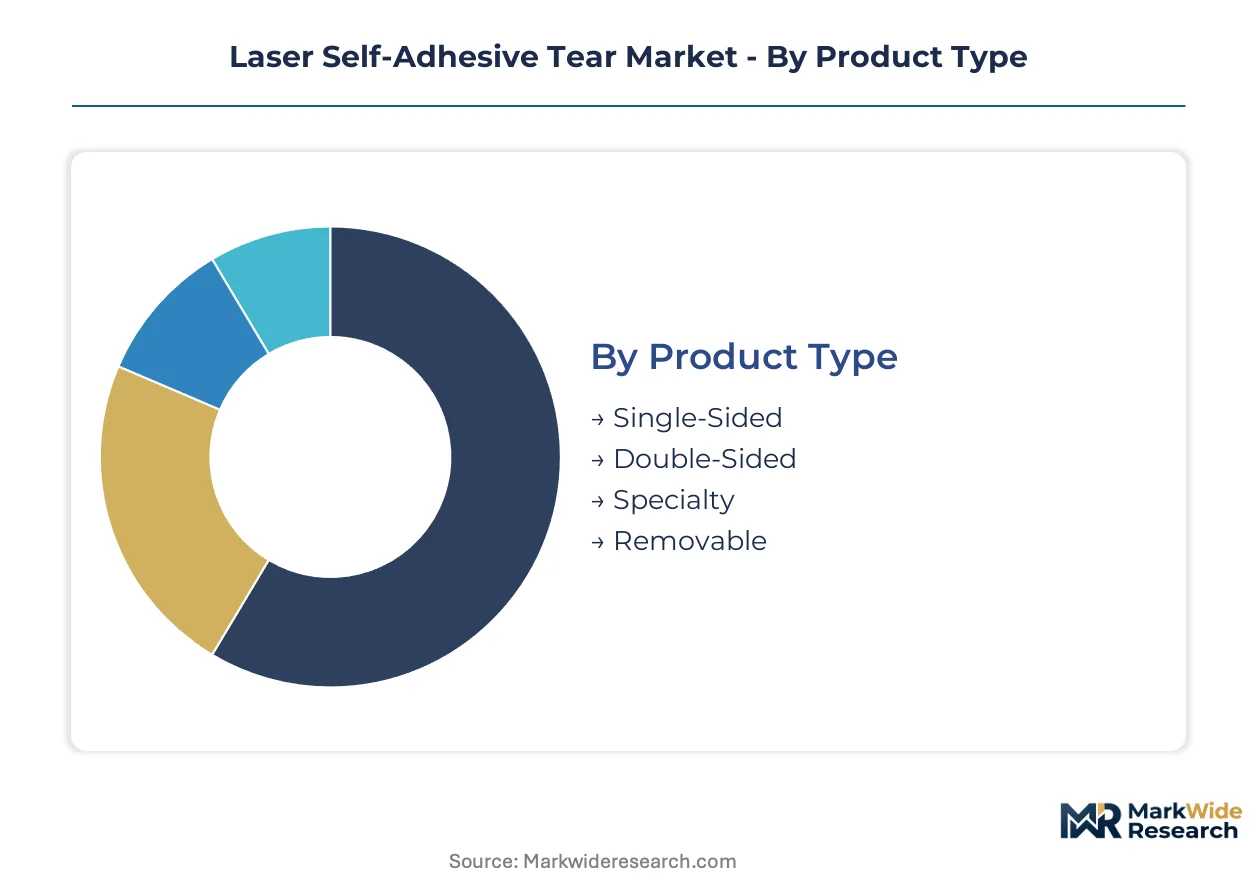
Laser self-adhesive tear markets fragment across four critical dimensions that determine specification complexity and margin capture. Product type and material choices dictate laser-reactive coating compatibility, while application and end-user segmentation governs regulatory validation requirements and procurement cycle length.
Product Type:
Specification cycles compress from 18 months for standard configurations down to 6-8 months for security-enhanced specialty grades as pharmaceutical serialization mandates accelerate validation timelines.
- Single-Sided:Pressure-sensitive substrates with laser-reactive coatings applied to one face, specified with tear initiation forces between 50-200 grams per inch. Retail and standard pharmaceutical packaging in Germany concentrate procurement volumes where FDA Drug Supply Chain Security Act compliance drives annual requalification cycles.
- Specialty:Custom holographic interlayers and controlled tear propagation engineering command premium positioning. Stuttgart automotive OEMs specify these for underhood component traceability where KBA type-approval documentation requires thermal stability exceeding 150°C and laser-etched provenance verification.
- Double-Sided:Dual-coated constructions serve industrial assembly applications requiring tamper evidence on both substrate faces.
- Removable:Low-tack adhesive systems enable temporary authentication layers for promotional and craft segments.
Single-Sided anchors the volume base while Specialty gains share at the steepest rate.
Material:
Cost tiers stratify sharply, with paper substrates occupying economy positioning and polyester films capturing premium thermal-critical applications.
- Polyester:High-performance films with thermal stability exceeding 150°C displace vinyl in automotive underhood labeling. REACH substance restrictions on legacy plasticizers accelerate this substitution in German OEM supply chains where ECHA compliance is non-negotiable.
- Paper:Cost-sensitive substrates retain craft and promotional segment share. California Proposition 65 disclosure obligations create qualification friction for North American pharmaceutical packaging using paper-backed constructions with certain adhesive chemistries.
- Vinyl:Legacy constructions face formulation constraints from ECHA plasticizer limitations.
- Foam:Compressible substrates serve irregular surface applications in industrial assembly.
Paper sustains the widest installed base while Polyester climbs the fastest on automotive and electronics demand.
Application:
Volume concentration diverges between high-unit pharmaceutical packaging and low-unit high-value industrial authentication systems.
- Packaging:Tamper-evident seals for pharmaceutical and retail containers dominate unit volumes. EU MDR mandates and FDA serialization requirements compress specification cycles and force adhesive-laser coating convergence at the specification level.
- Industrial:Component-level traceability applications command highest per-unit value. Asian electronics manufacturers embed micro-optic laser engraving for semiconductor supply chain provenance tracking.
- Labeling:Authentication layers for automotive parts and medical devices require harmonized test protocol validation.
- Crafts:Promotional and hobby applications sustain paper substrate demand.
Packaging generates the deepest volume while Industrial shows the steepest expansion trajectory.
End User:
Procurement authority centralizes differently: retail buyers optimize unit cost, while automotive and healthcare procurement teams bundle material supply with authentication platform licensing.
- Healthcare:Pharmaceutical contract packagers demand FDA-compliant tamper-evident solutions with permanent laser-mark traceability. EU MDR and Drug Supply Chain Security Act requirements force simultaneous EMA and FDA dual-protocol testing.
- Automotive:Germany's OEM cluster around Stuttgart and Munich consolidates supplier qualifications around captive tear tape specifications. KBA type-approval documentation mandates laser-etched provenance for safety-critical underhood components.
- Retail:Cost-optimized procurement sustains single-sided and paper-based segment volumes.
- Electronics:Asian contract manufacturers seek chip-level traceability through micro-optic laser engraving systems.
Healthcare commands the most stringent compliance overhead while Automotive drives the fastest platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail buyers in emerging markets exhibit acute price sensitivity toward paper-based single-sided configurations, while German automotive OEMs and US pharmaceutical contract packagers absorb substantial premiums for validated specialty grades with embedded authentication layers.
United States
FDA Drug Supply Chain Security Act mandates compress pharmaceutical packaging qualification cycles to annual revalidation. California Proposition 65 disclosure obligations create compliance friction for adhesive chemistries, particularly for paper-backed constructions entering North American healthcare supply chains. Greater Boston and New Jersey pharmaceutical corridors concentrate contract packager procurement authority.
Germany
KBA type-approval documentation mandates laser-etched provenance for safety-critical underhood components, driving specialty grade absorption. EU MDR tamper-evident mandates force simultaneous EMA and FDA dual-protocol testing for medical device exports. Stuttgart and Munich automotive clusters consolidate supplier qualifications around multi-year platform contracts with embedded holographic security feature updates.
China
Asian electronics manufacturers embed micro-optic laser engraving for semiconductor supply chain provenance tracking. SAMR serialization requirements for pharmaceutical packaging accelerate adoption of machine-readable optical features. Yangtze River Delta contract manufacturers represent the fastest-expanding demand vector for component-level traceability applications.
Japan
METI industrial standards for automotive component authentication align with export OEM requirements in German and US markets. PMDA pharmaceutical serialization mandates mirror FDA timelines, forcing adhesive-laser coating convergence at specification level. Kansai and Chubu industrial corridors specialize in high-performance polyester substrates for thermal-critical electronics assembly.
South Korea
MFDS track-and-trace regulations for pharmaceutical packaging compress specification cycles to match EU MDR compliance windows. Samsung and SK Hynix supply chain traceability requirements drive micro-optic laser engraving adoption for chip-level provenance. Seoul Capital Area electronics manufacturers specify tear initiation forces between 50-200 grams per inch for precision component handling.
Laser Self-Adhesive Tear Market Competitive Landscape
Capability concentration sits with specialty-grade formulators possessing cross-functional expertise spanning materials science and optical engineering; scale advantage sits with diversified adhesive and film producers serving commodity pharmaceutical and retail segments. The market structure tiers across three archetypes: integrated materials-science conglomerates with holographic security portfolios, precision coating specialists focused on laser-reactive layer integration, and regional substrate converters supplying cost-optimized paper and vinyl constructions. Dominant competitive moves include backward integration into captive laser-reactive coating production and strategic partnerships with track-and-trace software platforms to bundle material supply with authentication licensing.
Within the integrated materials-science tier, 3M Company and Avery Dennison Corporation exemplify archetypes combining pressure-sensitive adhesive expertise with embedded security feature development. Suzhou Image Laser Technology occupies a specialist position representing precision micro-optic engraving capabilities for Asian electronics supply chains. These three anchors illustrate the market's bifurcation between scale-driven substrate supply and capability-intensive authentication platform integration.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| UPM Raflatac |
| Lintec Corporation |
| H.B. Fuller |
| Tesa SE |
| Wuxi Mu Lei Anti-counterfeit Packaging Technology |
| Suzhou Image Laser Technology |
| Bangla Group |
| Others |
Value Network & Pricing Analysis
Undercapacity in German automotive laser-etching facilities drives aggressive capacity reservation contracts from Stuttgart OEMs, compressing spot-market availability and amplifying pricing power for validated specialty-grade suppliers serving FDA and EU MDR compliance windows.
Pricing Analysis
Aftermarket authentication licensing generates lifetime value multiples exceeding substrate-only sales, with recurring software-hardware bundles capturing margins unavailable to commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels separates KBA-validated automotive constructions from pharmaceutical single-sided grades and paper-based craft segments. Price differentiation hinges on certification tier—FDA master file validation commands substantial premiums—and volume scale, with contract packagers negotiating annual requalification discounts. Cost compression in standard pharmaceutical grades intensifies as Asian contract manufacturers enter with SAMR-compliant alternatives. Retail buyers exhibit acute price sensitivity, while German automotive procurement teams absorb premiums for thermal-stable polyester with embedded holographic layers.
Supply Chain Analysis
Contract-manufacturing concentration centers on Suzhou Image Laser Technology and Yangtze River Delta precision coating specialists, with secondary capacity clusters in Stuttgart automotive corridors and New Jersey pharmaceutical packaging zones. Geographic supply concentration spans China, Germany, and the United States, with raw material dependencies on polyester film feedstocks, laser-reactive coating chemistries, and pressure-sensitive adhesive resins. Single-source vulnerability in micro-optic engraving equipment creates qualification bottlenecks for specialty-grade production. Distribution runs through direct OEM platform contracts in automotive, pharmaceutical contract packager networks in healthcare, and regional substrate converters in retail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Authentication platform licensing expands faster than hardware substrate sales, transforming margin capture toward recurring-revenue software-hardware bundles with embedded holographic security updates.
For Market Incumbents: Build regulatory certification moats through simultaneous FDA master file and EU MDR notified body submissions, compressing competitor qualification timelines. Deepen backward integration into captive laser-reactive coating production to secure supply continuity against REACH substance restrictions. Defend position by locking multi-year platform contracts with Stuttgart OEMs that bundle material supply with authentication software licensing, displacing spot-buy relationships. For New Entrants and Emerging Players: Establish a beachhead in Asian electronics component traceability, where micro-optic laser engraving demand outpaces established supplier capacity. Target SAMR-compliant pharmaceutical packaging in China, where serialization mandates accelerate faster than domestic coating expertise accumulation. Penetrate through partnerships with track-and-trace software platforms, avoiding direct confrontation with integrated materials-science conglomerates in saturated automotive and North American healthcare segments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across specialty-grade holographic interlayer production, favoring scaled precision coating specialists over fragmented substrate converters. Long-term viability over the analysis window rests on authentication platform integration capabilities rather than commodity film supply. Acquisition target archetype: precision micro-optic engraving specialists with validated pharmaceutical and automotive qualifications. Monitor KBA type-approval documentation timelines as inflection indicator for German automotive contract consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser-Reactive Coating Production | Captive supply of REACH-compliant chemistries secures formulation flexibility against ECHA plasticizer restrictions. |
| Authentication Platform Licensing Partnerships | Software-hardware bundles shift profit pools from commodity substrates toward recurring-margin verification services. |
| Dual-Protocol Validation Investment | Simultaneous FDA and EU MDR qualification compresses competitor entry timelines in pharmaceutical serialization. |
| Mono-Material Recyclable Construction Development | EU Green Deal circularity mandates create specification pull for fully recyclable tear tape constructions. |
| Micro-Optic Engraving Capacity Expansion | Picosecond laser marking systems digitize serialized authentication for Asian electronics supply chain traceability. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, engaging pharmaceutical contract packager procurement directors, automotive OEM platform engineers, laser-reactive coating R&D leads, and track-and-trace software platform executives. Secondary validation drew from FDA Drug Supply Chain Security Act guidance documents, EMA MDR implementation reports, KBA type-approval databases, and ECHA REACH substance restriction filings. Bottom-up and top-down triangulation reconciled unit volume estimates from substrate converters with value assessments from authentication platform licensing disclosures.
Calibration against historical qualification timeline compression and regulatory mandate implementation pacing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material substrate, application function, and end-user procurement authority. CAGRs were derived from installed base growth in pharmaceutical serialization and automotive parts authentication, cross-referenced with adhesive-laser coating convergence adoption curves and mono-material recyclable construction migration patterns.
Stress conditions across polyester raw material cost volatility, REACH substance restriction expansion, and FDA-EU MDR harmonization timeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory mandate adherence rates and OEM platform contract consolidation velocity. Quarterly review of KBA type-approval documentation issuance and SAMR pharmaceutical serialization compliance deadlines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Fabric Adhesive Market
Adhesives & Sealants
Amine Curing Agents Market
Adhesives & Sealants
American Epoxy Adhesives Market
Adhesives & Sealants
Lead Encapsulants Market
Adhesives & Sealants
Adhesive Primer Market
Adhesives & Sealants
Global Cyanoacrylate Adhesives Market
Adhesives & Sealants
Spain Adhesives Market
Adhesives & Sealants
Carpet Adhesive Market
Adhesives & Sealants
Anti-Corrosion Tape Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
Wood Adhesives and Binders Market
Adhesives & Sealants
India Adhesives and Sealants Market
Adhesives & Sealants
Global Disposable Hygiene Adhesives Market
Adhesives & Sealants
Japan Adhesives Market
Adhesives & Sealants
Fuel Resistant Sealant Market
Adhesives & Sealants
Middle East and Africa Adhesives Market