
 Global Construction Adhesives and Sealants Market | 2026-2036
Global Construction Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Construction Adhesives and Sealants Market Foresight
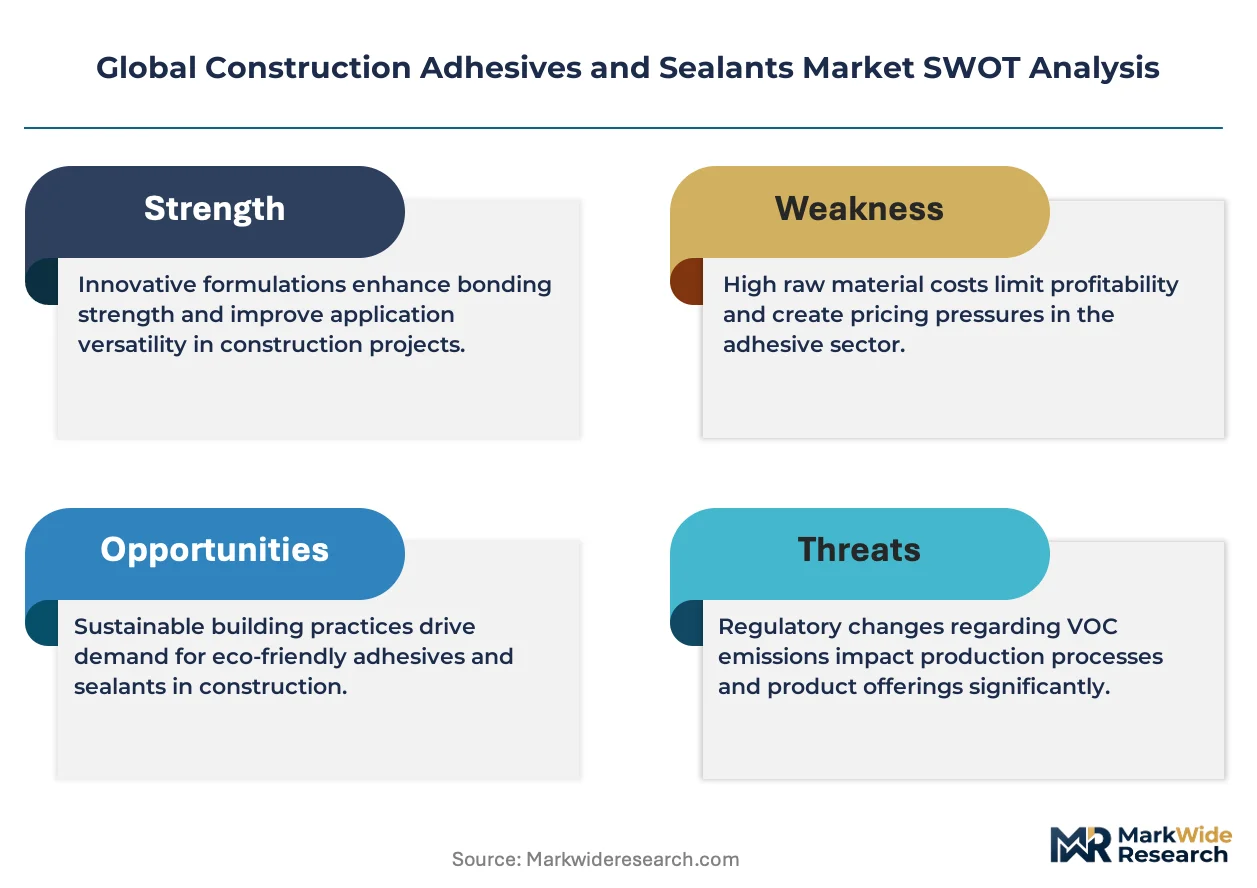
The EU Green Deal is broadening specification requirements for low-VOC, high-durability bonding systems across commercial and residential construction. Henkel AG & Co. KGaA leverages its adhesive chemistry portfolio to serve structural glazing and insulation panel markets. Sika AG anchors its position through formulation leadership in polyurethane and silicone technologies for expansion joint and waterproofing applications. Dow Inc. competes on silicone innovation, sustaining R&D investment in weather-resistant sealants for high-performance building envelopes.
Construction adhesives and sealants comprise formulated polymer systems—acrylics, polyurethanes, silicones, epoxies, butyl rubbers, and MS polymers—designed to bond, seal, or fill joints in structural and non-structural building assemblies, typically specified by tensile strength, elongation at break, and service temperature range. Their primary purpose is to ensure air and water barrier continuity, structural integrity, and thermal performance across building envelopes and interior systems. The polyurethane segment dominates volume in flooring and wall panel applications where flexibility and gap-filling capacity command premium positioning, while MS polymer formulations represent the fastest-growing chemistry due to hybrid performance combining silicone durability with paintability and primerless adhesion. Among end users, renovation specialists and facility maintenance operators constitute the most dynamic demand pool as building stock aging and energy efficiency retrofits drive recurring sealant replacement cycles.
REACH in Europe, EPA VOC regulations in the United States, and China's GB standards under SAMR oversight collectively restrict solvent content and mandate disclosure of hazardous substance thresholds, forcing reformulation investments and reshaping competitive access. The EU F-Gas Regulation and evolving state-level green building codes in California and New York further tighten performance benchmarks for thermal and moisture management systems. Stakeholders must monitor regulatory divergence between jurisdictions to align product registration strategies with regional compliance timelines and specification gatekeepers.
Market Dynamics
Building energy retrofit mandates across the European Union are compressing replacement cycles and elevating specification standards for structural bonding systems, forcing reformulation investments and reshaping competitive access.
Growth Catalysts
- EU Green Deal implementation:Mandatory energy performance upgrades for commercial building stock are accelerating specification of low-VOC, high-durability sealants in Germany, France, and the Netherlands.
- Structural glazing expansion:Curtain wall and facade engineering firms are specifying silicone and MS polymer chemistries for their combined weather resistance and primerless adhesion properties.
- India infrastructure renewal:Metro rail, airport, and smart city projects are driving specification of polyurethane flooring adhesives and expansion joint sealants in Mumbai, Delhi, and Bangalore corridors.
Market Restraints
- Petrochemical feedstock volatility:Propylene oxide and silicone monomer price swings compress margin predictability for polyurethane and silicone formulators.
- Specialty additive supply concentration:Tin-based catalysts and fumed silica production clusters in China create single-source vulnerability for Western compounders.
- REACH registration burden:Substance authorization costs and data requirements block mid-tier Asian exporters from European specification channels.
Strategic Opportunities
- US state-level green building codes:California Title 24 and New York Local Law 97 are creating regulatory tailwinds for high-performance air barrier sealants in commercial retrofits.
- Prefabricated construction integration:Offsite panel manufacturers require factory-applied adhesive systems with extended open times and rapid cure profiles.
- Digital specification platforms:Building information modeling (BIM) libraries are emerging as gatekeepers, enabling direct-to-architect technical marketing bypassing traditional distributor relationships.
Industry Challenges
- Formulation chemist scarcity:Hybrid polymer expertise combining silicone and polyurethane chemistry knowledge commands premium compensation and limits R&D team scaling.
- Multi-jurisdiction compliance synchronization:Divergent VOC limits between EPA, REACH, and China's SAMR force parallel product line maintenance and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Construction Adhesives and Sealants Market |
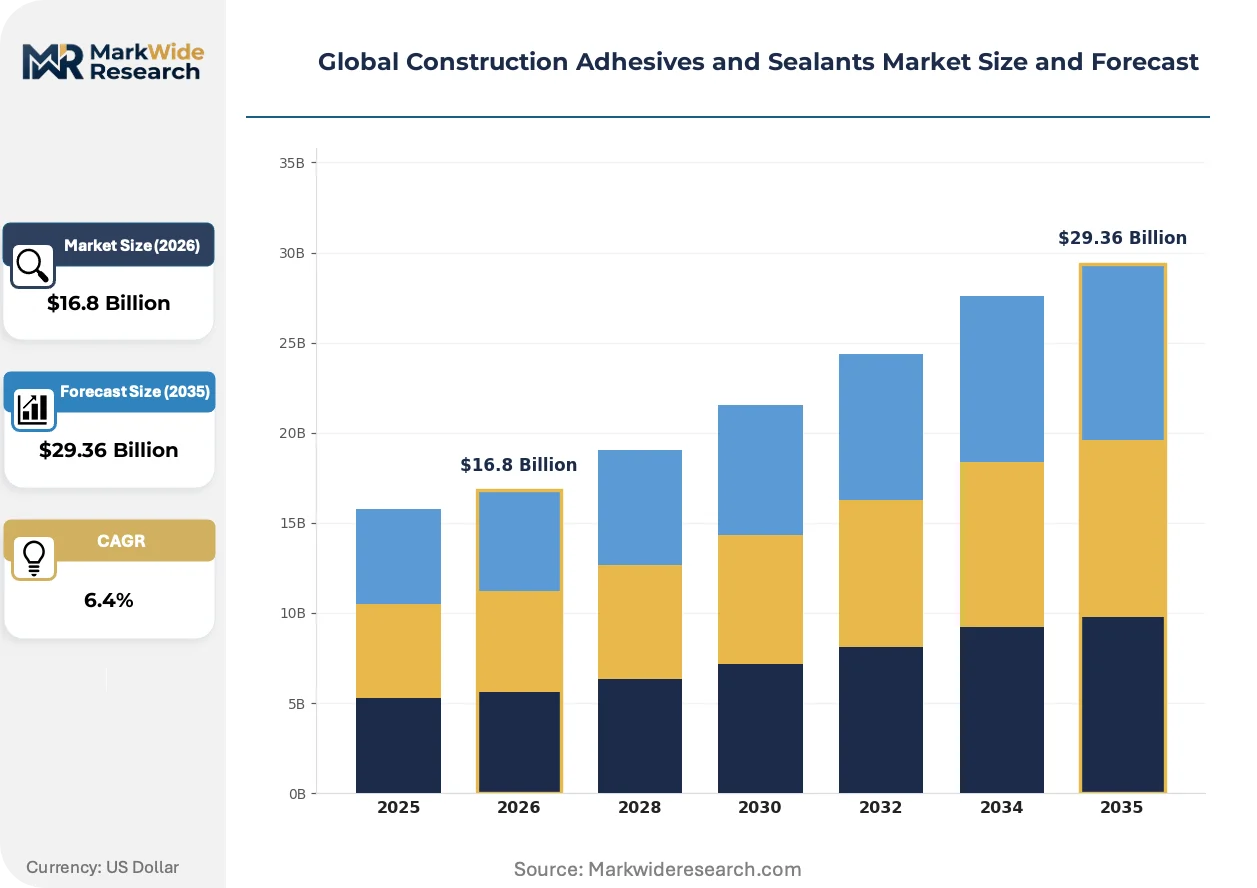
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $29.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Silicone, Epoxy, Butyl Rubber, MS Polymer Application: Wall Panels, Flooring, Roofing, Window Glazing, Door Frames, Expansion Joints End User: General Contractors, Subcontractors, Facility Maintenance, Renovation Specialists, Structural Engineers Sales Channel: Distributors, Direct Sales, Online Retailers, Hardware Stores, Wholesalers |
| Companies Covered | Henkel AG & Co. KGaA, Sika AG, 3M, H.B. Fuller Company, Arkema, Dow Inc., Wacker Chemie AG, MAPEI S.p.A., Huntsman International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Construction Adhesives and Sealants Market Shifts & Advancements
Formulation chemistry is converging with digital building design workflows, compressing the path from specification to installation while elevating performance verification standards across commercial and residential construction.
MS polymer hybrid technology is unifying the previously separate silicone and polyurethane specification categories. Façade engineers and waterproofing contractors are adopting these systems at accelerating rates for their paint compatibility and primerless substrate adhesion. The technology is unifying performance tiers that historically required distinct product lines, compressing SKU complexity for distributors while expanding application versatility for contractors.
REACH authorization requirements and the EU F-Gas Regulation are tightening substance restrictions on tin catalysts and fluorinated blowing agents used in sealant production. Industrial consequence includes forced migration to bismuth and zinc-based cure systems with reformulation timelines compressed by sunset dates. Polyurethane foam sealant manufacturers serving Northern European markets are most affected, accelerating partnerships with catalyst suppliers to secure compliant alternative supply.
Renovation specialists are consolidating procurement through integrated supply agreements with national distributors, displacing spot purchasing through local hardware channels. Technical support and on-site training are bundling with volume commitments, shifting margin capture toward specification influence rather than product margin alone. This pattern is most visible in German and Austrian markets where facility maintenance operators manage multi-property portfolios under energy efficiency service contracts.
Global Construction Adhesives and Sealants Market Segmentation
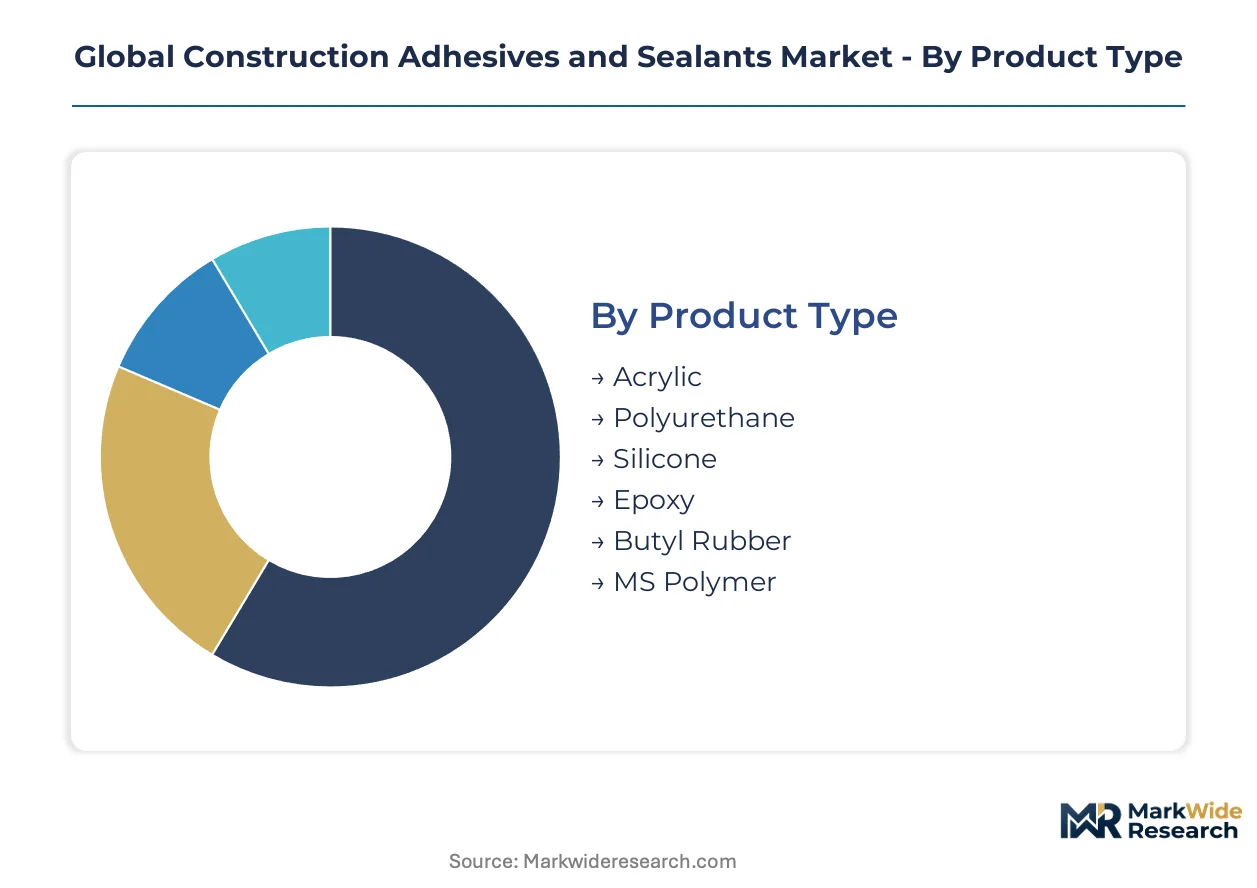
Construction adhesives and sealants fragment across chemistry, application, and procurement channel dimensions. Specification power varies sharply by segment, with structural engineers and facility maintenance operators driving premium formulation demand while general contractors prioritize cost efficiency and availability.
Product Type:
Buyers differentiate by durability requirements, substrate compatibility, and regulatory compliance burden rather than price alone.
- Polyurethane:These systems combine gap-filling capacity with flexibility across temperature cycles, making them indispensable for flooring and wall panel bonding in Germany and India's commercial construction corridors. Facility maintenance operators specify polyurethane for expansion joint refurbishment where movement accommodation exceeds 25% elongation.
- MS Polymer:Hybrid formulations merge silicone weather resistance with paintability and primerless adhesion, capturing specification from façade engineers in the Netherlands and curtain wall contractors in China's tier-one cities. The chemistry eliminates the traditional trade-off between durability and aesthetic finish compatibility.
- Silicone:Structural glazing applications in high-rise commercial towers depend on these formulations for UV stability and 50-year service life projections.
- Acrylic:Water-based systems serve interior finishing trades where low odor and fast tack drive selection in occupied building retrofits.
- Epoxy:High-strength structural bonding for precast concrete connections and metal-to-substrate anchoring in infrastructure projects.
- Butyl Rubber:Preformed tapes and sealants for window perimeter sealing where immediate tack and vapor barrier continuity matter.
Volume concentrates in polyurethane formulations; MS polymer climbs fastest as hybrid performance rewrites specification standards.
Application:
End-use selection hinges on exposure severity, code compliance depth, and replacement cycle frequency.
- Flooring:Polyurethane adhesives dominate resilient and wood flooring installation across India's metro rail commercial developments and Germany's office renovation wave. Subcontractors prioritize open time and early strength development to compress installation schedules.
- Window Glazing:Silicone and MS polymer systems command structural glazing specifications in curtain wall engineering, with Sika AG and Dow Inc. formulations specified for weather seal longevity in high-rise envelopes from Mumbai to Frankfurt.
- Roofing:Membrane attachment and flashing sealants face the most severe thermal cycling and ponding water exposure.
- Wall Panels:Offsite construction manufacturers specify factory-applied systems with extended open times for panel-to-panel bonding.
- Door Frames:Foam and tape sealants for perimeter air sealing in energy code compliance.
- Expansion Joints:Movement-capable sealants for podium decks, parking structures, and facade joints subject to seismic and thermal displacement.
Replacement frequency runs highest in expansion joints; window glazing carries the steepest specification premium.
End User:
Procurement sophistication separates price-driven spot buyers from specification-influenced volume contractors.
- Renovation Specialists:These operators consolidate multi-property portfolios under energy efficiency service contracts in Germany and Austria, bundling technical support with volume commitments. Their influence over sealant specification has displaced local hardware channel purchasing for commercial building stock.
- Facility Maintenance:Operators managing aging building envelopes across the European Union prioritize compliant low-VOC systems as the EU Green Deal tightens energy retrofit mandates. Recurring replacement cycles create predictable demand for durable silicone and MS polymer formulations.
- General Contractors:Project-based procurement prioritizes availability and cost control over technical specification depth.
- Subcontractors:Flooring, glazing, and waterproofing trades select adhesives based on installation speed and callback risk mitigation.
- Structural Engineers:Façade and connection design professionals specify structural glazing and anchoring systems with certified performance data.
Margin capture tilts toward renovation specialists; general contractors drive highest volume throughput.
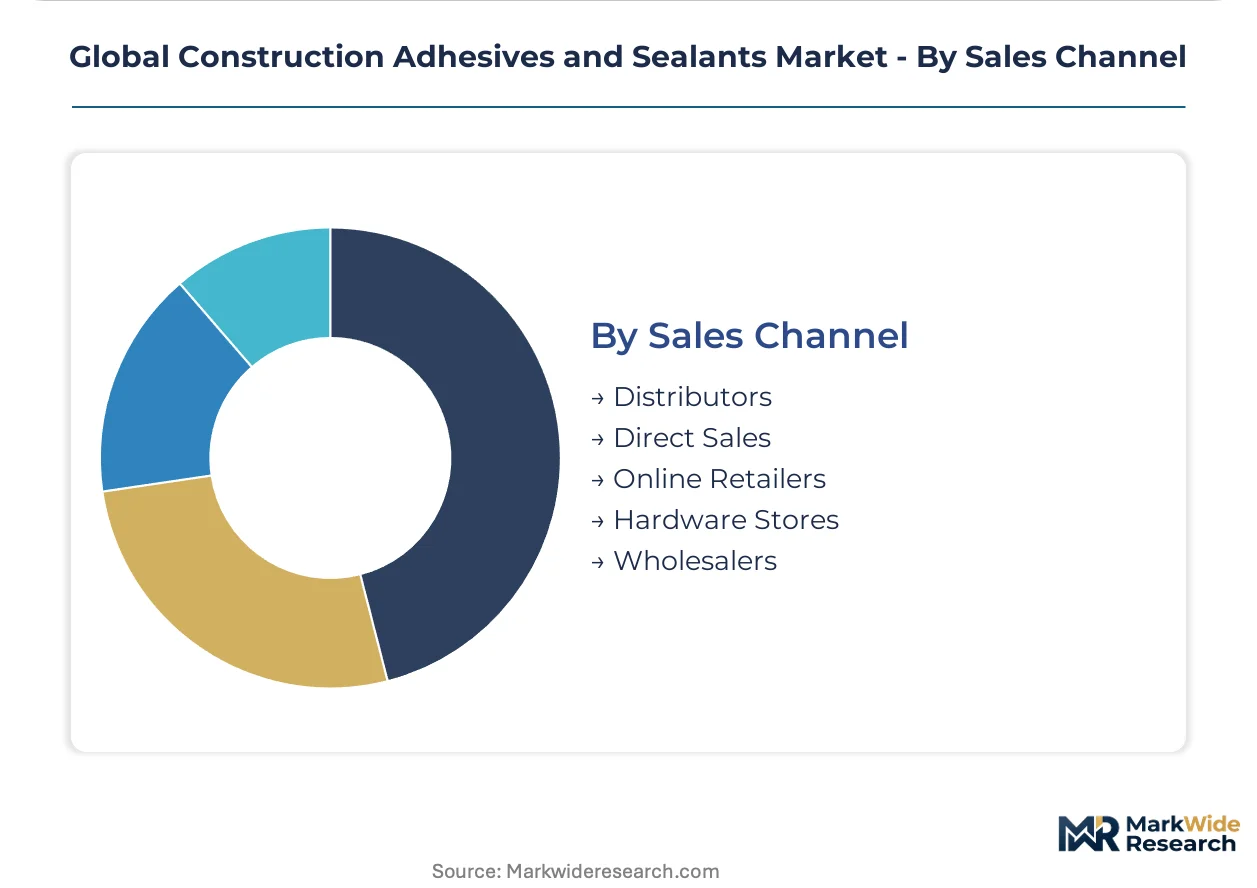
Sales Channel:
Channel selection reflects order size, technical support requirements, and geographic coverage needs.
- Distributors:National distributors serve as specification gatekeepers for renovation specialists and facility maintenance operators, bundling on-site training with volume agreements. Their technical sales teams influence architect and engineer selection before product reaches the job site.
- Direct Sales:Large-scale projects and national accounts bypass distribution for pricing transparency and dedicated supply security, particularly in India's infrastructure corridor developments.
- Online Retailers:Growing share for standardized small-format products among subcontractor spot purchasing.
- Hardware Stores:Local availability for emergency repair and residential renovation.
- Wholesalers:Bulk supply for general contractor project staging and inventory management.
Influence concentrates with distributors; direct sales expand fastest among large-project procurement teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the most active construction chemicals corridor, with Pudong and Lingang New Area hosting formulation plants serving curtain wall projects across China's eastern seaboard.
China
Metro rail expansions in Beijing, Shenzhen, and Chengdu are consuming polyurethane flooring adhesives at accelerating rates. GB standards under SAMR oversight mandate VOC disclosure thresholds that force reformulation investments by domestic compounders. The Yangtze River Delta cluster around Suzhou and Ningbo concentrates silicone sealant production for structural glazing exports.
Germany
Renovation specialists in Berlin and Hamburg are consolidating procurement under energy efficiency service contracts as building stock ages. REACH authorization requirements and the EU F-Gas Regulation restrict tin catalysts and fluorinated blowing agents, compressing reformulation timelines for polyurethane foam sealant manufacturers. The Rhine-Ruhr industrial corridor hosts technical centers developing bismuth-based cure systems.
United States
Commercial retrofit activity in California and New York is elevating specification standards for air barrier sealants under Title 24 and Local Law 97. EPA VOC regulations enforce solvent content limits that diverge from European thresholds, forcing parallel product line maintenance. The Gulf Coast petrochemical corridor supplies propylene oxide feedstock to polyurethane formulators serving the Southeast construction market.
India
Smart city projects in Mumbai, Delhi, and Bangalore are driving specification of expansion joint sealants for airport and metro infrastructure. BIS certification requirements and state-level green building codes are tightening performance benchmarks for thermal management systems. The Gujarat industrial corridor near Ahmedabad concentrates adhesive manufacturing for western India construction corridors.
Netherlands
Façade engineering firms in Rotterdam and Eindhoven are specifying MS polymer systems for their paint compatibility and primerless adhesion properties. EU Green Deal implementation mandates energy performance upgrades for commercial building stock, accelerating replacement cycles. The Randstad logistics hub enables just-in-time distribution to renovation specialists managing multi-property portfolios.
Global Construction Adhesives and Sealants Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with adhesive chemistry portfolios spanning multiple polymer systems. Tier-one positions concentrate among European and North American formulators with established specification relationships in structural glazing and waterproofing channels. Three archetypes dominate: integrated chemical majors with captive silicone supply, construction-specialist compounders with deep distribution partnerships, and regional challengers competing on reformulation speed for emerging market compliance. Capacity expansion and portfolio diversification through hybrid polymer development represent the primary competitive vectors.
Among European chemical majors, Henkel AG & Co. KGaA, Sika AG, and Dow Inc. occupy positions exemplifying the integrated formulation archetype. Henkel represents the diversified adhesive chemistry portfolio model serving insulation panel and structural glazing markets. Sika anchors the construction-specialist position through polyurethane and silicone technology leadership. Dow exemplifies the silicone innovation vector with sustained R&D investment in weather-resistant building envelope systems.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Sika AG |
| 3M |
| H.B. Fuller Company |
| Arkema |
| Dow Inc. |
| Wacker Chemie AG |
| MAPEI S.p.A. |
| Huntsman International LLC |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap compounders in Germany and Italy anchor regional supply clusters, translating generational technical expertise into pricing discipline that resists commoditization pressure from Asian spot-market entrants. Their long-tenured relationships with renovation specialists and facility maintenance operators create contract structures that bundle formulation customization with volume commitments, insulating margin capture from raw material volatility.
Pricing Analysis
Value-based pricing anchored to energy retrofit outcome metrics dominates specification channels serving EU Green Deal compliance projects. Three-tier pricing structure across premium, standard, and economy levels separates certified low-VOC formulations from commodity-grade alternatives, with certification tier and after-sales technical support bundling as primary differentiation drivers. Cost compression in economy-grade polyurethane flooring adhesives is intensifying because propylene oxide feedstock volatility compresses compounder margins. General contractors exhibit highest price sensitivity through spot purchasing behavior, while renovation specialists accept premium positioning for lifecycle performance guarantees.
Supply Chain Analysis
Regional distribution centers in the Randstad logistics hub and Rhine-Ruhr corridor operate hub-and-spoke patterns serving renovation specialists with just-in-time replenishment. Manufacturing concentrates in Germany, China, and India, with silicone monomer production clustering in the Yangtze River Delta and polyurethane systems compounding in the Gujarat industrial corridor. Fumed silica and tin-based catalyst supply rests on Chinese production concentration, creating single-source vulnerability for Western formulators facing REACH authorization deadlines. Distribution runs through national technical distributors who bundle on-site training with specification influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH substance authorization and EU F-Gas Regulation timelines create barrier-to-entry moats for compounders with pre-registered formulation portfolios and technical data packages.
For Market Incumbents: Cement specification relationships through BIM library integration and certified performance data archiving that locks out reformulation-lagged competitors. Prioritize backward integration into silicone monomer supply or captive catalyst production to defend margin position against feedstock volatility. Threaten emerging MS polymer specialists from Asia by accelerating hybrid formulation patent filings in European jurisdictions. For New Entrants and Emerging Players: The price-point gap between Sika-grade premium structural glazing systems and unbranded commodity sealants offers white-space entry through private-label supply to national distributors. Target India's smart city infrastructure corridor where BIS certification requirements remain less stringent than REACH equivalents. Pursue direct sales relationships with offsite panel manufacturers requiring factory-applied systems with extended open times. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European compounders with established REACH registrations but strained working capital from tin-catalyst reformulation costs. Long-term viability hinges on hybrid polymer R&D capabilities spanning silicone and polyurethane chemistry. Watch for inflection signals in MS polymer patent filing velocity from Chinese state-backed research institutes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Monomer Supply | Captive raw material sourcing insulates margin capture from propylene oxide price volatility in Germany. |
| MS Polymer Hybrid Formulation Patent Expansion | Intellectual property positioning in primerless adhesion technology blocks Asian competitor specification entry. |
| BIM Library Technical Data Integration | Direct-to-architect specification bypasses distributor gatekeepers in Dutch and German renovation markets. |
| REACH-Compliant Catalyst Supply Partnership | Bismuth-based cure system securing meets EU F-Gas Regulation sunset deadlines for foam sealant manufacturers. |
| India Infrastructure Corridor Direct Sales Buildout | Bypass distribution margin capture in Mumbai-Delhi-Bangalore metro rail adhesive specifications. |
Research Methodology
Independent corroboration across formulation plant managers, procurement leads at curtain wall engineering firms, distribution channel partners, and technical R&D directors at hybrid polymer developers underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through customs/trade data, Cefic sector reports, SEC 10-K chemical segment disclosures, and SAMR GB standards documentation. Bottom-up volume modeling across chemistry types triangulated against top-down construction spending forecasts.
Rate-of-change decomposition across chemistry segment, application exposure severity, end-user procurement sophistication, and regional regulatory cluster intensity structured the analytical framework. CAGRs derived from elasticity-adjusted demand curves incorporating EU Green Deal retrofit mandate timelines, India infrastructure project pipelines, and China property sector correction impacts. Forecast inputs included petrochemical feedstock price scenario modeling and REACH authorization sunset date compliance schedules.
Inputs from distributor technical sales teams and facility maintenance operator procurement databases were available through the study window; gaps in real-time Chinese MS polymer production capacity data introduce uncertainty bands around Asia-Pacific volume assumptions. Forecasts reflect documented elasticity and regulatory timeline assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Adhesive Equipment Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market
Adhesives & Sealants
Malaysia Adhesives and Sealants Market
Adhesives & Sealants
Germany Adhesives Market
Adhesives & Sealants
Global Isononyl Acrylate Market
Adhesives & Sealants
Hot Glue Guns Market
Adhesives & Sealants
Flooring Adhesive Market
Adhesives & Sealants
United Kingdom Sealants Market
Adhesives & Sealants
Wood Adhesives and Binders Market
Adhesives & Sealants
Europe EVA Adhesives Market
Adhesives & Sealants
Tissue Sealants and Tissue Adhesive Market
Adhesives & Sealants
High Temperature Adhesives Market
Adhesives & Sealants
Urea Formaldehyde Concrete Market
Adhesives & Sealants
North America Sealants Market
Adhesives & Sealants
Japan Adhesives Market
Adhesives & Sealants
Pressure Sensitive Adhesives (PSA) Market