
 United Kingdom Hot-Melt Adhesives Market | 2026-2036
United Kingdom Hot-Melt Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Hot-Melt Adhesives Market Analytics
Polyurethane reactive formulations is shifting the cost-performance calculus away from traditional solvent-based bonding in furniture assembly. Henkel AG & Company KGaA leverages its European R&D footprint to sustain formulation leadership in high-temperature automotive grades. Beardow Adams anchors domestic supply through its Milton Keynes production complex, while HB Fuller Company competes aggressively on packaging segment contracts.
United Kingdom hot-melt adhesives are thermoplastic polymer systems that soften upon heating above their melting point, typically formulated from ethylene vinyl acetate copolymers or polyolefin base polymers with tackifying resins and wax modifiers, and they bond substrates through physical solidification rather than chemical curing for rapid processing in automated lines. Ethylene vinyl acetate formulations dominate volume due to their cost position in corrugated board sealing, while polyolefin grades capture faster growth in food-contact packaging where odor and migration limits tighten. Styrenic block copolymers occupy the premium tier in electronics assembly where precise viscosity control and clean removability command higher margin pools.
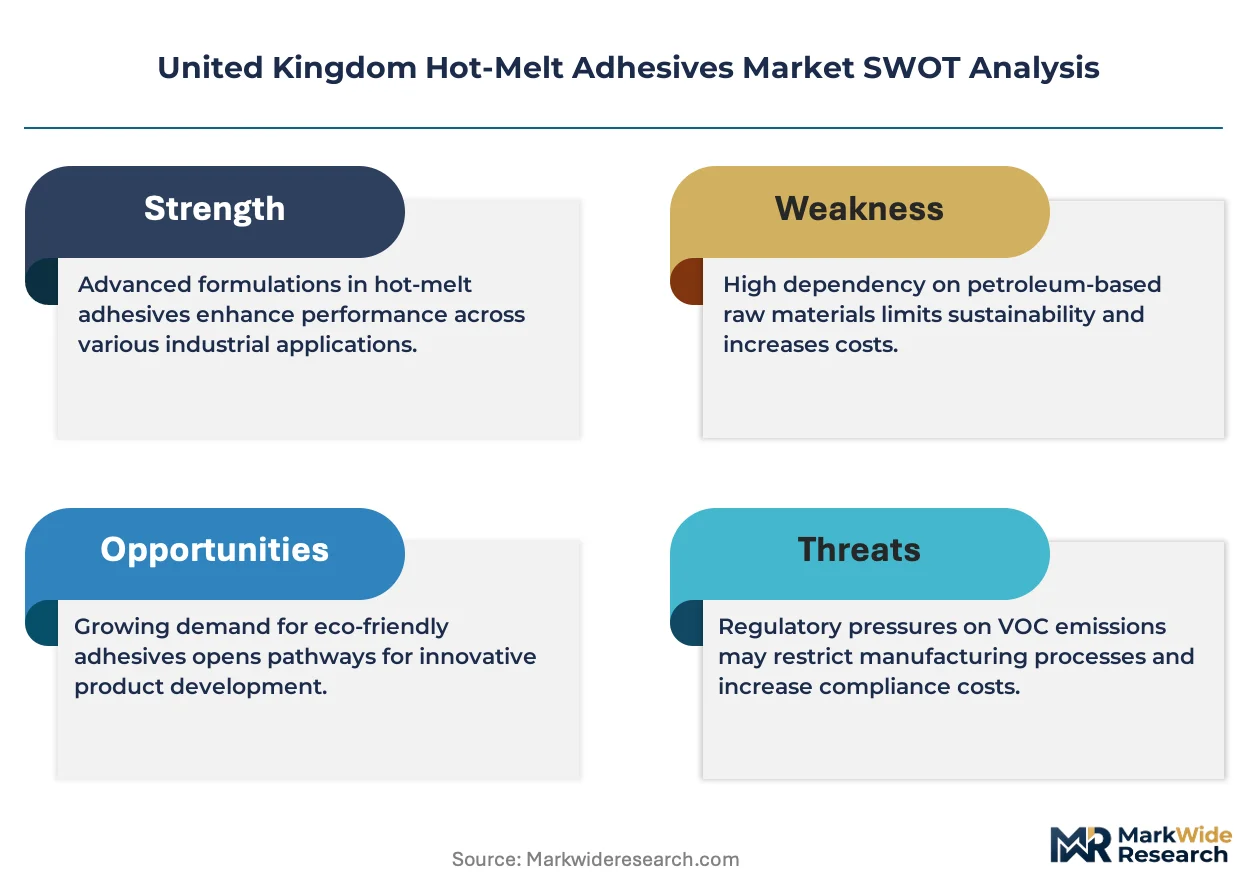
The Health and Safety Executive enforces workplace exposure limits that restrict volatile organic compound emissions, while BSI standards govern adhesive performance in structural timber applications and the EU REACH framework regulates chemical substance registration across the UK supply base. These overlapping requirements compel manufacturers to maintain dual certification portfolios and limit sourcing flexibility. Stakeholders must monitor how post-EU regulatory divergence affects mutual recognition of chemical safety assessments.
Market Dynamics
Polyurethane reactive formulations are displacing solvent-based bonding across furniture and automotive assembly lines, compressing cycle times while eliminating volatile organic compound exposure liabilities for manufacturers.
Growth Catalysts
- EU REACH chemical restrictions:Solvent-based adhesive alternatives face registration barriers and hazard classifications that push converters toward compliant hot-melt systems with lower environmental footprints.
- Lightweight vehicle assembly:Automotive OEMs expand adhesive bonding in aluminum-intensive body structures where mechanical fastening adds weight and corrosion risk.
- Midlands manufacturing corridor:England's concentrated packaging and furniture production base generates localized demand density that rewards just-in-time adhesive supply contracts.
Market Restraints
- Crude oil derivative volatility:Ethylene and propylene feedstock costs swing with naphtha cracking economics, compressing margin visibility for copolymer-based formulations.
- Domestic supply concentration:Beardow Adams and a limited cohort of UK-based compounders control domestic blending capacity, creating bottleneck risk during demand spikes.
- Temperature performance ceiling:Standard ethylene vinyl acetate grades soften above 60°C, excluding them from under-hood automotive applications without costly formulation upgrades.
Strategic Opportunities
- Scotland and Northern England packaging hubs:Regional beverage and food processing clusters remain underpenetrated by reactive hot-melt technical service teams.
- Biobased feedstock integration:Tackifying resins derived from rosin esters and hydrogenated wood resins align with UK Plastic Packaging Tax incentives for renewable content.
- Radio-frequency identification tag bonding:Electronics manufacturers seek low-stress adhesives for antenna substrate attachment in logistics tracking devices.
Industry Challenges
- Formulation chemist scarcity:UK polymer science programs produce insufficient specialists trained in reactive hot-melt rheology and substrate compatibility testing.
- Dual certification maintenance:Manufacturers must simultaneously satisfy BSI timber adhesive standards and evolving post-EU REACH divergence protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Hot-Melt Adhesives Market |
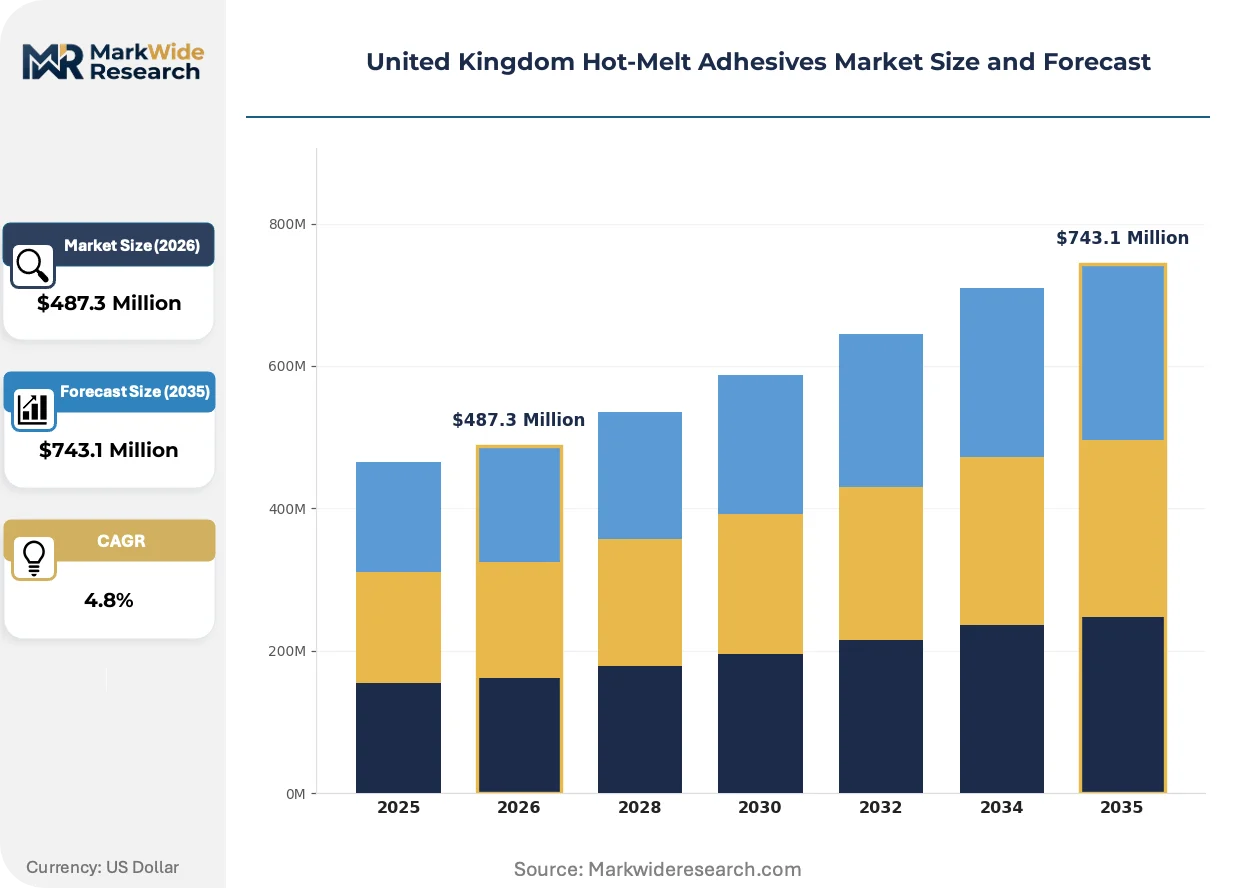
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene Vinyl Acetate, Polyamide, Polyolefin, Styrenic Block Copolymers End User: Automotive OEMs, Packaging Industry, Furniture Manufacturing, Electronics Assembly Application: Labeling, Bookbinding, Woodworking, Assembly Form: Granules, Films, Strips, Pads |
| Companies Covered | Beardow Adams, Arkema, 3M Company, HB Fuller Company, Henkel AG & Company KGaA, Jowat UK Limited, Avery Dennison Corporation, Huntsman Corporation, Sika AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Hot-Melt Adhesives Market Evolving Landscape
Automation integration and regulatory chemistry restrictions are compressing traditional adhesive selection criteria toward systems that bond faster, cure cooler, and leave no solvent residue.
Reactive polyurethane hot-melt dispensing is automating assembly line changeovers in flat-pack furniture manufacturing. IKEA's UK suppliers and domestic kitchen component producers adopt slot-die and swirl-spray applicators that eliminate compressed-air overspray. This shift is automating quality consistency while reducing adhesive waste and compressed air energy costs.
EU REACH substance restrictions continue tightening migration limits for food-contact adhesives. The framework now requires extensive analytical documentation for oligomer content in polyolefin grades used in flexible packaging laminations. UK converters serving Marks & Spencer and Tesco private-label contracts face accelerated reformulation timelines to maintain shelf-life performance under stricter extractables protocols.
Consolidated buying desks at major corrugated packaging groups now specify annual volume commitments with technical service bundling. Smaller independent box plants lose direct supplier relationships as DS Smith and Mondi centralize adhesive procurement across their UK mill networks. This concentration is most visible in the West Midlands where independent converters face margin pressure from captive supply arrangements.
United Kingdom Hot-Melt Adhesives Market Segmentation
Hot-melt adhesive selection in the United Kingdom pivots on thermal performance requirements, substrate compatibility, and automated line integration. Segment boundaries increasingly blur as reactive formulations penetrate traditional thermoplastic strongholds, forcing suppliers to recalibrate technical service deployment.
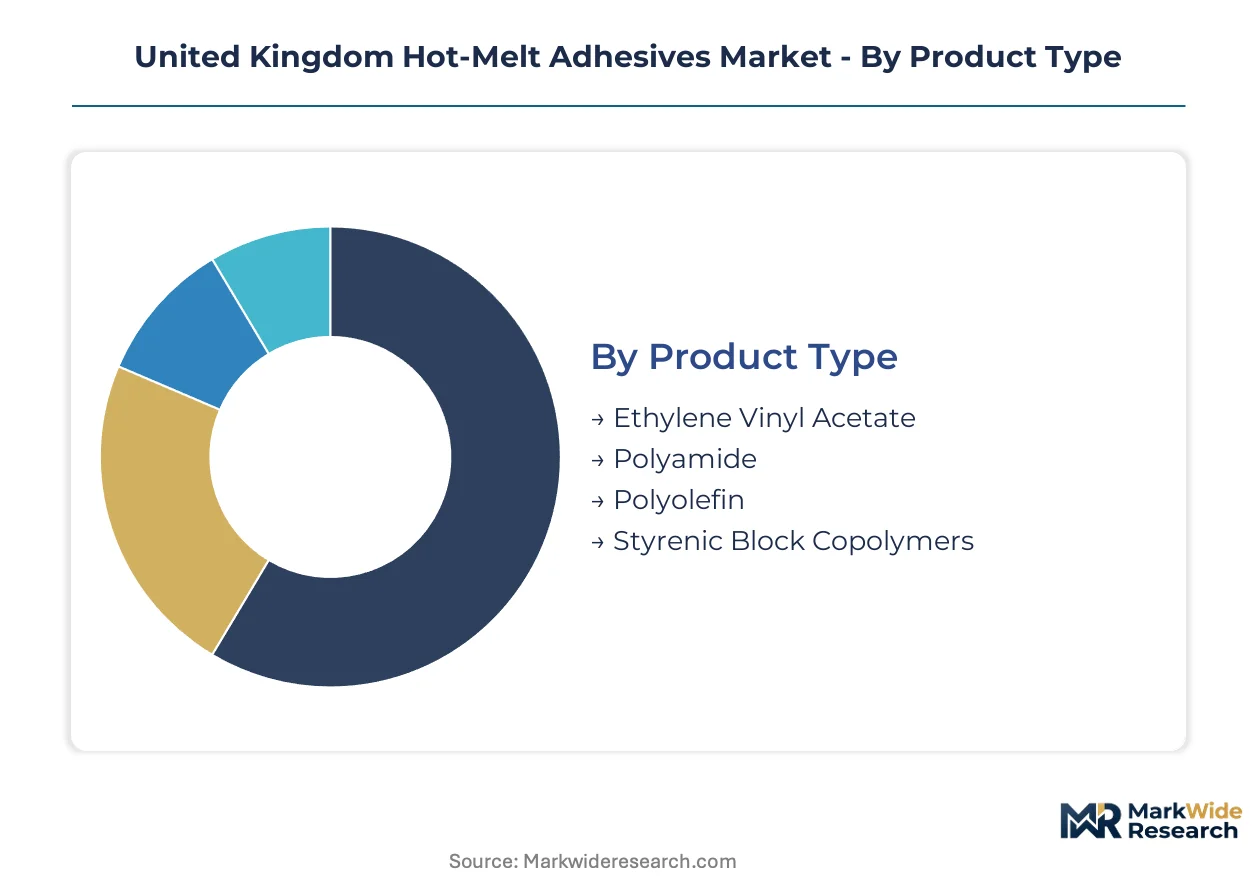
Product Type:
Capital intensity varies sharply across chemistries, with reactive polyurethane systems demanding specialized moisture-controlled production environments while commodity copolymers run on standard extrusion assets.
- Ethylene Vinyl Acetate:Copolymer formulations with 18-40% vinyl acetate content balance tack and flexibility for high-speed corrugated sealing lines. Demand concentrates in England's West Midlands packaging corridor where DS Smith and Mondi operate integrated mill networks, though margin pressure from centralized procurement desks compresses supplier pricing power.
- Polyolefin:Metallocene-catalyzed grades deliver narrow molecular weight distribution for food-contact laminations with minimal odor and migration. Marks & Spencer and Tesco private-label contracts drive specification tightening under EU REACH extractables protocols, accelerating converter reformulation timelines.
- Polyamide:Dimer acid-based high-temperature grades bond leather and textiles in automotive trim assembly.
- Styrenic Block Copolymers:Hydrogenated midblock architectures provide precise viscosity control for electronics removability applications.
Most installed capacity flows through Ethylene Vinyl Acetate. Expansion is steepest in Polyolefin.
End User:
Customer technical sophistication determines service intensity, with automotive and electronics buyers requiring joint formulation development while packaging purchasers negotiate on annual volume commitments.
- Automotive OEMs:Aluminum-intensive body structures expand adhesive bonding to replace mechanical fastening, eliminating corrosion risk and weight penalties. Jaguar Land Rover and Nissan Sunderland operations in England's Midlands specify high-temperature grades for under-hood applications where standard EVA softening limits exclude commodity formulations.
- Packaging Industry:Beverage and food processing clusters in Scotland and Northern England remain underpenetrated by reactive hot-melt technical service teams, creating whitespace for suppliers with regional application engineering capabilities.
- Furniture Manufacturing:Flat-pack producers automate dispensing with slot-die and swirl-spray applicators to eliminate compressed-air overspray.
- Electronics Assembly:Low-stress adhesives bond radio-frequency identification antenna substrates in logistics tracking devices.
Procurement concentration is highest in Packaging Industry. Technical service bundling is expanding most quickly in Automotive OEMs.
Application:
Process speed requirements separate high-throughput continuous operations from batch assembly workflows, dictating adhesive open time and set speed specifications.
- Labeling:Pressure-sensitive hot-melt coatings on PET and PP film facestocks demand clean die-cutting and permanent adhesion to glass, HDPE, and steel containers. Breweries and soft drink bottlers in Scotland drive specification diversity across container geometries.
- Bookbinding:Spine and side gluing operations in print finishing require flexible, fatigue-resistant bonds that withstand repeated opening cycles.
- Woodworking:BSI standards govern structural timber adhesive performance in load-bearing applications.
- Assembly:General industrial bonding spans diverse substrate combinations with formulation customization.
Volume throughput peaks in Labeling. Specification complexity is climbing fastest in Woodworking.
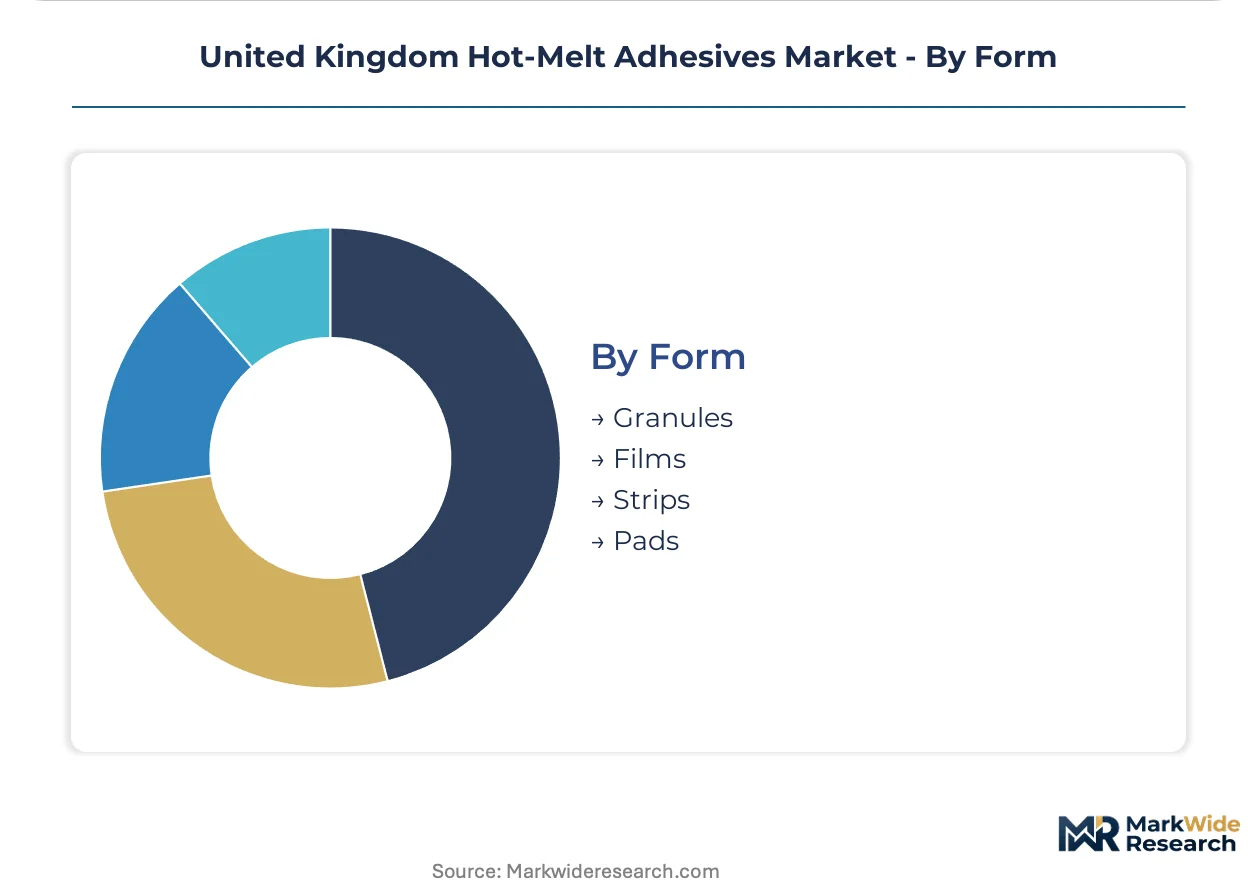
Form:
Physical presentation determines melting equipment capital requirements and energy efficiency in automated versus manual dispensing environments.
- Granules:Bulk-fed extrusion-grade pellets dominate high-volume corrugated and case sealing operations with rapid melt rates and minimal handling labor. Midlands manufacturing corridor demand density rewards just-in-time bulk tanker deliveries from compounders like Beardow Adams.
- Films:Continuous web formats enable precision lamination in flexible packaging and textile bonding with controlled coat weights.
- Strips:Hand-held glue gun feedstock serves maintenance, repair, and small-batch assembly workflows.
- Pads:Pre-measured portions reduce weighing error in batch compounding and manual application settings.
Supply chain infrastructure is optimized for Granules. Niche growth is strongest in Films.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England's Midlands manufacturing corridor concentrates the bulk of UK hot-melt adhesive consumption, with packaging mills and automotive assembly plants driving localized demand density that rewards just-in-time supply contracts.
England Midlands
Corrugated packaging mills operated by DS Smith and Mondi generate sustained volume demand for ethylene vinyl acetate formulations in high-speed sealing lines. The Health and Safety Executive enforces workplace exposure limits that restrict volatile organic compound emissions from solvent-based alternatives. Birmingham and Coventry industrial zones host flat-pack furniture manufacturers automating polyurethane reactive dispensing systems.
Scotland
Beverage bottling clusters around Glasgow and Edinburgh drive specification diversity in pressure-sensitive labeling adhesives for glass and polymer containers. EU REACH migration limits for food-contact materials accelerate converter reformulation timelines. Grangemouth's petrochemical infrastructure supplies feedstock derivatives to regional compounders.
North England
Food processing hubs in Yorkshire and Lancashire remain underpenetrated by reactive hot-melt technical service teams. The UK Plastic Packaging Tax incentivizes biobased tackifying resin adoption in flexible laminations. Manchester and Leeds distribution centers consolidate procurement for independent corrugated converters facing margin pressure.
Wales
Automotive component suppliers in the Cardiff-Newport corridor specify high-temperature grades for under-hood bonding applications. BSI standards govern structural timber adhesive performance in construction materials manufacturing. Deeside industrial parks attract packaging investment from English-headquartered groups seeking lower operating costs.
Northern Ireland
Cross-border supply chains with the Republic of Ireland create dual certification requirements under post-EU regulatory divergence protocols. Belfast-area furniture manufacturers import specialized formulations through Dublin distribution channels. Larne and Belfast ports handle bulk adhesive shipments for regional packaging converters.
United Kingdom Hot-Melt Adhesives Market Competitive Landscape
Capacity expansion dominates the current landscape as compounders respond to procurement consolidation at major corrugated packaging groups. The vendor base separates into three distinct tiers: multinational chemical conglomerates with European R&D footprints, domestic blending specialists with Midlands production assets, and niche applicator technology providers. Strategic archetypes include formulation leaders competing on technical service bundling, scale-driven suppliers capturing annual volume commitments, and regional compounders defending position through logistics proximity. M&A activity and backward integration into tackifying resin production represent the two dominant competitive vectors reshaping supply relationships.
Among UK-based compounders, Beardow Adams anchors domestic supply through its Milton Keynes production complex. Henkel AG & Company KGaA exemplifies the multinational formulation tier with sustained investment in high-temperature automotive grades. HB Fuller Company occupies a position competing aggressively on packaging segment contracts with centralized buying desks.
| Leading Market Players |
|---|
| Beardow Adams |
| Arkema |
| 3M Company |
| HB Fuller Company |
| Henkel AG & Company KGaA |
| Jowat UK Limited |
| Avery Dennison Corporation |
| Huntsman Corporation |
| Sika AG |
| Others |
Value Network & Pricing Analysis
EU REACH chemical registration mandates gate qualified supply access and premium-tier pricing power for UK hot-melt adhesive compounders serving automotive and food-contact segments. Manufacturers lacking extensive substance dossiers face exclusion from Marks & Spencer and Tesco private-label contracts, compressing their addressable market to commodity corrugated applications with thinner margins.
Pricing Analysis
Ethylene and propylene derivative costs transmit directly to formulation pricing through naphtha cracking economics, creating margin volatility for EVA-based commodity grades. Three-tier pricing structure across high-temperature automotive, food-contact compliant, and standard packaging levels separates suppliers by certification depth and technical service bundling. Pricing pressure stems from centralized procurement at DS Smith and Mondi, which extracts annual volume discounts from compounders. Independent corrugated converters exhibit highest price sensitivity due to captive supply arrangements, while automotive OEMs prioritize performance specifications over unit cost.
Supply Chain Analysis
BSI timber adhesive certification and EU REACH substance registration requirements filter qualified suppliers to a narrow cohort with dual compliance portfolios. Domestic blending capacity concentrates in England's Midlands manufacturing corridor, with Beardow Adams anchoring regional supply through its Milton Keynes production complex. Feedstock dependence draws from Grangemouth petrochemical infrastructure and imported tackifying resins. Single-source vulnerability runs through limited UK-based compounders controlling reactive polyurethane moisture-controlled production environments. Distribution runs through just-in-time bulk tanker deliveries to packaging mills and automated dispensing system integrators serving furniture manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK hot-melt adhesives market represents a late-cycle quality story as automotive lightweighting and food-contact migration limits shift procurement toward premium reactive formulations with documented compliance trails.
For Market Incumbents: Anchor technical service capabilities in underpenetrated Scotland and Northern England packaging hubs where reactive polyurethane expertise remains scarce. Deepen backward integration into hydrogenated wood resin production to capture UK Plastic Packaging Tax incentives and defend margin position against feedstock volatility. Prioritize dual certification maintenance under evolving post-EU REACH divergence protocols to preserve access to cross-border Irish supply chains. For New Entrants and Emerging Players: Capture whitespace in regional beverage labeling applications around Glasgow and Edinburgh where specification diversity exceeds local technical service capacity. Target electronics assembly segments seeking low-stress RFID antenna bonding solutions with precise viscosity control requirements. Lead with application engineering partnerships rather than price competition to bypass entrenched supplier relationships at centralized corrugated procurement desks. For Investors and Strategic Acquirers: Roll-up economics work for domestic compounders with Midlands production assets because procurement consolidation at major packaging groups rewards scale and logistics proximity over formulation differentiation. Platform viability extends through the medium-term as regulatory chemistry restrictions deepen compliance moats. Monitor automotive OEM specification shifts toward high-temperature under-hood grades as the inflection signal for premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tackifying Resins | Captures UK Plastic Packaging Tax incentives for renewable content in flexible laminations. |
| Reactive Polyurethane Capacity Expansion | Serves Jaguar Land Rover and Nissan Sunderland lightweighting programs with high-temperature grades. |
| Regional Technical Service Deployment | Penetrates Scotland beverage bottling clusters currently underserved by application engineering teams. |
| Dual Certification Investment | Maintains BSI timber standards and EU REACH compliance access for post-regulatory divergence trade. |
| Automated Dispensing System Partnerships | Integrates slot-die applicators with IKEA supplier flat-pack furniture manufacturing lines. |
Research Methodology
Direct dialogue with adhesive formulation chemists, procurement leads at corrugated packaging groups, automotive Tier 1 supplier quality engineers, and Health and Safety Executive compliance officers grounded qualitative findings in operational reality. Secondary validation drew from BSI standards documentation, EU REACH substance registration databases, UK trade customs records, and SEC filings of multinational chemical conglomerates. Bottom-up volume estimates from individual compounder capacity and top-down demand segmentation triangulated market sizing across chemistries and end-use applications.
Bottom-up modeling tracked ethylene vinyl acetate, polyolefin, polyurethane reactive, and specialty grade volumes through production facility utilization rates and customer contract disclosures. Top-down analysis calibrated segment shares against automotive production data from England's Midlands assembly plants and packaging output metrics from DS Smith and Mondi mill networks. CAGRs derived from regression analysis of historical feedstock cost pass-through patterns and regulatory-driven substitution elasticities across solvent-based alternatives. Price-volume relationships incorporated centralized procurement desk negotiation dynamics and just-in-time supply contract premiums.
Feedstock derivative volatility, post-EU regulatory divergence timing, and automotive platform electrification schedules are the dominant revision risks to projection assumptions. A model refresh is warranted upon material change in EU REACH substance restriction timelines or significant capacity additions by domestic compounders.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle East & Africa Construction Adhesives & Sealants Market
Adhesives & Sealants
2K Epoxy Adhesives Market
Adhesives & Sealants
Russia Adhesives Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
Flexible Packaging Adhesive Market
Adhesives & Sealants
Epoxy Active Diluent Market
Adhesives & Sealants
Specialty Adhesives Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
Lamination Adhesive Market
Adhesives & Sealants
Global Slack Wax Market
Adhesives & Sealants
Spain Adhesives Market
Adhesives & Sealants
EMEA Epoxy Adhesives Market
Adhesives & Sealants
Lignin for Adhesives Market
Adhesives & Sealants
United Kingdom Adhesives Market
Adhesives & Sealants
Japan Adhesives Market