
 Global Epoxy Tooling Board Market | 2026-2036
Global Epoxy Tooling Board Market Size, Share, and Industry Trends Forecast 2026-2036
Global Epoxy Tooling Board Market Analysis
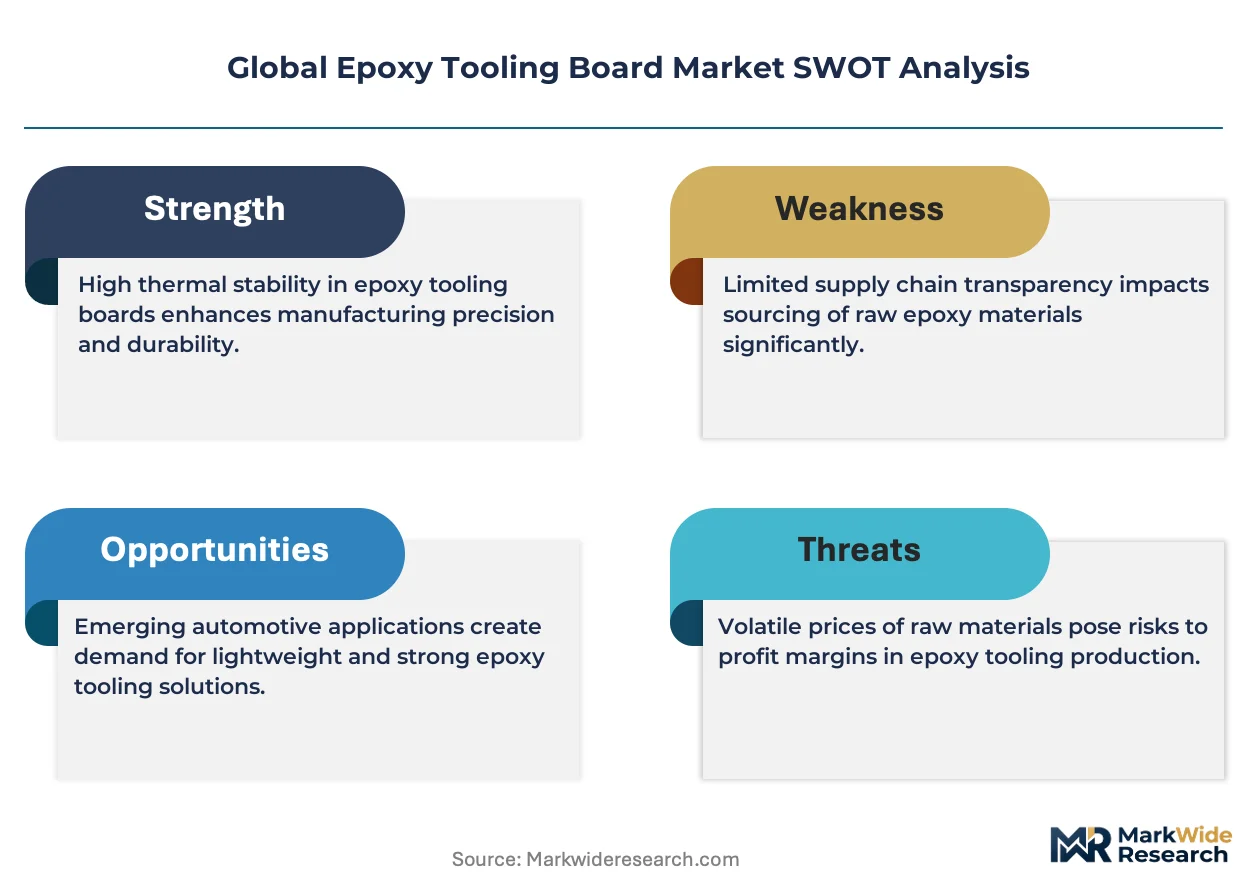
The EU Green Deal is repositioning epoxy tooling board procurement across European aerospace and wind energy supply chains, with converters now screening suppliers for REACH-compliant resin systems. Sika Axson leverages its vertically integrated polymer portfolio to supply certified board grades to Airbus tier-one mold shops. Huntsman Corporation anchors its position through dedicated R&D centers in Basel and Shanghai that formulate temperature-stable epoxy systems for autoclave cycling. RAMPF Tooling Solutions differentiates via polyurethane-epoxy hybrid boards that compete on price in industrial prototyping segments.
Epoxy tooling board denotes high-density, dimensionally stable epoxy resin blocks engineered for master models, check fixtures, and composite layup molds, typically formulated with glass microsphere fillers to achieve compressive strengths exceeding 70 MPa and thermal stability past 130 degrees Celsius. Rigid board dominates current volume owing to its established use in aerospace master models where CNC machinability and low coefficient of thermal expansion prevent dimensional drift across cure cycles. Thermal curing technology leads application method share, though UV curing is gaining traction in automotive styling studios where rapid turnaround of design prototypes compresses development timelines.
REACH in Europe, EPA TSCA in the United States, and GB standards administered by SAMR in China collectively constrain bisphenol-A and volatile organic compound content in epoxy formulations, forcing reformulation investments that raise barriers for undifferentiated imports. ECHA's ongoing substance evaluation of epoxy curing agents is accelerating substitution toward anhydride-based hardeners in board grades destined for marine and industrial equipment applications. Stakeholders must monitor regulatory divergence across these three jurisdictions to avoid stranded inventory and qualify alternative chemistries before compliance deadlines tighten.
Market Dynamics
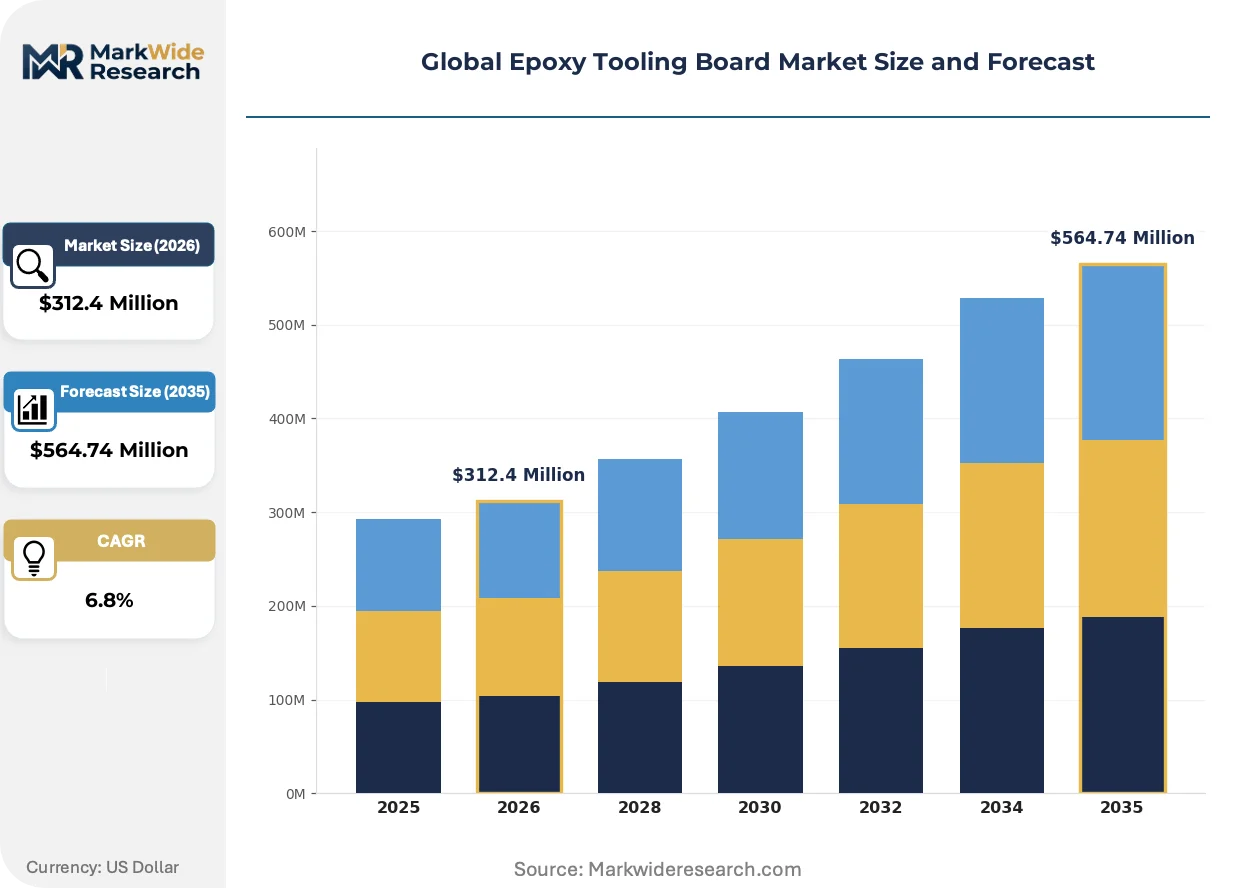
Aerospace mold shops in Germany, China, and the United States are accelerating epoxy tooling board consumption as composite wing and fuselage programs expand autoclave capacity. REACH substance evaluations in Europe and EPA TSCA reviews in North America are simultaneously constraining legacy resin formulations while opening qualification pathways for low-VOC alternatives.
Growth Catalysts
- Wind blade fabrication scale-up:Manufacturers in China and Germany are commissioning longer blades that require dimensionally stable master models for female mold production.
- REACH-compliant resin reformulation:ECHA's ongoing evaluation of epoxy curing agents is creating first-mover advantages for converters with certified low-bisphenol-A board grades.
- Autoclave temperature cycling:Aerospace OEMs specify tooling boards rated past 180 degrees Celsius for thermoplastic composite consolidation cycles.
Market Restraints
- Glass microsphere supply concentration:High-purity filler sourcing clusters in limited coastal processing zones, exposing board producers to logistics volatility.
- Substitute material encroachment:Polyurethane-epoxy hybrid boards compete on price for industrial prototyping where thermal stability requirements relax.
- Regulatory fragmentation:Divergent GB standards under SAMR, REACH in Europe, and EPA TSCA in the United States force parallel qualification runs that extend product launch timelines.
Strategic Opportunities
- Marine superyacht tooling:Italian and Dutch shipbuilders are adopting epoxy boards for one-off custom hull plug fabrication where CNC accuracy replaces traditional hand lofting.
- UV curing channel expansion:Automotive styling studios in Japan are installing UV-curable board capacity to compress design iteration cycles from weeks to days.
- India aerospace tier-two emergence:Bangalore and Hyderabad mold shops are qualifying European-certified board grades for Airbus and Boeing supplier programs.
Industry Challenges
- Certification timeline compression:EASA and FAA material qualification protocols for flight-critical tooling impose 18-24 month validation periods that strain working capital.
- CNC programming expertise scarcity:Master model fabrication requires simultaneous competence in epoxy machinability and composite mold design that training pipelines have not matched.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Epoxy Tooling Board Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Board, Flexible Board, Foam Core, Composite Material Application: Aerospace, Automotive, Marine, Industrial Equipment End User: Manufacturers, OEMs, Aerospace Companies, Tooling Providers Technology: Thermal Curing, UV Curing, Injection Molding, CNC Machining |
| Companies Covered | Sika Axson, BCC Products Inc, Trelleborg AB, Alchemie Ltd, General Plastics Manufacturing Company, RAMPF Tooling Solutions, Base Group, Guangzhou LiHong Mould Material Co, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Epoxy Tooling Board Market Emerging Trajectories
Epoxy tooling board production is bifurcating between aerospace-grade thermal stability and industrial-grade cost efficiency as end-use specifications diverge. Formulation chemistry, curing methodology, and procurement contracting are each undergoing distinct transformations.
Hybrid epoxy systems incorporating anhydride-based hardeners are consolidating market share in marine and industrial equipment segments where ECHA's substance evaluation has flagged traditional amine curing agents. German mold shops serving superyacht builders have adopted these formulations fastest, compressing supplier qualification cycles by six months compared to legacy amine-based boards.
REACH authorization requirements for bisphenol-A derivatives are forcing European converters to reformulate entire product lines before 2026 sunset dates. Board grades destined for wind energy applications face the tightest substitution timelines, with Danish and Spanish blade manufacturers now mandating supplier certificates of compliance before contract renewal.
Long-term supply agreements with indexed raw material clauses are displacing spot purchasing in aerospace procurement. Tier-one mold shops in Toulouse, Hamburg, and Wichita are locking three-year epoxy board contracts with price adjustment mechanisms tied to benzene and epichlorohydrin futures, insulating program budgets from petrochemical volatility.
Global Epoxy Tooling Board Market Segmentation
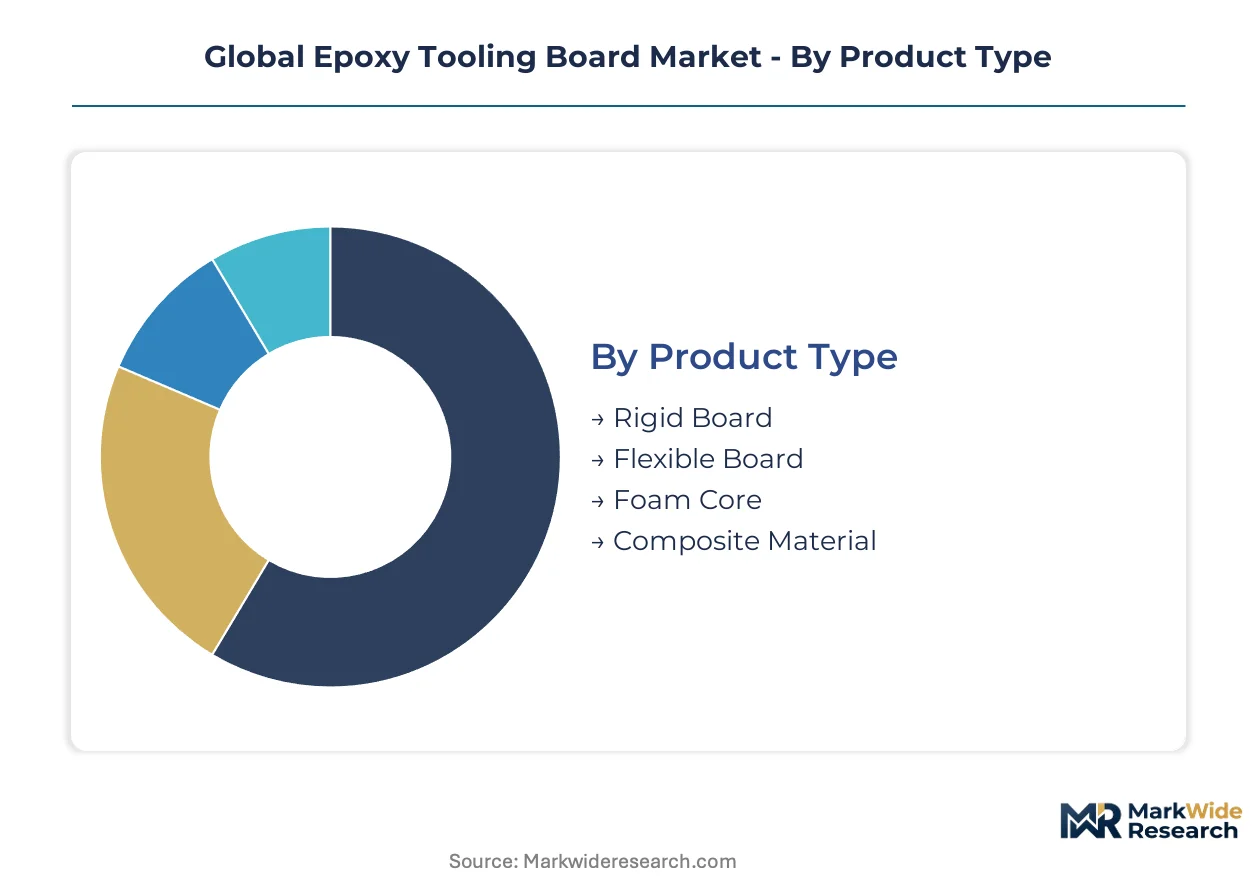
Epoxy tooling board specifications diverge sharply between aerospace master models requiring thermal stability past 180 degrees Celsius and industrial prototypes tolerating lower-performance grades. Procurement patterns track these technical tiers, with long-term contracts dominating aerospace while spot purchasing persists in automotive styling studios.
Product Type:
Customization intensity spans from fully engineered rigid systems to commodity foam cores, with price multiples exceeding 4x between premium and standard tiers.
- Rigid Board:High-density epoxy resin blocks formulated with glass microsphere fillers achieve compressive strengths exceeding 70 MPa and thermal stability past 130 degrees Celsius. German and Chinese aerospace mold shops specify these grades for autoclave cycling in composite wing fabrication, though glass microsphere supply concentration in limited coastal processing zones creates logistics exposure.
- Flexible Board:Modified epoxy formulations incorporating plasticizers or flexible hardeners permit limited deflection without fracture, serving check fixtures and assembly jigs where dimensional tolerance must accommodate part variability. Automotive manufacturers in Japan and Germany deploy these for prototype door panel and fascia validation.
- Foam Core:Lightweight expanded epoxy structures reduce material cost for large master models in wind blade fabrication. Chinese blade manufacturers commission these for female mold plugs exceeding 80 meters in length.
- Composite Material:Hybrid constructions layering epoxy board with carbon fiber or fiberglass skins enhance stiffness-to-weight ratios for marine hull plugs. Italian superyacht builders in Viareggio specify these for one-off custom fabrication.
Most installed capacity flows through Rigid Board. Expansion is steepest in Composite Material as marine and industrial segments adopt hybrid constructions.
Application:
End-use specifications dictate margin structures, with aerospace commanding premium pricing for certified grades and automotive accepting lower-performance alternatives.
- Aerospace:Master models for composite wing and fuselage molds require CNC machinability, low coefficient of thermal expansion, and autoclave temperature ratings past 180 degrees Celsius. Toulouse, Hamburg, and Wichita mold shops lock three-year supply contracts with indexed raw material clauses to insulate program budgets from benzene and epichlorohydrin volatility.
- Automotive:Design studios prioritize rapid turnaround over thermal stability, with UV-curable board grades compressing iteration cycles from weeks to days. Japanese styling centers in Toyota City and Nissan Technical Center have installed dedicated UV curing capacity.
- Marine:Custom hull plug fabrication for superyachts demands CNC accuracy that replaces traditional hand lofting. Dutch builders in Amsterdam and Italian yards in Viareggio specify REACH-compliant anhydride-cured grades.
- Industrial Equipment:General-purpose tooling for machinery prototypes and factory fixtures tolerates lower specifications, exposing this segment to polyurethane-epoxy hybrid competition on price.
Procurement value concentrates in Aerospace. Fastest volume gains are occurring in Marine as superyacht builders abandon traditional lofting methods.
End User:
Customer sophistication determines qualification timelines, with tier-one aerospace OEMs imposing 18-24 month validation protocols that strain supplier working capital.
- Manufacturers:Wind blade and industrial equipment producers purchase standard grades in volume, prioritizing cost efficiency over certification depth. Chinese blade manufacturers commission the longest master models, driving demand for foam core and rigid board hybrids.
- OEMs:Airbus and Boeing tier-one suppliers in Germany, France, and the United States mandate supplier certificates of REACH and EPA TSCA compliance before contract renewal, with EASA and FAA material qualification protocols extending onboarding timelines.
- Aerospace Companies:Direct procurement by airframers for in-house mold shops concentrates in Toulouse, Hamburg, and Seattle, where long-term agreements with price adjustment mechanisms are displacing spot purchasing.
- Tooling Providers:Independent mold shops serving multiple end-use segments require portfolio breadth across thermal stability ratings, favoring converters with vertically integrated polymer capabilities.
Contract duration stretches longest for Aerospace Companies. Tooling Providers are gaining share fastest as outsourcing of master model fabrication accelerates.
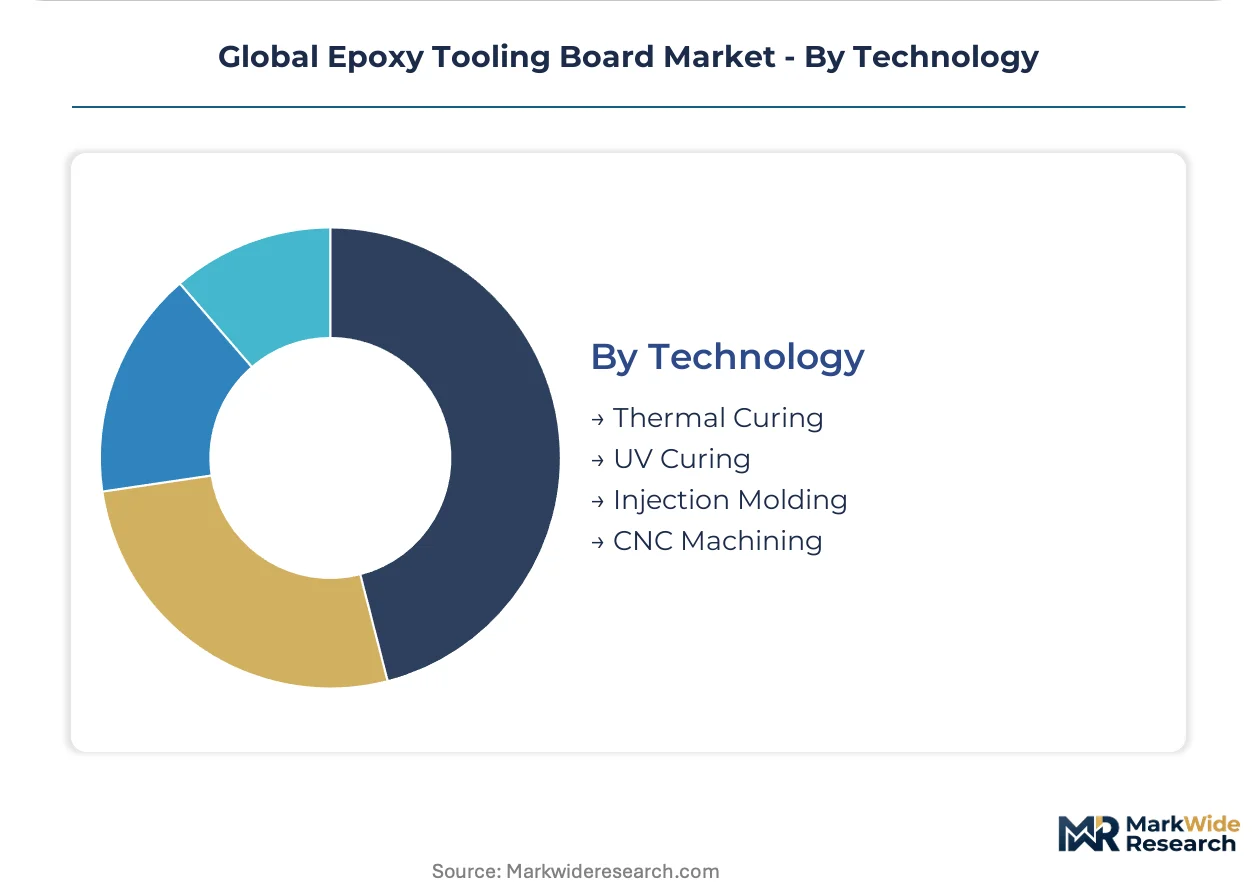
Technology:
Curing methodology and fabrication technique determine throughput economics, with thermal systems dominating aerospace and UV installations penetrating automotive studios.
- Thermal Curing:Conventional oven or autoclave curing delivers full crosslink density and thermal stability required for aerospace master models. Huntsman Corporation anchors its position through dedicated R&D centers in Basel and Shanghai that formulate temperature-stable systems for autoclave cycling.
- UV Curing:Photoinitiated polymerization enables near-instantaneous cure, compressing design iteration timelines in automotive styling. Japanese studios have invested most aggressively in UV-capable board capacity.
- Injection Molding:Limited application for small, complex tooling components where net-shape forming reduces machining time. Industrial equipment prototyping employs this for bracket and fixture production.
- CNC Machining:Subtractive fabrication remains universal for master model production, though programming expertise scarcity in epoxy machinability and composite mold design constrains shop capacity expansion.
Capital deployment concentrates in Thermal Curing. UV Curing is climbing the fastest as Asian automotive studios upgrade styling center capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Epoxy tooling board manufacturing originated in post-war Germany and the United States, where aerospace prototyping demands drove early formulation chemistry. Production scale later concentrated in China as wind energy composite fabrication expanded. Today procurement patterns track composite manufacturing clusters across three continents.
United States
Wichita and Seattle aerospace mold shops sustain rigid board demand for Boeing supplier programs. EPA TSCA reviews of bisphenol-A derivatives constrain legacy resin imports while qualifying low-VOC alternatives. Tooling providers in the Pacific Northwest are locking three-year supply contracts with indexed epichlorohydrin clauses to hedge petrochemical volatility.
Germany
Airbus tier-one suppliers in Hamburg and Toulouse-dependent German shops drive premium-grade consumption for autoclave-rated master models. ECHA REACH substance evaluations of amine curing agents accelerate anhydride-based reformulation across Bavarian converter facilities. Hamburg mold shops have compressed supplier qualification cycles by six months for REACH-certified board grades.
China
Wind blade manufacturers commission 80-meter-plus female mold plugs, driving foam core and rigid board hybrid demand. SAMR-administered GB standards on volatile organic compound content parallel REACH constraints, forcing parallel qualification runs. Yangtze River Delta processing zones concentrate glass microsphere supply, exposing board producers to coastal logistics volatility.
Japan
Automotive styling studios in Toyota City and Nissan Technical Center deploy UV-curable board grades to compress design iteration timelines. METI industrial standards govern epoxy formulation disclosure requirements for imported resin systems. Osaka-based mold shops are installing dedicated photoinitiated curing capacity to serve compressed prototype schedules.
Italy
Viareggio superyacht builders abandon traditional hand lofting for CNC-machined hull plugs, opening marine-grade board demand. EU Green Deal procurement screening now mandates REACH-compliant resin certificates for custom fabrication contracts. Dutch-Italian supply corridors are consolidating anhydride-cured board distribution for one-off yacht tooling programs.
Global Epoxy Tooling Board Market Vendor Landscape
Capital-heavy integrated resin producers compete with asset-light specialty converters across distinct capability tiers. Market structure tilts toward consolidated supply at the aerospace-grade extreme and fragmented competition in industrial prototyping segments. Three archetypes dominate: vertically integrated polymer houses, regional board fabricators with captive machining services, and hybrid-technology specialists competing on price. Strategic moves concentrate on backward integration into specialty hardener supply and long-term contracting with raw material indexation.
Within the integrated polymer tier, Sika Axson and Huntsman Corporation exemplify archetypes spanning European REACH compliance and Asian production scale. RAMPF Tooling Solutions occupies a position among hybrid-technology specialists competing at the industrial-grade boundary. Chinese fabricators including Guangzhou LiHong Mould Material Co. represent regional converters serving wind energy demand clusters. Trelleborg AB and General Plastics Manufacturing Company sit within the diversified industrial materials tier, leveraging cross-product manufacturing infrastructure.
| Leading Market Players |
|---|
| Sika Axson |
| BCC Products Inc |
| Trelleborg AB |
| Alchemie Ltd |
| General Plastics Manufacturing Company |
| RAMPF Tooling Solutions |
| Base Group |
| Guangzhou LiHong Mould Material Co |
| Huntsman Corporation |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap converters in Germany and coastal China anchor supply discipline through long-held relationships with benzene and epichlorohydrin suppliers, insulating aerospace-grade board pricing from spot volatility while compressing margins for undifferentiated industrial grades. REACH compliance investments and glass microsphere logistics exposure concentrate pricing power among vertically integrated polymer houses.
Pricing Analysis
Three-tier pricing structure across aerospace-certified, industrial-standard, and wind-energy-economy levels separates procurement contracts by thermal stability rating and EASA qualification depth. Price differentiation hinges on REACH certification status and autoclave cycle ratings above 180 degrees Celsius. Cost compression in industrial prototyping intensifies as polyurethane-epoxy hybrids undercut on thermal stability trade-offs. Wind blade manufacturers in China exhibit highest price sensitivity; Airbus tier-one mold shops in Hamburg show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale aerospace demand from Toulouse and Wichita, while distributor networks serve fragmented automotive styling studios. Production concentrates in Germany, China, and the United States, with glass microsphere processing anchored in Yangtze River Delta coastal zones. Raw material flows draw from benzene crackers, epichlorohydrin plants, and high-purity hollow glass sphere facilities. Single-source vulnerability in specialty hardener supply from Bavarian chemical parks threatens REACH-compliant board output.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between European REACH compliance costs and Chinese wind-blade scale economics creates margin capture opportunities for converters with dual-continent formulation capabilities.
For Market Incumbents: Anchor aerospace certification portfolios through captive anhydride hardener supply, defending against polyurethane-epoxy hybrid encroachment in industrial segments. Compress EASA qualification timelines by six months through pre-validated resin libraries. Prioritize backward integration into glass microsphere sourcing to neutralize Yangtze River Delta logistics exposure. For New Entrants and Emerging Players: E-commerce tooling material platforms offer direct access to Bangalore and Hyderabad tier-two mold shops bypassing established distributor markups. Marine superyacht hull plug fabrication in Viareggio and Amsterdam presents the most penetrable segment, with REACH-compliant anhydride-cured grades commanding premium positioning. Target one-off custom fabrication shops with CNC machining service bundling. For Investors and Strategic Acquirers: Specialty chemical conglomerates with existing epoxy resin divisions are the most active acquirer in this space, seeking REACH-certified board capabilities for aerospace vertical integration. Five-to-ten year viability favors converters with indexed raw material contracting and dual-continent production footprints. Monitor ECHA substance evaluation timelines for amine curing agent restrictions as inflection signals for anhydride-based formulation winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Hardeners | Secures REACH-compliant supply chains against ECHA amine restrictions for Bavarian converters. |
| Long-term Supply Agreement with Raw Material Indexation | Locks benzene and epichlorohydrin pricing for Hamburg mold shops across multi-year aerospace programs. |
| UV Curing Capacity Installation | Enables Toyota City styling studios to compress design iteration cycles from weeks to days. |
| REACH Certification Pre-Validation | Accelerates supplier qualification by six months for Airbus tier-one procurement in Toulouse. |
| Hybrid Board Technology Licensing | Transfers polyurethane-epoxy formulations to industrial prototyping segments competing on price. |
Methodological Framework
Multiple input streams — converter production data, aerospace procurement contract structures, and regulatory filing repositories — were reconciled across primary interviews with epoxy formulation chemists, wind blade procurement directors, and EASA certification officers, validated against secondary sources including ECHA substance evaluation databases, SAMR GB standard releases, and customs trade flow records. Bottom-up volume builds from individual mold shop consumption patterns were cross-checked against top-down resin producer shipment disclosures.
Historical capacity utilization trends were cross-referenced against expert panel assessments of autoclave expansion timelines across the projection horizon. Segmentation modeling incorporated product type rigidity grades, application thermal stability requirements, end-user contract duration patterns, and curing technology adoption curves. CAGRs were derived from slope-consistency tests across volume and value trajectories, with wind blade length scaling and aerospace program ramp schedules serving as industry-specific demand anchors.
Regulatory sunset date acceleration, glass microsphere supply disruption, and aerospace program delay are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding REACH reformulation compliance rates and SAMR VOC enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
United Kingdom Sealants Market
Adhesives & Sealants
South America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Mexico Sealants Market
Adhesives & Sealants
Global Silicone Adhesives Market
Adhesives & Sealants
Asia-Pacific Adhesives and Sealants Market
Adhesives & Sealants
Capillary Underfill Material Market
Adhesives & Sealants
Europe Construction Adhesives Market
Adhesives & Sealants
Amine Curing Agents Market
Adhesives & Sealants
Middle East and Africa Adhesives Market
Adhesives & Sealants
Tile Adhesive Market
Adhesives & Sealants
PVA Glue Market
Adhesives & Sealants
France Sealants Market
Adhesives & Sealants
Flooring Installation Adhesives Market
Adhesives & Sealants
Wood Repair Epoxy Market
Adhesives & Sealants
Europe Polyurethane (PU) Hot-Melt Adhesives Market