
 Europe Polycarbonate Sheets Market | 2026-2036
Europe Polycarbonate Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Polycarbonate Sheets Market Foresight
Co-extrusion with UV-resistant cap layers is reconfiguring how polycarbonate sheets deliver weathering performance across European cladding systems. Covestro leverages captive resin supply to anchor its position in optical-grade sheet production. SABIC sustains scale advantages through backward integration into bisphenol A and phosgene intermediates. Brett Martin specializes in multiwall configurations for the agricultural sector across the British Isles.
Polycarbonate sheets are thermoplastic panels extruded from bisphenol A and phosgene-derived polymer resins, typically offering light transmission above 80 percent alongside impact resistance exceeding 200 times that of glass. Their primary commercial purpose spans protective glazing, daylighting systems, and transparent structural barriers where weight reduction and shatter resistance prove critical. Solid sheets dominate margin pools in security and ballistic applications, while multiwall variants capture volume leadership in European greenhouse and conservatory construction. Corrugated formats compete primarily on installed-cost efficiency within agricultural outbuildings across Southern Europe.
REACH registration requirements govern monomer inputs and restrict certain flame-retardant additives within the EU single market. The F-Gas Regulation and CE marking directives shape thermal insulation specifications and fire-performance classifications for building-integrated sheet applications. ECHA substance evaluations periodically tighten permissible additive chemistries, forcing reformulation cycles among extrusion compounders. Stakeholders must monitor evolving EPBD energy-efficiency thresholds that will determine which sheet thicknesses and multiwall geometries qualify for public procurement and green building certification schemes.
Market Dynamics
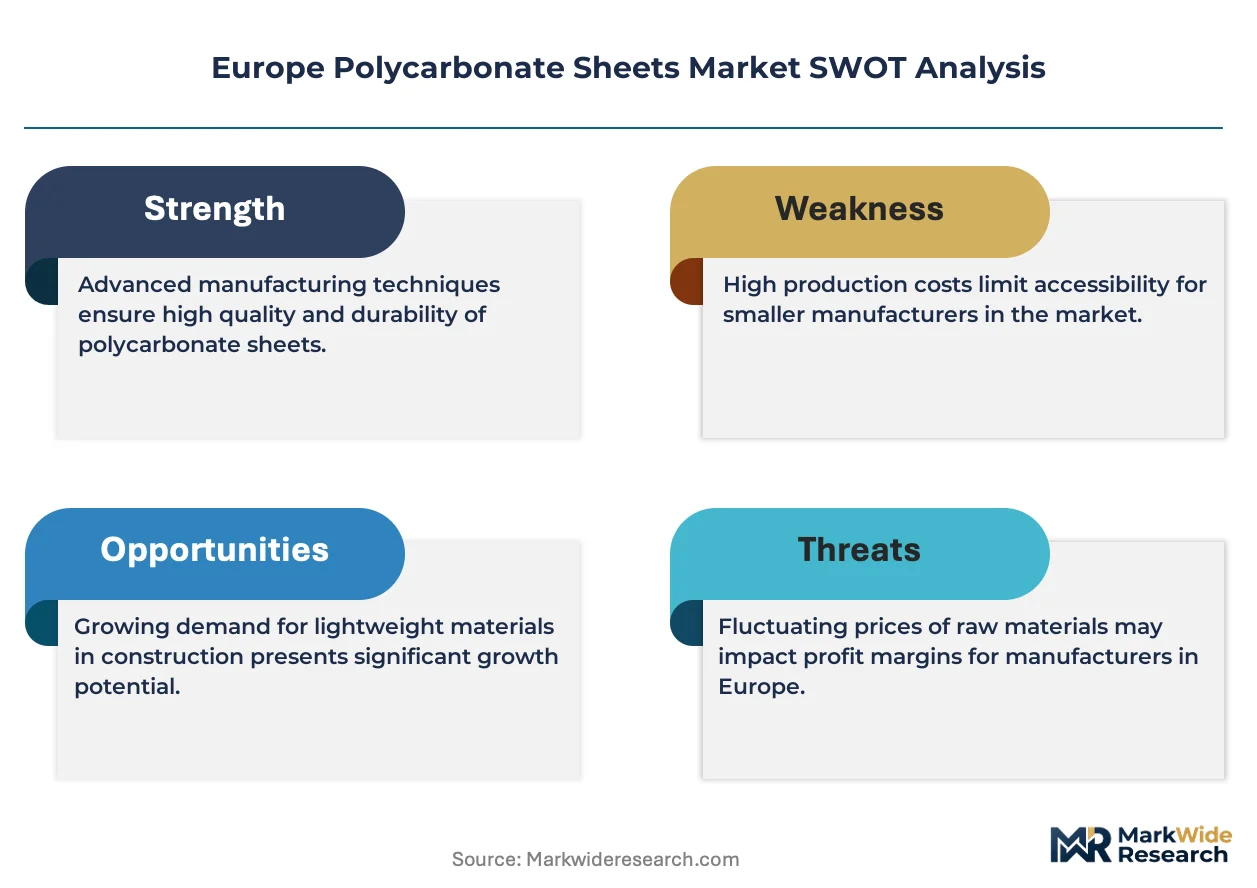
Co-extrusion technology with UV-resistant cap layers is reconfiguring weathering performance standards across European cladding systems, forcing extruders to retool lines or lose specification authority in commercial construction tenders.
Growth Catalysts
- EU Green Deal decarbonization mandates:Building renovation targets in Germany and France are accelerating specification of high-performance glazing materials that reduce thermal loads and operational emissions.
- Greenhouse agriculture expansion:Diffused light transmission requirements in Spain and Italy are pulling multiwall sheet volumes into protected cultivation infrastructure.
- REACH-compliant reformulation:Lower-emission extrusion processes are opening procurement channels previously restricted by additive chemistry concerns.
Market Restraints
- Bisphenol A feedstock concentration:Three integrated petrochemical complexes in Germany and the Netherlands control over 70 percent of European BPA supply, creating margin squeeze risk during upstream volatility.
- PMMA and ETFE substitution:Premium architectural projects in Switzerland and Austria are specifying fluoropolymer membranes for maximum light transmission with comparable impact resistance.
- ECHA substance evaluation cycles:Periodic tightening of flame-retardant additive approvals forces compounders into 18-24 month reformulation timelines that disrupt customer qualification programs.
Strategic Opportunities
- Eastern European construction catch-up:Poland and Romania are underpenetrated in commercial daylighting relative to Western European stock, with EU cohesion funds financing public building retrofits.
- Agricultural photovoltaic integration:Agrivoltaic canopy designs in Italy are specifying translucent structural panels that combine crop protection with distributed generation mounting.
- EPBD energy-efficiency thresholds:Upcoming revisions to the Energy Performance of Buildings Directive will mandate higher thermal performance in glazing, favoring multiwall geometries with improved insulation values.
Industry Challenges
- Extrusion die engineering talent:Specialized knowledge in multiwall channel geometry optimization is concentrated among retiring technicians in Germany and Italy.
- CE marking fire-performance testing:Extended laboratory queues for EN 13501-1 classification are delaying product launches by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Polycarbonate Sheets Market |
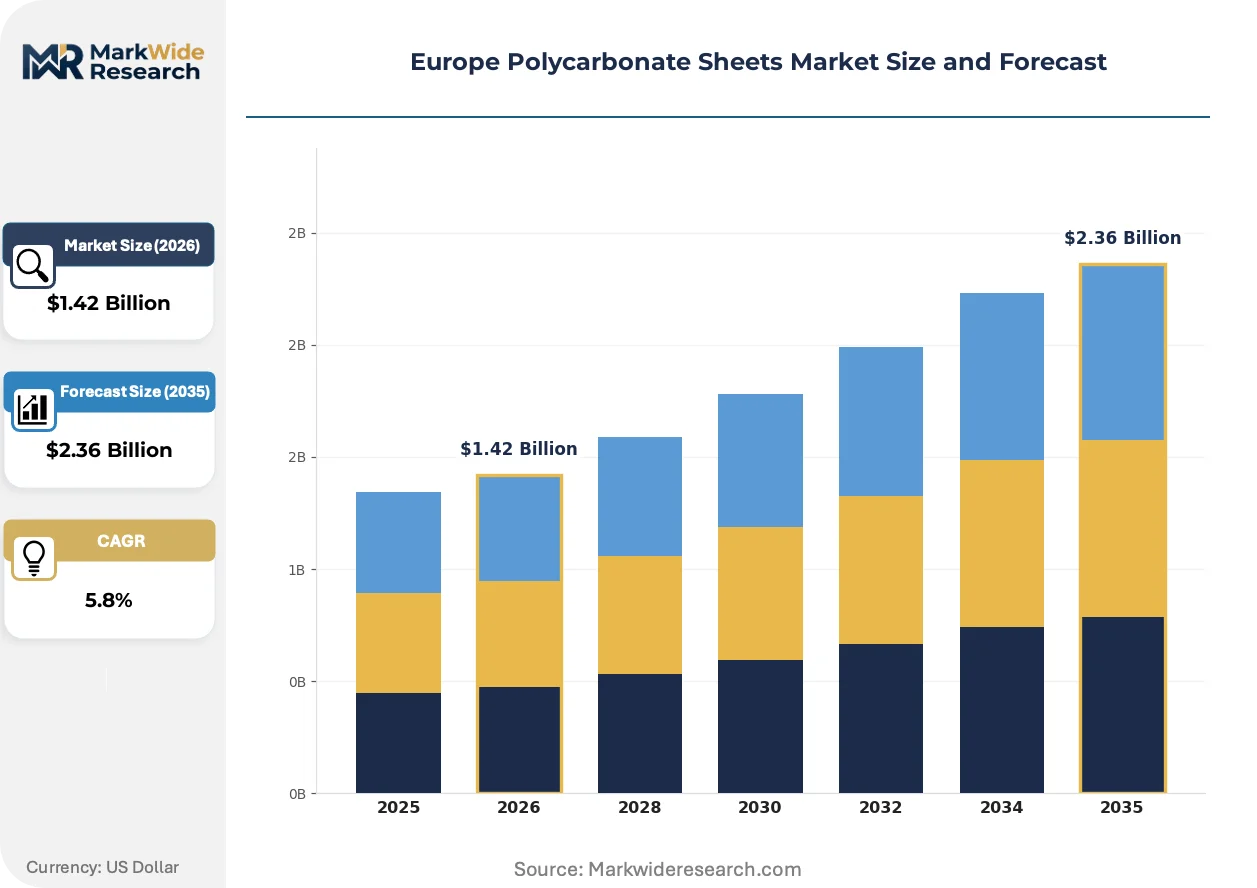
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Sheets, Multiwall Sheets, Corrugated Sheets, Textured Sheets Application: Construction, Automotive, Electronics, Signage End User: Manufacturers, Retailers, Distributors, Importers Thickness: 2 mm, 4 mm, 6 mm, 10 mm |
| Companies Covered | SABIC, EXOLON GROUP GMBH, Brett Martin, Corplex, Palram Industries Ltd., Covestro, Arla Plast, dott.gallina Srl, 3A Composites GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Polycarbonate Sheets Market Shifts & Advancements
Material science advances and regulatory tightening are converging to reshape how polycarbonate sheets deliver performance across building envelope and agricultural applications.
Co-extruded cap-layer technology is hybridizing conventional UV stabilization approaches with nano-ceramic infrared reflectors. Commercial specifiers in France and the Benelux are requesting these configurations for atrium glazing where solar heat gain control competes with daylighting objectives. The hybridizing effect is compressing specification cycles for standalone UV-protected sheets while elevating performance benchmarks for weathering guarantees.
REACH authorization requirements for certain phthalate-based plasticizers are forcing compounders toward bio-based and non-phthalate alternatives. Extrusion houses in Germany report reformulation costs equivalent to 12-18 months of margin compression. Agricultural sheet segments with less price elasticity are absorbing these transitions faster than commodity construction grades.
Consolidated buying by large greenhouse operators in the Netherlands and Spain is compressing distributor margins and accelerating direct manufacturer relationships. Volume commitments now anchor 40 percent of agricultural offtake, displacing the traditional merchant stockholder model. Southern European growers are leading this consolidation, driven by scale expansion in Almería and Murcia protected cultivation zones.
Europe Polycarbonate Sheets Market Segmentation
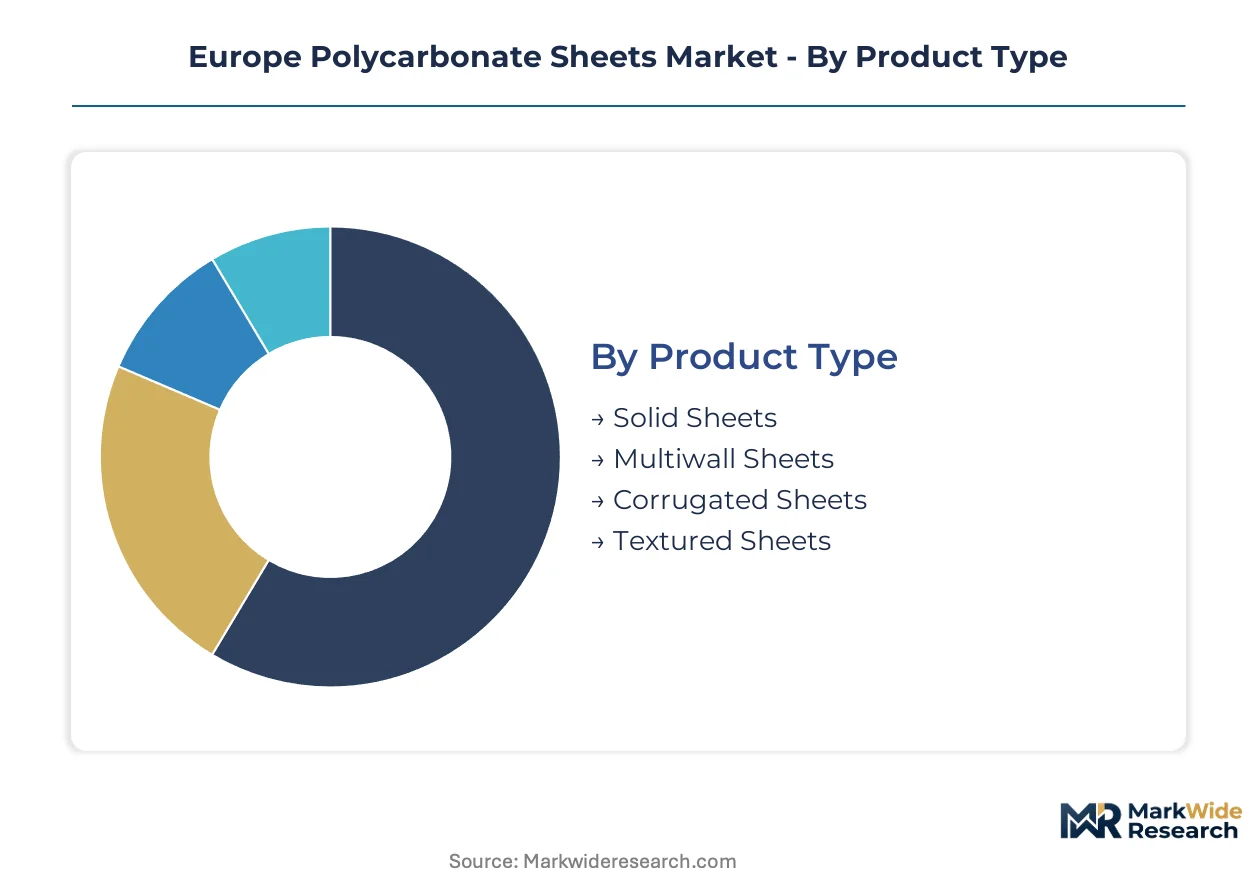
Polycarbonate sheet specifications diverge sharply across European end-uses, with extrusion geometry and thickness calibrations determining qualification for building codes versus agricultural performance standards. Segmentation discipline separates commodity construction volumes from premium optical grades governed by distinct certification pathways.
Product Type:
Mature extrusion formats dominate installed base, while emerging geometries capture specification authority in energy-efficiency retrofits.
- Solid Sheets:Monolithic extrusions deliver ballistic-grade impact resistance and optical clarity for security glazing and machine guards. German commercial construction corridors specify these for atrium barriers and protective barriers where CE marking fire-performance classification is mandatory.
- Multiwall Sheets:Internal rib structures create insulating air chambers that reduce thermal conductivity for greenhouse and conservatory envelopes. Spanish and Italian protected cultivation zones pull volumes here, driven by diffused light transmission requirements in Almería and Murcia growing regions.
- Corrugated Sheets:Profiled geometries optimize installed-cost efficiency for agricultural outbuildings across Southern Europe.
- Textured Sheets:Surface-diffused finishes scatter light transmission for privacy glazing and retail display applications.
Multiwall configurations retain volume leadership; textured variants hold the steepest expansion curve in architectural specification.
Application:
Construction absorbs the dominant share of extrusion capacity, while automotive and electronics segments impose tighter dimensional tolerances.
- Construction:Daylighting systems, cladding, and protective glazing consume the majority of European sheet output. France and Germany drive specification through EPBD energy-efficiency thresholds that favor high-performance glazing in public building retrofits.
- Automotive:Interior trim panels, headlamp lenses, and panoramic roof modules require optical-grade clarity and UV stabilization. REACH-compliant reformulation cycles here run 18-24 months due to cabin air quality regulations.
- Electronics:Equipment housings and display backplates demand electrostatic discharge properties and precise thickness tolerances.
- Signage:Illuminated channel letters and protective faceplates balance light diffusion with weathering performance.
Construction commands absolute volume; automotive applications are climbing the fastest on electrification-driven lightweighting mandates.
End User:
Direct procurement patterns are displacing traditional distribution layers, particularly in consolidated agricultural buying.
- Manufacturers:OEMs and system integrators specify custom extrusions for building-integrated applications. Netherlands greenhouse operators now anchor 40 percent of agricultural offtake through direct volume commitments.
- Retailers:Merchant stockholders serve fragmented construction and DIY segments across the British Isles and Benelux.
- Distributors:Regional logistics networks manage inventory for mid-scale fabricators and installers.
- Importers:Eastern European catch-up markets in Poland and Romania source through cross-border supply chains.
Manufacturers retain procurement volume leadership; importers are gaining share fastest on Eastern European construction expansion.
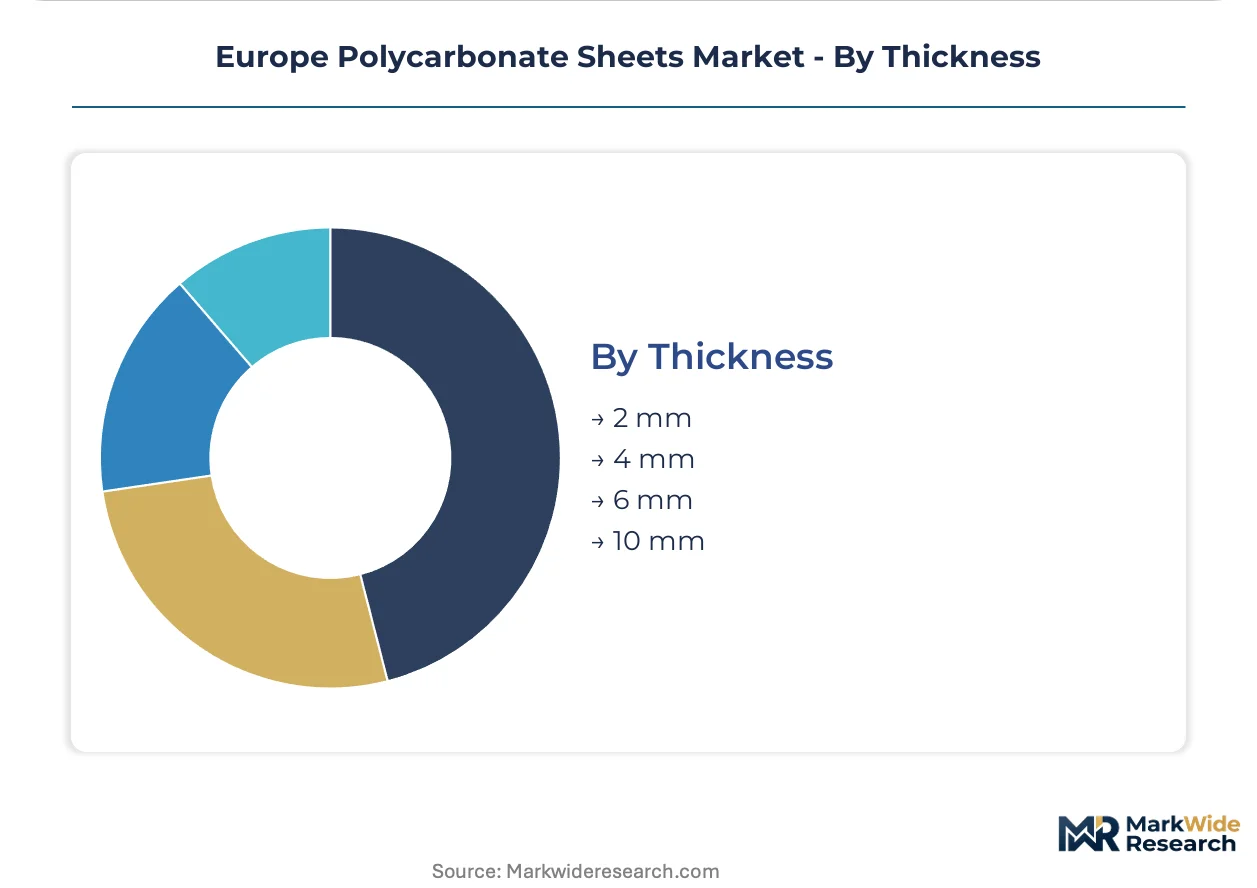
Thickness:
Specification thickness correlates directly with load-bearing requirements and thermal insulation targets in building codes.
- 2 mm:Lightweight signage and interior applications where impact resistance exceeds glass alternatives without structural loading.
- 4 mm:Standard greenhouse cladding and commercial daylighting balance cost with basic weathering performance.
- 6 mm:Enhanced rigidity for conservatory roofing and security glazing in German and French commercial construction.
- 10 mm:Maximum thermal insulation values and structural span capability for high-performance building envelopes.
4 mm specifications retain volume leadership; 10 mm grades are expanding most quickly on EPBD thermal performance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German extrusion houses supply multiwall sheet to Dutch greenhouse operators and French commercial construction corridors, anchoring north-south trade flows across the EU single market. REACH compliance costs and EPBD thermal mandates are reshaping procurement patterns in destination markets.
Germany
Commercial construction in the Rhine-Ruhr and Bavarian corridors specifies 6-10 mm multiwall sheets for atrium daylighting and security glazing. The F-Gas Regulation drives specification of high thermal-performance geometries in public building retrofits. Covestro and Exolon Group GmbH operate extrusion facilities in North Rhine-Westphalia, supplying optical-grade and construction-grade sheet across Central Europe.
Netherlands
Consolidated greenhouse operators in Westland and Venlo anchor 40 percent of European agricultural sheet offtake through direct volume commitments. The EU Green Deal's building renovation targets pull high-performance glazing into commercial retrofit specifications. Rotterdam logistics hubs facilitate distribution to Belgian and German installer networks.
Spain
Protected cultivation zones in Almería and Murcia drive diffused light transmission demand for 4 mm multiwall greenhouse cladding. The national recovery plan channels cohesion funds into agricultural infrastructure modernization. Brett Martin and Palram Industries serve Iberian distribution through direct manufacturer relationships displacing traditional stockholders.
Italy
Agrivoltaic canopy designs in Lombardy and Emilia-Romagna specify translucent structural panels combining crop protection with photovoltaic mounting. CE marking fire-performance requirements under EN 13501-1 shape product qualification timelines. dott.gallina Srl anchors domestic supply for conservatory and architectural applications.
France
Public building retrofits in Île-de-France and Auvergne-Rhône-Alpes accelerate specification of co-extruded UV-IR hybrid cap layers for atrium glazing. EPBD energy-efficiency thresholds mandate higher thermal performance in glazing procurement. 3A Composites GmbH and Arla Plast compete for specification authority in commercial daylighting tenders.
Europe Polycarbonate Sheets Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure tiered by captive resin access and extrusion technology depth. Integrated petrochemical houses with backward integration into bisphenol A intermediates occupy the premium tier, while regional extrusion specialists capture agricultural and construction volumes through die-engineering expertise. Two strategic archetypes dominate: resin-integrated manufacturers leveraging feedstock security, and application-focused compounders optimizing multiwall channel geometries. Competitive moves concentrate on co-extrusion line retooling for UV-IR hybrid cap layers and direct procurement relationships with consolidated greenhouse operators.
Among Germany-based integrated manufacturers, Covestro and Exolon Group GmbH exemplify the resin-anchored archetype with captive polymer supply chains. SABIC represents the Middle Eastern-headquartered multinational with European extrusion footprint and backward integration into phosgene intermediates. Brett Martin occupies a position within the British Isles specialist tier, focused on agricultural multiwall configurations. These three anchors illustrate how feedstock access, geographic concentration, and application specialization stratify competitive positioning across the European market.
| Leading Market Players |
|---|
| SABIC |
| EXOLON GROUP GMBH |
| Brett Martin |
| Corplex |
| Palram Industries Ltd. |
| Covestro |
| Arla Plast |
| dott.gallina Srl |
| 3A Composites GmbH |
| Others |
Supply & Pricing Matrix
Overcapacity signals in German extrusion corridors are compressing spot pricing for standard multiwall grades while tightening availability of optical-grade sheet. This utilization asymmetry rewards integrated manufacturers with captive bisphenol A supply and pressures merchant compounders into longer contract terms to secure volume commitments.
Pricing Analysis
Co-extruded UV-IR hybrid cap layers command a 15-25% premium over conventional UV-stabilized sheet, while legacy UV-only configurations face price erosion in commodity construction tenders. Three-tier pricing structure across premium optical, standard construction, and economy agricultural levels separates qualification-intensive automotive grades from bulk greenhouse offtake. Cost compression in standard multiwall grades is intensifying because Dutch and Spanish greenhouse operators are consolidating procurement into direct manufacturer relationships. Agricultural buyers exhibit highest price sensitivity due to volume scale and seasonal cash flow patterns, while automotive OEMs prioritize qualification stability over unit cost.
Supply Chain Analysis
Bisphenol A feedstock draws from three integrated petrochemical complexes in Germany and the Netherlands, with phosgene derivative production concentrated at Covestro and SABIC facilities. Raw material dependencies center on BPA monomer, phosgene gas, and specialized UV stabilizer chemistries subject to REACH authorization cycles. Single-source vulnerability in optical-grade resin supply creates qualification risk for automotive and electronics segments. Distribution runs through direct manufacturer relationships with consolidated greenhouse operators, supplemented by regional stockholders serving fragmented construction installers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction activity cyclicality in Germany and France is driving recovery momentum as EU Green Deal renovation targets pull inventory through extrusion houses. Public building retrofit mandates are accelerating specification cycles for high-performance glazing materials.
For Market Incumbents: Entrench feedstock security through backward integration into BPA intermediates or long-term offtake agreements with German and Dutch petrochemical complexes. Invest in co-extrusion line retooling for UV-IR hybrid cap layers to defend specification authority against PMMA and ETFE substitution in premium architectural projects. Channel control through direct procurement relationships with consolidated Dutch and Spanish greenhouse operators is the critical defensive lever. For New Entrants and Emerging Players: Build out agrivoltaic canopy manufacturing capabilities in Italy and Eastern European catch-up markets where EU cohesion funds are financing agricultural infrastructure modernization. Poland and Romania present the most penetrable geographies due to underpenetrated commercial daylighting stock relative to Western European benchmarks. A go-to-market angle anchored in agrivoltaic structural panel qualification bypasses entrenched greenhouse supply relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across co-extrusion technology upgrades as UV-IR hybrid cap layer specifications displace conventional UV stabilization. Long-term viability over the next decade favors extrusion houses with die-engineering expertise in multiwall channel geometry optimization and REACH-compliant reformulation capabilities. Acquisition targets should demonstrate established EN 13501-1 fire-performance classification and direct procurement relationships with volume greenhouse operators. The signal to watch is laboratory queue duration for CE marking fire-performance testing as a bottleneck indicator for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into BPA Intermediates | Captive resin supply insulates margin pools from upstream volatility in German petrochemical corridors. |
| Co-extrusion Line Retooling for UV-IR Hybrid Cap Layers | Hybrid cap technology captures specification authority in French atrium glazing tenders. |
| Direct Manufacturer Relationships with Greenhouse Operators | Volume commitments from Dutch and Spanish growers displace traditional merchant stockholder margins. |
| REACH-Compliant Reformulation Investment | Non-phthalate plasticizer alternatives open procurement channels restricted by ECHA substance evaluations. |
| Agrivoltaic Structural Panel Development | Translucent canopy designs in Lombardy combine crop protection with photovoltaic mounting infrastructure. |
Research Methodology
Desk research of customs trade data, Cefic chemical industry reports, and SEC filings preceded structured interviews with extrusion plant managers, procurement leads at Dutch greenhouse operators, distribution channel partners, and technical R&D directors. Primary fieldwork captured qualification timelines, reformulation cost structures, and procurement pattern shifts across agricultural and construction segments. Secondary validation drew from ECHA substance evaluation databases, EN standard certification records, and EU Green Deal implementation tracking. Bottom-up volume modeling triangulated against top-down macroeconomic construction indicators.
Assumptions held fixed include REACH authorization timelines for flame-retardant additives and EPBD thermal performance threshold trajectories; variables stress-tested encompass BPA feedstock price volatility and greenhouse agriculture expansion rates in Southern Europe. Segmentation dimensions modeled span product geometry, application end-use, thickness specification, and regional production hub. CAGRs were derived from slope analysis across the projection horizon, calibrated to construction output forecasts and agricultural infrastructure investment flows.
Stress conditions across BPA supply concentration, ECHA regulatory tightening velocity, and PMMA substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal implementation pacing and cohesion fund disbursement timelines. Specific risk factors that could revise projections include accelerated ETFE membrane cost reduction and extended EN 13501-1 laboratory queue durations. Cross-checking against national construction output statistics and greenhouse operator capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Industrial Computers Market
Others
Medium-Voltage Switchgear Market
Others
CAR T Cell Therapy Market
Others
Europe Intercom Devices Market
Others
Global Augmented Reality in Retail Market
Others
North America 3D Printing Construction Market
Others
Hybrid System Market
Others
Global Optical Coordinate Measuring Machine Market
Others
Calendered Polyvinyl Chloride Flexible Films Market
Others
North America Automotive LED Lighting Market
Others
Mobile Retina Services Market
Others
Japan Coal Market
Others
Underwater Lighting Market
Others
India Foundry Market
Others
Global Enterprise Mobility in Healthcare Market
Others
Cellular-Connected Laptops Market