
 Global Enterprise Mobility in Healthcare Market | 2026-2036
Global Enterprise Mobility in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enterprise Mobility in Healthcare Market Foresight
Subscription-based financing for mobile device fleets is narrowing the competitive field to vendors with capital reserves or banking partnerships. Microsoft Corporation leverages its Azure cloud infrastructure to bundle device management with identity services. SAP SE anchors its position through ERP-integrated mobile workflows for hospital procurement and inventory tracking.
Enterprise mobility in healthcare encompasses the deployment, management, and security of smartphones, tablets, and wearables used by clinical staff to access patient data, communicate care plans, and operate diagnostic peripherals, typically requiring AES-256 encryption, biometric authentication, and real-time compliance auditing. Mobile Device Management solutions dominate procurement budgets as health systems consolidate thousands of endpoints under unified policy engines. Cloud-Based deployment is accelerating fastest among multi-site hospital networks seeking elastic capacity for seasonal patient surges without data center capital.
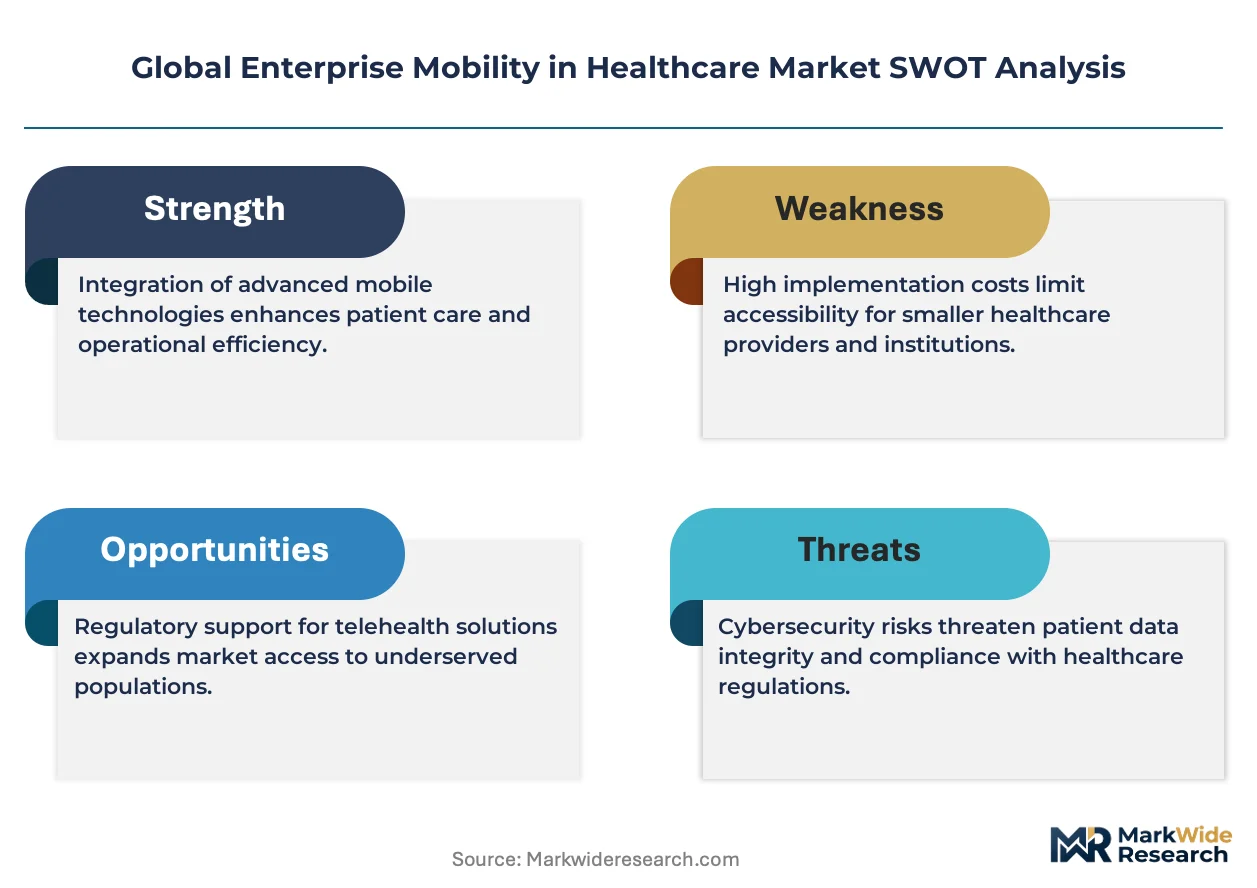
The FDA enforces premarket cybersecurity controls for networked mobile medical devices, while HIPAA mandates audit trails for every patient data access from endpoints, collectively elevating Security Solutions from optional to mandatory line items. The EU AI Act and GDPR impose additional algorithmic transparency and cross-border data residency constraints on European deployments. Stakeholders must weigh regional certification requirements against platform consolidation strategies when selecting mobility vendors.
Market Dynamics
Hospital networks are consolidating mobile endpoints under unified policy engines as cybersecurity mandates from the FDA and HIPAA transform security solutions from optional add-ons to mandatory procurement line items.
Growth Catalysts
- Cloud-Based Deployment Elasticity:Multi-site hospital networks in Germany prioritize cloud infrastructure to handle seasonal patient surges without data center capital expenditure.
- FDA Cybersecurity Premarket Controls:The FDA's tightened authentication requirements for networked medical devices are accelerating vendor consolidation toward platforms with integrated identity services.
- Biometric Authentication Mandates:Electronic health record access protocols now require fingerprint or facial recognition systems, driving hardware refresh cycles across clinical workflows.
Market Restraints
- Input Cost Volatility in Semiconductor Components:Mobile device fleet procurement faces margin pressure from fluctuating chip availability affecting MDM hardware bundles.
- EU Cross-Border Data Residency Constraints:GDPR and the EU AI Act impose algorithmic transparency requirements that complicate centralized mobility platform architectures.
- Technical Limitation in Legacy System Interoperability:Proprietary electronic health record formats resist standardized API integration with modern mobile endpoints.
Strategic Opportunities
- Underpenetrated Rural Hospital Networks:Subscription-based financing models create access for capital-constrained facilities in secondary US markets previously excluded from enterprise mobility.
- Regulatory Tailwind from Hospital Digitization Programs:Germany's federal investment in secure mobile EHR access creates procurement windows for compliant vendors.
- Convergence of Wearable Diagnostics and Mobile Platforms:Integration of continuous glucose monitors and cardiac sensors with clinical smartphones opens new endpoint categories.
Industry Challenges
- Cybersecurity Workforce Scarcity:Health systems lack sufficient personnel to manage AES-256 encryption deployment and real-time compliance auditing across thousands of endpoints.
- Certification Timeline Compression:FDA premarket cybersecurity reviews for mobile medical devices extend product launch schedules beyond traditional hardware cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enterprise Mobility in Healthcare Market |
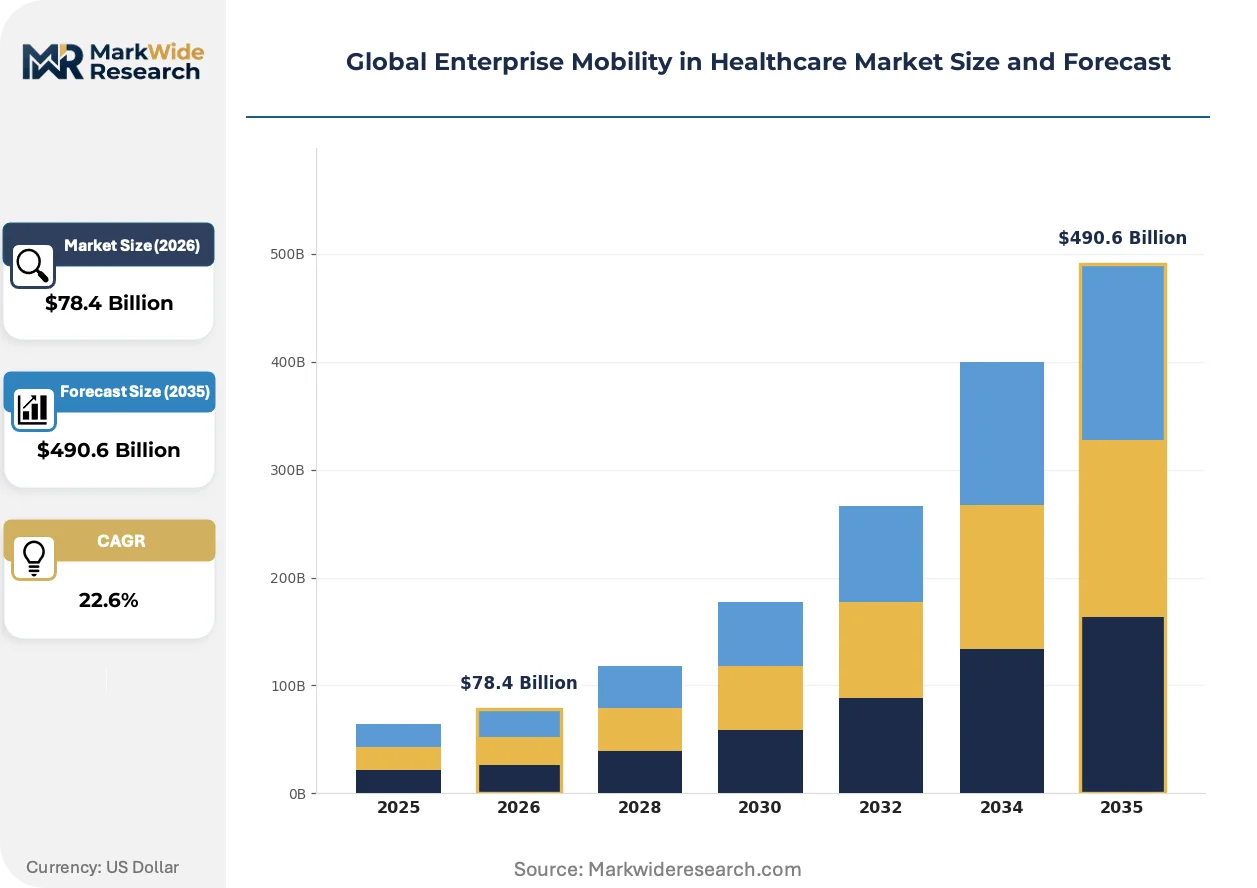
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $490.6 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Mobile Device Management, Mobile Application Management, Content Management, Security Solutions, Collaboration Tools Deployment Model: On-Premises, Cloud-Based, Hybrid, Private Cloud, Public Cloud Use Case: Remote Patient Monitoring, Clinical Data Access, Telemedicine, Staff Communication, Inventory Management User Category: Hospitals, Clinics, Diagnostic Centers, Pharmacies, Research Institutes |
| Companies Covered | McKesson Corporation, Microsoft Corporation, Oracle Corporation, Koninklijke Philips N.V., Cisco Systems Inc., IBM Corporation, Zebra Technologies Corporation, Apple Inc., SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enterprise Mobility in Healthcare Market Shifts & Advancements
Enterprise mobility platforms are pivoting from device-centric management to identity-centric security architectures. This shift reflects the collapse of network perimeters in distributed clinical environments.
Zero-trust network access architectures are virtualizing the traditional VPN model for clinical staff. Hospital IT departments in the United States are deploying these frameworks to replace legacy remote access within eighteen-month refresh cycles. The technology is virtualizing perimeter security into continuous endpoint verification, compressing vendor selection criteria toward integrated identity-cloud bundles.
The EU AI Act's algorithmic transparency mandates are reshaping European deployment roadmaps. Machine learning models embedded in diagnostic peripherals must now provide interpretable decision trails. German hospital procurement teams are prioritizing vendors with pre-certified explainability documentation, delaying non-compliant platform evaluations.
Clinical staff are rejecting siloed communication apps in favor of unified collaboration platforms. Nurses and physicians in multi-site networks demand single-interface access to paging, EHR alerts, and care team coordination. This preference shift is most visible in US health systems consolidating previously separate point solutions under Microsoft Teams or similar integrated environments.
Global Enterprise Mobility in Healthcare Market Segmentation
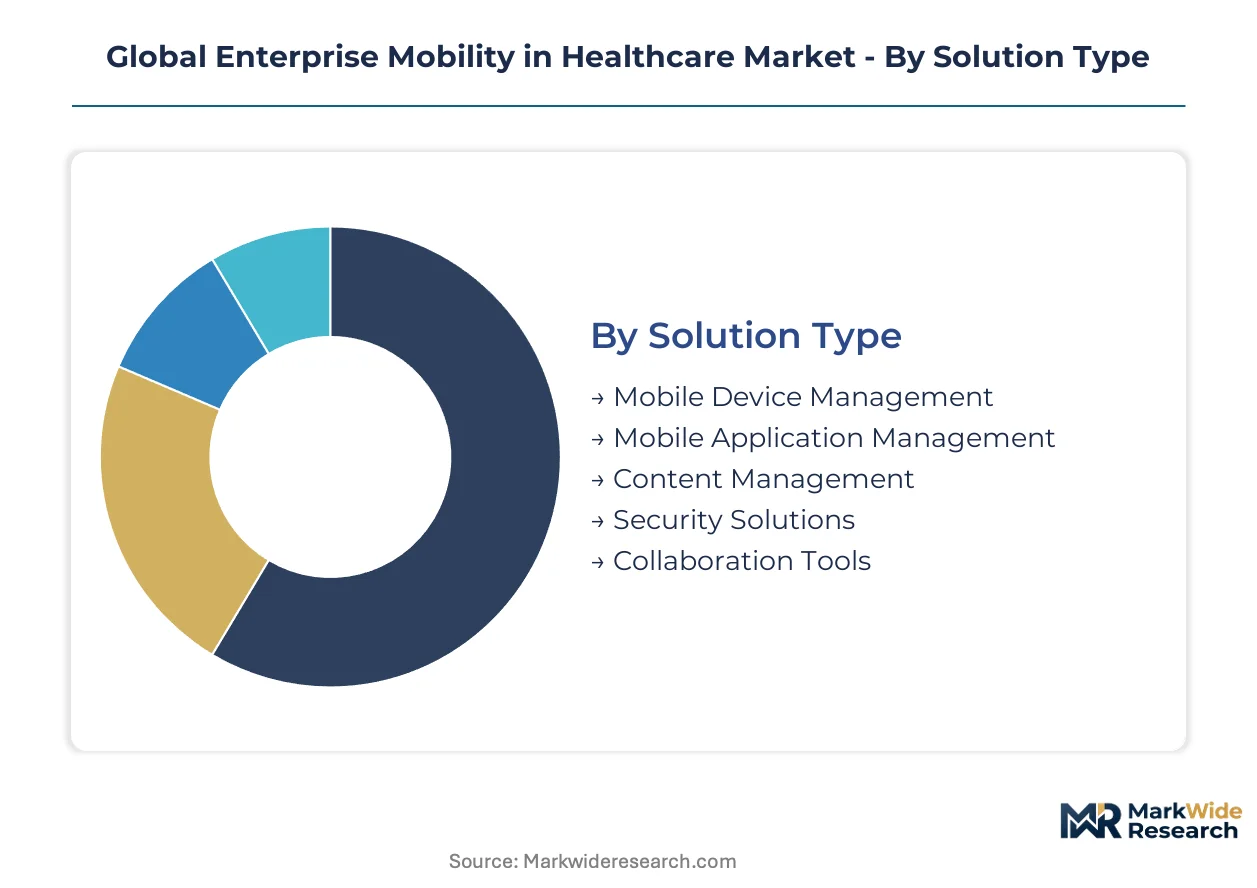
Enterprise mobility procurement in healthcare diverges sharply by operational scale and regulatory exposure. Hospital networks consolidate endpoints under unified policy engines while smaller facilities prioritize modular, pay-as-you-grow configurations. Understanding these segment boundaries clarifies vendor positioning and margin architecture across the value chain.
Solution Type:
After-sales service intensity varies dramatically across solution categories, with security and management platforms demanding continuous policy updates versus collaboration tools requiring lighter ongoing support.
- Mobile Device Management:Unified policy engines govern thousands of clinical endpoints through centralized enrollment, configuration enforcement, and remote wipe capabilities. Demand concentrates in United States hospital networks consolidating fragmented device fleets under HIPAA-compliant audit trails. The segment commands premium pricing due to 24/7 incident response requirements and FDA cybersecurity alignment.
- Security Solutions:AES-256 encryption, biometric authentication modules, and real-time compliance auditing protect patient data access from clinical smartphones and tablets. German hospital digitization programs prioritize these solutions to satisfy GDPR cross-border data residency constraints and EU AI Act algorithmic transparency mandates.
- Mobile Application Management:Containerized app deployment separates clinical software from personal data on BYOD endpoints.
- Content Management:Secure document repositories enable encrypted sharing of diagnostic imaging and care plans across distributed care teams.
- Collaboration Tools:Unified paging, EHR alerts, and care team coordination replace siloed communication applications.
Mobile Device Management holds the largest share; momentum sits with Security Solutions.
Deployment Model:
Capital efficiency pressures favor subscription-based consumption models, with elasticity requirements driving divergence between seasonal patient surge handling and steady-state operational workloads.
- Cloud-Based:Elastic infrastructure scales compute and storage resources without data center capital expenditure, enabling multi-site hospital networks to absorb seasonal patient volume spikes. Germany's federal hospital digitization investments accelerate procurement of cloud-native mobility platforms with automated compliance patching.
- Hybrid:Sensitive patient data resides in private infrastructure while collaboration workloads burst to public cloud resources. United States health systems deploy hybrid architectures to satisfy HIPAA business associate agreement requirements while maintaining Microsoft Teams integration for clinical communication.
- On-Premises:Legacy data center investments and specialized latency requirements sustain demand in research-intensive institutions.
- Private Cloud:Dedicated tenant environments address data sovereignty concerns for cross-border hospital networks.
- Public Cloud:Shared infrastructure delivers lowest per-seat economics for capital-constrained rural facilities.
Cloud-Based deployment captures dominant procurement volume; Hybrid architectures are climbing the fastest as compliance complexity intensifies.
Use Case:
Workflow digitization priorities reflect reimbursement model shifts, with value-based care contracts accelerating investment in continuous patient visibility outside traditional clinical settings.
- Remote Patient Monitoring:Integration of continuous glucose monitors, cardiac sensors, and pulse oximeters with clinical smartphones enables proactive intervention before acute episodes. United States accountable care organizations drive demand through shared savings incentives tied to reduced hospital readmission rates.
- Telemedicine:Video consultation platforms with embedded EHR access extend specialist reach into underserved geographies. German statutory health insurance reimbursement reforms expanded telemedicine eligibility, creating procurement windows for HIPAA-GDPR dual-compliant vendors.
- Clinical Data Access:Real-time EHR retrieval from mobile endpoints accelerates bedside decision-making.
- Staff Communication:Secure messaging replaces pagers with encrypted, traceable care team coordination.
- Inventory Management:Barcode scanning and RFID tracking from mobile devices reduce pharmaceutical waste and equipment loss.
Remote Patient Monitoring holds the largest share; Telemedicine is gaining share fastest as reimbursement parity expands.
User Category:
Endpoint density and cybersecurity maturity create distinct purchasing profiles, with acute care facilities managing ten-thousand-plus devices versus ambulatory settings operating leaner fleets.
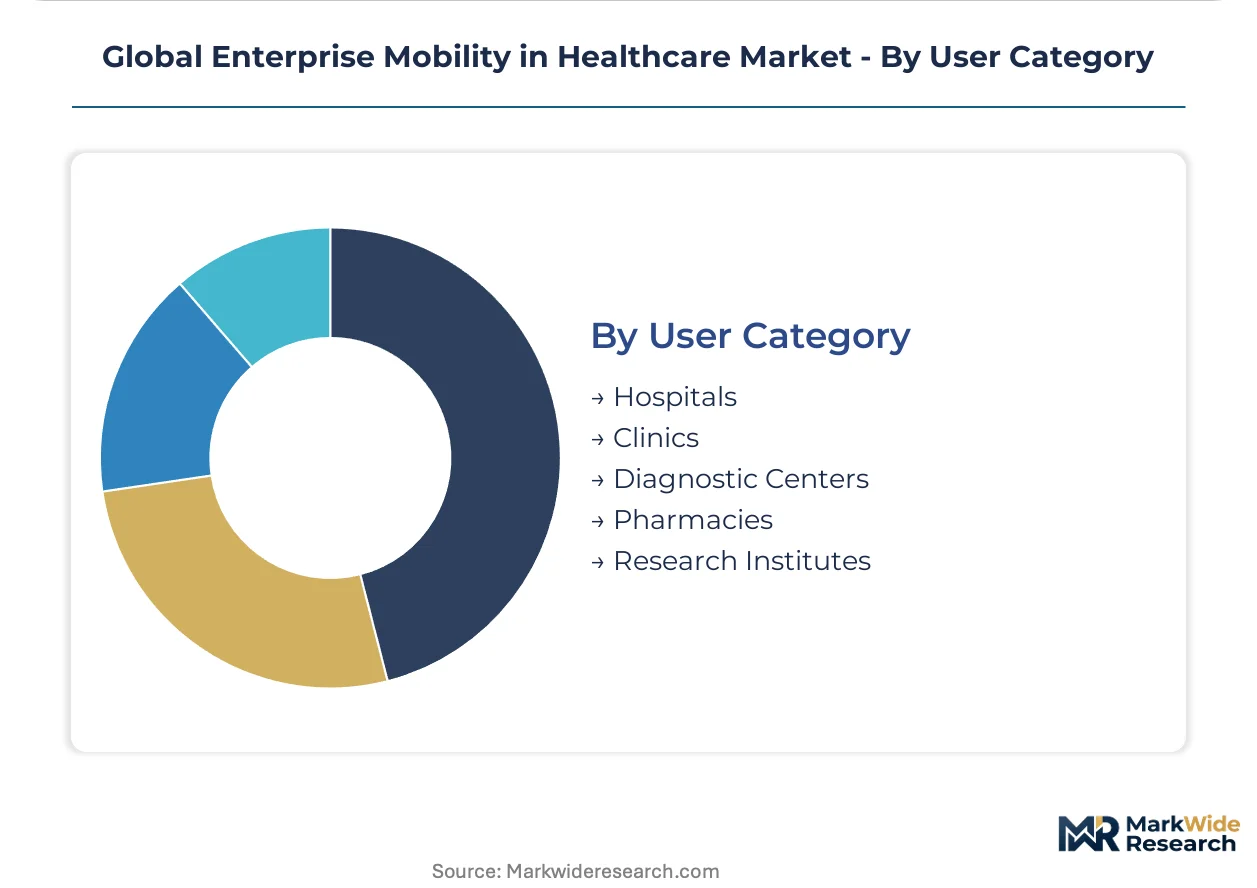
- Hospitals:Multi-site networks consolidate mobile endpoints under unified MDM policy engines spanning emergency departments, surgical suites, and inpatient wards. FDA premarket cybersecurity controls for networked medical devices elevate procurement criteria toward integrated identity-cloud bundles in United States health systems.
- Clinics:Smaller device counts and limited IT staffing drive preference for fully managed service models with predictable monthly expenditure. Subscription-based financing creates access for capital-constrained rural facilities previously excluded from enterprise mobility.
- Diagnostic Centers:Imaging-heavy workflows require high-bandwidth mobile access to PACS systems.
- Pharmacies:Inventory scanning and prescription verification applications dominate mobility requirements.
- Research Institutes:Data integrity and chain-of-custody documentation impose specialized compliance burdens.
Hospitals command the largest procurement volume; Clinics represent the steepest expansion trajectory as managed service penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare enterprise mobility solutions flow predominantly from North American and European vendors into Asia-Pacific and Middle Eastern hospital networks, creating a trade pattern where regulatory certification in source markets becomes a de facto export requirement for destination procurement.
United States
Hospital network consolidation and value-based care contracts drive demand for unified MDM platforms spanning multi-site deployments. FDA premarket cybersecurity controls for networked medical devices tighten vendor qualification criteria, favoring suppliers with integrated identity-cloud architectures. The Texas Medical Center in Houston and Mayo Clinic's Rochester-Phoenix-Jacksonville network anchor procurement volume for zero-trust mobile access systems.
Germany
Federal hospital digitization programs prioritize secure mobile EHR access, directing capital toward cloud-native mobility platforms with automated compliance patching. The EU AI Act and GDPR impose cross-border data residency constraints that complicate centralized architectures. Berlin-Brandenburg and Bavaria's university hospital clusters concentrate procurement activity for biometric authentication modules.
China
Domestic health system digitization accelerates demand for localized mobile clinical workflows, though NMPA cybersecurity guidelines for networked medical devices slow foreign platform entry. National hospital grading standards mandate mobile access to electronic records. Shanghai's Ruijin Hospital and Peking Union Medical College Hospital anchor pilot deployments for indigenous MDM solutions.
Japan
Aging demographics and labor shortages propel investment in mobile-enabled remote patient monitoring and telemedicine reimbursement expansion. METI guidelines on medical device software security elevate procurement scrutiny for endpoint encryption. Tokyo's St. Luke's International Hospital and Osaka University Hospital concentrate demand for wearable-integrated clinical smartphones.
United Kingdom
NHS Long Term Plan digitization targets consolidate mobile endpoint procurement under national framework agreements, compressing vendor selection toward platforms with pre-certified NHS Digital compliance. London's Guy's and St Thomas' NHS Foundation Trust and Manchester's NHS trusts anchor regional deployment patterns for secure clinical communication tools.
Global Enterprise Mobility in Healthcare Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying authentication modules, encryption engines, and diagnostic peripherals. The vendor base stratifies between cloud-native suite providers and point-solution specialists addressing legacy interoperability gaps. Three archetypes dominate: enterprise software conglomerates bundling mobility with existing infrastructure, pure-play MDM vendors with healthcare-specific compliance tooling, and device manufacturers extending into management software. Competitive dynamics center on strategic partnerships with hospital networks and vertical integration into biometric hardware.
Among enterprise software conglomerates, Microsoft Corporation and Oracle Corporation occupy positions exemplifying the platform-integrator archetype, leveraging cloud infrastructure and database dominance to anchor mobility within broader health IT ecosystems. SAP SE represents the ERP-anchored variant, embedding mobile workflows within procurement and inventory systems. Zebra Technologies Corporation and Koninklijke Philips N.V. illustrate the device-to-software extension pattern, with hardware heritage informing specialized clinical endpoint design.
| Leading Market Players |
|---|
| McKesson Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| Koninklijke Philips N.V. |
| Cisco Systems Inc. |
| IBM Corporation |
| Zebra Technologies Corporation |
| Apple Inc. |
| SAP SE |
| Others |
Supply & Pricing Matrix
Shenzhen's semiconductor packaging clusters feed AES-256 encryption module production for mobile device management hardware, concentrating component pricing power among Asian suppliers serving United States hospital networks. This geographic concentration amplifies margin pressure when chip availability fluctuates, forcing MDM vendors to absorb cost volatility or pass through to subscription pricing.
Pricing Analysis
Hospital procurement committees anchor subscription-based SaaS pricing for enterprise mobility platforms, with three-tier pricing structure across premium, standard, and economy levels differentiated by FDA cybersecurity certification tier and 24/7 incident response bundling. Price differentiation hinges on biometric authentication hardware integration and automated compliance patching frequency. Cost compression in standard tiers is intensifying because semiconductor input volatility squeezes MDM hardware bundle margins. Rural clinic networks exhibit highest price sensitivity; multi-site hospital systems with GPO contracts show lowest.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for encryption chip sourcing, compelling vendor diversification toward Taiwan and South Korea alternatives. Component manufacturing draws from Chinese PCB fabrication, Taiwanese semiconductor foundries, and German precision sensor suppliers. Single-source vulnerability concentrates in biometric authentication module production. Distribution runs through healthcare GPOs and direct hospital system contracts, with cloud-native platforms bypassing traditional device logistics entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise mobility in healthcare operates as a service-attach opportunity where security solution subscriptions and compliance auditing services expand faster than device hardware sales, embedding recurring revenue deeper into hospital procurement cycles than capital equipment models permit.
For Market Incumbents: Harden platform stickiness by embedding zero-trust identity services into existing Azure or ERP-anchored workflows, neutralizing pure-play MDM vendors with inferior integration depth. Acquire biometric hardware specialists to close authentication module supply gaps exposed by FDA premarket cybersecurity timeline compression. Certification investment in EU AI Act explainability documentation defends German hospital procurement position against cloud-native challengers. For New Entrants and Emerging Players: Pursue rural United States clinic networks as the most penetrable segment, where subscription financing models bypass capital constraints excluding legacy vendors. Target Germany's federal hospital digitization program windows with GDPR-native architectures that incumbent ERP-anchored players retrofit poorly. Go-to-market through healthcare-focused managed service providers accelerates trust-building without direct hospital sales infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-utility play because regulatory mandates from FDA and EU AI Act transform security solutions from discretionary to mandatory spend, insulating revenue from hospital budget cycles. Acquisition target archetype: pure-play MDM vendors with healthcare-specific HIPAA tooling and pre-certified biometric modules. Watch FDA premarket cybersecurity review queue lengths as inflection signal for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Premarket Submission | Accelerates hospital network vendor qualification under tightened authentication mandates. |
| Zero-Trust Architecture Deployment | Virtualizes perimeter security into continuous endpoint verification for distributed clinical staff. |
| Biometric Hardware Backward Integration | Captures authentication module margins and compresses FDA certification timelines. |
| Hospital System GPO Partnership | Locks multi-site procurement under national framework agreements with compliance bundling. |
| EU AI Act Explainability Certification | Unlocks German federal digitization program procurement windows ahead of non-compliant rivals. |
Research Methodology
Cross-validation between hospital CIO interviews and GPO contract databases anchors the qualitative findings, with secondary validation against FDA 510(k) filings and CMS Medicare reimbursement data. Primary fieldwork engaged hospital procurement managers, biomedical engineers, MDM platform engineers, and GPO contracts specialists. Bottom-up endpoint deployment estimates triangulate against top-down health system IT budget allocations from SEC 10-K disclosures and hospital association capital expenditure surveys.
Calibration against historical MDM adoption curves and HIPAA enforcement patterns shapes the analytical framework across the analysis window. Segmentation dimensions modeled include solution type, deployment architecture, use case intensity, and user category scale. CAGRs derive from elasticity-adjusted endpoint penetration rates and subscription pricing trajectory analysis. Forecast inputs incorporate FDA premarket review timeline data and Germany's federal hospital digitization investment schedules.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-native platform moves by hyperscalers or device manufacturers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Rotary Dial Machine Market
Others
Cat Dry Food Market
Others
Surface Green Mining Market
Others
Asia-Pacific Medium-Density Fiberboard Market
Others
Dry Washer Market
Others
Global OTA Testing Market
Others
Flexographic Printing Plate Market
Others
Asia-Pacific Air Separation Unit Market
Others
Programmatic Display Market
Others
North America Machine Vision Systems Market
Others
AC Switchgear Market
Others
Global Car Wax Market
Others
Global Electroshock Weapons Market
Others
Storm Surge Barriers Market
Others
Nanomedicine for Drug Delivery Market
Others
Connected Living Room Market