
 Industrial Computers Market | 2026-2036
Industrial Computers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Computers Market Foresight
Edge-to-cloud workload distribution is tilting compute architecture toward localized processing nodes with hardened thermal envelopes. Advantech Co., Ltd. leverages its embedded systems portfolio to anchor Asia-Pacific supply chains for fanless and panel PC variants. Siemens AG sustains dominance in rackmount and DIN rail configurations through deep ties to process automation integrators. Beckhoff Automation GmbH & Co. KG differentiates via PC-based control convergence, merging traditional PLC logic with industrial server-class hardware in modular form factors.
Industrial computers comprise ruggedized computing platforms engineered to operate across extended temperature ranges, typically from -40°C to 75°C, with shock and vibration resistance certified to IEC 60068-2-6 standards; these systems execute real-time control, data acquisition, and visualization functions in environments where consumer-grade electronics would fail. Panel PCs and fanless computers command margin pools in food processing and pharmaceutical cleanroom applications where sealed enclosures eliminate particulate contamination risks. Embedded systems lead volume in transportation infrastructure, while edge computing technology within the architecture dimension represents the fastest-expanding configuration as OEMs consolidate PLC, HMI, and gateway functions onto single-board platforms.
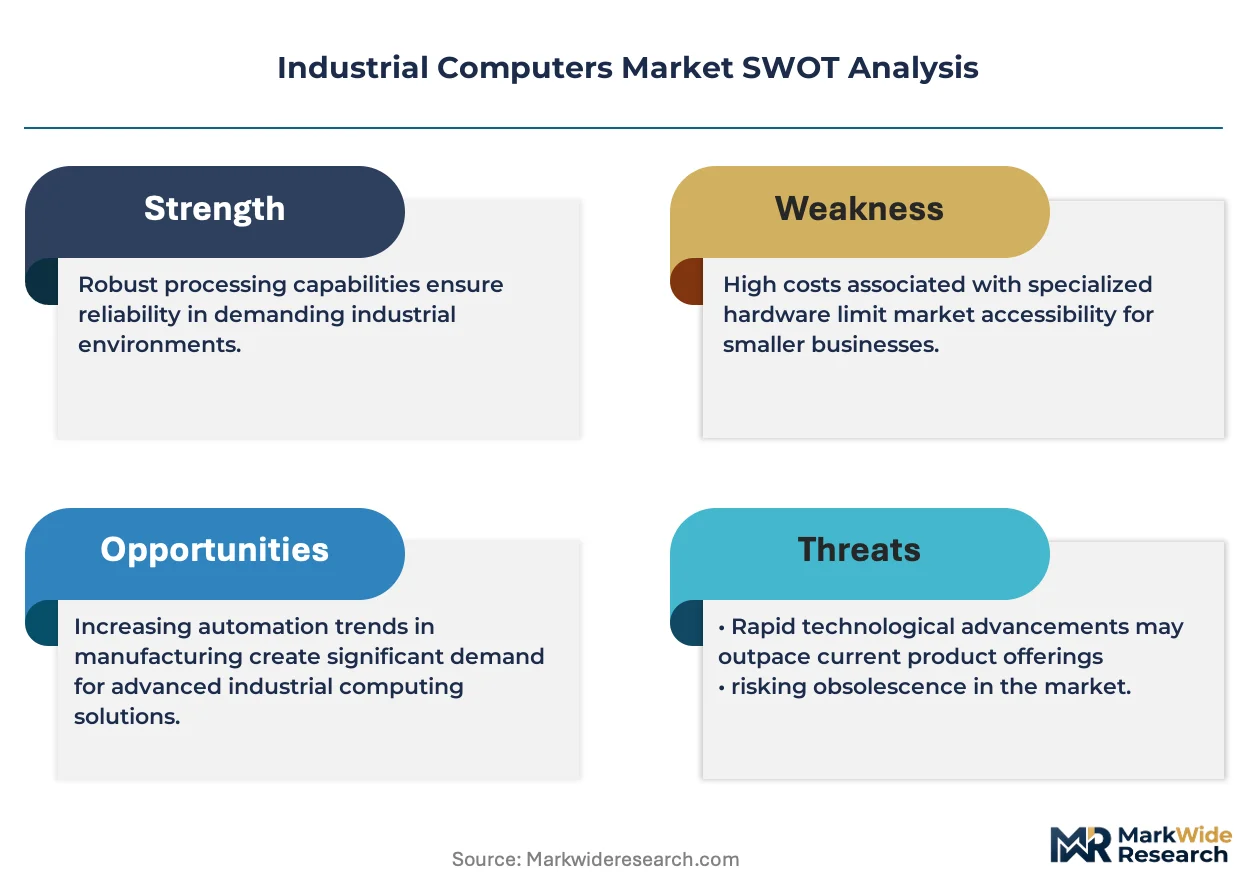
The U.S. FCC Part 15 emissions framework and the EU's CE marking directive, supplemented by IEC 61000-4-x immunity standards, collectively dictate enclosure shielding, grounding topology, and radiated susceptibility thresholds for industrial computer designs seeking transatlantic market access. NEMA 4X and IP65/IP67 ingress protection ratings, enforced by OSHA-aligned facility inspectors in U.S. manufacturing plants, further segment product positioning between washdown-capable stainless steel chassis and standard aluminum enclosures for dry environments. Stakeholders must weigh ARM architecture adoption against x86 software legacy burdens as real-time Linux distributions and containerized runtime environments erode traditional ISA lock-in.
Market Dynamics
Edge computing architectures are compressing control system footprints across automotive and process manufacturing, forcing enclosure designs to absorb PLC, HMI, and gateway functions into single-board platforms with hardened thermal envelopes certified to IEC 60068-2-6 vibration standards.
Growth Catalysts
- EU CE marking directive:Transatlantic market access requirements for IEC 61000-4-x immunity compliance are accelerating shielding and grounding investments in enclosure designs targeting European process automation integrators.
- Food processing cleanroom demand:Sealed NEMA 4X and IP65/IP67 enclosures are eliminating particulate contamination risks in pharmaceutical and food-grade deployments where washdown-capable stainless steel chassis command premium positioning.
- ARM architecture adoption:Real-time Linux distributions and containerized runtime environments are eroding traditional x86 ISA lock-in, opening design flexibility for fanless and panel PC variants in transportation infrastructure.
Market Restraints
- Semiconductor supply concentration:Dependency on concentrated foundry capacity in Taiwan and South Korea creates vulnerability for industrial-grade SoC and FPGA sourcing needed for extended temperature range platforms.
- NEMA/IP certification costs:OSHA-aligned facility inspection requirements in U.S. manufacturing plants impose recurring testing burdens for enclosure ingress protection validation, elevating fixed costs for mid-volume producers.
- Software legacy burdens:x86 instruction set architecture lock-in persists in process automation environments, delaying ARM migration despite superior thermal efficiency in fanless form factors.
Strategic Opportunities
- German industrial automation corridor:Demand concentration in Bavaria and Baden-Württemberg creates anchor demand for rackmount and DIN rail configurations serving automotive OEM production lines.
- Containerized runtime convergence:Merging PC-based control with traditional PLC logic via modular hardware platforms enables single-board consolidation of edge gateway functions.
- India PLI scheme for electronics:Production-linked incentives for component manufacturing are attracting enclosure and embedded systems assembly capacity to serve Asia-Pacific transportation infrastructure demand.
Industry Challenges
- Embedded Linux firmware expertise:Scarcity of engineers proficient in real-time kernel patching and Yocto build systems for ARM-based industrial platforms is extending product development cycles.
- IEC 61000-4-x certification timelines:Electromagnetic compatibility testing for radiated susceptibility thresholds creates 4-6 month validation bottlenecks for designs seeking simultaneous FCC Part 15 and CE marking approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Computers Market |
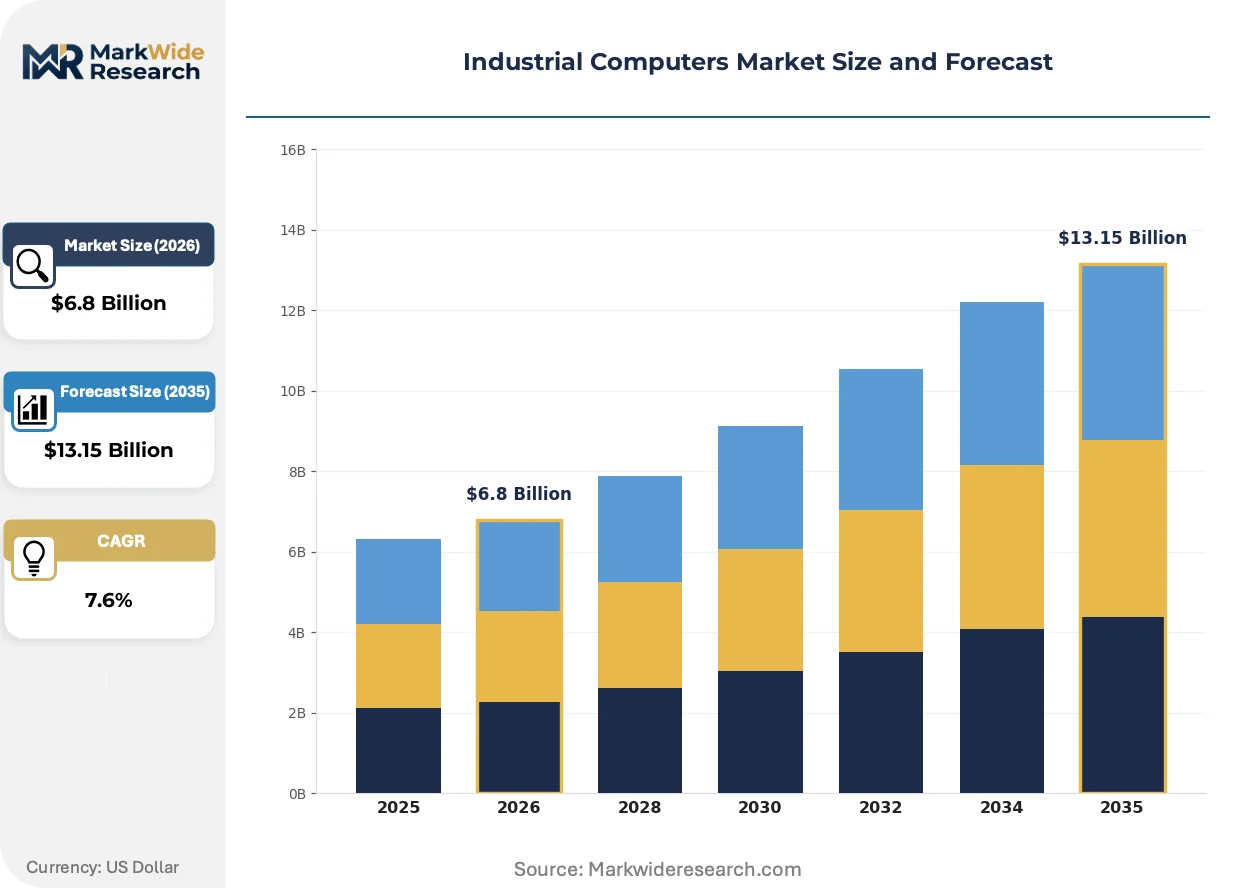
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Systems, Panel PCs, Rackmount Computers, Fanless Computers Technology: X86 Architecture, ARM Architecture, Industrial IoT, Edge Computing End User: Manufacturing, Energy, Transportation, Retail Form Factor: Box PCs, DIN Rail PCs, All-in-One PCs, Modular Systems |
| Companies Covered | Advantech Co., Ltd., Siemens AG, Beckhoff Automation GmbH & Co. KG, Kontron AG, IEI Integration Corporation, Rockwell Automation, Inc., Schneider Electric SE, B&R Industrial Automation GmbH, NEXCOM International Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Computers Market Shifts & Advancements
Virtualization technologies are collapsing hardware layers across factory floors, enabling software-defined control systems to run on consolidated compute nodes rather than distributed PLC racks. This architectural compression is redrawing supplier boundaries and enclosure form factor requirements.
Hypervisor software is virtualizing real-time control workloads onto multicore x86 and ARM processors, consolidating historically separate PLC, motion control, and vision processing threads onto single-board computers. Automotive powertrain manufacturers in Germany are deploying these platforms at line-replacement cadences of 18-24 months. The technology is virtualizing hardware margins by reducing dedicated controller counts per station from six units to two.
REACH substance restrictions and RoHS recast directives in the European Union are banning cadmium and hexavalent chromium in surface finishes for industrial enclosures, forcing conversion to zinc-nickel plating and powder coating chemistries. German machinery OEMs face the steepest compliance deadlines for existing product lines. Panel PC suppliers serving pharmaceutical cleanrooms are accelerating stainless steel chassis adoption to preempt regulatory friction.
Specification authority is migrating from plant engineering departments to corporate IT procurement functions, compressing vendor qualification cycles and elevating cybersecurity certification requirements over traditional MTBF metrics. System integrators in North American automotive manufacturing are responding by bundling managed security services with hardware supply contracts. This shift is most visible in Michigan and South Carolina assembly plants where CISO oversight now gates vendor approval.
Industrial Computers Market Segmentation
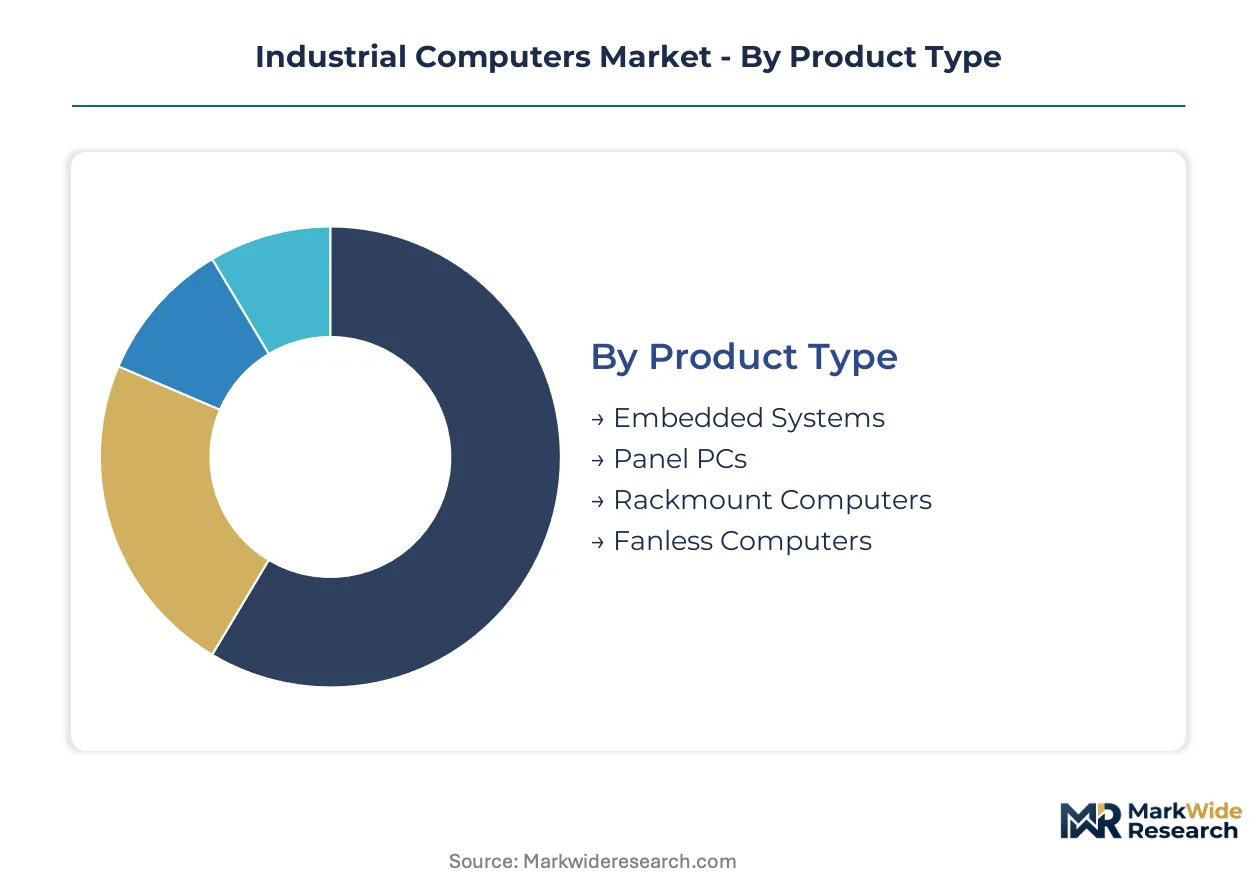
Industrial computer segmentation reveals divergent replacement dynamics across hardware configurations. Product lifecycles range from 18-month automotive line refreshes to decade-long infrastructure deployments, creating tiered margin pools for suppliers.
Product Type:
Replacement cadence varies sharply: embedded systems in transportation infrastructure turn over every 7-10 years, while panel PCs in automotive manufacturing refresh at 18-24 month intervals driven by model changeovers.
- Embedded Systems:Compact compute modules integrate directly into OEM equipment with extended temperature specifications from -40°C to 85°C. Transportation infrastructure in Germany's rail signaling networks and Japan's Shinkansen control systems anchor demand, with IEC 61000-4-x immunity certification extending procurement cycles.
- Panel PCs:Integrated display-compute units with sealed NEMA 4X or IP65 enclosures serve HMI and visualization functions. Food processing facilities in Wisconsin and pharmaceutical cleanrooms in Basel, Switzerland concentrate demand where washdown protocols eliminate particulate contamination risks.
- Rackmount Computers:19-inch chassis configurations dominate data acquisition and SCADA server applications with redundant power supply options.
- Fanless Computers:Passive thermal designs eliminate moving parts for vibration-heavy environments in mining equipment and heavy machinery.
Embedded systems anchor the volume base while panel PCs gain share at the steepest rate.
Technology:
Cost tiers separate legacy software investments from thermal efficiency gains, with x86 platforms commanding premium pricing for backward compatibility while ARM alternatives undercut on BOM costs.
- X86 Architecture:Intel and AMD processor platforms maintain dominance in process automation environments where Windows-based SCADA and proprietary control software create switching costs. German automotive OEMs in Bavaria sustain demand despite higher thermal loads requiring active cooling.
- ARM Architecture:RISC-based processors from NXP, Texas Instruments, and Qualcomm deliver superior watt-per-compute ratios for fanless designs. Real-time Linux distributions and containerized runtimes in Indian transportation infrastructure projects are eroding traditional ISA lock-in.
- Industrial IoT:Connectivity-optimized platforms with integrated 5G, Wi-Fi 6, and fieldbus gateways consolidate edge-to-cloud pipelines.
- Edge Computing:Localized processing nodes merge PLC, HMI, and analytics functions onto single-board platforms with hardened thermal envelopes.
X86 architecture captures the largest revenue pool while edge computing configurations expand most quickly.
End User:
Application criticality drives specification divergence: manufacturing tolerates 24-hour downtime windows while energy sector deployments demand five-nines availability with hot-swappable redundancy.
- Manufacturing:Discrete and process automation lines require real-time deterministic control with cycle times under 1 millisecond. Michigan and South Carolina automotive assembly plants specify IEC 61000-4-x immunity alongside FCC Part 15 emissions compliance for transatlantic equipment sourcing.
- Energy:Oil and gas upstream, midstream, and renewable generation assets deploy explosion-proof and extended temperature platforms. North Sea offshore installations and Texas Permian Basin operations specify Class I Division 2 hazardous location certifications.
- Transportation:Rail signaling, fleet management, and autonomous vehicle testing infrastructure demand shock and vibration resistance per IEC 60068-2-6.
- Retail:Point-of-sale, digital signage, and inventory management systems prioritize compact form factors and wireless connectivity over industrial-grade environmental hardening.
Manufacturing anchors the volume base while energy sector deployments command the steepest premium expansion.
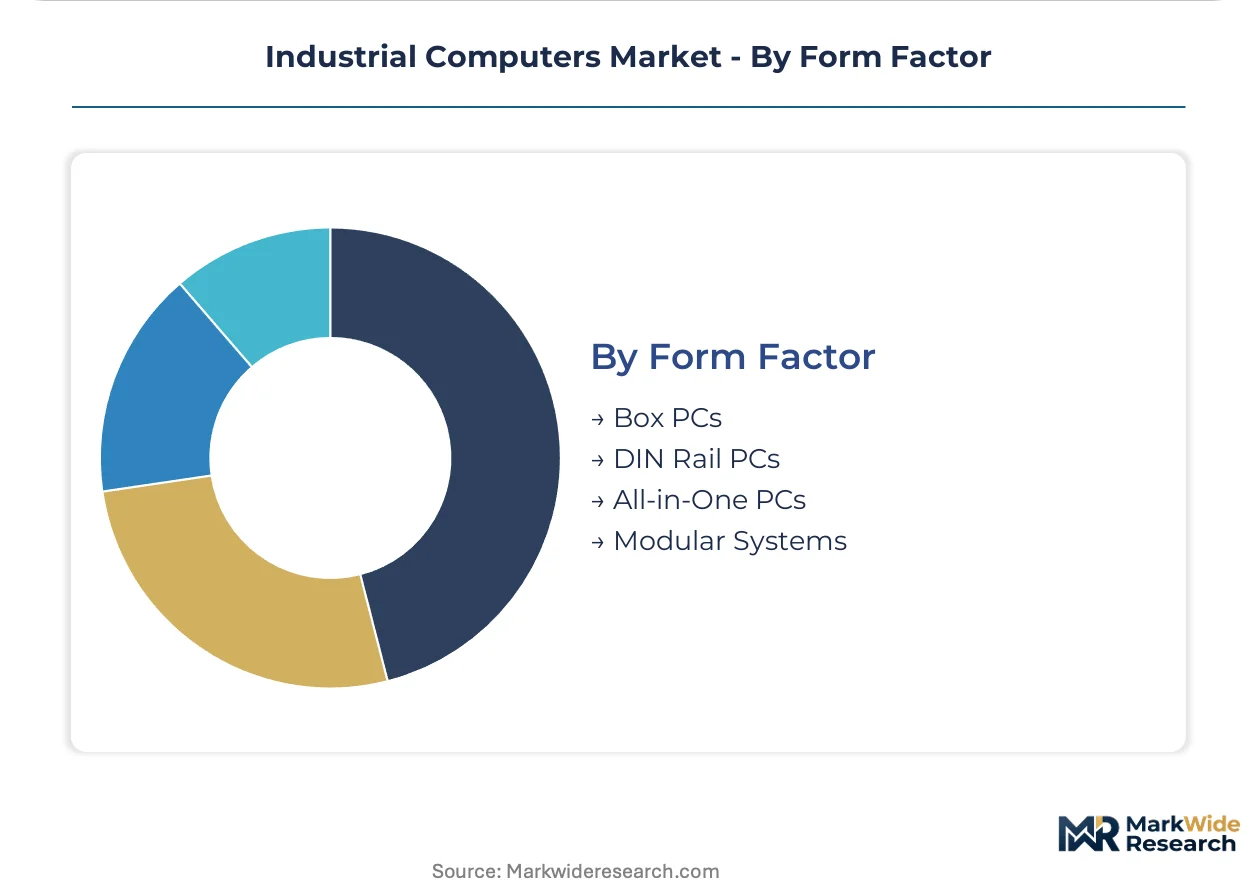
Form Factor:
Customer type segmentation separates system integrator preferences from end-user procurement patterns, with DIN rail configurations dominating panel builder specifications and modular systems serving OEM design-in opportunities.
- Box PCs:Rectangular enclosures with flexible mounting options accommodate wall, panel, and VESA installations across factory floor distributed I/O applications. Machine builders in Italy's Emilia-Romagna packaging machinery cluster specify compact aluminum chassis with passive cooling.
- DIN Rail PCs:35mm top-hat rail mounting integrates directly into electrical panels alongside breakers, terminals, and power supplies. German control panel manufacturers in Baden-Württemberg standardize on this form factor for PLC consolidation projects.
- All-in-One PCs:Display-integrated designs reduce cabling complexity for space-constrained operator stations.
- Modular Systems:Stackable or expandable architectures allow field-upgradable I/O, communication, and processing cards without full system replacement.
DIN rail PCs anchor the volume base while modular systems gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial computer exports flow primarily to automotive assembly plants in the United States and process automation integrators across Central Europe, establishing a transatlantic trade corridor that shapes certification requirements and thermal envelope specifications for ruggedized platforms.
United States
Michigan and South Carolina automotive assembly plants specify IEC 61000-4-x immunity alongside FCC Part 15 emissions compliance for transatlantic equipment sourcing. OSHA-aligned facility inspectors enforce NEMA 4X and IP65/IP67 ingress protection ratings in washdown manufacturing environments. Detroit-area powertrain manufacturers deploy edge computing nodes with hardened thermal envelopes certified to IEC 60068-2-6 vibration standards.
Germany
Bavaria and Baden-Württemberg anchor demand for rackmount and DIN rail configurations serving automotive OEM production lines with 18-24 month replacement cadences. REACH substance restrictions and RoHS recast directives ban cadmium and hexavalent chromium in surface finishes for industrial enclosures. Stuttgart-based machinery OEMs face steep compliance deadlines for converting to zinc-nickel plating and powder coating chemistries.
China
MIIT's GB standards and dual carbon goals accelerate ARM architecture adoption in transportation infrastructure projects seeking superior thermal efficiency. Yangtze River Delta manufacturing clusters consolidate PLC, HMI, and gateway functions onto single-board platforms. Shanghai rail signaling networks specify extended temperature range platforms from -40°C to 85°C with IEC 61000-4-x immunity certification.
India
The PLI scheme for electronics attracts enclosure and embedded systems assembly capacity to serve Asia-Pacific transportation infrastructure demand. Real-time Linux distributions and containerized runtimes in Indian transportation projects erode traditional x86 ISA lock-in. Gujarat and Maharashtra industrial corridors deploy fanless computers in vibration-heavy mining equipment and heavy machinery applications.
Japan
METI industrial policy drives edge computing adoption in Shinkansen control systems and rail signaling infrastructure with decade-long deployment cycles. JIS standards complement IEC 61000-4-x immunity requirements for electromagnetic compatibility in transportation applications. Nagoya-area automotive component manufacturers specify shock and vibration resistance per IEC 60068-2-6 for factory-floor deployments.
Industrial Computers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers, with industrial automation incumbents leveraging deep integrator relationships against embedded computing specialists pushing thermal efficiency boundaries. The vendor base separates into three strategic archetypes: diversified industrial conglomerates with process automation heritage, embedded systems pure-plays with Asia-Pacific manufacturing footprints, and PC-based control convergence specialists merging PLC logic with server-class hardware. Dominant competitive moves include strategic partnerships with system integrators and geographic expansion through local assembly capacity.
Among diversified industrial conglomerates, Siemens AG and Schneider Electric SE exemplify channel control through deep ties to process automation integrators and corporate IT procurement functions. Beckhoff Automation GmbH & Co. KG occupies a distinctive position within the PC-based control convergence archetype, while Advantech Co., Ltd. anchors the embedded systems specialist tier with Asia-Pacific supply chain presence. These three represent divergent strategic postures on architecture standards, thermal design philosophy, and go-to-market channel configuration.
| Leading Market Players |
|---|
| Advantech Co., Ltd. |
| Siemens AG |
| Beckhoff Automation GmbH & Co. KG |
| Kontron AG |
| IEI Integration Corporation |
| Rockwell Automation, Inc. |
| Schneider Electric SE |
| B&R Industrial Automation GmbH |
| NEXCOM International Co., Ltd. |
| Others |
Supply & Pricing Matrix
Semiconductor supply concentration in Taiwan and South Korea creates tariff exposure that widens pricing spreads between x86 legacy platforms and ARM-based alternatives while forcing enclosure manufacturers toward multi-source qualification programs.
Pricing Analysis
Current-generation edge computing nodes with integrated PLC-HMI-gateway functions command substantial premiums over prior-generation distributed rackmount configurations, while next-generation ARM-based fanless designs undercut on BOM costs. Three-tier pricing structure across premium certified-grade, standard industrial-grade, and economy commercial-grade levels separates NEMA 4X stainless steel chassis from standard aluminum enclosures. Cost compression in mid-volume DIN rail configurations intensifies as German automotive OEMs consolidate procurement under corporate IT functions. Transportation infrastructure buyers exhibit highest price sensitivity due to decade-long replacement cycles, while pharmaceutical cleanroom operators accept premiums for sealed washdown-capable enclosures.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment limit foundry capacity expansion for industrial-grade SoCs and FPGAs, constraining supply flexibility. Taiwan, South Korea, and China anchor component sourcing for extended temperature range processors, while Germany and Japan supply precision enclosure fabrication. Raw material dependencies center on aluminum alloys for chassis, nickel-based platings for corrosion resistance, and high-reliability capacitors for thermal tolerance. Single-source vulnerability concentrates in 7nm and below foundry nodes for high-performance edge computing platforms. Distribution runs through system integrator channels in North America and direct OEM relationships in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial computer hardware margins are compressing while cybersecurity service contracts and predictive maintenance subscriptions expand at multiples of base equipment growth, creating a service-attach imperative for sustainable revenue.
For Market Incumbents: Harden defensive positions by deepening backward integration into enclosure manufacturing in India to exploit PLI scheme incentives and offset Taiwan foundry concentration risk. Fortify channel control through exclusive certification partnerships with German automotive OEMs facing REACH compliance deadlines for surface finish conversions. For New Entrants and Emerging Players: Mid-market food processing facilities in India's Gujarat and Maharashtra industrial corridors represent the most penetrable entry point, as these buyers prioritize cost-efficient IP65 enclosures over premium stainless steel alternatives. Target containerized runtime convergence opportunities in transportation infrastructure where real-time Linux expertise scarcity extends incumbent product cycles. Establish technical partnerships with Yocto build system specialists to accelerate ARM-based platform development. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors embedded systems pure-plays with captive Asia-Pacific manufacturing footprints. Long-term viability hinges on exposure to edge computing architecture transitions rather than legacy rackmount dependencies. Watch for inflection signals in containerized control software adoption rates among German machinery OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Containerized Runtime Convergence | Merges PLC, HMI, and gateway functions onto single-board platforms for German automotive OEMs. |
| ARM Architecture Migration | Exploits real-time Linux distributions to displace x86 lock-in in Indian transportation infrastructure. |
| India PLI Scheme Assembly | Captures production-linked incentives for enclosure and embedded systems manufacturing capacity. |
| Cybersecurity Service Bundling | Addresses CISO oversight requirements in Michigan and South Carolina automotive assembly plants. |
| REACH-Compliant Surface Conversion | Preempts regulatory deadlines for zinc-nickel plating adoption among Stuttgart machinery OEMs. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers, OEM procurement managers, system integrator technical leads, and aftermarket service directors, then refined through secondary validation. Primary fieldwork combined structured interviews with control panel manufacturers in Baden-Württemberg and transportation infrastructure operators in Japan's rail networks. Secondary sources encompassed IEC 61000-4-x certification databases, FCC Part 15 equipment authorization filings, customs trade data for industrial computing equipment, and ECHA REACH substance restriction updates. Bottom-up volume estimates from product-type segmentation were triangulated against top-down demand projections from end-use industry analysis.
Demand-supply balance dynamics across the analysis window were modeled through iterative reconciliation of OEM production line refresh schedules with foundry capacity constraints for industrial-grade semiconductors. Segmentation dimensions included product type, processor architecture, end-use industry, and form factor specification. CAGRs were derived from slope-log regression of annual volume trajectories adjusted for replacement cycle compression in automotive applications. Forecast inputs incorporated IEC certification timeline bottlenecks and ARM ecosystem maturity indicators.
Practitioners should monitor foundry utilization rates, REACH substance restriction enforcement intensity, and containerized control software penetration for early signals of forecast deviation. Forecasts reflect documented assumptions regarding semiconductor supply normalization and regulatory compliance deadline adherence. Material shifts in export control scope or extended temperature range component availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
North America 3D Printing Construction Market
Others
Europe Legal Services Market
Others
Molecular Spectroscopy Market
Others
North America IT Device Market
Others
Inflight Entertainment Solutions Market
Others
Czech Republic Market
Others
Global Smartphone ODM Market
Others
Football Sportswear Market
Others
Language Translation Device Market
Others
Depth Gauge Market
Others
Deflectometer Market
Others
Surgical Simulation Market
Others
Advanced Combat Helmet Market
Others
Global Optical Comparator Market
Others
Bakery Packaging Market
Others
Pediatric Measuring Devices Market