
 India Foundry Market | 2026-2036
India Foundry Market Size, Share, and Industry Trends Forecast 2026-2036
India Foundry Market Insights
Automotive buyer concentration is hardening as OEMs consolidate supplier bases across powertrain and chassis programs. Bharat Forge leverages its forging-casting integration to capture high-specification defense and aerospace contracts. JSW Steel anchors western India operations through captive pig iron supply and backward integration into raw material refining. Nelcast competes on ductile iron scale for commercial vehicle suspension components across southern manufacturing corridors.
Foundries are metal-forming facilities that melt ferrous or non-ferrous alloys and pour molten metal into molds to produce engineered cast components, typically achieving dimensional tolerances of CT9-CT11 for sand-cast parts. These facilities supply critical structural and functional parts where net-shape forming reduces machining waste and material cost for heavy industrial applications. Cast iron dominates current output volumes across automotive parts applications, while aluminum die casting captures expanding share in light-weighting programs for passenger vehicle engine brackets and transmission housings. Sand casting sustains margin pools in heavy machinery and energy sector components where low-volume, large-dimension parts resist process substitution.
BIS certification requirements govern alloy specifications and mechanical testing protocols for domestic supply into automotive and defense end uses. India's PLI scheme for automobile and auto components incentivizes foundry capacity expansion linked to domestic value-add thresholds. CEA efficiency mandates and state pollution control board emissions standards shape furnace technology upgrade cycles across Uttar Pradesh, Gujarat, and Karnataka operations. Stakeholders must monitor how BIS alignment with ISO 9001 quality systems and evolving MEE environmental norms reshape capital deployment timelines for greenfield versus brownfield capacity decisions.
Market Dynamics
Automotive OEM consolidation across Maharashtra and Tamil Nadu foundry clusters is compressing supplier margins while elevating quality certification barriers. Tier-1 buyers now mandate BIS-aligned ISO 9001 systems and captive testing facilities as baseline qualification thresholds.
Growth Catalysts
- PLI scheme for auto components:Domestic value-add thresholds incentivize foundry capacity expansion linked to powertrain and chassis programs across Pune and Coimbatore corridors.
- Defense and aerospace demand:High-specification casting requirements for armored vehicle hulls and aircraft structural components pull investment toward forging-casting integration capabilities.
- Aluminum die casting:Passenger vehicle lightweighting programs for engine brackets and transmission housings displace gray iron in select powertrain applications.
Market Restraints
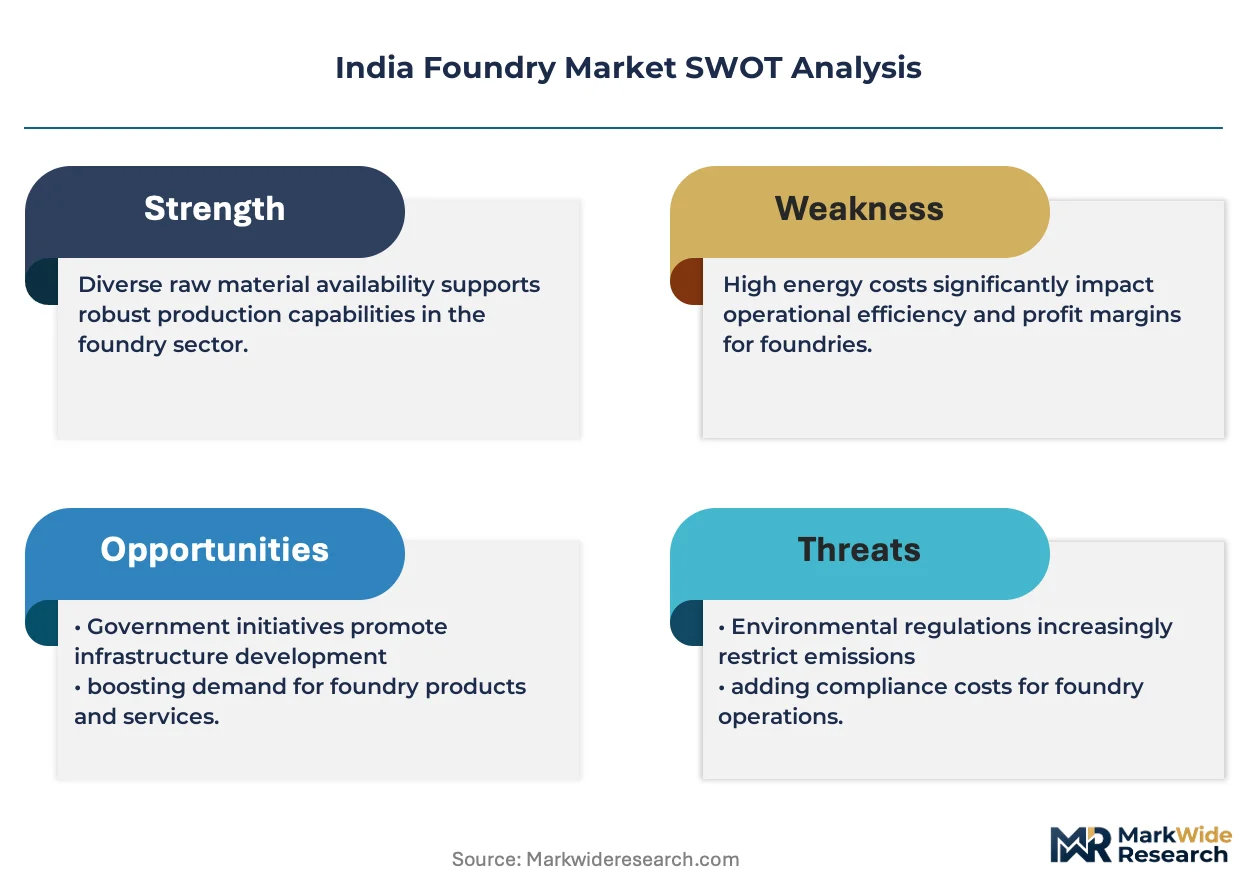
- Pig iron cost volatility:Scrap metal and coke price swings transmit directly into foundry conversion margins, compressing EBITDA at non-integrated operators lacking captive refining.
- CEA efficiency mandates:Furnace technology upgrade cycles impose capital intensity on Uttar Pradesh and Gujarat operations already facing thin margin pools.
- Sand casting substitution ceiling:Low-volume heavy machinery and energy sector components resist process migration despite pressure from investment casting and additive manufacturing.
Strategic Opportunities
- Karnataka industrial corridor expansion:Underpenetrated foundry capacity in the state's precision engineering zones offers greenfield positioning ahead of automotive supplier migration.
- MEE environmental norm alignment:Early compliance with evolving emissions standards creates qualification advantages for defense and export-facing contracts.
- Digital mold flow simulation:Convergence of computational fluid dynamics with automated pouring systems reduces trial casting waste and accelerates new product introduction timelines.
Industry Challenges
- Certification timeline compression:BIS mechanical testing protocols and alloy specification audits extend qualification cycles, delaying revenue recognition on new OEM programs.
- Capex intensity for pollution control:State pollution control board mandates for baghouse filtration and effluent treatment demand front-loaded investment without proportional pricing recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Foundry Market |
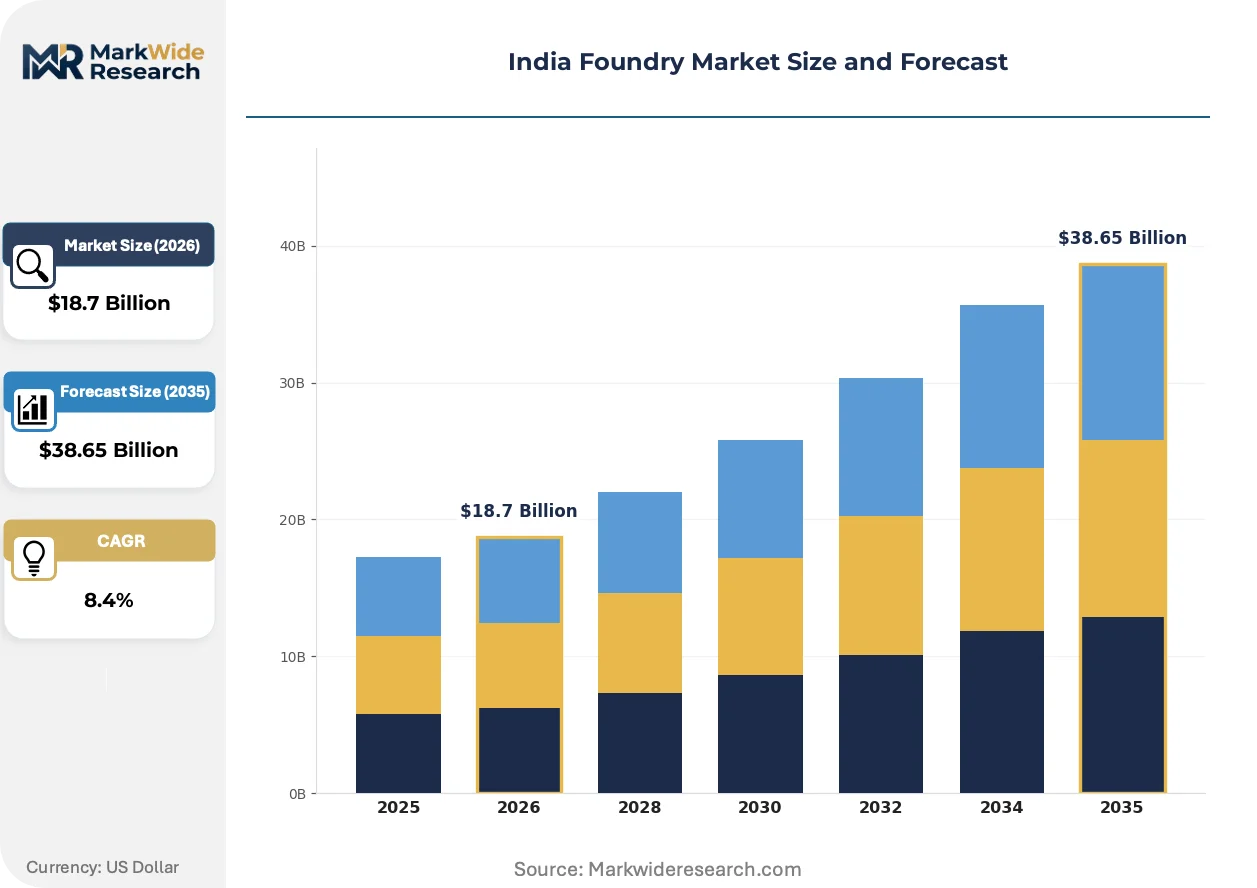
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Iron, Aluminum, Steel, Copper Application: Automotive Parts, Construction Machinery, Energy Sector, Industrial Equipment End User: Aerospace, Defense, Consumer Goods, Heavy Machinery Process Type: Sand Casting, Die Casting, Investment Casting, Centrifugal Casting |
| Companies Covered | Aditya Birla Management Corp, Larsen & Toubro, Bharat Forge, CALMET, JSW Steel, Nelcast, Brakes India, Endurance Technologies, A-Cast Foundry, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Foundry Market Trends and Innovations
Digital foundry technologies are penetrating melting and molding operations across Indian automotive supplier parks. Process control systems and predictive maintenance platforms now define competitive differentiation in quality-sensitive segments.
Automated pouring and robotic finishing systems are automating mold filling and casting extraction across high-volume ductile iron operations serving commercial vehicle suspension programs. Tier-1 suppliers in Coimbatore and Pune industrial belts deploy these systems to achieve CT9 dimensional tolerances on brake caliper and steering knuckle castings. Labor arbitrage erosion and defect rate reduction targets are automating the economics of brownfield modernization versus greenfield capacity.
BIS certification requirements now govern alloy specifications and mechanical testing protocols for domestic automotive and defense supply. The alignment with ISO 9001 quality systems elevates documentation and traceability burdens on mid-scale operators. Foundries serving export markets face parallel pressure from EU REACH substance restrictions and RoHS compliance for aluminum alloy compositions.
Automotive OEM procurement is consolidating supplier bases across powertrain and chassis programs, compressing the qualified vendor list at major manufacturers. Long-term framework agreements with volume commitments and penalty clauses for quality excursions displace spot purchasing and annual bidding cycles. This concentration is most visible across Maharashtra foundry clusters supplying forging-casting integrated components to commercial vehicle assemblers.
India Foundry Market Segmentation
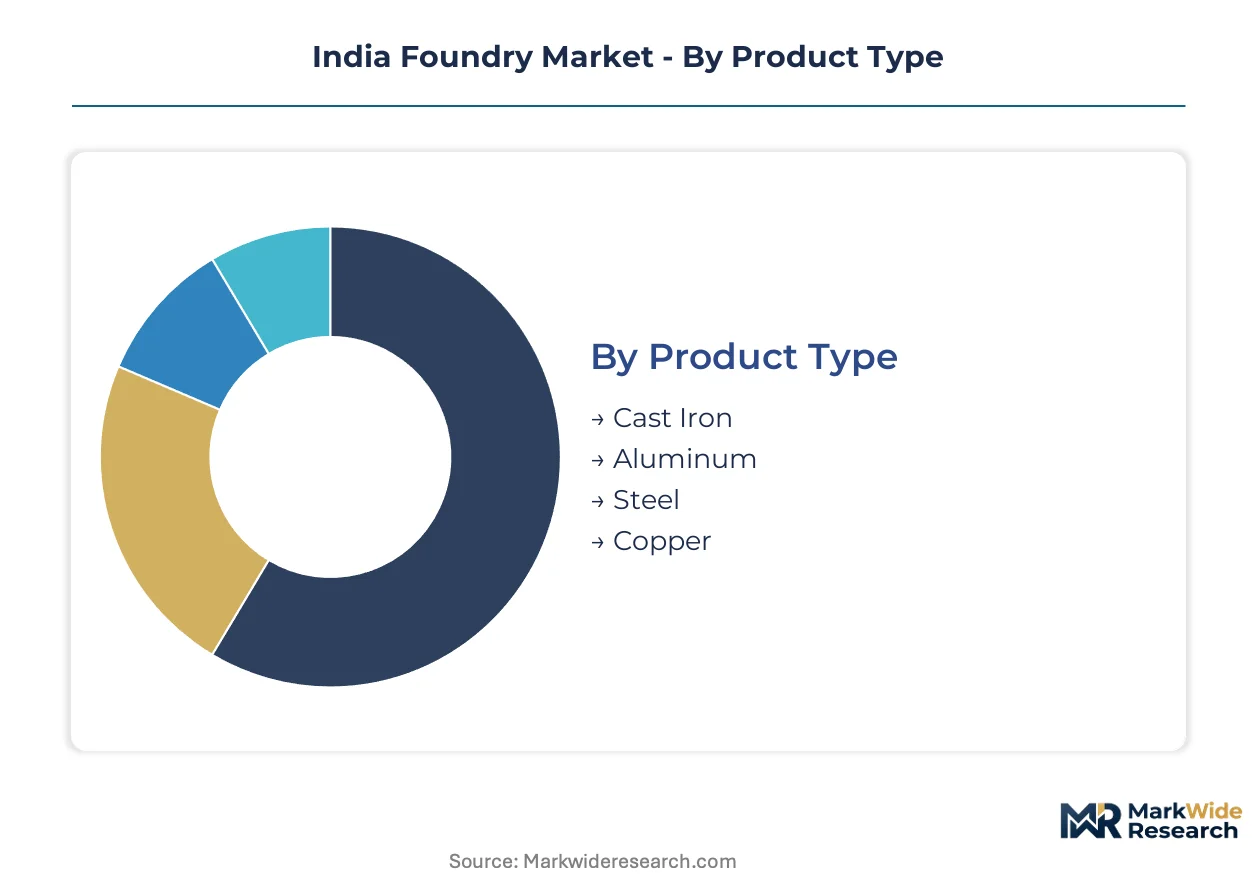
Foundry segmentation in India tracks material substitution patterns, process automation economics, and end-use certification intensity. Each dimension reveals distinct margin pools and capital deployment requirements for operators across Maharashtra, Tamil Nadu, and Gujarat clusters.
Product Type:
Volume concentration in ferrous alloys contrasts with premium pricing in non-ferrous precision grades.
- Cast Iron:Gray and ductile iron formulations dominate tonnage across automotive powertrain and chassis castings. Maharashtra foundry clusters supply brake calipers and steering knuckles to commercial vehicle OEMs under BIS-certified alloy specifications.
- Aluminum:Die-cast alloys capture passenger vehicle lightweighting programs for engine brackets and transmission housings. Pune and Coimbatore corridors expand capacity to meet PLI scheme domestic value-add thresholds for auto component exports.
- Steel:Alloy and carbon steel castings serve high-wear mining and construction machinery applications requiring impact resistance.
- Copper:Electrical conductivity grades concentrate in switchgear and motor winding components for industrial equipment manufacturers.
Today's leader: Cast Iron. Tomorrow's challenger: Aluminum.
Application:
Customer concentration intensity separates automotive contract manufacturing from project-based industrial supply.
- Automotive Parts:Powertrain castings—cylinder blocks, heads, and transmission cases—anchor volume demand across Tamil Nadu supplier parks. Tier-1 procurement consolidation mandates captive testing facilities and ISO 9001 alignment as baseline qualification.
- Construction Machinery:Bucket teeth, track links, and boom castings withstand abrasive wear in mining operations. Gujarat foundries serve domestic equipment assemblers with sand-cast components resistant to investment casting substitution.
- Energy Sector:Turbine housings and valve bodies for thermal and renewable power generation require pressure-tight integrity certifications.
- Industrial Equipment:Pump casings and compressor housings serve general engineering demand across Karnataka precision engineering zones.
Automotive Parts commands current margin pools. Construction Machinery offers counter-cyclical diversification.
End User:
Certification burden and contract duration define commercial attractiveness across buyer categories.
- Aerospace:Investment-grade aluminum and titanium castings for aircraft structural components demand NADCAP-accredited processes. Limited domestic capacity creates import dependence for critical flight-safety parts.
- Defense:Armored vehicle hulls and artillery components pull toward forging-casting integration capabilities. Bharat Forge and similar integrated operators capture high-specification contracts requiring traceability documentation.
- Consumer Goods:Appliance castings for washing machine drums and cookware face price pressure from Asian import competition.
- Heavy Machinery:Mining and earthmoving equipment manufacturers source large-dimension castings where sand casting sustains cost advantages over process substitution.
Defense contracts anchor premium positioning. Aerospace represents the steepest expansion trajectory pending domestic certification infrastructure.
Process Type:
Capital intensity and dimensional precision separate mass-production die casting from flexible sand-cast operations.
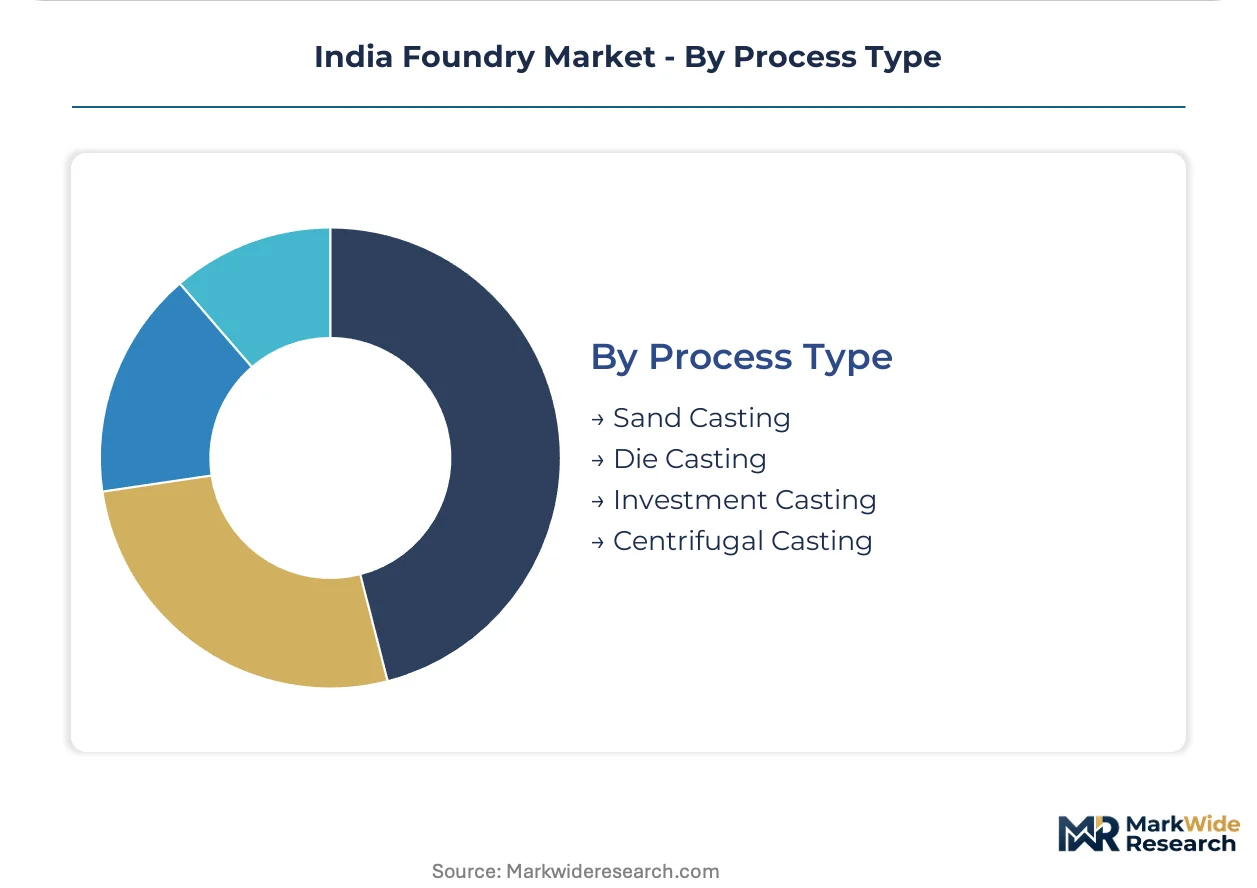
- Sand Casting:Green sand and chemically bonded mold processes produce low-volume, large-dimension parts for energy and heavy machinery sectors. Uttar Pradesh and Gujarat operations face CEA efficiency mandates driving furnace technology upgrade cycles.
- Die Casting:High-pressure aluminum injection achieves CT6-CT8 tolerances for automotive engine brackets and transmission housings. Coimbatore corridors deploy automated pouring systems to reduce defect rates and labor arbitrage erosion.
- Investment Casting:Lost-wax precision processes serve aerospace and medical components requiring near-net-shape forming with minimal machining.
- Centrifugal Casting:Rotational mold filling produces cylindrical components—pipes, liners, and rings—with directional solidification control.
Sand Casting retains volume dominance. Die Casting climbs the fastest on automotive lightweighting demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's foundry capacity outpaces neighboring manufacturing economies in tonnage terms, yet Vietnam and Indonesia are accelerating aluminum die-casting investments for export-oriented automotive supply.
Maharashtra
Pune and Aurangabad industrial corridors concentrate gray and ductile iron capacity for commercial vehicle powertrain castings. The state's pollution control board enforces MEE environmental norms that accelerate furnace technology replacements. Foundry clusters around Chakan and Talegaon supply brake calipers and steering knuckles to Tier-1 automotive suppliers under BIS-certified alloy specifications.
Tamil Nadu
Coimbatore and Chennai manufacturing belts anchor southern India's precision casting output for passenger vehicle engine brackets. CEA efficiency mandates drive induction furnace upgrades across Salem and Hosur operations. The Sriperumbudur supplier park hosts aluminum die-casting facilities serving PLI-linked auto component export programs.
Gujarat
Vadodara and Rajkot foundry clusters specialize in sand-cast components for construction machinery and energy sector valve bodies. State pollution control board emissions standards impose baghouse filtration investments on legacy cupola operations. The Sanand industrial corridor attracts greenfield capacity for high-pressure die-casting serving western automotive OEMs.
Karnataka
Peenya and Mysuru precision engineering zones remain underpenetrated relative to neighboring states' foundry density. BIS quality mandates and ISO 9001 alignment requirements create certification barriers for mid-scale operators entering automotive supply chains. The Tumakuru industrial belt is emerging as a destination for ductile iron capacity serving mining equipment manufacturers.
Uttar Pradesh
Kanpur and Agra foundries supply agricultural machinery castings and pump components for irrigation equipment. CEA efficiency mandates and state pollution control board directives compress margins at non-integrated operators lacking captive pig iron supply. The Greater Noida industrial corridor hosts limited automotive-facing capacity compared to western and southern clusters.
India Foundry Market Competitive Landscape
Western India producers anchor the integrated tier; southern specialists hold positions in ductile iron scale and precision aluminum casting. The market structures around three archetypes: steel majors with captive raw material integration, independent ferrous foundries competing on automotive contract volume, and aluminum die-casters capturing lightweighting programs. Consolidation pressure from OEM procurement rationalization and M&A activity among mid-scale operators defines current competitive dynamics.
Within the integrated steel-tier, JSW Steel exemplifies backward control over pig iron supply and refining operations. Bharat Forge occupies a position spanning forging-casting integration for defense and aerospace specifications. Among independent ferrous specialists, Nelcast represents scale-driven positioning in commercial vehicle suspension components across southern manufacturing corridors.
| Leading Market Players |
|---|
| Aditya Birla Management Corp |
| Larsen & Toubro |
| Bharat Forge |
| CALMET |
| JSW Steel |
| Nelcast |
| Brakes India |
| Endurance Technologies |
| A-Cast Foundry |
| Others |
Pricing and Supply Chain Analysis
Automated pouring systems and robotic finishing lines are compressing labor arbitrage advantages while concentrating production economics in high-volume corridors. This technology transition simultaneously elevates capital barriers for new entrants and reshapes margin distribution between integrated and non-integrated operators across Maharashtra and Tamil Nadu clusters.
Pricing Analysis
Capacity additions in Karnataka and Gujarat are reshaping price floors for aluminum die-cast components serving passenger vehicle programs. Contract-based long-term offtake agreements dominate Tier-1 automotive supply, with pricing stratifying across BIS-certified premium grades, ISO 9001-aligned standard tiers, and uncertified economy supply for aftermarket channels. Cost compression in gray iron foundries is intensifying due to pig iron volatility, with commercial vehicle OEMs exhibiting highest price sensitivity while defense contractors absorb premiums for traceability documentation.
Supply Chain Analysis
Dual-sourcing mandates from automotive OEMs now require Tier-1 suppliers to qualify secondary foundries across Maharashtra, Tamil Nadu, and Gujarat. Raw material flows draw from captive pig iron refining at JSW Steel's western India operations, imported coke through Mundra and Chennai ports, and scrap metal aggregation networks across Pune and Coimbatore industrial belts. Single-source vulnerability concentrates in specialized alloy formulations for aerospace-grade aluminum castings. Distribution runs through OEM-directed supplier parks with just-in-sequence delivery protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in India's foundry sector rests on furnace technology upgrades that cut energy intensity per ton and defense-aerospace certification premiums that detach pricing from commodity cycles.
For Market Incumbents: Anchor market position through backward integration into captive pig iron supply and induction furnace replacements ahead of CEA efficiency mandate deadlines. Consolidate supplier relationships with Maharashtra-based commercial vehicle OEMs before procurement rationalization compresses qualified vendor lists further. Prioritize BIS certification investment as the baseline qualification barrier rises. For New Entrants and Emerging Players: Begin with Karnataka's underpenetrated precision engineering zones where certification gaps create entry windows for ISO 9001-aligned operators. Target ductile iron capacity for mining equipment manufacturers in Tumakuru as automotive supply chains harden qualification thresholds. Pursue joint development agreements with Tier-2 construction machinery assemblers as the fastest path to volume scale. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale ferrous foundries lacking furnace automation but holding BIS-certified alloy specifications and established OEM relationships. Long-term viability favors operators with demonstrated compliance pathways for evolving MEE environmental norms and defense contract traceability infrastructure. Watch for PLI scheme domestic value-add threshold adjustments as the inflection signal for export-facing capacity repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Pig Iron | JSW Steel's refining operations insulate conversion margins from coke price volatility at western India clusters. |
| Furnace Technology Replacement | CEA efficiency mandates force induction furnace upgrades across Uttar Pradesh and Gujarat legacy operations. |
| Defense Certification Investment | NADCAP-aligned processes unlock premium pricing for armored vehicle hull castings at Bharat Forge. |
| Aluminum Die-Casting Capacity Expansion | Coimbatore corridor investments capture PLI-linked auto component export programs for engine brackets. |
| Digital Mold Flow Simulation Deployment | Computational fluid dynamics integration at Nelcast reduces trial casting waste and accelerates new product introduction. |
Research Methodology
Bottom-up automotive and construction machinery modeling reconciled against top-down foundry capacity tracking forms the analytical core of this study. Primary interviews with foundry operations managers, Tier-1 supplier procurement leads, OEM platform engineers, and state pollution control board officials combined with secondary validation from BIS certification databases, CEA efficiency mandate filings, PLI scheme administrative records, and customs trade data on pig iron and coke imports.
Input-output matrices map molten metal throughput to end-use demand across cast iron, aluminum, steel, and copper alloy categories. Segmentation dimensions include material type, process technology, application vertical, and regional production cluster. CAGRs derive from production volume trajectories indexed to OEM program lifecycles and infrastructure capex pipelines. Forecast inputs incorporate furnace energy efficiency curves and alloy substitution elasticity parameters for lightweighting programs.
Caveats apply where BIS mechanical testing protocol revisions or MEE environmental norm enforcement intensity could materially shift the outlook. Deviation in PLI scheme domestic value-add thresholds or automotive OEM supplier consolidation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Fibert Market
Others
Hydrostatic Testing Market
Others
Operator Training Simulator Market
Others
ISO Cylinder Market
Others
Heavy Duty Vacuum Bottle Market
Others
Printed Leather Market
Others
Electrical Calibration Equipment Market
Others
Global Computer Graphics Market
Others
Middle East Paper Making Machine Market
Others
Global Social Networking Market
Others
Global Laser Defense Eyewear Market
Others
Lepidolite Market
Others
Crystal Growth Equipment Market
Others
North America Cashew Market
Others
Global Telemetry Market
Others
Semiconductor Gas Filters Market