
 Japan Coal Market | 2026-2036
Japan Coal Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Coal Market Outlook
Australia's export corridor expansion is tilting supply reliability toward Pacific Basin miners. ITOCHU Corporation leverages long-term offtake agreements with Queensland producers to secure coking coal volumes. Mitsubishi Corporation anchors its trading position through integrated logistics control across Newcastle and Gladstone terminals. JERA Co., Inc. competes aggressively on thermal coal procurement efficiency for its combined-cycle fleet.
Coal comprises combustible sedimentary rock formed from compressed organic matter, with thermal grades typically containing 45-86% carbon content and calorific values between 24-33 MJ/kg; metallurgical varieties command premium pricing due to specific coking properties essential for blast furnace ironmaking. Thermal coal dominates volume flows into power generation, though that segment faces structural pressure from LNG and renewables substitution. Metallurgical coal retains firmer margin pools as Japanese steelmakers lack commercially viable alternatives for primary steel production. Distribution through direct sales channels captures the largest value share, reflecting utility procurement practices favoring term contracts over spot market exposure.
METI governs fuel security policy and strategic petroleum and coal stockpiling requirements, while JIS standards specify coal quality parameters for industrial acceptance. The country's national environmental regulator enforces emission caps that tighten combustion efficiency requirements without outright banning coal-fired capacity. Stakeholders must monitor METI's next Basic Energy Plan revision and its treatment of high-efficiency low-emission coal technology against carbon neutrality commitments.
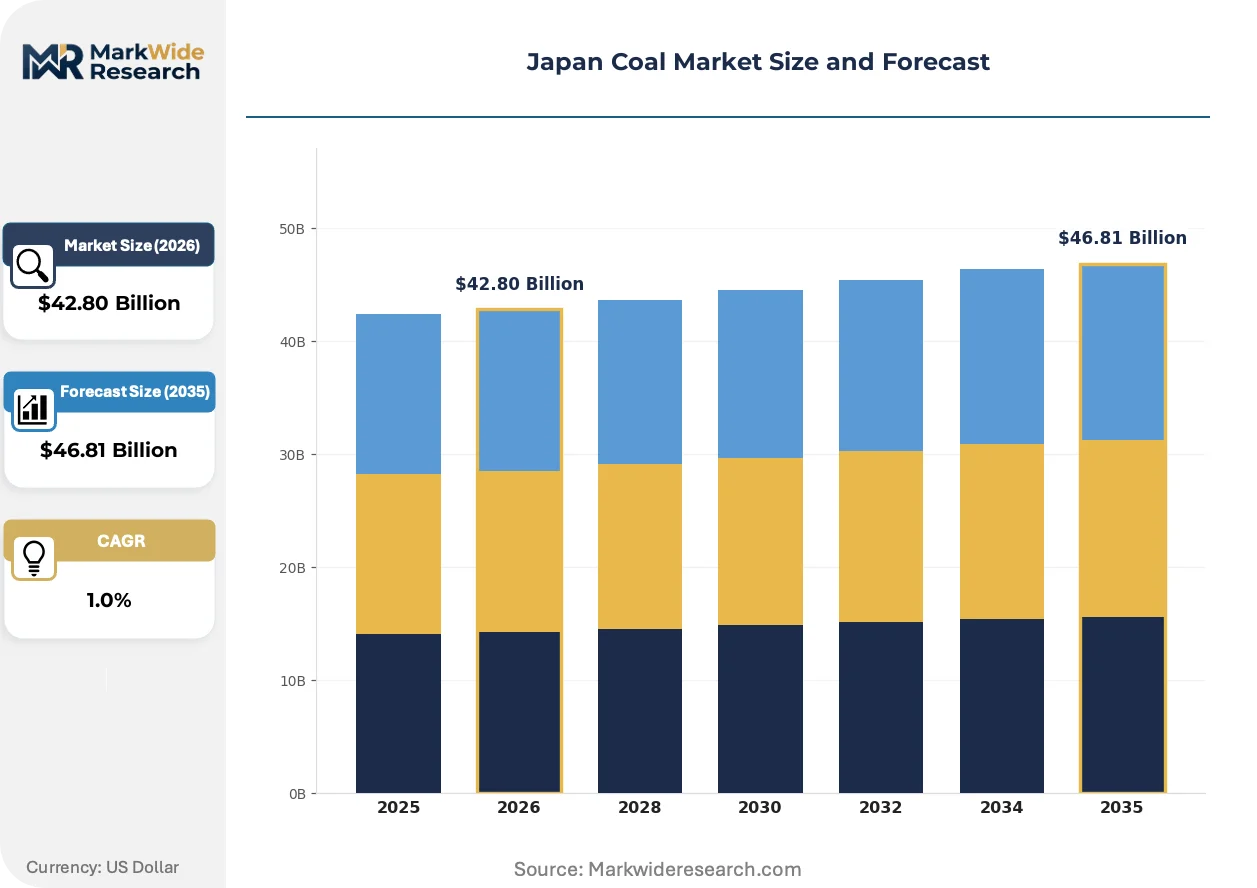
Market Dynamics
METI's pending Basic Energy Plan revision is compressing investment timelines for high-efficiency low-emission coal technology against Japan's carbon neutrality commitments. Utilities now face simultaneous pressure to secure fuel supply reliability while demonstrating decarbonization progress to institutional lenders.
Growth Catalysts
- Steel sector coking demand:Japanese blast furnace operators lack commercially viable alternatives to metallurgical coal for primary ironmaking, sustaining premium-grade import volumes despite thermal coal substitution.
- Kyushu industrial clustering:Coastal manufacturing zones in Fukuoka and Kitakyushu concentrate coal-fired captive power demand that resists grid-scale renewable penetration due to reliability requirements.
- METI strategic stockpiling mandates:Government fuel security requirements compel utilities to maintain minimum coal inventory levels, creating baseline demand independent of spot price volatility.
Market Restraints
- LNG price convergence:Asian spot LNG benchmarks periodically undercut thermal coal delivered costs, enabling direct fuel switching in combined-cycle plants with dual-firing capability.
- Queensland supply concentration:Australian exporters control over half of Japan's import volume, exposing buyers to weather-related production disruptions and port congestion risks.
- Emission intensity disclosure:EU CSRD-equivalent sustainability reporting requirements from Japanese institutional investors restrict capital access for coal-dependent power generators.
Strategic Opportunities
- Chubu carbon capture integration:Nagoya industrial corridor facilities can retrofit post-combustion capture systems to extend asset life under tightening emission caps.
- Ammonia co-firing infrastructure:METI subsidies for 20% ammonia blending trials create upgrade pathways for existing coal units without full replacement capex.
- Direct procurement platforms:Digital freight matching and terminal storage optimization reduce intermediary layers between Queensland miners and Kyushu utilities.
Industry Challenges
- Plant engineering expertise attrition:Retirement waves among ultra-supercritical boiler specialists constrain maintenance quality and efficiency upgrade execution.
- Emission factor certification complexity:JIS standard updates for coal quality testing create compliance lag between shipment arrival and utility acceptance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Coal Market |
| Market Size in 2026 | $42.80 Billion |
| Market Size in 2035 | $46.81 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Coal, Metallurgical Coal, Coking Coal, Anthracite End User: Power Generation, Steel Manufacturing, Cement Production, Chemical Industry Application: Electricity Generation, Heating, Industrial Process, Carbon Black Production Distribution Channel: Direct Sales, Online Platforms, Wholesale, Import |
| Companies Covered | ITOCHU Corporation, Mitsubishi Corporation, Electric Power Development Co., Ltd., JERA Co., Inc, Nippon Steel, Mitsubishi Heavy Industries Ltd, Chiyoda Corp, Mitsui & Co., Ltd., Taiheiyo Coal Mining Co., Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Coal Market Strategic Shifts
Japanese utilities are restructuring fuel procurement around carbon intensity metrics rather than calorific value alone, forcing trading houses to reconfigure supply portfolios and quality blending strategies.
Integrated coal gasification combined cycle technology is collapsing the capital cost differential between new coal capacity and LNG peaking plants for baseload replacement. Chubu Electric Power and JERA are piloting 540°C-class advanced ultra-supercritical units that achieve efficiency gains sufficient to meet 2030 emission intensity targets without fuel switching. The technology is collapsing project finance timelines as development banks recalibrate lending criteria around absolute emission reductions rather than technology exclusion lists.
METI's Green Transformation bond framework is redirecting subsidy eligibility toward emission reduction equipment retrofits rather than new capacity additions. Steelmakers must now document supply chain emission reductions to qualify for preferential financing under the GX initiative. Thermal power generators in the Chubu and Kansai regions are responding by accelerating ammonia co-firing pilot programs to maintain grid reliability while demonstrating decarbonization progress.
Utility procurement departments are consolidating term contract volumes and reducing spot market exposure to manage carbon accounting complexity. Trading houses are absorbing price risk through back-to-back offtake structures rather than traditional merchant trading models. This concentration is most visible in thermal coal purchasing by JERA and Chubu Electric, where direct mine equity stakes are replacing arm's-length spot purchases to secure emission factor transparency.
Japan Coal Market Segmentation
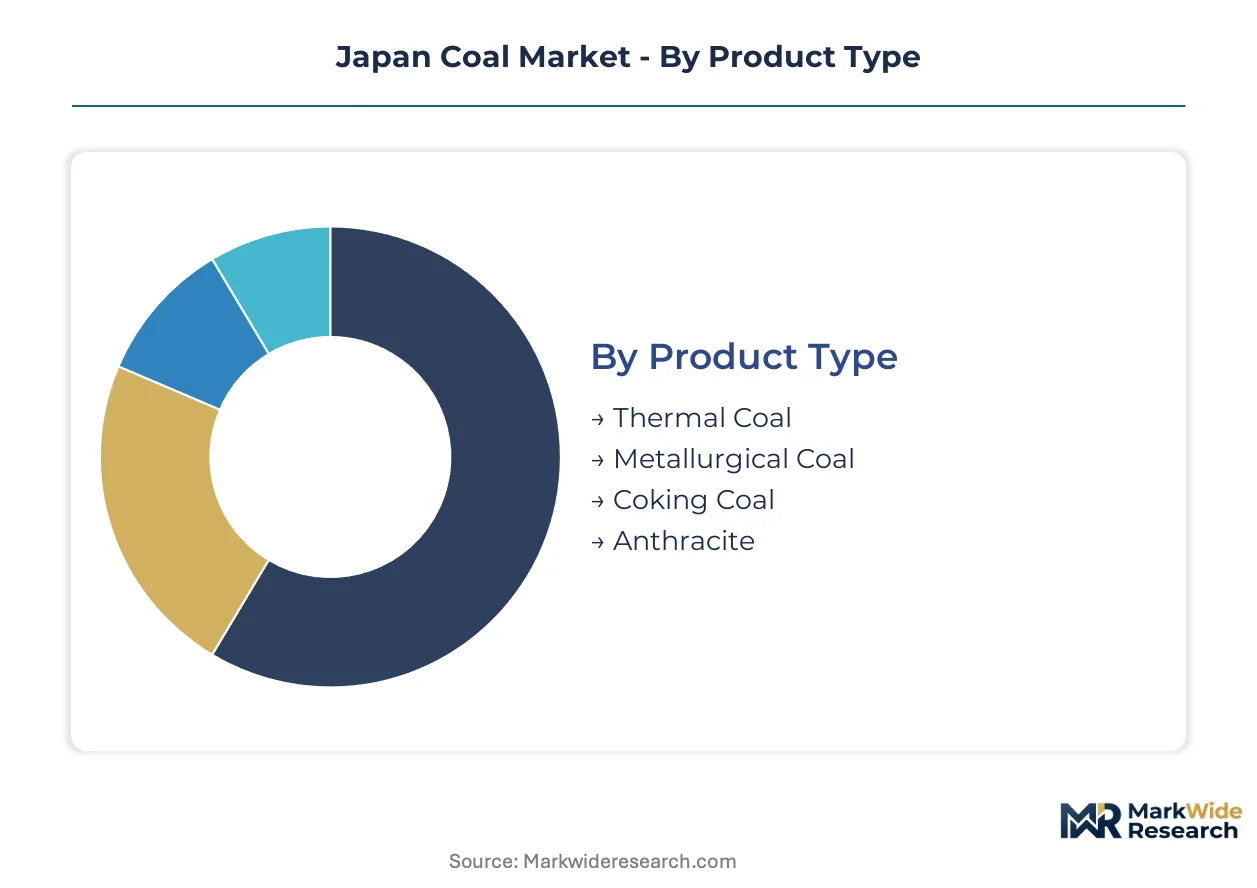
Coal segmentation in Japan reflects divergent procurement cycles across utility and industrial buyers. Power generators operate on multi-year term contracts with slow inventory turnover, while steelmakers face quarterly price renegotiations tied to volatile coking coal benchmarks. Understanding these rhythm differences shapes trading house inventory strategies and METI stockpiling compliance.
Product Type:
Thermal grades turn over fastest in utility stockpiles with 30-60 day cycles, while metallurgical varieties sit in steelmaker inventories for 90-120 days due to quality testing protocols.
- Thermal Coal:Combustible sedimentary rock with 45-86% carbon content and calorific values between 24-33 MJ/kg, primarily consumed by JERA and Chubu Electric in coastal baseload plants. Kyushu utilities concentrate procurement through Newcastle-linked term contracts to secure emission factor transparency for institutional lender disclosure.
- Metallurgical Coal:Premium-grade varieties command pricing spreads over thermal benchmarks due to specific coking properties essential for blast furnace ironmaking. Nippon Steel and JFE Holdings anchor demand in the Chugoku industrial corridor, where captive coke ovens lack fuel-switching alternatives under current commercial technology.
- Coking Coal:Specialized subset of metallurgical grades processed into metallurgical coke for steelmaking reduction reactions. Japanese blast furnace operators source predominantly from Queensland's Bowen Basin through ITOCHU-structured long-term offtakes.
- Anthracite:Highest-rank coal with dense carbon structure and low volatile matter, deployed in specialty metallurgical applications and residential heating in northern Honshu prefectures with limited natural gas pipeline access.
Thermal Coal anchors the volume base while Metallurgical Coal gains share at the steepest rate as steelmakers expand premium-grade procurement under GX initiative emission accounting requirements.
End User:
Cost tier stratification separates capital-intensive continuous processors from batch-oriented industrial consumers with divergent fuel flexibility.
- Power Generation:Combined-cycle and ultra-supercritical thermal plants consume the largest coal volumes under METI strategic stockpiling mandates. JERA's fleet dominates procurement through direct mine equity stakes in Queensland, replacing arm's-length spot purchases to manage carbon accounting complexity.
- Steel Manufacturing:Blast furnace operators and coke oven facilities sustain premium coking coal demand without commercially viable primary ironmaking alternatives. Nippon Steel's Nagoya Works anchors metallurgical coal consumption in the Chubu region, where ammonia co-firing pilot programs aim to extend asset life under tightening emission caps.
- Cement Production:Rotary kiln operators in Kyushu and Chubu prefectures utilize low-grade thermal coal for clinker calcination, facing pressure from alternative fuel substitution including waste-derived fuels.
- Chemical Industry:Coal-to-chemicals facilities in coastal industrial zones process feedstock for synthetic ammonia and methanol production, with procurement cycles tied to petrochemical margin fluctuations.
Power Generation commands the largest procurement volumes while Steel Manufacturing demonstrates the most resilient demand trajectory against thermal substitution pressures.
Application:
Volume concentration favors continuous-process applications over intermittent heating uses with pronounced seasonal demand patterns.
- Electricity Generation:Baseload thermal plants in Kyushu and Chubu regions consume coal through 540°C-class advanced ultra-supercritical units achieving efficiency gains sufficient to meet emission intensity targets.
- Heating:District heating networks and industrial facility boilers in northern Honshu prefectures with limited LNG infrastructure access.
- Industrial Process:Steelmaking reduction reactions, cement clinker production, and chemical synthesis requiring controlled high-temperature environments.
- Carbon Black Production:Specialty rubber reinforcement manufacturing for tire and industrial rubber applications, concentrated in coastal petrochemical complexes.
Electricity Generation maintains the dominant volume position while Industrial Process applications expand most quickly under steel sector capacity additions.
Distribution Channel:
Customer type segmentation separates utility direct procurement from intermediary-dependent industrial buyers with divergent risk management capabilities.
- Direct Sales:Term contracts between Queensland miners and Japanese utilities capture the largest value share, reflecting procurement department preferences for price stability over spot market exposure. JERA and Chubu Electric consolidate volumes through back-to-back offtake structures rather than traditional merchant trading models.
- Online Platforms:Digital freight matching and terminal storage optimization tools emerging to reduce intermediary layers between Australian miners and Kyushu industrial consumers.
- Wholesale:Trading houses including Mitsubishi Corporation absorb price risk through inventory positioning across Newcastle and Gladstone terminals.
- Import:Captive port infrastructure at coastal power plants and steel mills enables vessel-to-silo direct discharge, minimizing inland logistics costs.
Direct Sales channels anchor procurement volume while Online Platforms climb the fastest as utilities seek emission factor transparency through supply chain digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kyushu and Chubu prefectures consume thermal coal through baseload power infrastructure, while Kanto utilities pivot faster toward LNG and ammonia co-firing trials. This consumption-mix differential separates industrial zones with captive reliability requirements from metropolitan demand centers under tighter emission scrutiny.
Kyushu
Fukuoka and Kitakyushu industrial corridors anchor thermal coal demand through captive power plants serving steel and chemical facilities. METI's strategic stockpiling mandates require utilities to maintain minimum inventory levels at coastal terminals. The region's limited grid-scale renewable penetration preserves coal-fired baseload roles despite national decarbonization targets.
Chubu
Nagoya industrial zone concentrates metallurgical coal consumption through Nippon Steel's blast furnace operations and coke oven facilities. The prefecture hosts ammonia co-firing pilot programs subsidized under METI's Green Transformation bond framework. Advanced ultra-supercritical units at Chubu Electric Power achieve efficiency gains sufficient to meet 2030 emission intensity benchmarks.
Kansai
Osaka-Kobe manufacturing belt sustains coking coal demand from JFE Holdings' integrated steelworks without commercially viable primary ironmaking alternatives. Regional utilities face EU CSRD-equivalent sustainability reporting pressure from institutional lenders. Carbon capture retrofit feasibility studies target cement and power assets in the Hanshin industrial corridor.
Kanto
Tokyo metropolitan demand center drives fuel-switching acceleration as JERA consolidates procurement through direct Queensland mine equity stakes. METI's pending Basic Energy Plan revision compresses investment timelines for high-efficiency low-emission coal technology against carbon neutrality commitments. The region's dense LNG infrastructure enables faster thermal coal displacement than western prefectures.
Hokkaido
Northern Honshu prefectures with limited natural gas pipeline access retain anthracite demand for district heating and residential applications. Coal distribution runs through import terminals at Tomakomai and Kushiro with vessel-to-silo direct discharge infrastructure. Local utilities manage seasonal demand peaks through METI-mandated inventory buffers distinct from western Japan's procurement cycles.
Japan Coal Market Competitive Environment
Capability concentration sits with integrated trading houses controlling Queensland supply corridors and logistics infrastructure; scale advantage sits with generation-heavy utilities consolidating term contract volumes. The market structures around three tiers: resource-holding majors with mine equity stakes, pure-play traders absorbing price risk through back-to-back offtakes, and captive procurement departments at steelmakers and power generators. Dominant competitive moves include direct mine equity acquisition replacing arm's-length spot purchases, and digital freight matching platforms reducing intermediary layers between Australian miners and Kyushu industrial consumers.
Within the integrated trading tier, ITOCHU Corporation and Mitsubishi Corporation exemplify resource-holding strategies through long-term Queensland offtake structures and terminal control positions. JERA Co., Inc. occupies a distinct scale-driven position as a generation-anchored buyer consolidating procurement through direct mine stakes rather than merchant trading models. These three entities represent the prevailing competitive archetypes: trading house vertical integration, utility direct procurement, and hybrid structures blending fuel security mandates with carbon accounting transparency requirements.
| Leading Market Players |
|---|
| ITOCHU Corporation |
| Mitsubishi Corporation |
| Electric Power Development Co., Ltd. |
| JERA Co., Inc |
| Nippon Steel |
| Mitsubishi Heavy Industries Ltd |
| Chiyoda Corp |
| Mitsui & Co., Ltd. |
| Taiheiyo Coal Mining Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Newcastle-Gladstone freight corridors transmit Queensland supply concentration into Japanese utility procurement costs, with vessel charter rates and port congestion fees feeding directly into term contract price differentiation between Kyushu baseload buyers and Chubu industrial consumers.
Pricing Analysis
Long-term offtake structures dominate thermal coal procurement, with JERA and Chubu Electric consolidating volumes through back-to-back arrangements rather than spot exposure. Price differentiation rests on emission factor transparency and calorific value bands, with premium metallurgical grades commanding spreads over thermal benchmarks due to coking property specificity. Cost compression in standard thermal grades is intensifying because LNG price convergence periodically undercuts delivered coal costs. Power generators demonstrate highest price sensitivity due to fuel-switching capability, while steelmakers show lowest sensitivity given absence of primary ironmaking alternatives.
Supply Chain Analysis
Extended payment terms from Queensland miners through trading house intermediaries finance inventory positioning across Newcastle and Gladstone terminals. Supply concentration draws from Australia, Indonesia, and Russia, with metallurgical coke feedstock and ultra-supercritical boiler components as critical input dependencies. Single-source vulnerability runs through Queensland's Bowen Basin, where weather-related production disruptions expose Japanese buyers to volume shortfalls. Distribution runs through direct vessel-to-silo discharge at captive port infrastructure, minimizing inland logistics layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
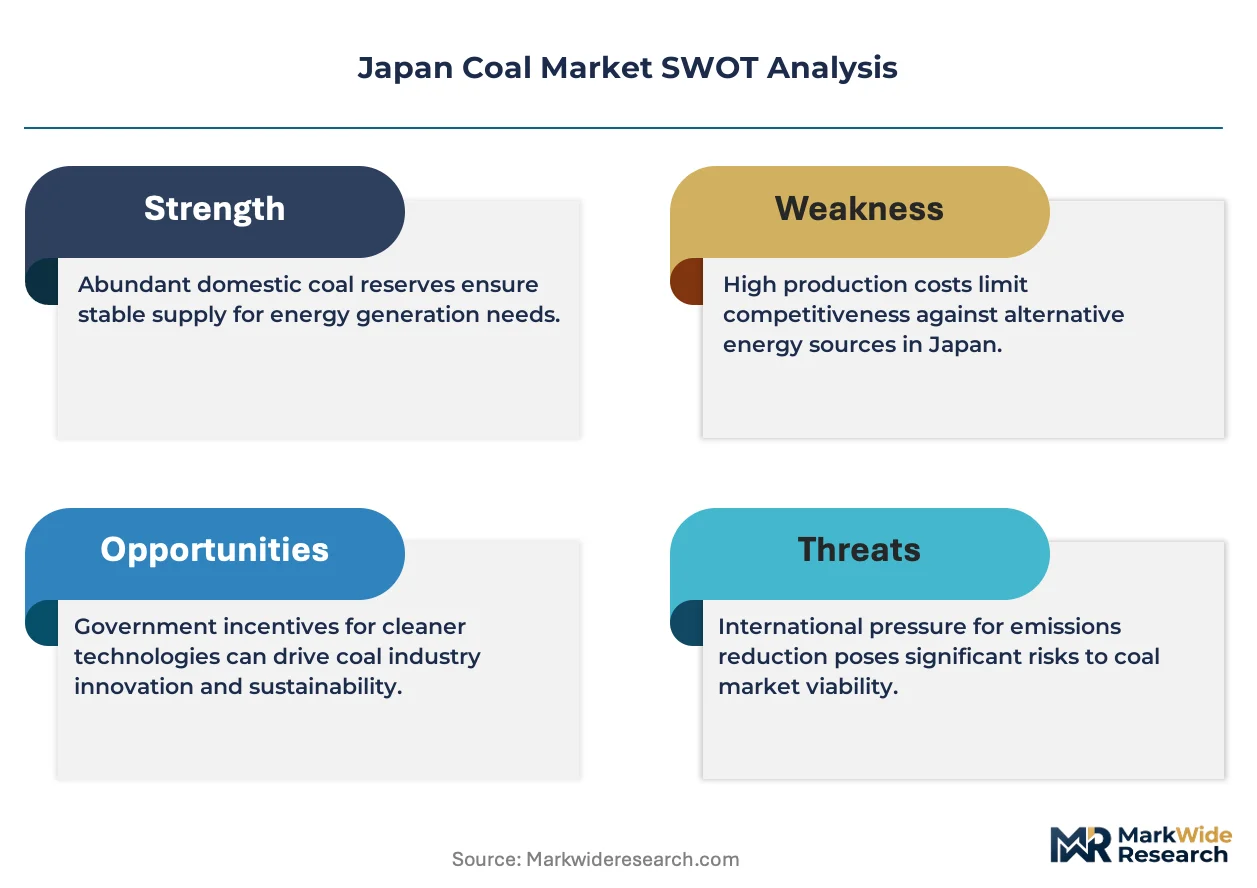
Fragmentation opportunity emerges from divergent decarbonization timelines across Japanese regional utilities, with METI's Basic Energy Plan revision creating niche procurement strategies for high-efficiency low-emission technology providers.
For Market Incumbents: Build emission factor transparency moats through direct Queensland mine equity stakes replacing arm's-length spot purchases. Consolidate term contract volumes to manage carbon accounting complexity for institutional lenders. Threat of LNG substitution demands accelerated ammonia co-firing pilot execution. Leverage METI Green Transformation bond subsidies for retrofit capex. For New Entrants and Emerging Players: Kyushu industrial zones with limited grid-scale renewable penetration offer the most penetrable demand pocket for captive power solutions. Target cement and chemical sector alternative fuel substitution gaps with waste-derived feedstock offerings. Digital freight matching platforms reduce intermediary layers between Australian miners and regional utilities as entry wedge. For Investors and Strategic Acquirers: Trading houses with integrated logistics control over Pacific Basin terminals represent the priority acquisition archetype for fuel security exposure. Long-term viability frames around ammonia co-firing infrastructure and carbon capture retrofit asset life extension. Watch METI stockpiling mandate adjustments as inflection signal for baseline demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Mine Equity Acquisition | JERA's Queensland stakes secure emission factor transparency for lender disclosure requirements. |
| Ammonia Co-firing Infrastructure | METI subsidies enable 20% blending trials without full plant replacement capex. |
| Carbon Capture Retrofit | Chubu Electric pilots post-combustion systems to extend asset life under tightening caps. |
| Digital Procurement Platforms | Freight matching tools reduce intermediary layers between miners and Kyushu utilities. |
| Long-term Offtake Restructuring | Back-to-back structures absorb price risk as trading houses exit merchant models. |
Study Parameters
Initial hypotheses were tested against primary input from utility fuel procurement officers, trading house supply specialists, steelmaker raw materials directors, and METI policy planners and refined through secondary validation. Primary fieldwork drew from Queensland mining operations, Newcastle terminal logistics, and Kyushu power plant intake facilities. Secondary sources incorporated IEA coal market reports, METI energy statistics, JIS quality standard documentation, and customs import clearance records. Bottom-up utility consumption models and top-down national energy balance triangulation anchored volume estimates.
Demand-supply balance modeling across the projection horizon segmented by coal grade tier, end-use sector, regional consumption cluster, and procurement channel structure. CAGRs derived from regression analysis of historical import volumes against power generation load factors and steel production capacity utilization. Forecast inputs incorporated METI Basic Energy Plan scenario weights and GX bond subsidy allocation trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by ammonia infrastructure specialists or carbon capture technology providers would shift outcomes. Macroeconomic deviation, regulatory acceleration, or breakthrough ironmaking technology would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Small Office Home Office (SOHO) Servers Market
Others
North America Forklift Truck Market
Others
Asia-Pacific Programmatic Display Advertising Market
Others
Asia-Pacific Adtech Market
Others
Solar Lighting Tower Market
Others
Global Extruded Plastics Market
Others
Hookah Tobacco Market
Others
Linear Shaft Market
Others
Architectural Fabrics Market
Others
US 3D Printing Construction Market
Others
Global Cosmetovigilance Market
Others
Vacuum Evaporators Market
Others
Receiving Scales Market
Others
Global Hair Loss Treatment Products Market
Others
Global Mica Market
Others
Asia-Pacific Medical Simulation Market