
 Europe Intercom Devices Market | 2026-2036
Europe Intercom Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Intercom Devices Market Foresight
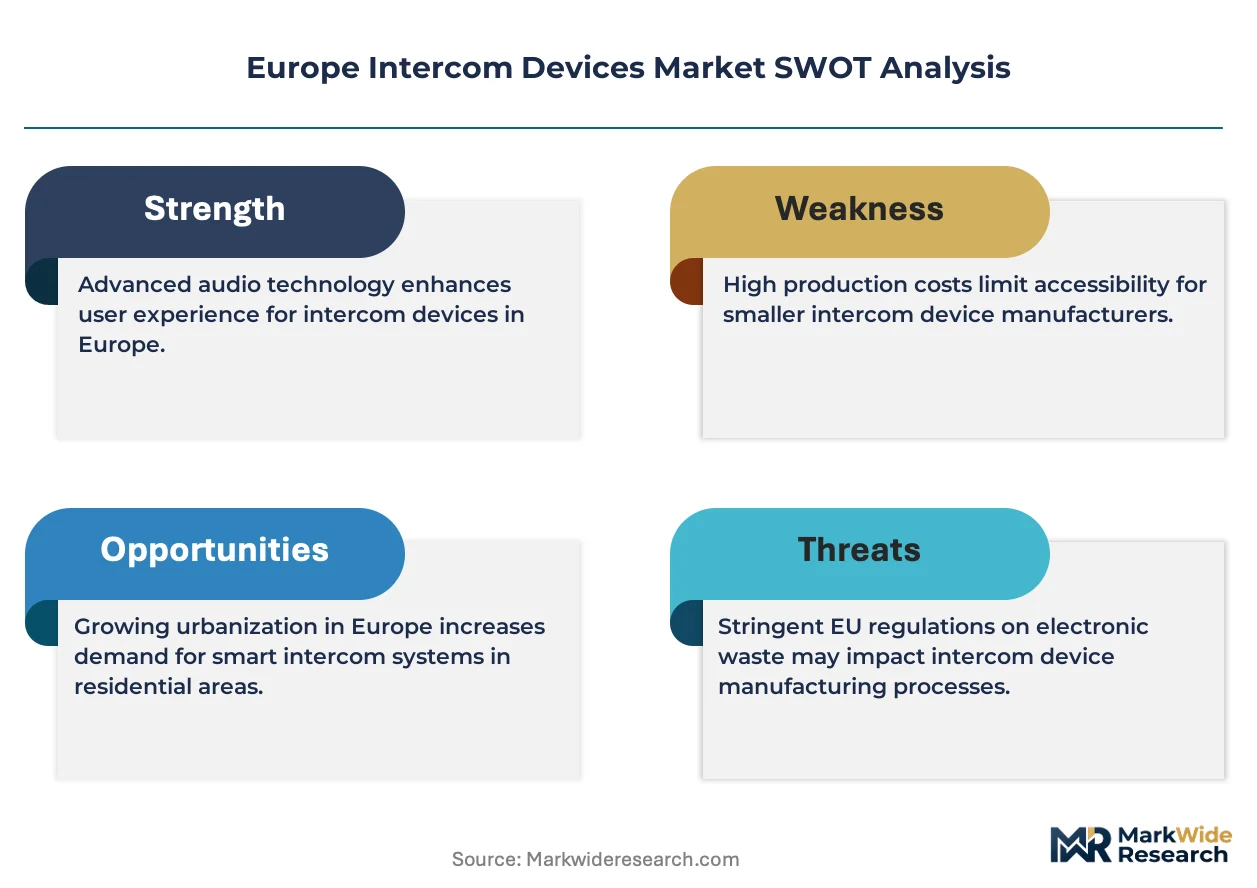
European electronics manufacturing is decoupling from legacy analog supply chains as semiconductor allocation shifts toward IP-enabled intercom architectures. Panasonic Corporation leverages its industrial sensor portfolio to anchor premium video intercom lines. Siedle sustains its position through in-house metal fabrication and channel control across German-speaking markets. Honeywell International Inc. competes on building-automation integration, extending its fire-safety distribution into integrated intercom systems.
Intercom devices comprise audio and video communication terminals that transmit voice, data, and visual signals between fixed points using analog wiring, digital IP protocols, or radio frequency links, typically operating on 12-24V DC power with IP65 or higher ingress protection for outdoor units. These systems serve security screening, access control, and internal coordination across residential, commercial, and industrial facilities. Video intercoms command the deepest margin pools as multi-tenant residential and healthcare facilities upgrade from audio-only legacy hardware. Wireless intercoms represent the fastest-expanding installation category where building retrofit constraints prohibit cable pulls. The public sector user segment remains the most price-sensitive, with procurement concentrated through framework agreements and distributor networks.
CE marking under the EU Radio Equipment Directive and cybersecurity certification aligned with ETSI standards govern market access, while the EU AI Act imposes transparency obligations on facial recognition features in video intercoms. Germany's KBA and France's ANSSI contribute national layer requirements for critical infrastructure deployments. Stakeholders must monitor harmonized standard revisions and national implementation gaps to avoid certification delays and procurement disqualification.
Market Dynamics
IP protocol migration is compressing product lifecycles across European intercom manufacturing, forcing simultaneous redesigns of hardware architectures and software stacks to maintain CE marking compliance under evolving ETSI cybersecurity standards.
Growth Catalysts
- Smart building mandates in Germany:Commercial real estate operators in Berlin and Munich are retrofitting access infrastructure to meet federal energy efficiency benchmarks, creating pull-through for integrated intercom systems.
- EU Cybersecurity Act certification pathways:The Common Criteria framework is standardizing security validation across member states, reducing fragmentation for vendors seeking multi-country deployment.
- Healthcare facility upgrades:French and Italian hospitals are replacing audio-only nurse call systems with video-enabled intercom terminals to support patient monitoring workflows.
Market Restraints
- Semiconductor allocation bottlenecks:Foundry capacity constraints for industrial-grade SoCs are extending lead times for IP-enabled intercom controllers by 12-18 weeks.
- Copper and aluminum price volatility:Analog system manufacturers face margin compression as wiring harness material costs fluctuate with commodity markets.
- Legacy infrastructure lock-in:Multi-tenant residential buildings across Southern Europe retain extensive 2-wire analog installations that resist cost-effective retrofit.
Strategic Opportunities
- Polish and Romanian greenfield construction:New commercial developments in Warsaw and Bucharest are specifying native IP intercom architectures without legacy migration burdens.
- EU AI Act transparency requirements:Facial recognition module vendors can differentiate through pre-certified compliance packages that accelerate end-user procurement cycles.
- Cloud-managed service models:Building operators in the United Kingdom are adopting subscription-based intercom maintenance, shifting revenue from hardware sales to recurring service fees.
Industry Challenges
- Firmware security patching cadence:Manufacturers must sustain decade-long update commitments for installed base devices to satisfy national cybersecurity regulators.
- Cross-vendor protocol interoperability:ONVIF and SIP standard implementation gaps create integration failures when mixing intercom terminals with third-party access control platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Intercom Devices Market |
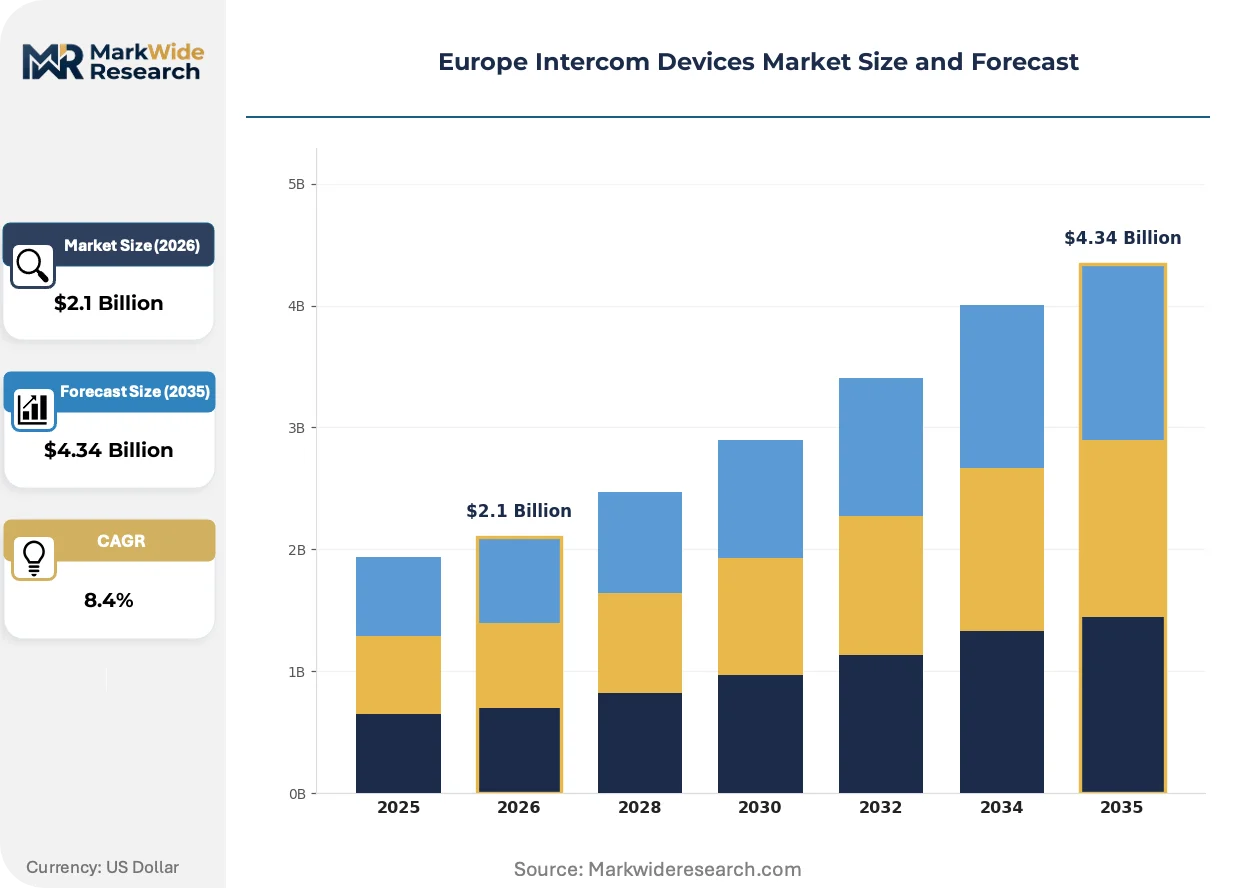
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Intercoms, Wireless Intercoms, Video Intercoms, Intercom Systems Installation Type: Indoor Installation, Outdoor Installation, Wall-Mounted, Portable User Type: Residential Users, Commercial Users, Industrial Users, Public Sector Distribution Channel: Direct Sales, Retail Stores, Online Sales, Distributors |
| Companies Covered | Panasonic Corporation, 2N Telekomunikace, Siedle, Farfisa, Commend International Gmbh, Honeywell International Inc., Urmet Spa, Doorbird, Samsung Electronics Co Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Intercom Devices Market Shifts & Advancements
Edge AI inference is redistributing computational load from central servers to door station hardware, enabling real-time analytics without persistent cloud connectivity. This architectural shift is redefining component specifications and supplier relationships across the value chain.
PoE++ power delivery is absorbing the electrical burden previously handled by separate 24V AC transformers, allowing single-cable deployment of video intercoms with pan-tilt cameras and heater elements. German system integrators are specifying these configurations for new commercial builds in Hamburg and Frankfurt. The technology is absorbing installation labor costs and reducing failure points in outdoor deployments.
France's ANSSI is mandating security certification for intercoms deployed in critical infrastructure facilities, creating a two-tier market where uncertified products face automatic disqualification from public tenders. Manufacturers are re-engineering supply chains to source components from pre-approved vendors. Healthcare and transportation verticals in France represent the initial compliance pressure points.
Facility managers in Italy and Spain are consolidating vendor relationships through framework agreements with national distributors, displacing the fragmented procurement of individual building projects. This concentration is compressing margins for smaller intercom specialists while rewarding scale players with service network coverage. The pattern is most pronounced in multi-site retail and logistics campus deployments.
Europe Intercom Devices Market Segmentation
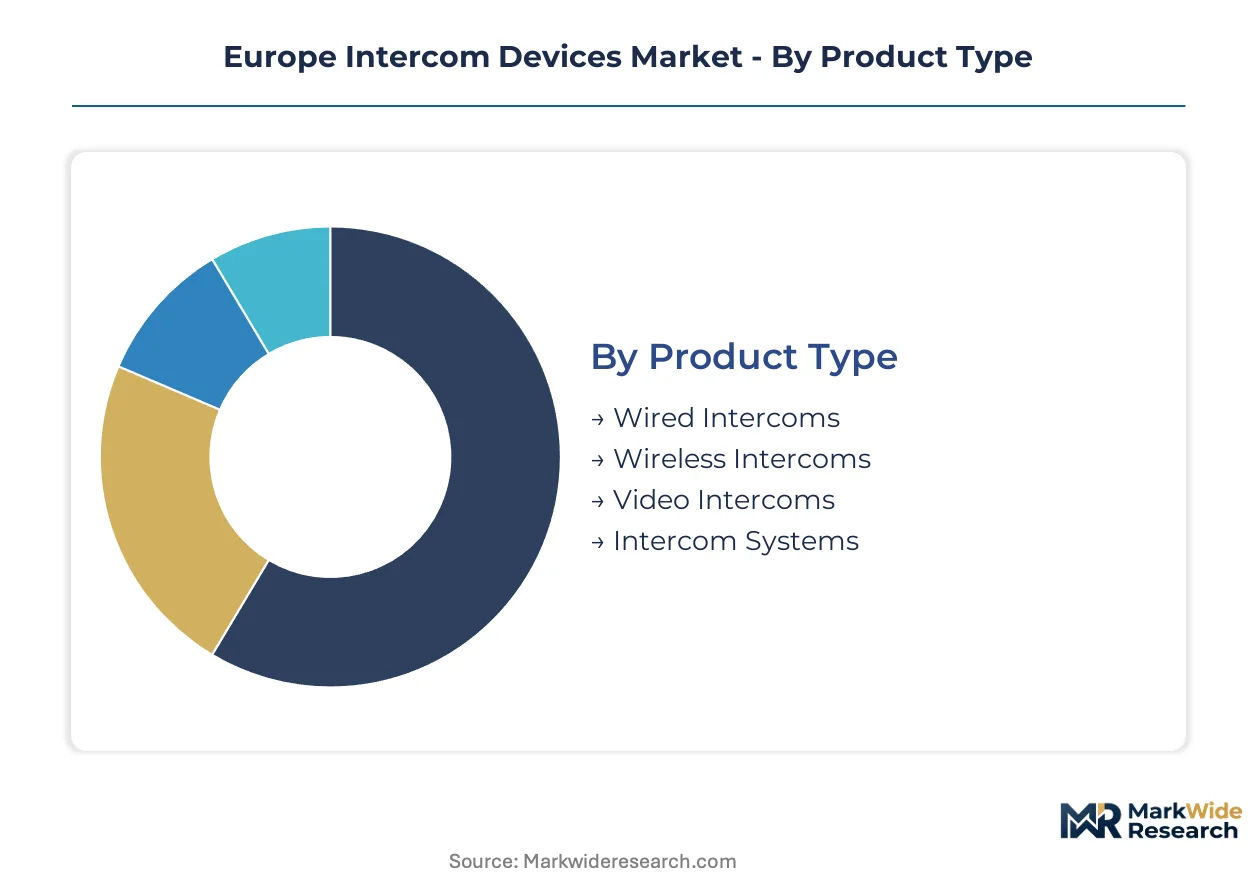
Segmentation in the Europe Intercom Devices Market reveals how technology specifications, installation constraints, and procurement pathways fragment demand across distinct customer workflows. Understanding these divisions helps vendors align product roadmaps with the divergent requirements of German smart building mandates, French healthcare retrofits, and UK cloud-managed service adoption.
Product Type:
Technology architecture determines power requirements, bandwidth consumption, and integration complexity across European deployments.
- Video Intercoms:Multi-sensor door stations transmit encrypted visual streams over IP networks with H.265 compression and ONVIF compliance. French hospitals and Italian multi-tenant residential towers in Milan are replacing audio-only legacy units to support facial recognition access workflows under evolving EU AI Act transparency obligations.
- Wireless Intercoms:Battery-powered or Wi-Fi-enabled terminals eliminate cable pulls in heritage buildings where structural preservation prohibits retrofit drilling. These configurations are expanding most quickly across Spanish and Portuguese apartment blocks with reinforced concrete walls that resist new conduit installation.
- Wired Intercoms:Analog 2-wire and digital IP-over-CAT5 systems dominate German commercial new-build specifications where PoE++ infrastructure is pre-installed during construction phases.
- Intercom Systems:Integrated platforms combining door stations, indoor monitors, and building management interfaces serve Polish and Romanian greenfield logistics campuses requiring centralized access control.
Video Intercoms leads on scale; Wireless Intercoms leads on momentum.
Installation Type:
Physical mounting constraints dictate enclosure ratings, thermal management, and labor cost structures across climate zones from Nordic winters to Mediterranean summers.
- Outdoor Installation:IP65+ rated door stations with integrated heaters and anti-condensation coatings withstand temperature cycling from Stockholm to Athens. German system integrators in Hamburg specify these for maritime climate exposure.
- Indoor Installation:Flush-mount monitors and desktop consoles operate in climate-controlled environments with lower ingress protection requirements. UK care facilities are standardizing on touch-screen nurse call terminals with video verification.
- Wall-Mounted:Surface-mounted brackets accommodate retrofit scenarios where recessed electrical boxes are absent, common in Italian Renaissance-era residential conversions.
- Portable:Handheld or mobile-app-linked units serve temporary construction sites and event security deployments across French commercial real estate developments.
Outdoor Installation commands premium pricing; Indoor Installation captures volume concentration in healthcare verticals.
User Type:
Procurement sophistication and total cost of ownership horizons diverge sharply between individual consumers and institutional buyers operating multi-site portfolios.
- Commercial Users:Property management firms and corporate facilities teams demand API-accessible platforms with centralized credential management. Berlin and Munich office landlords are bundling intercom upgrades into federal energy efficiency retrofit programs.
- Residential Users:Single-family homeowners and small multi-tenant buildings prioritize plug-and-play simplicity over integration depth. Spanish coastal vacation rental operators are adopting app-managed video entry for remote guest access.
- Industrial Users:Manufacturing plants and logistics hubs require ATEX-certified or heavy-duty intercoms with noise cancellation for high-decibel environments.
- Public Sector:Municipal procurement through framework agreements prioritizes lowest compliant bid, with French ANSSI certification increasingly mandatory for critical infrastructure tenders.
Commercial Users drives technology upgrade cycles; Public Sector imposes compliance barriers that filter vendor participation.
Distribution Channel:
Channel economics reflect the technical support burden and project scale fragmentation characteristic of European building automation markets.
- Distributors:National and regional wholesaler networks provide inventory buffering and pre-sales technical consultation for system integrators. Italian and Spanish facility managers are consolidating procurement through framework agreements with these intermediaries.
- Direct Sales:Manufacturer-led account teams serve large multi-site rollouts requiring custom firmware and dedicated project management, prevalent in UK cloud-managed service transitions.
- Online Sales:E-commerce platforms capture price-sensitive residential replacement demand and standardized product configurations with minimal technical support requirements.
- Retail Stores:Big-box and specialized electrical retailers serve emergency replacement and small contractor walk-in purchases.
Distributors maintains channel dominance; Direct Sales gains traction in subscription-based service conversions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as vendors relocate final assembly to Poland and Romania to offset compliance costs from Germany's KBA and France's ANSSI certification requirements. Production migration follows a clear cost-of-compliance gradient, with CE marking and EU Cybersecurity Act obligations concentrating higher-value engineering in Western Europe while assembly shifts eastward.
Germany
Commercial real estate operators in Berlin and Munich are retrofitting access infrastructure to meet federal energy efficiency benchmarks under the Building Energy Act. The KBA imposes national-layer cybersecurity requirements for critical infrastructure deployments. System integrators in Hamburg specify PoE++ video intercom configurations for maritime climate exposure in new commercial builds.
France
Healthcare facilities are replacing audio-only nurse call systems with video-enabled terminals to support patient monitoring workflows. ANSSI mandates security certification for intercoms in critical infrastructure, creating automatic disqualification for uncertified products in public tenders. The Paris metropolitan area concentrates demand from multi-site retail and logistics campus deployments consolidating through framework agreements.
United Kingdom
Building operators are adopting subscription-based intercom maintenance models, shifting revenue from hardware sales to recurring service fees. GDPR compliance requirements govern biometric data processing in facial recognition deployments. London facility managers are bundling cloud-managed service conversions into multi-site portfolio upgrades.
Italy
Multi-tenant residential towers in Milan are upgrading from audio-only legacy units to support modern access workflows. The EU AI Act transparency obligations apply to facial recognition features in video intercom installations. Facility managers are consolidating vendor relationships through national distributor framework agreements, displacing fragmented project-level procurement.
Poland
New commercial developments in Warsaw are specifying native IP intercom architectures without legacy migration burdens. CE marking under the EU Radio Equipment Directive governs market access for all imported devices. Greenfield logistics campuses are driving demand for integrated platforms combining door stations with centralized access control.
Europe Intercom Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-managed service models and edge AI differentiation. The vendor base clusters around three strategic archetypes: industrial conglomerates with sensor portfolios, specialized metal fabricators with channel control, and building-automation integrators extending fire-safety distribution. Competitive moves concentrate on M&A for cybersecurity certification capabilities and strategic partnerships for cloud service infrastructure.
Among Japan-based electronics manufacturers, Panasonic Corporation exemplifies the industrial-sensor-to-intercom extension archetype. Siedle anchors the specialized fabrication tier with in-house metal production and German-speaking market channel control. Honeywell International Inc. occupies the building-automation integration position, leveraging fire-safety distribution networks into intercom system deployments.
| Leading Market Players |
|---|
| Panasonic Corporation |
| 2N Telekomunikace |
| Siedle |
| Farfisa |
| Commend International Gmbh |
| Honeywell International Inc. |
| Urmet Spa |
| Doorbird |
| Samsung Electronics Co Ltd |
| Others |
Supply & Pricing Matrix
Captive semiconductor sourcing from Taiwan and South Korea anchors tiered pricing power for European intercom vendors, while in-house metal fabrication by Siedle and Panasonic insulates premium video intercom lines from commodity wiring harness volatility. This integration choice separates vendors who control critical component pipelines from those exposed to foundry allocation bottlenecks and copper price swings.
Pricing Analysis
Distributor margin layers in German-speaking markets absorb 25-35 points before system integrator markup, compressing netbacks for analog specialists facing copper and aluminum volatility. Three-tier pricing structure across premium video, standard IP, and economy analog levels stratifies by cybersecurity certification grade under ETSI standards and after-sales service bundling. Pricing pressure stems from framework agreement consolidation by Italian and Spanish facility managers, with public sector procurement showing highest sensitivity to lowest-compliant-bid thresholds.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based foundries supplying industrial-grade SoCs for IP-enabled controllers, extending lead times when capacity tightens. Component sourcing draws from China for camera modules, Germany for precision metalwork, and South Korea for memory chips. Supply chain risk centers on tariff exposure for Chinese-sourced facial recognition modules under evolving EU AI Act transparency obligations. Distribution runs through national wholesaler networks in Italy and Spain, with direct sales gaining traction in UK cloud-managed service transitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Intercom Devices Market functions as a regulatory compounder where CE marking under the EU Radio Equipment Directive and cybersecurity certification aligned with ETSI standards create recurring compliance-driven replacement cycles. The EU AI Act transparency obligations for facial recognition features represent the most recent milestone accelerating video intercom upgrades across French healthcare and German commercial real estate.
For Market Incumbents: Deploy firmware security patching infrastructure to sustain decade-long update commitments demanded by Germany's KBA and France's ANSSI. Backward integration into in-house metal fabrication and captive semiconductor allocation agreements defends margin position against emerging cloud-native entrants. Channel control through framework agreements with Italian and Spanish national distributors locks out smaller specialists lacking service network coverage. For New Entrants and Emerging Players: Edge AI inference modules without persistent cloud connectivity offer a technology-first wedge into Polish and Romanian greenfield logistics campuses specifying native IP architectures. White-space targets include subscription-based maintenance models for UK building operators shifting from hardware sales to recurring service fees. A go-to-market angle through pre-certified EU AI Act compliance packages accelerates procurement cycles for facial recognition deployments in French critical infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for cybersecurity certification specialists because ANSSI and KBA national-layer requirements fragment vendor qualification across member states. Long-term viability favors platforms with recurring revenue exposure and captive component sourcing. The signal to watch is framework agreement consolidation velocity in Southern Europe, where distributor concentration displaces fragmented project-level procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | ANSSI and KBA compliance unlocks French and German critical infrastructure tenders. |
| Cloud-Managed Service Launch | Subscription models capture UK building operators shifting from hardware ownership. |
| Edge AI Module Development | On-device inference meets EU AI Act transparency obligations without cloud dependency. |
| Framework Agreement Partnership | National distributor consolidation in Italy and Spain compresses competitor access. |
| PoE++ Infrastructure Integration | Single-cable deployment reduces German commercial new-build installation labor costs. |
Research Methodology
Multiple input streams — primary interviews with system integrators, facility managers, and cybersecurity compliance officers; secondary validation through ETSI standard documentation, EU regulatory filings, and building automation trade data; plus customs records for component import flows — were reconciled to construct segment-level demand estimates. Bottom-up project pipeline analysis across Warsaw, Bucharest, Berlin, and Milan construction databases was cross-checked against top-down equipment spend ratios from commercial real estate retrofit programs.
Data-stream reconciliation anchored volume projections to smart building mandate adoption curves in Germany and healthcare facility upgrade timelines in France and Italy. Segmentation dimensions modeled include product architecture, installation environment, user procurement sophistication, and channel pathway across the analysis window. CAGRs were derived from installed base replacement cycles intersecting with regulatory compliance deadlines, with semiconductor allocation constraints and copper price volatility feeding scenario bands.
The model holds under stable regulatory implementation timelines; deviation in EU AI Act enforcement intensity or ETSI standard revision cadence would shift replacement cycle assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Computer Peripherals Market
Others
Fluorapatite Market
Others
North America Video Conferencing Hardware Market
Others
India 3D Printing Construction Market
Others
Aerospace and Defense Fiber Optic Cables Market
Others
Industrial Computers Market
Others
Asia-Pacific Intercom Devices Market
Others
Document Camera Market
Others
Coalescing Filter Market
Others
South Korea Automotive LED Lighting Market
Others
Smart Home and Office Market
Others
Air Purification Systems Market
Others
Smart Home Controller Market
Others
Badminton Apparel Market
Others
Global Emergency Spill Response Market
Others
Edge Computing in Healthcare Market