
 Medium-Voltage Switchgear Market | 2026-2036
Medium-Voltage Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Medium-Voltage Switchgear Market Intelligence
Aftermarket service revenue is narrowing the margin gap between original equipment sales and lifecycle support contracts across the medium-voltage switchgear industry. ABB leverages its installed base of gas-insulated systems to secure long-term service agreements in European utilities. Siemens sustains R&D intensity in digital protection platforms that integrate with smart grid architectures. Schneider Electric anchors its competitive position through geographic dominance in African and Middle Eastern electrification projects.
Medium-voltage switchgear comprises electrical disconnect switches, fuses, and circuit breakers rated between 1 kV and 52 kV, designed to protect, control, and isolate power distribution circuits in industrial and utility networks. Gas-insulated switchgear dominates high-density urban installations where footprint constraints and environmental sealing prove critical, while air-insulated switchgear retains cost advantages in rural and outdoor substation deployments. The renewable energy end-user segment represents the fastest-growing demand pool as wind and solar farms require specialized switchgear capable of managing variable load profiles and bi-directional power flows.
The International Electrotechnical Commission's IEC 62271 series governs switchgear design and testing protocols, while the EU F-Gas Regulation restricts sulfur hexafluoride emissions from gas-insulated installations and compels manufacturers toward alternative insulation technologies. India's Central Electricity Authority mandates BIS certification for all medium-voltage equipment deployed on the national grid, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor the pace of SF6-phase-out regulations alongside digital interoperability standards that determine which technology platforms capture utility procurement contracts over the next decade.
Market Dynamics
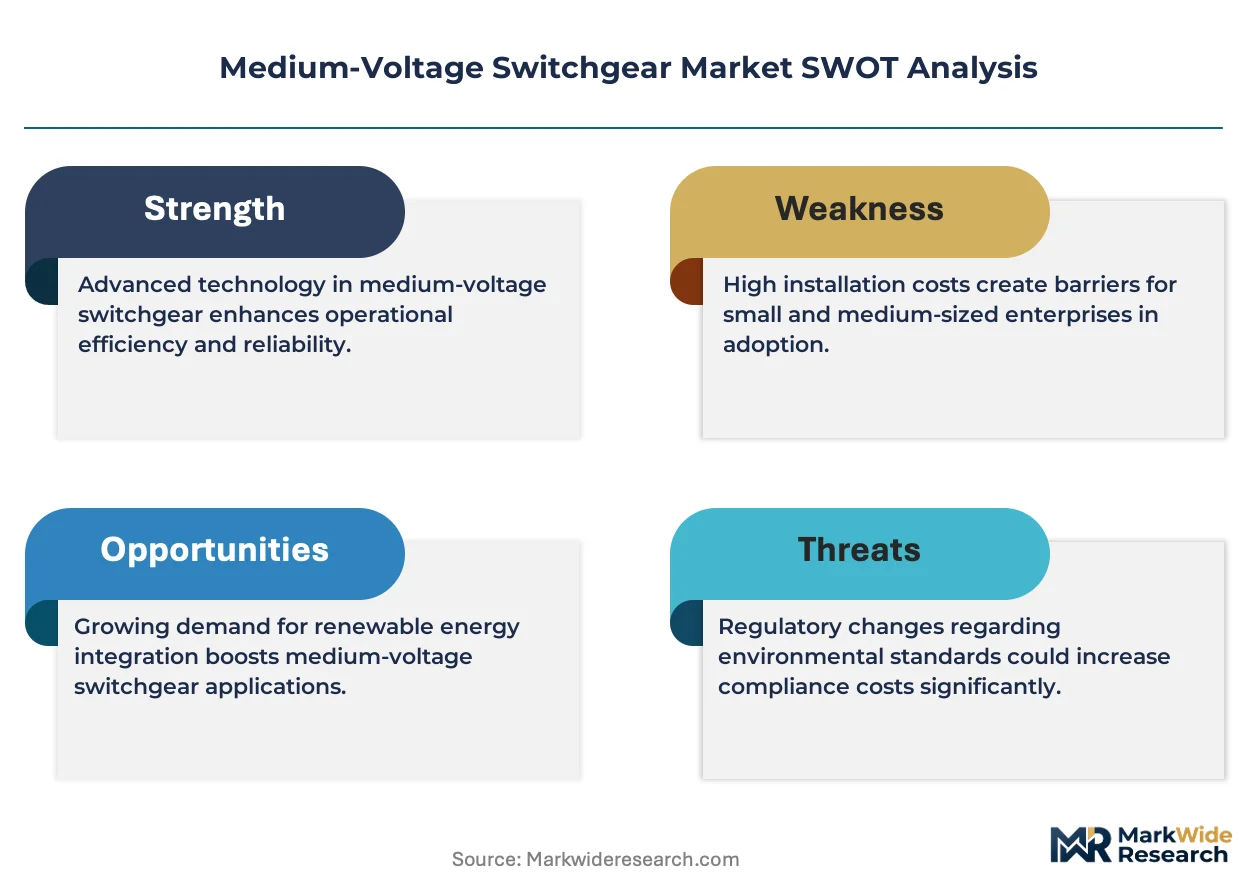
The medium-voltage switchgear sector faces structural pressure from the EU F-Gas Regulation, which mandates sulfur hexafluoride phase-out timelines and forces manufacturers toward alternative insulation chemistries before patent-protected designs mature.
Growth Catalysts
- Rural electrification mandates:India's Central Electricity Authority drives procurement volumes through village-level grid extension programs requiring air-insulated switchgear assemblies.
- IEC 62271-200 revisions:Updated arc-flash containment standards compel utility asset replacement cycles across European distribution networks.
- Bi-directional power hardware:Solar and wind farm interconnection specifications create specialized demand for switchgear managing variable frequency infeed.
Market Restraints
- SF6 alternative R&D costs:Vacuum interrupter and fluoronitrile development programs consume capital without guaranteed regulatory grandfathering.
- Copper and aluminum price volatility:Raw material input swings compress fabrication margins for air-insulated busbar assemblies.
- Certification fragmentation:India's BIS testing protocols diverge from IEC baseline, creating duplicate compliance burdens for multinational suppliers.
Strategic Opportunities
- Vietnam and Indonesia grid buildouts:State utility expansion plans in Southeast Asia favor gas-insulated switchgear for coastal substation density.
- Digital twin integration:Protection relay data streams converge with SCADA platforms, enabling predictive maintenance service contracts.
- EU Green Deal funding windows:National recovery facility allocations subsidize SF6-free switchgear retrofits in German and French distribution zones.
Industry Challenges
- Arc-flash engineering specialization:Short-circuit withstand calculation expertise concentrates among aging utility engineering cohorts.
- Legacy electromechanical relay replacement:Digital protection platform integration demands protocol translation skills scarce in field service organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium-Voltage Switchgear Market |
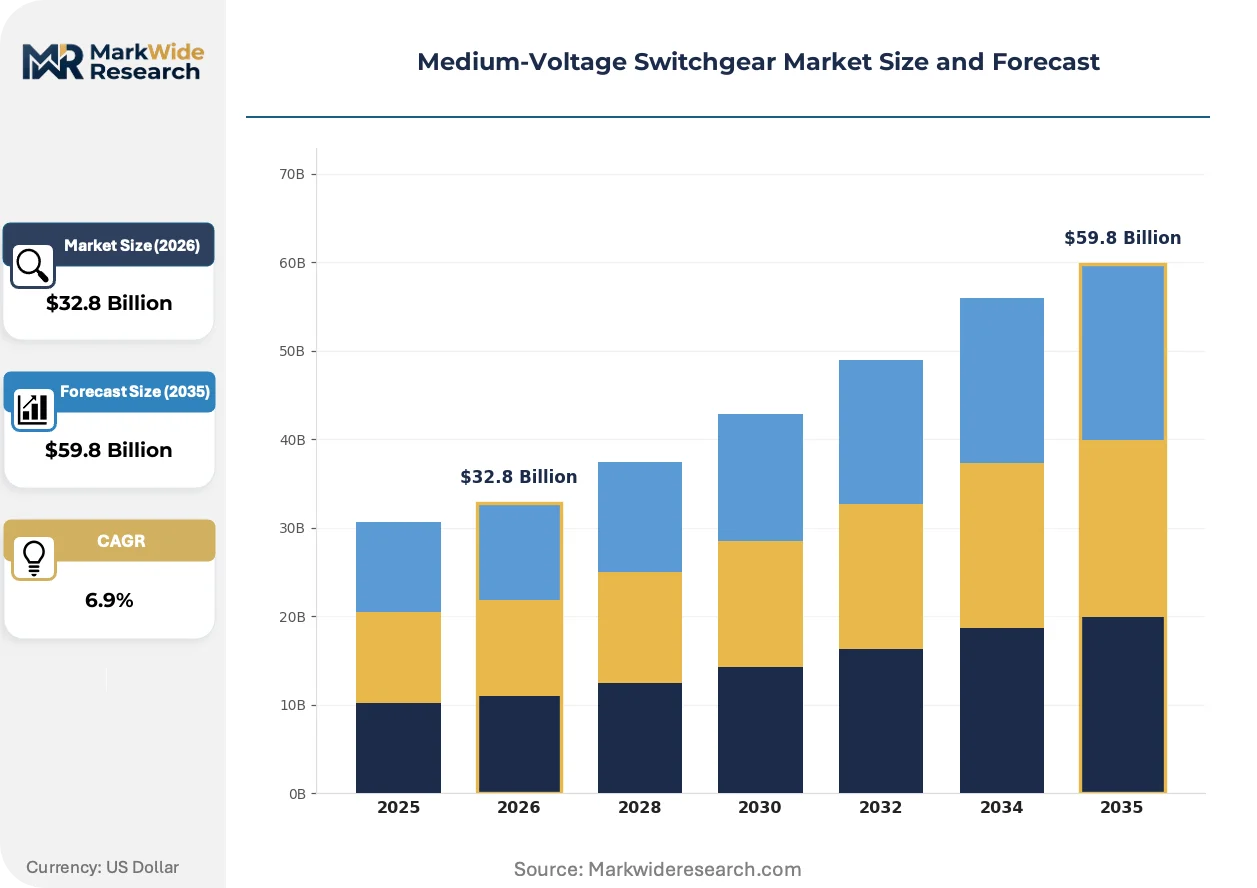
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $59.8 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas-Insulated Switchgear, Air-Insulated Switchgear, Hybrid Switchgear, Modular Switchgear End User: Utilities, Industrial, Commercial, Renewable Energy Installation Type: Indoor, Outdoor, Stationary, Mobile Technology: Digital Protection, Smart Grid, Automation, Conventional |
| Companies Covered | ABB, Schneider Electric, Siemens, Eaton, General Electric, Mitsubishi Electric, CG Power and Industrial Solutions, Bharat Heavy Electricals, HD Hyundai Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium-Voltage Switchgear Market Strategic Shifts & Innovations
Switchgear architecture is pivoting around insulation technology transitions and digital protection convergence, with regulatory chemistry mandates now determining R&D allocation faster than pure performance metrics.
Vacuum interrupter technology is migrating from distribution voltage classes toward higher short-circuit rating applications previously dominated by SF6 puffer designs. European utilities in Germany and the Netherlands are specifying vacuum-based gas-insulated switchgear for urban substation rebuilds. This technology trajectory is compressing the addressable market for conventional SF6 equipment ahead of regulatory bans.
The EU F-Gas Regulation imposes mandatory leakage monitoring and reporting thresholds on all switchgear containing sulfur hexafluoride above one kilogram. Manufacturers must now certify end-of-life gas recovery protocols and document alternative insulation migration roadmaps. German TSOs and French DSOs are accelerating procurement of fluoronitrile and vacuum-based alternatives to avoid stranded asset risk.
Utility procurement departments are unbundling switchgear supply from installation and commissioning services, creating standalone vendor pools for each phase. European distribution cooperatives now separate primary equipment tendering from civil works and protection setting contracts. This pattern is most pronounced in German municipal utilities restructuring their vendor qualification frameworks.
Medium-Voltage Switchgear Market Segmentation
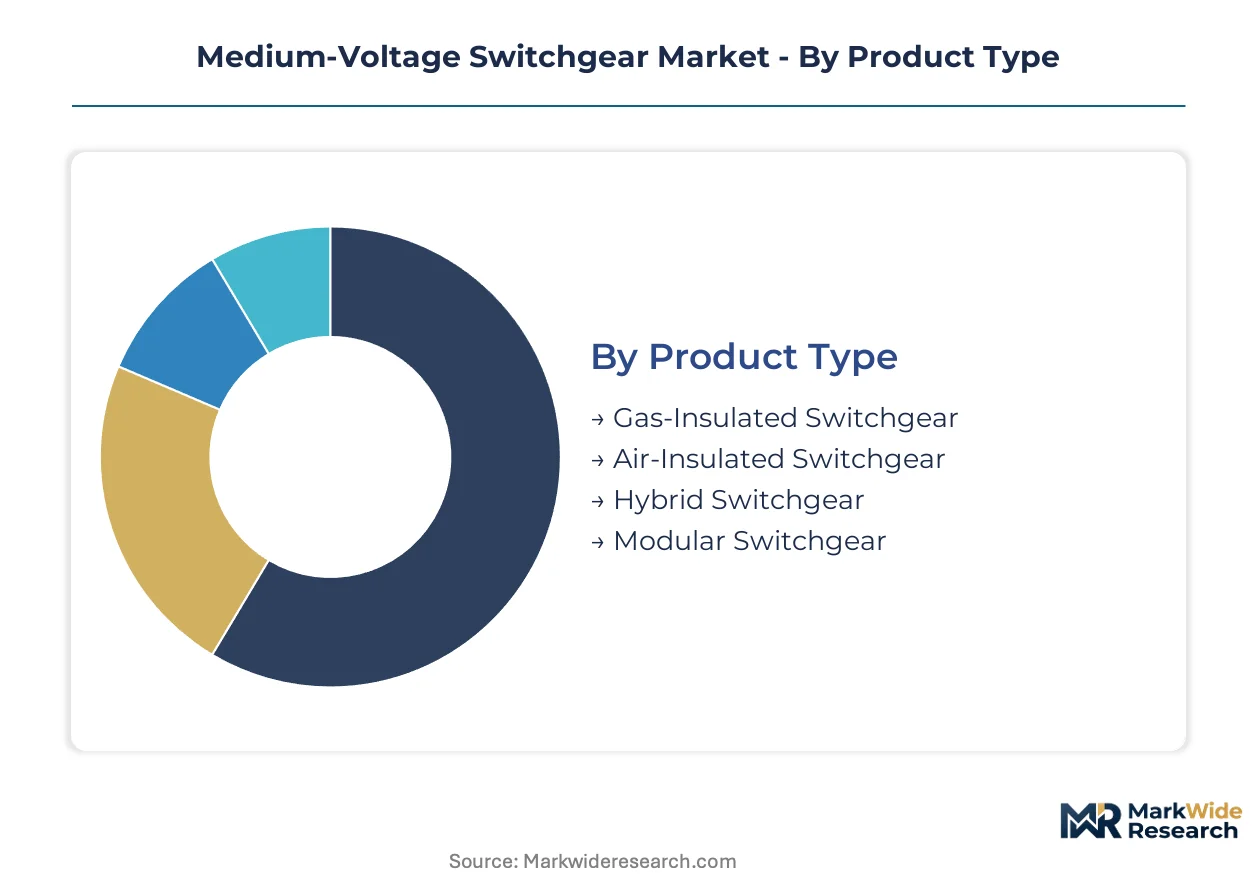
Segmentation in medium-voltage switchgear determines service contract attach rates and lifecycle revenue capture. Procurement patterns diverge sharply between utility buyers seeking decades-long maintenance partnerships and industrial purchasers prioritizing upfront capital efficiency.
Product Type:
After-sales-service intensity varies dramatically across insulation technologies, with gas-insulated systems generating three to five times the service revenue density of air-insulated alternatives over operational lifespans.
- Gas-Insulated Switchgear:Sealed SF6 or fluoronitrile insulation enables compact footprint deployment in urban substations where land scarcity drives specification. German and Dutch utilities specify vacuum-based variants for coastal density projects, creating specialized service protocols around leakage monitoring mandated by EU F-Gas Regulation.
- Air-Insulated Switchgear:Open-air busbar assemblies with porcelain or composite insulators dominate rural electrification programs where capital constraints outweigh footprint concerns. India's Central Electricity Authority procures these assemblies for village-level grid extensions, with lower service intensity but higher replacement frequency due to environmental exposure.
- Hybrid Switchgear:Combines gas-insulated compactness for high-current paths with air-insulated sections for cost-sensitive portions.
- Modular Switchgear:Factory-assembled skid-mounted units reduce field commissioning time for rapid deployment scenarios.
Gas-Insulated Switchgear holds the largest share; momentum sits with Hybrid configurations bridging cost and density requirements.
End User:
Customer type determines specification complexity, with utility procurement departments unbundling equipment supply from installation and commissioning services.
- Utilities:Grid operators specify arc-flash containment ratings per IEC 62271-200 revisions and demand digital protection integration. European distribution cooperatives now separate primary equipment tendering from civil works contracts, fragmenting vendor relationships.
- Renewable Energy:Wind and solar farm developers require switchgear managing bi-directional power flows and variable frequency infeed. This segment climbs the fastest as interconnection standards harden across Germany, Spain, and emerging Southeast Asian markets.
- Industrial:Manufacturing facilities prioritize short-circuit withstand ratings and motor protection coordination.
- Commercial:Data centers and large building complexes specify compact indoor installations with limited maintenance access.
Utilities command the dominant procurement volume; Renewable Energy gains share fastest on capacity addition timelines.
Installation Type:
Physical deployment mode shapes civil works cost allocation and vendor qualification requirements across project types.
- Indoor:Climate-controlled switchgear halls in urban substations enable sealed gas-insulated designs with minimal environmental degradation. German municipal utilities favor these for density-constrained rebuilds.
- Outdoor:Exposed installations in rural India and Southeast Asia demand corrosion-resistant enclosures and elevated maintenance schedules.
- Stationary:Fixed-position assemblies constitute the baseline for permanent substation infrastructure.
- Mobile:Trailer-mounted units serve emergency restoration and temporary construction power needs.
Indoor configurations dominate revenue; Mobile installations see steepest expansion trajectory on grid resilience investment.
Technology:
Protection platform architecture determines interoperability scope and predictive maintenance service potential.
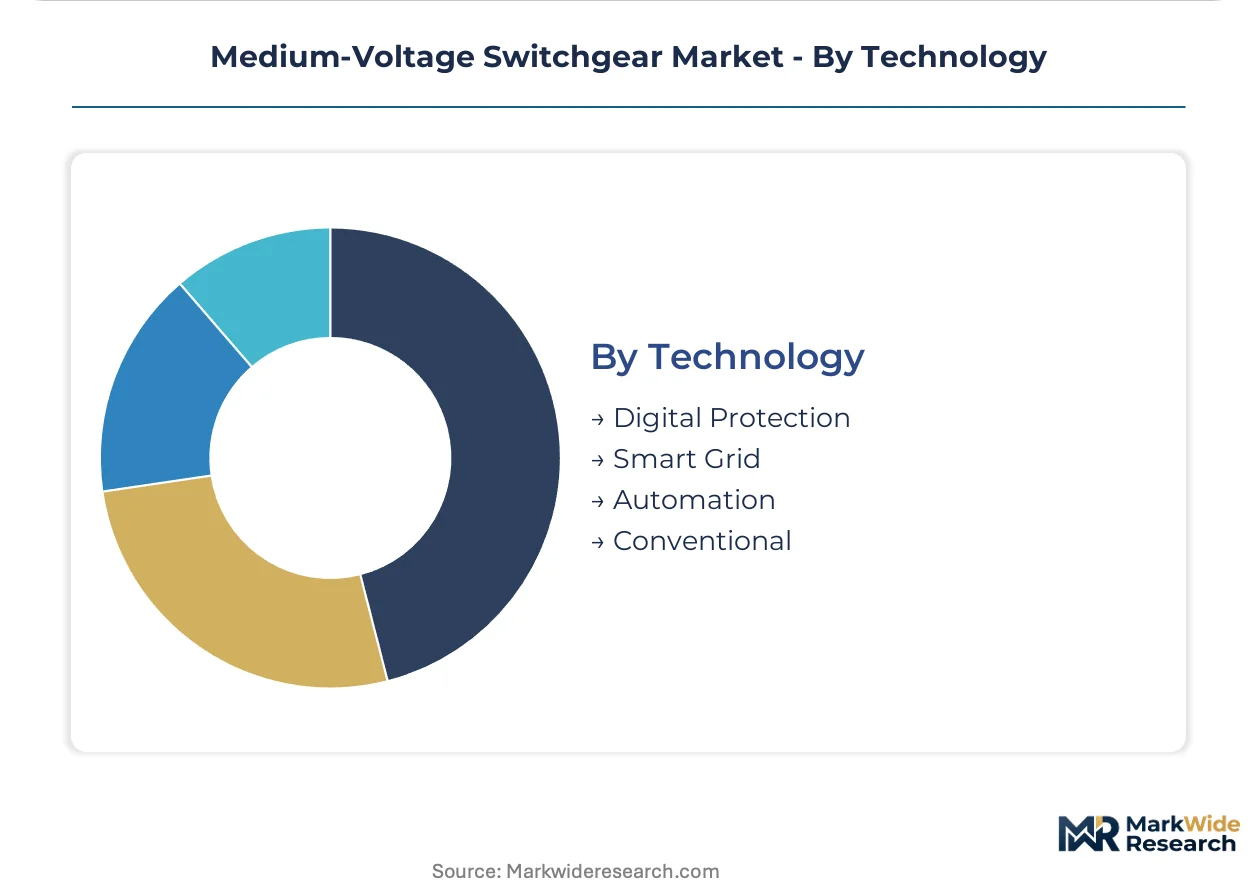
- Digital Protection:Microprocessor-based relays with IEC 61850 communication enable SCADA integration and digital twin deployment. Siemens sustains R&D intensity here, anchoring smart grid architecture penetration.
- Smart Grid:Bi-directional communication and automated reconfiguration capabilities support distributed energy resource integration.
- Automation:Programmable logic controllers and remote terminal units reduce manual switching operations.
- Conventional:Electromechanical relays persist in legacy installations where protocol translation skills are scarce.
Digital Protection captures the largest installed base; Smart Grid technology expands most quickly on utility modernization budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility buyers in India and Southeast Asia exhibit acute price sensitivity toward air-insulated assemblies, while German and Dutch grid operators prioritize sealed gas-insulated specifications regardless of premium positioning. This demand-elasticity contrast shapes regional procurement patterns and vendor qualification frameworks.
India
Rural electrification mandates and village-level grid extensions drive substantial procurement volumes for air-insulated switchgear. The Central Electricity Authority enforces BIS certification requirements that create compliance barriers for non-domestic suppliers. Maharashtra and Gujarat host concentrated manufacturing clusters where domestic fabricators scale production for national grid deployment.
Germany
Municipal utility rebuilds and urban substation density requirements sustain premium demand for vacuum-based gas-insulated systems. The EU F-Gas Regulation imposes mandatory SF6 leakage monitoring and accelerates alternative insulation migration timelines. The Ruhr industrial corridor and Bavarian cities anchor specialized engineering capabilities for arc-flash containment design.
China
State Grid Corporation expansion programs and coastal urbanization sustain procurement of compact indoor installations. National dual carbon goals pressure manufacturers toward SF6-free technology transitions ahead of patent maturation. The Yangtze River Delta concentration around Shanghai hosts integrated supply chains for vacuum interrupter components.
United States
Data center load growth and renewable interconnection standards stimulate demand for digital protection integration. FERC Order 2222 and state-level grid modernization mandates accelerate utility asset replacement cycles. Texas and California utilities lead procurement volumes for bi-directional power flow management hardware.
Vietnam
State utility EVN grid buildout programs and coastal substation development favor gas-insulated specifications for space-constrained installations. National power development plans prioritize transmission infrastructure investment through foreign contractor partnerships. The Ho Chi Minh City metropolitan area concentrates demand for urban distribution network upgrades.
Medium-Voltage Switchgear Market Key Industry Players
Capability concentration sits with engineering-intensive specialists; scale advantage sits with diversified electrical conglomerates. The market exhibits tiered structure with premium-tier players commanding service contract attach rates three to five times above commodity-tier competitors. Strategic archetypes include integrated automation-platform vendors, regional installation-service bundlers, and SF6-alternative technology specialists. Dominant competitive moves encompass digital protection platform acquisitions and geographic expansion through local certification partnerships.
Among diversified industrial conglomerates, ABB and Siemens exemplify the integrated automation-platform archetype, anchoring competitive positioning through smart grid architecture penetration. Schneider Electric represents the geographic bundler archetype, with its S.A. structure signaling French-origin multinational scope. These three entities occupy positions that determine interoperability standards and utility procurement qualification frameworks across European and Asian markets.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Siemens |
| Eaton |
| General Electric |
| Mitsubishi Electric |
| CG Power and Industrial Solutions |
| Bharat Heavy Electricals |
| HD Hyundai Electric |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese vacuum interrupter foundries compresses component pricing while tightening margin capture for European gas-insulated assembly integrators, forcing procurement departments toward long-term offtake contracts that lock input costs against raw material volatility.
Pricing Analysis
Project-based tendering dominates utility procurement, with three-tier pricing structure across premium, standard, and economy levels reflecting IEC 62271-200 arc-flash certification grade and digital protection integration depth. Price differentiation stems from SF6-alternative insulation chemistry and bundled lifecycle service intensity. Cost compression in air-insulated rural electrification assemblies intensifies because Indian BIS certification creates compliance barriers that fragment vendor pools. Industrial buyers in manufacturing segments exhibit acute price sensitivity compared to German municipal utilities prioritizing sealed-system reliability premiums.
Supply Chain Analysis
Contract manufacturing concentration rests with vacuum interrupter specialists in China, South Korea, and Germany holding capacity for medium-voltage component fabrication. Raw material dependencies center on copper busbar stock, aluminum castings, and fluoronitrile gas chemistry. Single-source vulnerability concentrates in SF6-alternative insulation supply where patent-protected formulations tether procurement to licensed producers. Distribution runs through EPC contractor networks and direct utility tendering channels with regional service bundlers anchoring aftermarket revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through European distribution cooperative consolidation, with unbundled procurement frameworks fragmenting vendor relationships and compressing equipment margins toward service-contract economics.
For Market Incumbents: Insulate margin structures through backward integration into vacuum interrupter production and captive fluoronitrile gas recovery infrastructure. Prioritize certification investment in India's BIS testing protocols to defend position against domestic fabricators capturing rural electrification volumes. Channel control through digital protection platform standardization anchors smart grid architecture penetration against emerging automation-platform competitors. For New Entrants and Emerging Players: Establish a beachhead in Vietnamese coastal substation buildouts where EVN grid expansion favors foreign contractor partnerships over established European vendors. Target mobile switchgear emergency restoration segments where procurement qualification barriers sit lower than permanent infrastructure tenders. Pursue joint-venture structures with Indian domestic fabricators to bypass BIS compliance duplication costs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across SF6-alternative R&D programs as EU F-Gas Regulation mandates accelerate patent-protected chemistry transitions. Long-term viability favors acquisition targets with installed base density enabling service contract attach rates three to five times above equipment sale economics. Monitor quarterly EU Green Deal funding window allocations as inflection signal for retrofit demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Alternative Technology Migration | Fluoronitrile and vacuum-based insulation chemistries displace sulfur hexafluoride ahead of regulatory bans. |
| Digital Protection Platform Integration | IEC 61850-compliant microprocessor relays enable SCADA convergence and predictive maintenance service contracts. |
| Geographic Certification Partnership | Local BIS testing alliances in India bypass compliance barriers for non-domestic suppliers. |
| Lifecycle Service Contract Expansion | Aftermarket revenue density from gas-insulated systems narrows margin gaps against original equipment sales. |
| Hybrid Switchgear Configuration Development | Combined gas-insulated and air-insulated architectures bridge urban density and rural cost constraints. |
Research Approach
Operator-level perspectives from utility planning officers, EPC contractor procurement leads, switchgear maintenance directors, and aftermarket service heads anchored the qualitative base. Secondary validation drew from IEC 62271 standard documentation, EU F-Gas Regulation compliance filings, Central Electricity Authority procurement circulars, and SEC 10-K disclosures from listed electrical equipment manufacturers. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the analysis window.
Scenario-bracketing framed the quantitative approach across insulation technology type, end-user procurement archetype, installation environment, and regional regulatory cluster dimensions. CAGRs derived from historical shipment trajectories and forward-looking utility capital expenditure commitments. Forecast inputs incorporated SF6-phase-out timeline assumptions and smart grid modernization budget allocations without year-specific anchoring.
Sensitivities concentrate around EU F-Gas Regulation enforcement pace, Indian BIS certification protocol revisions, and raw material copper price volatility. Forecasts reflect documented assumptions subject to revision from regulatory acceleration or supply chain disruption. Quarterly review of utility tender award volumes and alternative insulation patent expiration schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Indoor LBS Market
Others
Subtilisin Market
Others
Global Molded Plastics Market
Others
Global Computer Peripherals Market
Others
Post Consumer Recycled Bottles Market
Others
Connected Living Room Market
Others
Asia-Pacific Road Safety Market
Others
ISO Cylinder Market
Others
Global Sports and Fitness Wears Market
Others
Middle East and Africa Surface Analysis Market
Others
Industrial Gauges Market
Others
Remanufacturing-as-a-Service (RaaS) Market
Others
Aerospace and Defense Fiber Optic Cables Market
Others
LAMEA Astrology Market
Others
Global Duty-Free Retailing Market
Others
Lepidolite Market