
 CAR T Cell Therapy Market | 2026-2036
CAR T Cell Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
CAR T Cell Therapy Market Intelligence
The capability gap in scalable, in-house manufacturing versus outsourced production is bifurcating the competitive landscape. Integrated pharmaceutical giants like Novartis leverage substantial internal cell processing and logistics infrastructure to control their supply chain. Bristol-Myers Squibb similarly sustains its market position through significant investment in manufacturing capacity. In contrast, many emerging biotechs and smaller research firms depend on contract development and manufacturing organizations such as Lonza for production expertise and capacity.
CAR T cell therapy is a form of immunotherapy that genetically engineers a patient's T cells to fight cancer. The process involves extracting T cells, modifying them in a lab using viral vectors like lentiviruses to express Chimeric Antigen Receptors (CARs), and re-infusing them into the patient to target and destroy malignant cells. Autologous products, derived from the patient, currently define the market, but allogeneic or "off-the-shelf" therapies represent a significant area of research. While applications in hematologic cancers are proven, substantial R&D investment is directed toward overcoming the challenges of treating solid tumors.
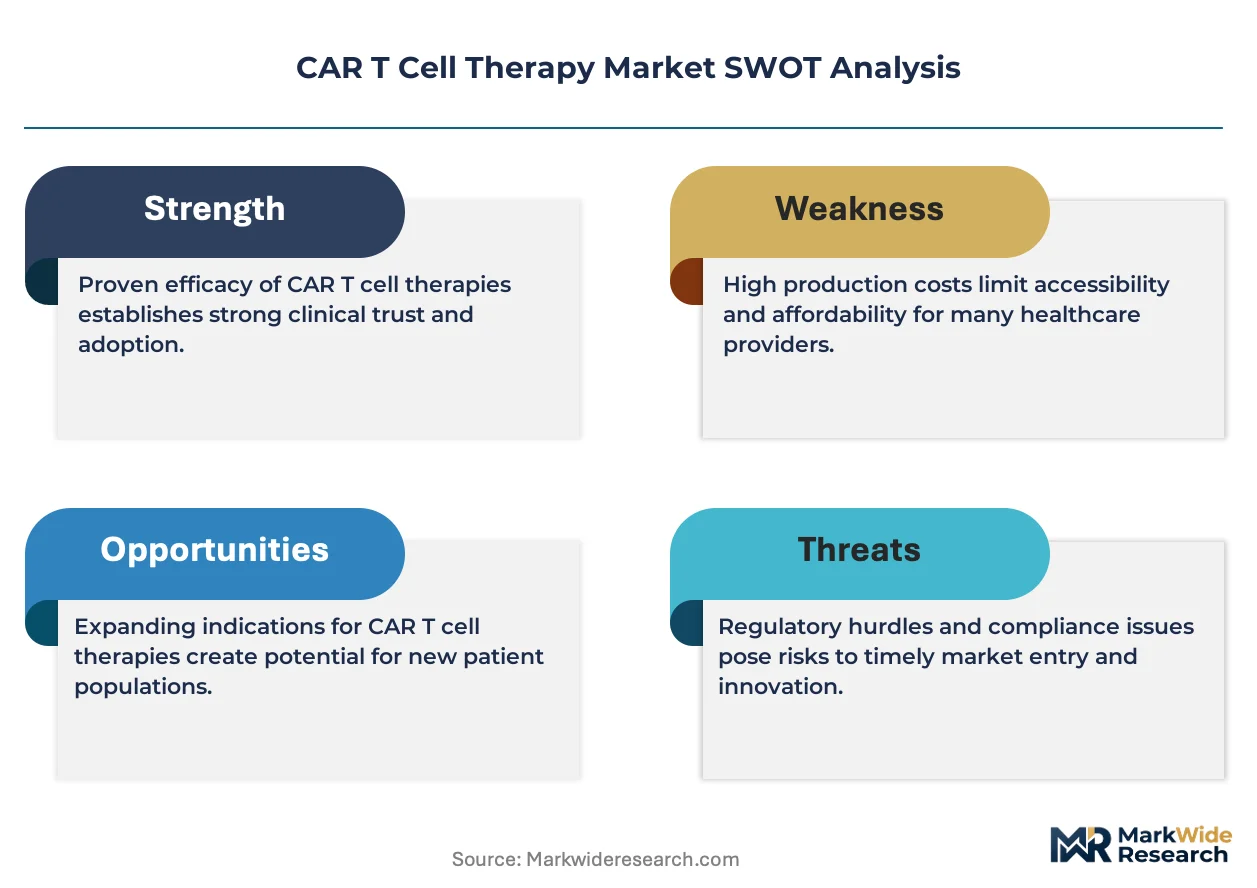
Regulatory oversight from bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA establishes stringent requirements for clinical trials, manufacturing, and patient safety. These frameworks govern the entire lifecycle from preclinical research to post-market surveillance, influencing development costs and timelines. A primary strategic decision for therapy developers involves balancing the pursuit of approvals for new indications with strategies to reduce the high cost of treatment and improve patient access.
Market Dynamics
The central dynamic in the CAR T cell therapy market is the tension between the proven efficacy of complex autologous treatments and the intense R&D pursuit of scalable, allogeneic "off-the-shelf" alternatives, accelerated by gene-editing tools like CRISPR.
Growth Catalysts
- Expanding Clinical Indications:The approval of CAR T therapies for additional hematologic malignancies, such as different types of lymphoma and leukemia, and their investigation for earlier lines of treatment, expands the addressable patient population.
- Regulatory Acceleration:Frameworks like the US FDA's Regenerative Medicine Advanced Therapy (RMAT) designation and the EMA's PRIME scheme provide expedited development and review pathways, incentivizing investment into novel cell therapies.
- Gene-Editing Advancement:The increasing sophistication of CRISPR-Cas9 and other gene-editing technologies enables the development of next-generation CAR T cells with enhanced safety profiles, persistence, and tumor-targeting capabilities.
Market Restraints
- Prohibitive Cost Structure:The high price of CAR T therapies, coupled with ancillary costs for hospitalization and side-effect management, creates significant reimbursement hurdles and restricts patient access globally.
- Manufacturing Complexity:Autologous therapy production involves a patient-specific, logistically intensive vein-to-vein process that is difficult to scale and presents a major bottleneck limiting treatment capacity. -
- Severe Side Effects:The risk of severe and potentially fatal toxicities, including Cytokine Release Syndrome (CRS) and neurotoxicity, necessitates administration in specialized centers with intensive care capabilities, limiting broader clinical use.
Strategic Opportunities
- Solid Tumor Applications:Overcoming the challenges of treating solid tumors, such as the immunosuppressive tumor microenvironment, represents the largest frontier for market expansion and a major focus of current R&D.
- Allogeneic Therapies:Developing "off-the-shelf" CAR T cells from healthy donor sources promises to dramatically reduce manufacturing time and cost, democratizing access and enabling treatment on demand.
- Geographic Expansion:There is significant opportunity in establishing qualified treatment centers and securing reimbursement in markets outside the US and China, particularly in Europe and Japan, to serve unmet clinical needs.
Industry Challenges
- Viral Vector Supply:A persistent bottleneck in the supply of clinical-grade lentiviral and retroviral vectors, which are essential for manufacturing most approved therapies, constrains production capacity across the industry.
- Specialized Talent Scarcity:A shortage of technicians and scientists with expertise in cell therapy manufacturing, quality control, and clinical administration impedes the ability of treatment centers and manufacturers to scale operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CAR T Cell Therapy Market |
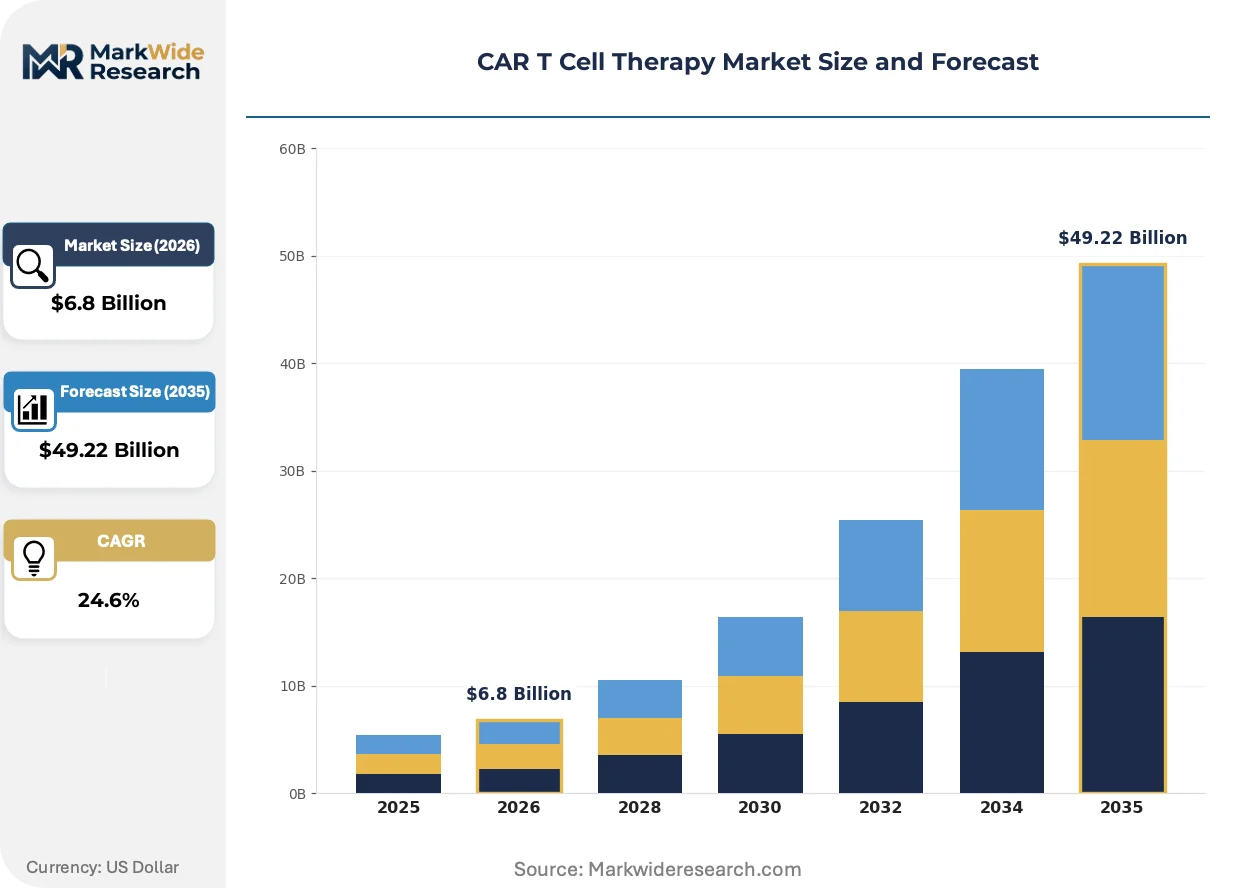
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $49.22 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autologous, Allogeneic, Gene-Edited, Bi-specific End User: Hospitals, Research Institutes, Cancer Clinics, Academic Medical Centers Application: B-cell Malignancies, Solid Tumors, Hematologic Cancers, Usage in Pediatric Patients Technology: CRISPR, Lentiviral Vectors, Viral Transduction, Electroporation |
| Companies Covered | Novartis, Bristol-Myers Squibb Company, Johnson & Johnson Services, Inc., Gilead Sciences, Inc., ALLOGENE THERAPEUTICS, Lonza, Cartesian Therapeutics, Inc., JW Therapeutics, Autolus Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CAR T Cell Therapy Market Strategic Shifts & Innovations
Innovation in the CAR T cell therapy sector is reshaping the therapeutic landscape, with a primary focus on improving manufacturing scalability, enhancing safety profiles, and extending efficacy to solid tumors. These efforts are geared toward overcoming the core limitations of first-generation products.
Non-viral gene delivery systems, including transposon-based methods and electroporation, provide an alternative to viral vectors for engineering T cells. Research institutions and emerging biotechnology firms are actively developing these platforms to simplify production and lower costs. This technological divergence is bifurcating the development pipeline between incumbent viral-based manufacturing and next-generation non-viral platforms that may offer greater scalability.
The European Medicines Agency's PRIority MEdicines (PRIME) scheme offers accelerated assessment and enhanced scientific advice for therapies addressing significant unmet needs. This regulatory pathway de-risks the development of novel CAR T candidates by facilitating early and frequent interaction with regulators. Consequently, therapy developers targeting the European Union are increasingly structuring their clinical programs to meet PRIME eligibility criteria from the outset.
A gradual decentralization of care delivery is underway, expanding beyond a few elite academic hospitals to a broader network of qualified cancer treatment centers. This model requires rigorous certification and training to ensure sites can safely manage the complexities of CAR T cell administration and patient monitoring. The trend is most advanced in the United States, where provider networks are forming to improve geographic access for eligible patients.
CAR T Cell Therapy Market Segmentation
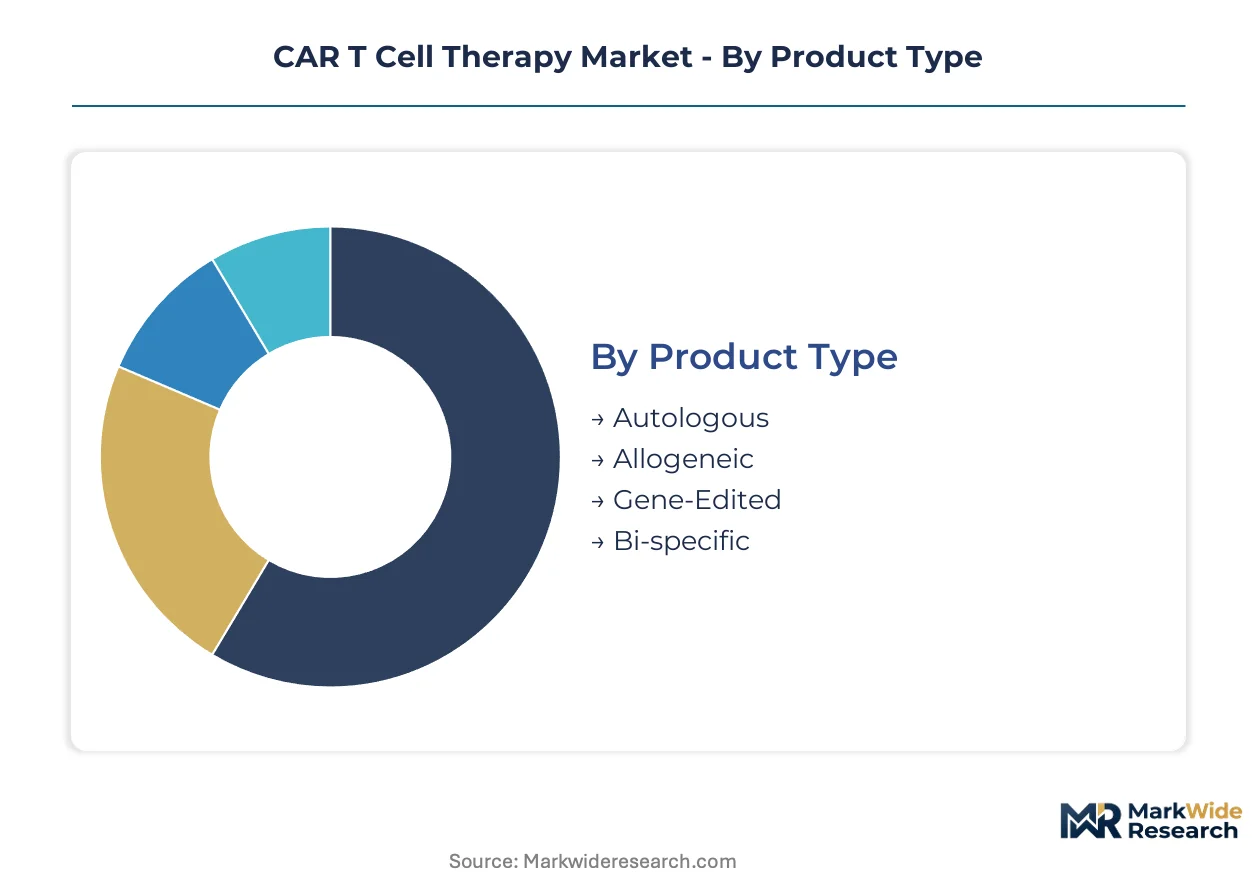
The CAR T cell therapy market segmentation highlights the diverse approaches to treatment development and delivery. Understanding these distinct segments provides clarity on where innovation is concentrating and how different therapeutic strategies address specific patient needs. This structural breakdown reveals the varying commercial pathways for advanced cell therapies.
Product Type:
Regulatory bodies like the US FDA and European Medicines Agency (EMA) differentiate CAR T cell products based on their manufacturing origin and genetic modification methods.
- Autologous:Autologous CAR T cells are derived from the patient's own T cells, which are then genetically modified and re-infused. Demand for these personalized therapies is concentrating within specialized cancer clinics in the United States, driven by their proven efficacy in specific hematologic cancers.
- Allogeneic:Allogeneic CAR T cell therapies are "off-the-shelf" products sourced from healthy donors, offering greater scalability and reduced manufacturing timelines. Research and development investment is significant in China, aiming to overcome immunological rejection and expand patient access.
- Gene-Edited:Gene-Edited products utilize advanced gene-editing tools like CRISPR to enhance T cell function or remove unwanted genes, improving safety and targeting.
- Bi-specific:Bi-specific CAR T cells are engineered to target two different antigens simultaneously, aiming to improve efficacy and prevent tumor escape mechanisms.
Established volume favors Autologous products; emerging adoption favors Allogeneic therapies.
End User:
The operational requirements and patient care models dictate distinct end-user environments for CAR T cell therapy administration.
- Hospitals:Hospitals provide comprehensive care settings, including intensive care units necessary for managing potential severe side effects of CAR T cell therapy. Treatment administration is expanding in major urban hospitals across Europe, driven by increasing regulatory approvals and physician training.
- Cancer Clinics:Specialized cancer clinics focus exclusively on oncology care, offering dedicated infrastructure and expert staff for complex cell therapy protocols. These clinics in the United States concentrate on efficient patient workflow and specialized post-treatment monitoring.
- Research Institutes:Research Institutes primarily conduct preclinical and early-phase clinical trials, contributing to the foundational science and novel CAR T cell development.
- Academic Medical Centers:Academic Medical Centers combine patient care with extensive research programs, often pioneering new CAR T applications and training future specialists.
The delivery infrastructure for CAR T therapies is evolving from centralized academic hubs to a broader network of specialized treatment facilities.
Application:
The therapeutic applications of CAR T cell therapies are expanding, targeting specific cancer types and patient populations.
- Hematologic Cancers:Hematologic cancers, including various lymphomas and leukemias, represent the most established and clinically proven applications for CAR T cell therapies. Demand is concentrated in regions with high incidence rates and advanced healthcare infrastructure, such as Japan, where treatment options are expanding.
- Solid Tumors:Solid tumors present significant biological challenges for CAR T cell efficacy, but overcoming these barriers represents the largest opportunity for market expansion. Substantial R&D investment is directed towards novel strategies to address the immunosuppressive tumor microenvironment in countries like Germany.
- B-cell Malignancies:B-cell Malignancies, a subset of hematologic cancers, were among the first indications for approved CAR T cell products due to their well-defined antigen targets.
- Usage in Pediatric Patients:Usage in Pediatric Patients addresses specific forms of childhood leukemia and lymphoma, requiring specialized protocols and care due to the unique physiological characteristics of young patients.
While hematologic cancers define current market activity, solid tumor applications are climbing the fastest in research and development.
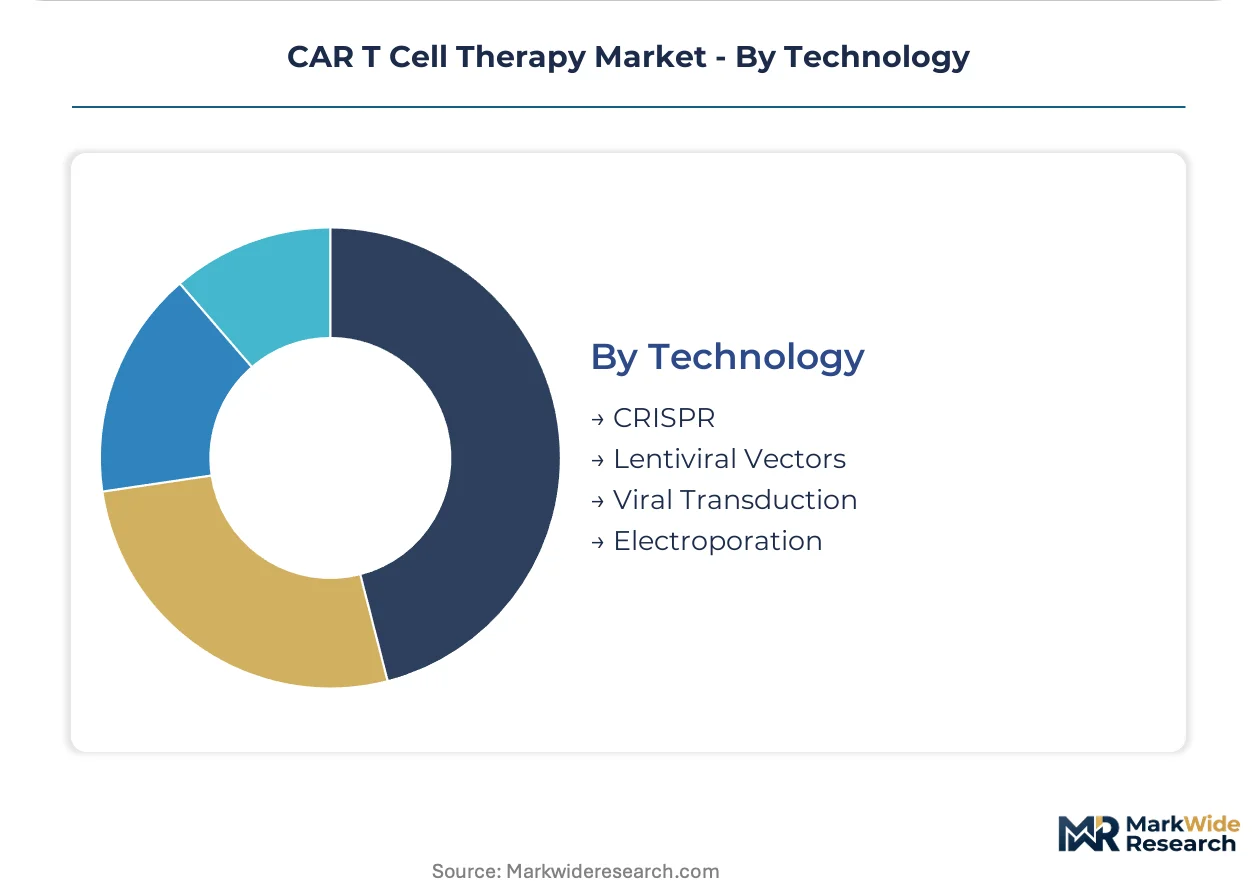
Technology:
The underlying technological platforms for CAR T cell engineering are diverse, influencing manufacturing scalability and therapeutic characteristics.
- Lentiviral Vectors:Lentiviral Vectors are widely used for stable genetic modification of T cells due to their efficient gene delivery capabilities into non-dividing cells. Their application is prevalent in commercial CAR T products manufactured by large pharmaceutical companies in the United States.
- CRISPR:CRISPR-Cas9 technology offers precise gene-editing capabilities, enabling the development of next-generation CAR T cells with enhanced safety profiles and tumor-targeting. Significant research is underway in academic centers and biotechs in China to optimize its use for allogeneic therapies.
- Viral Transduction:Viral Transduction encompasses methods using viral vectors like lentiviruses and retroviruses to introduce CAR genes into T cells, forming the backbone of many approved therapies.
- Electroporation:Electroporation is a non-viral gene delivery method that uses electrical pulses to create temporary pores in cell membranes, facilitating CAR gene insertion.
Viral vector technologies currently dominate production, but non-viral gene editing methods like CRISPR are gaining significant traction for future development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The CAR T cell therapy market exhibits a differential consumption mix across major global economies. While the United States and China lead in both development and adoption, Europe is rapidly expanding its treatment footprint. Japan focuses on specific hematologic indications, leveraging advanced healthcare infrastructure for patient access.
United States
Demand for autologous CAR T cell therapies in the United States is driven by established reimbursement pathways and a high incidence of hematologic cancers. The US FDA's Regenerative Medicine Advanced Therapy (RMAT) designation accelerates novel therapy development. Specialized cancer clinics in major metropolitan areas like Boston and Houston concentrate on efficient patient workflow and complex administration protocols.
China
China demonstrates significant research and development investment into allogeneic "off-the-shelf" CAR T cell therapies, aiming for greater scalability. The NMPA establishes stringent requirements for clinical trials and manufacturing, influencing product development. Academic centers and biotechs in Shanghai and Beijing are optimizing CRISPR technology for next-generation therapies.
Germany
Expanding clinical indications for CAR T cell therapies and their investigation for solid tumors drive market expansion in Germany. The EMA's PRIME scheme provides expedited review pathways, incentivizing investment into novel cell therapies. Major urban hospitals in cities such as Munich and Berlin are expanding their capabilities to manage complex CAR T cell administration.
Japan
Hematologic cancers represent the most established applications for CAR T cell therapies in Japan, with demand concentrated in regions with advanced healthcare infrastructure. PMDA regulations govern the entire lifecycle from preclinical research to post-market surveillance. Treatment options are expanding in major medical centers across Tokyo and Osaka, serving unmet clinical needs.
CAR T Cell Therapy Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the CAR T cell therapy market structure. This tiered landscape includes large pharmaceutical companies, specialized biotechnology firms, and contract development and manufacturing organizations. Strategic archetypes encompass integrated manufacturers, innovative biotechs, and essential service providers. Dominant competitive moves include significant investment in manufacturing capacity and the pursuit of regulatory approvals for new indications.
Within the integrated pharmaceutical archetype, Novartis and Bristol-Myers Squibb Company leverage substantial internal cell processing and logistics infrastructure to control their supply chains. These entities sustain market positions through significant investment in manufacturing capacity for their approved autologous products. Lonza occupies a position as a critical contract development and manufacturing organization, providing essential production expertise and capacity to emerging biotechs and smaller research firms globally.
| Leading Market Players |
|---|
| Novartis |
| Bristol-Myers Squibb Company |
| Johnson & Johnson Services, Inc. |
| Gilead Sciences, Inc. |
| ALLOGENE THERAPEUTICS |
| Lonza |
| Cartesian Therapeutics, Inc. |
| JW Therapeutics |
| Autolus Therapeutics |
| Others |
Cost & Logistics Intelligence
Capacity reservation agreements for manufacturing slots and critical raw materials lock in both supply access and price visibility for advanced cell therapies. This structure is essential given the complex, patient-specific nature of autologous CAR T cell production and the specialized inputs required for allogeneic development.
Pricing Analysis
After-sales service and long-term patient monitoring drive significant lifetime value for CAR T cell therapies. The pricing model primarily operates on a value-based structure, often tied to clinical outcomes and regulatory approval status in specific indications. Price differentiation stems from the customization level required for autologous products versus the scalability of "off-the-shelf" allogeneic therapies, and geographic market access. Pricing pressure stems from reimbursement hurdles and payer scrutiny across major healthcare systems. Healthcare systems are most price-sensitive, while early-phase research institutes demonstrate less price sensitivity.
Supply Chain Analysis
The United States and China anchor the production of viral vectors and the manufacturing of advanced cell therapies. The market's raw material dependencies center on clinical-grade lentiviral vectors and specialized cell culture media. A persistent supply chain risk is the single-source vulnerability for specific viral vector types, constraining production capacity across the industry. Distribution runs through a specialized direct-to-hospital/clinic model, requiring stringent cold chain logistics for cryopreserved patient samples and final products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the demand-side shift towards overcoming challenges in solid tumor applications and expanding into new patient populations.
For Market Incumbents: Shield existing market share by expanding approved indications for autologous therapies into earlier lines of treatment. Invest in enhancing in-house manufacturing capacity, particularly for viral vectors, to mitigate supply chain threats from specialized input scarcity. Focus R&D on improving the safety profile and persistence of current products to counter emerging allogeneic competition.
For New Entrants and Emerging Players: The US FDA's Regenerative Medicine Advanced Therapy (RMAT) designation provides a certification fast-track for novel CAR T candidates. Target underpenetrated solid tumor applications or develop scalable allogeneic "off-the-shelf" platforms utilizing non-viral gene delivery methods. A key go-to-market angle involves strategic partnerships with academic medical centers for early-phase clinical trials and data generation.
For Investors and Strategic Acquirers: Capital is best deployed toward innovative biotechs developing allogeneic CAR T cell platforms or novel gene-editing technologies. The long-term viability of the CAR T cell market extends beyond the next decade, driven by continuous innovation and expanding indications. Identify acquisition targets with robust intellectual property in non-viral gene delivery. A signal to watch is successful Phase 2/3 clinical trial readouts for solid tumor applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Ensures consistent supply for autologous therapies and prepares for allogeneic demand. |
| Regulatory Approval Pathway | Expedites market access for novel CAR T cell candidates in Europe and the US. |
| Pipeline Diversification | Addresses unmet needs in solid tumors and expands therapeutic reach beyond hematologic cancers. |
| Licensing Agreement | Accelerates development of allogeneic platforms by sharing intellectual property and expertise. |
| Clinical Trial Advancement | Demonstrates efficacy and safety for new indications, supporting broader patient access. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary validation from regulatory filings anchors the qualitative findings. This approach integrates insights from R&D directors, regulatory affairs specialists, hospital procurement managers, and cell therapy clinicians. Secondary data sources include FDA filings, EMA submissions, ClinicalTrials.gov, and company annual reports, triangulated through both bottom-up and top-down analyses.
The analytical framework incorporates sensitivity analysis for key variables across the analysis window, modeling segmentation dimensions such as product type, end user, application, technology, and regional regulatory clusters. Compound Annual Growth Rates are derived from historical trends and projected market dynamics. Key forecast inputs include clinical trial success rates and evolving reimbursement policies.
Underlying assumptions cover regulatory shifts, technological breakthroughs, and changes in healthcare funding, with deviation risk concentrated in unexpected clinical trial failures or major supply chain disruptions. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Video-As-A-Service (Vaas) Market
Others
Versatile Video Coding Market
Others
Vegan Confectionery Market
Others
Server Market
Others
South Asia Geosynthetics Market
Others
Underwater Lighting Market
Others
Smart Home Gateways Market
Others
AC Switchgear Market
Others
Inflight Entertainment Solutions Market
Others
Global Recruitment and Staffing Market
Others
Insoluble Sulfur Market
Others
Couscous Market
Others
Latin America IT Device Market
Others
Port Replicator Market
Others
Enterprise Video Market
Others
Vacuum Evaporators Market