
 Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market | 2026-2036
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market Foresight
Brazil is reconfiguring regional supply dynamics through expanded fill-finish capacity for biologic injectables. Novo Nordisk anchors Latin American operations with dedicated cold-chain infrastructure across São Paulo and Rio de Janeiro distribution nodes. Eli Lilly and Company competes through intensified R&D spending on next-generation oral peptide formulations. Sanofi leverages established insulin manufacturing footprints to extend into GLP-1 analog production for regional markets.
Glucagon-Like Peptide-1 (GLP-1) Agonists constitute a class of incretin-mimetic biologic drugs that activate GLP-1 receptors to stimulate glucose-dependent insulin secretion, with peptide sequences typically delivered via subcutaneous injection or emerging oral permeation technologies. These agents primarily serve type 2 diabetes management and expanding obesity therapeutics by slowing gastric emptying and suppressing appetite. Injectable formulations dominate current prescription volumes due to established bioavailability profiles and clinician familiarity, while oral segments attract development investment aimed at patient adherence improvement. Weight management applications outpace traditional diabetes indications in growth velocity across Latin American markets. Hospital pharmacies retain the largest margin pool through specialty dispensing requirements, though online pharmacies gain share in recurring prescription fulfillment.
ANVISA in Brazil and COFEPRIS in Mexico enforce bioequivalence and GMP certification requirements that shape product registration timelines and market access conditions for imported biologics. The national pharmaceutical regulators across Argentina and Chile adopt ICH harmonized guidelines that streamline multi-country filing strategies for sponsors. Stakeholders must monitor evolving pharmacovigilance obligations and local production incentives as determinants of sustainable market participation.
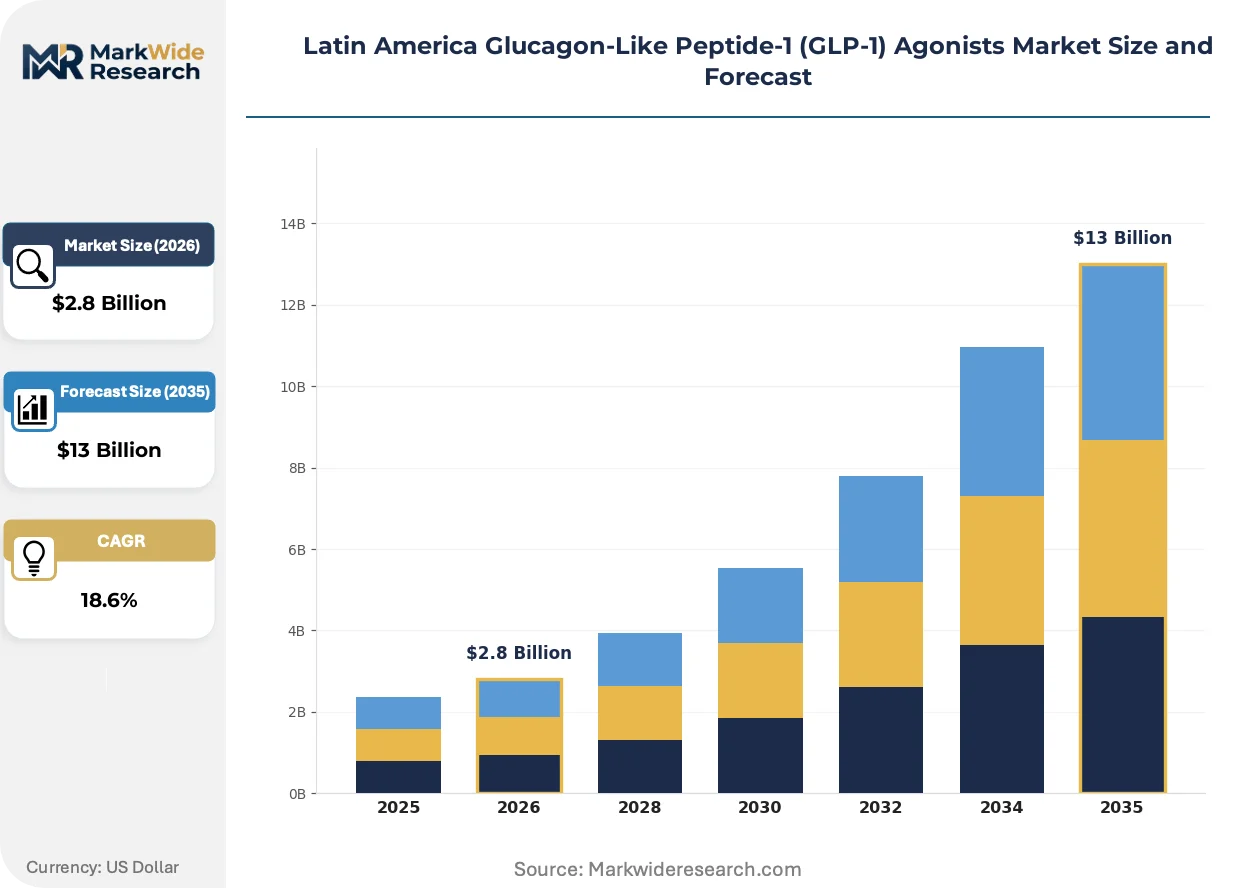
Market Dynamics
ANVISA's tightened bioequivalence standards for biologic injectables are restructuring competitive entry barriers across Latin America, favoring sponsors with dedicated fill-finish infrastructure over pure import-reliant models.
Growth Catalysts
- Homecare weight management demand:Mexico's obesity therapeutics segment pulls GLP-1 prescriptions toward subcutaneous self-administration, expanding addressable patient populations beyond hospital-centric diabetes care.
- Cold-chain infrastructure expansion:São Paulo and Rio de Janeiro distribution nodes now support temperature-controlled biologic storage, reducing spoilage rates for peptide-based formulations.
- COFEPRIS streamlined pathways:Mexico's national pharmaceutical regulator accelerates review timelines for products with prior FDA or EMA approval, compressing market entry cycles for qualified sponsors.
Market Restraints
- Recombinant peptide input concentration:Active pharmaceutical ingredient supply for GLP-1 analogs concentrates among specialized biologics manufacturers in Asia-Pacific and North America, exposing Latin American formulators to cross-border logistics risk.
- ANVISA GMP certification friction:Brazil's national pharmaceutical regulator mandates on-site inspections for foreign manufacturing facilities, extending registration timelines by twelve to eighteen months for non-local production.
- Oral formulation bioavailability ceiling:Peptide permeation enhancers face absorption variability across patient populations, limiting clinical equivalence claims against established injectable benchmarks.
Strategic Opportunities
- Argentina's underpenetrated diabetes clinics:Provincial healthcare networks outside Buenos Aires maintain limited GLP-1 agonist formularies, creating first-mover advantage for sponsors establishing local medical liaison presence.
- Online pharmacy channel emergence:Recurring prescription fulfillment platforms gain regulatory clearance for temperature-controlled biologic delivery, opening direct-to-patient access for maintenance dosing regimens.
- Chile's ICH harmonization adoption:The national pharmaceutical regulator's alignment with international conference guidelines enables multi-country dossier submissions, reducing per-market registration costs for regional portfolio builds.
Industry Challenges
- Biologics process engineer scarcity:Latin American universities produce limited graduates with recombinant protein purification expertise, forcing sponsors to import technical talent or delay facility commissioning.
- Legacy insulin manufacturing retrofit complexity:Sanofi's established production footprints require cleanroom reconfiguration and chromatography suite upgrades to accommodate GLP-1 peptide chemistry, stretching capital deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral, Combination Therapy, Pre-filled Pen End User: Diabetes Clinics, Hospitals, Homecare Settings, Research Institutions Application: Type 2 Diabetes, Weight Management, Cardiovascular Health, Metabolic Disorders Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Direct Sales |
| Companies Covered | Novo Nordisk, Eli Lilly and Company, AstraZeneca, Sanofi, Novartis, Biocon, Hypera S.A., Pfizer, Takeda Pharmaceutical Company, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market Shifts & Advancements
Oral peptide permeation technologies and regional regulatory harmonization are compressing traditional competitive moats, while patient-administered delivery models redistribute care settings away from hospital pharmacies.
Oral GLP-1 agonist formulations employing small-molecule permeation enhancers are rendering obsolete the assumption that subcutaneous injection represents the only viable bioavailability pathway for peptide therapeutics. Brazilian diabetes clinics are piloting these tablets for treatment-naïve patients, accelerating clinician familiarity with non-injectable options. The structural consequence compresses hospital pharmacy margins by enabling prescription fulfillment through retail and online channels previously excluded from biologic dispensing.
COFEPRIS and ANVISA are converging toward mutual recognition of bioequivalence study protocols, reducing redundant clinical trial requirements for sponsors seeking simultaneous Brazil-Mexico market entry. This regulatory alignment lowers per-market registration costs and accelerates patient access timelines. Weight management applications benefit most, as indication expansions require supplemental efficacy data that previously demanded country-specific replication.
Homecare settings in Mexico are displacing hospital outpatient departments as the primary site for GLP-1 agonist initiation and maintenance. Patients with obesity indications prefer self-administration flexibility over scheduled clinic visits, driving demand for simplified injection devices and telehealth-supported dosing protocols. This behavioral shift concentrates recurring revenue with pharmacy benefit managers and online dispensers rather than institutional purchasers.
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market Segmentation
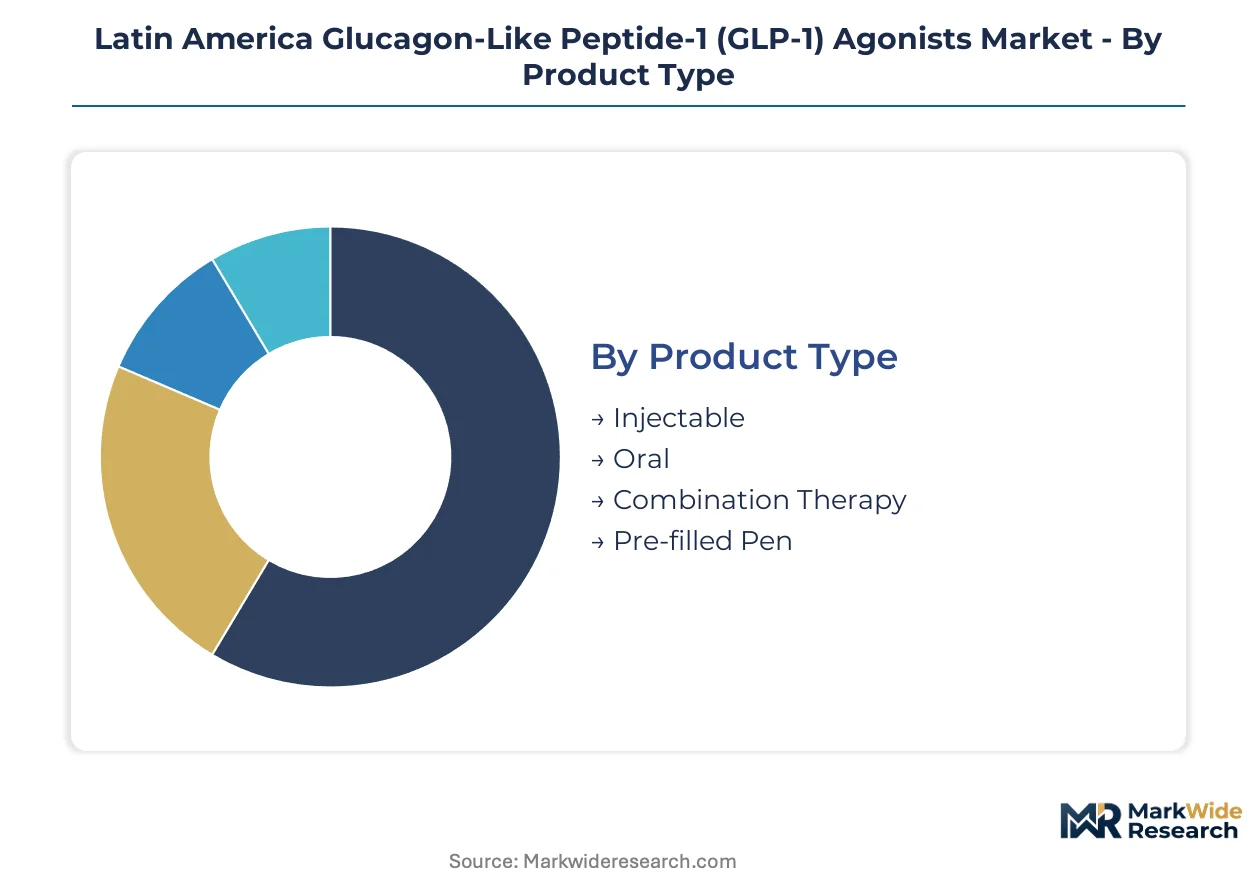
GLP-1 agonist commercialization across Latin America fragments across delivery technologies, care settings, and regulatory pathways. Each segmentation dimension carries distinct margin structures, cold-chain requirements, and prescriber access patterns that determine sponsor resource allocation.
Product Type:
Mature injectable platforms anchor current prescription volumes while emerging oral formulations reshape competitive entry strategies.
- Injectable:Subcutaneous peptide delivery via vial or syringe dominates Brazilian diabetes clinic formularies due to established bioequivalence dossiers and ANVISA's familiarity with parenteral biologic review. São Paulo's cold-chain distribution nodes support temperature-controlled storage, though homecare self-administration in Mexico pulls demand toward simplified device formats.
- Oral:Small-molecule permeation enhancers enable tablet-based GLP-1 receptor activation, bypassing injection barriers for treatment-naïve patients. COFEPRIS accelerated review pathways for oral candidates compress Mexico market entry timelines relative to Brazil's more conservative biologics stance.
- Combination Therapy:Fixed-dose pairings with insulin or SGLT-2 inhibitors target refractory type 2 diabetes populations in Argentine hospital settings.
- Pre-filled Pen:Disposable injection devices with dose-titration features concentrate demand among Mexican homecare users seeking self-administration convenience.
Injectable retains volume leadership; oral holds the steepest expansion curve.
End User:
Cost tier stratification separates institutional purchasers with formulary negotiation power from direct-pay channels with price inelasticity.
- Diabetes Clinics:Specialized outpatient facilities in Brazil's Sistema Único de Saúde network drive GLP-1 agonist adoption through endocrinologist-led protocol standardization. ANVISA's tightened bioequivalence standards favor sponsors with dedicated medical liaison presence in provincial capitals.
- Hospitals:Tertiary care institutions manage acute metabolic complications and initiate therapy for complex comorbid patients. Cold-chain infrastructure investments by Novo Nordisk and Eli Lilly target hospital pharmacy dispensing requirements in Rio de Janeiro and São Paulo metropolitan corridors.
- Homecare Settings:Self-administration models expand addressable populations beyond clinic-dependent diabetes management. Mexican obesity therapeutics demand concentrates here, with patients preferring flexible dosing schedules over scheduled institutional visits.
- Research Institutions:Academic medical centers conduct investigator-initiated trials for cardiovascular outcome studies and novel indication exploration.
Diabetes clinics capture the largest prescription base; homecare settings climb the fastest in patient volume contribution.
Application:
Volume concentration in metabolic disease management contrasts with margin expansion in expanding lifestyle therapeutics.
- Type 2 Diabetes:Established glycemic control indication drives reimbursement eligibility through public health systems. Brazilian national formulary inclusion requires ANVISA registration plus Ministry of Health technology assessment, creating multi-year access timelines.
- Weight Management:Obesity therapeutics command premium pricing outside diabetes-limited reimbursement frameworks. Mexican private insurance coverage expansion and direct-pay pharmacy channels accelerate uptake among middle-class demographics.
- Cardiovascular Health:Post-myocardial infarction risk reduction represents emerging indication territory requiring supplemental clinical evidence.
- Metabolic Disorders:Non-alcoholic steatohepatitis and polycystic ovary syndrome applications remain pre-commercial across Latin American regulatory jurisdictions.
Type 2 diabetes maintains volume leadership; weight management gains share fastest.
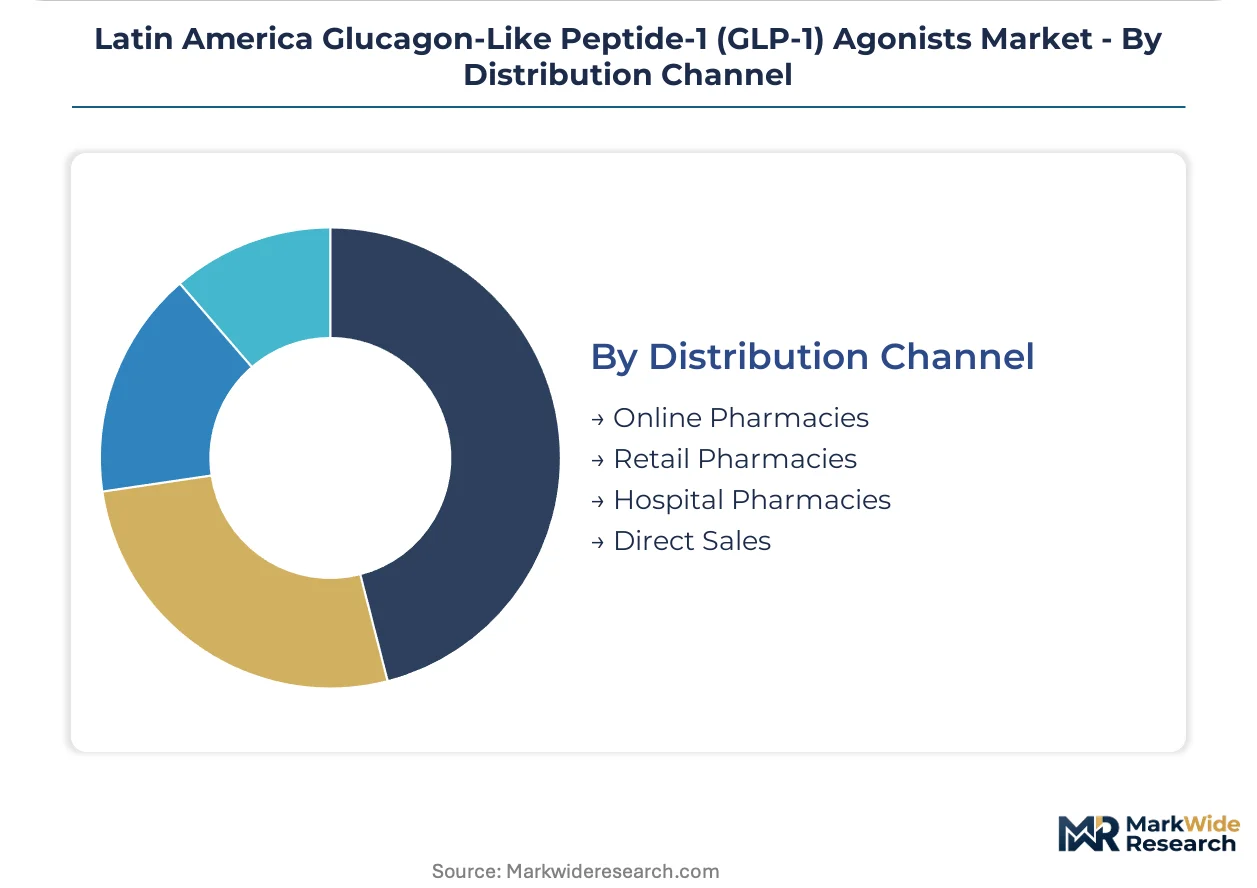
Distribution Channel:
Customer type fragmentation separates recurring maintenance prescriptions from acute dispensing with distinct logistics requirements.
- Online Pharmacies:Temperature-controlled biologic delivery platforms gain regulatory clearance for direct-to-patient fulfillment. COFEPRIS and ANVISA convergence on cold-chain validation standards enables cross-border operational templates for regional pharmacy benefit managers.
- Retail Pharmacies:Community-based dispensing captures maintenance dosing for established patients with stable prescriptions. Brazilian retail networks in São Paulo and Minas Gerais invest in refrigerated storage capacity to compete with hospital pharmacy capture.
- Hospital Pharmacies:Institutional dispensing retains specialty biologic margin pools through controlled distribution and prescriber proximity. ANVISA GMP certification requirements for foreign manufacturing facilities extend procurement lead times, concentrating purchasing power with sponsors possessing local fill-finish infrastructure.
- Direct Sales:Manufacturer-to-institution contracting serves large hospital systems and government procurement tenders.
Hospital pharmacies retain margin leadership; online pharmacies expand most quickly in prescription fulfillment share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
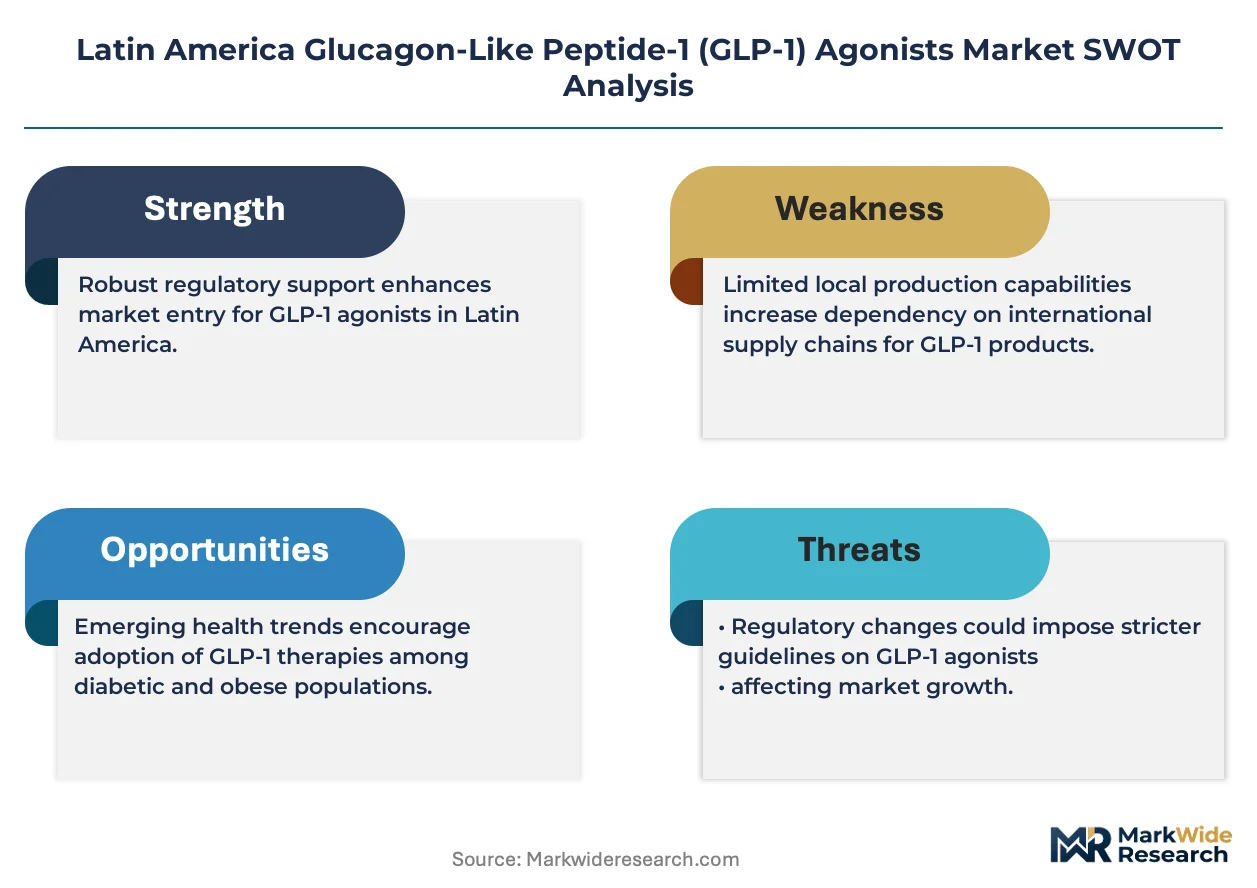
ANVISA anchors Latin American GLP-1 agonist commercialization through tightened bioequivalence standards that favor sponsors with Brazilian fill-finish infrastructure over import-reliant competitors.
Brazil
São Paulo and Rio de Janeiro diabetes clinics drive injectable formulation demand through Sistema Único de Saúde network standardization. ANVISA's on-site GMP inspection mandate for foreign facilities extends registration timelines by twelve to eighteen months. Novo Nordisk's dedicated cold-chain distribution nodes in both metropolitan corridors reduce spoilage rates for temperature-sensitive peptide therapeutics.
Mexico
Homecare settings concentrate obesity therapeutics demand among middle-class demographics seeking flexible self-administration schedules. COFEPRIS accelerates review timelines for products holding prior FDA or EMA approval, compressing market entry cycles. Mexico City Metro and Nuevo León pharmacy networks invest in refrigerated storage capacity to capture recurring prescription fulfillment from hospital outpatient displacement.
Argentina
Provincial healthcare networks outside Buenos Aires maintain limited GLP-1 agonist formularies, creating first-mover opportunity for medical liaison presence. The national pharmaceutical regulator adopts ICH harmonized guidelines that streamline multi-country filing strategies alongside Brazil and Chile. Córdoba and Mendoza diabetes clinics represent underpenetrated prescriber access points for injectable initiation protocols.
Chile
Santiago's tertiary care institutions manage acute metabolic complications and complex comorbid patient initiation. The national pharmaceutical regulator's ICH alignment enables dossier submissions across multiple Latin American jurisdictions simultaneously. Valparaíso and Biobío regions concentrate emerging online pharmacy channel development for temperature-controlled biologic delivery.
Colombia
Bogotá hospital pharmacies retain specialty biologic margin pools through controlled distribution and prescriber proximity. The national pharmaceutical regulator enforces bioequivalence study requirements that shape registration timelines for imported peptide formulations. Medellín and Cali diabetes clinics pilot oral GLP-1 permeation technologies for treatment-naïve patient segments.
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market Competitive Landscape
Capability concentration sits with integrated biologics manufacturers; scale advantage sits with established insulin producers retrofitting existing infrastructure. The market structures around three tiers: multinational peptide specialists with dedicated cold-chain networks, legacy insulin manufacturers extending into GLP-1 analog production, and emerging regional formulators seeking local fill-finish partnerships. Dominant competitive moves include capacity expansion in São Paulo distribution corridors and strategic technology licensing for oral peptide permeation platforms.
Within the integrated biologics tier, Novo Nordisk and Eli Lilly and Company exemplify sponsors with anchored Latin American operations through dedicated regional infrastructure. Sanofi occupies a position among legacy insulin manufacturers leveraging established production footprints for GLP-1 analog extension. AstraZeneca represents the diversified pharmaceutical archetype competing through portfolio breadth rather than vertical peptide manufacturing concentration.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly and Company |
| AstraZeneca |
| Sanofi |
| Novartis |
| Biocon |
| Hypera S.A. |
| Pfizer |
| Takeda Pharmaceutical Company |
| Others |
Supply & Pricing Matrix
São Paulo-Rio de Janeiro freight corridors carry cold-chain biologics at premium rates that compound with API import duties, concentrating margin capture among sponsors with Brazilian fill-finish infrastructure while forcing pure importers toward higher retail price points.
Pricing Analysis
Brazil-Mexico price spreads exceed those within either national market, with São Paulo hospital pharmacies commanding premium positioning against Mexican homecare direct-pay channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by cold-chain certification grade and prescriber access tier. Cost compression in economy-tier injectables is intensifying because Argentine provincial formularies negotiate volume tenders. Homecare obesity patients in Mexico City show least price sensitivity; Brazilian Sistema Único de Saúde procurement committees show most.
Supply Chain Analysis
Tariff exposure between Asia-Pacific API manufacturers and Latin American formulators dominates supply chain risk planning for peptide therapeutics. Active pharmaceutical ingredient production draws from specialized biologics manufacturers in South Korea, Singapore, and the United States. Recombinant peptide inputs, chromatography resins, and sterile vial components constitute critical dependencies. Single-source vulnerability concentrates in fill-finish equipment suppliers. Distribution runs through temperature-controlled logistics networks anchored by Novo Nordisk and Eli Lilly dedicated nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers—telehealth dosing support, patient adherence monitoring, and cold-chain delivery subscriptions—expand faster than hardware margins for GLP-1 agonist sponsors, reframing competitive advantage around recurring patient relationship value.
For Market Incumbents: Harden cold-chain infrastructure ownership in São Paulo and Rio de Janeiro distribution corridors against emerging online pharmacy disintermediation. Secure ANVISA GMP certification for foreign manufacturing facilities to compress registration timelines against import-reliant competitors. Prioritize backward integration into peptide API sourcing to reduce cross-border logistics exposure. For New Entrants and Emerging Players: Argentine provincial healthcare networks outside Buenos Aires offer first-mover advantage for medical liaison presence and formulary inclusion. Target Córdoba and Mendoza diabetes clinics with injectable initiation protocols ahead of oral formulation competition. Deploy telehealth-supported dosing platforms to bypass hospital pharmacy channel control. For Investors and Strategic Acquirers: ANVISA-COFEPRIS bioequivalence protocol convergence reshapes the acquisition landscape toward sponsors with multi-country registration dossiers. Five-to-ten year viability centers on fill-finish infrastructure ownership rather than pure marketing plays. Monitor oral peptide permeation technology licensing deals as inflection signal for injectable margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Fill-Finish Capacity Expansion | Brazilian cold-chain node construction captures ANVISA-compliant supply security against import-reliant rivals. |
| Oral Peptide Permeation Licensing | Small-molecule enhancer technology acquisition compresses hospital pharmacy dependency for treatment-naïve segments. |
| Telehealth Adherence Platform Launch | Mexican homecare connectivity deepens recurring revenue attachment beyond device-only transactions. |
| Provincial Medical Liaison Deployment | Argentine prescriber access in Córdoba and Mendoza secures formulary position ahead of competitor saturation. |
| ICH Harmonization Dossier Strategy | Multi-country Brazil-Mexico-Chile submissions reduce per-market registration costs for regional portfolio builds. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and secondary sources including ANVISA registration filings, COFEPRIS approval databases, ClinicalTrials.gov protocols, and Ministry of Health technology assessments anchors the qualitative findings. Bottom-up prescription volume modeling triangulates against top-down market sizing from sponsor revenue disclosures and distributor shipment data.
Calibration against historical approval timelines and pricing realization patterns informs the analytical framework across the projection horizon. Segmentation dimensions include delivery technology, care setting, application indication, and regulatory cluster. CAGRs derive from fitted growth curves adjusted for reimbursement expansion trajectories and cold-chain infrastructure buildout schedules. Patient population epidemiology and prescriber adoption curves constitute primary forecast inputs.
Practitioners should monitor ANVISA GMP inspection backlogs, COFEPRIS accelerated pathway eligibility changes, and oral bioequivalence study readouts for early signals of competitive repositioning. Forecasts reflect documented assumptions about regulatory convergence timelines and reimbursement expansion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
India Nicotine Replacement Therapy Market
Pharmaceuticals
North America Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Wilson Disease Drugs Market
Pharmaceuticals
Latin America FMD Vaccine Market
Pharmaceuticals
Global Vaccine Contract Manufacturing Market
Pharmaceuticals
Veterinary Insulin Drugs Market
Pharmaceuticals
Global Human Rabies Vaccine Market
Pharmaceuticals
Global Basal Insulin Market
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market
Pharmaceuticals
Plasma-Derived Protein Therapies Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Indonesia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Lamotrigine API Market
Pharmaceuticals
US Compounding Pharmacies Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market