
 Soft Capsules Drugs CMO Market | 2026-2036
Soft Capsules Drugs CMO Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Capsules Drugs CMO Market Insights
Market Context with Strategic Players
Buyer concentration among mid-sized pharmaceutical developers is broadening as virtual biotech firms and specialty generics companies multiply their outsourcing relationships. Catalent, Inc. leverages integrated soft-gel formulation and commercial-scale production to anchor North American supply chains for complex oral delivery. WuXi AppTec competes through multi-site manufacturing scale across Asia-Pacific, while Lonza (Capsugel) sustains technology leadership in gelatin-alternative capsule platforms for vegetarian and halal-certified product lines.
Technical Definition and Structural Segments
Soft capsules drugs contract manufacturing organizations produce liquid or semi-solid filled gelatin or polymer shells, typically ranging from 100 to 1500 mg fill weight, designed to enhance bioavailability of poorly soluble APIs and enable precise unit dosing. The primary commercial purpose centers on protecting oxidation-sensitive actives, masking unpleasant tastes, and achieving reproducible dissolution profiles for oral administration. Gelatin-based capsules dominate current volume, though vegetarian segments are gaining fastest as kosher and halal certification requirements reshape procurement criteria across nutraceutical and pharmaceutical therapy areas. Oral delivery mode commands the largest margin pool, while topical soft-gel applications in cosmetic segments represent an emerging structural opportunity with higher per-unit value but smaller absolute scale.
Regulatory Framework and Forward Outlook
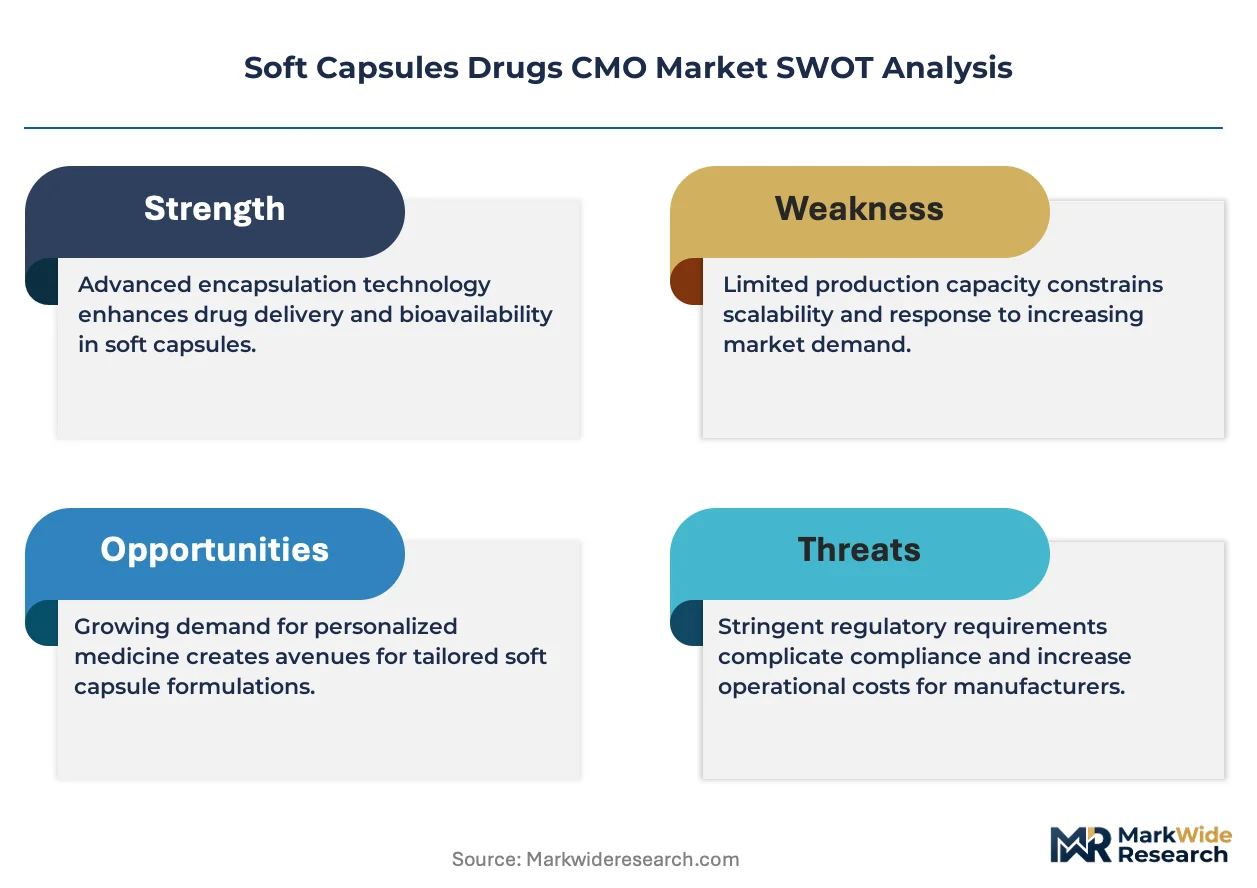
FDA current Good Manufacturing Practice enforcement and EMA's updated guidelines on cross-contamination control in multi-product facilities are elevating compliance costs and favoring CMOs with dedicated soft-gel lines. ISO 22000 and HACCP frameworks increasingly govern gelatin sourcing traceability, particularly as BSE-related restrictions tighten in European and Japanese import jurisdictions. Stakeholders must monitor evolving pharmacopeial standards for dissolution testing and leachable profiles, as regulatory divergence between FDA and EMA pathways could fragment qualification requirements for global product registrations.
Market Dynamics
Specialty pharmaceutical pipelines are exhausting available soft-gel manufacturing capacity faster than CMOs can commission dedicated lines, creating a structural bottleneck that favors partners with pre-qualified commercial-scale infrastructure. This capacity scarcity is compressing qualification timelines and elevating contract values for established operators.
Growth Catalysts
- Nutraceutical format conversion:Wellness brands are migrating liquid supplements into soft-gel shells to improve shelf stability and consumer compliance, expanding addressable volume beyond traditional pharmaceutical applications.
- FDA gelatin integrity guidance:Updated sourcing traceability requirements are disqualifying underqualified CMOs and consolidating demand among partners with validated supply chain documentation.
- Vegetarian capsule chemistry:Carrageenan and modified starch formulations are unlocking kosher and halal certification pathways, opening procurement channels in Middle Eastern and Southeast Asian markets.
Market Restraints
- Gelatin cost volatility:Bovine and porcine raw material prices fluctuate with livestock feed commodity cycles, compressing margin predictability for fixed-price contract structures.
- Equipment supplier concentration:Soft-gel encapsulation machinery production centers on German and Italian engineering firms, creating lead time vulnerability for capacity expansion projects.
- Dissolution test standard divergence:USP Chapter 711 and Ph. Eur. 2.9.3 specify different apparatus and acceptance criteria, forcing dual validation investments for global product registrations.
Strategic Opportunities
- Pediatric and geriatric dosing formats:Mini-soft-gel platforms below 8mm diameter address swallowing difficulty in aging populations and children, penetrating untapped therapeutic categories.
- Topical cosmetic soft-gels:Transdermal vitamin and CBD delivery applications command 3-4x per-unit value versus oral equivalents, with smaller batch scale requirements suited to flexible CMO operations.
- India PLI scheme for pharmaceuticals:Production-linked incentives for active pharmaceutical ingredient and formulation manufacturing are attracting soft-gel capacity investment to serve export markets.
Industry Challenges
- Formulation scientist scarcity:Lipid-based drug delivery expertise remains concentrated among retiring specialists, constraining process development throughput for complex bioavailability enhancement projects.
- Multi-product facility segregation:EMA cross-contamination guidelines demand dedicated air handling and cleaning validation protocols that extend campaign changeover intervals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Capsules Drugs CMO Market |
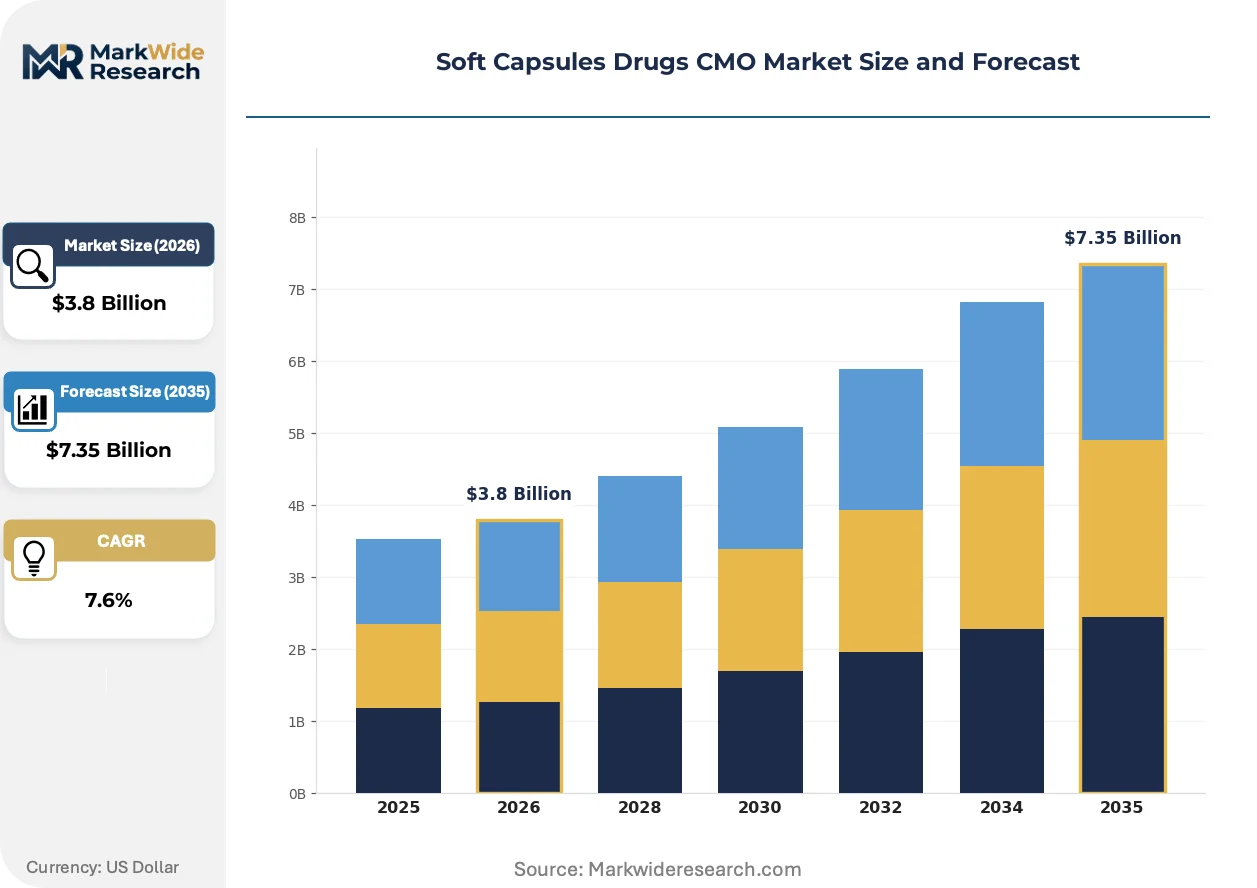
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Vegetarian, Enteric-Coated, Soft Gel Therapy Area: Nutraceuticals, Pharmaceuticals, Cosmetic, Veterinary Delivery Mode: Oral, Topical, Injection, Subcutaneous End User: Contract Manufacturers, Pharmaceutical Companies, Health Organizations, Research Institutions |
| Companies Covered | Samsung Biologics, Recipharm, Lonza (Capsugel), Pfizer CentreOne, Siegfried, Catalent, Inc., WuXi AppTec, Eurofins CDMO, Thermo Fisher Scientific (Patheon), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Capsules Drugs CMO Market Trends and Innovations
Continuous manufacturing architectures and real-time release testing are converging to compress batch cycle times and reduce in-process inventory exposure for high-value soft-gel products. These operational shifts are redrawing competitive boundaries between asset-heavy incumbents and technology-licensed entrants.
Starch-based shell formulations incorporating gellan gum and pullulan are rewriting vegetarian capsule performance benchmarks, achieving oxygen permeability rates comparable to gelatin while eliminating temperature-sensitive cross-linking. Nutraceutical contract buyers in Germany and Switzerland are specifying these platforms for oxidation-sensitive omega-3 and vitamin D products. The technology is compressing price premiums between vegetarian and conventional capsules from 40% to 15%.
EMA's updated guidelines on nitrosamine risk assessment in chemically synthesized APIs are extending to excipient and capsule shell leachable profiles, forcing CMOs to implement additional extractable testing protocols. The industrial consequence is extended qualification timelines for new product introductions and elevated analytical chemistry staffing requirements. Oral oncology and hormone therapies face the most stringent scrutiny, with sponsors accelerating supplier audits to preempt regulatory action.
Virtual biotech firms are consolidating purchasing through platform CMO partnerships that bundle formulation development, clinical supply, and commercial manufacturing under master service agreements. This procurement consolidation displaces fragmented supplier relationships with single-source accountability models. The pattern is most visible in the United States, where specialty pharmaceutical developers prioritize speed-to-IND over unit cost minimization.
Soft Capsules Drugs CMO Market Segmentation
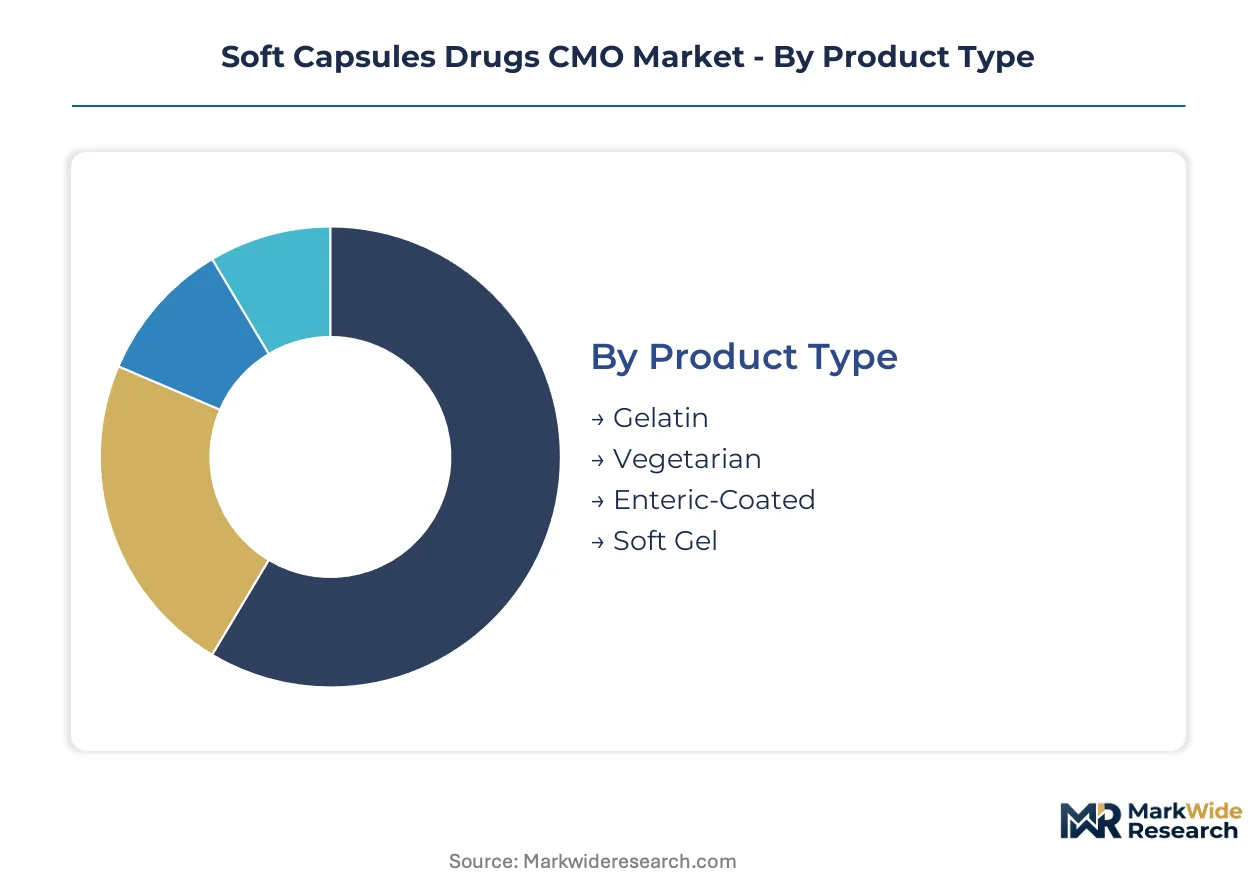
Soft-gel contract manufacturing demands diverge sharply across shell chemistry, therapeutic application, and delivery modality. Each segmentation axis carries distinct qualification protocols, margin structures, and capacity allocation priorities that reshape procurement strategies for pharmaceutical and nutraceutical sponsors.
Product Type:
Upgrade cycles in capsule shell chemistry are accelerating as certification requirements and bioavailability specifications tighten across import jurisdictions.
- Gelatin:Bovine and porcine-derived gelatin shells deliver proven oxygen barrier performance and mechanical stability across standard storage conditions. Pharmaceutical sponsors in the United States specify gelatin for high-potency lipid formulations where dissolution profile consistency outweighs vegetarian certification requirements. Raw material traceability documentation now dominates supplier qualification timelines.
- Vegetarian:Carrageenan, modified starch, and pullulan formulations achieve halal and kosher certification while narrowing the oxygen permeability gap with conventional gelatin. German and Swiss nutraceutical brands are specifying these platforms for omega-3 and vitamin D products where consumer preference for plant-based labeling commands shelf price premiums.
- Enteric-Coated:pH-resistant polymer overlays protect acid-labile actives through gastric transit, enabling targeted intestinal release for enzyme and probiotic therapies.
- Soft Gel:Standard liquid-filled gelatin capsules remain the default specification for generic pharmaceutical volume production and cost-sensitive contract structures.
Gelatin sits at the top of the volume ranking, with vegetarian climbing the fastest.
Therapy Area:
Application-driven segmentation reveals divergent regulatory intensity and batch scale economics across therapeutic categories.
- Nutraceuticals:Wellness brands converting liquid supplements into unit-dose soft-gels are exhausting available contract capacity faster than CMOs can expand. Vitamin D, CoQ10, and omega-3 fatty acid formulations dominate current volume, with shelf stability and swallowability driving format conversion from traditional tablets and liquids.
- Pharmaceuticals:Specialty oral products for cardiovascular, dermatology, and neurology indications rely on soft-gel bioavailability enhancement for poorly soluble APIs. FDA current Good Manufacturing Practice enforcement and EMA cross-contamination guidelines are elevating compliance costs and consolidating demand among partners with dedicated soft-gel infrastructure.
- Cosmetic:Transdermal vitamin and CBD delivery applications command elevated per-unit value with smaller batch scale requirements suited to flexible manufacturing operations.
- Veterinary:Palatability masking and precise dosing for companion animal formulations represent a niche procurement channel with specialized stability testing protocols.
Pharmaceuticals generate the largest revenue pool, though nutraceuticals are expanding most quickly as wellness brands multiply their outsourcing relationships.
Delivery Mode:
Route of administration determines equipment configuration, validation complexity, and regulatory pathway requirements for contract manufacturers.
- Oral:Standard liquid-filled soft-gels for gastrointestinal absorption dominate installed capacity and qualification expertise across CMO networks. Dissolution testing per USP Chapter 711 and Ph. Eur. 2.9.3 creates dual validation obligations for sponsors pursuing simultaneous FDA and EMA registrations.
- Topical:Vitamin E, retinol, and CBD soft-gels designed for transdermal rupture and rub-in application are penetrating cosmetic and dermatology segments with 3-4x per-unit value versus oral equivalents.
- Injection:Sterile soft-gel formats for parenteral lipid emulsion delivery remain experimental with limited commercial-scale infrastructure.
- Subcutaneous:Depot-formulation soft-gels for sustained hormone release face extended pharmacokinetic validation timelines and specialized toxicology requirements.
Oral commands absolute volume leadership, while topical gains share fastest on cosmetic segment demand.
End User:
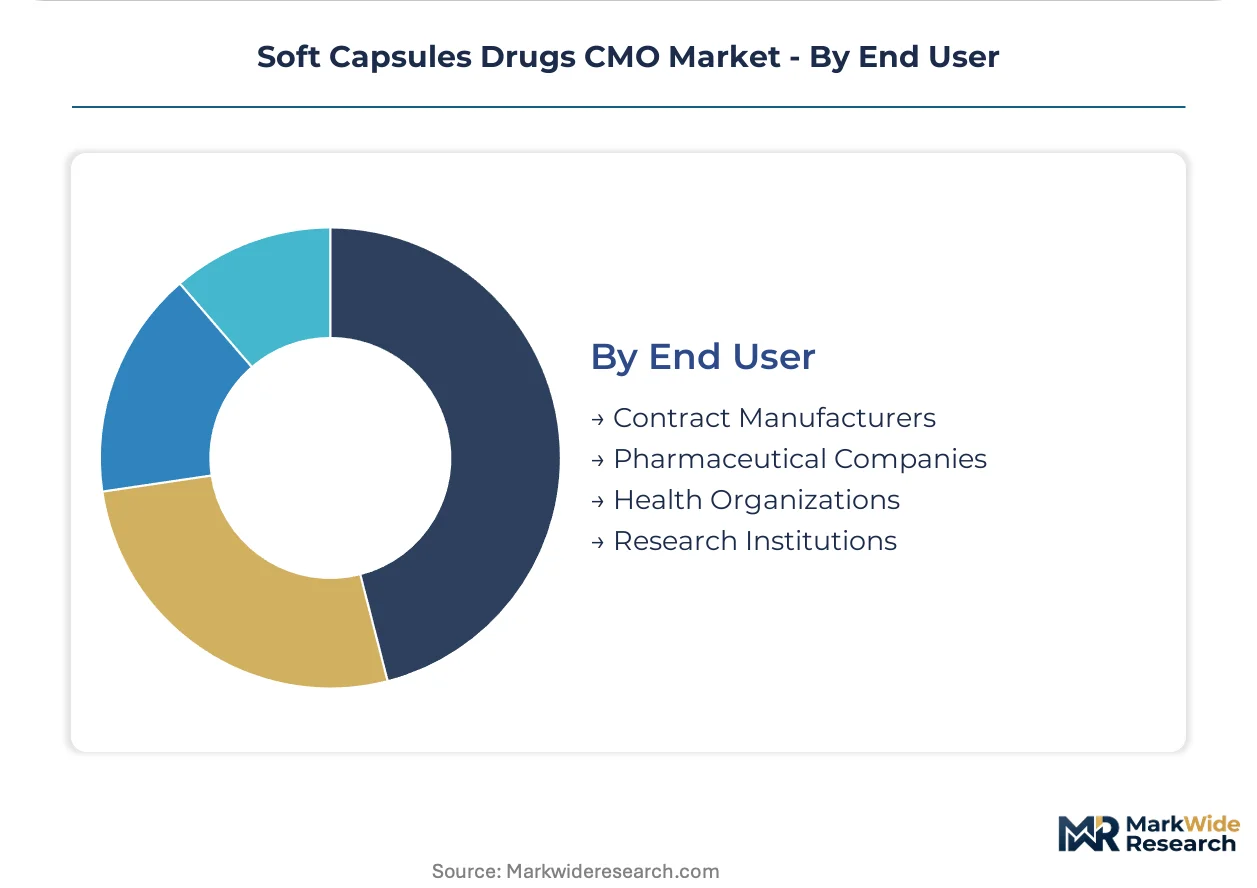
Customer-type segmentation exposes divergent procurement sophistication, technical specification intensity, and contract duration preferences across the demand base.
- Contract Manufacturers:Tier-two and tier-three CMOs without in-house soft-gel capability subcontract to specialized partners, creating nested outsourcing relationships with compressed margin stacking.
- Pharmaceutical Companies:Mid-sized specialty developers and virtual biotech firms are consolidating purchasing through platform partnerships that bundle formulation, clinical supply, and commercial manufacturing under master service agreements.
- Health Organizations:Hospital systems and government procurement entities specify soft-gel formats for patient compliance programs, particularly in geriatric and pediatric populations.
- Research Institutions:Academic and clinical trial sponsors require flexible batch scales and accelerated qualification timelines for investigator-initiated studies.
Pharmaceutical companies anchor contract value, with contract manufacturers expanding fastest as nested outsourcing proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands contract values that exceed German and Swiss markets combined, while India's export-oriented capacity expansion is compressing lead times for international sponsors seeking cost-competitive soft-gel manufacturing.
United States
Specialty pharmaceutical developers and virtual biotech firms are exhausting qualified soft-gel capacity along the Eastern seaboard. FDA current Good Manufacturing Practice enforcement and updated gelatin sourcing traceability requirements are disqualifying underqualified contract manufacturers. The New Jersey-Pennsylvania corridor anchors North American supply chains, with Catalent operating integrated formulation-to-commercial facilities that serve lipid-based bioavailability enhancement programs.
Germany
Nutraceutical brands headquartered in Frankfurt and Düsseldorf are specifying vegetarian capsule platforms for omega-3 and vitamin D products. EMA cross-contamination guidelines and nitrosamine risk assessment protocols are elevating compliance costs for multi-product facilities. The Baden-Württemberg region concentrates analytical chemistry expertise, with Stuttgart-area laboratories validating dissolution profiles per Ph. Eur. 2.9.3 specifications for pan-European registrations.
Switzerland
Swissmedic pharmacopeial standards and kosher certification requirements are reshaping procurement criteria for oxidation-sensitive actives. Basel-based pharmaceutical sponsors are consolidating purchasing through platform partnerships that bundle formulation development with commercial manufacturing. The Zurich-Basel corridor hosts specialized CMOs with dedicated soft-gel lines serving oral oncology and hormone therapy pipelines.
India
The Production-Linked Incentive scheme for pharmaceuticals is attracting soft-gel capacity investment to serve export markets in Europe and Southeast Asia. CDSCO manufacturing license requirements and FSSAI nutraceutical regulations are tightening qualification protocols for international sponsors. Maharashtra and Gujarat host expanding contract manufacturing clusters, with Mumbai-Pune facilities qualifying carrageenan-based vegetarian capsules for Middle Eastern halal-certified procurement channels.
China
Domestic pharmaceutical sponsors are migrating complex oral delivery programs to contract manufacturers with validated gelatin-alternative platforms. NMPA Good Manufacturing Practice inspections and dual carbon goals are accelerating equipment modernization in multi-product facilities. The Yangtze River Delta concentrates soft-gel encapsulation machinery suppliers, with Shanghai-area engineering firms reducing lead times for capacity expansion projects serving Asia-Pacific nutraceutical brands.
Soft Capsules Drugs CMO Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service levels, creating a bifurcated structure where integrated CDMOs capture platform partnerships while niche operators serve flexible batch requirements. The vendor base organizes around three strategic archetypes: asset-heavy incumbents with dedicated commercial-scale infrastructure, technology-licensed entrants leveraging continuous manufacturing architectures, and regional specialists optimizing for local regulatory pathways. Dominant competitive moves include M&A-driven geographic expansion and strategic partnerships that bundle formulation development with analytical chemistry services.
Among diversified conglomerates with pharmaceutical manufacturing heritage, Lonza (Capsugel) and Thermo Fisher Scientific (Patheon) exemplify asset-heavy incumbents with validated supply chain documentation and multi-site manufacturing networks. Catalent, Inc. occupies a position within the integrated services tier, representing pure-play specialists that anchor North American supply chains through formulation-to-commercial bundling. WuXi AppTec sits within the Asia-Pacific scale-driven segment, exemplifying regional operators that compete through multi-site capacity and accelerated qualification timelines for international sponsors.
| Leading Market Players |
|---|
| Samsung Biologics |
| Recipharm |
| Lonza (Capsugel) |
| Pfizer CentreOne |
| Siegfried |
| Catalent, Inc. |
| WuXi AppTec |
| Eurofins CDMO |
| Thermo Fisher Scientific (Patheon) |
| Others |
Pricing and Supply Chain Analysis
Captive gelatin sourcing from bovine and porcine rendering operations anchors supply security for established CMOs while insulating them from spot-market volatility that compresses margin predictability for competitors dependent on third-party raw material procurement.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard soft-gel manufacturing, compressing contract values for commodity oral formulations while premium vegetarian and enteric-coated platforms sustain wider spreads. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification intensity and batch scale, with kosher and halal-certified production commanding sustained premiums. Pricing pressure stems from German and Italian equipment supplier concentration that extends lead times for capacity expansion. Virtual biotech firms exhibit lowest price sensitivity as speed-to-IND overrides unit cost, while generic pharmaceutical sponsors negotiate aggressively on volume commitments.
Supply Chain Analysis
Return flows of defective batches and expired inventory to gelatin recovery processors complete a circular raw material loop that supplements virgin bovine and porcine inputs for non-pharmaceutical applications. Supply concentrates in the United States, Germany, and India, with the New Jersey-Pennsylvania corridor anchoring North American pharmaceutical-grade production. Raw material dependencies center on bovine hide splits, pharmaceutical-grade glycerin, and colorant excipients from specialized chemical suppliers. Single-source vulnerability pervades soft-gel encapsulation machinery, where German and Italian engineering firms control global equipment production. Distribution runs through direct CMO-sponsor master service agreements, displacing fragmented spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between FDA-regulated US capacity and India's PLI-subsidized export infrastructure creates cost differentials of 30-40% on comparable quality certifications, rewarding sponsors with multi-site qualification strategies.
For Market Incumbents: Anticipate formulation scientist scarcity constraining complex bioavailability project throughput by accelerating apprenticeship programs and acquiring boutique lipid-based drug delivery specialists. Defend market position by deepening backward integration into gelatin rendering operations to neutralize raw material cost volatility. Preempt EMA nitrosamine guideline extensions by implementing extractable testing protocols ahead of competitor compliance timelines.
For New Entrants and Emerging Players: Continuous manufacturing architectures with real-time release testing offer a technology-first wedge against asset-heavy incumbents burdened by batch-oriented legacy infrastructure. Target pediatric mini-soft-gel platforms below 8mm diameter, where swallowability-driven demand outpaces qualified supply. Penetrate through topical cosmetic soft-gel applications, where smaller batch scales and 3-4x per-unit value reduce capital intensity barriers.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier European CMOs because EMA cross-contamination guidelines are disqualifying multi-product facilities and consolidating demand among operators with dedicated soft-gel lines. Platform partnerships bundling formulation development with commercial manufacturing anchor long-term contract visibility. Watch FDA warning letter issuance rates as an inflection indicator for qualification-driven demand surges.
| Strategic Initiative | Industry Significance |
|---|---|
| Vegetarian Capsule Chemistry Investment | Carrageenan and pullulan formulations unlock kosher and halal procurement channels in Middle Eastern markets. |
| Continuous Manufacturing Transition | Real-time release testing compresses batch cycle times and reduces in-process inventory exposure. |
| Multi-Site Geographic Expansion | India PLI-subsidized capacity serves export demand while mitigating FDA inspection backlogs. |
| Platform Partnership Structuring | Master service agreements bundling formulation-to-commercial displace fragmented supplier relationships. |
| Extractable Testing Protocol Implementation | Preemptive EMA nitrosamine compliance extends qualification timelines for unprepared competitors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with soft-gel formulation scientists, CMO procurement directors, regulatory affairs specialists, and nutraceutical brand managers with secondary validation against FDA 483 observations, EMA inspection reports, CDSCO manufacturing licenses, and USP pharmacopeial revision notices. Bottom-up project pipeline tracking and top-down capacity utilization estimates were triangulated to anchor volume forecasts.
Historical reference periods spanning pre-pandemic baseline through post-regulatory-guidance implementation established the trajectory anchors for projection modeling across the analysis window. The analytical framework segmented by shell chemistry, therapy area, delivery mode, and end-user archetype, with CAGRs derived from weighted capacity expansion announcements and sponsor pipeline conversion rates. Forecast inputs incorporated lipid-based drug development program counts and gelatin raw material price indices.
The model holds under stable regulatory enforcement intensity; deviation in FDA inspection frequency or EMA cross-contamination guideline revision would shift capacity utilization assumptions and contract value trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Japan Generic Drug Market
Pharmaceuticals
Gonorrhea Therapeutics Market
Pharmaceuticals
Global Fluorouracil (5FU) Market
Pharmaceuticals
Proton Pump Inhibitors Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Plasma-Derived Protein Therapies Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Indapamide Market
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
Tranquilizer Drugs Market
Pharmaceuticals
Anti-Radiation Drugs Market
Pharmaceuticals
Vaginal Antifungals Market
Pharmaceuticals
OTC Dry Eye Drops Market
Pharmaceuticals
Intravitreal (IVT) Injectables Market
Pharmaceuticals
Global Pharmerging Market
Pharmaceuticals
Naproxen Market