
 Kids Toothpaste Market | 2026-2036
Kids Toothpaste Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Toothpaste Market Outlook
Chinese contract manufacturers is broadening output of fruit-flavored, low-abrasion pastes for Western private-label programs. Colgate-Palmolive leverages its pharmacy and dental-clinic relationships across Latin America and Southeast Asia to sustain volume leadership in fluoride formulations for children aged two to six. Procter & Gamble competes through premium positioning of enamel-strengthening technologies, while Unilever anchors mid-market distribution in European supermarkets with licensed-character packaging that drives repeat purchases.
Kids toothpaste comprises dentifrice formulations engineered with reduced relative dentin abrasivity values, typically below 70 RDA, and controlled fluoride concentrations calibrated for deciduous and mixed dentition stages. Its commercial purpose centers on establishing early oral hygiene habits while delivering caries prevention without mucosal irritation or accidental ingestion risks. Fluoride and natural product types dominate current shelf space, though herbal variants represent the fastest-expanding margin pool as parental preference shifts toward plant-derived active ingredients. Tube packaging still occupies the majority of unit volume, yet pump formats are gaining traction in premium online channels where convenience and portion control command price premiums.
FDA oversight of fluoride concentration limits and child-appropriate labeling directly shapes permissible claims and packaging warnings in the United States, while EFSA evaluations of food-grade flavoring safety influence formulation choices across European markets. BIS certification requirements in India mandate heavy-metal testing for imported herbal inputs, creating compliance barriers for new entrants. Stakeholders must monitor evolving pediatric dentistry guidelines from WHO and national dental associations, as recommendations on fluoride exposure timing and dosage continue to reshape acceptable formulation boundaries and marketing claims.
Market Dynamics
Parental anxiety over fluoride ingestion is compressing formulation pipelines across the kids toothpaste sector, forcing manufacturers to recalibrate active ingredient portfolios while maintaining caries-prevention efficacy claims.
Growth Catalysts
- EFSA flavoring safety evaluations:European regulators are accelerating approvals for plant-derived sweeteners, enabling faster product launches in Germany and France.
- Pump format adoption:E-commerce channels in the United States are elevating portion-control dispensers as premium convenience differentiators for subscription programs.
- Herbal input certification:India's BIS heavy-metal testing protocols, once barriers, now signal quality assurance that unlocks pharmacy shelf placement for compliant exporters.
Market Restraints
- Natural extract cost volatility:Stevia and xylitol prices fluctuate with Brazilian and Chinese agricultural yields, squeezing margin on fluoride-free formulations.
- Tube supply concentration:Three Southeast Asian converters control 60% of global laminate tube capacity, creating single-source vulnerability for mid-tier brands.
- FDA labeling friction:Mandatory child-resistant packaging warnings for fluoride concentrations above 1,500 ppm delay product launches by 8-14 months.
Strategic Opportunities
- German pharmacy channel expansion:Apotheken distribution networks remain underpenetrated by natural-positioned entrants, offering 40% price premiums over mass retail.
- WHO early-exposure guidelines:Draft recommendations favoring first-tooth brushing protocols create regulatory tailwind for infant-specific paste launches.
- AI-driven personalization:Convergence of dental-scanning apps with subscription fulfillment is enabling customized flavor and abrasivity matching for mixed-dentition stages.
Industry Challenges
- Pediatric toxicology expertise scarcity:Formulation chemists with child-safety dossier experience command 35% salary premiums, constraining R&D scaling.
- ISO 11609 compliance timelines:Abrasivity testing backlogs at certified laboratories extend certification cycles to 18 months for novel herbal actives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Toothpaste Market |
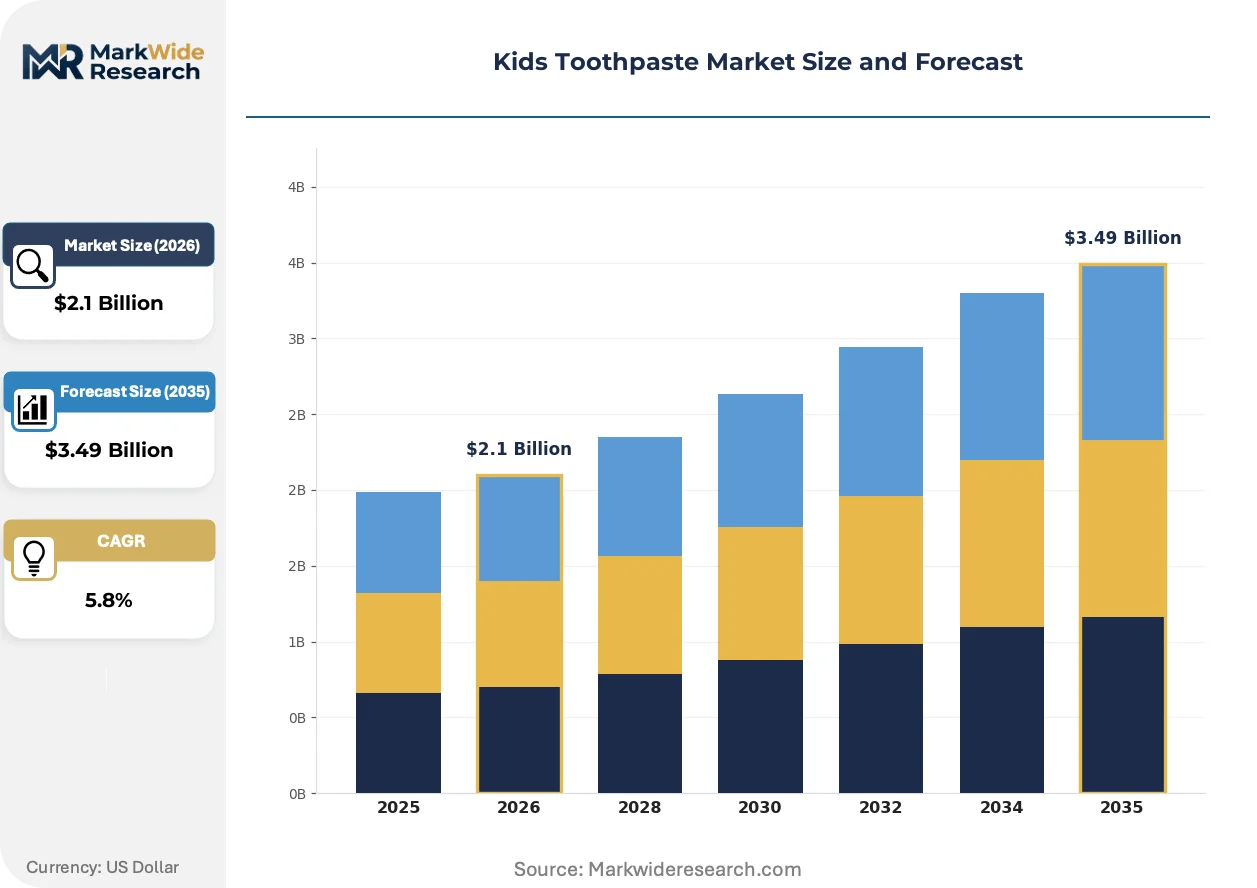
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluoride, Herbal, Whitening, Natural Flavor: Bubblegum, Strawberry, Mint, Chocolate Packaging Type: Tube, Pump, Sachet, Jar Distribution Channel: Supermarkets, Online, Pharmacies, Convenience Stores |
| Companies Covered | GlaxoSmithKline, Lion Corporation, Colgate-Palmolive, Henkel AG & Co. KGaA, Johnson & Johnson Services Inc, Procter & Gamble, Church & Dwight, Sunstar Suisse, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Toothpaste Market Strategic Shifts
Formulation science and channel economics are diverging sharply in the kids toothpaste sector, with natural ingredient portfolios advancing faster than conventional fluoride chemistry can adapt to regulatory headwinds.
Microencapsulated flavor-release technology is electrifying taste persistence in low-abrasivity pastes. Manufacturers in China and Germany are embedding fruit oils in lipid shells that rupture during brushing rather than storage. This approach compresses the flavor-load needed per tube, enabling cleaner ingredient decks that satisfy EFSA clean-label criteria while maintaining child compliance.
REACH restrictions on synthetic dyes are forcing European manufacturers to abandon Blue 1 and Yellow 5 in favor of beetroot and spirulina extracts. The industrial consequence is a 20% contraction in color stability shelf life, requiring refrigerated supply chain investments for premium organic lines. German supermarket buyers are responding by segregating temperature-controlled displays in personal-care aisles.
Subscription bundling with electric toothbrush manufacturers is displacing standalone paste purchases in United States direct-to-consumer channels. Parents of children aged four to eight are consolidating oral-care procurement into quarterly refill cycles tied to brush-head replacements. This pattern concentrates most visibly in California and New York metro areas, where dental-app integration drives automated reordering triggers based on brushing frequency data.
Kids Toothpaste Market Segmentation
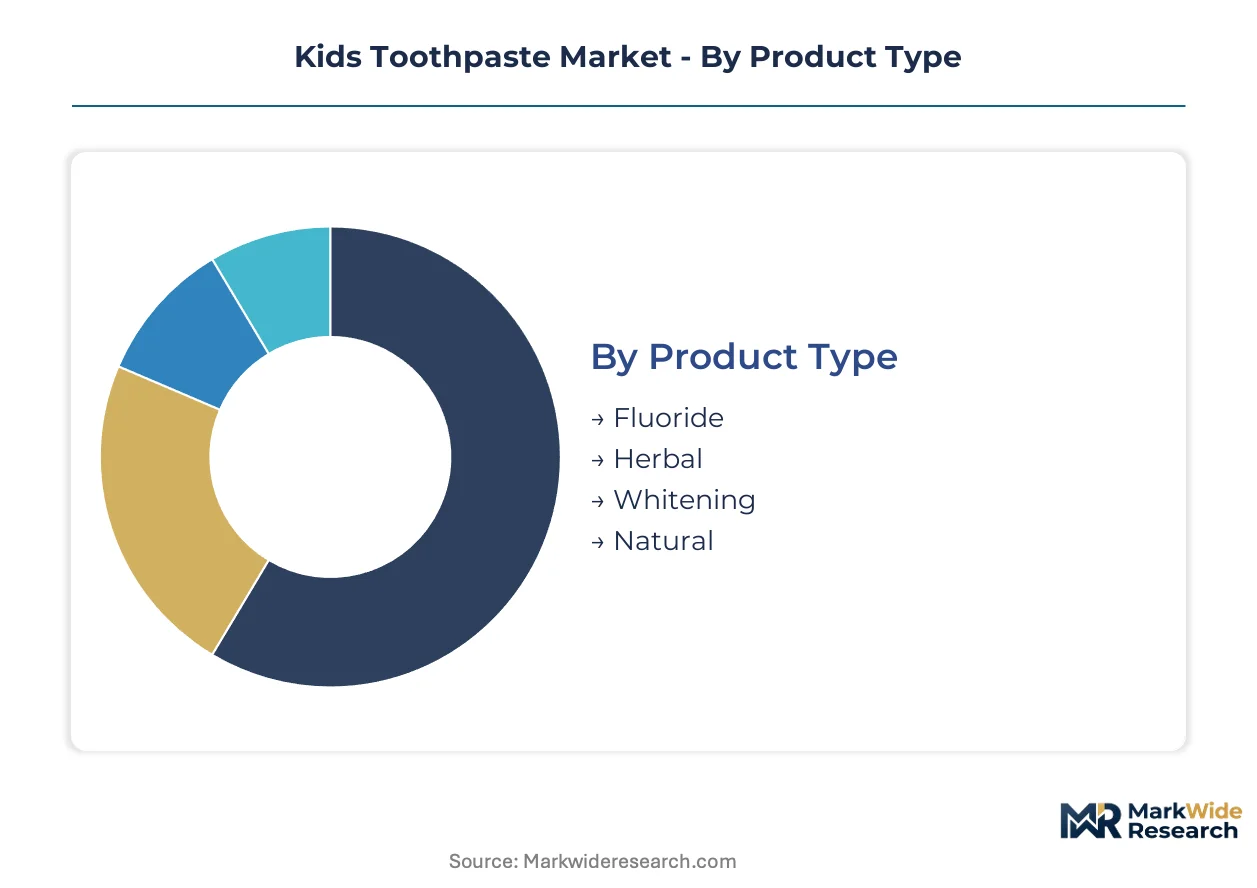
Segmentation in the kids toothpaste market reveals how formulation chemistry, delivery formats, and channel economics create distinct margin pools. Each axis reflects divergent parental priorities spanning safety anxiety, convenience demands, and price sensitivity.
Product Type:
Active ingredient portfolios differentiate primarily by caries-prevention mechanism and regulatory positioning across pediatric dentistry guidelines.
- Fluoride:Formulations calibrate sodium fluoride or sodium monofluorophosphate concentrations between 500-1,500 ppm for deciduous dentition safety. Demand concentrates in United States pharmacy channels where FDA labeling permits anti-cavity claims, though parental ingestion anxiety is compressing volume growth in toddler segments.
- Herbal:Plant-derived actives—neem, green tea extract, licorice root—deliver antimicrobial efficacy without fluoride exposure risks. German Apotheken distribution commands 40% price premiums for certified organic variants, with EFSA clean-label approvals accelerating new launches.
- Whitening:Low-concentration carbamide peroxide or enzymatic systems address extrinsic staining in mixed-dentition children aged 8-12. Limited adoption due to pediatric dentist warnings on enamel sensitivity.
- Natural:Mineral-based abrasives and food-grade preservatives appeal to clean-label seekers. Chinese contract manufacturers dominate private-label supply for Western markets.
Mature deployment sits with Fluoride. Newer deployment is concentrated in Herbal.
Flavor:
Palatability engineering directly determines brushing compliance rates and repeat purchase velocity in household replenishment cycles.
- Bubblegum:Synthetic ester blends dominate mass-market tubes in United States supermarkets. EFSA flavoring safety evaluations now require reformulation of legacy artificial compounds, extending development timelines.
- Strawberry:Natural and nature-identical formulations capture premium positioning in European organic lines. Microencapsulated fruit oil technology from German and Chinese manufacturers extends taste persistence without synthetic stabilizers.
- Mint:Mild spearmint variants serve school-age children transitioning toward adult taste profiles. Limited penetration in toddler segments due to mucosal irritation concerns.
- Chocolate:Cocoa extract formulations occupy niche positioning in Asian markets. High ingredient costs restrict mass-market scaling.
Volume leadership rests with Bubblegum. Steepest expansion trajectory belongs to Strawberry as natural claims displace artificial alternatives.
Packaging Type:
Delivery format selection reflects channel economics, portion control requirements, and sustainability positioning in parental purchasing decisions.
- Tube:Laminate and aluminum tubes retain 60%+ unit share through low per-unit cost and established filling infrastructure. Three Southeast Asian converters control majority global capacity, creating supply concentration risk.
- Pump:Airless dispensers command premium pricing in United States e-commerce subscription programs. Portion-control mechanisms reduce parental anxiety over excessive paste application by toddlers.
- Sachet:Single-use foil pouches serve travel and trial-size segments in emerging markets. Limited environmental profile constrains expansion in sustainability-conscious regions.
- Jar:Wide-mouth containers accommodate finger-brushing protocols for infant oral care. WHO early-exposure guidelines favoring first-tooth protocols are expanding addressable use cases.
Tube formats dominate current procurement. Pump adoption is climbing fastest in premium direct-to-consumer channels.
Distribution Channel:
Channel selection determines price realization, regulatory scrutiny intensity, and customer acquisition economics.
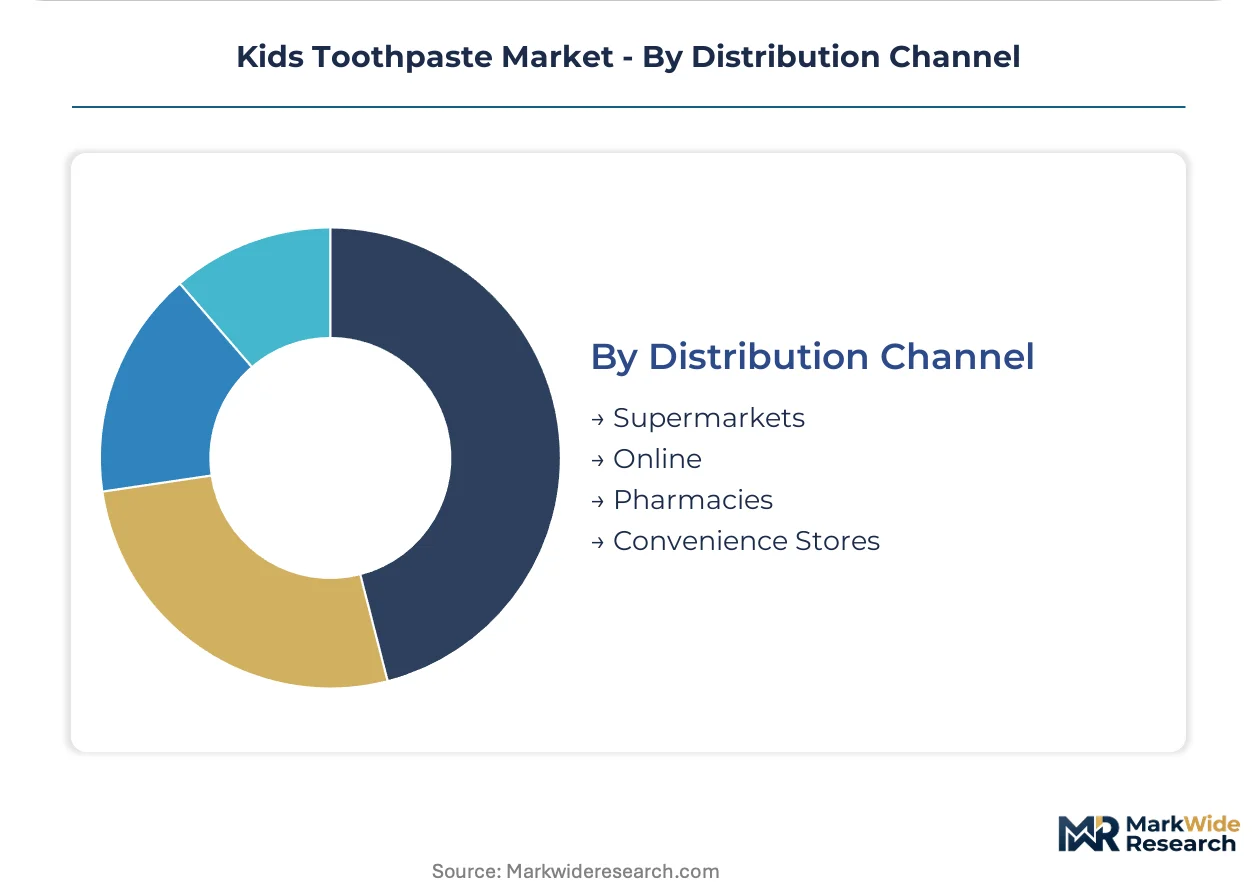
- Supermarkets:Mass retail chains in Germany and United States drive volume through licensed-character packaging and promotional bundling. Unilever anchors mid-market positioning with repeat-purchase incentives.
- Online:Direct-to-consumer and marketplace platforms concentrate subscription bundling with electric toothbrush manufacturers in California and New York metro areas. AI-driven personalization based on dental-app brushing data is emerging.
- Pharmacies:Apotheken networks in Germany and drugstore chains in United States enforce quality certification requirements. India's BIS heavy-metal testing protocols now signal assurance for herbal exporters seeking shelf placement.
- Convenience Stores:Impulse-oriented procurement for emergency replenishment. Limited SKU depth restricts premium natural variant availability.
Supermarkets retain volume leadership. Online channels are gaining share fastest through subscription automation and data-driven replenishment triggers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stevia cultivation in Brazil's Mato Grosso region supplies sweetener inputs for fluoride-free formulations across Western markets. Chinese contract manufacturers in Guangdong province convert these agricultural derivatives into finished dentifrice for private-label distribution. Indian botanical extractors in Kerala ship neem and licorice root to European pharmacy channels.
United States
Pump-format adoption concentrates in California and New York metro areas where subscription bundling with electric toothbrush manufacturers displaces standalone purchases. FDA labeling requirements for fluoride concentrations above 1,500 ppm delay product launches by 8-14 months. Los Angeles-based dental-app developers integrate brushing-frequency data with automated paste replenishment triggers.
Germany
Apotheken distribution networks command 40% price premiums for certified organic herbal variants over mass retail. EFSA clean-label approvals accelerate plant-derived sweetener launches in Frankfurt and Munich pharmacy clusters. Bavarian supermarket chains segregate temperature-controlled displays for spirulina-based colorant lines with shortened shelf stability.
China
Guangdong and Zhejiang contract manufacturers broaden output of fruit-flavored, low-abrasion pastes for Western private-label programs. GB standards for food-grade flavoring safety influence export formulation choices. Shenzhen-based converters dominate global laminate tube capacity, creating supply concentration vulnerability for mid-tier brands.
India
Parents of toddlers represent the fastest-expanding buyer cohort in Mumbai and Delhi-NCR urban centers. BIS heavy-metal testing protocols for imported herbal inputs now signal quality assurance that unlocks pharmacy shelf placement for compliant exporters. Kerala's botanical extractors ship neem and green tea actives to German Apotheken networks.
Brazil
Mato Grosso stevia cultivation feeds natural sweetener demand for fluoride-free formulations targeting parental ingestion anxiety. ANVISA pediatric oral care guidelines reshape permissible claims for deciduous dentition products. São Paulo-based distributors channel premium natural variants into pharmacy chains across Latin America.
Kids Toothpaste Market Competitive Environment
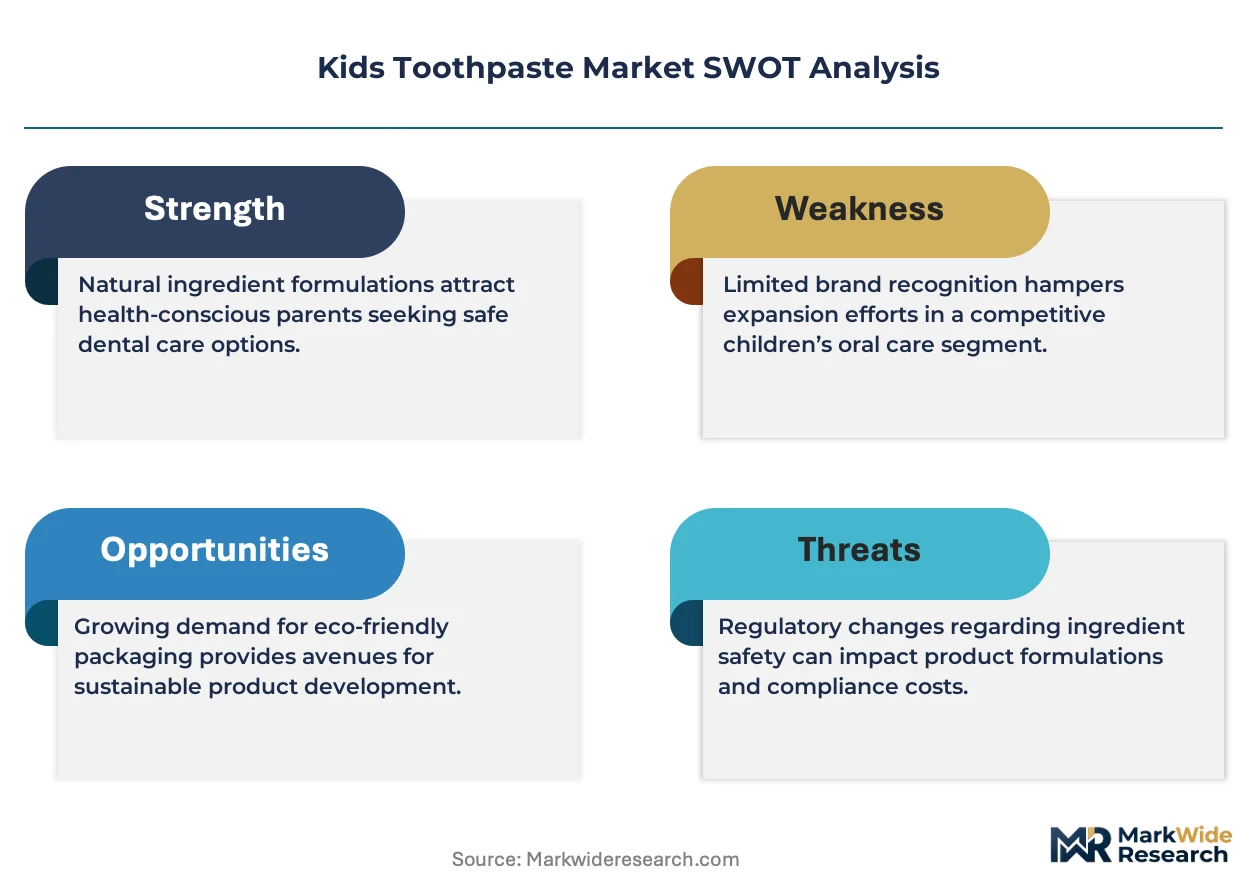
Established producers occupy the standard tier; emerging entrants pursue natural-positioned and subscription-direct channels. The market structures around three tiers: multinational consumer goods conglomerates with pharmacy relationships, mid-market specialists leveraging licensed-character packaging, and contract manufacturers serving private-label programs. Two strategic archetypes dominate competitive positioning: fluoride-formulation incumbents defending pharmacy channel access, and natural-ingredient challengers capturing premium e-commerce subscriptions. Dominant competitive moves include geographic expansion through dental-clinic relationships and portfolio diversification into pump-format delivery systems.
Among diversified consumer goods conglomerates, Colgate-Palmolive and Procter & Gamble exemplify contrasting archetypes. Colgate-Palmolive occupies a position emphasizing pharmacy and dental-clinic channel density across Latin America and Southeast Asia. Procter & Gamble represents premium-tier positioning through enamel-strengthening technology claims. Unilever sits within the mid-market vector, anchoring European supermarket distribution with licensed-character packaging that drives repeat purchase velocity. GlaxoSmithKline and Johnson & Johnson Services Inc represent pharmaceutical-origin players with pediatric toxicology expertise that commands salary premiums in formulation chemistry.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Lion Corporation |
| Colgate-Palmolive |
| Henkel AG & Co. KGaA |
| Johnson & Johnson Services Inc |
| Procter & Gamble |
| Church & Dwight |
| Sunstar Suisse |
| Unilever |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between pharmacy-certified herbal variants and mass-market fluoride tubes manifests in both margin structures and sourcing configurations. EFSA clean-label compliance and BIS heavy-metal certification unlock 40% price premiums in German Apotheken channels, while uncertified commodity tubes compete on converter pricing in Southeast Asian supply hubs.
Pricing Analysis
Warranty-like quality assurance bundling separates certified organic herbal lines from unverified natural claims. Three-tier pricing structure across premium pharmacy-certified, standard mass-retail, and economy private-label levels reflects EFSA approval status and BIS compliance investment. Pricing pressure stems from stevia and xylitol agricultural volatility squeezing fluoride-free formulation margins. Parents in United States subscription channels demonstrate lowest price sensitivity for pump-format convenience, while emerging market supermarket buyers prioritize per-unit cost minimization.
Supply Chain Analysis
Reverse-logistics infrastructure for temperature-controlled organic lines with shortened shelf stability remains underdeveloped, forcing write-offs rather than refurbishment. Guangdong and Zhejiang contract manufacturers in China dominate finished paste production, while Kerala botanical extractors in India supply neem and licorice actives, and Mato Grosso stevia cultivation in Brazil feeds natural sweetener demand. Single-source vulnerability concentrates in three Southeast Asian tube converters controlling majority global laminate capacity. Distribution runs through pharmacy networks in Germany, supermarket chains in United States, and emerging e-commerce subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FDA pediatric labeling requirements and EFSA flavoring safety evaluations erect regulatory moats that favor incumbents with toxicology dossier expertise and certification infrastructure.
For Market Incumbents: Deploy pediatric toxicology talent retention as a defensive lever against formulation chemist scarcity commanding 35% salary premiums. Consolidate pharmacy channel relationships in Latin America and Southeast Asia against natural-positioned challengers. Accelerate ISO 11609 certification pipeline investment to compress 18-month abrasivity testing backlogs for herbal active launches. For New Entrants and Emerging Players: Enter via German Apotheken distribution networks where 40% price premiums for certified organic variants remain underpenetrated by natural-positioned specialists. Target United States direct-to-consumer subscription channels in California and New York metro areas where AI-driven personalization based on dental-app brushing data creates acquisition efficiency. Pursue pump-format convenience positioning with portion-control mechanisms that reduce parental application anxiety. For Investors and Strategic Acquirers: Re-rating potential sits with contract manufacturers possessing BIS-compliant herbal input sourcing and EFSA-approved clean-label formulation capabilities given accelerating parental preference shifts. Long-term viability favors players with backward integration into botanical extraction or captive stevia supply arrangements. Monitor WHO early-exposure guideline finalization as inflection signal for infant-specific paste addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Clean-Label Certification Investment | Unlocks German pharmacy channel access commanding 40% price premiums over mass retail. |
| Pump-Format Manufacturing Scale-Up | Captures United States e-commerce subscription growth tied to electric toothbrush bundling. |
| Backward Integration into Botanical Extraction | Secures neem and licorice supply chains from Kerala extractors for European pharmacy networks. |
| AI-Driven Personalization Platform Development | Enables customized flavor and abrasivity matching based on dental-scanning app data integration. |
| BIS Heavy-Metal Testing Compliance Infrastructure | Signals quality assurance for Indian pharmacy shelf placement and export certification credibility. |
Study Parameters
Multi-period observation of formulation patent filings, regulatory submission timelines, and pharmacy channel SKU expansions anchored the trend analysis, supplemented by interviews with pediatric dentistry specialists, cosmetic chemists with child-safety dossier experience, pharmacy category buyers in Frankfurt and Munich, and contract manufacturing procurement leads in Guangdong. Secondary validation drew from FDA 510(k) pediatric oral care submissions, EFSA flavoring safety opinions, BIS certification registries, and Nielsen retail audit data for licensed-character packaging velocity. Bottom-up demand modeling triangulated against top-down category spending projections.
Segment-weighting across active ingredient type, distribution channel, and packaging format dimensions informed volume and value outputs throughout the forecast period. CAGRs derived from regression analysis of historical pharmacy and supermarket scan data against parental demographic shifts and regulatory approval velocity. Industry-specific inputs included ISO 11609 abrasivity testing backlog durations, EFSA clean-label approval timelines, and dental-app integration penetration rates in United States metropolitan markets.
Revisions become necessary when FDA fluoride concentration guidance shifts, EFSA flavoring safety evaluations accelerate or restrict approved compounds, or WHO early-exposure recommendations alter pediatric dentistry protocol timing. Material deviation in these regulatory triggers warrants strategic pause and re-evaluation of formulation pipeline investments and channel prioritization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Herbal Toothpaste Market
Oral Care
Kids Oral Care Products Market
Oral Care
Oral Care Market
Oral Care
Global Oral Hygiene Market
Oral Care
Oral Hygiene Products Market
Oral Care
China Oral Care Market
Oral Care
Japan Oral Hygiene Market
Oral Care
Asia-Pacific Oral Care Market
Oral Care
Adult Oral Care Products Market
Oral Care
Oral Mucositis Market
Oral Care
South America Oral Care Market
Oral Care
Oral Thrush Treatment Market
Oral Care
Toothcare Market
Oral Care
Ayurvedic Toothpaste Market
Oral Care
Children's Oral Care Market
Oral Care
Us Oral Care Market